
 Histopathology Testing Equipment Market | 2026-2036
Histopathology Testing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Histopathology Testing Equipment Market Outlook
German precision engineering clusters is shifting toward fully automated histopathology workflows. Thermo Fisher Scientific leverages its reagent-instrument bundling strategy to sustain installed-base loyalty across European academic medical centers. Roche differentiates through integrated digital pathology platforms that combine slide scanning with AI-assisted image analysis. Leica Biosystems anchors the high-end microtome segment with cryostat systems designed for intraoperative frozen section applications.
Histopathology testing equipment encompasses instruments that prepare, section, stain, and visualize tissue specimens for disease diagnosis, with microtomes achieving section thickness precision of 1–60 micrometers depending on rotary or ultramicrotome configuration. These systems serve primarily to enable morphological examination of biopsied tissue, supporting definitive diagnosis in oncology and infectious disease pathways. Slide scanner adoption within digital pathology is accelerating fastest as laboratories seek remote consultation capabilities and archival efficiency. Automated staining systems command premium pricing due to throughput advantages in high-volume clinical laboratories, while traditional microscopy persists in resource-constrained settings where capital replacement cycles extend beyond ten years.
FDA 510(k) clearance requirements govern automated tissue processors and digital slide scanners in the United States, while the EU Medical Device Regulation mandates notified body conformity assessment for staining platforms sold in Europe. ISO 15189 accreditation standards for medical laboratories indirectly drive equipment specifications by mandating traceable quality control in histopathology workflows. Stakeholders must weigh regulatory validation burdens against the operational savings of closed-system automation as laboratory consolidation accelerates.
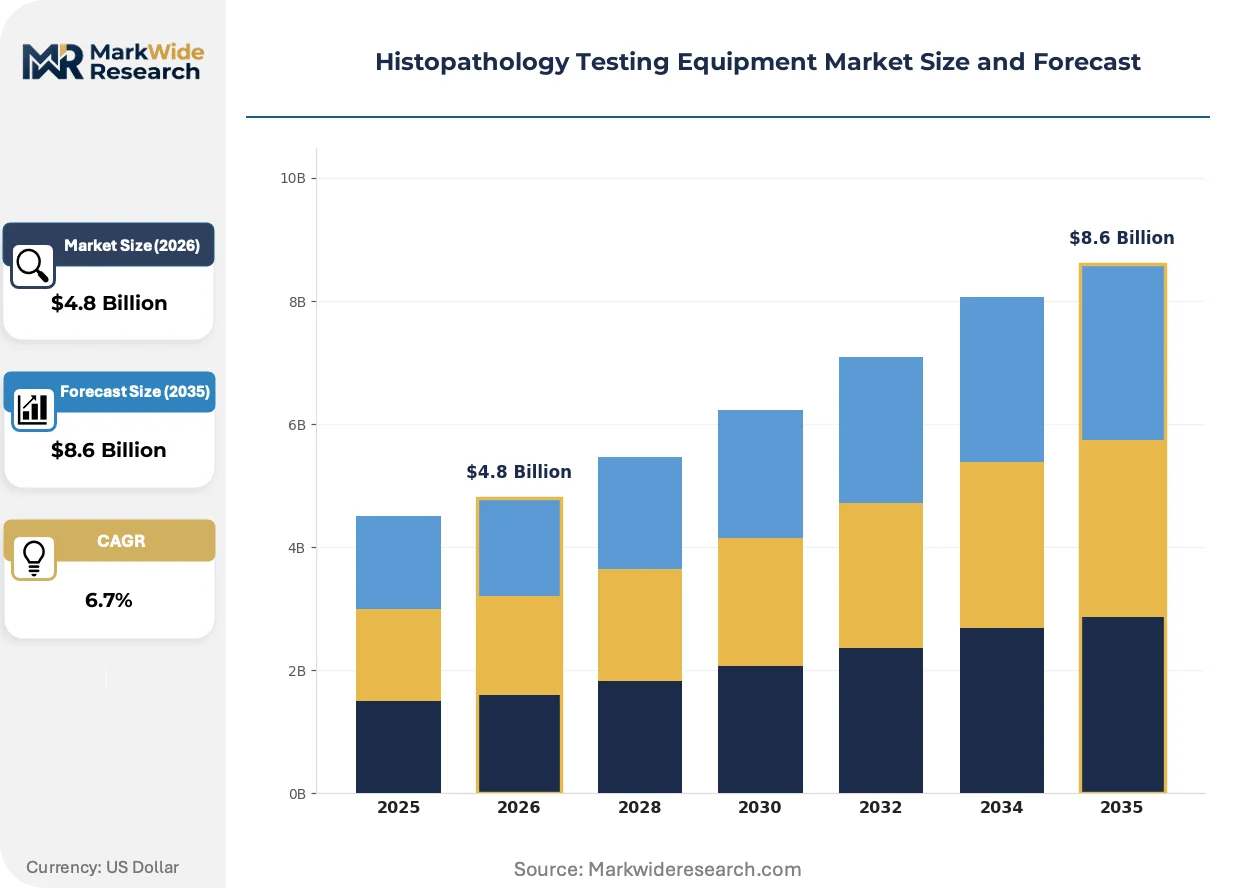
Market Dynamics
Automated tissue processing systems are compressing diagnostic turnaround times from days to hours, forcing laboratories to retire manual staining workflows and triggering wholesale replacement cycles across hospital-based pathology departments.
Growth Catalysts
- Rising biopsy volumes:Oncology screening programs in Germany and the United States are generating specimen loads that exceed manual processing capacity, compelling laboratories to adopt continuous-feed tissue processors.
- FDA 510(k) pathway clarity:Predictable premarket notification timelines for Class II automated staining devices enable manufacturers to synchronize product launches with laboratory capital budgeting cycles.
- Digital pathology infrastructure:Whole-slide imaging systems are expanding into remote consultation networks, creating downstream demand for standardized slide preparation equipment that integrates with scanner workflows.
Market Restraints
- Capital intensity barriers:Fully automated staining platforms require seven-figure investments that strain pathology department budgets in community hospitals and smaller diagnostic centers.
- Reagent supply concentration:Specialty histochemical dyes and antibody cocktails derive from a limited supplier base concentrated in Western European chemical manufacturing clusters, exposing buyers to input cost volatility.
- Technical interoperability limits:Proprietary data formats from competing digital slide scanner vendors prevent seamless exchange of pathology images across multi-site laboratory networks.
Strategic Opportunities
- Underpenetrated Indian diagnostics:Tier-2 and Tier-3 cities in India lack automated tissue processing capacity, creating first-mover advantages for manufacturers establishing localized service infrastructure.
- AI-assisted diagnostic integration:Convergence of convolutional neural networks with whole-slide imaging is opening revenue streams in computational pathology that bundle software subscriptions with hardware placements.
- EU MDR compliance services:The Medical Device Regulation's enhanced clinical evidence requirements generate consulting and validation service opportunities for equipment vendors with regulatory affairs expertise.
Industry Challenges
- Histotechnologist workforce scarcity:Specialized technicians capable of operating cryostat microtomes and troubleshooting automated staining protocols are in short supply across North American and European laboratory markets.
- Legacy system integration friction:New digital pathology platforms must interface with decades-old laboratory information systems that lack modern API architectures, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Histopathology Testing Equipment Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microtome, Stainer, Slide Scanner, Tissue Processor End User: Clinical Laboratories, Research Institutes, Hospitals, Academic Institutions Technology: Digital Pathology, Immunohistochemistry, Automated Staining, Traditional Microscopy Application: Cancer Diagnosis, Infectious Diseases, Cardiovascular Disorders, Neurological Disorders |
| Companies Covered | Thermo Fisher Scientific, Roche, Agilent Technologies, Leica Biosystems, Sakura Finetek, Hologic, PerkinElmer, Merck KGaA, Epredia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Histopathology Testing Equipment Market Strategic Shifts
Artificial intelligence is embedding into every stage of the histopathology workflow, from specimen tracking through diagnostic reporting, compressing the traditional separation between analytical instruments and decision-support software.
Multiplex immunohistochemistry staining protocols are expanding into precision oncology applications, enabling simultaneous visualization of multiple biomarkers on a single tissue section. Academic medical centers in the United States and Germany are adopting these systems at accelerated pace to support companion diagnostic development. This capability is expanding into pharmaceutical contract research workflows, compressing the timeline between biomarker discovery and clinical trial patient stratification.
The EU Medical Device Regulation is tightening clinical evidence requirements for automated tissue processors sold in Europe, mandating prospective validation studies that were previously satisfied by predicate device equivalence. Manufacturers targeting European academic medical centers must now maintain dedicated clinical affairs teams to manage notified body interactions. High-complexity staining platforms face the steepest compliance burden, driving some vendors to prioritize 510(k) clearance in the United States before pursuing CE marking.
Consolidated procurement by multi-hospital health systems is displacing individual laboratory purchasing autonomy, centralizing equipment selection decisions at regional supply chain offices. Group purchasing organizations now negotiate enterprise-wide contracts that bundle histopathology instruments with multi-year reagent supply commitments. This concentration is most visible in United States integrated delivery networks, where standardized platforms across dozens of sites generate volume discounts that independent laboratories cannot match.
Histopathology Testing Equipment Market Segmentation
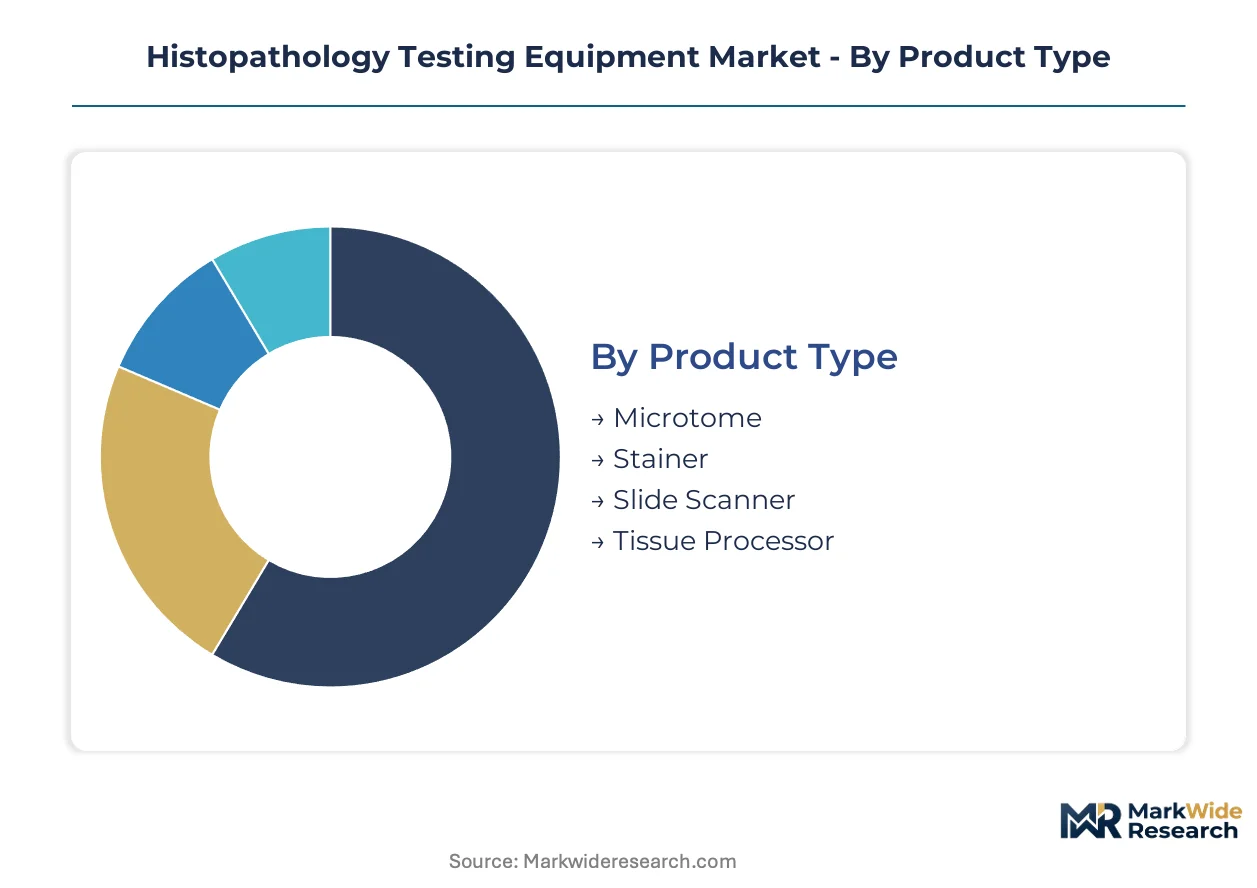
Histopathology testing equipment segments reflect divergent capital deployment patterns across diagnostic workflows. Laboratories prioritize throughput automation in high-volume settings while research environments favor analytical precision over speed.
Product Type:
Equipment specifications define the technical boundary between manual preparation and fully automated tissue processing pipelines.
- Microtome:Rotary and cryostat configurations achieve section thickness precision from 1 to 60 micrometers depending on specimen requirements. German academic medical centers drive demand for cryostat systems designed specifically for intraoperative frozen section applications where diagnostic turnaround compresses to minutes.
- Stainer:Automated staining platforms deploy continuous-feed architectures that process hundreds of slides per hour with reagent-instrument bundling to lock in consumable revenue streams. Hospital-based pathology labs in the United States are retiring manual workflows and triggering replacement cycles as biopsy volumes exceed technician capacity.
- Slide Scanner:Whole-slide imaging systems digitize glass slides at sub-micron resolution for remote consultation networks.
- Tissue Processor:Automated processors compress diagnostic timelines from days to hours through continuous specimen infiltration.
Stainers lead on scale through installed-base expansion; slide scanners lead on momentum as digital pathology infrastructure spreads.
End User:
Procurement authority concentrates differently across settings with varying capital autonomy and reimbursement structures.
- Clinical Laboratories:High-throughput reference labs in Germany and the United States operate centralized tissue processing systems serving multi-site networks. These facilities command volume discounts through consolidated procurement that independent hospital labs cannot replicate.
- Hospitals:Hospital-based pathology departments face capital intensity barriers that strain community hospital budgets while academic centers access institutional research funding. FDA 510(k) clearance timelines shape their capital budgeting cycles for automated staining platforms.
- Research Institutes:Precision oncology applications drive multiplex immunohistochemistry adoption for biomarker discovery workflows.
- Academic Institutions:Medical school laboratories balance teaching requirements with research-grade analytical demands.
Clinical laboratories lead on scale; research institutes lead on momentum through precision oncology expansion.
Technology:
Workflow integration determines whether platforms operate as standalone instruments or as nodes within connected diagnostic pipelines.
- Digital Pathology:Whole-slide imaging combined with AI-assisted image analysis enables computational pathology revenue streams through software subscription bundling. Technical interoperability limits persist as proprietary data formats from competing scanner vendors block seamless image exchange across multi-site networks.
- Automated Staining:Closed-system automation reduces technician touchpoints while mandating reagent lock-in that sustains manufacturer margins. EU MDR compliance burdens are driving some vendors to prioritize FDA 510(k) clearance before pursuing CE marking for high-complexity platforms.
- Immunohistochemistry:Antibody-based detection protocols support companion diagnostic development for pharmaceutical contract research.
- Traditional Microscopy:Conventional light microscopy persists in resource-constrained settings where capital replacement cycles extend beyond ten years.
Automated staining leads on scale through clinical laboratory penetration; digital pathology leads on momentum as AI integration accelerates.
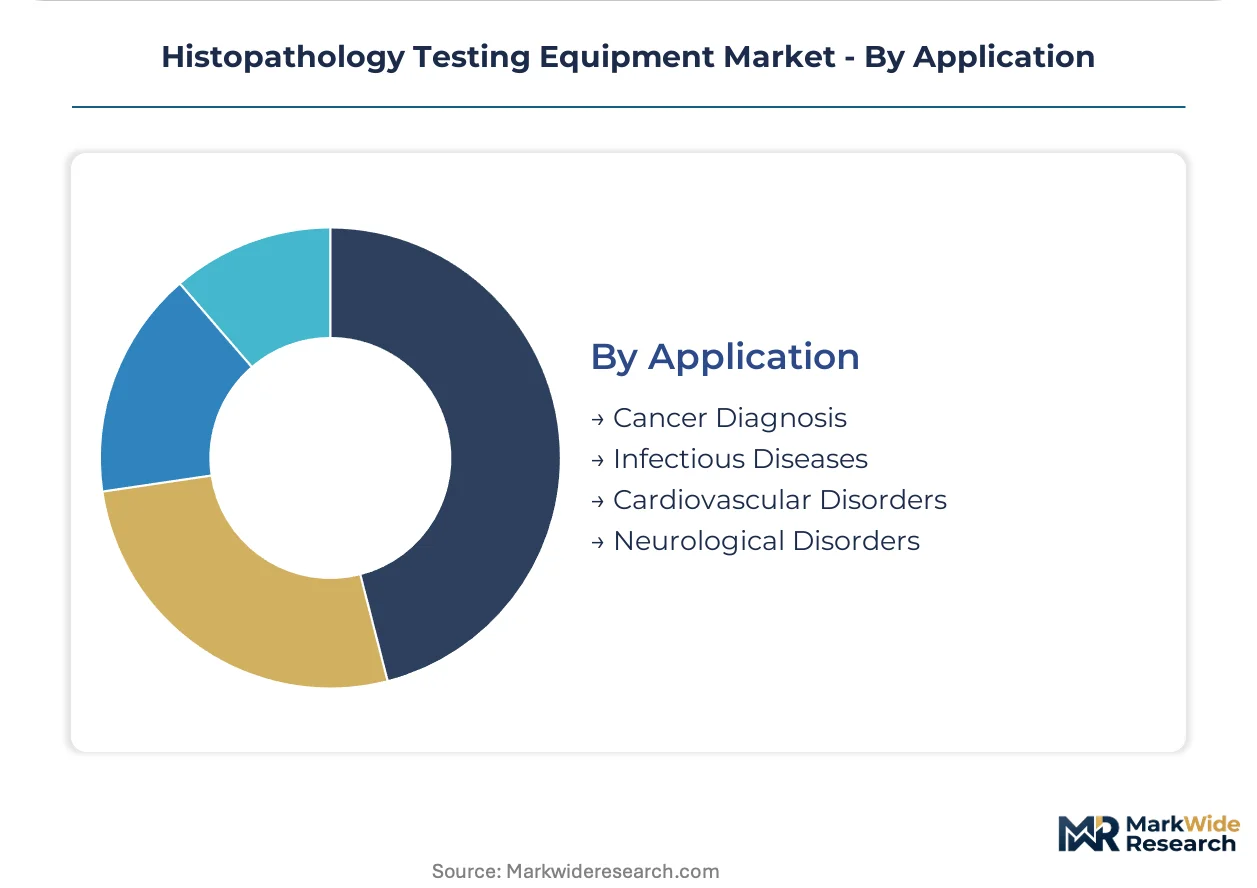
Application:
Disease-specific diagnostic volumes shape equipment utilization rates and reagent consumption patterns.
- Cancer Diagnosis:Oncology screening programs generate specimen loads that exceed manual processing capacity and compel adoption of continuous-feed tissue processors. Multiplex immunohistochemistry staining enables simultaneous visualization of multiple biomarkers to support precision oncology patient stratification.
- Infectious Diseases:Histopathological examination identifies tissue-invasive pathogens when culture methods fail or timelines prove inadequate. Academic medical centers deploy specialized staining protocols for emerging infectious disease diagnostics.
- Cardiovascular Disorders:Cardiac biopsy analysis requires specialized specimen handling to preserve tissue architecture.
- Neurological Disorders:Brain tissue sectioning demands ultramicrotome precision for electron microscopy correlation studies.
Cancer diagnosis leads on scale through screening program expansion; infectious diseases lead on momentum through emerging pathogen response requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturer investment patterns as the cost-of-compliance gap between the FDA's 510(k) pathway and the EU MDR's clinical evidence mandates widens. Equipment vendors now sequence market entry strategies around these divergent validation timelines.
United States
Hospital-based pathology departments in the United States drive automated staining platform procurement as biopsy volumes from oncology screening programs exceed manual processing capacity. FDA 510(k) clearance timelines for Class II medical devices enable manufacturers to synchronize product launches with laboratory capital budgeting cycles. Academic medical centers in Boston and the Research Triangle anchor demand for integrated digital pathology platforms that combine slide scanning with AI-assisted image analysis.
Germany
Centralized reference laboratories in Germany drive bulk procurement of tissue processing systems through consolidated multi-site networks serving hospital consortia. The EU Medical Device Regulation mandates notified body conformity assessment for staining platforms, with enhanced clinical evidence requirements extending validation timelines. Precision engineering clusters in Baden-Württemberg and Bavaria are shifting toward fully automated histopathology workflows that compress diagnostic turnaround times.
China
Domestic manufacturers are expanding automated tissue processing capacity to serve tier-2 and tier-3 city hospitals previously dependent on manual workflows. NMPA medical device registration requirements govern digital slide scanners and automated staining systems entering the Chinese market. Biomedical industrial parks in Suzhou and Hangzhou concentrate production of entry-level microtome systems for resource-constrained settings across provincial healthcare networks.
India
Tier-2 and tier-3 cities in India lack automated tissue processing infrastructure, creating first-mover advantages for manufacturers establishing localized service and maintenance networks. CDSCO medical device rules classify automated staining platforms and digital pathology systems under risk-based registration frameworks. Diagnostic laboratory clusters in Mumbai, Delhi-NCR, and Bangalore are piloting whole-slide imaging systems for remote consultation networks linking metropolitan centers with district hospitals.
Japan
Academic medical centers in Japan deploy specialized cryostat microtome systems for intraoperative frozen section applications where diagnostic turnaround compresses to minutes. PMDA premarket approval requirements for high-risk medical devices shape development timelines for multiplex immunohistochemistry platforms. Research institutes in the Kanto and Kansai regions anchor demand for ultramicrotome precision systems serving electron microscopy correlation studies in neurological disorder diagnostics.
Histopathology Testing Equipment Market Competitive Environment
German precision engineering specialists anchor one tier; United States-based diversified life science conglomerates hold another through reagent-instrument bundling strategies. The market structure concentrates around three to five integrated platform vendors with established installed bases, while mid-tier specialists compete on sub-segment precision. Two strategic archetypes dominate: diversified conglomerates leveraging consumable lock-in, and focused instrumentation specialists defending premium microtome positions. Competitive moves center on M&A for digital pathology software capabilities and strategic partnerships for AI-assisted diagnostic integration.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Roche exemplify platform breadth through reagent-instrument bundling and integrated digital pathology offerings respectively. Leica Biosystems occupies a position representing precision microtome specialization for intraoperative applications. These three anchors demonstrate how geographic origin and corporate structure shape competitive positioning: Waltham-based Thermo Fisher Scientific and Basel-headquartered Roche operate as multinational life science conglomerates, while Leica Biosystems represents German-focused instrumentation heritage.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Roche |
| Agilent Technologies |
| Leica Biosystems |
| Sakura Finetek |
| Hologic |
| PerkinElmer |
| Merck KGaA |
| Epredia |
| Others |
Value Chain & Pricing Dynamics
Consolidated procurement by United States integrated delivery networks is forcing manufacturers to restructure pricing architectures around enterprise-wide reagent-instrument bundles, compressing margins on standalone hardware while expanding recurring revenue streams through consumable lock-in.
Pricing Analysis
Distributor margins on automated staining platforms typically range from 15 to 25 percent depending on geographic market maturity and service bundling intensity. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared systems with AI-integration capabilities from basic manual microtome configurations. Pricing pressure stems from group purchasing organization consolidation that extracts volume discounts exceeding independent laboratory procurement leverage. Community hospital pathology departments exhibit highest price sensitivity due to capital intensity barriers, while academic medical centers prioritize analytical precision over unit economics.
Supply Chain Analysis
Refurbishment flows for cryostat microtomes and automated tissue processors concentrate in Germany and the United States, where precision engineering heritage supports remanufacturing to OEM specifications. Specialty histochemical dyes and antibody cocktails draw from Western European chemical manufacturing clusters in Germany and Switzerland, with chromogenic substrates and detection reagents sourced from Japanese fine chemical producers. Single-source vulnerability persists for multiplex immunohistochemistry detection kits where proprietary formulations limit supplier switching. Distribution runs through authorized service networks that bundle installation validation with multi-year maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on the shift from transactional hardware sales toward recurring reagent revenue and software subscription bundling, with automated staining platforms capturing consumable pull-through at 3-5x original equipment value over the installed base lifecycle.
For Market Incumbents: Deploy reagent-instrument bundling as the primary defensive lever against emerging digital pathology specialists. Deepen field service infrastructure in India and China to preempt localized competitors from capturing replacement cycles. Counter proprietary data format fragmentation by participating in industry standardization initiatives for whole-slide imaging interoperability. For New Entrants and Emerging Players: FDA 510(k) pathway clarity in the United States opens a window for streamlined market entry of Class II automated staining devices with predicate device equivalence. Tier-2 and tier-3 Indian cities present the most penetrable geography due to absent automated tissue processing infrastructure. Pursue hospital system partnership models that embed equipment through reagent rental arrangements rather than capital purchase. For Investors and Strategic Acquirers: Asymmetric upside sits with digital pathology software specialists possessing convolutional neural network capabilities for computational pathology. Long-term viability over the next decade favors platforms integrating AI-assisted image analysis with standardized slide preparation workflows. Monitor FDA breakthrough device designations for AI-enabled diagnostic algorithms as inflection signals for valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Reagent-Instrument Bundling | Thermo Fisher Scientific sustains installed-base loyalty through consumable lock-in across European academic medical centers. |
| AI-Assisted Diagnostic Integration | Roche captures computational pathology revenue streams by bundling software subscriptions with whole-slide imaging hardware. |
| Localized Service Infrastructure | First-mover manufacturers in Indian tier-2 cities preempt domestic competitors from establishing maintenance networks. |
| EU MDR Compliance Services | Equipment vendors with clinical affairs expertise monetize consulting and validation support for notified body interactions. |
| Multiplex IHC Platform Development | Academic medical centers in Germany and the United States accelerate companion diagnostic development for pharmaceutical contract research. |
Study Parameters
Coverage spans the United States, Germany, China, India, and Japan, with primary inputs from each market through structured interviews with hospital pathology department directors, clinical laboratory managers, biomedical equipment procurement officers, and histotechnologist workforce trainers. Secondary validation draws from FDA 510(k) clearance databases, EU MDR notified body conformity assessments, NMPA registration filings, CDSCO medical device rules, and PMDA premarket approval documentation. Bottom-up triangulation across equipment shipment data and top-down reconciliation against healthcare capital expenditure surveys ensure cross-verified market sizing.
Granularity-level modeling extends to product type configurations including rotary microtomes, cryostat systems, continuous-feed stainers, whole-slide scanners, and automated tissue processors, with end-user segmentation distinguishing clinical laboratories, hospital-based pathology departments, research institutes, and academic institutions. Technology dimensions capture digital pathology platforms, automated staining architectures, immunohistochemistry protocols, and traditional microscopy persistence. CAGRs derive from logistic growth curve fitting against biopsy volume projections and replacement cycle timing across the analysis window. Industry-specific forecast inputs incorporate oncology screening program expansion rates and histotechnologist workforce scarcity indices.
Revisions become necessary when regulatory validation timelines shift materially, when supply chain disruptions affect specialty reagent availability, or when AI diagnostic algorithm approvals accelerate platform replacement decisions. Forecasts reflect documented assumptions regarding laboratory consolidation trajectories and reimbursement stability for pathology services. Practitioners should monitor FDA breakthrough device designations, EU MDR clinical evidence requirement enforcement, and histotechnologist training program graduation rates for early signals of forecast deviation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Centrifuge Tubes Market
Laboratory Equipment
Blood Volume Analyzer Market
Laboratory Equipment
Electronic Multichannel Pipettes Market
Laboratory Equipment
Albumin Analyzers Market
Laboratory Equipment
Laboratory Vacuum Drying Oven Market
Laboratory Equipment
Global Hematology Analyzers and Reagents Market
Laboratory Equipment
Global Blood Collection Tubes Market
Laboratory Equipment
Ion-Selective Clinical Lab Analyzers Market
Laboratory Equipment
Global Graduated Cylinder Market
Laboratory Equipment
Vacuum Blood Collection Tube Market
Laboratory Equipment
Hemostasis Analyzers Market
Laboratory Equipment
Absorbance Micro Plate Reader Market
Laboratory Equipment
Laboratory Ovens Market
Laboratory Equipment
Middle East and Africa Laboratory Hoods and Enclosure Market
Laboratory Equipment
Colony Counters Market
Laboratory Equipment
ASEAN Laboratory Equipment Market