
 Congestive Heart Failure Treatment Devices Market | 2026-2036
Congestive Heart Failure Treatment Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Congestive Heart Failure Treatment Devices Market Intelligence
The European Union's Corporate Sustainability Reporting Directive (CSRD) is restructuring supply chain and material sourcing strategies for medical device manufacturers. Medtronic leverages its extensive distribution network to maintain a dominant position in implantable devices. Abbott differentiates through its focus on advanced diagnostics integrated with therapeutic solutions. Boston Scientific Corporation competes on innovation in less-invasive transcatheter technologies, particularly for structural heart interventions.
Congestive heart failure treatment devices are medical implants and external systems designed to manage the symptoms and progression of a weakened heart muscle. These devices, such as pacemakers with bi-ventricular pacing capabilities, work to restore normal cardiac rhythm or assist in blood circulation. Ventricular Assist Devices (VADs) represent a high-growth product category, often serving as a bridge to transplant or destination therapy. While hospitals remain the primary end-user, the homecare setting is expanding for post-operative monitoring and management.
Market access is governed by stringent regulatory approvals from bodies like the US FDA, the European Union under its Medical Device Regulation (MDR), and China's NMPA. These regulations mandate extensive clinical trial data and post-market surveillance, influencing product design and development timelines. Future competitive advantage will hinge on a manufacturer's ability to navigate these diverse regulatory pathways while demonstrating clear clinical and economic value to healthcare providers and payers.
Market Dynamics
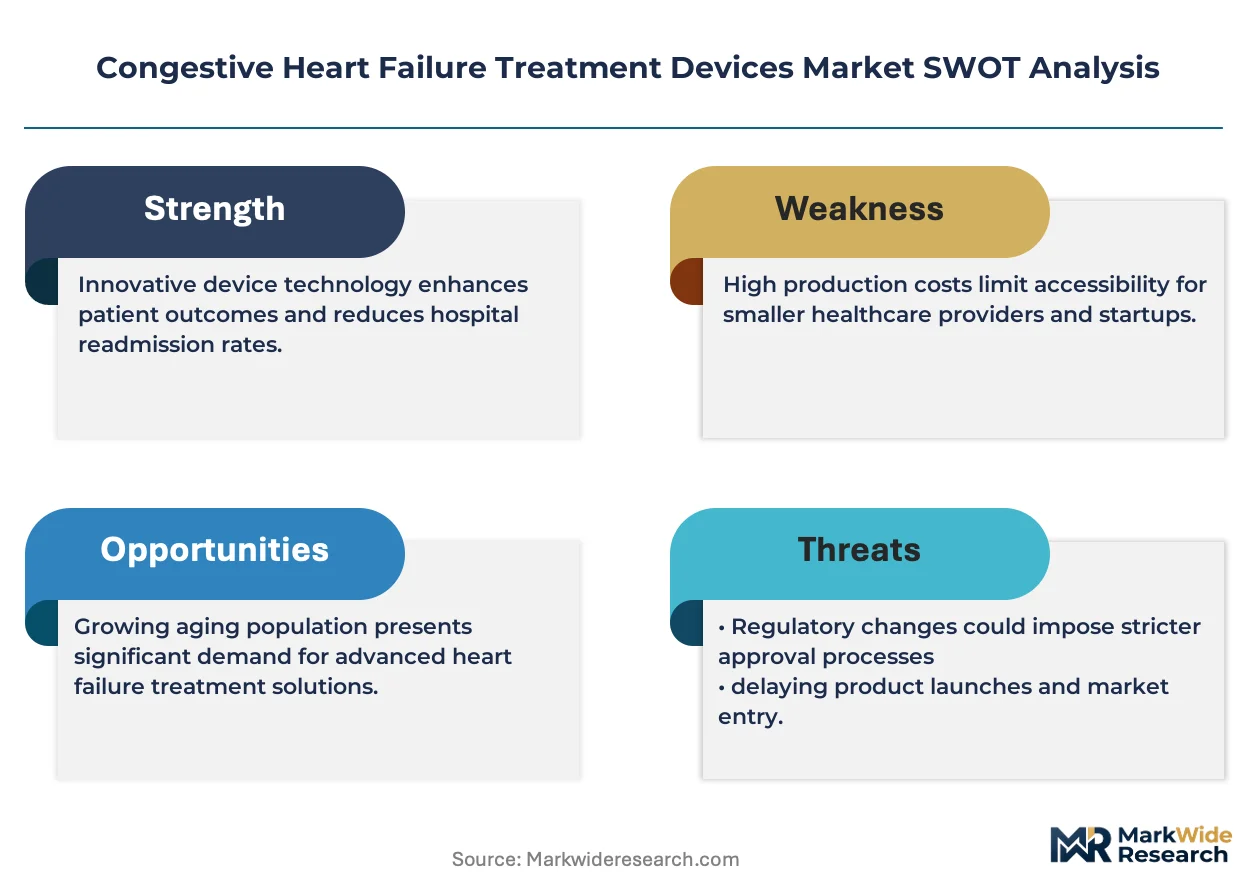
The convergence of device miniaturization with AI-driven data analytics is reshaping the market's structure. This technological shift enables a move from reactive, hospital-based interventions to proactive, remote patient management, altering the fundamental delivery of cardiac care.
Growth Catalysts
- AI-Driven Analytics:The integration of artificial intelligence into smart implants and monitoring systems enhances device performance and provides predictive insights into patient health, allowing for pre-emptive clinical interventions.
- Aging Demographics:Advanced economies with aging populations, particularly Germany, exhibit high demand for congestive heart failure treatments due to the increased prevalence of cardiovascular diseases among the elderly.
- Remote Patient Management:The expansion of reimbursement frameworks for telehealth and remote patient monitoring is accelerating adoption in the homecare setting, creating a significant growth channel beyond traditional hospitals.
Market Restraints
- High Device and Procedure Costs:The substantial cost associated with advanced devices like Ventricular Assist Devices (VADs) and their implantation procedures limits accessibility, particularly in healthcare systems with constrained budgets or unfavorable reimbursement policies.
- Stringent Regulatory Hurdles:The European Union's Medical Device Regulation (MDR) imposes extensive clinical data and post-market surveillance requirements, increasing development costs and lengthening time-to-market for new technologies.
- Clinical Complication Risks:Implantable devices carry inherent risks, including infection, thrombosis, and device malfunction, which can lead to severe patient morbidity and necessitate costly revision surgeries.
Strategic Opportunities
- Emerging Market Penetration:Large, developing healthcare markets such as Brazil present significant growth opportunities as infrastructure improves and healthcare spending on chronic disease management increases.
- Predictive Analytics Platforms:Developing software platforms that use machine learning to analyze data from connected devices offers a path to create new, subscription-based revenue streams focused on predictive and preventative care.
- Fully Implantable VADs:Innovation focused on developing totally implantable ventricular assist systems without external drivelines would address a major source of infection and significantly improve patient quality of life.
Industry Challenges
- Specialized Talent Scarcity:A shortage of clinical specialists trained in implanting and managing advanced heart failure devices, coupled with a lack of data scientists for analytics, constrains market expansion.
- Data Interoperability:Ensuring seamless data flow and integration between various manufacturers' devices, electronic health records (EHRs), and remote monitoring platforms remains a significant technical and operational hurdle.
- Post-Market Surveillance Burden:Complying with rigorous post-market surveillance mandates from regulators like the US FDA requires substantial investment in data collection and reporting infrastructure, adding operational complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Congestive Heart Failure Treatment Devices Market |
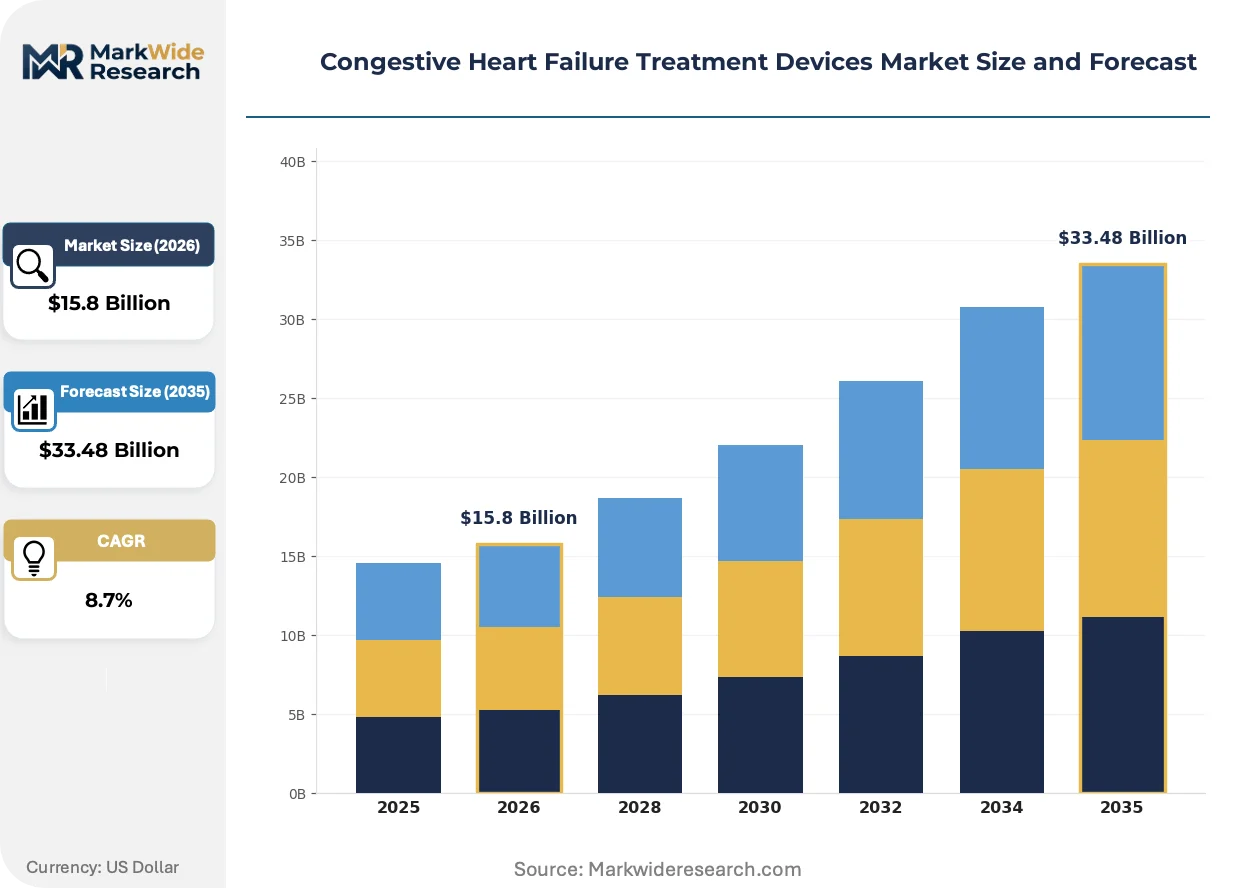
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $33.48 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Defibrillators, Pacemakers, Ventricular Assist Devices, Cardiac Resynchronization Therapy Devices End User: Hospitals, Homecare, Ambulatory Surgical Centers, Rehabilitation Centers Delivery Mode: Surgical, Implantable, Transcatheter, External Technology: Wireless Monitoring, Bi-Ventricular Pacing, Smart Implants, AI-Driven Analytics |
| Companies Covered | Boston Scientific Corporation, Medtronic, Abbott, Biotronik SE & Co. KG, GE HealthCare, LivaNova PLC, Jarvik Heart, Inc., Edwards Lifesciences, Berlin Heart GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Congestive Heart Failure Treatment Devices Market Strategic Shifts & Innovations
The market's evolution is defined by a fundamental pivot from episodic treatment to continuous, data-driven disease management. This transition is powered by connected device ecosystems that extend clinical oversight into the patient's daily life, fostering more proactive care models.
Wearable biosensors and smart implants provide continuous monitoring of key physiological parameters like fluid status and cardiac rhythms. Homecare providers and patients recovering from cardiac procedures are rapidly adopting these technologies. This flow of real-time information is decentralizing chronic care management from specialized clinics directly to the patient's environment, enabling earlier detection of decompensation events.
The European Union's Corporate Sustainability Reporting Directive (CSRD) is compelling manufacturers to re-evaluate their supply chains. This regulation requires extensive disclosure on environmental and social impacts, including material sourcing for components like batteries and microelectronics. Device makers with complex global sourcing, especially for energy-intensive or rare materials, must now implement robust traceability and reporting systems to maintain market access in Europe.
A shift from traditional fee-for-service purchasing to value-based healthcare agreements is altering procurement dynamics. This model displaces purely transactional device sales with long-term partnerships where manufacturers may be compensated based on achieving specific patient outcomes, such as reduced hospital readmission rates. This trend is gaining the most traction within large, integrated health systems in the United States and select national health services in Europe.
Congestive Heart Failure Treatment Devices Market Segmentation
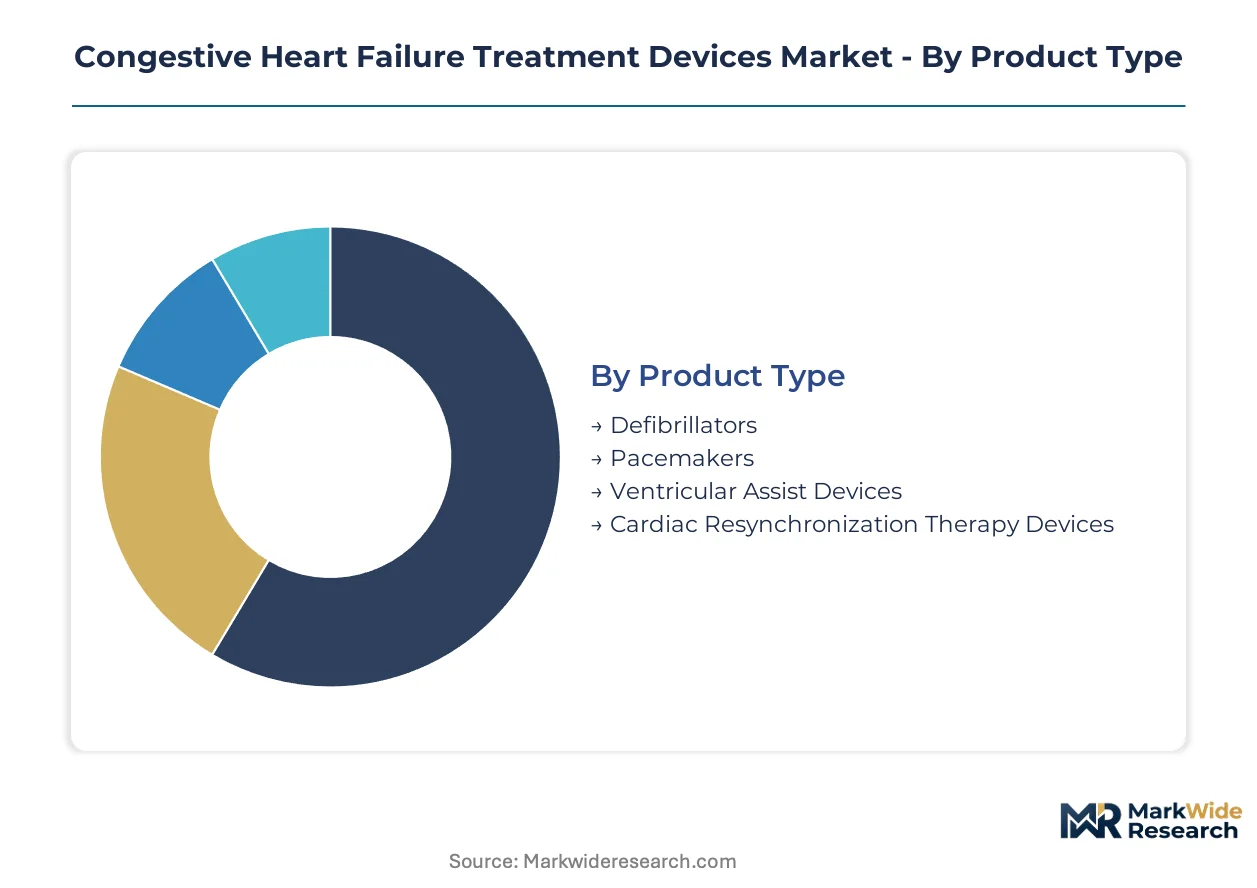
The segmentation of the congestive heart failure treatment devices market reveals distinct patterns in product evolution, end-user adoption, delivery mechanisms, and technological integration. Understanding these categories is essential for manufacturers to tailor product development and market access strategies effectively.
Product Type:
The product type segmentation highlights the varying levels of device integration, from standalone external systems to fully embedded cardiac solutions.
- Ventricular Assist Devices:Ventricular Assist Devices are mechanical pumps supporting heart function in advanced heart failure patients. Demand for VADs concentrates in advanced healthcare economies like Germany, driven by their role as bridge-to-transplant or destination therapy.
- Pacemakers:Pacemakers are small electronic devices implantable under the skin, delivering electrical impulses to regulate heart rhythm. Demand for pacemakers remains strong in aging populations across Europe, addressing bradycardia and other rhythm disorders.
- Defibrillators:These devices deliver electrical shocks to restore normal heart rhythm for patients with life-threatening arrhythmias.
- Cardiac Resynchronization Therapy Devices:CRT devices coordinate the pumping of the heart's ventricles, improving cardiac output in specific heart failure patients.
Pacemakers lead volumes today; Ventricular Assist Devices are gaining share fastest.
End User:
The end-user segmentation illustrates how different healthcare settings specialize in patient care pathways, influencing device utilization.
- Hospitals:Hospitals serve as the primary sites for complex device implantation procedures and acute heart failure management. These institutions focus on comprehensive patient care, including diagnostics, surgery, and initial post-operative recovery.
- Homecare:The homecare segment involves remote monitoring and ongoing management of stable heart failure patients in their residences. Demand in this segment is accelerating due to advancements in connected devices and expanding telehealth reimbursement in countries like the United States.
- Ambulatory Surgical Centers:ASCs perform less invasive procedures, offering cost-effective alternatives for specific device implantations.
- Rehabilitation Centers:These centers provide structured programs for patients recovering from cardiac events or device implantations, focusing on physical therapy and lifestyle adjustments.
Hospitals remain the dominant end-user category, while homecare settings exhibit the steepest expansion trajectory.
Delivery Mode:
Delivery mode segmentation differentiates device placement based on invasiveness and procedural complexity.
- Surgical:Surgical delivery involves open-chest procedures for implanting larger devices or performing complex cardiac repairs. This traditional approach is necessary for devices like certain VADs and requires extensive hospital infrastructure.
- Transcatheter:Transcatheter delivery utilizes minimally invasive techniques, threading devices through blood vessels to the heart. This method reduces patient recovery times and is gaining favor for structural heart interventions in markets such as France.
- Implantable:These devices are permanently placed inside the body, providing continuous therapy without external components.
- External:External devices are worn outside the body, offering temporary support or diagnostic monitoring capabilities.
Surgical methods still account for a substantial portion of procedures, but transcatheter approaches are rapidly increasing their procedural share.
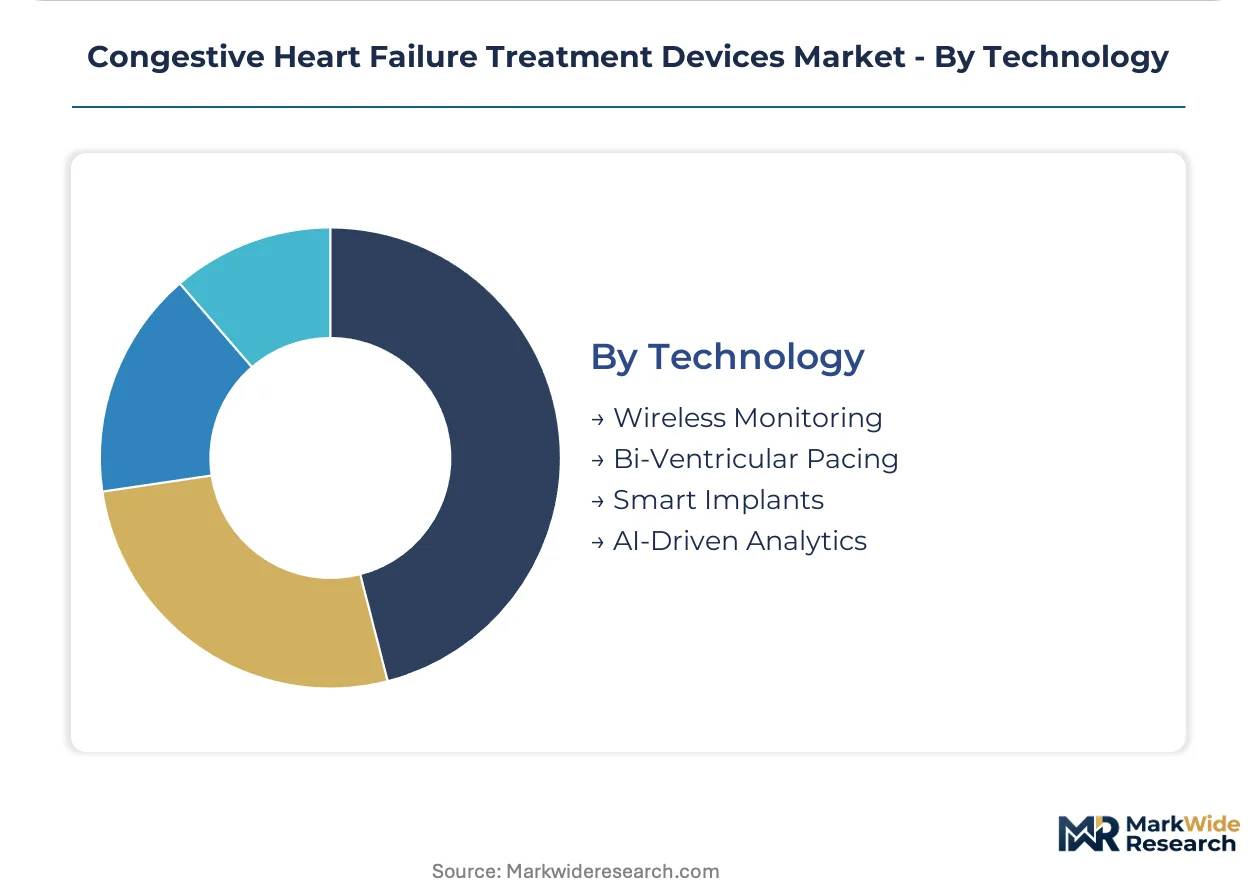
Technology:
The technology segment highlights the evolving capabilities embedded within heart failure devices, from basic rhythm management to advanced data integration.
- Smart Implants:Smart implants incorporate sensors and communication capabilities, enabling continuous physiological data collection and remote transmission. These devices are pivotal in decentralizing chronic care management and improving patient outcomes.
- AI-Driven Analytics:AI-driven analytics processes vast datasets from connected devices to provide predictive insights into patient health and device performance. This technology enhances pre-emptive clinical interventions and optimizes treatment strategies.
- Wireless Monitoring:This technology allows for remote transmission of patient data from devices to healthcare providers, facilitating continuous oversight.
- Bi-Ventricular Pacing:Bi-ventricular pacing coordinates the pumping action of both heart ventricles, improving efficiency in specific heart failure conditions.
While bi-ventricular pacing remains a core therapeutic technology, AI-driven analytics represents a critical frontier for future device innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Congestive Heart Failure Treatment Devices market first scaled in advanced Western economies, driven by early cardiovascular research and medical device innovation. These regions established the foundational technologies and clinical practices that define modern heart failure management. Subsequent expansion has followed improving healthcare infrastructure and increasing chronic disease prevalence globally, establishing diverse regional market dynamics.
United States
The United States presents substantial demand for advanced heart failure therapies due to a large patient pool and high healthcare spending. The US FDA's stringent approval processes ensure device safety and efficacy, shaping product development. Major medical device manufacturing and research hubs in areas like Minnesota and Massachusetts drive continuous innovation.
Germany
Germany's robust healthcare system and aging population fuel consistent demand for congestive heart failure devices. Compliance with the European Union's Medical Device Regulation (MDR) is critical for market access and product distribution. Medical technology clusters in Bavaria and North Rhine-Westphalia are central to device development and clinical adoption.
Japan
Japan faces a significant burden from cardiovascular diseases, particularly among its elderly population, sustaining demand for treatment devices. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees all product approvals and post-market surveillance. Research and manufacturing activities are concentrated in major metropolitan areas such as Tokyo and Osaka.
China
China's rapidly expanding healthcare infrastructure and rising chronic disease prevalence are driving significant market growth. The National Medical Products Administration (NMPA) regulates medical device market entry and quality standards. Industrial parks in Shanghai and Shenzhen are becoming key centers for medical device production and innovation.
Brazil
Brazil demonstrates significant potential for market expansion as healthcare spending increases and infrastructure improves. ANVISA, the national health surveillance agency, manages regulatory approvals for medical devices entering the market. São Paulo serves as a primary hub for medical technology distribution and healthcare services in Latin America.
Congestive Heart Failure Treatment Devices Market Key Industry Players
Capital-heavy producers compete with asset-light designers within the congestive heart failure treatment devices market. Large, established companies maintain extensive manufacturing capabilities and distribution networks, often offering comprehensive portfolios. Specialized technology developers frequently focus on niche innovations or software solutions for remote monitoring. Mergers and acquisitions remain a primary strategy for portfolio expansion, alongside strategic partnerships to enhance market access and technological reach.
Integrated device manufacturers like Medtronic, Inc. and Abbott Laboratories represent a significant portion of the market, offering comprehensive portfolios of implantable and diagnostic solutions. Boston Scientific Corporation, also a major global player, exemplifies innovation in less-invasive therapeutic devices. These firms anchor the market through broad product offerings and established clinical relationships across diverse geographies.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medtronic |
| Abbott |
| Biotronik SE & Co. KG |
| GE HealthCare |
| LivaNova PLC |
| Jarvik Heart, Inc. |
| Edwards Lifesciences |
| Berlin Heart GmbH |
| Others |
Cost & Logistics Intelligence
The performance-tier divergence between advanced implantable devices and basic rhythm management solutions directly shapes both pricing strategies and supply chain configurations in the congestive heart failure market.
Pricing Analysis
Value-based pricing models are gaining traction, particularly for advanced devices like Ventricular Assist Devices (VADs), where compensation links to patient outcomes. Price differentiation stems from device complexity and clinical efficacy, alongside brand premium established by companies like Medtronic. Pricing pressure stems from increasing scrutiny by public health systems and private payers on cost-effectiveness. Hospitals, managing constrained budgets, are often the most price-sensitive buyers, while specialized cardiac centers prioritize advanced technology.
Supply Chain Analysis
Single-source vulnerability sits with specialized component manufacturers for microelectronics and high-purity medical-grade materials, often concentrated in East Asia and Europe. Geographic supply concentration for critical inputs resides in countries like Germany for precision engineering and China for various electronic components. Device manufacturing relies heavily on specialized components, including custom-designed batteries and biocompatible polymers. Stringent regulatory restrictions on medical device components represent a significant structural risk. Distribution runs through established global logistics networks, with direct sales forces supporting complex device placements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a geographic-arbitrage play, where the cost of advanced R&D in Western economies contrasts with emerging market demand for accessible solutions.
For Market Incumbents:Anchor market leadership by investing in next-generation AI-driven analytics for smart implants, mitigating the threat from specialized software developers. Consolidate market share through strategic acquisitions of smaller technology firms with novel sensor or data processing capabilities. Reinforce channel control by strengthening partnerships with major hospital systems and expanding homecare service networks. Invest in robust post-market surveillance infrastructure to navigate evolving regulatory mandates like the European Union's MDR.
For New Entrants and Emerging Players:Predictive analytics platforms offer a technology-first wedge into the congestive heart failure market by providing subscription-based insights. Target underpenetrated homecare segments in the United States and emerging markets like Brazil, focusing on remote monitoring solutions. A go-to-market angle emphasizing data-driven early intervention and reduced readmission rates can appeal to value-based healthcare providers. Focus on developing cost-effective, user-friendly external monitoring devices that integrate seamlessly with existing electronic health records.
For Investors and Strategic Acquirers:Consolidation pressure builds where smaller innovators struggle with the high costs of regulatory compliance and market access. The long-term viability favors firms with strong intellectual property in AI-driven diagnostics and fully implantable VADs. Acquisition targets should include companies specializing in advanced biosensors, machine learning algorithms for cardiac data, or telehealth platforms. A signal to watch is the expansion of reimbursement codes for remote patient monitoring and predictive analytics services.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in AI-Driven Analytics Platforms | Enhances device efficacy and provides predictive insights for proactive patient management. |
| Expand Homecare Monitoring Solutions | Captures growth in remote patient management and extends clinical oversight beyond hospitals. |
| Develop Fully Implantable Ventricular Assist Devices | Addresses infection risks and significantly improves patient quality of life with advanced VADs. |
| Strengthen Emerging Market Penetration | Accesses new patient populations and leverages improving healthcare infrastructure in developing economies. |
| Navigate Value-Based Healthcare Agreements | Aligns manufacturer incentives with patient outcomes, securing long-term partnerships with healthcare providers. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region informing the market landscape. The analysis combines in-depth primary interviews with clinicians, hospital purchasing committees, and biomedical engineers, validated through extensive secondary research. Secondary sources include medical device regulatory filings, cardiology association reports, and hospital procurement databases. This approach ensures robust bottom-up and top-down triangulation of market data.
The rate-of-change decomposition framing underpins the analytical framework across the modeling period, dissecting market growth drivers and restraints. Segmentation dimensions modeled include product type, end user, delivery mode, technology, and patient age group. Compound annual growth rates are derived from historical data analysis and projected future trends. Key industry-specific forecast inputs include prevalence rates of congestive heart failure and advancements in cardiac device technology.
The model holds under current regulatory frameworks and technological development trajectories; deviation in clinical trial outcomes or reimbursement policy shifts would alter projections. Forecasts reflect documented assumptions regarding healthcare spending and demographic changes. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Global Vascular Patch Market
Cardiovascular Devices
Saudi Arabia Cardiovascular Devices Market
Cardiovascular Devices
Venous Reservoirs Market
Cardiovascular Devices
Cerebral Vascular Stent Market
Cardiovascular Devices
Global Cardiovascular Disease Monitoring and Diagnostic Devices Market
Cardiovascular Devices
Anticoagulation Market
Cardiovascular Devices
Chile Cardiovascular Devices Market
Cardiovascular Devices
Global Blood Pressure Cuffs Market
Cardiovascular Devices
Intravenous Catheters Market
Cardiovascular Devices
Global Percutaneous Coronary Intervention (PCI) Devices Market
Cardiovascular Devices
Global Sclerotherapy Market
Cardiovascular Devices
Canada Cardiovascular Devices Market
Cardiovascular Devices
Neurovascular Stent Retrievers Market
Cardiovascular Devices
Atherosclerotic Renovascular Treatment Market
Cardiovascular Devices
Extracorporeal Membrane Oxygenation (ECMO) Market
Cardiovascular Devices
Epinephrine Auto-Injectors Market