
 Stent-Assisted Coiling Market | 2026-2036
Stent-Assisted Coiling Market Size, Share, and Industry Trends Forecast 2026-2036
Stent-Assisted Coiling Market Analytics
Neurovascular device manufacturing in Ireland and Switzerland is expanding as European producers build dedicated cleanroom capacity for braided nitinol stent production. Medtronic leverages its integrated supply chain across Galway and Minneapolis to sustain high-volume output of self-expanding intracranial stents. Stryker Corporation anchors its competitive position through specialized neurovascular R&D facilities in Fremont, California. MicroPort Scientific Corporation differentiates by dominating domestic distribution channels across China's tier-one hospital stroke centers.
Stent-assisted coiling refers to the endovascular placement of a metallic scaffold across a wide-necked intracranial aneurysm followed by coil embolization, typically using nitinol or cobalt-chromium alloys with 0.014-inch delivery wire compatibility and radial forces engineered to resist foreshortening during deployment. Self-expanding stents occupy the largest share of product type demand due to their conformability in tortuous cerebrovascular anatomy. Hospitals represent the dominant end user segment, though outpatient surgery centers are capturing faster growth as ambulatory surgical facility certification for neurointervention spreads. Nitinol material formulations command premium positioning because superelastic recovery properties enable reliable wall apposition in curved vessels.
FDA 510(k) and PMA pathways govern U.S. market access for these devices, while the EU MDR requires notified body involvement and clinical follow-up data under stricter post-market surveillance rules. Japan's PMDA enforces QMS ordinance compliance plus mandatory adverse event reporting for intravascular implants. Stakeholders must monitor evolving reimbursement decisions for stroke intervention codes across Medicare, national health systems, and private payers.
Market Dynamics
EU MDR clinical evidence requirements for intracranial stent systems are forcing manufacturers to restructure trial protocols and post-market surveillance infrastructure before 2025 deadlines.
Growth Catalysts
- Stroke center certification expansion:Hospital accreditation programs in the United States, Germany, and Japan are mandating neurointerventional capability, creating institutional demand pull for stent-assisted coiling suites.
- Nitinol superelastic recovery:Advanced alloy formulations enable reliable wall apposition in tortuous cerebrovascular anatomy, expanding treatable aneurysm morphologies previously deemed unsuitable for endovascular repair.
- MDR transition timelines:European notified bodies are prioritizing intracranial implant reviews, accelerating compliant product availability for wide-necked aneurysm indications.
Market Restraints
- Braided nitinol supply concentration:Cleanroom production capacity clusters in Ireland and Switzerland, creating geographic vulnerability for European and North American device manufacturers.
- 0.014-inch delivery wire incompatibility:Legacy catheter systems in aging hospital inventories limit deployment of next-generation stent designs without full suite replacement.
- FDA PMA pathway duration:Premarket approval timelines for novel intracranial stent designs extend commercialization horizons beyond typical R&D amortization periods.
Strategic Opportunities
- Outpatient surgery center certification:Ambulatory surgical facility neurointervention standards are spreading in the United States, opening lower-acuity volume channels outside traditional hospital settings.
- Japan PMDA QMS ordinance alignment:Harmonized quality management requirements with ISO 13485 are reducing duplicative audit burdens for multinational manufacturers.
- Cobalt-chromium alloy convergence:Integration with flow-diverter technologies is creating hybrid device categories for complex aneurysm geometries.
Industry Challenges
- Neurointerventionalist training pipelines:Fellowship programs are not producing proceduralists at rates matching stroke center certification expansion, creating treatment access bottlenecks.
- Adverse event reporting complexity:Japan's PMDA mandatory intravascular implant surveillance and EU MDR post-market clinical follow-up impose overlapping data collection obligations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stent-Assisted Coiling Market |
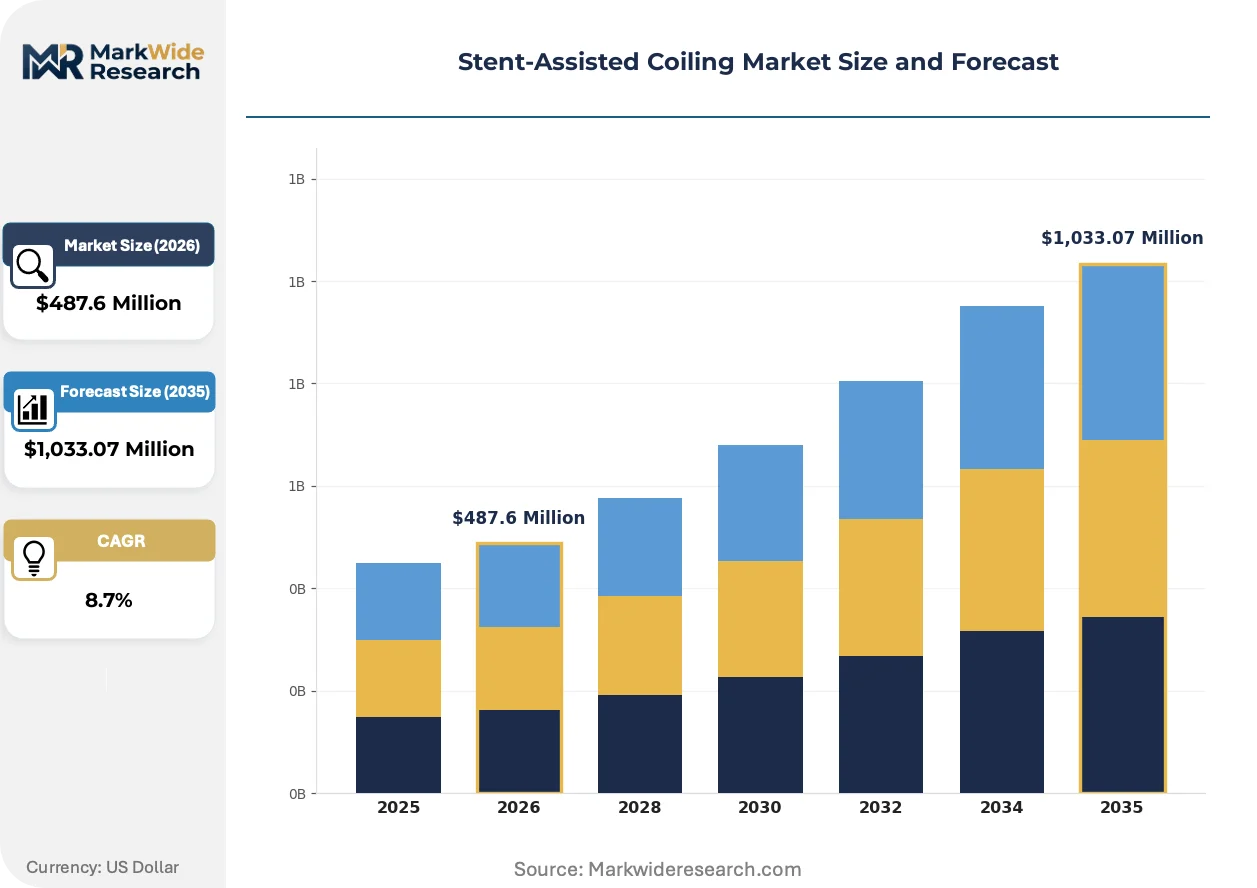
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Expanding Stents, Balloon-Expandable Stents, Microcoils, Delivery Systems End User: Hospitals, Outpatient Surgery Centers, Specialty Clinics, Academic Medical Centers Procedure Type: Elective Procedures, Emergency Procedures, Diagnostic Procedures, Therapeutic Procedures Material: Stainless Steel, Nitinol, Polymer, Coated Materials |
| Companies Covered | Medtronic, Stryker Corporation, MicroPort Scientific Corporation, DePuy Synthes, OBEX Medical, Penumbra, Inc., Balt Extrusion, Abbott Laboratories, Terumo Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stent-Assisted Coiling Market Evolving Landscape
Endovascular aneurysm repair is experiencing material science and regulatory harmonization pressures that are compressing product development cycles and reshaping competitive entry barriers.
Self-expanding nitinol stents with engineered radial force profiles are electrifying adoption curves in academic medical centers. Neurovascular suites are replacing balloon-mounted systems at accelerated procurement cycles. The technology is electrifying market segmentation by enabling single-device treatment of previously complex wide-necked morphologies.
EU MDR post-market surveillance rules for intracranial implants are tightening clinical follow-up obligations. Manufacturers must now submit periodic safety update reports with real-world performance data. High-volume braided stent producers in Ireland and Switzerland are restructuring quality management systems to accommodate notified body inspection intensity.
Hospital procurement committees are consolidating vendor relationships around integrated stroke care platform contracts. Independent device distributors are losing shelf space to manufacturer-direct clinical specialist teams. This concentration is most visible in United States academic medical centers where value-analysis committees now mandate supply chain rationalization.
Stent-Assisted Coiling Market Segmentation
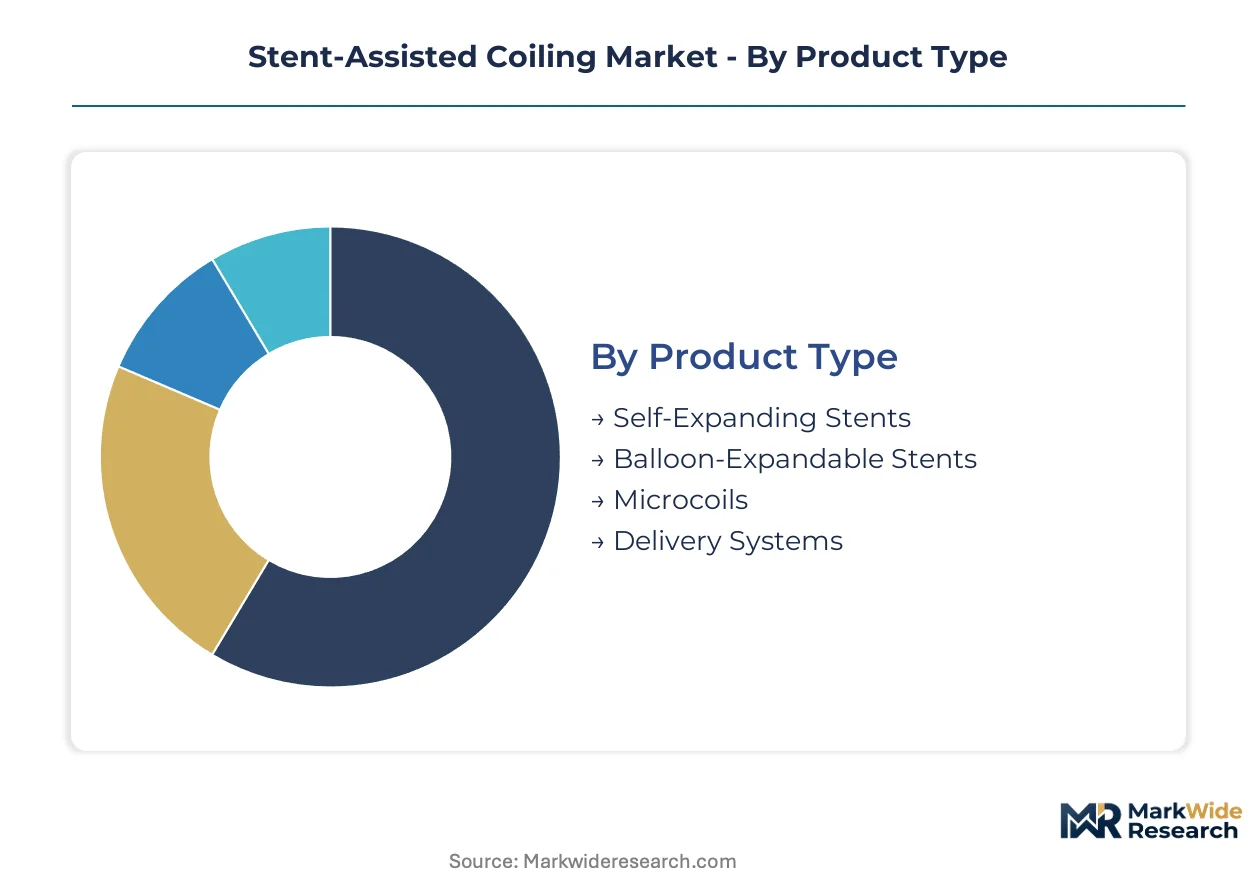
Segmentation in stent-assisted coiling reveals distinct procurement patterns across device architectures and care settings. Manufacturers must align product portfolios with the divergent technical requirements of emergency neurointervention versus scheduled elective repair.
Product Type:
Self-expanding stents operate as standalone scaffold systems, while balloon-expandable variants and microcoils embed within integrated delivery platforms requiring catheter compatibility.
- Self-Expanding Stents:Nitinol superelastic alloys engineered with radial force profiles resist foreshortening during deployment through tortuous cerebrovascular anatomy. Demand clusters in United States academic medical centers where stroke center certification mandates neurointerventional capability for wide-necked aneurysm repair.
- Balloon-Expandable Stents:Cobalt-chromium or stainless steel platforms mounted on angioplasty balloons enable precise diameter control at target vessel segments. Procurement concentrates in German university hospitals integrating these devices with hybrid operating suite infrastructure for complex bifurcation aneurysms.
- Microcoils:Platinum-tungsten filament constructs with synthetic fiber jackets promote thrombotic occlusion within the aneurysm sac.
- Delivery Systems:0.014-inch compatible microcatheters and guidewires enable stent and coil navigation through distal cerebrovascular territories.
Volume placements concentrate in self-expanding stents; the faster expansion belongs to microcoils as adjunctive embolization protocols standardize.
End User:
Cost tier stratification separates capital-intensive hospital installations from leaner outpatient facility models with lower per-procedure overhead.
- Hospitals:Comprehensive stroke centers maintain 24/7 neurointerventional coverage with dedicated biplane angiography suites and ICU step-down capacity. These institutions in Japan absorb the majority of emergency aneurysm rupture cases under national health insurance reimbursement frameworks.
- Outpatient Surgery Centers:Ambulatory facilities with neurointervention certification perform elective unruptured aneurysm repairs on same-day discharge protocols. Growth accelerates in United States metropolitan markets where certificate-of-need restrictions on hospital expansion redirect volume to licensed ASC networks.
- Specialty Clinics:Focused cerebrovascular practices concentrate high-volume operators achieving superior outcomes through procedural repetition.
- Academic Medical Centers:Teaching hospitals balance clinical service with fellowship training pipelines and device trial enrollment.
Revenue gravity sits with hospitals; outpatient surgery centers are climbing the fastest as regulatory certification spreads.
Procedure Type:
Application urgency dictates device selection, with emergency protocols favoring rapid-deployment self-expanding systems over precision-positioned alternatives.
- Elective Procedures:Scheduled unruptured aneurysm repairs allow preoperative imaging review and device sizing optimization. United States patients with commercial insurance coverage drive preference for flow-diverter and stent-assisted coiling over surgical clipping in eligible anatomies.
- Emergency Procedures:Ruptured aneurysm interventions demand immediate securing of the bleeding source, often with temporary balloon occlusion adjuncts. Japanese stroke centers achieve fastest door-to-puncture times through pre-hospital notification systems integrated with emergency medical services.
- Diagnostic Procedures:Cerebral angiography with possible intervention determines aneurysm morphology and treatment candidacy.
- Therapeutic Procedures:Definitive endovascular repair encompasses stent placement, coiling, or flow diversion as primary treatment modality.
Procedure volume concentrates in emergency interventions; elective scheduling is gaining share fastest as screening detection of unruptured aneurysms expands.
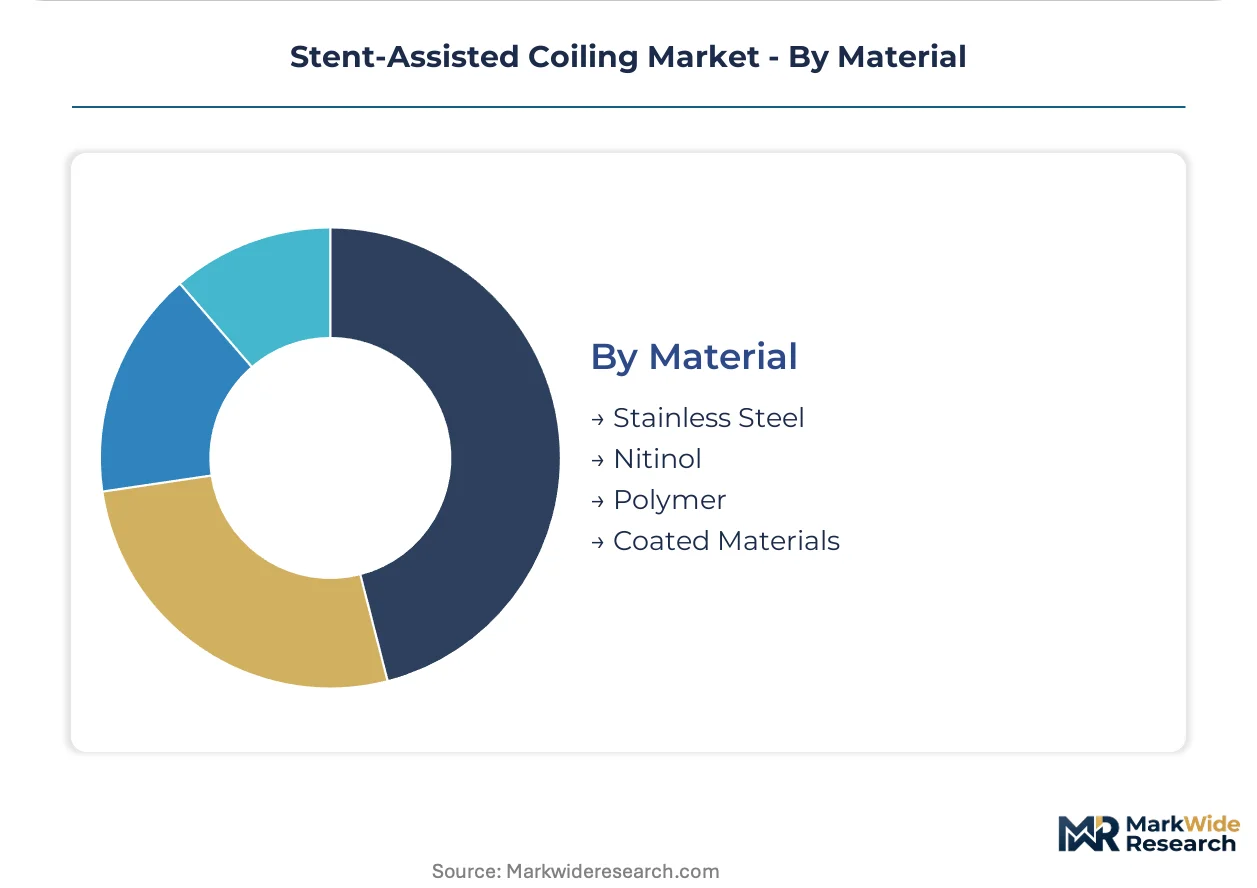
Material:
Supply concentration in nitinol forging and braided stent production creates geographic dependencies that shape material selection in device portfolios.
- Nitinol:Nickel-titanium superelastic alloys with Af temperature tuning enable reliable self-expansion at body temperature. Cleanroom production clusters in Ireland and Switzerland supply European and North American manufacturers with precision-woven stent constructs.
- Stainless Steel:316LVM grade provides corrosion resistance and radiopacity for balloon-expandable platforms at lower material cost. German device producers leverage regional precision metalworking supply chains for hypotube and stent laser-cutting operations.
- Polymer:Bioabsorbable and permanent polymer coatings modify thrombogenicity and endothelialization rates.
- Coated Materials:Drug-eluting and passive coatings address restenosis and thromboembolic complication risks.
Device unit economics favor nitinol; coated materials are expanding most quickly as manufacturers differentiate through surface modification technologies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nitinol forging and braided stent production clusters in Ireland and Switzerland anchor European supply chains, while end-use demand concentrates in stroke center networks across the United States, Germany, and Japan.
United States
Comprehensive stroke center certification programs are expanding institutional demand for neurointerventional suites. FDA 510(k) and PMA pathways govern market access with tightening clinical evidence requirements. Minneapolis anchors Medtronic's integrated supply chain operations alongside Galway production capacity.
Germany
University hospital procurement concentrates in hybrid operating suite infrastructure for complex bifurcation aneurysm repair. EU MDR notified body involvement and post-market surveillance rules are restructuring quality management systems. Precision metalworking supply chains in Baden-Württemberg support hypotube and stent laser-cutting operations.
Japan
National health insurance reimbursement frameworks absorb the majority of emergency aneurysm rupture cases. PMDA enforces QMS ordinance compliance plus mandatory adverse event reporting for intravascular implants. Tokyo metropolitan stroke centers achieve fastest door-to-puncture times through pre-hospital notification integration.
China
Tier-one hospital stroke centers are scaling domestic distribution channel penetration for elective unruptured aneurysm repairs. NMPA regulatory pathways for intracranial implants require clinical trial data and manufacturing quality system audits. Shanghai-based MicroPort Scientific Corporation dominates domestic procurement committee relationships.
Switzerland
Cleanroom production capacity for braided nitinol stents is expanding to serve European and North American device manufacturers. Swissmedic oversight aligns with EU MDR conformity assessment procedures for intracranial implant systems. Geneva and Basel regions concentrate precision weaving and superelastic alloy processing infrastructure.
Stent-Assisted Coiling Market Competitive Landscape
Global majors compete with regional champions across integrated stroke care platform contracts and specialized neurovascular R&D footprints. The vendor base organizes around three tiers: diversified medical technology conglomerates with neurovascular divisions, pure-play cerebrovascular device specialists, and emerging Asia-Pacific manufacturers leveraging domestic hospital relationships. Strategic moves concentrate on supply chain rationalization through direct clinical specialist teams and backward integration into nitinol forging capacity.
Within the diversified technology tier, Medtronic plc and Stryker Corporation exemplify integrated platform strategies spanning Galway-to-Minneapolis supply chain coordination and Fremont-based neurovascular R&D anchoring. MicroPort Scientific Corporation occupies a position among Asia-Pacific specialists capitalizing on tier-one hospital stroke center penetration. These three represent distinct archetypes: the transatlantic integrated supply chain operator, the concentrated R&D facility anchor, and the domestic distribution channel dominator.
| Leading Market Players |
|---|
| Medtronic |
| Stryker Corporation |
| MicroPort Scientific Corporation |
| DePuy Synthes |
| OBEX Medical |
| Penumbra, Inc. |
| Balt Extrusion |
| Abbott Laboratories |
| Terumo Corporation |
| Others |
Value Network & Pricing Analysis
Hospital value-analysis committee consolidation around integrated stroke care platform contracts is compressing vendor margins and forcing manufacturers to unbundle service components from device pricing. This procurement shift is reshaping how stent-assisted coiling systems are costed, with clinical specialist support and training now frequently priced separately from the nitinol scaffold and delivery system.
Pricing Analysis
Warranty and post-market surveillance service bundling separates premium-tier manufacturers from economy competitors in stent-assisted coiling procurement. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by FDA PMA pathway completion versus 510(k) clearance status and geographic service coverage. Cost compression in the standard tier is intensifying because EU MDR clinical evidence requirements are elevating quality system investments. Academic medical centers in the United States demonstrate lowest price sensitivity due to bundled platform contracting, while outpatient surgery centers in metropolitan markets exhibit highest sensitivity to unbundled device pricing.
Supply Chain Analysis
Domestic-content mandates in China's NMPA regulatory framework are reshaping sourcing patterns for multinational manufacturers serving tier-one hospital stroke centers. Cleanroom production capacity clusters in Ireland, Switzerland, and Germany, with braided nitinol stent forging and precision weaving operations concentrated in Galway and Basel regions. Raw material dependencies center on nickel-titanium alloy feedstock, platinum-tungsten coil filament, and cobalt-chromium hypotube stock. Single-source vulnerability runs through the limited qualified suppliers of superelastic nitinol with Af temperature specifications tuned for cerebrovascular deployment. Distribution runs through manufacturer-direct clinical specialist teams rather than independent distributors in United States academic medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Stent-assisted coiling market consolidation is accelerating as EU MDR compliance costs and FDA PMA pathway investments force sub-scale manufacturers toward exit or acquisition. Regulatory evidence requirements are functioning as a structural filter, advantaging integrated platform operators with Galway-to-Minneapolis supply chain coordination over pure-play device specialists.
For Market Incumbents: Deepen backward integration into nitinol forging capacity to secure supply continuity against braided stent production concentration in Ireland and Switzerland. Expand clinical specialist headcount in United States academic medical centers to defend against hospital procurement committee vendor consolidation. Prioritize MDR transition completion ahead of 2025 notified body deadlines to capture competitor displacement volume. For New Entrants and Emerging Players: Outpatient surgery centers in United States metropolitan markets with certificate-of-need restrictions represent the most penetrable buyer archetype for stent-assisted coiling system entry. Elective unruptured aneurysm repair protocols in these facilities require lower capital intensity than comprehensive stroke center infrastructure. Target go-to-market positioning through GPO contracts and value-analysis committee relationships rather than direct hospital sales. For Investors and Strategic Acquirers: The window for entry favors Asia-Pacific specialists with established NMPA regulatory pathways and domestic distribution channel control in China's tier-one hospital networks. Long-term viability in stent-assisted coiling hinges on reimbursement strategy execution across national health insurance frameworks. Monitor Japan PMDA adverse event reporting trends as an inflection indicator for device safety profile differentiation.| Strategic Initiative | Industry Significance |
|---|---|
| FDA PMA Pathway Completion | Premarket approval unlocks wide-necked aneurysm indications beyond 510(k) scope in United States stroke centers. |
| EU MDR Notified Body Certification | Conformity assessment enables continued European market access for intracranial stent systems post-transition. |
| Hospital System Partnership | Integrated stroke care platform contracts with academic medical centers secure multi-year volume commitments. |
| Software Companion Development | Preoperative aneurysm sizing and stent selection algorithms differentiate device portfolios in procurement evaluations. |
| Reimbursement Strategy | CPT code optimization for stent-assisted coiling procedures determines commercial viability across Medicare and private payer networks. |
Research Methodology
FDA 510(k) and PMA filings, EU MDR notified body certification databases, and hospital procurement contract records formed the secondary backbone of this analysis. Primary interviews with neurointerventionalists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers validated device adoption patterns and pricing dynamics. Bottom-up and top-down triangulation across segmentation dimensions ensured consistency between manufacturer shipment data and end-use demand estimates.
Bottom-up modeling anchored volume projections to hospital stroke center certification expansion and procedural volume trends, while top-down analysis cross-checked against macroeconomic healthcare expenditure patterns. Segmentation across product type, end user, procedure urgency, and material formulation informed the analytical framework over the projection horizon. CAGRs were derived from fitted growth curves incorporating regulatory timeline impacts and reimbursement decision trajectories specific to neurointerventional device markets.
Revisions become necessary when EU MDR enforcement intensity, FDA PMA review duration, or nitinol supply chain disruptions materialize outside baseline assumptions. Forecasts reflect documented expectations regarding stroke center certification program expansion and adverse event reporting harmonization across PMDA and European frameworks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
India Coronary Stent Market
Cardiovascular Devices
Vascular Access Systems Market
Cardiovascular Devices
Global Vascular Injury Treatment Market
Cardiovascular Devices
Self-Expanding Stents Market
Cardiovascular Devices
Mobile Cardiac Telemetry Device Market
Cardiovascular Devices
Europe Heart Valve Repair and Replacement Market
Cardiovascular Devices
Arterial Cannula Market
Cardiovascular Devices
Global Non-Vascular Stents Market
Cardiovascular Devices
United Kingdom Cardiovascular Devices Market
Cardiovascular Devices
Global Intravascular Catheters Market
Cardiovascular Devices
Arterial Stabilization Device Market
Cardiovascular Devices
Cardiac Rhythm Management Devices Market
Cardiovascular Devices
Fractional Flow Reserve-Computed Tomography (FFR-CT) Market
Cardiovascular Devices
Cardiac Valve Market
Cardiovascular Devices
Cardiovascular Prosthetic Devices Market
Cardiovascular Devices
Arrhythmogenic Right Ventricular Dysplasia Treatment Market