
 Absorbable Antibacterial Envelope Market | 2026-2036
Absorbable Antibacterial Envelope Market Size, Share, and Industry Trends Forecast 2026-2036
Absorbable Antibacterial Envelope Market Outlook
Hospital buying consortium consolidation in North America is expanding as integrated delivery networks centralize cardiac rhythm management procurement. Medtronic plc leverages its electrophysiology ecosystem to bundle envelope offerings with device implants. Aziyo Biologics, Inc. specializes in bioresorbable antimicrobial formulations that differentiate its portfolio from permanent synthetic alternatives. Stryker Corporation sustains orthopedic-to-cardiovascular crossover capabilities that anchor its surgical infection prevention division.
An absorbable antibacterial envelope is a bioresorbable mesh or pouch, typically incorporating antibiotics such as rifampin and minocycline, engineered to elute antimicrobial agents locally around implanted cardiac devices before fully degrading within weeks to months. Its primary purpose centers on reducing pocket infections following pacemaker or defibrillator implantation without requiring secondary removal surgery. Polymer-based envelopes currently dominate commercial volumes due to established manufacturing scalability and predictable degradation profiles. Implantable delivery mode categories exhibit the fastest structural expansion as surgeons prefer site-specific placement over topical or injectable alternatives that lack sustained tissue concentration.
FDA enforces premarket notification and quality system regulation under 21 CFR Part 820 for absorbable antimicrobial device accessories, while EMA MDR requirements now mandate clinical evidence for bioresorbable antimicrobial claims across European member states. The FDA's breakthrough devices program accelerates review timelines for novel infection prevention technologies, directly shaping competitive entry sequencing. Stakeholders must monitor evolving CMS transitional pass-through payment status for antibacterial envelopes and corresponding NICE technology appraisal pathways in England to anticipate reimbursement-driven demand inflections.
Market Dynamics
Hospital procurement consolidation is compressing vendor margins as integrated delivery networks leverage volume to extract standardized pricing for cardiac device accessories across multi-hospital systems.
Growth Catalysts
- CMS Transitional Pass-Through Payments:The Centers for Medicare & Medicaid Services reimbursement framework for novel infection prevention technologies accelerates hospital adoption of absorbable antibacterial envelopes in the United States.
- Bioresorbable Polymer Advancements:Controlled-release kinetics from synthetic absorbable polymers enable sustained antimicrobial elution profiles that outperform conventional topical prophylaxis in cardiac implantation settings.
- Electrophysiology Procedure Volumes:Germany, Japan, and the United States exhibit concentrated demand expansion as aging populations drive pacemaker and implantable cardioverter-defibrillator implantation rates.
Market Restraints
- Rifampin Supply Concentration:Active pharmaceutical ingredient sourcing for this critical envelope component concentrates among a limited set of contract manufacturers, exposing production continuity to geopolitical disruption.
- EMA MDR Clinical Evidence Requirements:The European Medical Device Regulation mandates costly post-market clinical follow-up studies for bioresorbable antimicrobial claims, extending commercialization timelines across EU member states.
- Permanent Synthetic Mesh Substitutes:Non-absorbable antimicrobial pouches retain entrenched positions in cost-sensitive hospital procurement categories where reoperation risk is deemed acceptable.
Strategic Opportunities
- Japan's PMDA Sakigake Pathway:Japan's regulator offers prioritized consultation and accelerated review timelines for novel infection prevention devices, creating early-mover advantages for envelope developers targeting the Asia-Pacific's second-largest cardiac device market.
- Subcutaneous Implantable Cardioverter-Defibrillator Expansion:Leadless and subcutaneous device formats generate demand for adapted envelope geometries that accommodate alternative implantation sites without pocket formation.
- Direct-to-Hospital Contracting:Bypassing traditional distributor markups through established vendor credentialing programs captures margin expansion in consolidated IDN environments.
Industry Challenges
- Sterilization Validation Complexity:Ethylene oxide residual limits and novel sterilization modality qualification timelines extend regulatory submission preparation for bioresorbable polymer formulations.
- Electrophysiology Device Integration:Surgeon workflow adaptation requires training programs that harmonize envelope placement techniques with varying pacemaker and defibrillator form factors across manufacturer portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Absorbable Antibacterial Envelope Market |
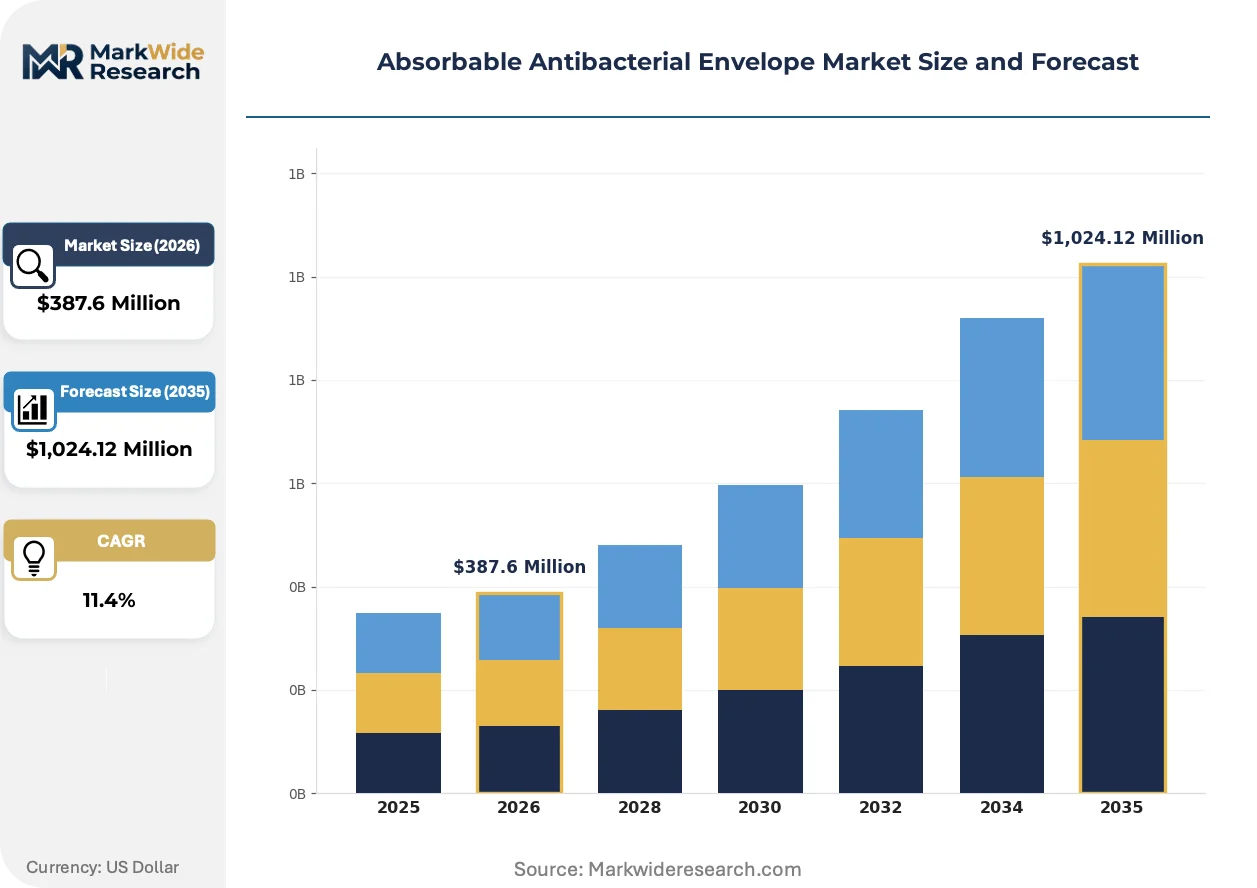
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer-based, Hydrogel, Composite, Membrane End User: Hospitals, Surgical Centers, Clinics, Research Labs Application: Wound Care, Surgical Procedures, Infection Prevention, Biodegradable Solutions Delivery Mode: Topical, Injectable, Implantable, Transdermal |
| Companies Covered | Medtronic plc, Aziyo Biologics, Inc., Stryker Corporation, Ethicon, Smith & Nephew, B. Braun Melsungen AG, Boston Scientific Corporation, Zimmer Biomet, Acelity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Absorbable Antibacterial Envelope Market Strategic Shifts
Antimicrobial delivery mechanisms are converging with cardiac rhythm management workflows as manufacturers engineer site-specific infection prevention into standard implantation protocols rather than adjunctive procedures.
Dual-antibiotic-loaded absorbable polymers are overtaking single-agent formulations in commercial development pipelines. Rifampin-minocycline combinations target gram-positive biofilm formation while addressing polymicrobial contamination risks. Electrophysiology-focused medical device manufacturers are integrating these envelopes into bundled procedural offerings. This convergence is compressing standalone envelope vendor margins while elevating ecosystem control by integrated cardiac device suppliers.
EMA Medical Device Regulation harmonization with FDA Quality System Regulation under 21 CFR Part 820 is reshaping clinical evidence standards for antimicrobial device accessories. European notified bodies now demand prospective infection rate data comparable to pharmaceutical trials. Bioresorbable envelope developers are responding with parallel US-EU clinical study designs that satisfy both FDA premarket notification and EMA MDR requirements through unified trial infrastructure.
Surgeon preference for site-specific antimicrobial delivery is displacing perioperative systemic prophylaxis as the default infection prevention protocol in high-volume cardiac implantation centers. Hospital pharmacy and therapeutics committees in Germany and Japan are revising standard order sets to incorporate absorbable envelopes into bundled payment calculations. This behavioral shift concentrates demand among academic medical centers with established electrophysiology fellowship programs where training standardization accelerates protocol adoption.
Absorbable Antibacterial Envelope Market Segmentation
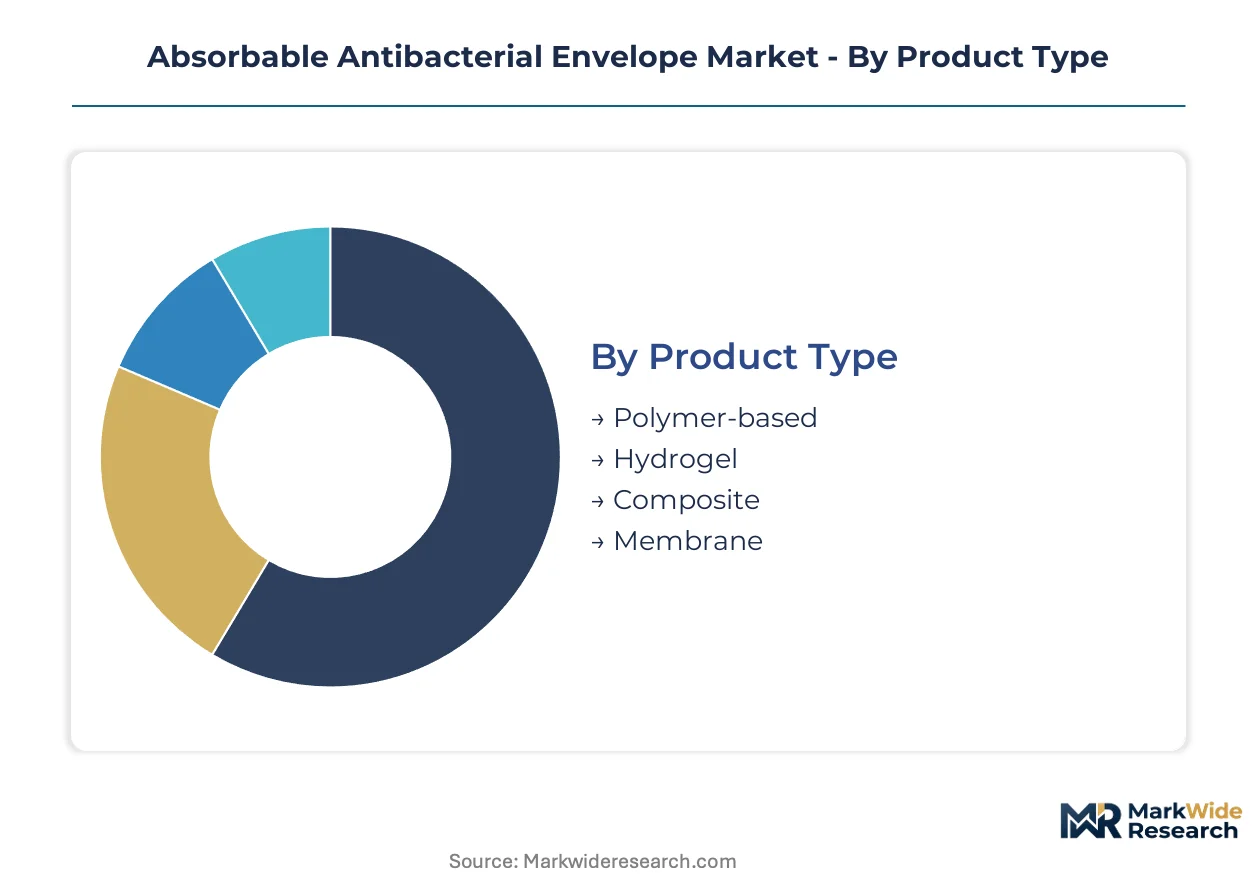
Segmentation in the absorbable antibacterial envelope market reveals how material science, clinical workflow, and procurement economics intersect. Manufacturers must align polymer formulations with specific implantation protocols while navigating hospital formulary constraints across cardiac rhythm management settings.
Product Type:
Supply concentration in polymer raw materials and specialized manufacturing equipment shapes competitive positioning across material categories.
- Polymer-based:Synthetic absorbable polymers such as polylactic acid and polyglycolic acid dominate commercial volumes due to predictable degradation timelines and established extrusion manufacturing. Demand concentrates in the United States where FDA 510(k) pathways for polymer-based antimicrobial devices are most mature, though rifampin-minocycline loading consistency remains a formulation challenge for contract manufacturers.
- Hydrogel:Water-swollen polymer networks enable conformable tissue interface and tunable antibiotic release kinetics that surpass rigid mesh alternatives in complex anatomical pockets. Germany's university hospitals are driving adoption as EMA MDR clinical evidence requirements favor hydrogel's demonstrable tissue integration profiles in post-market surveillance studies.
- Composite:Hybrid architectures combining polymer scaffolds with ceramic or metallic phases for structural reinforcement during enzymatic degradation.
- Membrane:Ultra-thin barrier formulations optimized for leadless device geometries and minimal pocket formation.
Today's leader: Polymer-based. Tomorrow's challenger: Hydrogel.
End User:
Procurement authority and infection prevention budgets vary sharply across facility types, creating tiered pricing structures that reflect scale and specialization.
- Hospitals:Integrated delivery networks in the United States and Germany command standardized pricing through centralized cardiac device procurement committees. Academic medical centers with electrophysiology fellowship programs drive protocol standardization, while community hospitals lag in envelope adoption due to lower implantation volumes and constrained pharmacy budgets.
- Surgical Centers:Ambulatory settings in Japan are gaining PMDA Sakigake pathway approvals for same-day cardiac device procedures, though reimbursement complexity limits envelope penetration compared to institutional settings.
- Clinics:Office-based electrophysiology practices with limited sterile processing capabilities.
- Research Labs:Preclinical and clinical trial sites generating pharmacokinetic data for regulatory submissions.
Hospitals capture the dominant revenue share. Surgical centers are climbing the fastest as ambulatory reimbursement frameworks mature.
Application:
Volume distribution across applications reflects the underlying procedure mix and infection risk stratification protocols in cardiac implantation centers.
- Infection Prevention:Prophylactic envelope placement around pacemakers and implantable cardioverter-defibrillators represents the core commercial application, with demand anchored in high-volume electrophysiology departments. Japan's aging population and established device reimbursement are expanding this segment most quickly among Asia-Pacific markets.
- Surgical Procedures:Cardiac resynchronization therapy upgrades and generator replacements generate recurring envelope demand, particularly in German hospitals where bundled payment models incentivize infection avoidance.
- Wound Care:Secondary applications in non-cardiac surgical sites with elevated contamination risk.
- Biodegradable Solutions:Emerging applications leveraging complete resorption to eliminate foreign body response.
Infection prevention commands current volumes. Surgical procedures present the steepest expansion trajectory as replacement cycles accelerate.
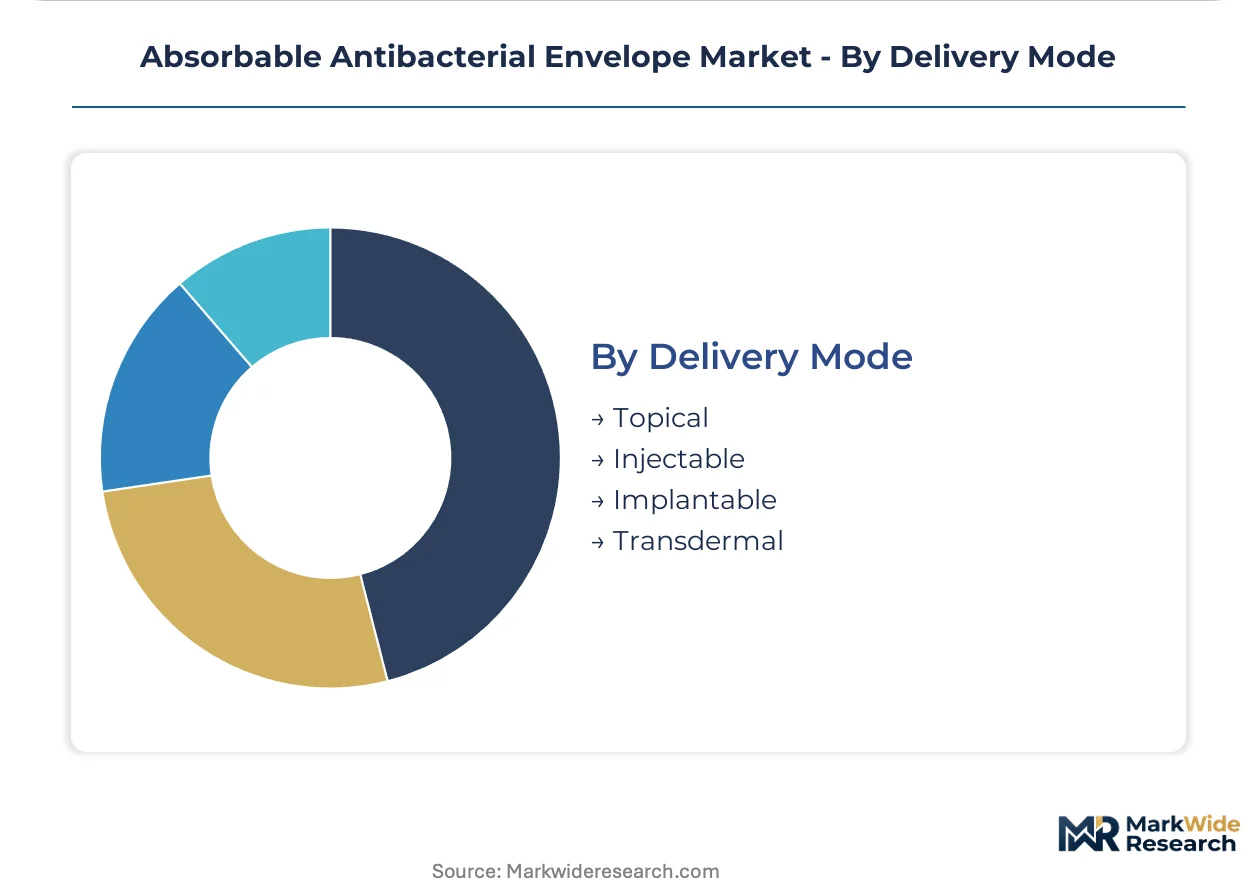
Delivery Mode:
Surgeon workflow integration and sustained tissue antibiotic concentration determine modality selection in cardiac device implantation protocols.
- Implantable:Site-specific pouch or mesh placement directly adjacent to device generators delivers localized rifampin-minocycline elution that systemic prophylaxis cannot replicate. The United States leads implantable adoption as CMS transitional pass-through payments offset acquisition costs, with Germany and Japan following as corresponding reimbursement frameworks mature.
- Topical:Intraoperative irrigation and pocket lavage remain standard of care in cost-sensitive settings despite inferior biofilm prevention.
- Injectable:Antibiotic-loaded hydrogel depots for minimally adapted implantation workflows.
- Transdermal:Percutaneous antibiotic delivery systems for specific device geometries.
Implantable modes anchor clinical preference. Injectable formats are gaining share fastest as leadless and subcutaneous device formats proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's bundled payment models for cardiac procedures contrast with Japan's PMDA Sakigake accelerated review pathway, illustrating how reimbursement architecture and regulatory velocity shape divergent adoption curves across major markets.
United States
CMS transitional pass-through payments offset acquisition costs for hospital systems performing high-volume electrophysiology procedures. FDA breakthrough device designation pathways compress review timelines for novel infection prevention technologies. The Cleveland Clinic and Mayo Clinic anchor protocol standardization efforts that diffuse through integrated delivery network procurement committees.
Germany
University hospitals in Bavaria and North Rhine-Westphalia drive hydrogel envelope adoption as EMA MDR clinical evidence requirements favor demonstrable tissue integration profiles. Bundled payment models for cardiac resynchronization therapy incentivize infection avoidance. Berlin's Charité and Munich's university hospital cluster generate post-market surveillance data that satisfies notified body demands.
Japan
Aging demographics accelerate pacemaker and defibrillator implantation volumes beyond other Asia-Pacific markets. PMDA Sakigake prioritized consultation pathways reward early-mover developers with accelerated review timelines. Tokyo and Osaka metropolitan medical centers concentrate electrophysiology fellowship programs that standardize envelope placement protocols.
Switzerland
Swissmedic's convergence with EMA MDR requirements streamlines market access for bioresorbable antimicrobial claims. Basel's pharmaceutical-industrial complex supplies active pharmaceutical ingredients for rifampin-minocycline formulations. Zurich's university hospital network participates in parallel US-EU clinical study designs.
United Kingdom
NICE technology appraisal pathways determine reimbursement-driven demand inflections for antibacterial envelopes in England. London's Imperial College Healthcare and Guy's and St Thomas' NHS Foundation Trust anchor clinical evidence generation for EMA MDR compliance. Scotland's health technology assessment processes lag England's adoption velocity.
Absorbable Antibacterial Envelope Market Competitive Environment
United States producers anchor one tier; European specialists hold differentiated positions through regulatory alignment. The vendor base concentrates among integrated cardiac device suppliers and standalone bioresorbable material developers. Three archetypes dominate: electrophysiology ecosystem bundlers, bioresorbable polymer specialists, and orthopedic-to-cardiovascular crossover manufacturers. M&A activity targets antimicrobial formulation capabilities, while direct-to-hospital contracting programs bypass traditional distributor markups.
Within the integrated device supplier tier, Medtronic plc exemplifies ecosystem bundling strategies that compress standalone envelope margins. Aziyo Biologics, Inc. occupies the bioresorbable antimicrobial formulation specialist position. Stryker Corporation represents orthopedic-to-cardiovascular crossover capabilities that anchor surgical infection prevention divisions. These three entities collectively illustrate the competitive tension between full-line cardiac device suppliers and focused material science developers.
| Leading Market Players |
|---|
| Medtronic plc |
| Aziyo Biologics, Inc. |
| Stryker Corporation |
| Ethicon |
| Smith & Nephew |
| B. Braun Melsungen AG |
| Boston Scientific Corporation |
| Zimmer Biomet |
| Acelity |
| Others |
Value Chain & Pricing Dynamics
Rifampin active pharmaceutical ingredient price indices cascade through contract manufacturing tiers into three distinct envelope pricing strata. Hospital procurement committees in the United States and Germany exploit volume concentration to compress margins at the standard tier while premium hydrogel formulations retain pricing power through EMA MDR clinical evidence requirements.
Pricing Analysis
Capacity additions in China and India are reshaping price floors for polymer raw materials while rifampin-minocycline formulation complexity sustains premium tiers. Three-tier pricing structure across premium, standard, and economy levels reflects FDA breakthrough designation status versus 510(k) clearance pathways. Cost compression in the standard tier is intensifying because integrated delivery networks centralize cardiac device accessory procurement. Community hospitals in Japan exhibit highest price sensitivity, while academic medical centers in Germany prioritize clinical evidence over acquisition cost.
Supply Chain Analysis
Rifampin active pharmaceutical ingredient supply rests on Swiss and Indian contract manufacturers with limited qualified alternative sources. Synthetic absorbable polymers draw from established extrusion facilities in the United States and Germany, while hydrogel precursor chemicals hinge on Japanese specialty chemical producers. Single-source vulnerability concentrates in rifampin API qualification batches required for FDA premarket notification. Distribution runs through GPO contracts and direct-to-hospital vendor credentialing programs that bypass traditional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in the absorbable antibacterial envelope market derives from bioresorbable polymer formulation cost-down curves and premium-tier clinical evidence differentiation. Hospital procurement consolidation creates volume leverage that rewards scale players with sustainable margin structures.
For Market Incumbents: To counter hydrogel envelope entrants in German university hospitals, deepen backward integration into rifampin API sourcing through captive supply agreements with Swiss manufacturers. Anchor channel control through exclusive GPO contracts with integrated delivery networks performing high-volume electrophysiology procedures. For New Entrants and Emerging Players: The premium-to-economy price-point gap in Japan's PMDA Sakigake pathway presents white-space opportunity for mid-tier polymer-based formulations. Target ambulatory surgical centers in Osaka and Tokyo metropolitan clusters with simplified envelope geometries for leadless device formats. For Investors and Strategic Acquirers: Asymmetric upside sits with bioresorbable antimicrobial formulation specialists possessing parallel FDA-EMA clinical study infrastructure. Over the projection horizon, acquisition targets should demonstrate completed post-market surveillance satisfying EMA MDR requirements. Watch CMS transitional pass-through payment status extensions as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Accelerated review timelines compress competitive entry sequencing for novel infection prevention technologies. |
| EMA MDR Parallel Study Design | Unified clinical trial infrastructure satisfies both FDA premarket notification and European notified body demands. |
| Direct-to-Hospital Contracting | Vendor credentialing programs capture margin expansion in consolidated integrated delivery network environments. |
| Rifampin API Backward Integration | Captive supply agreements with Swiss manufacturers mitigate single-source vulnerability in critical antibiotic sourcing. |
| Subcutaneous Device Geometry Adaptation | Leadless and subcutaneous ICD expansion generates demand for adapted envelope formats without pocket formation. |
Study Parameters
Multiple input streams — electrophysiology department heads, hospital procurement committee members, biomedical engineers at GPO contract offices, and regulatory affairs leads at notified bodies — were reconciled against FDA 510(k) databases, EMA MDR submission records, CMS Medicare reimbursement files, and hospital procurement contract repositories. Bottom-up demand modeling from procedure volume data and top-down market sizing from manufacturer revenue disclosures were cross-validated to establish segmentation boundaries.
Historical infection rate trends from Cleveland Clinic and Charité Berlin were cross-referenced against panel input from electrophysiology fellowship program directors. Segmentation dimensions modeled include material type, delivery mode, end-user facility tier, application protocol, and regional reimbursement framework cluster. CAGRs were derived from weighted average procedure volume trajectories and pricing elasticity assumptions specific to cardiac device accessory procurement.
Caveats apply where PMDA Sakigake pathway timeline revisions or CMS pass-through payment discontinuations could materially shift the outlook. Forecasts reflect assumptions about regulatory convergence velocity and hospital procurement consolidation pace. A small set of named triggers — rifampin supply disruption, EMA MDR clinical evidence requirement escalation, and subcutaneous ICD format adoption curves — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Smart Wearable Healthcare Devices Market
Medical Devices
Annuloplasty Rings Market
Medical Devices
IV Fluid Monitoring Device Market
Medical Devices
Rectal Catheters Market
Medical Devices
Injectable Drug Delivery Market
Medical Devices
Asia Pacific Veterinary Equipment and Disposables Market
Medical Devices
Russia Massage Equipment Market
Medical Devices
Cough Assist Devices Market
Medical Devices
IV Therapy and Vein Access Devices Market
Medical Devices
Incubator Devices Market
Medical Devices
Intravaginal Device Market
Medical Devices
Corneal Surgery Devices Market
Medical Devices
Nerve Ablation Devices Market
Medical Devices
South Africa Minimally Invasive Surgical Devices Market
Medical Devices
Neurovascular Stent Market
Medical Devices
Anesthesia Face Masks Market