
 China Ophthalmic Devices Market | 2026-2036
China Ophthalmic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
China Ophthalmic Devices Market Outlook
Trained vitreoretinal surgeons is reorganizing provincial access to advanced interventions across central and western provinces. Alcon leverages its femtosecond laser platform to dominate premium cataract workflow integration in tier-one hospitals. Hoya Corporation anchors the intraocular lens supply chain through localized manufacturing partnerships in Suzhou. Carl Zeiss Meditec AG competes on diagnostic imaging density, positioning its OCT systems in ophthalmology residency training centers.
Ophthalmic devices comprise precision instruments for ocular diagnosis, surgical intervention, and vision correction, typically operating within wavelength-specific laser parameters and micron-scale positioning tolerances for tissue safety. These systems serve the primary commercial purpose of restoring, preserving, or enhancing visual function across outpatient and surgical settings. Diagnostic Equipment leads product type revenue contribution due to replacement cycles driven by imaging resolution upgrades, while Intraocular Lenses capture expanding margin pools as multifocal and toric designs displace monofocal standards in urban hospitals. Eye Clinics represent the fastest-growing end user channel as regulatory clarity on outpatient surgery licensing enables chain expansion beyond traditional hospital dominance.
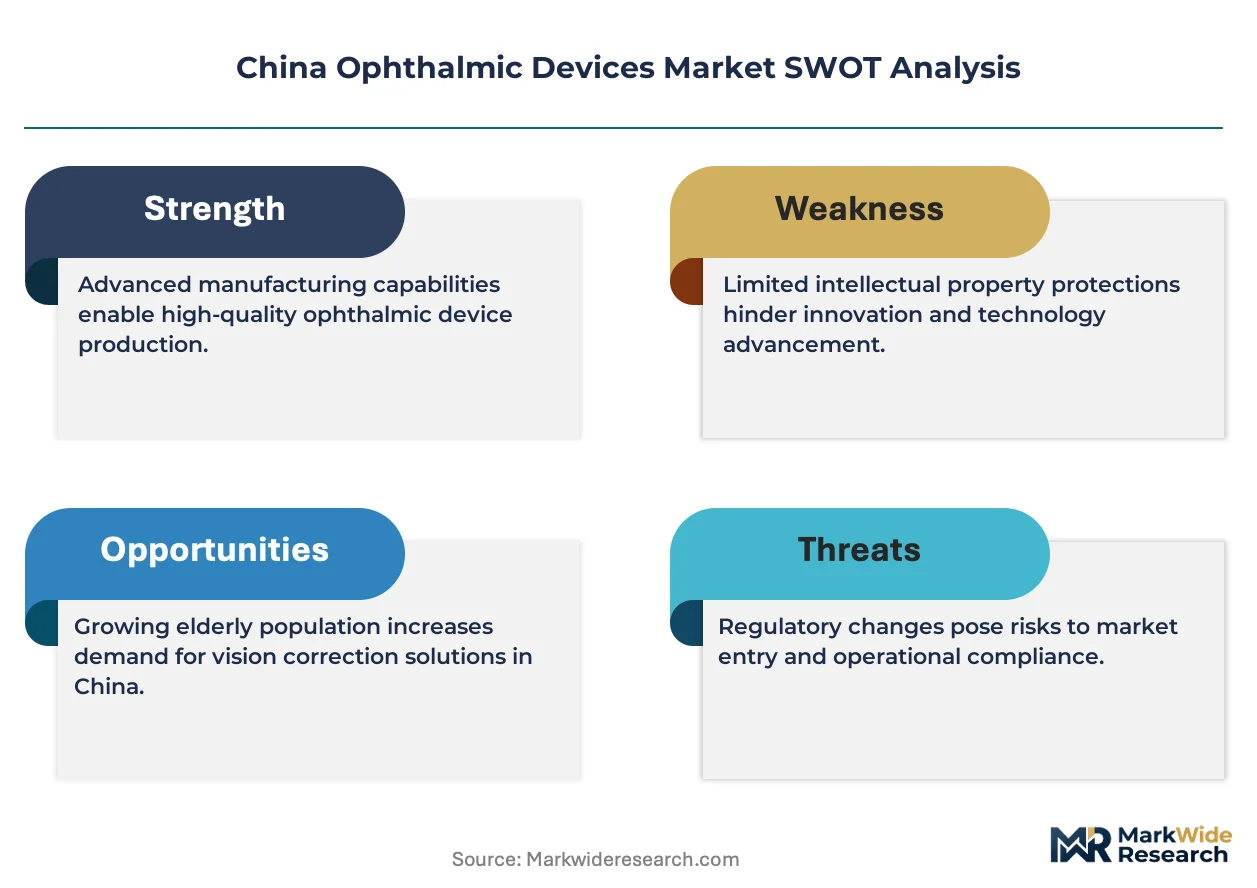
NMPA Class III medical device registration requirements and GB standards for ophthalmic laser safety shape product entry timelines and clinical trial obligations for imported systems. The national dual carbon goals pressure manufacturers to redesign sterilization and packaging workflows for domestic production facilities. Stakeholders must monitor how provincial centralized procurement pilots for intraocular lenses reshape pricing power and channel economics across public hospital networks.
Market Dynamics
Provincial centralized procurement pilots for intraocular lenses are compressing pricing power across public hospital networks and forcing manufacturers to restructure channel economics around volume guarantees rather than premium positioning.
Growth Catalysts
- NMPA Class III streamlined review:The 2023 reform directive has collapsed registration timelines for imported femtosecond laser systems, accelerating market entry for advanced surgical platforms.
- Eye clinic chain licensing clarity:Regulatory frameworks enabling standalone outpatient surgery centers are unlocking private capital deployment beyond traditional hospital infrastructure.
- Yangtze River Delta cataract density:Shanghai and Hangzhou anchor premium procedure volumes that absorb high-margin diagnostic and surgical equipment at scale.
Market Restraints
- GB laser safety compliance costs:Domestic manufacturing facilities must redesign sterilization workflows to meet dual carbon goals, elevating facility capex for multinational assembly operations.
- Import dependency for optical components:Precision laser crystals and high-resolution sensors concentrate in German and Japanese supply bases, exposing OEMs to currency and logistics volatility.
- Monofocal IOL substitution pressure:Provincial procurement mandates favor standard single-vision lenses, limiting premium multifocal and toric penetration in price-controlled public tiers.
Strategic Opportunities
- Central and western provincial expansion:Trained vitreoretinal surgeons are reorganizing access corridors, creating first-mover advantage for equipment vendors establishing service networks in Chengdu and Xi'an.
- AI-assisted diagnostic convergence:Integration of machine learning with OCT image analysis is opening software-as-a-service revenue streams alongside hardware placements in residency training centers.
- Tier-two hospital network upgrades:Municipal hospital ophthalmology department expansions are absorbing advanced surgical platforms previously concentrated in tier-one academic centers.
Industry Challenges
- Vitreoretinal surgeon training pipelines:The four-year fellowship requirement creates bottlenecks that limit procedure volume scaling even where equipment is installed.
- NMPA clinical trial obligations:Imported Class III systems require domestic patient cohorts, extending time-to-revenue by 18-24 months against accelerated competitor registrations.
- Legacy hospital IT integration:Diagnostic imaging platforms must interface with fragmented hospital information systems, complicating deployment workflows and elevating implementation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Ophthalmic Devices Market |
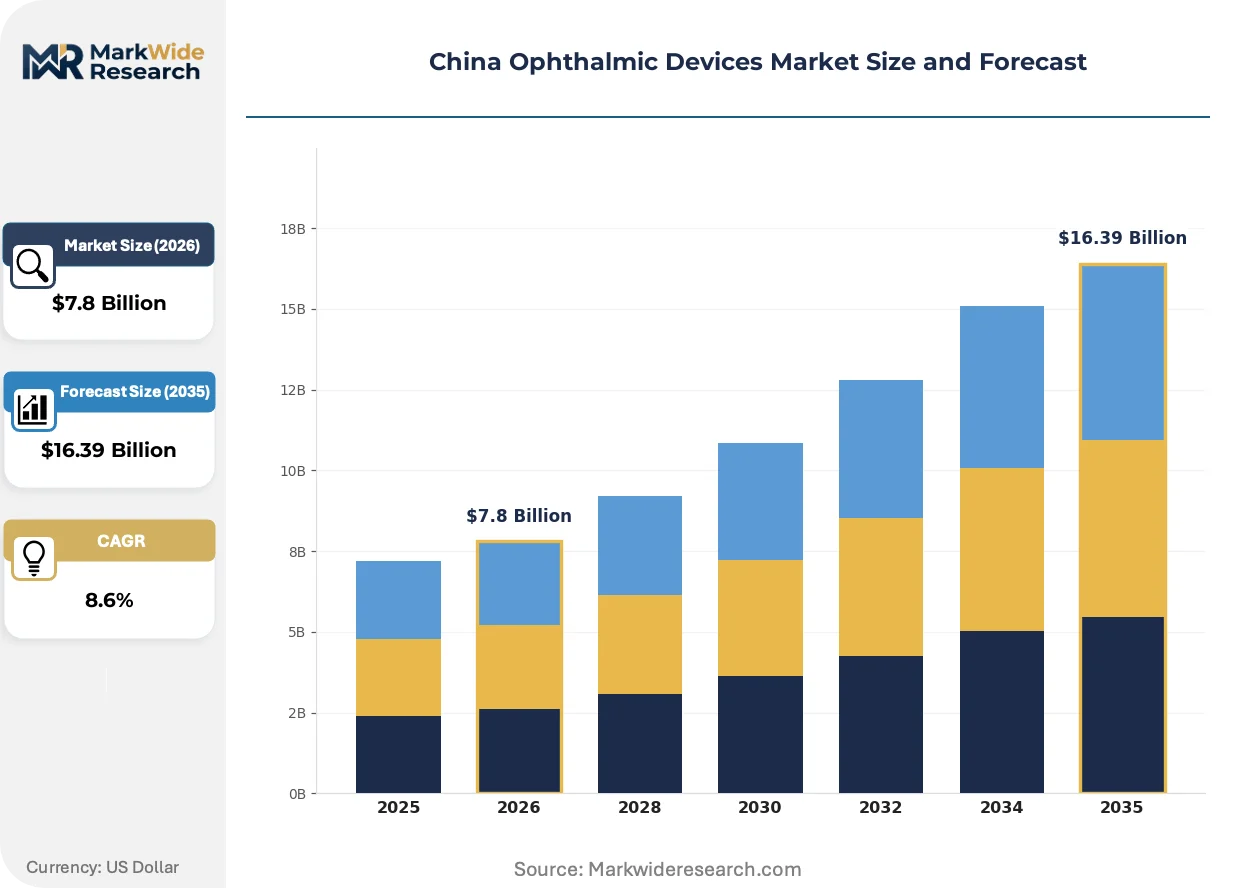
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $16.39 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intraocular Lenses, Ophthalmoscopes, Retinal Lasers, Diagnostic Equipment End User: Hospitals, Eye Clinics, Ambulatory Surgical Centers, Home Care Technology: Laser Surgery, Refractive Surgery, Visual Field Testing, Imaging Technology Application: Cataract Treatment, Glaucoma Surgery, Vision Correction, Eye Examination |
| Companies Covered | Bausch Health Companies Inc, Nidek Co Ltd, Alcon, Ziemer Group AG, Topcon Corporation, Johnson & Johnson, Hoya Corporation, Lumenis, Carl Zeiss Meditec AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Ophthalmic Devices Market Strategic Shifts
Optical coherence tomography hardware is compressing form factors while expanding diagnostic capabilities, reshaping deployment patterns across outpatient and surgical environments.
Handheld OCT systems are miniaturizing retinal imaging from cart-based hospital installations to portable units deployable in community screening settings. Municipal eye clinics in Jiangsu and Zhejiang provinces are adopting these platforms for diabetic retinopathy detection at twice the pace of traditional desktop systems. The technology is miniaturizing capital requirements for diagnostic service expansion, enabling chain operators to scale footprint without proportional facility investment.
NMPA's 2023 medical device review reform has collapsed Class III registration timelines from 18 months to under 12 months for qualified submissions. This regulatory compression is accelerating competitive entry for imported laser platforms, forcing domestic manufacturers to accelerate R&D cycles to defend installed base positions. Ophthalmic surgical equipment categories face the most intense timeline pressure, with femtosecond laser systems now clearing review ahead of traditional phacoemulsification upgrades.
Public hospital procurement committees are consolidating vendor relationships around single-source maintenance contracts that bundle equipment, consumables, and technical service. This purchasing consolidation is displacing fragmented multi-vendor arrangements previously common in ophthalmology departments. The shift is most visible in Shanghai municipal hospital networks, where three-year total-cost-of-ownership contracts now dominate premium cataract workflow tenders.
China Ophthalmic Devices Market Segmentation
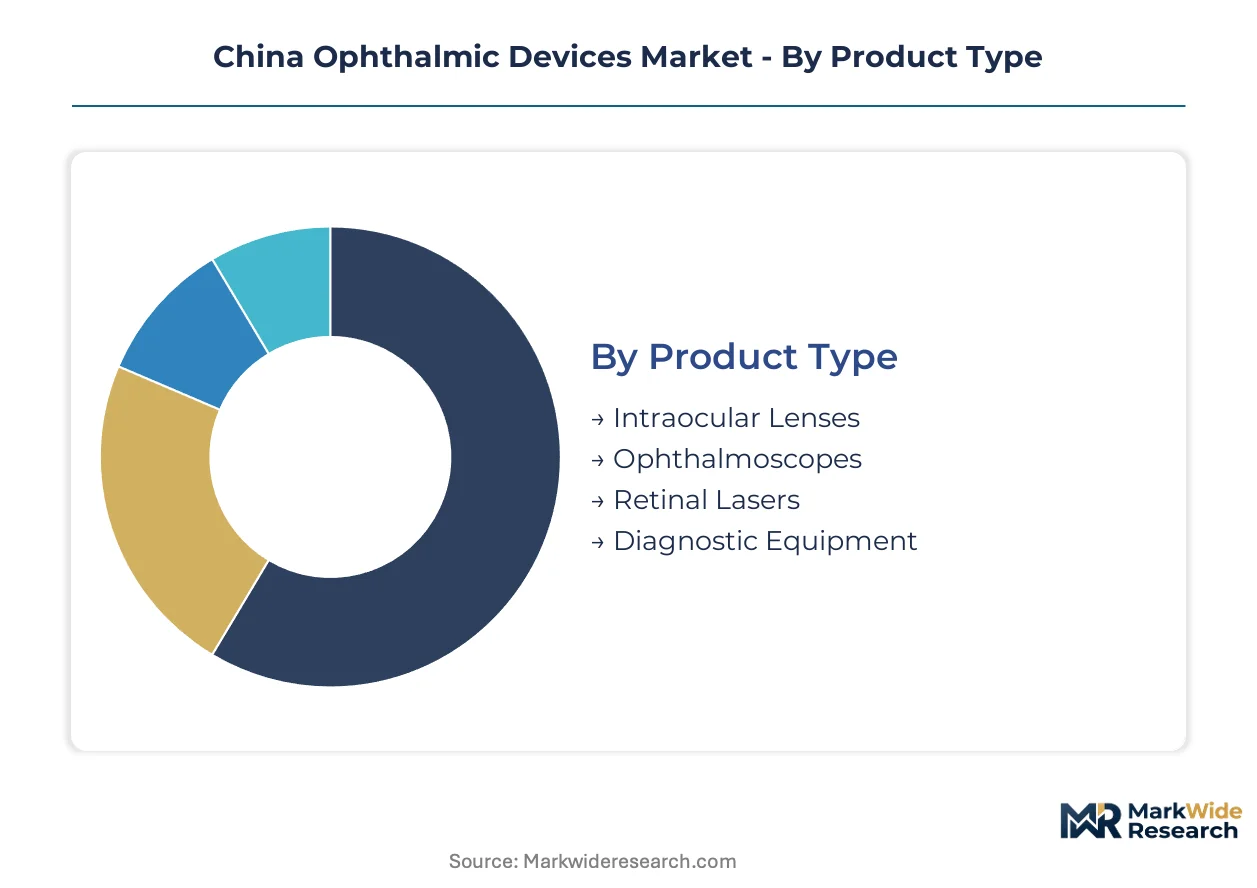
Margin distribution across China's ophthalmic devices market tracks procedure reimbursement tiers and capital replacement cycles differently by segment. Understanding where premium positioning survives against provincial procurement pressure determines viable entry strategies for equipment vendors and consumables suppliers.
Product Type:
Diagnostic Equipment commands the highest replacement frequency as resolution upgrades drive hospital purchasing committees, while Intraocular Lenses concentrate margin vulnerability under centralized procurement pilots.
- Diagnostic Equipment:Optical coherence tomography systems and fundus cameras operate at wavelength-specific parameters requiring micron-scale calibration. Shanghai and Hangzhou hospital networks absorb high-end imaging platforms at twice the density of tier-two cities, pressured by residency training center accreditation standards.
- Intraocular Lenses:Multifocal and toric designs displace monofocal standards in urban private-pay channels, though provincial procurement mandates favor single-vision lenses in public tiers. Suzhou manufacturing partnerships anchor supply chain localization for foreign OEMs seeking NMPA registration efficiency.
- Retinal Lasers:Photocoagulation systems for diabetic retinopathy and macular edema target vitreoretinal surgical suites.
- Ophthalmoscopes:Direct and indirect examination instruments serve primary screening infrastructure in community health centers.
Diagnostic Equipment holds installed capacity. Intraocular Lenses is rotating up the share rankings.
End User:
Channel economics diverge sharply between capital-intensive hospital installations and asset-light clinic expansion enabled by regulatory licensing clarity.
- Eye Clinics:Standalone outpatient surgery centers deploy portable diagnostic platforms and streamlined surgical workflows under clarified licensing frameworks. Jiangsu and Zhejiang provinces lead chain expansion, absorbing handheld OCT systems at twice the pace of traditional hospital deployments.
- Hospitals:Tier-one academic centers and tier-two municipal networks dominate femtosecond laser placements and premium cataract procedure volume. NMPA Class III registration timelines determine competitive access to these concentrated procurement committees.
- Ambulatory Surgical Centers:Focused ophthalmology facilities target high-volume cataract and refractive procedures outside full hospital overhead structures.
- Home Care:Visual acuity monitoring and low-vision aids serve aging populations in community-based settings.
Hospitals retain procedure volume concentration. Eye Clinics is climbing the fastest as a channel for capital deployment.
Technology:
Revenue attachment rates vary by whether technology platforms generate consumable pull-through or standalone capital sales.
- Laser Surgery:Femtosecond and excimer platforms for corneal and lenticular procedures require precision optical components concentrated in German and Japanese supply bases. Currency exposure and logistics volatility constrain OEM margin stability despite NMPA registration acceleration.
- Imaging Technology:OCT and fundus imaging systems compress form factors while expanding diagnostic capabilities. Miniaturization is enabling community screening deployment without proportional facility investment.
- Refractive Surgery:Corneal reshaping platforms target myopia correction demand concentrated in younger demographics.
- Visual Field Testing:Perimetry systems for glaucoma monitoring serve specialized diagnostic workflows.
Imaging Technology holds installed capacity. Laser Surgery is rotating up the share rankings.
Application:
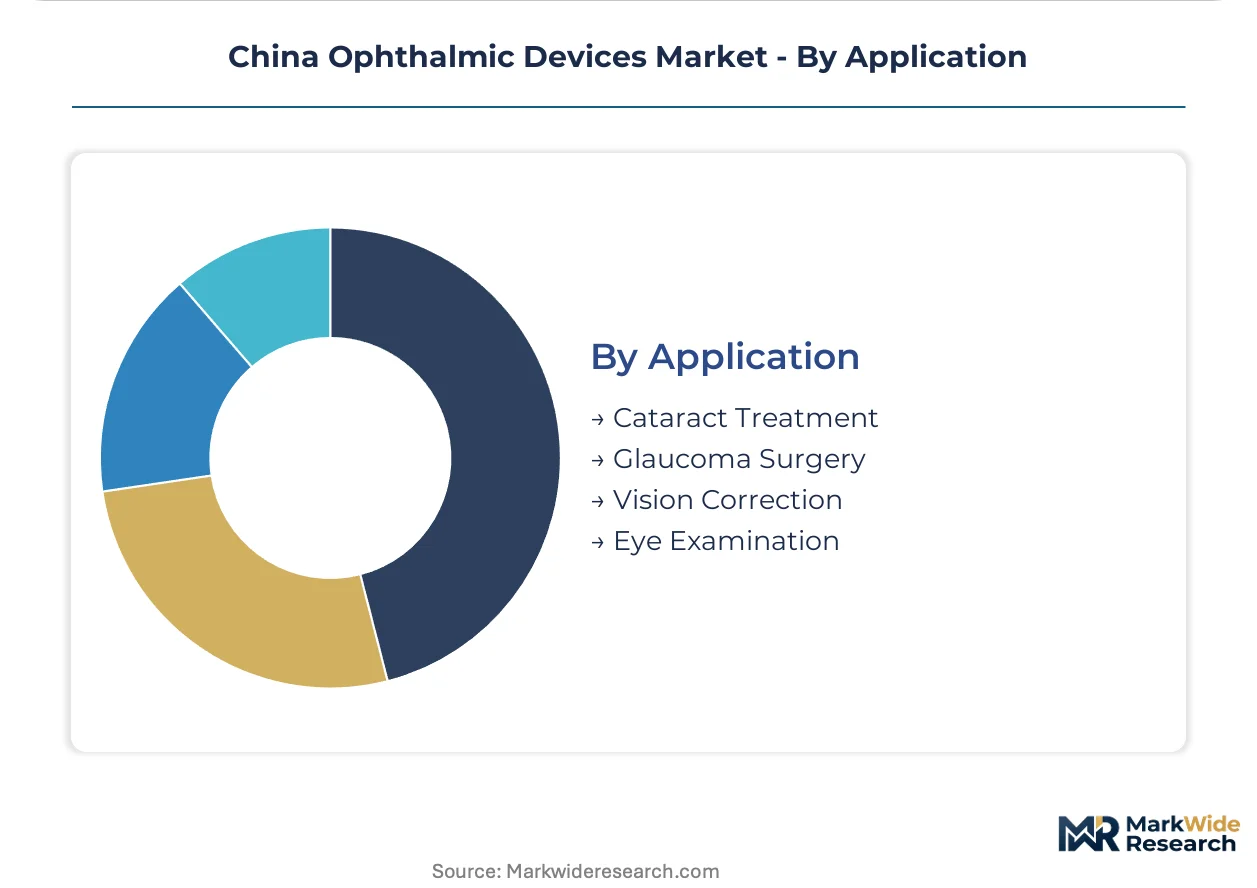
Procedure reimbursement tiers and patient out-of-pocket tolerance stratify addressable market value across clinical indications.
- Cataract Treatment:Premium workflow integration combining femtosecond laser capsulotomy with multifocal IOL implantation survives in private-pay urban channels. Provincial procurement pilots compress pricing power for standard procedures across public hospital networks.
- Vision Correction:Refractive surgery demand concentrates in Shanghai and Hangzhou where disposable income supports laser-based myopia correction. Younger demographic targeting distinguishes this application from age-related cataract volume.
- Glaucoma Surgery:MIGS devices and trabecular meshwork interventions target intraocular pressure management.
- Eye Examination:Routine screening and diagnostic workups serve population-scale visual health monitoring.
Cataract Treatment holds installed capacity. Vision Correction is gaining share fastest among premium-positioned applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NMPA registration timelines anchor market access across China's ophthalmic device landscape, with provincial procurement pilots and hospital network expansion patterns determining equipment deployment density.
Yangtze River Delta
Shanghai and Hangzhou concentrate premium cataract surgery volume and refractive correction procedure density. NMPA Class III streamlined review accelerates femtosecond laser platform entry for tier-one hospital networks. Suzhou manufacturing partnerships anchor intraocular lens supply chain localization for foreign OEMs seeking registration efficiency.
Pearl River Delta
Guangzhou and Shenzhen eye clinic chains absorb handheld OCT systems for diabetic retinopathy screening at expanded pace. Guangdong provincial health commission licensing frameworks enable standalone outpatient surgery center deployment beyond traditional hospital infrastructure. Shenzhen diagnostic imaging distributors compress deployment timelines for miniaturized retinal imaging platforms.
Beijing-Tianjin-Hebei
Capital region academic medical centers dominate vitreoretinal surgical suite installations and residency training center accreditation. SAMR procurement oversight shapes public hospital equipment tender consolidation around single-source maintenance contracts. Tianjin municipal hospital networks pilot three-year total-cost-of-ownership arrangements for premium cataract workflow integration.
Sichuan-Chongqing
Chengdu anchors central China access corridor expansion for trained vitreoretinal surgeons reorganizing provincial intervention capacity. Western China hospital network upgrades absorb advanced surgical platforms previously concentrated in eastern tier-one centers. Chongqing municipal ophthalmology department expansions target equipment vendors establishing service networks.
Shandong Peninsula
Qingdao and Jinan tier-two city hospital networks expand ophthalmology departments with accelerated absorption of laser surgery platforms. Shandong provincial centralized procurement pilots for intraocular lenses reshape pricing power and channel economics across public hospital networks. Local manufacturing facilities face GB laser safety compliance costs requiring sterilization workflow redesign.
China Ophthalmic Devices Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across China's ophthalmic devices market. The vendor base concentrates around multinational precision instrument specialists and domestic assembly operations with NMPA registration advantages. Three strategic archetypes dominate: German-Japanese optical component suppliers, US-European surgical platform integrators, and Chinese domestic manufacturers with provincial procurement relationships. Competitive moves center on Suzhou manufacturing partnerships for supply chain localization and AI-assisted diagnostic software bundling with hardware placements.
Among Swiss-German precision instrument specialists, Alcon and Carl Zeiss Meditec AG occupy positions exemplifying premium-tier surgical platform and diagnostic imaging archetypes. Japanese optical specialists including Nidek Co Ltd and Topcon Corporation represent imaging technology leadership through localized manufacturing partnerships. Hoya Corporation anchors the intraocular lens supply chain tier through Suzhou-based production facilities serving NMPA registration requirements.
| Leading Market Players |
|---|
| Bausch Health Companies Inc |
| Nidek Co Ltd |
| Alcon |
| Ziemer Group AG |
| Topcon Corporation |
| Johnson & Johnson |
| Hoya Corporation |
| Lumenis |
| Carl Zeiss Meditec AG |
| Others |
Value Chain & Pricing Dynamics
Multifocal intraocular lens substitution for monofocal standards in private-pay urban channels simultaneously redistributes manufacturing activity toward Suzhou-based partnerships and compresses margin pools in provincial procurement tiers. This input replacement dynamic exposes foreign OEMs to divergent pricing economics across hospital network segments while accelerating domestic assembly localization for NMPA registration efficiency.
Pricing Analysis
Shanghai and Hangzhou command 40-60% premiums over Chengdu and Xi'an for equivalent femtosecond laser platforms, reflecting tier-one hospital network purchasing power concentration. Three-tier pricing structure across premium, standard, and economy levels stratifies by after-sales service bundling and NMPA Class III certification tier. Cost compression in public hospital tiers is intensifying because provincial centralized procurement pilots mandate volume guarantees. Price-sensitive municipal procurement committees in Shandong and Sichuan favor economy-tier phacoemulsification systems over premium laser platforms.
Supply Chain Analysis
Container availability constraints on German and Japanese trade lanes elevate inbound logistics costs for precision laser crystals and high-resolution sensors by 15-25% against domestic component sourcing. Optical component manufacturing concentrates in Germany, Japan, and Switzerland, while final assembly increasingly shifts to Suzhou and Tianjin facilities. Supply chain risk centers on single-source vulnerability for femtosecond laser crystals concentrated in two German suppliers. Distribution runs through hospital procurement committees and eye clinic chain operators with divergent technical service requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflection in ophthalmic devices hinges on AI-assisted diagnostic software bundling with OCT hardware placements, creating interoperability-dependent revenue streams that favor ecosystem-integrated vendors over standalone equipment suppliers.
For Market Incumbents: Secure service network density in central and western provinces before trained vitreoretinal surgeon pipelines mature, as first-mover installation advantage converts to multi-year maintenance contracts. Deepen backward integration into Suzhou-based intraocular lens manufacturing to defend margin position against provincial procurement price compression. Threat: domestic manufacturers with NMPA registration timeline advantages. For New Entrants and Emerging Players: Anchor in tier-two municipal hospital ophthalmology department expansions absorbing advanced surgical platforms previously concentrated in academic centers. Most penetrable segment: handheld OCT systems for Jiangsu and Zhejiang eye clinic chains deploying diabetic retinopathy screening at community scale. Go-to-market angle: software-as-a-service revenue attachment for AI image analysis without proportional hardware investment. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors diagnostic imaging platform specialists with software companion development capabilities. Long-term viability rests on 5-10 year procedure volume growth in aging demographics and myopia correction demand. Acquisition target archetype: AI-assisted OCT analysis software firms with hospital information system integration expertise. Signal to watch: NMPA streamlined review expansion to Class II diagnostic categories.| Strategic Initiative | Industry Significance |
|---|---|
| Suzhou Manufacturing Partnership | Localized intraocular lens production accelerates NMPA registration timelines for foreign OEMs. |
| AI Software Companion Development | Machine learning integration with OCT systems opens recurring revenue streams beyond hardware sales. |
| Central and Western Service Network Expansion | Chengdu and Xi'an infrastructure capture vitreoretinal surgeon corridor reorganization. |
| Three-Year Total-Cost-of-Ownership Contracting | Shanghai municipal hospital pilots bundle equipment, consumables, and maintenance for vendor consolidation. |
| Handheld OCT Platform Miniaturization | Jiangsu and Zhejiang eye clinic chains deploy portable retinal imaging without proportional facility investment. |
Study Parameters
The analysis maps diagnostic equipment, intraocular lenses, and laser surgery platforms, each validated through hospital purchasing committee directors, eye clinic chain operators, biomedical engineers, and NMPA regulatory consultants. Primary interviews with these stakeholders combined with secondary validation against hospital procurement databases, GPO contracts, NMPA registration filings, and customs import records. Bottom-up equipment placement modeling and top-down procedure volume estimates triangulate market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, end user channel, technology platform, and application indication. CAGRs derived from equipment replacement cycle analysis, procedure reimbursement tier evolution, and provincial hospital network expansion plans. Industry-specific inputs incorporate NMPA Class III registration timeline trajectories and vitreoretinal surgeon training pipeline throughput.
Decision-makers should treat outputs as directional under assumptions of sustained NMPA review streamlining and provincial procurement pilot expansion; material deviation would warrant model refresh. Specific risk factors include GB laser safety compliance cost escalation and currency volatility affecting German and Japanese optical component sourcing. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Reflex Hammer Market
Medical Devices
Bone Anchored Hearing Aids Market
Medical Devices
Japan Respiratory Devices Market
Medical Devices
Transcatheter Aortic Valve Implantation (TAVI) Market
Medical Devices
Ocular Implants Market
Medical Devices
Global Continuous Peripheral Nerve Block Catheter Market
Medical Devices
Global Holter ECG Market
Medical Devices
Pressure Ulcer Devices Market
Medical Devices
Interventional Oncology Devices Market
Medical Devices
Knee Walkers Market
Medical Devices
AI Colonoscopy Withdrawal Quality Monitoring System Market
Medical Devices
MRI Motion Tracking Systems Market
Medical Devices
Disposable Medical Devices Sensors Market
Medical Devices
Veterinary Ultrasound Devices Market
Medical Devices
MIS Sacroiliac Joint Fusion Market
Medical Devices
Electroencephalography Devices Market