
 Global Handheld Bladder Scanner Market | 2026-2036
Global Handheld Bladder Scanner Market Size, Share, and Industry Trends Forecast 2026-2036
Global Handheld Bladder Scanner Market Foresight
Three-dimensional imaging capability is reorganizing competitive tiers in the handheld bladder scanner landscape. Verathon Inc. dominates premium hospital installations through proprietary algorithmic volume calculation. Laborie Medical Technologies Inc. extends its urology franchise into point-of-care settings with specialized probe design. GE Healthcare Inc. leverages existing radiology relationships to cross-sell portable bladder assessment tools into integrated delivery networks.
A handheld bladder scanner is a portable diagnostic instrument employing high-frequency ultrasound transducers to measure bladder volume non-invasively, typically operating at 2-5 MHz with real-time volumetric rendering. The device eliminates catheterization for post-void residual assessment in urology, emergency medicine, and geriatric care settings. Wireless connectivity configurations are capturing fastest-growing demand as hospitals prioritize electronic health record integration and telemetry-enabled workflows. Ultrasound technology retains the dominant installed base due to proven accuracy and lower per-procedure cost, though 3D imaging segments command superior margins where precision measurement drives reimbursement rates.
FDA 510(k) premarket notification requirements shape product development timelines and clinical validation standards for manufacturers targeting United States commercialization. CE marking under the EU Medical Device Regulation and Japan's PMDA quality management system certification create parallel compliance obligations that filter market entrants by technical documentation capacity. Stakeholders must monitor evolving post-market surveillance obligations across FDA, EMA, and PMDA jurisdictions as software-as-medical-device classifications expand to AI-enhanced volume interpretation algorithms.
Market Dynamics
Wireless telemetry integration is decomposing traditional bedside diagnostic workflows across acute care networks. Hospitals are reallocating capital toward connected bladder assessment systems that feed directly into electronic health record architectures.
Growth Catalysts
- Catheter-Associated Urinary Tract Infection Prevention Mandates:CMS non-payment policies for preventable hospital-acquired conditions are forcing postoperative units toward non-invasive volume measurement protocols.
- Geriatric Care Infrastructure Expansion:Japan's PMDA quality management system certification is accelerating device registration for long-term care facilities managing aging populations.
- 3D Volumetric Rendering Algorithms:Enhanced ultrasound processing capabilities are displacing two-dimensional bladder estimation in premium hospital installations.
Market Restraints
- High-Frequency Transducer Supply Concentration:Piezoelectric crystal fabrication capacity clusters in East Asian component foundries, creating single-source vulnerability for 2-5 MHz probe assemblies.
- EU Medical Device Regulation Documentation Burden:CE marking technical file requirements are extending product launch timelines by 12-18 months for software-as-medical-device classifications.
- Point-of-Care Ultrasound Substitution:General-purpose handheld ultrasound systems with bladder presets are capturing price-sensitive ambulatory segments.
Strategic Opportunities
- Home-Based Postoperative Monitoring:Germany's DiGA fast-track approval pathway for digital health applications is opening reimbursement for telemedicine-integrated bladder scanners.
- Emergency Medical Services Prehospital Adoption:Wireless-enabled devices are penetrating mobile intensive care units for trauma-related urinary retention assessment.
- Artificial Intelligence Volume Interpretation:FDA 510(k) clearance for machine learning-enhanced measurement algorithms is creating premium pricing tiers for automated diagnostic support.
Industry Challenges
- Clinical Validation Timeline Compression:FDA premarket notification requirements demand prospective accuracy studies against catheterized reference standards.
- Legacy Electronic Health Record Integration:HL7 FHIR interoperability standards vary across Epic, Cerner, and Meditech installations, forcing customized interface development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Handheld Bladder Scanner Market |
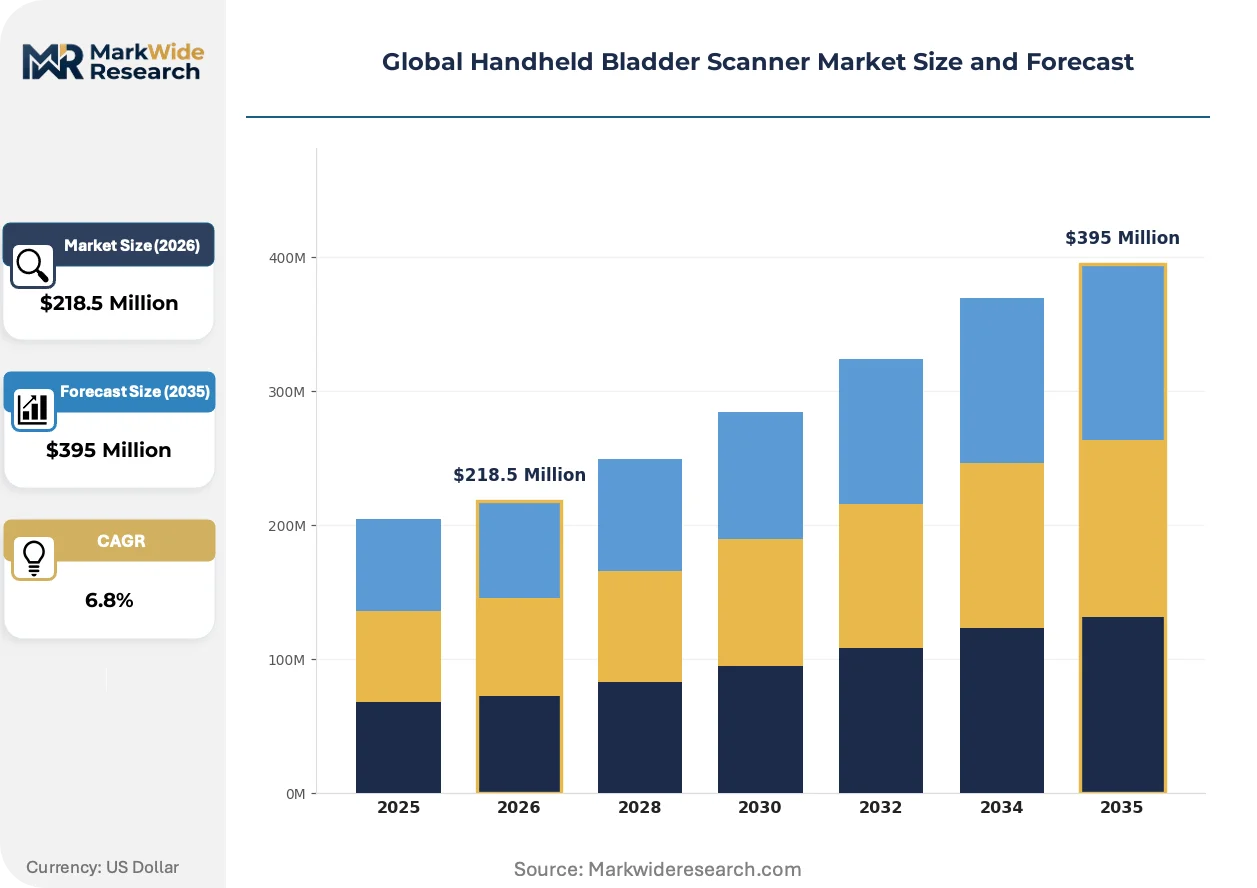
| Market Size in 2026 | $218.5 Million |
| Market Size in 2035 | $395 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Wireless, Battery-operated, Standalone Technology: Ultrasound, Doppler, 3D Imaging, Infrared, Piezoelectric Application: Urology, Postoperative Care, Emergency Medicine, Geriatrics, Nephrology End User: Hospitals, Ambulatory Care Centers, Nursing Homes, Diagnostic Laboratories |
| Companies Covered | Verathon Inc., Laborie Medical Technologies Inc., GE Healthcare Inc., Vitacon, dBMEDx Inc., Caresono Technology Co., Ltd., Sonostar Technologies Co., Limited, Mcube Technology Co. Ltd., Infinium Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Handheld Bladder Scanner Market Shifts & Advancements
Artificial intelligence inference at the edge is restructuring how bladder volume calculations execute on handheld hardware. Device manufacturers are racing to deploy neural network accelerators without cloud dependency.
Three-dimensional ultrasound reconstruction is decomposing the premium segment's reliance on operator-dependent probe positioning. Academic medical centers in the United States are adopting automated bladder contour detection for resident training programs. The technology is compressing inter-operator variability in volume estimation accuracy.
EU Medical Device Regulation post-market surveillance obligations are tightening software update governance for AI-enhanced devices. Manufacturers must now submit periodic safety reports for algorithm modifications. This regulatory friction is favoring established players with dedicated quality management infrastructure over emerging entrants.
Hospital procurement committees are unbundling device acquisition from service contracts in integrated delivery networks. Third-party biomedical engineering groups are absorbing preventive maintenance responsibilities previously captive to original equipment manufacturers. This shift is most pronounced in United States health systems pursuing capital expense reduction targets.
Global Handheld Bladder Scanner Market Segmentation
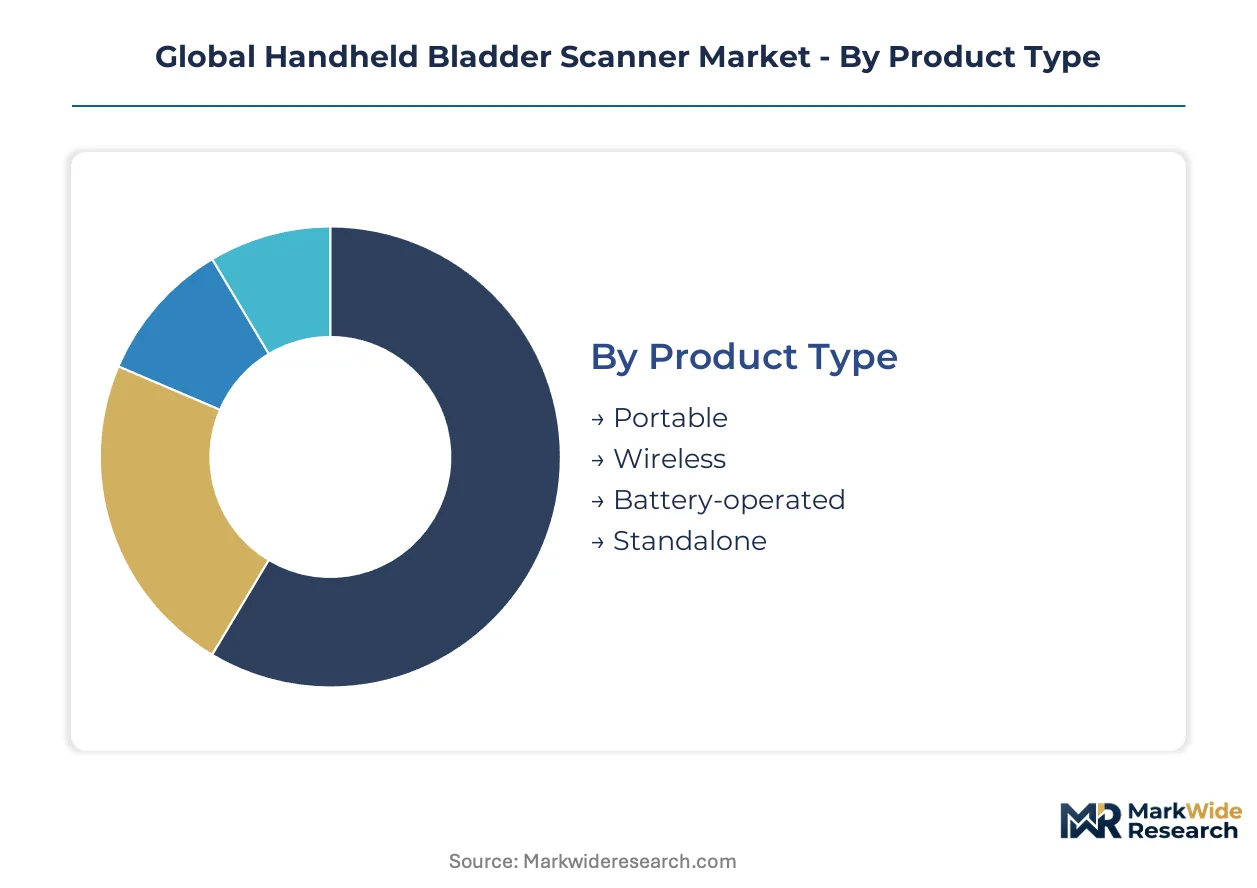
Segmentation in the handheld bladder scanner market reveals distinct procurement patterns across acute care networks and long-term care facilities. Product configuration choices directly correlate with electronic health record integration requirements and catheter-associated urinary tract infection prevention mandates in postoperative units.
Product Type:
Domestic procurement dominates portable and battery-operated configurations in Japan and Germany, while wireless variants show stronger export-led demand into emerging acute care networks.
- Portable:Compact units weighing under 2 kg enable bedside deployment across crowded postoperative wards. Demand concentrates in United States community hospitals where space constraints limit dedicated urology suite allocation and capital budgets favor multi-department rotation.
- Wireless:Bluetooth and Wi-Fi enabled devices transmit volume data directly into Epic and Cerner architectures. Export-led growth is strongest into German DiGA-eligible telemedicine programs and Japanese long-term care facilities pursuing Ministry of Health, Labour and Welfare connectivity standards.
- Battery-operated:Lithium-ion powered systems support 8-12 hour continuous clinical use without tethered power.
- Standalone:Self-contained units with integrated displays serve price-sensitive ambulatory segments lacking dedicated IT infrastructure.
Portable configurations hold the largest share; momentum sits with wireless systems.
Technology:
Cost tier stratification separates premium 3D imaging from economy ultrasound segments, with reimbursement rates in United States Medicare and German statutory health insurance driving hospital procurement decisions.
- Ultrasound:2-5 MHz piezoelectric transducers deliver proven volume accuracy within 15% of catheterized reference standards. Demand concentrates in United States critical access hospitals where per-procedure cost minimization outweighs precision requirements for routine post-void residual assessment.
- 3D Imaging:Automated bladder contour reconstruction eliminates operator-dependent probe angulation errors. Premium installations in academic medical centers across Massachusetts and Bavaria justify superior margins through reduced inter-operator variability in resident training programs.
- Doppler:Blood flow detection capabilities extend utility into vascular assessment adjacent to urology applications.
- Infrared:Optical volume estimation serves emerging home-based monitoring segments with lower regulatory barriers.
- Piezoelectric:Crystal array miniaturization enables probe head diameter reduction below 4 cm for pediatric applications.
Ultrasound retains installed base dominance; 3D imaging climbs the fastest.
Application:
Volume concentration in postoperative care units contrasts with margin expansion in emergency medicine, where throughput pressure justifies premium pricing for rapid triage decisions.
- Postoperative Care:Orthopedic and abdominal surgery recovery wards deploy scanners to replace indwelling catheter protocols. United States CMS non-payment policies for catheter-associated urinary tract infections are forcing adoption across 4,000+ acute care hospitals.
- Emergency Medicine:Trauma bays and fast-track units require sub-60 second volume assessment for urinary retention triage. German mobile intensive care units and Japanese emergency medical services are expanding prehospital adoption.
- Urology:Outpatient clinics manage benign prostatic hyperplasia and neurogenic bladder monitoring.
- Geriatrics:Long-term care facilities in Japan address aging population voiding dysfunction.
- Nephrology:Dialysis centers track fluid status in chronic kidney disease populations.
Postoperative care holds the largest share; emergency medicine shows steepest expansion trajectory.
End User:
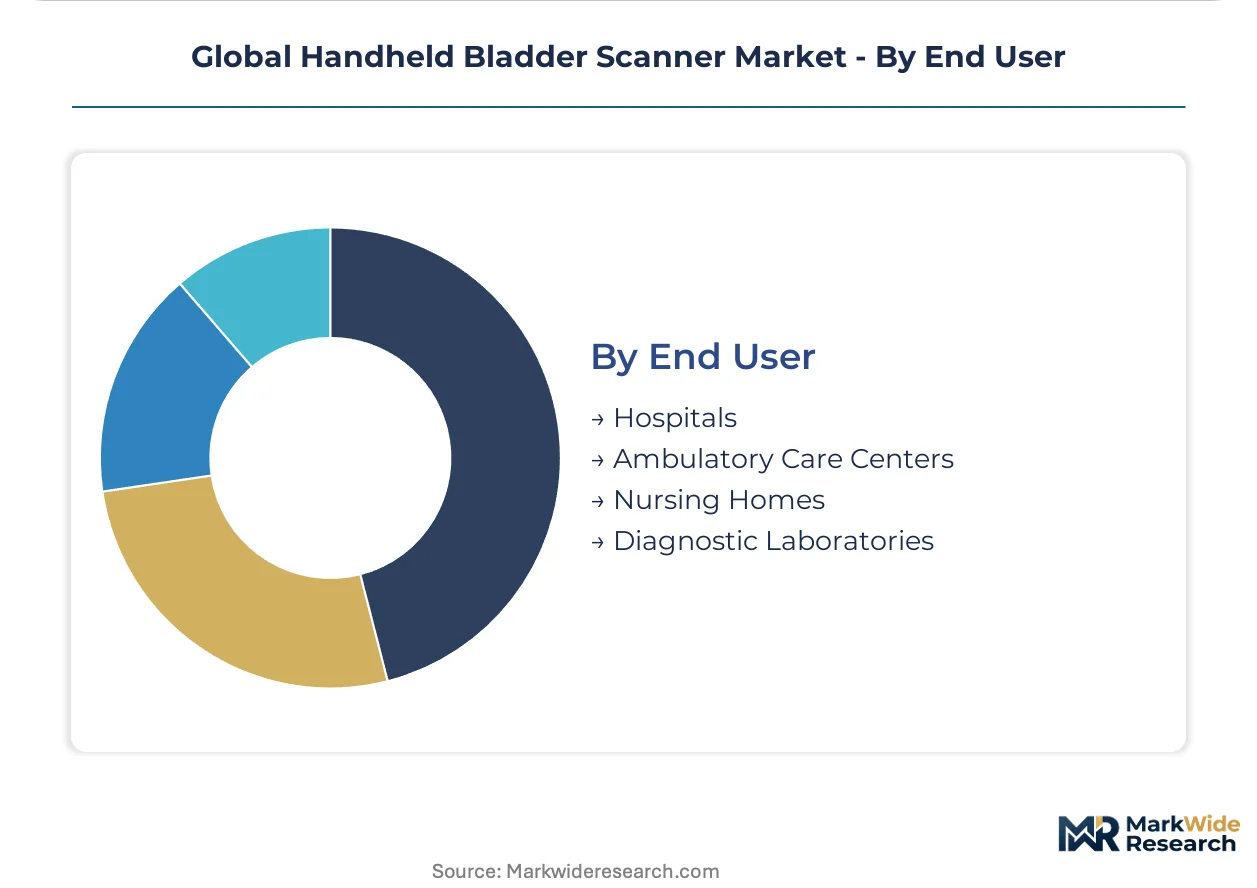
Customer type maturity separates consolidated hospital procurement from fragmented nursing home purchasing, with integrated delivery networks extracting volume discounts unavailable to independent long-term care operators.
- Hospitals:IDNs with 10+ facility footprints standardize on wireless-enabled platforms to simplify biomedical engineering training and spare parts inventory. United States health systems pursuing operating margin recovery are unbundling service contracts from device acquisition.
- Ambulatory Care Centers:Freestanding surgical and urology clinics prioritize portable configurations with rapid patient turnover. German outpatient specialty practices leverage DiGA reimbursement pathways for telemedicine-integrated monitoring.
- Nursing Homes:Long-term care facilities in Japan's prefectural health systems adopt simplified interfaces for non-specialist staff.
- Diagnostic Laboratories:Reference labs add bladder volume assessment to comprehensive metabolic panels.
Hospitals hold the largest share; ambulatory care centers gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Piezoelectric crystal fabrication clusters in East Asian foundries supply transducer assemblies worldwide, while regulatory clearance velocity separates commercial winners across North America, Europe, and Asia-Pacific hospital procurement committees.
United States
CMS non-payment policies for catheter-associated urinary tract infections drive postoperative unit adoption across 4,000-plus acute care hospitals. FDA 510(k) premarket notification requirements compress product launch timelines against catheterized reference standards. Academic medical centers in Massachusetts deploy automated bladder contour detection for resident training programs.
Germany
Statutory health insurance reimbursement rates for precision measurement justify premium 3D imaging installations in Bavarian university hospitals. The DiGA fast-track approval pathway opens telemedicine-integrated bladder scanner reimbursement for outpatient specialty practices. Mobile intensive care units in North Rhine-Westphalia expand wireless-enabled prehospital adoption.
Japan
PMDA quality management system certification accelerates device registration for long-term care facilities managing the world's most aged population. Ministry of Health, Labour and Welfare connectivity standards shape wireless procurement specifications in prefectural health systems. Kanto region nursing homes adopt simplified interfaces for non-specialist staff.
China
NMPA medical device registration requirements filter market entrants by technical documentation capacity for software-as-medical-device classifications. Domestic procurement preferences favor portable and battery-operated configurations in tier-two city hospitals. Yangtze River Delta component foundries concentrate high-frequency transducer supply.
Global Handheld Bladder Scanner Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the handheld bladder scanner landscape. Premium hospital installations consolidate around algorithmic volume calculation specialists, while price-sensitive ambulatory segments fragment across portable configuration assemblers. Three archetypes dominate: integrated radiology equipment multinationals, urology-focused point-of-care specialists, and emerging Asian component-integrated manufacturers. M&A activity concentrates in telemetry-enabled workflow platforms, while strategic partnerships target electronic health record interoperability customization.
Among North American medical technology incumbents, Verathon Inc. and Laborie Medical Technologies Inc. occupy positions within the premium algorithmic tier, exemplifying proprietary software differentiation strategies. GE Healthcare Inc. anchors the radiology-crossover archetype, representing established imaging equipment relationships leveraged into portable assessment tools. Chinese specialists including Caresono Technology Co., Ltd. and Sonostar Technologies Co., Limited sit within the cost-optimized manufacturing tier, reflecting component supply proximity and domestic market scale advantages.
| Leading Market Players |
|---|
| Verathon Inc. |
| Laborie Medical Technologies Inc. |
| GE Healthcare Inc. |
| Vitacon |
| dBMEDx Inc. |
| Caresono Technology Co., Ltd. |
| Sonostar Technologies Co., Limited |
| Mcube Technology Co. Ltd. |
| Infinium Medical |
| Others |
Supply & Pricing Matrix
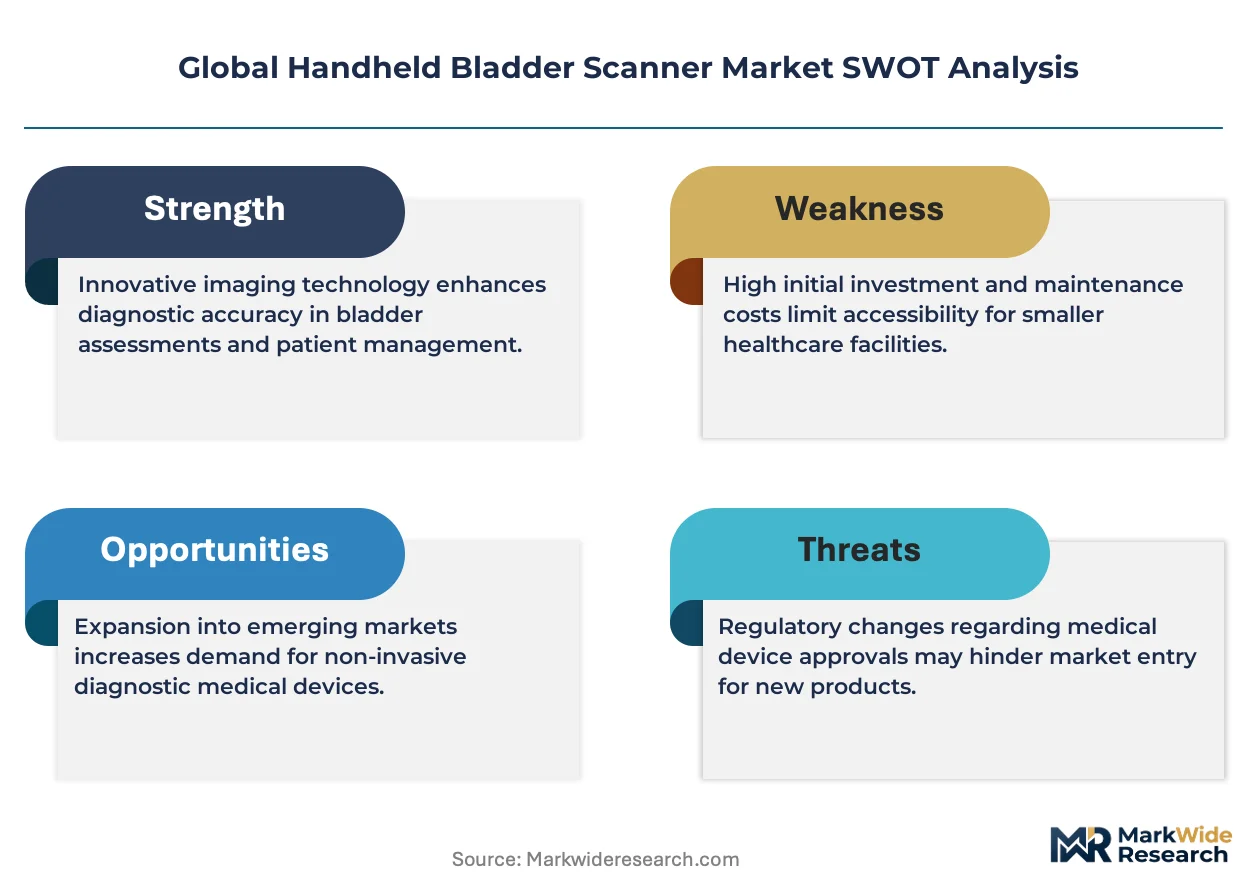
FDA 510(k) premarket notification requirements gate both supplier qualification and price differentiation simultaneously, as manufacturers must demonstrate clinical validation against catheterized reference standards before commanding premium positioning in United States hospital procurement committees. This regulatory threshold creates a bifurcated market where cleared devices capture reimbursement-linked pricing power while uncertified alternatives compete on capital cost alone in price-sensitive ambulatory segments.
Pricing Analysis
FDA 510(k) dictates the pricing tier structure across hospital procurement networks, separating premium wireless-enabled platforms with EHR integration from economy portable configurations serving nursing homes. Three-tier pricing stratifies across premium algorithmic volume calculation, standard ultrasound-based measurement, and economy infrared optical estimation. Cost compression in the standard tier intensifies as general-purpose handheld ultrasound systems with bladder presets capture price-sensitive ambulatory demand. Critical access hospitals exhibit highest price sensitivity; academic medical centers pursuing resident training standardization show lowest.
Supply Chain Analysis
Piezoelectric crystal fabrication capacity in East Asian foundries creates single-source vulnerability for 2-5 MHz transducer assemblies, with Yangtze River Delta component manufacturers supplying probe heads worldwide. High-frequency piezoelectric crystals, lithium-ion battery cells, and neural network accelerator chips constitute critical input dependencies. Tariff exposure on semiconductor components from Taiwan and South Korea threatens margin stability for AI-enhanced volume interpretation algorithms. Distribution runs through integrated delivery network procurement committees in the United States, GPO contracts in Germany, and prefectural health system tenders in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The handheld bladder scanner market is exiting a post-pandemic capital expenditure trough as hospital operating margin recovery and CMS infection prevention mandates synchronize to drive replacement demand. Cyclical recovery justification rests on the 4,000-plus United States acute care hospital installed base modernizing toward wireless telemetry-enabled platforms.
For Market Incumbents: Compound installed base loyalty through backward integration into high-frequency transducer supply and preemptive FDA 510(k) submissions for AI-enhanced volume interpretation algorithms. Defend against point-of-care ultrasound substitution by embedding proprietary bladder contour detection into resident training program curricula at academic medical centers. Channel control through exclusive biomedical engineering service contracts retains pricing power as procurement committees unbundle acquisition from maintenance. For New Entrants and Emerging Players: Lead with telemedicine-integrated configurations targeting Germany's DiGA fast-track reimbursement pathway for home-based postoperative monitoring, the most penetrable white-space segment. Emergency medical services prehospital adoption in Japanese mobile intensive care units offers secondary entry with lower incumbent saturation. Go-to-market angle should emphasize HL7 FHIR interoperability customization for Epic and Cerner architectures without legacy technical debt. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across software-as-medical-device classifications as edge AI inference reduces cloud dependency and per-unit silicon costs. Long-term viability over the next decade favors acquisition targets with dedicated quality management infrastructure capable of managing EU MDR post-market surveillance obligations for algorithm modifications. Signal to watch: FDA 510(k) clearance velocity for machine learning-enhanced measurement algorithms as inflection indicator for premium pricing tier expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Clears algorithmic volume calculation for CMS reimbursement-linked hospital procurement. |
| CE Marking Pathway | Unlocks Bavarian university hospital premium installations under EU MDR technical file requirements. |
| Hospital System Partnership | Secures integrated delivery network standardization contracts with 10-plus facility footprints. |
| Software Companion Development | Enables wireless telemetry integration into Epic and Cerner EHR architectures. |
| Reimbursement Strategy | Positions telemedicine-integrated devices for Germany's DiGA fast-track approval pathway. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and urology department heads; and secondary validation through FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR technical documentation. Bottom-up triangulation across product configuration demand curves and top-down reconciliation against acute care hospital installed base estimates anchored volume projections.
Across the analysis window, the forecasting framework modeled segmentation dimensions including product configuration, imaging technology tier, clinical application setting, and end-user facility type. CAGRs were derived from trend extrapolation of catheter-associated urinary tract infection prevention mandate adoption curves and wireless EHR integration penetration rates. Industry-specific inputs incorporated PMDA quality management system certification timelines and DiGA reimbursement eligibility thresholds.
Forecasts assume regulatory continuity in FDA 510(k), EU MDR, and PMDA quality management regimes; material policy shifts in software-as-medical-device classification or post-market surveillance obligations would require re-modeling. Specific risk factors include piezoelectric crystal supply disruption, point-of-care ultrasound substitution acceleration, and HL7 FHIR interoperability standard fragmentation. Practitioners should keep alternative scenarios live as AI-enhanced volume interpretation algorithm clearance velocity and hospital capital expenditure recovery trajectories evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Syringe Pumps Market
Medical Devices
Disposable Contact Lenses Market
Medical Devices
Breast Localization System Market
Medical Devices
Spain Respiratory Devices Market
Medical Devices
Life Science and Chemical Instruments Market
Medical Devices
3D and 4D Ultrasound Devices Market
Medical Devices
3D Printing Medical Devices Market
Medical Devices
Unilateral Biportal Endoscopy Market
Medical Devices
Asia-Pacific Manual Resuscitators Market
Medical Devices
Global Brachytherapy Devices Market
Medical Devices
Mexico Artificial Organs and Bionic Implants Market
Medical Devices
Physiotherapy Laser Wrist Watch Market
Medical Devices
Global Medical Radiation Shielding Market
Medical Devices
Non-Invasive Ventilators Market
Medical Devices
Acute External Ventricular Drain Market
Medical Devices
Global Automated Suturing Devices Market