
 United Arab Emirates General Surgical Devices Market | 2026-2036
United Arab Emirates General Surgical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates General Surgical Devices Market Analytics
Maintenance and calibration service contracts is restructuring how surgical device vendors monetize relationships with UAE hospital procurement teams. Medtronic PLC leverages its Gulf distribution hub to sustain direct technical service agreements with Ministry of Health facilities. Stryker Corporation anchors its UAE position through specialized orthopedic power tool refurbishment programs that extend equipment life cycles.
General surgical devices encompass manually operated and powered instruments designed for tissue manipulation, dissection, hemostasis, and wound closure during operative procedures, typically fabricated from medical-grade stainless steel or titanium alloys with Rockwell hardness ratings between 40 and 55 HRC to maintain edge integrity through repeated sterilization cycles. Electrosurgical devices and handheld surgical tools represent the dominant technology segments, with electrosurgical platforms capturing premium margin pools due to generator-disposable blade pairing models while handheld tools remain volume-dense across public hospital tenders. 3D-printed surgical devices constitute the fastest-growing technology category as UAE teaching hospitals adopt patient-specific osteotomy guides and anatomical models for complex reconstructive training.
MOHAP, the Dubai Health Authority, and the Emirates Authority for Standardization and Metrology collectively govern device registration, facility licensing, and product conformity assessment for surgical instruments entering the UAE market, with MOHAP's mandatory adverse event reporting system now shaping supplier selection criteria among private hospital groups. The UAE's alignment with Gulf Standardization Organization medical device technical regulations further harmonizes import requirements across GCC member states. Stakeholders must monitor how MOHAP's impending digital platform for real-time surgical device traceability will reshape distributor accountability and inventory financing structures.
Market Dynamics
MOHAP's compressed Class II surgical device approval timelines are accelerating product refresh cycles across UAE hospital procurement departments. This regulatory velocity is compressing distributor inventory financing periods while forcing technical service capabilities closer to point-of-use locations.
Growth Catalysts
- Minimally invasive instrument adoption:Ambulatory surgical centers in Dubai's healthcare free zones are expanding procurement of laparoscopic and arthroscopic tool sets to support same-day discharge protocols.
- MOHAP registration pathway reform:Updated medical device registration frameworks are eliminating redundant conformity assessment steps for surgical instruments already certified under Gulf Standardization Organization technical regulations.
- 3D-printed surgical guide proliferation:Teaching hospitals in Abu Dhabi and Sharjah are deploying patient-specific osteotomy guides and anatomical models for complex reconstructive training programs.
Market Restraints
- Medical-grade titanium alloy cost volatility:Raw material price fluctuations for Rockwell 40-55 HRC certified alloys are compressing margin structures for handheld surgical instrument manufacturers serving public hospital tenders.
- Generator-disposable blade pairing lock-in:Electrosurgical platform vendors maintain captive aftermarket revenue streams through proprietary blade interfaces, limiting hospital switching flexibility.
- Adverse event reporting liability exposure:MOHAP's mandatory surgical device incident disclosure system is elevating supplier selection criteria and extending vendor qualification timelines for new market entrants.
Strategic Opportunities
- Al Ain and Northern Emirates penetration:Secondary cities outside Dubai-Abu Dhabi corridors present underdeveloped surgical device infrastructure with concentrated public hospital expansion budgets.
- Real-time traceability platform integration:MOHAP's impending digital surgical device tracking system will create first-mover advantages for distributors pre-positioning serialized inventory management capabilities.
- Orthopedic power tool refurbishment services:Equipment life extension programs represent uncaptured revenue pools as hospitals defer capital expenditure on replacement generator systems.
Industry Challenges
- Biomedical engineering talent scarcity:Electrosurgical generator calibration and preventive maintenance expertise remains concentrated among a limited pool of Gulf-domiciled technical service specialists.
- Legacy sterilization protocol incompatibility:3D-printed polymer surgical guides face integration friction with existing steam and hydrogen peroxide sterilization infrastructure at established UAE medical centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates General Surgical Devices Market |
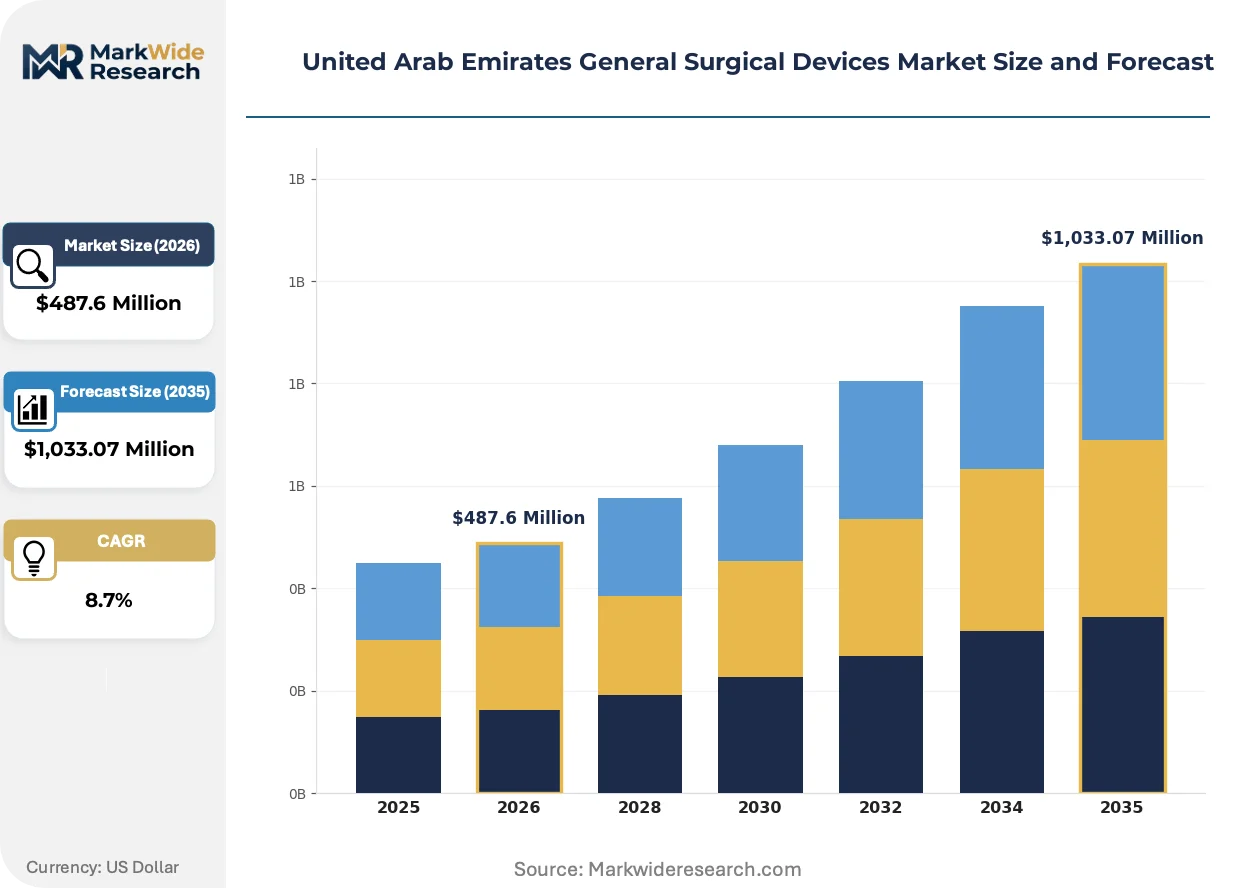
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scalpels, Forceps, Scissors, Clamps Application: General Surgery, Orthopedic Surgery, Cardiothoracic Surgery, Gynecological Surgery End User: Hospitals, Clinics, Ambulatory Surgical Centers, Home Care Technology: Electrosurgical Devices, Laser Surgical Instruments, Handheld Surgical Tools, 3D-Printed Surgical Devices |
| Companies Covered | Medtronic PLC, Stryker Corporation, Smith & Nephew, B. Braun SE, Olympus Corporation, Johnson & Johnson, Boston Scientific Corporation, Getinge AB, 3M, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates General Surgical Devices Market Evolving Landscape
Digital traceability mandates and patient-specific manufacturing capabilities are restructuring how surgical device value flows between manufacturers, distributors, and UAE hospital procurement teams.
3D-printed surgical guides fabricated from biocompatible photopolymers and selective laser sintered titanium are absorbing design-to-implant timelines for complex maxillofacial and orthopedic procedures. Cleveland Clinic Abu Dhabi and Sheikh Khalifa Medical City are deploying these patient-matched instruments at expanding volumes. The technology is absorbing traditional CNC-machined guide market share while compressing preoperative planning service revenue models.
MOHAP's alignment with Gulf Standardization Organization medical device technical regulations is harmonizing import documentation requirements across GCC member states. This regulatory convergence reduces redundant conformity assessment costs for surgical instrument suppliers maintaining multi-country distribution networks. Dubai-based specialized surgical distributors near Jebel Ali logistics corridors are consolidating regional hub functions to capture cross-border efficiency gains.
After-sales service unbundling is fragmenting traditional capital equipment procurement relationships across UAE private hospital groups. Technical service contracts for electrosurgical generators and orthopedic power systems are being negotiated separately from hardware acquisition, enabling third-party biomedical engineering specialists to displace manufacturer-captive service organizations. This pattern concentrates in Dubai's healthcare free zones where procurement teams maintain direct vendor relationships.
United Arab Emirates General Surgical Devices Market Segmentation
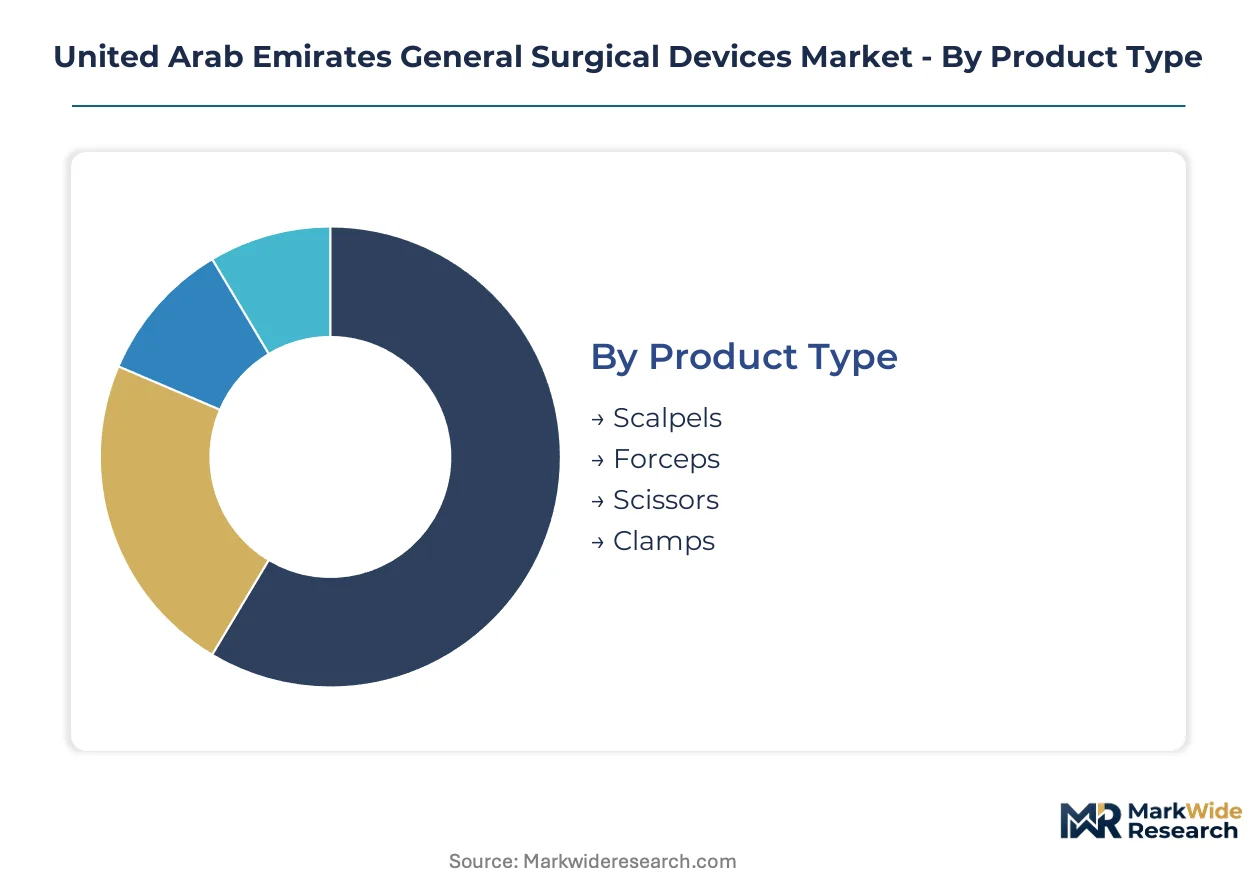
Segmentation in the UAE surgical devices market reveals distinct procurement patterns across public hospital tenders and private specialty centers. Understanding these divides enables suppliers to align product portfolios with MOHAP registration pathways and distributor financing structures.
Product Type:
Volume concentration favors single-use disposable instruments, while premium margin capture sits with reusable precision-crafted tools.
- Scalpels:Fabricated from medical-grade stainless steel with carbon or ceramic blade options, these instruments dominate high-volume public hospital procurement. Dubai's healthcare free zones absorb the largest share of safety-engineered disposable variants to support same-day discharge protocols.
- Forceps:Available in thumb, ratchet, and locking configurations with tungsten carbide inserts for enhanced grip, these tools concentrate demand in orthopedic and cardiothoracic suites. Abu Dhabi's teaching hospitals drive procurement of microsurgical forceps for reconstructive training programs.
- Scissors:Metzenbaum and Mayo patterns with hardened Rockwell 45-50 HRC cutting edges serve general surgery departments across MOHAP facilities.
- Clamps:Hemostatic and non-crushing variants with titanium construction address vascular and gastrointestinal applications in Sheikh Khalifa Medical City networks.
Mature deployment sits with scalpels and forceps. Newer deployment is concentrated in specialized clamp configurations for minimally invasive access.
Application:
Procedure volume distribution tracks directly to Dubai-Abu Dhabi healthcare infrastructure concentration and Northern Emirates expansion budgets.
- General Surgery:Appendectomy, cholecystectomy, and hernia repair procedures generate baseline instrument demand across MOHAP-supervised facilities. Dubai's ambulatory surgical centers are redirecting volumes from inpatient settings through laparoscopic platform adoption.
- Orthopedic Surgery:Joint replacement and trauma fixation procedures require powered instruments and patient-specific guides. Cleveland Clinic Abu Dhabi deploys 3D-printed osteotomy guides at expanding scale for complex reconstructive cases.
- Cardiothoracic Surgery:Sternotomy and valve repair applications concentrate in Sheikh Khalifa Medical City and specialized cardiac centers with electrosurgical generator pairing requirements.
- Gynecological Surgery:Hysterectomy and fertility procedure volumes are climbing fastest in Sharjah and Ras Al Khaimah as secondary city infrastructure matures.
Procedure concentration centers on general surgery. Gynecological surgery is expanding most quickly outside Dubai-Abu Dhabi corridors.
End User:
Procurement authority fragmentation creates divergent vendor qualification pathways across facility licensing categories.
- Hospitals:MOHAP and Dubai Health Authority-licensed facilities with centralized procurement departments negotiate multi-year maintenance contracts alongside capital equipment. Public hospital tenders favor Rockwell-certified reusable instruments with extended sterilization cycle ratings.
- Clinics:Outpatient procedure centers with limited sterilization infrastructure drive single-use instrument demand. Jebel Ali logistics corridor distributors maintain dedicated inventory buffers for clinic segment rapid replenishment.
- Ambulatory Surgical Centers:Same-day discharge protocols in Dubai's healthcare free zones are accelerating minimally invasive instrument set procurement with compressed turnaround requirements.
- Home Care:Wound closure and basic surgical supply demand remains nascent, concentrated in post-operative recovery support for medical tourism patients.
Established procurement systems sit with hospitals. Ambulatory surgical centers are gaining share fastest through free zone expansion.
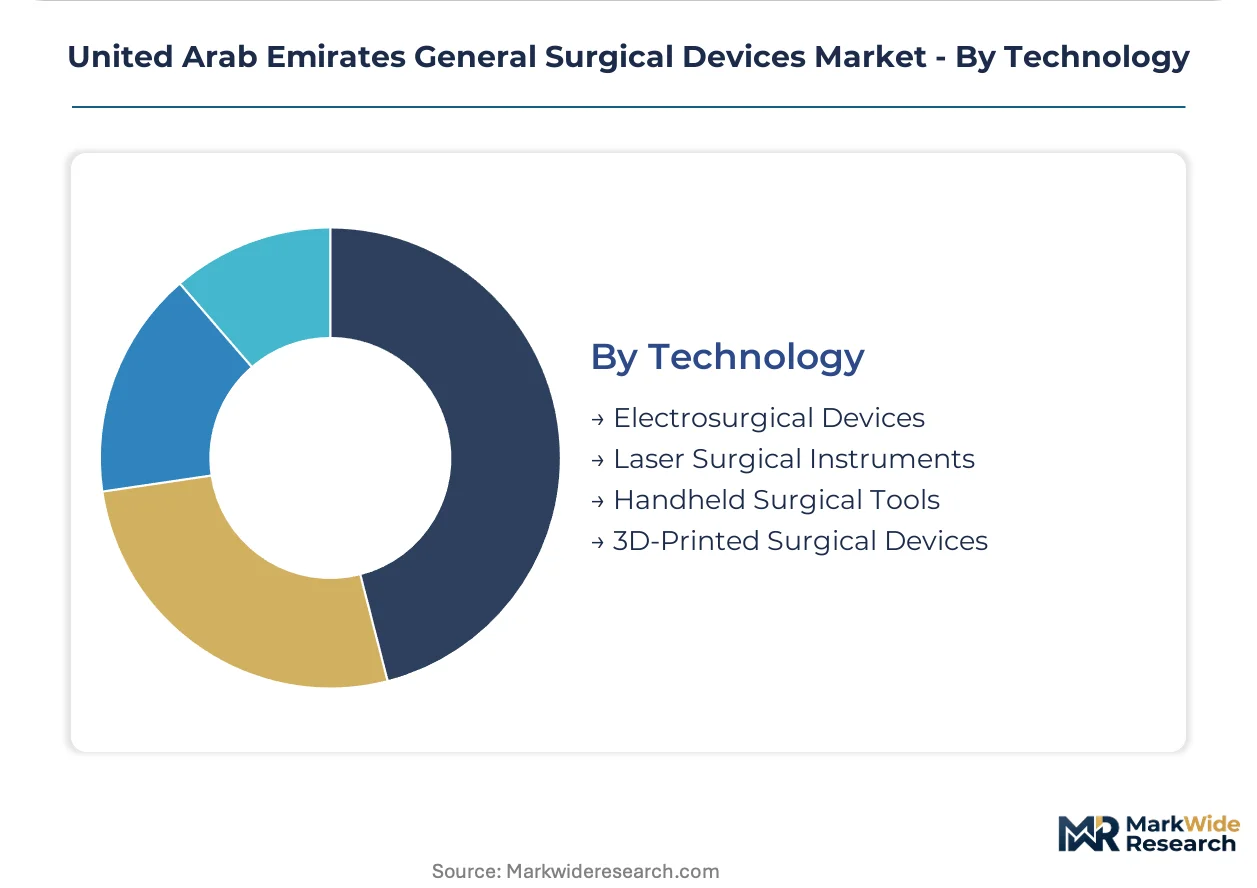
Technology:
Margin architecture separates capital-intensive platform systems from high-volume handheld tool replacement cycles.
- Electrosurgical Devices:Generator systems with proprietary blade interfaces capture recurring disposable revenue through locked-in pairing models. MOHAP's adverse event reporting system is elevating supplier technical service capability requirements for these platforms.
- Laser Surgical Instruments:CO2 and fiber-optic systems for precision cutting and coagulation concentrate in ophthalmology and dermatology suites. Dubai's private hospital groups absorb premium-priced laser platforms for medical tourism positioning.
- Handheld Surgical Tools:Manual instruments fabricated from titanium alloys with 40-55 HRC hardness ratings serve volume-dense public tenders. Raw material cost volatility is compressing manufacturer margins in this segment.
- 3D-Printed Surgical Devices:Patient-specific osteotomy guides and anatomical models fabricated from biocompatible photopolymers and selective laser sintered titanium are absorbing traditional CNC-machined guide market share. Teaching hospitals in Abu Dhabi and Sharjah deploy these for complex reconstructive training.
Mainstream adoption sits with handheld tools and electrosurgical platforms. 3D-printed surgical devices represent the steepest expansion trajectory as patient-matched manufacturing capabilities mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic manufacturing of surgical-grade alloys and precision instruments remains minimal across the Emirates, forcing reliance on imports through Jebel Ali logistics corridors. Consumption concentrates in Dubai and Abu Dhabi healthcare clusters, with secondary cities now absorbing expanding procurement volumes.
Dubai
Dubai's healthcare free zones anchor the Emirates' surgical device consumption, with ambulatory surgical centers driving minimally invasive instrument procurement. Dubai Health Authority licensing frameworks compress facility qualification timelines for international suppliers. Specialized distributors cluster near Jebel Ali logistics corridors to service same-day discharge protocols across Dubai Healthcare City and Dubai Silicon Oasis medical clusters.
Abu Dhabi
Abu Dhabi's teaching hospitals deploy patient-specific 3D-printed osteotomy guides at expanding scale for complex reconstructive training. Department of Health licensing requirements shape vendor qualification pathways distinct from Dubai's regulatory environment. Cleveland Clinic Abu Dhabi and Sheikh Khalifa Medical City networks concentrate electrosurgical platform procurement with integrated technical service agreements.
Sharjah
Sharjah's secondary city infrastructure is maturing fastest for gynecological and general surgery procedure volumes outside the Dubai-Abu Dhabi corridor. MOHAP facility licensing is accelerating hospital expansion budgets across the emirate. University Hospital Sharjah and specialized women's health centers are redirecting procurement from Dubai-based distributors toward localized inventory buffers.
Northern Emirates
Ras Al Khaimah and Fujairah present underdeveloped surgical device infrastructure with concentrated public hospital expansion budgets. MOHAP's centralized procurement frameworks for Ministry of Health facilities are standardizing instrument specifications across these emirates. Ras Al Khaimah Medical District is absorbing laparoscopic platform investments previously concentrated in Dubai healthcare free zones.
Al Ain
Al Ain's geographic isolation from coastal logistics corridors creates distributor service coverage gaps for preventive maintenance and calibration. Tawam Hospital and Al Ain Hospital networks rely on Abu Dhabi-based technical service specialists with extended response timelines. MOHAP is piloting remote electrosurgical generator diagnostics to compress service intervals for this interior market.
United Arab Emirates General Surgical Devices Market Competitive Landscape
Top-tier vendors anchor premium electrosurgical and orthopedic power system segments, while mid-tier distributors capture volume-dense handheld instrument procurement through public hospital tenders. Market structure reflects a bifurcation between capital-intensive platform providers with captive aftermarket revenue and commodity instrument suppliers competing on Rockwell certification and sterilization cycle ratings. Three strategic archetypes dominate: multinational manufacturers with Gulf distribution hubs, regional specialized surgical distributors with Jebel Ali logistics integration, and third-party biomedical engineering service specialists unbundling technical contracts from hardware acquisition. Competitive moves concentrate on maintenance contract unbundling and localized refurbishment program deployment.
Within the multinational manufacturer tier, Medtronic PLC and Stryker Corporation exemplify platform-centric positioning with integrated technical service capabilities. Medtronic leverages its Gulf distribution hub to sustain direct service agreements with Ministry of Health facilities. Stryker anchors its Emirates presence through specialized orthopedic power tool refurbishment programs. Among diversified healthcare conglomerates, Johnson & Johnson occupies a position spanning consumer wound closure through capital surgical platforms.
| Leading Market Players |
|---|
| Medtronic PLC |
| Stryker Corporation |
| Smith & Nephew |
| B. Braun SE |
| Olympus Corporation |
| Johnson & Johnson |
| Boston Scientific Corporation |
| Getinge AB |
| 3M |
| Others |
Value Network & Pricing Analysis
MOHAP's impending digital surgical device traceability mandate gates both qualified supply access and premium-tier pricing eligibility for distributors serving UAE hospital procurement teams. Manufacturers lacking serialized inventory management capabilities face exclusion from high-margin maintenance contract negotiations while certified suppliers capture pricing power through technical service bundling.
Pricing Analysis
Cost-down pressure on handheld surgical instruments accelerates because medical-grade titanium alloy volatility compresses manufacturer margins serving MOHAP public tenders. Three-tier pricing structure across premium, standard, and economy levels separates electrosurgical platform vendors with captive blade revenue from commodity instrument suppliers competing on Rockwell certification. Price differentiation hinges on after-sales service bundling and sterilization cycle ratings. Ambulatory surgical centers in Dubai's healthcare free zones exhibit highest price sensitivity, while Cleveland Clinic Abu Dhabi and Sheikh Khalifa Medical City networks prioritize technical service capability over unit cost.
Supply Chain Analysis
Domestic content requirements for Gulf Standardization Organization certification are reshaping sourcing patterns for surgical instrument suppliers maintaining UAE distribution networks. Manufacturing concentrates in Germany, Switzerland, and the United States for precision electrosurgical generators and orthopedic power systems. Raw material flows draw from Swedish titanium sponge, Japanese surgical-grade steel, and German carbide inserts. Single-source vulnerability sits with proprietary electrosurgical blade interfaces that lock hospitals into captive aftermarket streams. Distribution runs through Jebel Ali logistics corridors where specialized surgical distributors cluster to service same-day discharge protocols across Dubai Healthcare City.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biomedical engineering talent scarcity for electrosurgical generator calibration props pricing power for vendors with Gulf-domiciled technical service specialists. Capacity bottlenecks in preventive maintenance expertise sustain premium contract rates across UAE hospital networks.
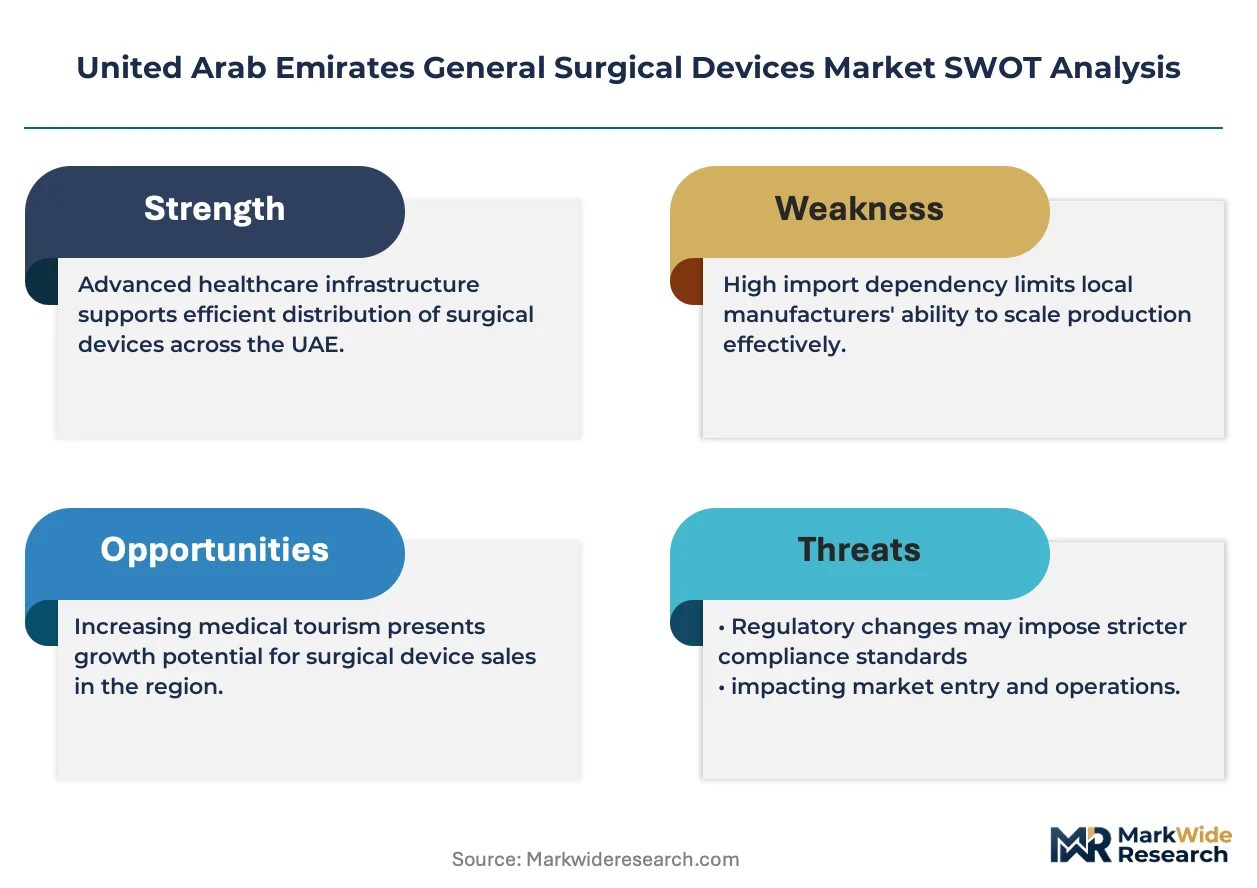
For Market Incumbents: Deploy backward integration into medical-grade titanium alloy sourcing to buffer margin compression from raw material volatility. Consolidate technical service capabilities through specialized orthopedic power tool refurbishment programs that extend equipment life cycles and displace third-party biomedical engineering specialists. Threat substitution emerges from 3D-printed polymer surgical guides requiring sterilization protocol investments. For New Entrants and Emerging Players: MOHAP's compressed Class II surgical device approval timelines in the UAE opens a window for distributors pre-positioning serialized inventory management capabilities ahead of digital traceability mandates. Target Al Ain and Northern Emirates secondary cities where public hospital expansion budgets concentrate and distributor service coverage gaps persist. Go-to-market angle: remote electrosurgical generator diagnostics partnerships with MOHAP pilot programs. For Investors and Strategic Acquirers: MOHAP's real-time surgical device traceability platform deployment is the leading indicator that distributor accountability structures will consolidate around serialized inventory capabilities. Long-term viability favors acquisition targets with Gulf distribution hub infrastructure and direct technical service agreements with Ministry of Health facilities. Signal to monitor: adverse event reporting liability exposure elevating vendor qualification timelines for new market entrants.| Strategic Initiative | Industry Significance |
|---|---|
| MOHAP Digital Traceability Integration | Serialized inventory capabilities capture first-mover positioning ahead of mandate enforcement. |
| Orthopedic Power Tool Refurbishment Program | Equipment life extension unlocks recurring revenue streams as hospitals defer capital expenditure. |
| Gulf Standardization Organization Certification Pathway | Harmonized import documentation reduces redundant conformity costs across GCC member states. |
| Biomedical Engineering Talent Acquisition | Preventive maintenance expertise scarcity concentrates service pricing power with certified specialists. |
| 3D-Printed Surgical Guide Manufacturing Partnership | Patient-specific osteotomy guides absorb traditional CNC-machined instrument market share. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with hospital procurement managers, biomedical engineers, GPO contracts managers, and distributor operations heads combined with MOHAP device registration databases, Dubai Health Authority licensing records, and Gulf Standardization Organization technical regulations. Bottom-up instrument volume estimates and top-down healthcare expenditure patterns were triangulated to validate market sizing.
Reconciliation of shipment data, import documentation, and facility procurement records informed the analytical framework across the analysis window. Segmentation dimensions modeled include product type, application, end user, and technology tier alongside regional regulatory cluster variations. CAGRs were derived from trend extrapolation of historical procurement patterns and projected facility expansion budgets. Forecast inputs incorporated laparoscopic platform adoption curves and 3D-printed surgical guide penetration rates.
The model assumes a particular technology adoption path; alternative pathways for 3D-printed polymer sterilization compatibility would alter the outlook. Forecasts reflect assumptions regarding MOHAP regulatory velocity and titanium alloy price stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Japan General Surgical Devices Market
Surgical Instruments
Ultrasonic Scissors Market
Surgical Instruments
Surgical Headband Market
Surgical Instruments
US Ophthalmic Handheld Surgical Instruments Market
Surgical Instruments
Huber Needles Market
Surgical Instruments
Minimally Invasive Thoracic Surgery Market
Surgical Instruments
US Surgical Sutures Market
Surgical Instruments
Cryosurgical Equipment Market
Surgical Instruments
Medical Penlights Market
Surgical Instruments
Electrocautery Enhanced Delivery System Market
Surgical Instruments
Surgical Sphincteroplasty Market
Surgical Instruments
Global Electromagnetic Surgical Navigation System Market
Surgical Instruments
Harmonic Scalpel Market
Surgical Instruments
Minimally Invasive Gastrointestinal Surgical System Market
Surgical Instruments
Absorbable Surgical Suture with Needle Market
Surgical Instruments
Disposable Spinal Instruments Market