
 PCR Films Market | 2026-2036
PCR Films Market Size, Share, and Industry Trends Forecast 2026-2036
PCR Films Market Analytics
Healthcare packaging is consolidating as the dominant end-use vertical for PCR films, displacing slower-growing industrial segments. Thermo Fisher leverages its diagnostic supply chain depth to anchor film demand across clinical and research channels. Eppendorf specializes in precision-fit sealing films that sustain premium positioning in automated liquid handling workflows. Bio-Rad competes through thermal cycling compatibility and optical clarity specifications that dominate qPCR instrument ecosystems.
PCR films are thin, optically clear sealing membranes engineered from polyethylene, polypropylene, or polylactic acid substrates, manufactured via extrusion or cast film processes with controlled thickness tolerances of 50-150 micrometers for thermal cycling integrity. These films create gas-tight barriers that prevent evaporation during polymerase chain reaction protocols while permitting fluorescence detection. Transparent films lead the product type landscape due to universal instrument compatibility, though biodegradable films represent the fastest-expanding margin pool as pharmaceutical buyers shift procurement toward compostable alternatives under ESG mandates. Medical packaging commands the highest application-specific premiums, whereas food packaging operates as a volume-driven, specification-tightened segment.
The EPA regulates volatile organic compound emissions from film extrusion operations, while the EU Green Deal and REACH restrict persistent chemical additives in polymer substrates destined for clinical contact. FDA device packaging standards further shape barrier performance requirements for diagnostic-grade films. Stakeholders must monitor evolving compostability certification thresholds and regional chemical disclosure rules that will determine which material formulations retain market access across jurisdictions.
Market Dynamics
EU Green Deal compliance mandates are compressing formulation timelines for PCR film suppliers, forcing rapid substrate transitions from conventional polyolefins to certified biodegradable alternatives before 2035 regulatory deadlines.
Growth Catalysts
- REACH chemical restrictions:Persistent additive bans are redirecting pharmaceutical procurement toward compliant film grades, creating premium positioning for certified substrate suppliers.
- Centralized laboratory infrastructure:Germany's diagnostic hub concentration generates pull-through demand for high-performance sealing films compatible with automated thermal cyclers.
- Biodegradable PLA substrates:Compostable film formulations are capturing ESG-driven procurement mandates from biopharmaceutical packaging buyers seeking Scope 3 emission reductions.
Market Restraints
- Petrochemical input volatility:Polyethylene and polypropylene resin prices fluctuate with crude oil indices, compressing margin stability for extrusion-based film manufacturers.
- Optical clarity limitations:Biodegradable substrates currently exhibit inferior fluorescence transmission compared to conventional films, restricting adoption in quantitative PCR workflows.
- Compostability certification bottlenecks:EN 13432 and ASTM D6400 testing timelines extend 12-18 months, delaying market access for novel biodegradable formulations.
Strategic Opportunities
- Indian diagnostic expansion:CDSCO regulatory harmonization and domestic biopharma manufacturing incentives are opening procurement channels for imported PCR film grades.
- Food-to-medical substrate pivot:Cast film extrusion expertise from food packaging is transferable to medical-grade barrier films with FDA device packaging certification.
- Digital inventory platforms:Direct procurement portals are disintermediating traditional distributor networks for mid-volume clinical laboratory buyers.
Industry Challenges
- Polymer science talent scarcity:Formulation chemists with simultaneous expertise in biodegradability kinetics and thermal cycling compatibility command premium compensation.
- Multi-jurisdiction certification complexity:Simultaneous FDA, EMA, and PMDA device packaging approvals require divergent barrier performance testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PCR Films Market |
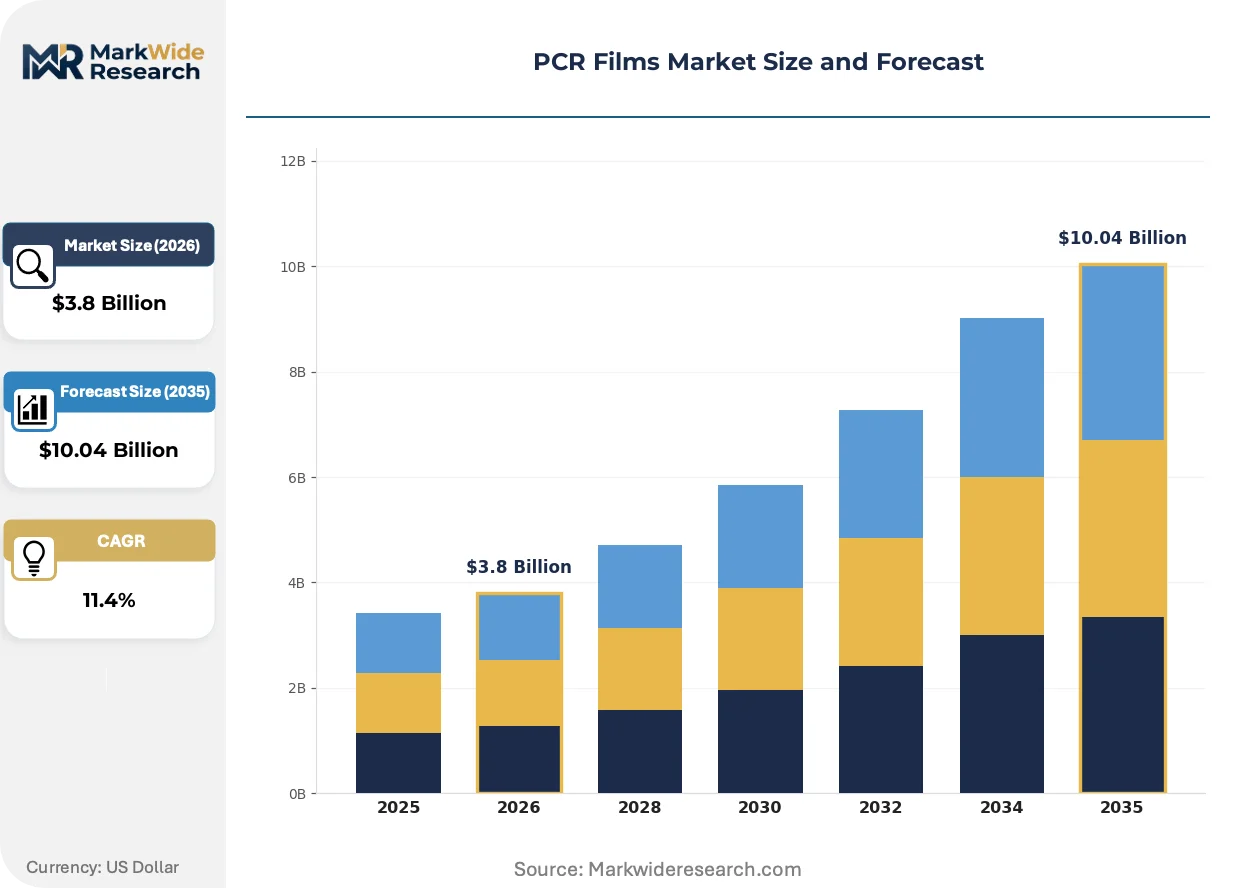
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biodegradable Films, Transparent Films, Coated Films, Non-Woven Films Application: Food Packaging, Medical Packaging, Industrial Packaging, Agricultural Mulching Material: Polyethylene, Polypropylene, Polylactic Acid, Polyvinyl Chloride End User: Food Industry, Healthcare, Agriculture, Manufacturing |
| Companies Covered | Eppendorf, Brooks Life Sciences, Thermo Fisher, Corning, National Scientific Corporation, Vitl Life Science Solutions, BioPointe Scientific, Starlab, Bio-Rad, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PCR Films Market Evolving Landscape
Material science advances and regulatory chemistry restrictions are converging to reshape PCR film specifications, with optical performance and compostability now treated as interdependent design parameters rather than trade-offs.
Cast polypropylene films with controlled crystallinity are consolidating as the dominant substrate for high-throughput diagnostic applications. Clinical laboratories in Germany and Switzerland are specifying these grades for automated liquid handling platforms. This consolidation is compressing demand for legacy polyethylene formulations that lack thermal dimensional stability.
EU Green Deal circular economy targets are mandating recycled content minimums in polymer substrates destined for clinical contact. REACH Annex XVII restrictions on phthalate plasticizers are forcing reformulation of legacy sealing films. Biopharmaceutical packaging buyers in the Netherlands and Denmark are now requiring third-party verified recycled content certificates.
Consolidated procurement through diagnostic instrument OEMs is displacing fragmented laboratory supply purchasing. Thermo Fisher and Eppendorf are bundling certified films with thermal cycler service contracts. This concentration is most visible in German university hospital networks and French national laboratory systems.
PCR Films Market Segmentation
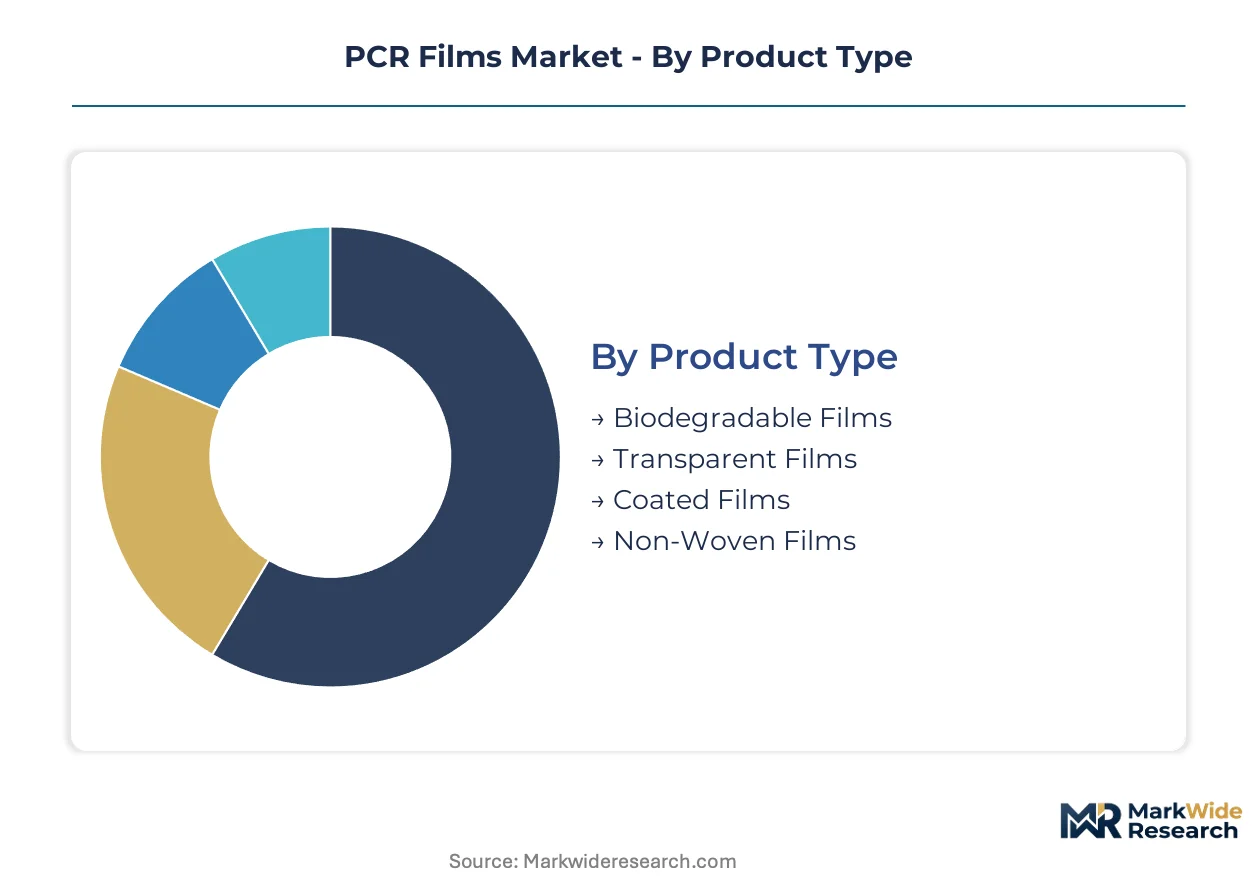
PCR film specifications diverge sharply across end-use requirements, with thermal cycling compatibility and optical clarity driving premium segmentation in diagnostic applications. Material composition and certification status now determine procurement eligibility under tightening EU and FDA frameworks.
Product Type:
Capital intensity varies substantially across manufacturing methods, with cast extrusion and coating lines requiring distinct equipment footprints and cleanroom investments.
- Transparent Films:Optical-grade polyethylene and polypropylene substrates manufactured via controlled cast extrusion deliver 90%+ fluorescence transmission for quantitative PCR instrumentation. German university hospital networks and Swiss diagnostic hubs specify these grades for automated thermal cycler compatibility.
- Biodegradable Films:Polylactic acid formulations processed through modified cast film lines with compostability certification infrastructure represent the steepest capital requirements due to extended EN 13432 testing timelines. ESG-mandated procurement from Dutch and Danish biopharmaceutical packagers is accelerating substrate transition investments.
- Coated Films:Barrier-enhanced substrates with silicone or acrylic adhesive layers for specialized sealing applications.
- Non-Woven Films:Fiber-based breathable membranes serving lower-barrier agricultural and industrial end-uses.
Transparent films absorb the bulk of installed capacity; biodegradable films are expanding most quickly.
Application:
Application segmentation tracks directly to regulatory burden and certification cost tiers, with medical-grade barriers commanding substantially higher qualification investments than commodity packaging.
- Medical Packaging:FDA device packaging standards and EMA sterilization barrier requirements govern gas-tight sealing films for diagnostic reagent kits and pharmaceutical primary packaging. Centralized laboratory infrastructure in Germany generates concentrated demand for validated film grades compatible with automated liquid handling workflows.
- Food Packaging:Cast polypropylene films with controlled crystallinity serve modified atmosphere packaging and fresh produce applications. REACH compliance and EU Green Deal recycled content mandates are redirecting formulation investments toward certified circular substrates.
- Industrial Packaging:General-purpose polyethylene sealing films for non-critical barrier applications with lower specification tolerance.
- Agricultural Mulching:Biodegradable and conventional films for soil temperature management and weed suppression in crop production systems.
Medical packaging commands premium pricing tiers; food packaging operates at volume scale with tightening specification convergence.
Material:
Raw material selection determines processing equipment compatibility and end-market access under evolving chemical restriction frameworks.
- Polypropylene:Isotactic homopolymers and random copolymers with controlled crystallinity profiles deliver thermal dimensional stability critical for automated thermal cycler workflows. Cast film grades specified by Thermo Fisher and Eppendorf instrument ecosystems dominate high-throughput diagnostic applications.
- Polylactic Acid:Bio-based aliphatic polyesters derived from corn starch or sugarcane require modified extrusion parameters and extended compostability certification timelines. REACH Annex XVII phthalate restrictions and EU Green Deal circular economy targets are accelerating substitution for conventional polyolefins in pharmaceutical packaging.
- Polyethylene:Linear low-density and metallocene grades for general-purpose sealing applications with lower thermal performance requirements.
- Polyvinyl Chloride:Legacy substrate facing declining clinical adoption due to plasticizer regulatory scrutiny and disposal restrictions.
Polypropylene holds the largest installed extrusion base; polylactic acid is climbing the fastest amid substrate transition mandates.
End User:
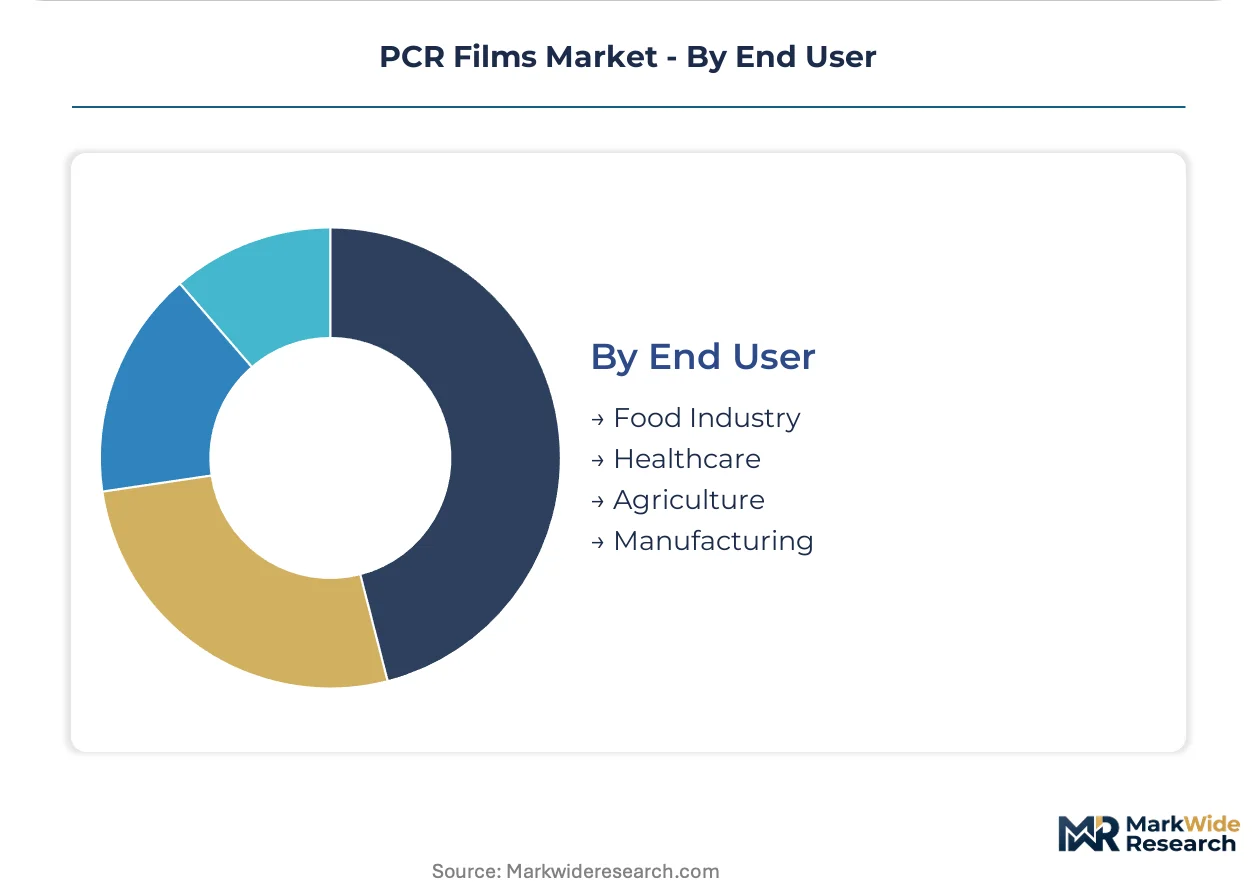
End-user concentration reflects procurement centralization trends, with diagnostic instrument OEMs and consolidated hospital networks displacing fragmented laboratory purchasing.
- Healthcare:Clinical diagnostic laboratories, biopharmaceutical manufacturers, and university hospital networks specify validated sealing films for PCR workflows and sterile barrier applications. Bundled procurement through thermal cycler service contracts with Thermo Fisher and Bio-Rad is concentrating demand in German and French national laboratory systems.
- Food Industry:Processors and packagers of fresh produce, dairy, and ready-to-eat meals utilizing modified atmosphere and vacuum sealing technologies. EU Green Deal recycled content certificates are becoming mandatory procurement filters in Netherlands and Denmark retail supply chains.
- Agriculture:Crop producers and horticultural operations deploying soil mulching and greenhouse climate control films.
- Manufacturing:Industrial assembly and logistics operations requiring general-purpose protective and barrier packaging solutions.
Healthcare end-users drive premium segment margins; food industry procurement is scaling fastest under sustainability certification expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Germany, India, and the United States are concentrating PCR film manufacturing through targeted tax incentives and streamlined pharmaceutical packaging approvals. These zones anchor regional supply networks serving diagnostic instrument clusters.
Germany
Centralized laboratory infrastructure in Baden-Württemberg and North Rhine-Westphalia drives demand for validated sealing films compatible with automated thermal cyclers. REACH Annex XVII restrictions on phthalate plasticizers redirect procurement toward compliant polypropylene grades. The Rhine-Main cluster around Frankfurt concentrates biopharmaceutical packaging operations requiring certified barrier films.
United States
FDA device packaging standards govern gas-tight sealing films for diagnostic reagent kits across Massachusetts and California life science corridors. EPA volatile organic compound regulations from film extrusion operations compress formulation timelines in Texas and Ohio manufacturing zones. The Research Triangle in North Carolina anchors clinical diagnostics demand through bundled thermal cycler service contracts.
India
CDSCO regulatory harmonization and domestic biopharma manufacturing incentives under the PLI scheme open procurement channels for imported PCR film grades in Maharashtra and Telangana. BIS certification requirements for medical device packaging materials create compliance barriers for local extrusion operations. The Genome Valley cluster near Hyderabad concentrates contract research organizations specifying validated sealing films.
Netherlands
ESG-mandated procurement from Dutch biopharmaceutical packagers accelerates substrate transitions toward compostable polylactic acid alternatives under EU Green Deal circular economy targets. EN 13432 compostability certification requirements extend testing timelines for novel biodegradable formulations. The Rotterdam-Antwerp port corridor facilitates import logistics for certified substrate suppliers serving Benelux diagnostic networks.
Switzerland
Swissmedic device packaging standards and precision diagnostic instrument manufacturing in Basel and Zurich sustain premium positioning for optical-grade sealing films. Dual carbon goals under federal climate legislation redirect pharmaceutical procurement toward verified recycled content certificates. The Greater Zurich Area concentrates thermal cycler OEM operations bundling certified films with service contracts.
PCR Films Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with diagnostic instrument OEMs consolidating procurement through bundled service contracts while independent laboratories fragment purchasing across distributor channels. The market structure tiers between premium-grade suppliers with multi-jurisdiction certifications and volume-oriented extrusion operations serving commodity packaging. Three archetypes dominate: thermal cycler OEM-captive film suppliers, independent medical-grade specialists, and diversified packaging converters pivoting from food to medical substrates. Capacity expansion and strategic partnerships represent the dominant competitive moves as suppliers seek EN 13432 certification infrastructure and FDA device packaging approvals.
Within the OEM-captive tier, Thermo Fisher and Eppendorf exemplify integrated supply chain positioning where instrument manufacturers anchor film demand through service contract bundling. Bio-Rad occupies a position representing thermal cycling compatibility specialists competing through optical clarity specifications. These three companies illustrate how diagnostic instrument ecosystems concentrate procurement power and compress margins for independent film suppliers lacking validated instrument compatibility.
| Leading Market Players |
|---|
| Eppendorf |
| Brooks Life Sciences |
| Thermo Fisher |
| Corning |
| National Scientific Corporation |
| Vitl Life Science Solutions |
| BioPointe Scientific |
| Starlab |
| Bio-Rad |
| Others |
Value Network & Pricing Analysis
Polypropylene resin futures on the London Metal Exchange serve as the primary cost anchor for PCR film extrusion operations, with price volatility cascading through three distinct procurement tiers that separate diagnostic OEM contract buyers from spot-market laboratory purchasers.
Pricing Analysis
Lead-time compression commands substantial premiums in PCR film procurement, with German university hospital networks paying elevated rates for validated grades delivered within 72 hours while spot inventory clears at discounted levels through distributor channels. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and instrument compatibility, with FDA device packaging validation and EN 13432 compostability certification anchoring the premium tier. Pricing pressure stems from petrochemical input volatility as polyethylene and polypropylene resin costs fluctuate with crude oil indices, compressing margin stability for extrusion-based manufacturers. Academic research laboratories exhibit the highest price sensitivity due to fragmented purchasing and grant-funded budget constraints, whereas biopharmaceutical packaging buyers prioritize compliance over cost.
Supply Chain Analysis
Dual-sourcing mandates from Thermo Fisher and Eppendorf instrument ecosystems require qualified suppliers to maintain redundant manufacturing footprints across Germany, Switzerland, and the United States. Raw material dependencies center on isotactic polypropylene homopolymers, polylactic acid feedstocks derived from corn starch or sugarcane, and silicone adhesive coatings for barrier-enhanced grades. Single-source vulnerability concentrates in specialized cast film extrusion lines with cleanroom specifications, where equipment lead times extend 18-24 months. Distribution runs through diagnostic instrument OEM service contracts for consolidated healthcare procurement, with independent laboratories accessing films via specialized life science distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PCR film manufacturing is consolidating into a vertical-integration race where control over compostability certification infrastructure and thermal cycler compatibility testing determines market access.
For Market Incumbents: Deploy backward integration into polylactic acid feedstock production to secure substrate supply amid EU Green Deal transition mandates. Incumbent suppliers must consolidate EN 13432 certification infrastructure and expand cast film extrusion capacity in Baden-Württemberg to defend against emerging biodegradable specialists capturing ESG-driven procurement. Capacity addition in certified cleanroom facilities represents the critical defensive lever against optical clarity limitations in novel PLA formulations. For New Entrants and Emerging Players: Compostable film formulations with third-party verified recycled content certificates offer the most penetrable wedge for disrupting established polypropylene supply relationships. New entrants should target Dutch and Danish biopharmaceutical packaging buyers where ESG mandates have outpaced incumbent certification timelines. Direct procurement portals for mid-volume clinical laboratories provide the optimal go-to-market angle for bypassing OEM-captive distribution channels. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap extrusion specialists with existing FDA device packaging approvals and underutilized cleanroom capacity in the Rhine-Main corridor. Long-term viability hinges on simultaneous REACH compliance and biodegradable substrate transition capabilities across the projection horizon. The signal to watch is CDSCO regulatory harmonization progress in India, which would unlock procurement channels for certified importers and signal inflection in emerging market penetration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PLA Feedstock | Secures substrate supply for EU Green Deal compliance ahead of 2035 deadlines. |
| EN 13432 Certification Infrastructure Buildout | Accelerates market access for biodegradable formulations facing 12-18 month testing timelines. |
| Direct Procurement Portal Development | Disintermediates distributor networks for mid-volume German and French laboratory buyers. |
| Cleanroom Cast Film Capacity Expansion | Addresses optical-grade polyethylene and polypropylene demand from Swiss diagnostic instrument OEMs. |
| CDSCO Regulatory Harmonization Partnership | Opens import channels for validated sealing films into Maharashtra and Telangana biopharma clusters. |
Research Methodology
Trade databases, ECHA REACH registration filings, and FDA device packaging 510(k) submissions formed the secondary backbone for supply-side mapping and regulatory trajectory assessment. Primary interviews with diagnostic instrument OEM procurement directors, biopharmaceutical packaging engineers, and polymer formulation chemists validated demand assumptions and pricing dynamics. Bottom-up and top-down triangulation reconciled extrusion capacity estimates against end-use consumption patterns across healthcare and food packaging verticals.
Bottom-up modeling anchored volume projections to installed thermal cycler base, instrument utilization rates, and per-run film consumption metrics across German, Swiss, and United States diagnostic hubs. Segmentation dimensions included product type, application, material composition, and end-user concentration to capture divergent margin structures. CAGRs were derived from regression analysis of historical resin price elasticity and regulatory-driven substitution curves for biodegradable substrates. Industry-specific inputs encompassed EN 13432 certification pipeline data and bundled service contract renewal rates from Thermo Fisher and Eppendorf ecosystems.
Several conditions sit outside the modeled scope, including abrupt REACH Annex XVII chemical restrictions, unilateral FDA device packaging standard revisions, and geopolitical disruptions to polylactic acid feedstock supply from corn starch or sugarcane sources. Deviation in EU Green Deal implementation timelines or compostability certification threshold adjustments would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Philippines Plastics Market
Plastic Packaging
Morocco Plastic Bottles Market
Plastic Packaging
United Arab Emirates Plastic Bottles Market
Plastic Packaging
Cast Films Market
Plastic Packaging
Plastic Packaging Market
Plastic Packaging
North America Plastic Bottles Market
Plastic Packaging
Japan Plastic Packaging Market
Plastic Packaging
North America Single-Use Plastic Packaging Market
Plastic Packaging
Plant-Based Plastic Packaging Market
Plastic Packaging
Plastic Ampoules Market
Plastic Packaging
Plastic Keg Market
Plastic Packaging
Europe Single-Use Plastic Packaging Market
Plastic Packaging
China Plastic Packaging Market
Plastic Packaging
Rewritable PVC Cards Market
Plastic Packaging
Global Plastic Tarpaulin Market
Plastic Packaging
Plastic Corrugated Sheets Market