
 Plastic Ampoules Market | 2026-2036
Plastic Ampoules Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Ampoules Market Analytics
Subscription-based packaging validation services are repositioning how pharmaceutical buyers procure plastic ampoules, shifting capital expenditure into operational contracts. Sanner GmbH leverages its German manufacturing base to dominate high-barrier polymer development for sensitive injectables. Gerresheimer AG sustains R&D intensity across blow-fill-seal technology platforms. Fresenius Kabi anchors European hospital supply chains through integrated fill-finish and distribution networks.
Plastic ampoules are small, sealed polymer containers manufactured through blow-fill-seal or injection-blow molding, typically holding 1–20 mL of liquid or powder for sterile single-use or multi-dose administration. Polypropylene dominates material selection for its thermal stability and chemical inertness during autoclave sterilization cycles. Single-use ampoules lead unit volume due to contamination risk reduction in hospital and laboratory settings, while multi-dose formats concentrate margin pools in ophthalmic and vaccine applications where preservative systems add formulation complexity.
EMA's Medical Device Regulation and the EU F-Gas Framework shape polymer selection and barrier validation protocols for European-market ampoules. FDA's Container Closure Guidance and USP <1207> package integrity standards govern US market access for sterile plastic primary packaging. India's CDSCO and BIS certification requirements for imported medical devices are tightening local manufacturing incentives. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and JP chapters to avoid redundant stability testing across export destinations.
Market Dynamics
Single-use sterility requirements and polymer barrier validation protocols are compressing procurement cycles, forcing pharmaceutical buyers to consolidate supplier relationships around validated blow-fill-seal platforms rather than spot-market sourcing.
Growth Catalysts
- EMA MDR compliance deadlines:Pharmaceutical manufacturers are accelerating polymer ampoule qualification to meet European Medical Device Regulation material traceability mandates before enforcement windows tighten.
- Biologics cold-chain expansion:mRNA vaccines and temperature-sensitive biologics require polypropylene ampoules with validated thermal stability profiles for distribution networks spanning Germany, India, and the United States.
- Blow-fill-seal automation:Contract packaging hubs are scaling continuous manufacturing lines that integrate forming, filling, and sealing into single validated workflows, reducing human intervention contamination risks.
Market Restraints
- Polypropylene feedstock volatility:Propylene monomer supply disruptions from petrochemical crackers in the US Gulf Coast and Rotterdam harbor create input cost instability for ampoule converters.
- High-barrier film concentration:Ethylene vinyl alcohol copolymer supply for oxygen-sensitive injectables concentrates among three Japanese and German specialty chemical suppliers, creating single-source vulnerability.
- Glass substitution persistence:Borosilicate ampoules retain preference for certain light-sensitive oncology formulations where polymer barrier validation remains incomplete.
Strategic Opportunities
- Indian CDSCO localization incentives:Import substitution policies for sterile primary packaging create manufacturing joint-venture openings for European ampoule specialists seeking tariff-advantaged supply positions.
- Ophthalmic preservative-free multi-dose:Novel valve technologies enable multi-use plastic ampoules without benzalkonium chloride, opening formulation partnerships with dry-eye therapy developers.
- WHO prequalification pathway:Vaccine ampoule suppliers pursuing WHO PQ certification gain preferred supplier status for UN procurement tenders and Gavi-funded immunization programs.
Industry Challenges
- Extractables-leachables validation timelines:USP <1664> and USP <1664.1> testing protocols for polymer additives require 18-24 month stability studies, delaying product launches.
- Sterile fill-finish technician scarcity:Aseptic processing operators with ISO 14644 cleanroom certification command premium wages in Germany and the United States, constraining capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Ampoules Market |
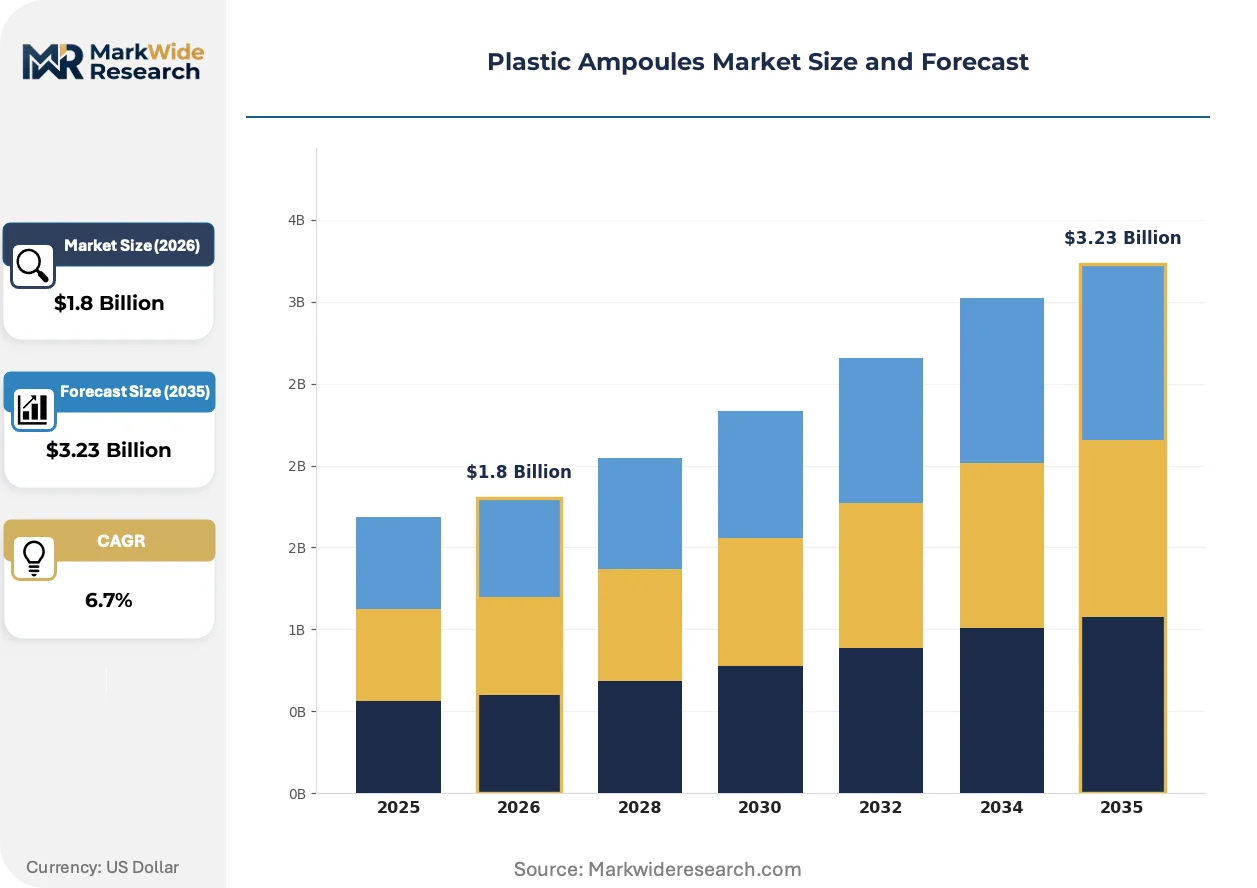
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-use, Multi-dose, Customizable, Standardized End User: Pharmaceutical Companies, Research Laboratories, Hospitals, Contract Packaging Material: Polypropylene, Polyethylene, PVC, PET Application: Injectables, Vaccines, Laboratory Samples, Diagnostic Reagents |
| Companies Covered | Sanner GmbH, James Alexander Corporation, LF of America Corporation, Lameplast Group SpA, VALMAPAK, LLC, CDM LAVOISIER, Fresenius Kabi, Gerresheimer AG, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Ampoules Market Evolving Landscape
Barrier engineering and digital traceability systems are converging to redefine how pharmaceutical manufacturers validate and track polymer primary packaging across distributed supply networks.
Cyclic olefin polymer-copolymer blends are unifying optical clarity with moisture barrier performance in blow-fill-seal ampoules. Ophthalmic and diagnostic reagent manufacturers are adopting these materials for light-sensitive formulations previously restricted to glass. The technology is unifying previously separate material qualification streams, collapsing dual-source polymer inventories into single-platform supply agreements.
EU F-Gas Regulation phase-down schedules are accelerating hydrofluorocarbon-free barrier coating development for polymer ampoules. Industrial gas suppliers and packaging converters are jointly validating plasma-enhanced chemical vapor deposition alternatives. European vaccine fill-finish contractors are absorbing qualification costs to maintain CE-marked product access.
Hospital procurement consortia are consolidating plastic ampoule purchasing through centralized sterile compounding pharmacy networks. Group purchasing organizations are displacing direct manufacturer relationships with formulary-managed contracts. This concentration is most visible in United States health system alliances and German hospital federation tendering.
Plastic Ampoules Market Segmentation
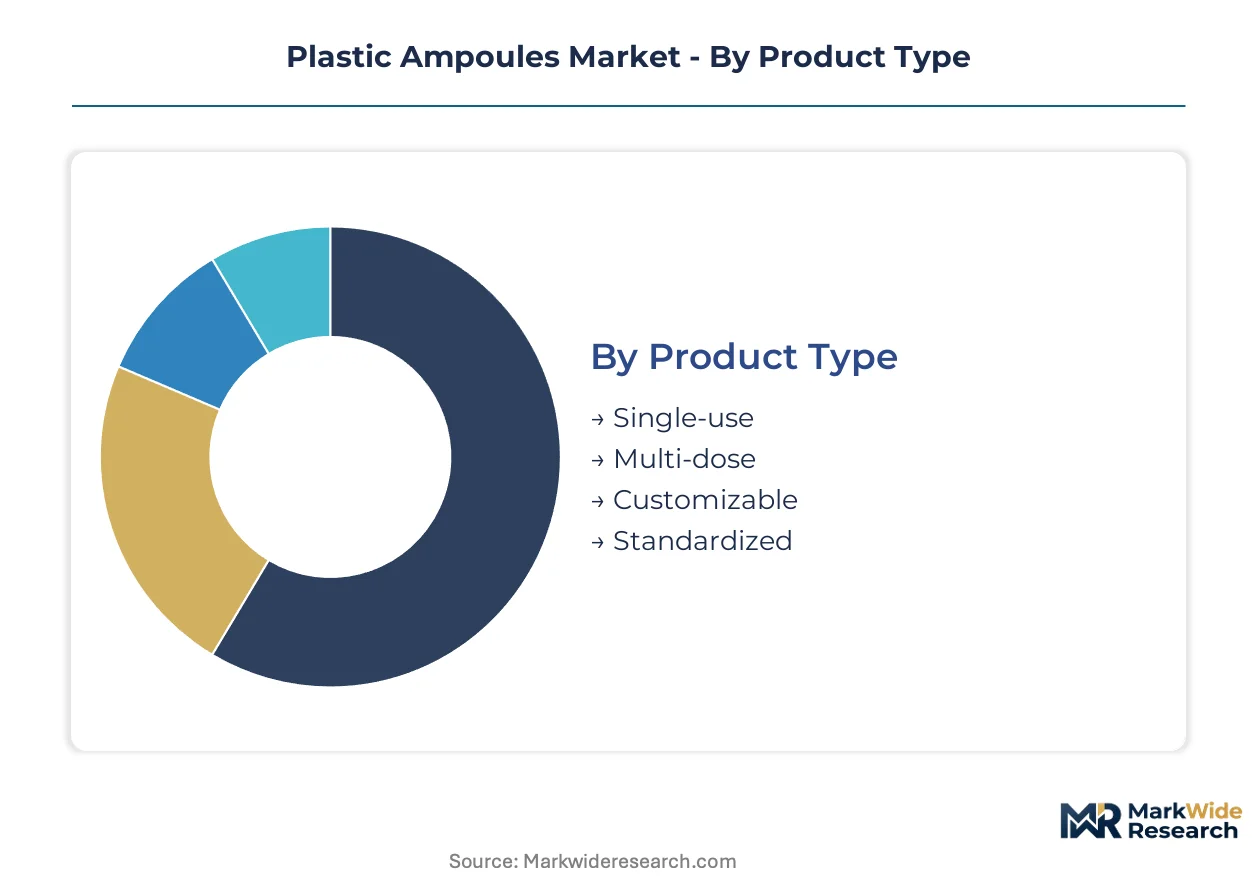
Segmentation in plastic ampoules reveals how polymer selection and sterility requirements split procurement decisions across pharmaceutical value chains. Material barriers, dosing formats, and end-user validation protocols create distinct competitive arenas with diverging margin structures and supplier consolidation patterns.
Product Type:
Single-use formats dominate standalone sterile applications where contamination elimination outweighs unit economics, while multi-dose systems embed into ophthalmic and vaccine delivery platforms requiring preservative integration.
- Single-use:Blow-fill-seal manufacturing yields hermetically sealed polypropylene units for immediate disposal after opening. Hospital pharmacies and biologics manufacturers in Germany and the United States specify these formats for parenteral nutrition and chemotherapy compounding to eliminate cross-contamination pathways.
- Multi-dose:Reclosable polymer ampoules incorporate valve mechanisms or septum seals for repeated sterile access. Ophthalmic dry-eye therapies and multi-injection vaccine regimens in India drive procurement, though benzalkonium chloride-free preservation systems add formulation qualification complexity.
- Customizable:Bespoke dimensional and barrier specifications for clinical trial materials and orphan drug packaging.
- Standardized:Off-the-shelf ISO 8362-compliant formats for high-volume generic injectables.
Single-use leads volumes today; multi-dose is gaining share fastest in preservative-free ophthalmic applications.
End User:
Customer type determines validation burden and contract structure, with integrated pharmaceutical manufacturers absorbing qualification costs internally while contract packagers monetize sterile processing expertise.
- Pharmaceutical Companies:Large molecule developers specify cyclic olefin polymer blends for light-sensitive biologics. Internal fill-finish operations at Merck KGaA and Fresenius Kabi sites in Germany maintain captive ampoule inventories validated against EMA MDR traceability mandates.
- Contract Packaging:Specialized sterile fill-finish providers like Vetter and Catalent consolidate multi-client demand onto validated blow-fill-seal lines. CDSCO localization requirements in India are accelerating joint ventures between European ampoule specialists and domestic contract manufacturers.
- Hospitals:Centralized sterile compounding pharmacies in United States health systems.
- Research Laboratories:Diagnostic reagent and assay developers with lower volume, higher SKU complexity.
Pharmaceutical companies anchor procurement value; contract packaging is climbing the fastest as biologics developers outsource capital-intensive sterile capacity.
Material:
Polymer selection trades thermal stability, moisture barrier, and optical clarity against extractables-leachables validation timelines and feedstock cost volatility.
- Polypropylene:Dominant material for autoclave-stable sterile packaging. Random and block copolymer grades withstand 121°C steam sterilization cycles while maintaining dimensional integrity for blow-fill-seal processing. United States and German vaccine manufacturers specify pharmaceutical-grade homopolymer for mRNA cold-chain distribution.
- PVC:Phthalate-plasticized formats for non-parenteral diagnostic reagents where barrier requirements relax. ECHA REACH restrictions on DEHP plasticizers are displacing volumes into polyethylene alternatives for European-market products.
- Polyethylene:Lower-cost option for non-sterile laboratory sample containers.
- PET:Limited penetration in oxygen-sensitive applications requiring co-injection barrier layers.
Polypropylene commands the largest installed base; polyethylene is expanding most quickly in cost-sensitive diagnostic segments.
Application:
Clinical use case dictates barrier specification, with injectables requiring the most stringent oxygen and moisture protection and diagnostic reagents tolerating broader polymer tolerances.
- Injectables:Parenteral drug delivery demands validated oxygen and moisture barriers for stability-critical biologics. Cyclic olefin polymer-copolymer blends are displacing glass for light-sensitive oncology formulations in German and United States hospital networks, though USP <1664> extractables studies extend qualification timelines.
- Vaccines:Temperature-sensitive formulations require polypropylene thermal stability profiles validated across distribution cold chains. WHO prequalification pathways for plastic primary packaging are opening UN procurement tenders to polymer ampoule suppliers meeting Gavi immunization program specifications.
- Diagnostic Reagents:PCR master mixes and immunoassay components with moderate barrier needs.
- Laboratory Samples:Research-grade containment with minimal regulatory validation burden.
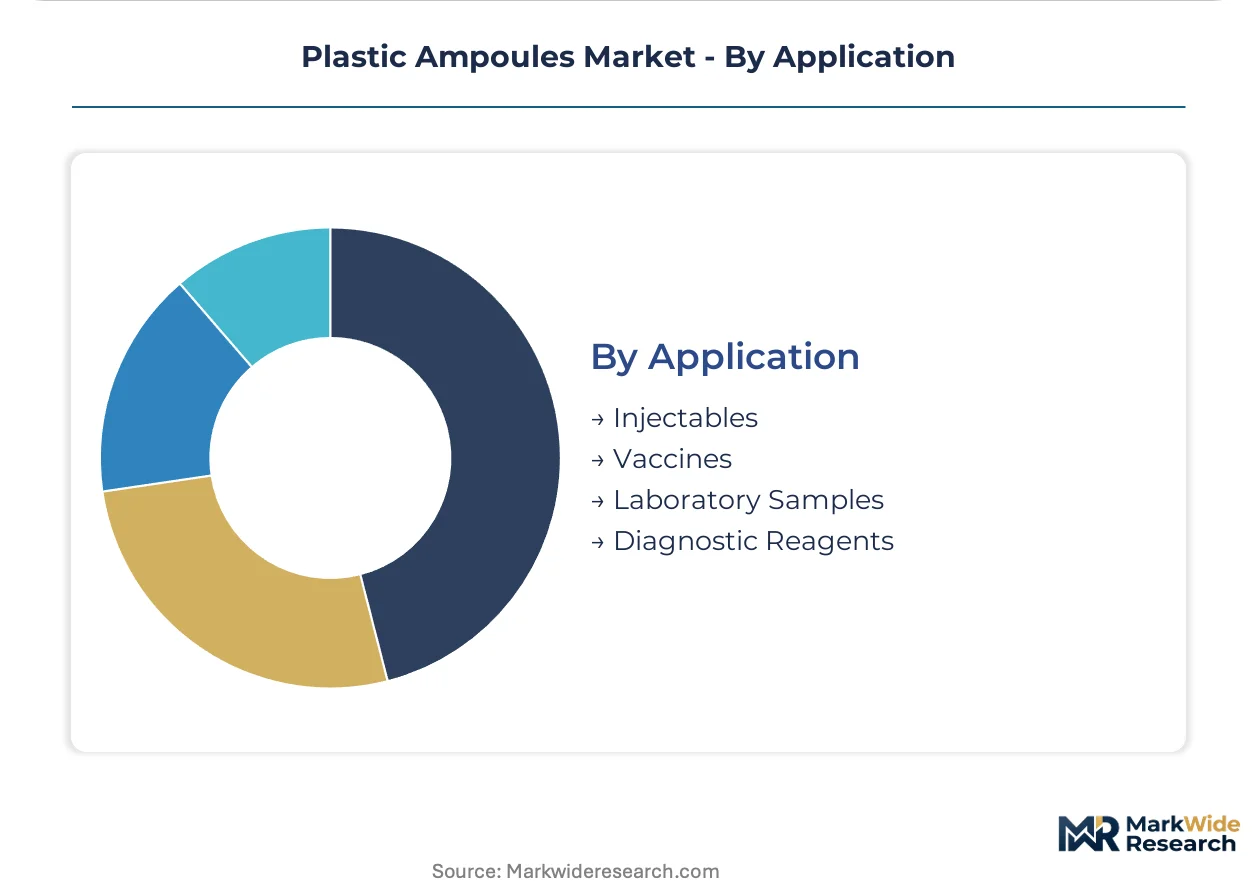
Injectables generate the highest revenue per unit; vaccines show the steepest expansion trajectory as mRNA platform developers qualify polymer alternatives to glass.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production geography as manufacturers migrate sterile fill-finish capacity toward jurisdictions with favorable compliance cost structures and localized procurement incentives.
Germany
Bavaria's pharmaceutical corridor anchors European demand for high-barrier polymer ampoules serving biologics manufacturers. EMA MDR traceability mandates and F-Gas Regulation phase-downs are accelerating qualification of hydrofluorocarbon-free barrier coatings among converters near Munich and Frankfurt. The Baden-Württemberg cluster concentrates blow-fill-seal automation engineering expertise for export-oriented sterile packaging lines.
United States
mRNA vaccine cold-chain expansion and hospital consolidation are concentrating procurement through group purchasing organizations in the Midwest and Southeast. FDA Container Closure Guidance and USP <1207> integrity standards govern market access, while sterile compounding pharmacy networks in Texas and Illinois displace direct manufacturer relationships with formulary-managed contracts.
India
CDSCO import substitution policies and BIS certification requirements for sterile primary packaging are incentivizing domestic manufacturing joint ventures. Maharashtra and Gujarat host contract packaging hubs scaling blow-fill-seal capacity for European and North American pharmaceutical clients seeking tariff-advantaged supply positions. Telangana's vaccine manufacturing corridor is driving polypropylene ampoule qualification for UN procurement tenders.
Japan
PMDA pharmacopeial harmonization with USP and EP chapters reduces redundant stability testing for polymer primary packaging exports. The Kanto region around Tokyo concentrates ethylene vinyl alcohol copolymer supply for oxygen-sensitive injectables, while Osaka-based converters develop cyclic olefin polymer blends for light-sensitive oncology formulations.
Switzerland
Swissmedic certification requirements and proximity to German pharmaceutical R&D clusters position Basel and Zurich as validation centers for novel barrier technologies. Alpine logistics hubs support temperature-sensitive biologics distribution across European markets, with local converters specializing in small-batch clinical trial materials for orphan drug developers.
Plastic Ampoules Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated pharmaceutical companies maintaining captive capacity for sensitive biologics while outsourcing commodity injectables to sterile fill-finish providers. The vendor base organizes around three strategic archetypes: German-engineered high-barrier polymer developers, North American blow-fill-seal automation specialists, and Indian contract packaging scale operators. Consolidation pressures favor backward integration into polymer compounding and forward integration into distribution networks. Technology licensing agreements and WHO prequalification partnerships represent the dominant competitive moves for vaccine ampoule suppliers.
Within the European-engineered tier, Sanner GmbH and Gerresheimer AG exemplify high-barrier polymer development for sensitive injectables, while Fresenius Kabi anchors integrated fill-finish and hospital supply chain positioning. These German-origin entities occupy positions that bridge pharmaceutical-grade material science with regulatory-validated manufacturing platforms, representing the archetype of compliance-forward supply relationships that pharmaceutical buyers consolidate around during procurement cycle compression.
| Leading Market Players |
|---|
| Sanner GmbH |
| James Alexander Corporation |
| LF of America Corporation |
| Lameplast Group SpA |
| VALMAPAK, LLC |
| CDM LAVOISIER |
| Fresenius Kabi |
| Gerresheimer AG |
| Merck KGaA |
| Others |
Value Network & Pricing Analysis
Family-owned German engineering specialists anchor supply-side discipline through long-tenured polymer compounding relationships, converting EMA MDR compliance investments into pricing premiums that pharmaceutical buyers absorb rather than arbitrage away through spot-market sourcing.
Pricing Analysis
Capacity additions in India are reshaping price floors for standardized polypropylene ampoules, compressing margins on commodity formats while premium cyclic olefin polymer blends sustain three-tier pricing structure across premium, standard, and economy levels in European and North American markets. Price differentiation hinges on USP <1664> extractables validation completion and ISO 15378 certification tier, with contract packaging buyers in Germany least sensitive to unit cost and Indian diagnostic reagent distributors most responsive to volume discounts. Pricing pressure stems from propylene monomer feedstock volatility originating in US Gulf Coast petrochemical complexes, forcing converters to index long-term offtake contracts to regional cracker margins.
Supply Chain Analysis
Single-source vulnerability sits with ethylene vinyl alcohol copolymer supply concentrated among Japanese and German specialty chemical producers, creating bottleneck exposure for oxygen-sensitive injectables. Manufacturing draws from polypropylene resin production in Germany, India, and the United States, with blow-fill-seal equipment fabrication anchored in Baden-Württemberg engineering clusters. Supply chain risk centers on tariff exposure for Indian contract manufacturers serving European pharmaceutical clients under evolving DGFT duty structures. Distribution runs through hospital group purchasing organizations in the United States Midwest and Southeast, displacing direct manufacturer relationships with formulary-managed contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where biologics cold-chain expansion shifts procurement toward validated barrier specifications that reward compliance-forward suppliers with durable margin structures.
For Market Incumbents: Deploy backward integration into pharmaceutical-grade polypropylene compounding to defend against feedstock volatility and capture EMA MDR traceability premiums. Incumbents should consolidate blow-fill-seal automation engineering expertise through selective acquisition of Baden-Württemberg equipment specialists, while accelerating cyclic olefin polymer blend qualification to preempt glass substitution persistence in oncology formulations. For New Entrants and Emerging Players: CDSCO localization incentives in India open a window for European ampoule specialists to establish tariff-advantaged manufacturing joint ventures with domestic contract packagers in Maharashtra and Gujarat. New entrants should target preservative-free ophthalmic multi-dose formats where novel valve technologies enable formulation partnerships with dry-eye therapy developers, leveraging WHO prequalification pathways to access UN procurement tenders and Gavi-funded immunization programs. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap Indian contract packaging scale operators with incomplete backward integration into polymer validation capabilities. Long-term viability favors targets with captive sterile fill-finish capacity and established EMA MDR compliance documentation, with the inflection signal to monitor being acceleration in mRNA vaccine platform developers qualifying polymer alternatives to borosilicate glass for light-sensitive biologics distribution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captures EMA MDR traceability premiums and insulates margins from propylene monomer volatility. |
| WHO Prequalification Pathway | Unlocks preferred supplier status for UN procurement tenders and Gavi-funded immunization programs. |
| Blow-Fill-Seal Automation Scale-Up | Reduces human intervention contamination risks for biologics manufacturers in Germany and the United States. |
| Cyclic Olefin Polymer Blend Qualification | Displaces glass for light-sensitive oncology formulations in hospital networks requiring USP <1664> validation. |
| Indian Manufacturing Joint Venture | Secures tariff-advantaged supply positions under CDSCO import substitution policies for European pharmaceutical clients. |
Research Methodology
Coverage spans Germany, India, the United States, Japan, and Switzerland, with primary inputs from each market combining structured interviews with sterile fill-finish operations directors, pharmaceutical regulatory affairs leads, hospital GPO contracts managers, and polymer compounding technical directors with secondary validation. Secondary sources include EMA MDR submission databases, FDA Container Closure Guidance filings, USP pharmacopeial chapter revisions, CDSCO import licensing records, and BIS certification registries. Bottom-up unit volume estimates triangulate against top-down pharmaceutical packaging expenditure flows.
Rate-of-change decomposition separates volume expansion from value capture across material grade tier, end-use application, and regional regulatory cluster dimensions throughout the forecast period. CAGRs derive from segmented demand modeling incorporating blow-fill-seal line capacity additions, biologics pipeline progression by therapeutic area, and polymer barrier validation timeline distributions.
Revisions become necessary when EMA MDR enforcement windows accelerate, propylene supply disruptions from US Gulf Coast crackers intensify, or WHO prequalification standards for plastic primary packaging shift. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Asia Pacific Plastic Bottles Market
Plastic Packaging
Japan Plastic Packaging Market
Plastic Packaging
Europe Polyethylene Terephthalate (PET) Market
Plastic Packaging
South Africa Rigid Plastic Packaging Market
Plastic Packaging
Plastic Caulk Tube Market
Plastic Packaging
Plastic Carboy Market
Plastic Packaging
Italy Plastic Bottles Market
Plastic Packaging
Vietnam Plastic Bottles Market
Plastic Packaging
Plastic Crates Market
Plastic Packaging
Poland Plastic Packaging Tubes Market
Plastic Packaging
Folding Plastic Crates Market
Plastic Packaging
Latin America Single-Use Plastic Packaging Market
Plastic Packaging
Spain Plastic Bottles Market
Plastic Packaging
Blow Moulded Plastic Packaging Market
Plastic Packaging
GCC PET Packaging Market
Plastic Packaging
North America Single-Use Plastic Packaging Market