
 GCC Plastic Packaging Market | 2026-2036
GCC Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Plastic Packaging Market Insights
Saudi Arabia's domestic resin production base is hardening around petrochemical feedstock advantages. SABIC leverages its upstream polyethylene and polypropylene output to supply captive and third-party converters across the Kingdom. Napco National anchors a diversified portfolio spanning industrial films, consumer bags, and food-service disposables. Hotpack Packaging Industries LLC specializes in thermoformed containers and printed flexible packaging for the food-service channel.
GCC plastic packaging encompasses fabricated polymer structures—typically 10–500 microns in film gauge, or 0.3–2.0 millimeters in rigid wall thickness—produced via extrusion blow molding, injection molding, or cast film processes, designed to contain, protect, and present goods across supply chains. Polyethylene dominates material throughput due to its versatility in both high-density rigid bottles and low-density flexible films. Food and Beverage end-use applications command the largest value share, though Healthcare packaging carries superior margin pools owing to sterilization-grade compliance and shorter production runs. Bottles represent a mature, high-volume format, while Films capture growth from snack-food expansion and e-commerce protective wrapping.
SASO's technical regulations for food-contact plastics, alongside UAE's ESMA conformity requirements and Gulf Standardization Organization harmonization protocols, collectively elevate barrier-property and migration-limit standards across member states. These frameworks compel converters to validate raw-material traceability and accelerate substitution of legacy additives. Stakeholders must monitor evolving extended-producer-responsibility consultations in the UAE and Saudi Arabia, as post-consumer collection mandates will reshape resin sourcing and recycling-capital allocation.
Market Dynamics
SASO's tightening food-contact material protocols are forcing Gulf converters to revalidate raw-material traceability and accelerate additive substitution, compressing legacy supply relationships while favoring integrated petrochemical-to-packaging operations.
Growth Catalysts
- Food-service channel expansion:Quick-service restaurant chains across Saudi Arabia and the UAE are standardizing thermoformed container specifications, pulling volume through dedicated converter capacity.
- SASO technical regulations:Migration-limit enforcement for polyethylene and polypropylene food-contact applications is filtering out non-compliant imports and protecting domestic converter margins.
- Flexible film substitution:Snack-food producers are displacing rigid formats with multilayer barrier films to reduce freight weight and extend shelf stability in ambient Gulf climates.
Market Restraints
- Feedstock concentration:SABIC's dominance in Saudi polyethylene and polypropylene supply creates single-source vulnerability for independent converters lacking long-term offtake agreements.
- Extended producer responsibility uncertainty:Pending post-consumer collection mandates in the UAE and Saudi Arabia are freezing recycling-capital commitments until compliance thresholds clarify.
- Monomaterial technical ceiling:Current polyethylene barrier performance cannot match multilayer structures for oxygen-sensitive applications, limiting circular-design adoption in premium food segments.
Strategic Opportunities
- Healthcare packaging vertical:Sterilization-grade compliance requirements for pharmaceutical blister packs and IV containers command margin pools three to four times above commodity food applications.
- Kuwait and Oman penetration:These markets remain undersupplied with localized flexible film converting, forcing brand owners to absorb freight-inflated Saudi or UAE supply.
- Digital printing convergence:Combination of narrow-web flexo with inline quality inspection is enabling run-length compression down to five thousand units for seasonal promotional packs.
Industry Challenges
- Migration testing capacity:SASO-accredited laboratories face eighteen-month backlogs for food-contact compliance certification, delaying new product launches.
- Skilled technician scarcity:Extrusion blow molding and cast film line operation requires specialized training unavailable in regional vocational pipelines, inflating wage premiums.
- Legacy equipment integration:Retrofitting existing lines for monomaterial output without sacrificing throughput demands capital expenditure many mid-cap converters cannot access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Plastic Packaging Market |
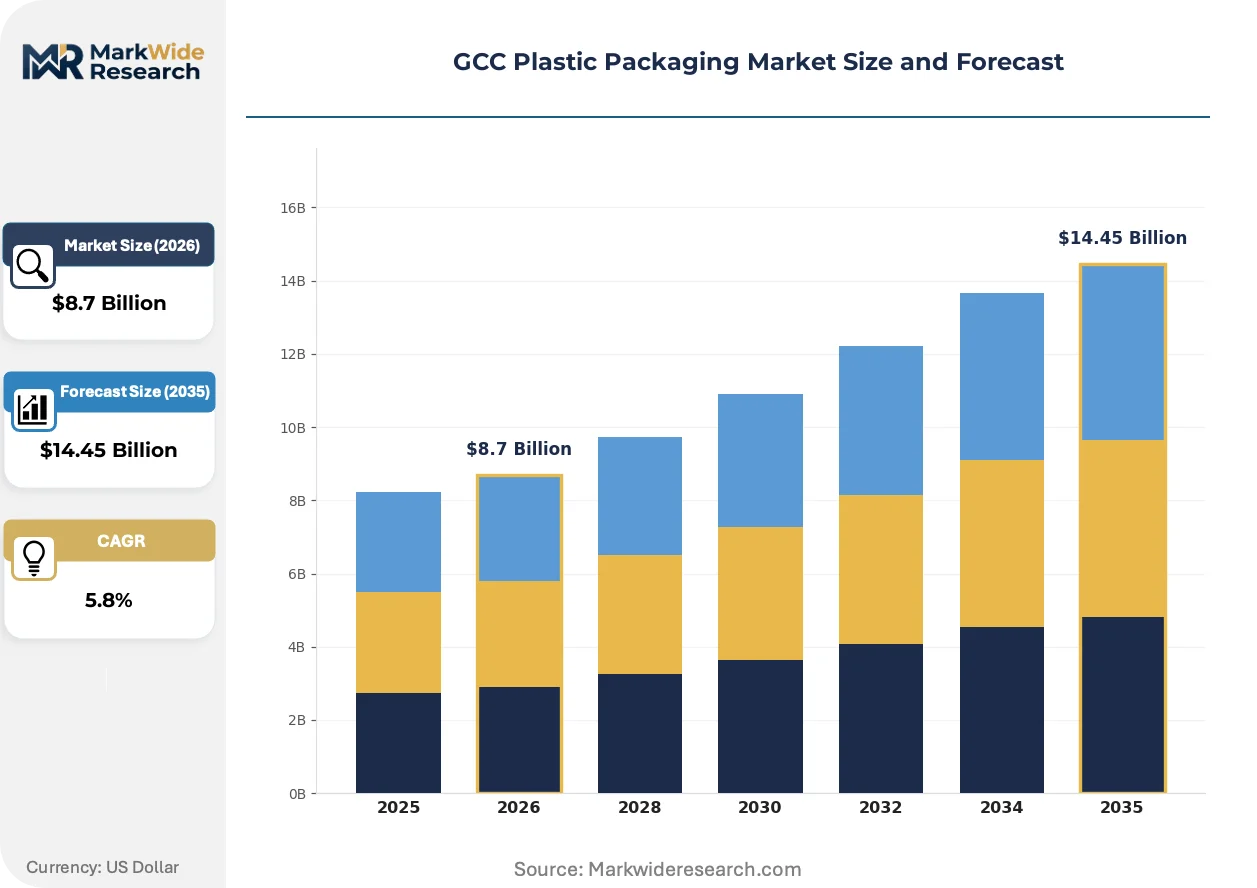
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bags, Containers, Bottles, Films End User: Food & Beverage, Healthcare, Cosmetics, Household Material: Polyethylene, Polypropylene, Polyvinyl Chloride, Polystyrene Application: Packaging, Labeling, Wrapping, Sealing |
| Companies Covered | Napco National, Saudi Basic Industries Corporation (SABIC), Zamil Plastic Industries Ltd., 3P Gulf Group, Arabian Plastic Industrial Company Limited (APICO), Hotpack Packaging Industries LLC, Integrated Plastics Packaging LLC, Amcor plc, Huhtamaki Oyj, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Plastic Packaging Market Trends and Innovations
Active and intelligent packaging formats are penetrating Gulf supply chains as brand owners seek differentiation in crowded retail environments and logistics operators demand real-time condition monitoring.
Smart labels incorporating time-temperature indicators and near-field communication tags are decentralizing quality verification away from centralized laboratory testing. Pharmaceutical distributors and premium dairy processors across Saudi Arabia are piloting these formats for cold-chain integrity. This shift is compressing the role of third-party inspection services while embedding compliance documentation directly into package structures.
SASO's harmonization with Gulf Standardization Organization protocols is elevating barrier-property benchmarks for imported food-contact plastics. Converters must now document raw-material chain of custody from resin pellet through finished article. Small-scale importers lacking this traceability infrastructure are exiting the market, consolidating volume with integrated domestic producers capable of end-to-end documentation.
Brand-owner buying committees are consolidating supplier panels from fifteen to three qualified converters per format category, prioritizing those with in-house testing laboratories and SASO pre-certification. This concentration is visible most acutely in Dubai's retail modernization projects, where master service agreements now span five-year horizons with volume guarantees and penalty clauses for non-compliance.
GCC Plastic Packaging Market Segmentation
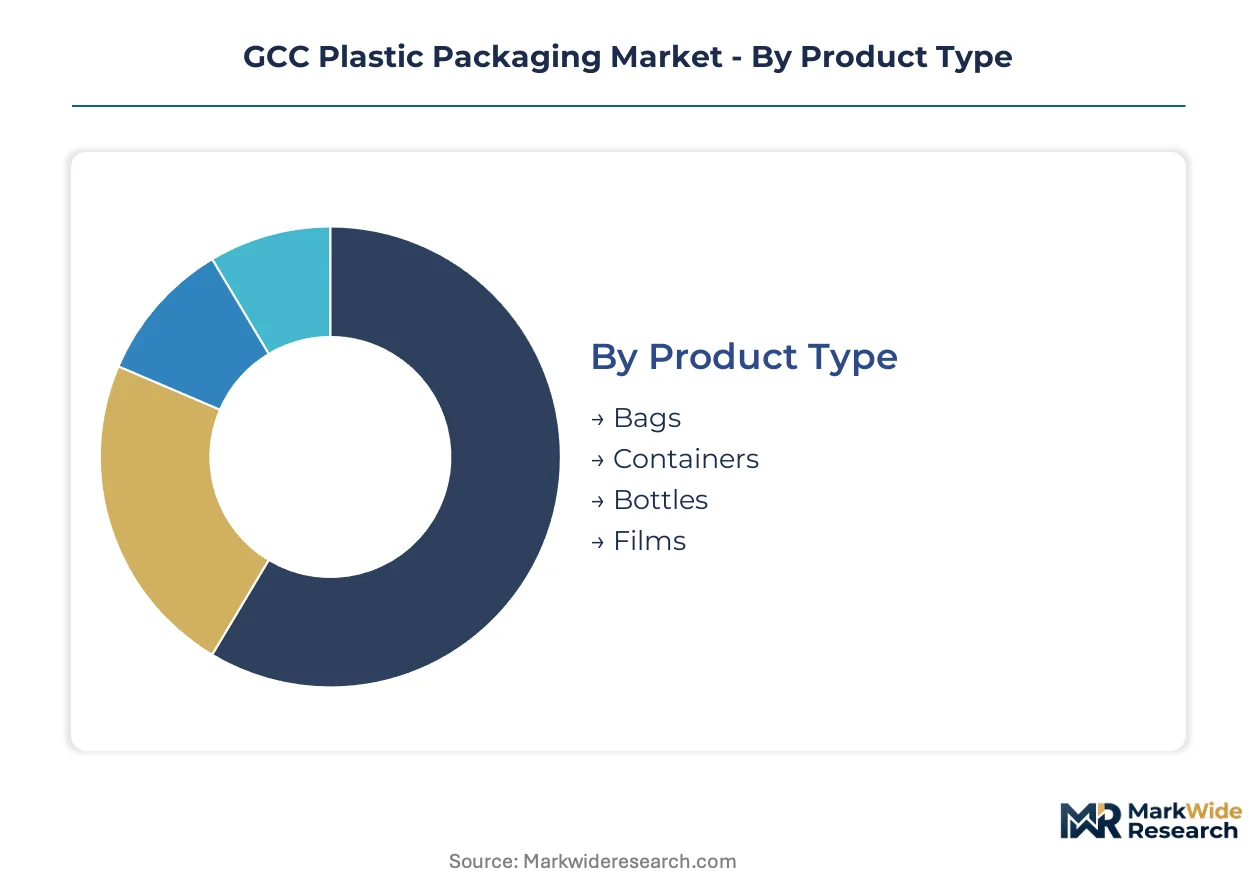
GCC plastic packaging procurement patterns diver sharply across product formats and compliance requirements. Material selection and end-use specifications dictate converter capability investments and margin structures throughout the Gulf supply chain.
Product Type:
Buyers differentiate by barrier performance needs and automation compatibility with existing filling lines.
- Bottles:High-density polyethylene and PET structures dominate beverage and dairy containment. Saudi dairy processors and UAE bottled-water brands drive volume through injection-stretch blow molding lines optimized for 250ml to 5-liter formats. SASO migration-limit compliance has eliminated several Asian import suppliers, tightening domestic capacity allocation.
- Films:Cast and blown polyethylene films with oxygen-barrier layers protect snack foods and frozen proteins across ambient Gulf distribution. Multilayer coextrusion lines at Napco National and Hotpack supply retail chains replacing rigid formats to cut freight weight.
- Containers:Thermoformed polypropylene tubs and trays serve quick-service restaurant chains standardizing on single-specification procurement across Saudi Arabia and UAE outlets.
- Bags:Low-density polyethylene shopper and refuse bags face margin compression from informal recycling feedstock competition in UAE free zones.
Volume sits with Bottles; growth tilts toward Films.
End User:
Margin pools separate sharply between commodity food applications and compliance-intensive healthcare segments.
- Food & Beverage:Dairy, bottled water, and snack-food producers account for the dominant throughput share. Saudi retail modernization and mega-infrastructure project canteen contracts pull volume through dedicated converter capacity with five-year master service agreements.
- Healthcare:Sterilization-grade blister packs, IV containers, and pharmaceutical bottles command premium pricing three to four times above commodity food tiers. Compliance with Gulf Standardization Organization medical-device protocols limits qualified supplier pools.
- Cosmetics:Premium skincare and fragrance brands in Dubai's retail corridors specify decorated rigid bottles with metallized finishes, requiring specialized injection molding and hot-stamping capabilities.
- Household:Detergent and cleaning-product bottles compete primarily on unit cost, with private-label converters leveraging SABIC feedstock proximity in Jubail Industrial City.
Revenue concentrates in Food & Beverage; margin expansion is steepest in Healthcare.
Material:
Upstream petrochemical integration determines converter cost position and formulation flexibility.
- Polyethylene:High-density grades serve rigid bottles and containers; low-density and linear-low variants dominate film extrusion. SABIC's Yanbu and Jubail complexes supply the majority of Gulf resin, creating feedstock advantage for Saudi-based converters.
- Polypropylene:Random and impact copolymers enable thermoformed food-service containers with hot-fill tolerance. Quick-service restaurant standardization on polypropylene specifications is displacing polystyrene in Saudi Arabia.
- Polyvinyl Chloride:Pharmaceutical blister packs and some construction-chemical bottles retain niche demand despite environmental scrutiny on chlorine chemistry.
- Polystyrene:General-purpose and high-impact grades persist in disposable cutlery and some dairy cups, though food-service channel substitution toward polypropylene is accelerating.
Throughput dominance belongs to Polyethylene; substitution momentum favors Polypropylene.
Application:
Functional role in the supply chain dictates performance specifications and value-added service requirements.
- Packaging:Primary containment structures—bottles, containers, pouches—represent the core revenue pool. Brand owners demand integrated design services and SASO pre-certification support from converter partners.
- Wrapping:Stretch film and shrink film protect palletized goods through Gulf distribution networks. E-commerce fulfillment center expansion in Dubai South and Riyadh is pulling automated wrapping equipment demand.
- Labeling:Pressure-sensitive and shrink-sleeve labels require compatible substrate surfaces and adhesive systems, often sourced from specialized narrow-web converters rather than primary packaging suppliers.
- Sealing:Induction seals and tamper-evident closures complete package integrity systems, with pharmaceutical and dairy applications driving compliance-grade specifications.
Primary value capture occurs in Packaging; automation integration is advancing fastest in Wrapping.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's Jubail and Yanbu petrochemical complexes anchor Gulf resin supply, feeding converter networks across six member states with differentiated demand profiles and regulatory maturity.
Saudi Arabia
Mega-infrastructure projects and retail modernization drive packaging throughput across dairy, bottled water, and quick-service restaurant channels. SASO technical regulations on food-contact migration limits filter non-compliant imports and protect domestic converter margins. Riyadh and Jeddah industrial zones concentrate thermoforming and flexible film capacity serving five-year master service agreements.
United Arab Emirates
Dubai South and Jebel Ali logistics corridors pull automated wrapping equipment demand from e-commerce fulfillment expansion. ESMA conformity requirements harmonize with Gulf Standardization Organization protocols for barrier-property validation. Sharjah and Abu Dhabi free zones host specialized narrow-web converters for pressure-sensitive label production.
Kuwait
Localized flexible film converting remains undersupplied, forcing brand owners to absorb freight-inflated Saudi or UAE supply for snack-food and frozen protein applications. The country's national standards body aligns food-contact protocols with GCC harmonization frameworks. Shuwaikh Industrial Area hosts mid-cap thermoforming operations serving domestic dairy processors.
Qatar
Healthcare packaging procurement concentrates around pharmaceutical distribution for hospital network expansion in Doha. The national regulator enforces Gulf Standardization Organization medical-device protocols limiting qualified supplier pools. Mesaieed Industrial City accommodates import-dependent converters lacking upstream petrochemical integration.
Oman
Construction-chemical and agricultural packaging demand outpaces local extrusion blow molding capacity. Sultan Qaboos University research partnerships explore barrier-film substitution for oxygen-sensitive food segments. Sohar Port and Freezone attract Saudi and UAE converters seeking tariff-advantaged export positioning.
GCC Plastic Packaging Market Competitive Landscape
Global majors compete with regional champions across feedstock access and compliance infrastructure, producing a tiered structure where integrated petrochemical-to-packaging operations command pricing power over import-dependent converters. The vendor base separates into three archetypes: upstream-integrated resin producers with captive converting, mid-cap specialists with SASO pre-certification capabilities, and trading-house distributors serving spot-market demand. Dominant competitive moves include backward integration into resin compounding and strategic partnerships with quick-service restaurant chains for dedicated capacity allocation.
Within the upstream-integrated tier, Saudi Basic Industries Corporation anchors feedstock supply across the Kingdom, while Napco National exemplifies diversified mid-cap positioning spanning industrial films and food-service disposables. Hotpack Packaging Industries LLC occupies a specialist position in thermoformed containers and printed flexible packaging for food-service channels.
| Leading Market Players |
|---|
| Napco National |
| Saudi Basic Industries Corporation (SABIC) |
| Zamil Plastic Industries Ltd. |
| 3P Gulf Group |
| Arabian Plastic Industrial Company Limited (APICO) |
| Hotpack Packaging Industries LLC |
| Integrated Plastics Packaging LLC |
| Amcor plc |
| Huhtamaki Oyj |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed petrochemical producers with captive resin supply anchor pricing discipline across Saudi Arabia and the UAE, while family-owned mid-cap converters absorb margin compression from feedstock concentration and SASO compliance costs. This ownership split between upstream-integrated state enterprises and downstream specialists creates divergent pricing power, with resin producers capturing value through long-term offtake structures and converters competing on certification bundling and volume guarantees.
Pricing Analysis
Warranty and testing-bundling arrangements separate qualified converters from spot-market traders across the GCC. Three-tier pricing structure across premium, standard, and economy levels reflects SASO pre-certification status and in-house laboratory investment, with premium tiers commanding substantial uplifts for healthcare-grade validation. Pricing pressure stems from SABIC's feedstock dominance squeezing independent converters without captive polyethylene supply. Quick-service restaurant chains exhibit lowest price sensitivity due to five-year master service agreements, while household detergent brand owners drive hardest unit-cost negotiations.
Supply Chain Analysis
Polyethylene resin supply rests on Saudi Arabia's Jubail and Yanbu petrochemical complexes, with secondary sourcing from SABIC's international affiliates and regional compounders in the UAE. Critical inputs include high-density polyethylene pellets for bottle blow molding, linear-low-density grades for film extrusion, and polypropylene copolymers for thermoformed containers. Single-source vulnerability concentrates around SABIC's domestic market share, exposing independent converters to allocation risk during maintenance turnarounds. Distribution runs through converter direct sales to brand-owner procurement committees, supplemented by trading-house spot supply for undersupplied Kuwait and Oman markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GCC plastic packaging sector is consolidating into a vertical-integration race where control over resin supply and SASO certification infrastructure determines margin capture. Players are pursuing backward integration into compounding operations and captive recycling feedstock to defend positioning against integrated petrochemical-to-packaging competitors.
For Market Incumbents: Anticipate regulatory tightening by accelerating additive substitution programs and securing eighteen-month SASO laboratory accreditation slots before backlogs worsen. Consolidate supplier panels through five-year master service agreements with volume penalties, while investing in monomaterial line retrofits to preempt extended producer responsibility mandates. Threats from import-dependent traders exiting under traceability requirements create acquisition opportunities for compliant domestic converters. For New Entrants and Emerging Players: E-commerce fulfillment channel penetration offers the most accessible entry vector, with automated stretch film and protective wrapping demand outpacing dedicated converter capacity in Dubai South and Riyadh logistics corridors. Target Kuwait and Oman flexible film converting gaps where freight-inflated Saudi supply forces brand owners toward localized alternatives. Pursue quick-service restaurant chain dedicated capacity agreements as the primary go-to-market anchor. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap converters with SASO pre-certification and healthcare packaging vertical exposure in Saudi Arabia's Riyadh and Jeddah industrial zones. Long-term viability over a five-to-ten-year horizon hinges on recycling-capital allocation discipline and monomaterial technical capabilities. Watch for clarity on UAE and Saudi extended producer responsibility compliance thresholds as the decisive inflection signal for recycling infrastructure deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | SASO traceability mandates favor converters controlling pellet-to-article documentation chains. |
| Healthcare Packaging Vertical Expansion | Sterilization-grade compliance requirements at SFDA and MOHAP limit qualified supplier pools. |
| Monomaterial Line Retrofit Investment | Extended producer responsibility consultations in the UAE and Saudi Arabia demand circular-design readiness. |
| Quick-Service Restaurant Dedicated Capacity | Standardized polypropylene container specifications across Saudi Arabia and UAE outlets lock in volume. |
| Kuwait and Oman Market Penetration | Undersupplied flexible film converting forces brand owners toward freight-advantaged local supply. |
Research Methodology
Multi-period observation of SASO regulatory filing volumes, SABIC resin allocation patterns, and quick-service restaurant chain procurement contracts anchored the trend analysis, supplemented by interviews with extrusion line operators, food-contact compliance laboratory directors, and retail category buyers across Saudi Arabia and the UAE. Secondary validation drew from Gulf Standardization Organization harmonization protocols, customs trade data for polyethylene and polypropylene resin flows, and industrial zone occupancy records from Jubail, Yanbu, and Dubai South. Bottom-up converter capacity modeling and top-down petrochemical supply forecasts were triangulated against end-use demand projections.
Segment-weighting approaches distributed value across product type, end user, material, and application dimensions, with additional granularity for compliance tier and geographic supply origin. CAGRs were derived from elasticity-adjusted demand curves and capacity expansion schedules across the projection horizon. Industry-specific forecast inputs included snack-food producer format substitution rates and healthcare packaging sterilization-grade compliance adoption curves.
Inputs from SASO-accredited laboratories and industrial zone development authorities were available through the study window; gaps in real-time converter utilization rates and private offtake contract terms introduce uncertainty bands around capacity tightness assumptions. Forecasts reflect documented assumptions on regulatory implementation timing and resin price normalization. A small set of triggers—extended producer responsibility mandate finalization, SABIC maintenance turnaround schedules, and Kuwait flexible film capacity additions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Plastic T-Shirt Bags Market
Plastic Packaging
Cast Stretch Films Market
Plastic Packaging
MENA Thermoform Plastic Packaging Market
Plastic Packaging
Advanced-Recycled Polyethylene for E-Commerce Packaging Market
Plastic Packaging
HDPE Jug Market
Plastic Packaging
Global Plastic Tarpaulin Market
Plastic Packaging
Canada Plastic Bottles Market
Plastic Packaging
Russia Plastic Packaging Market
Plastic Packaging
Brazil Plastic Packaging Market
Plastic Packaging
Poland Plastic Bottles Market
Plastic Packaging
India Plastic Bottles Market
Plastic Packaging
Europe Plastic Packaging Films Market
Plastic Packaging
Mexico Plastic Packaging Market
Plastic Packaging
Plastic Crates Market
Plastic Packaging
Plastic Bottles and Containers Market
Plastic Packaging
FFS Rigid Films Market