
 China Plastic Bottles Market | 2026-2036
China Plastic Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
China Plastic Bottles Market Insights
Multi-source procurement among national beverage brands is consolidating around domestic molders with captive resin access. Shenzhen Zhenghao Plastic & Mold Co. Ltd. leverages integrated mold-making capacity to shorten lead times for custom bottle designs. Zhejiang Xinlei Packaging Co. Ltd anchors supply relationships with provincial dairy and soft drink bottlers through dedicated production lines. Berry Global, Inc. competes by extending its technical service footprint to tier-two cities where quality specifications are tightening.
China plastic bottles are hollow thermoplastic containers, typically blow-molded from PET or HDPE resin with wall thickness calibrated for carbonation retention or chemical resistance, serving as primary packaging for liquids and semi-solids across consumer and industrial supply chains. PET bottles hold the dominant position in volume terms due to their clarity, barrier performance, and compatibility with existing beverage filling infrastructure. HDPE bottles represent the faster-expanding structural category as personal care and pharmaceutical formulators specify opaque, chemically resistant containers for active-ingredient stability. Closure type segmentation shows screw caps maintaining the broadest applicability while pump dispensers capture premium positioning in personal care SKUs.
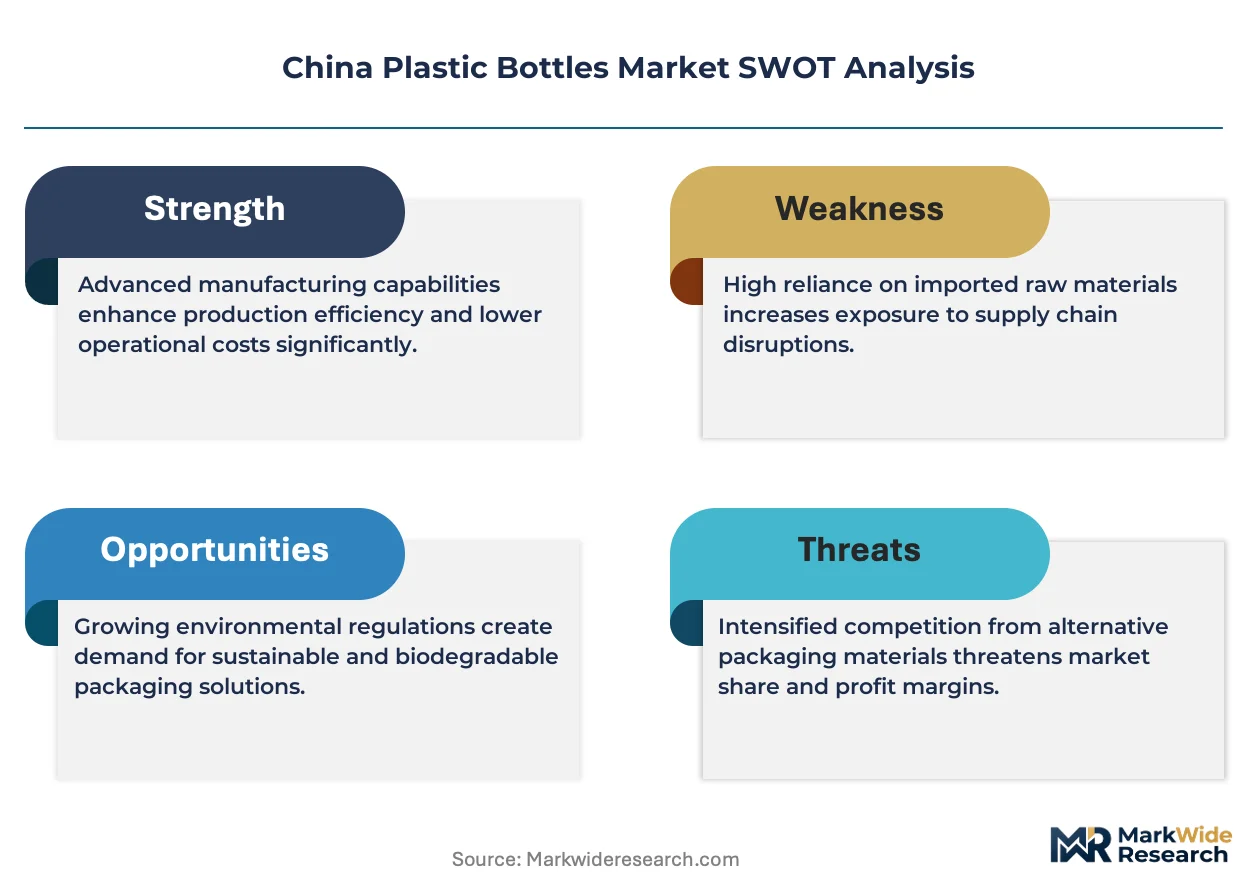
MEE enforces dual carbon goals that cap virgin polymer consumption and mandate post-consumer recycled content thresholds in packaging applications. GB standards from SAMR specify migration limits and food-contact compliance protocols that determine which resin grades qualify for beverage end uses. BIS-equivalent testing requirements for pharmaceutical bottles from NMPA add certification layers that filter supplier participation. Stakeholders must monitor how provincial enforcement of carbon intensity targets reshapes resin sourcing economics and whether recycled PET flake availability keeps pace with brand commitments.
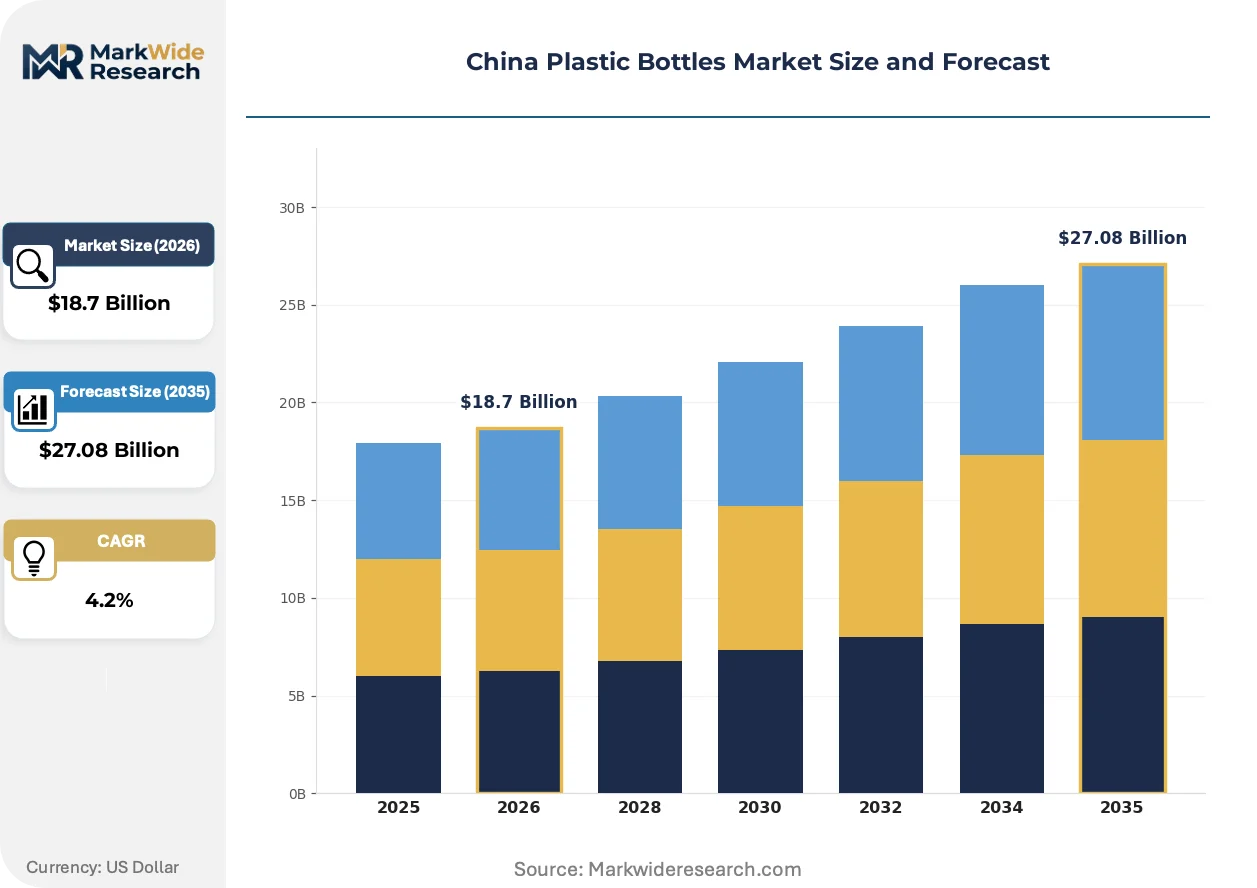
Market Dynamics
China's plastic bottles sector is being restructured by the Ministry of Ecology and Environment's dual carbon goals, which impose binding caps on virgin polymer consumption and mandate escalating post-consumer recycled content thresholds across packaging applications.
Growth Catalysts
- Recycled content mandates:MEE's phased quotas for post-consumer PET in beverage packaging are forcing brand owners to secure long-term flake supply contracts, creating dedicated demand streams for domestic recyclers.
- Guangdong converter clustering:Dense concentrations of blow-molding equipment and mold-making capacity in the Pearl River Delta enable 72-hour turnaround on custom bottle prototypes for regional beverage brands.
- HDPE pharmaceutical specifications:NMPA's barrier testing protocols for active-ingredient stability are disqualifying conventional containers and qualifying chemically resistant HDPE grades for oncology and biologic formulations.
Market Restraints
- Virgin PET price volatility:Crude-linked resin contracts expose converters to margin compression when naphtha spreads widen, particularly affecting small-batch producers without hedging infrastructure.
- rPET flake supply deficit:Collection infrastructure lags behind MEE mandate schedules, creating certified material shortages that force brands to delay label claims or absorb premium sourcing costs.
- GB standard migration limits:SAMR's food-contact compliance protocols exclude certain recycled resin grades from beverage end uses, restricting available supply pools and extending qualification timelines.
Strategic Opportunities
- Zhejiang dairy bottler integration:Provincial processors are specifying dedicated production lines for aseptic HDPE formats, creating multi-year offtake agreements for converters with barrier coating capabilities.
- Pump dispenser premiumization:Personal care formulators in Shanghai and Hangzhou are specifying custom actuator mechanisms for skincare SKUs, displacing standard screw caps in prestige segments.
- Carbon intensity benchmarking:MEE's provincial enforcement mechanisms are rewarding converters with verified lifecycle data, creating differentiation for early adopters of energy-efficient blow-molding equipment.
Industry Challenges
- Multi-resin qualification expertise:Converters lack technical staff capable of simultaneous PET, HDPE, and PP validation protocols, slowing response to brand material diversification requests.
- Legacy filling line compatibility:Pharmaceutical and beverage bottlers operate equipment calibrated to specific wall-thickness ranges, requiring expensive retrofitting to accommodate lightweighted or bio-based alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Plastic Bottles Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $27.08 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PET Bottles, HDPE Bottles, PVC Bottles, LDPE Bottles End User: Beverage Industry, Personal Care, Pharmaceutical, Household Use Closure Type: Screw Cap, Flip Top, Pump Dispenser, Spray Cap Capacity: 100ml, 250ml, 500ml, 1L |
| Companies Covered | Berry Global, Inc., Alpla Group, Shenzhen Zhenghao Plastic & Mold Co. Ltd., Shanghai COPAK Industry Co., Ltd., Hubei Mingda Plastics Products Co., Ltd., Paupack, GracePack, Zhejiang Xinlei Packaging Co. Ltd, Dongguan Xianglin Plastic Product Co. Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Plastic Bottles Market Trends and Innovations
Active developments across China's plastic bottles market center on material science advances, regulatory compliance automation, and procurement restructuring that favors converters with verified sustainability credentials and regional logistics density.
Barrier-enhanced PET is converging with plasma coating deposition systems to extend carbonation retention in 500ml formats without weight penalties. Domestic mineral water brands in Yunnan and Sichuan are piloting these containers for high-altitude distribution where pressure differentials stress conventional structures. The technology is compressing the performance gap between standard PET and multilayer alternatives, threatening niche barrier film suppliers.
SAMR's GB standards for food-contact migration limits are tightening testing protocols for recycled content streams, forcing converters to invest in spectroscopic sorting and decontamination verification. The industrial consequence is a bifurcation between certified rPET suppliers and secondary markets limited to non-food applications. Beverage bottlers in Guangdong are responding by integrating batch-level testing into incoming quality procedures rather than relying on supplier certificates alone.
Brand procurement departments are consolidating mold approval authority at headquarters level, stripping regional bottling plants of supplier selection autonomy. This centralization is displacing fragmented local sourcing relationships and favoring national converters with standardized quality systems and multi-province logistics networks. The shift is most visible among carbonated soft drink producers restructuring their Zhejiang and Jiangsu supply bases.
China Plastic Bottles Market Segmentation
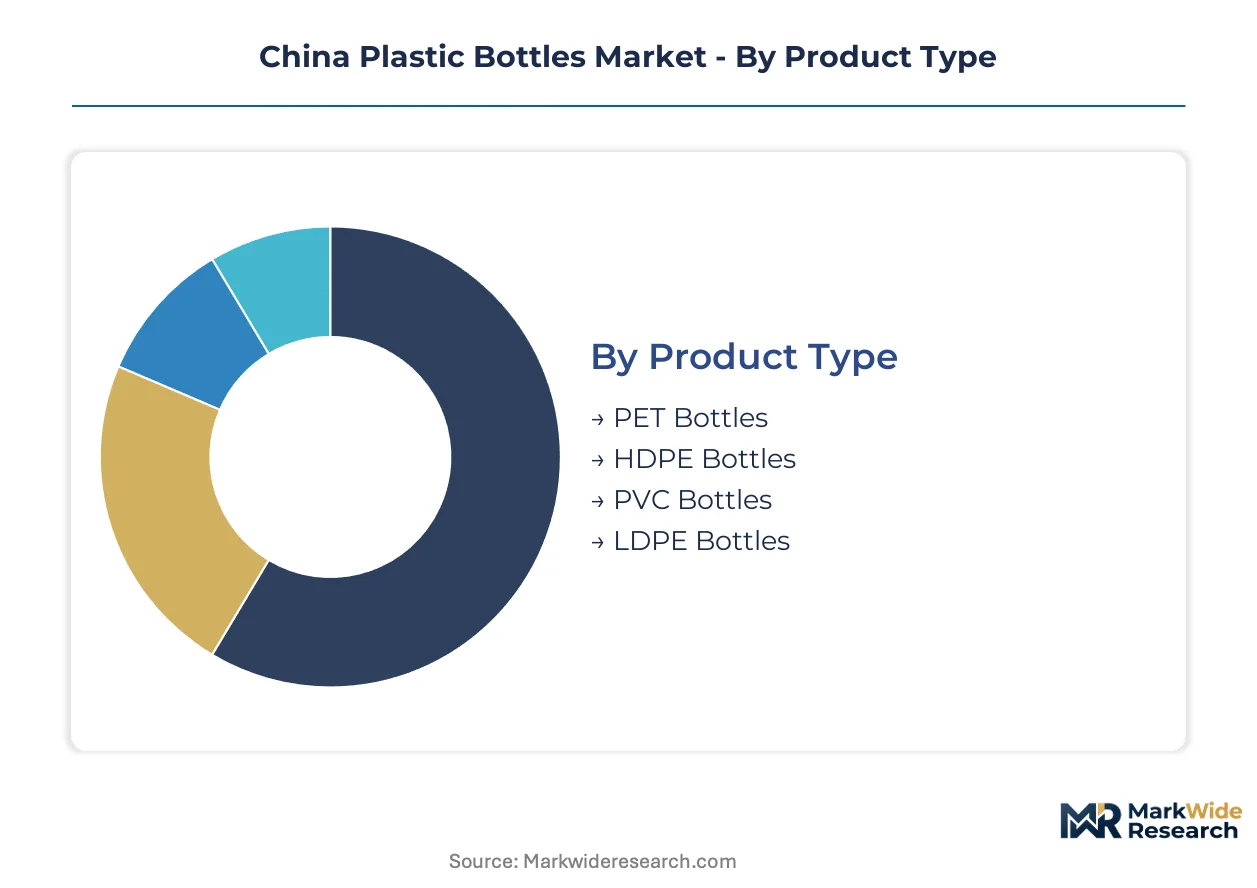
China's plastic bottles market fragments across resin chemistry, end-use specifications, and functional closure requirements that determine converter specialization and procurement patterns. Each segmentation axis carries distinct margin profiles and regulatory compliance burdens that reshape competitive positioning among domestic molders.
Product Type:
PET bottles dominate volume flows while HDPE commands premium positioning in chemically resistant applications, creating a bifurcated supply structure across Guangdong and Zhejiang converter clusters.
- PET Bottles:Blow-molded from polyethylene terephthalate resin with calibrated wall thickness for carbonation retention and clarity specifications. Beverage bottlers in Guangdong and Zhejiang specify these for carbonated soft drinks and mineral water, though virgin PET price volatility compresses margins for small-batch converters lacking hedging infrastructure.
- HDPE Bottles:Opaque high-density polyethylene containers engineered for chemical resistance and active-ingredient stability. NMPA barrier testing protocols for pharmaceutical formulations in Jiangsu and Shandong are accelerating qualification of these grades for oncology and biologic drug packaging, displacing conventional containers in high-value segments.
- PVC Bottles:Rigid polyvinyl chloride format with inherent barrier properties for industrial chemical containment. Demand concentrates in Guangdong manufacturing corridors for cleaning agent and solvent packaging where cost sensitivity outweighs sustainability preferences.
- LDPE Bottles:Flexible low-density polyethylene squeeze formats for viscous personal care and household products. Hangzhou and Shanghai formulators specify these for shampoo and lotion SKUs requiring controlled dispensing.
Today's leader: PET Bottles. Tomorrow's challenger: HDPE Bottles.
End User:
Application-driven procurement patterns separate high-volume beverage contracts from specification-intensive pharmaceutical agreements that demand dedicated production line investment.
- Beverage Industry:Carbonated soft drink, mineral water, and dairy bottlers procuring aseptic and carbonation-retentive formats. Domestic brands scaling production are consolidating multi-source procurement around domestic molders with captive resin access in the Pearl River Delta.
- Pharmaceutical:Drug manufacturers requiring NMPA-certified barrier performance for active-ingredient stability. Oncology and biologic formulators in Jiangsu are specifying HDPE grades with verified migration compliance, creating multi-year offtake agreements for converters with coating capabilities.
- Personal Care:Skincare and haircare brands in Shanghai and Hangzhou specifying custom actuator mechanisms and premium closure systems for prestige segment differentiation.
- Household Use:Cleaning agent and detergent packagers prioritizing cost-efficient LDPE and PVC formats for non-food contact applications with lower regulatory compliance burdens.
Beverage Industry holds volume dominance. Pharmaceutical delivers margin expansion.
Closure Type:
Functional differentiation in dispensing mechanisms creates pricing stratification between commodity screw formats and engineered pump systems for premium personal care positioning.
- Screw Cap:Standard threaded closure maintaining broadest applicability across beverage and household segments. Zhejiang dairy bottlers are specifying tamper-evident variants for aseptic HDPE formats.
- Pump Dispenser:Engineered actuator mechanism capturing premium positioning in Shanghai and Hangzhou skincare SKUs, displacing standard closures in prestige personal care segments.
- Flip Top:Hinged single-hand operation format for on-the-go beverage and personal care consumption. Regional brands in Sichuan and Yunnan favor these for high-altitude distribution convenience.
- Spray Cap:Aerosol-compatible trigger mechanism for household cleaning and cosmetic applications requiring fine mist dispersion.
Screw Cap anchors commodity volume. Pump Dispenser climbs the fastest in value terms.
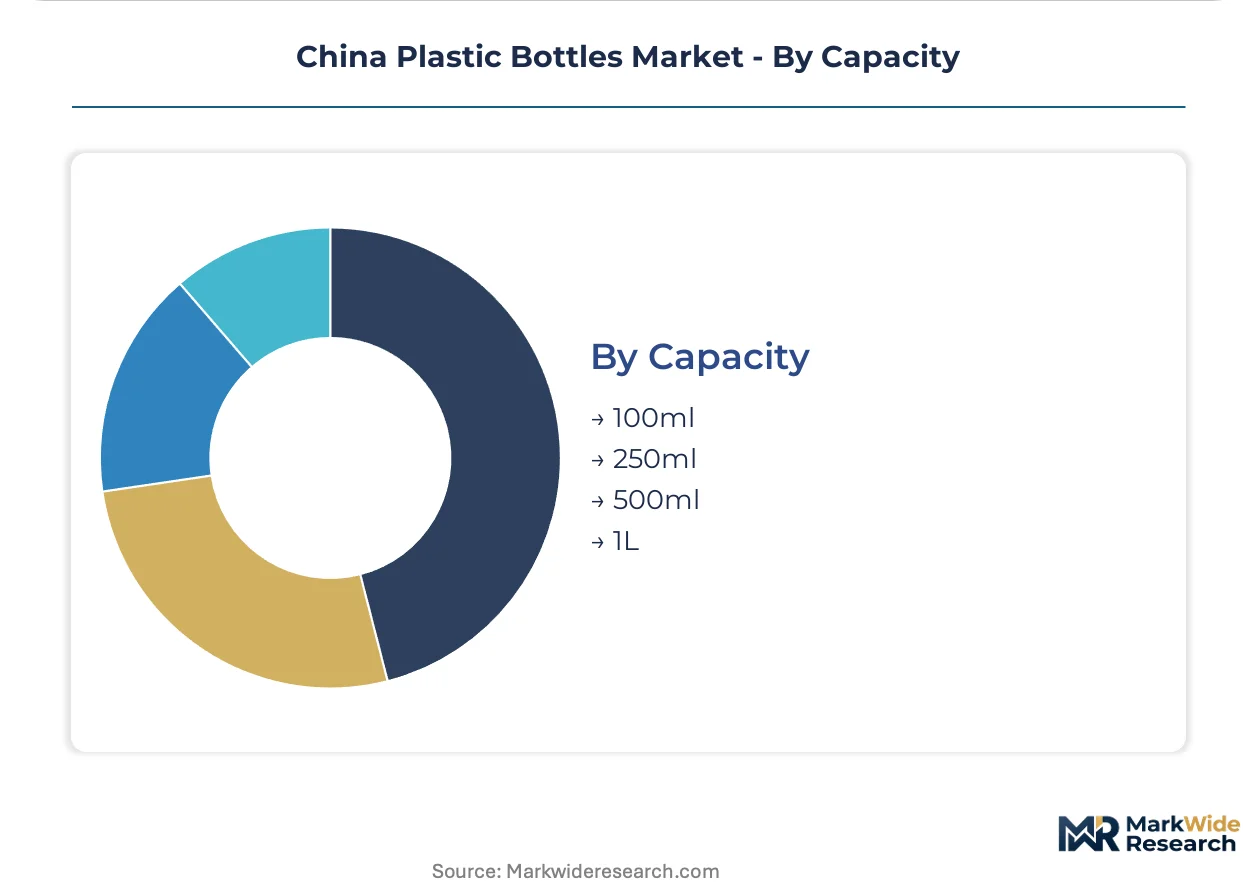
Capacity:
Size-based procurement aligns with distribution channel requirements and consumption occasion segmentation across retail and foodservice formats.
- 500ml:Standard single-serve format for carbonated beverages and mineral water. Domestic mineral water brands in Yunnan and Sichuan are piloting plasma-coated barrier-enhanced PET for high-altitude distribution.
- 1L:Multi-serve household format for dairy and soft drink value positioning. Zhejiang processors specify dedicated aseptic production lines for these HDPE formats.
- 250ml:Compact on-the-go and sample-size format for premium personal care and pharmaceutical trial packaging.
- 100ml:Travel-size and unit-dose specification for pharmaceutical and cosmetic sampler applications.
500ml commands current volume leadership. 1L formats gain share in household consolidation trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pearl River Delta anchors national production capacity with dense concentrations of blow-molding equipment and resin conversion infrastructure serving coastal consumer markets.
Guangdong Province
Carbonated soft drink and mineral water bottlers drive procurement volumes for PET formats across the Pearl River Delta manufacturing corridor. MEE's dual carbon goals enforce binding caps on virgin polymer consumption that reshape converter sourcing economics. Shenzhen and Dongguan house integrated mold-making clusters that compress prototype turnaround timelines for regional beverage brands.
Zhejiang Province
Dairy processors and aseptic bottlers specify dedicated HDPE production lines for multi-serve household formats in the Yangtze River Delta supply base. SAMR's GB standards for food-contact migration limits filter which resin grades qualify for beverage end uses. Hangzhou and Ningbo converter clusters anchor supply relationships through captive resin access and barrier coating capabilities.
Jiangsu Province
Pharmaceutical formulators in oncology and biologic segments accelerate qualification of chemically resistant HDPE grades for active-ingredient stability. NMPA barrier testing protocols add certification layers that filter supplier participation in drug packaging applications. Suzhou and Nanjing host specialized converters with verified migration compliance and multi-year offtake agreements.
Sichuan and Yunnan
High-altitude mineral water distribution creates demand for plasma-coated barrier-enhanced PET containers that withstand pressure differentials. Provincial enforcement of carbon intensity targets rewards converters with verified lifecycle data and energy-efficient equipment. Chengdu and Kunming bottlers pilot advanced formats for regional brands expanding into premium positioning.
Shandong Province
Household cleaning and industrial chemical packagers prioritize cost-efficient PVC and LDPE formats for non-food contact applications. The province's manufacturing base serves northern distribution networks with lower regulatory compliance burdens than beverage or pharmaceutical segments. Qingdao and Yantai host converters supplying detergent and solvent containment solutions.
China Plastic Bottles Market Competitive Landscape
Global majors compete with regional champions across resin access and mold-making integration, producing a tiered structure where scale advantages concentrate among converters with captive supply chains. Domestic players dominate volume flows through proximity to Guangdong and Zhejiang consumer markets, while international firms extend technical service footprints to tier-two cities. Two strategic archetypes emerge: integrated molders with in-house resin conversion and specialized barrier-coating operators serving pharmaceutical specifications. Competitive moves center on multi-year offtake agreements with provincial dairy bottlers and centralization of mold approval authority at brand headquarters level.
Within the domestic converter tier, Shenzhen Zhenghao Plastic & Mold Co. Ltd. and Zhejiang Xinlei Packaging Co. Ltd. exemplify regional champions with integrated production capabilities. Berry Global, Inc. occupies a position among international operators extending service infrastructure across provincial markets. Dongguan Xianglin Plastic Product Co. Ltd. and Hubei Mingda Plastics Products Co., Ltd. represent mid-scale fabricators serving specialized end-use requirements. These named entities anchor the competitive map without constituting an exhaustive inventory of market participants.
| Leading Market Players |
|---|
| Berry Global, Inc. |
| Alpla Group |
| Shenzhen Zhenghao Plastic & Mold Co. Ltd. |
| Shanghai COPAK Industry Co., Ltd. |
| Hubei Mingda Plastics Products Co., Ltd. |
| Paupack |
| GracePack |
| Zhejiang Xinlei Packaging Co. Ltd |
| Dongguan Xianglin Plastic Product Co. Ltd |
| Others |
Pricing and Supply Chain Analysis
National beverage brand procurement departments in Guangdong and Zhejiang are consolidating mold approval authority at headquarters level, compressing regional supplier margins and enforcing contract-based long-term offtake pricing with volume-tier discounts.
Pricing Analysis
Input-cost pass-through from naphtha-linked virgin PET contracts dominates converter economics, with crude price volatility transmitting directly to resin procurement budgets. Three-tier pricing structure across premium certified-rPET, standard virgin-PET, and economy non-food-grade tiers separates beverage bottlers by compliance requirements. Cost compression in standard-grade segments is intensifying because small-batch producers lack hedging infrastructure. Dairy processors in Zhejiang show least price sensitivity due to aseptic specification premiums, while household cleaning packagers in Shandong absorb maximum pressure.
Supply Chain Analysis
Regional distribution centers in Shenzhen and Dongguan anchor hub-and-spoke patterns that compress 72-hour prototype turnaround for Pearl River Delta beverage brands. Manufacturing concentrates in China, with secondary mold-making capacity in South Korea and Taiwan. Raw material flows draw from Saudi naphtha crackers, domestic PTA synthesis, and imported rPET flake. Single-source vulnerability around certified rPET supply creates procurement risk. Distribution runs through converter-direct-to-bottler relationships with diminishing wholesaler intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's plastic bottles market offers margin-expansion pathways through barrier-coating premiumization and energy-efficient equipment retrofits that satisfy MEE carbon intensity benchmarking.
For Market Incumbents: To counter virgin PET price volatility, secure captive resin access through backward integration into PTA synthesis or multi-year naphtha contract structures. Invest in spectroscopic sorting and decontamination verification to capture certified rPET premium tiers as SAMR tightens GB standard migration protocols. For New Entrants and Emerging Players: Begin with plasma-coated barrier-enhanced PET prototypes for high-altitude mineral water distribution in Sichuan and Yunnan, where pressure-differential requirements filter incumbent participation. Target pharmaceutical HDPE specifications in Jiangsu through NMPA barrier testing compliance as a go-to-market credential. For Investors and Strategic Acquirers: National beverage conglomerates are the most active acquirer in this space, consolidating fragmented regional converter relationships into standardized quality systems. Over the medium-term horizon, prioritize targets with verified lifecycle data and energy-efficient blow-molding equipment. Monitor rPET flake spot price spreads against virgin resin as the inflection signal for recycled content mandate feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Coating Technology Deployment | Plasma deposition systems extend carbonation retention for Yunnan and Sichuan high-altitude distribution. |
| rPET Decontamination Certification | SAMR-compliant spectroscopic sorting qualifies converters for MEE recycled content mandates. |
| Energy-Efficient Equipment Retrofit | MEE provincial benchmarking rewards verified lifecycle data with carbon intensity differentiation. |
| Multi-Year Offtake Agreements | Zhejiang dairy processors lock dedicated aseptic HDPE production lines through long-term contracts. |
| Mold-Making Integration | Shenzhen and Dongguan clusters compress prototype turnaround for regional beverage brand procurement. |
Research Methodology
Direct dialogue with blow-molding plant managers, beverage procurement directors, pharmaceutical packaging engineers, and resin distribution channel partners grounded qualitative findings. Secondary validation drew from SAMR GB standard filings, MEE dual carbon policy documents, customs trade data, and NMPA barrier testing protocols. Bottom-up converter capacity surveys and top-down end-use demand estimates were triangulated for consistency.
Segmented outputs across resin chemistry, end-use application, closure mechanism, and provincial regulatory cluster were generated across the projection horizon. CAGRs were derived from historical trajectory analysis and policy-mandated demand inflection points. Modeled inputs included MEE recycled content quota schedules, naphtha-PTA spread correlations, and pharmaceutical NMPA certification timelines.
Several conditions sit outside the modeled scope, including abrupt shifts in crude oil benchmarks, provincial enforcement variance in carbon intensity targets, and breakthrough bio-based resin commercialization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Mexico Plastic Bottles Market
Plastic Packaging
North America Plastic Bottles Market
Plastic Packaging
Blow Molded Plastic Bottles Market
Plastic Packaging
Recycled Plastic Envelope Market
Plastic Packaging
Sugarcane Based PET Bottles Market
Plastic Packaging
Plastic Vials Market
Plastic Packaging
Plastic Cutlery Market
Plastic Packaging
Reusable Plastic Water Bottles Market
Plastic Packaging
Italy Plastic Bottles Market
Plastic Packaging
United States Plastic Packaging Films Market
Plastic Packaging
Plastic Bottles and Containers Market
Plastic Packaging
Spain Plastic Bottles Market
Plastic Packaging
BOPP Tobacco Films Market
Plastic Packaging
PCR Films Market
Plastic Packaging
Europe Blow Molded Plastic Market
Plastic Packaging
Blow Moulded Plastic Packaging Market