
 Europe Single-Use Plastic Packaging Market | 2026-2036
Europe Single-Use Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Single-Use Plastic Packaging Market Insights
Food-grade specification tiers for contact-sensitive applications is bifurcating the competitive landscape across Europe. Amcor PLC leverages its integrated film extrusion and printing network to sustain premium supply contracts with pan-European dairy and meat processors. Berry Global Inc. anchors its position through large-scale thermoforming operations serving discount retail channels in France and Central Europe. Constantia Flexibles GmbH differentiates via specialized lidding and barrier laminates for extended-shelf-life food segments.
Single-use plastic packaging denotes containers, films, and formed articles manufactured from thermoplastic resins such as polyethylene, polypropylene, or polystyrene, engineered for one consumer interaction before disposal or recycling through mechanical or chemical reprocessing routes. These materials function primarily to preserve food safety, extend shelf stability, and enable cost-efficient distribution across fragmented retail networks. Polyethylene formats dominate volume flows across bags and wraps, where thin-gauge blown film extrusion keeps unit economics favorable for high-velocity consumer goods. Polypropylene containers capture structural margin pools in ready-meal and dairy segments, driven by clarity and microwave compatibility. Food & Beverage end users absorb the majority of resin throughput, though Medical-grade polystyrene trays retain specialist value in sterile instrument packaging.
REACH chemical safety protocols, the EU Packaging and Packaging Waste Regulation (PPWR), and national extended producer responsibility schemes across Germany, France, and Italy collectively reshape material specifications and recyclability claims accessible to converters. ECHA substance restrictions limit certain additives and colorants, compressing formulation flexibility for legacy product lines. Stakeholders must monitor evolving delegated acts under PPWR that will define performance grades for recycled content verification and sorting infrastructure compatibility.
Market Dynamics
The EU Packaging and Packaging Waste Regulation (PPWR) is forcing converters to redesign entire product portfolios for recyclability, compressing formulation flexibility and accelerating capital redeployment toward mono-material structures and chemical recycling feedstock preparation.
Growth Catalysts
- Extended producer responsibility schemes:Germany's Verpackungsgesetz mandates higher recycling quotas, pulling investment into compliant film structures and sort-compatible rigid formats.
- Portion-controlled retail formats:Food & Beverage processors across France and Italy are expanding flexible pouch adoption for convenience and shelf-life extension in discount channels.
- Mechanical recycling infrastructure:Polyethylene film collection and reprocessing capacity is concentrating in Benelux and Northern Italy, lowering feedstock costs for converters with backward integration.
Market Restraints
- Recycled resin price volatility:Post-consumer polyethylene flake supply fluctuates with collection rates, squeezing margin predictability for converters meeting PPWR minimum content thresholds.
- ECHA substance restrictions:REACH protocols limit certain plasticizers and colorants, forcing reformulation of legacy barrier coatings and lidding structures.
- Paper-fiber substitution:Molded pulp and coated paperboard formats are capturing ready-meal and fresh produce segments where microwave compatibility is non-essential.
Strategic Opportunities
- Chemical recycling scale-up:Pyrolysis and depolymerization projects in Poland and Spain offer pathways for mixed-polymer waste streams currently rejected by mechanical sorting.
- Medical-grade polystyrene trays:Sterile instrument packaging for Central European hospital networks remains underpenetrated by flexible alternatives due to EFSA migration limits.
- Digital watermarking integration:AI-driven sorting infrastructure in France and Germany rewards packaging with embedded traceability, creating premium positioning for early adopters.
Industry Challenges
- Mono-material barrier engineering:Replacing multi-layer laminates with single-polymer structures capable of equivalent oxygen and moisture protection requires extended R&D cycles.
- Sorting infrastructure fragmentation:Inconsistent waste collection systems across Italian regions and Spanish autonomous communities complicate national-scale recyclability claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Single-Use Plastic Packaging Market |
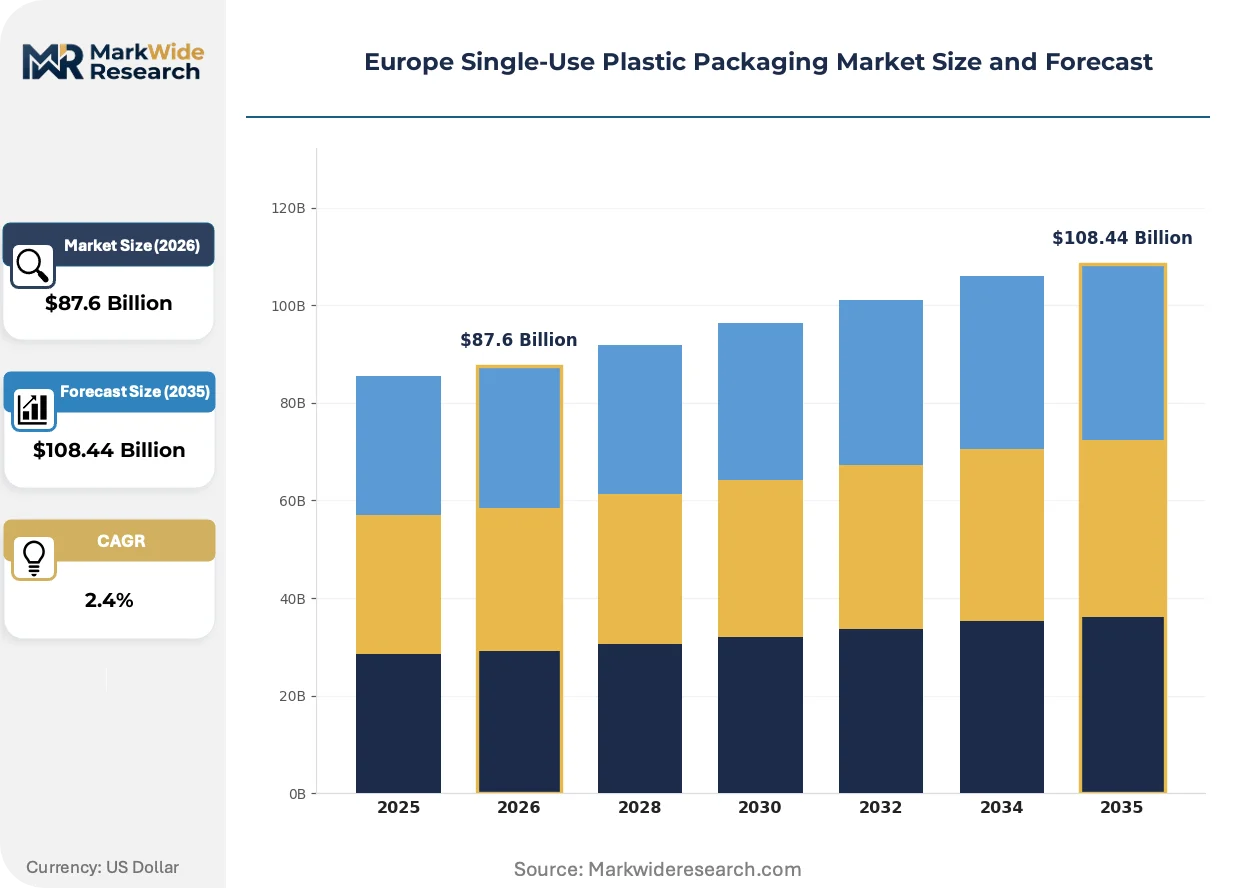
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $108.44 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bags, Bottles, Containers, Wraps Material: Polyethylene, Polypropylene, Polystyrene, Others End User: Food & Beverage, Personal Care, Household, Medical Distribution Channel: Online, Supermarkets, Convenience Stores, Wholesalers |
| Companies Covered | Amcor PLC, Sealed Air Corporation, Berry Global Inc., Constantia Flexibles GmbH, Sonoco Products Company, Mondi Group, Coveris Holdings, Huhtamaki Oyj, ALPLA Werke GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Single-Use Plastic Packaging Market Trends and Innovations
Packaging converters are racing to align material science with regulatory sorting requirements, embedding traceability technologies and redesigning barrier systems for mechanical recyclability without sacrificing shelf-life performance.
Chemical recycling via pyrolysis is decomposing mixed-polymer waste streams into virgin-quality feedstock. Petrochemical majors in the Netherlands and Belgium are offtaking output from pilot plants to supply food-contact compliant resins. This technology is decomposing the historical barrier between mechanical recycling limitations and circular packaging claims.
REACH delegated acts under ECHA oversight are tightening migration limits for certain additives in food-contact applications. Converters must reformulate masterbatches and seek alternative stabilizers, compressing product development timelines. Dairy and meat packaging segments in Germany face the most immediate compliance pressure, accelerating substitution toward polypropylene and polyethylene mono-materials.
Retail procurement teams are consolidating supplier panels and demanding audited recyclability certifications ahead of PPWR enforcement. Discount chains in France are unbundling packaging specification from traditional resin supply agreements, awarding contracts to converters with verified chemical recycling partnerships. This concentration is most visible in Central European markets where centralized retail chains dominate volume allocation.
Europe Single-Use Plastic Packaging Market Segmentation
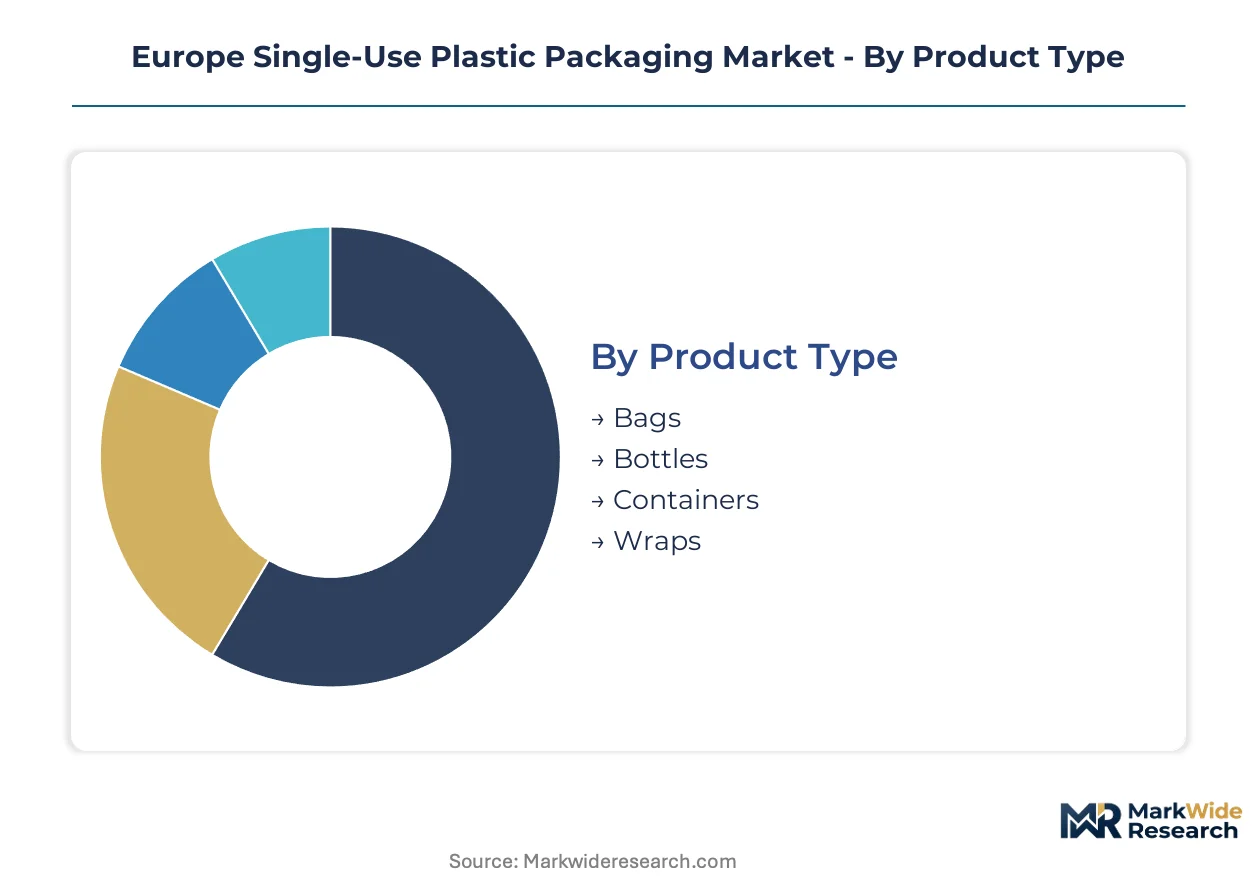
Single-use plastic packaging in Europe fragments across material chemistry, functional form, and channel access. Each segment carries distinct compliance burdens under PPWR and divergent margin profiles depending on recyclability certification tiers.
Product Type:
Margin pools concentrate in rigid formats where barrier engineering commands specification premiums, while flexible formats compete on throughput velocity.
- Bags:Thin-gauge polyethylene blown film dominates unit economics for high-velocity retail distribution. German discount chains and French hypermarkets absorb the majority of European volume, driven by lightweighting mandates that favor gauge reduction over material substitution.
- Containers:Thermoformed polypropylene and polystyrene structures capture structural margin in ready-meal and dairy applications. Italian processors and Central European meat packers specify these formats for clarity, stackability, and microwave compatibility in portion-controlled retail.
- Bottles:Blow-molded PET and HDPE formats serve beverage and personal care segments with established mechanical recycling pathways. EFSA migration limits constrain post-consumer resin ratios in food-contact grades.
- Wraps:Cling film and stretch formats prioritize oxygen transmission control for fresh produce. Benelux reprocessing infrastructure supports limited closed-loop claims for industrial stretch film.
Containers hold installed capacity. Bags is rotating up the share rankings.
Material:
Polymer selection determines recyclability tier eligibility and sorting infrastructure compatibility across national collection schemes.
- Polyethylene:Linear low-density and high-density grades constitute the majority of European film and bottle production. German Verpackungsgesetz quotas and Benelux mechanical recycling concentration pull demand toward mono-material PE structures with verified sort compatibility.
- Polypropylene:Clarified and random copolymer grades serve dairy lidding, ready-meal trays, and sterile medical packaging. France's centralized retail procurement increasingly specifies PP for thermoformed applications where chemical recycling partnerships can verify circularity claims.
- Polystyrene:Crystal and high-impact grades retain niche value in medical tray sterilization and protective packaging. ECHA substance restrictions on styrene monomer migration compress formulation flexibility for food-contact lines.
- Others:PET, PLA, and bio-based alternatives occupy specialty tiers with limited mechanical recycling infrastructure. Italian and Spanish pilot projects evaluate chemical recycling compatibility for mixed-polymer streams.
Polyethylene dominates volume throughput. Polypropylene is climbing the fastest.
End User:
Application sensitivity to migration limits and shelf-life performance creates divergent specification tiers across customer categories.
- Food & Beverage:Dairy, meat, and ready-meal processors across Germany, France, and Italy specify barrier laminates and thermoformed trays with EFSA-compliant contact layers. PPWR minimum recycled content thresholds force reformulation of legacy multi-material structures.
- Personal Care:Cosmetic and hygiene brands prioritize clarity and dispensing functionality over recyclability certification. Bottled formats in this segment face less immediate pressure from extended producer responsibility schemes.
- Household:Cleaning product containers and refuse sacks compete on unit cost with limited premium for circular content. Italian and Spanish autonomous communities apply inconsistent sorting requirements that complicate national-scale recyclability claims.
- Medical:Sterile instrument trays and pharmaceutical blisters demand polystyrene and PET grades with validated migration profiles. Central European hospital networks maintain specification rigidity that resists flexible format substitution.
Food & Beverage holds installed capacity. Medical is rotating up the share rankings.
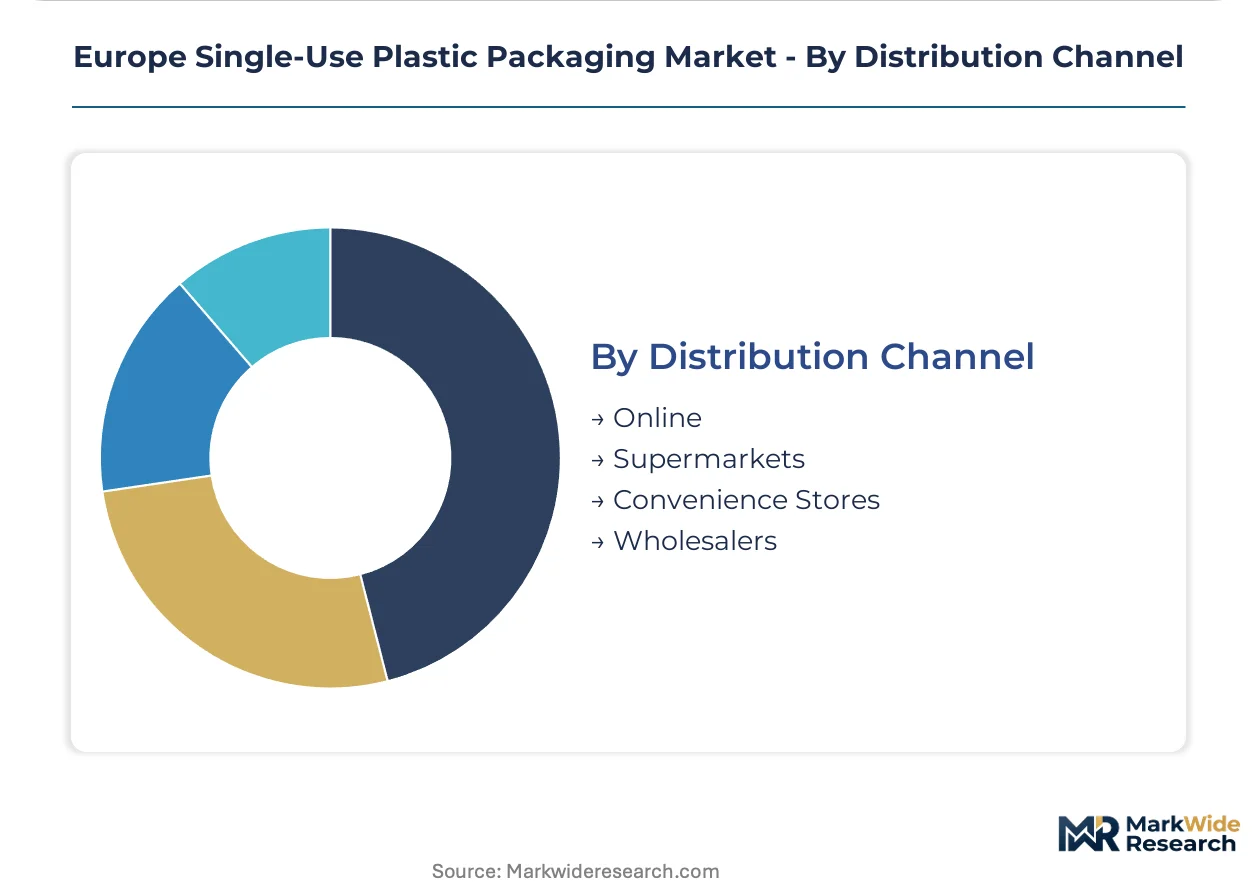
Distribution Channel:
Channel concentration determines scale economics and compliance documentation requirements for converters.
- Supermarkets:Centralized retail chains in Germany and France consolidate procurement panels and demand audited recyclability certifications ahead of PPWR enforcement. Discounters unbundle packaging specification from resin supply agreements.
- Online:E-commerce fulfillment drives demand for lightweight protective formats with minimal dimensional variance. Last-mile logistics constraints prioritize puncture resistance over circular content verification.
- Convenience Stores:Fragmented independent retail across Italy and Spain absorbs smaller production runs with limited standardization. Regional waste collection inconsistency complicates recyclability messaging.
- Wholesalers:Foodservice and institutional supply channels specify industrial-grade formats with volume pricing structures. Chemical recycling feedstock partnerships offer differentiation in contract negotiations with centralized buyers.
Supermarkets hold installed capacity. Online is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German converters export thermoformed trays and barrier films to French and Italian retail chains, establishing the Rhine-Ruhr corridor as the dominant trade-flow axis for compliant single-use formats.
Germany
Centralized retail procurement and strict Verpackungsgesetz quotas pull demand toward mono-material polyethylene structures. ECHA substance restrictions under REACH protocols compress formulation flexibility for legacy barrier coatings. The Rhine-Ruhr industrial cluster hosts thermoforming operations serving discount chains with sort-compatible rigid formats.
France
Hypermarket consolidation and discount channel expansion drive specification of clarified polypropylene for ready-meal applications. The EU Packaging and Packaging Waste Regulation mandates minimum recycled content thresholds that reshape converter procurement panels. The Lyon-Grenoble corridor concentrates lidding and barrier laminate production for extended-shelf-life dairy segments.
Italy
Meat processors and fresh produce distributors specify thermoformed containers with EFSA-compliant contact layers. Inconsistent regional waste collection systems complicate national-scale recyclability claims for converters. The Emilia-Romagna cluster anchors flexible pouch production for portion-controlled retail formats serving Central European buyers.
Netherlands
Benelux mechanical recycling infrastructure lowers feedstock costs for converters with backward integration into polyethylene film reprocessing. The EU Green Deal circular economy targets accelerate chemical recycling pilot projects near Rotterdam. The Randstad region concentrates blown film extrusion serving cross-border retail supply chains.
Spain
Autonomous community fragmentation in waste sorting creates compliance complexity for converters seeking national market coverage. EFSA migration limits constrain post-consumer resin ratios in food-contact bottle applications. The Barcelona-Tarragona corridor hosts PET blow-molding operations supplying Iberian beverage processors with mechanically recycled content.
Europe Single-Use Plastic Packaging Market Competitive Landscape
Listed leaders compete with private specialists across capital access and portfolio flexibility, producing a tiered structure where scale-driven multinationals anchor volume contracts while mid-cap converters capture niche specification premiums. Three archetypes dominate: integrated resin-to-film operators with captive recycling streams, regional thermoforming specialists serving single-country retail chains, and barrier-lamination experts with pharmaceutical-grade certification tiers. Competitive moves concentrate on chemical recycling partnerships and mono-material R&D alliances.
Within the integrated-film tier, Amcor PLC and Berry Global Inc. occupy positions exemplifying scale-driven supply chain control. Constantia Flexibles GmbH represents the specialized-barrier archetype, anchoring premium positioning through lidding and extended-shelf-life laminate expertise. These three names illustrate the competitive spectrum from multinational volume leadership to focused specification dominance.
| Leading Market Players |
|---|
| Amcor PLC |
| Sealed Air Corporation |
| Berry Global Inc. |
| Constantia Flexibles GmbH |
| Sonoco Products Company |
| Mondi Group |
| Coveris Holdings |
| Huhtamaki Oyj |
| ALPLA Werke GmbH |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at blown film extrusion lines across the Rhine-Ruhr corridor shapes both supply concentration and price floors for polyethylene formats. German converters leverage scale economies to defend margin structures against recycled resin volatility, while smaller Italian and Spanish operators absorb cost compression through gauge reduction rather than material substitution.
Pricing Analysis
Mono-material barrier engineering commands a generation-based premium gap, with next-generation sort-compatible laminates priced above legacy multi-layer structures and economy-grade polyethylene films. Pricing stratifies across premium, standard, and economy tiers, with EFSA-compliant food-contact certification and chemical recycling partnership status driving differentiation. Cost compression in standard-tier films is intensifying because post-consumer flake supply fluctuates with collection rates. Discount retail procurement teams in France exhibit the highest price sensitivity, while medical-grade polystyrene tray buyers accept premium positioning due to migration limit compliance requirements.
Supply Chain Analysis
Inventory buffers for polyethylene resin have compressed to three-to-four-week cycles as converters align procurement with volatile recycled content quotas. Supply concentrates in Germany, the Netherlands, and Belgium, with the Benelux mechanical recycling cluster feeding backward-integrated film operations. Raw material flows draw from naphtha crackers in the ARA region, imported polyethylene pellets from Saudi producers, and post-consumer flake from Northern Italian collection schemes. Single-source vulnerability runs through pyrolysis feedstock offtake agreements with Rotterdam-area petrochemical majors. Distribution runs through centralized retail procurement panels in Germany and France, with fragmented Italian convenience channels absorbing spot-market volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mono-material R&D capability and chemical recycling feedstock access represent the scarcest assets in this market, separating converters who can verify PPWR compliance from those facing specification exclusion.
For Market Incumbents: Shield premium positioning by accelerating chemical recycling partnerships in Poland and Spain before pilot-scale capacity saturates. Consolidate thermoforming operations in the Rhine-Ruhr corridor to capture scale economies on sort-compatible rigid formats. Capacity addition in Benelux reprocessing infrastructure offers defensive leverage against recycled resin price volatility. For New Entrants and Emerging Players: Digital watermarking integration for AI-driven sorting infrastructure presents a service-layer gap where incumbents under-serve French and German retail procurement requirements. Target medical-grade polystyrene tray segments in Central European hospital networks, where EFSA migration limits resist flexible format substitution. A go-to-market angle anchored in audited recyclability certification ahead of PPWR enforcement unlocks panel consolidation opportunities. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among converters with long-term offtake agreements to centralized retail chains and backward-integrated recycling streams. Over a five-to-ten-year viability window, acquisition targets cluster around mid-cap barrier-lamination specialists with pharmaceutical-grade certification tiers. The signal to watch is delegated act finalization under PPWR defining performance grades for recycled content verification.| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Partnership | Pyrolysis offtake agreements with Rotterdam petrochemical majors unlock food-contact compliant resin supply. |
| Mono-Material R&D Alliance | Collaborative barrier engineering with German dairy processors accelerates EFSA-compliant laminate substitution. |
| Digital Watermarking Integration | Embedded traceability rewards early adopters with AI-driven sorting infrastructure access in France. |
| Backward Integration into Recycling | Captive polyethylene flake supply from Benelux reprocessing infrastructure compresses feedstock cost volatility. |
| Medical-Grade Certification Investment | Polystyrene tray sterilization validation for Central European hospital networks defends niche margin pools. |
Research Methodology
Cross-validation between converter production data and retail procurement panel disclosures anchors the qualitative findings on specification tier evolution. Primary interviews with blown film extrusion plant managers, barrier laminate R&D directors, French hypermarket category buyers, and German waste management operators combined with secondary validation from ECHA substance restriction filings, EU PPWR delegated act drafts, Verpackungsgesetz compliance databases, and Benelux mechanical recycling capacity reports. Bottom-up volume modeling triangulates against top-down resin consumption estimates from European polymer associations.
Sensitivity analysis across recycled content quota scenarios and chemical recycling scale-up timelines tests forecast robustness over the projection horizon. Segmentation dimensions include material chemistry, functional form, end-use application sensitivity, and channel concentration tier. CAGRs derive from iterative reconciliation of unit economics trajectories and regulatory enforcement phasing. Industry-specific forecast inputs incorporate EFSA migration limit tightening schedules and retail procurement panel consolidation patterns.
Underlying assumptions cover PPWR delegated act finalization timelines and mechanical recycling collection rate trajectories, with deviation risk concentrated in autonomous community waste sorting fragmentation across Italy and Spain. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Australia and New Zealand Plastic Bottles Market
Plastic Packaging
Plastic Liners Market
Plastic Packaging
Europe Blow Molded Plastic Market
Plastic Packaging
Plastic Water Storage Tank Market
Plastic Packaging
Injection Molded Plastics Market
Plastic Packaging
Corrugated Plastic Trays Market
Plastic Packaging
Philippines Plastics Market
Plastic Packaging
Global Plastic Packaging Sacks Market
Plastic Packaging
PCR Plastic Packaging Market
Plastic Packaging
GCC PET Packaging Market
Plastic Packaging
Plastic Tumblers Market
Plastic Packaging
South America Polyethylene Terephthalate (PET) Market
Plastic Packaging
Plastic Medicine Bottles Market
Plastic Packaging
Plastic Bottles Market
Plastic Packaging
Plastic Shrink Wrap Market
Plastic Packaging
PET Clamshell Market