
 Plastic Bottles Market | 2026-2036
Plastic Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Bottles Market Outlook
Aftermarket collection and recycling revenue is fragmenting across regional waste management ecosystems and brand-owned takeback programs. Amcor plc leverages its global recycling infrastructure to secure post-consumer PET feedstock. Graham Packaging Co Inc. anchors its competitive position through captive blow-molding capacity tied to dairy and juice accounts. Plastipak Holdings Inc. dominates North American rPET flake supply through integrated collection-to-resin operations.
Plastic bottles are hollow containers formed through extrusion blow molding, injection blow molding, or stretch blow molding, typically ranging from 10ml to 20L in capacity, with wall thickness calibrated for internal pressure, chemical compatibility, and drop resistance. They serve primarily as portable, lightweight vessels for liquid and semi-liquid goods across retail, institutional, and industrial channels. PET commands the largest volume share due to its clarity, barrier performance, and established recycling stream, while HDPE sustains relevance in dairy and household cleaner segments where opacity and chemical resistance matter. Flip-top and screw cap closure formats are gaining preference in personal care and on-the-go beverage applications as convenience features reshape purchasing behavior.
The EPA regulates recycled content claims and waste stream diversion targets in the United States, while the EU Green Deal and REACH framework impose extended producer responsibility obligations and chemical safety thresholds on packaging placed in European markets. FDA food contact regulations and EFSA migration limits determine which resin grades and additives qualify for beverage and pharmaceutical applications, directly constraining material substitution timelines. Stakeholders must monitor evolving rPET certification standards and deposit-return scheme expansions to anticipate feedstock cost shifts and compliance-driven redesign requirements.
Market Dynamics
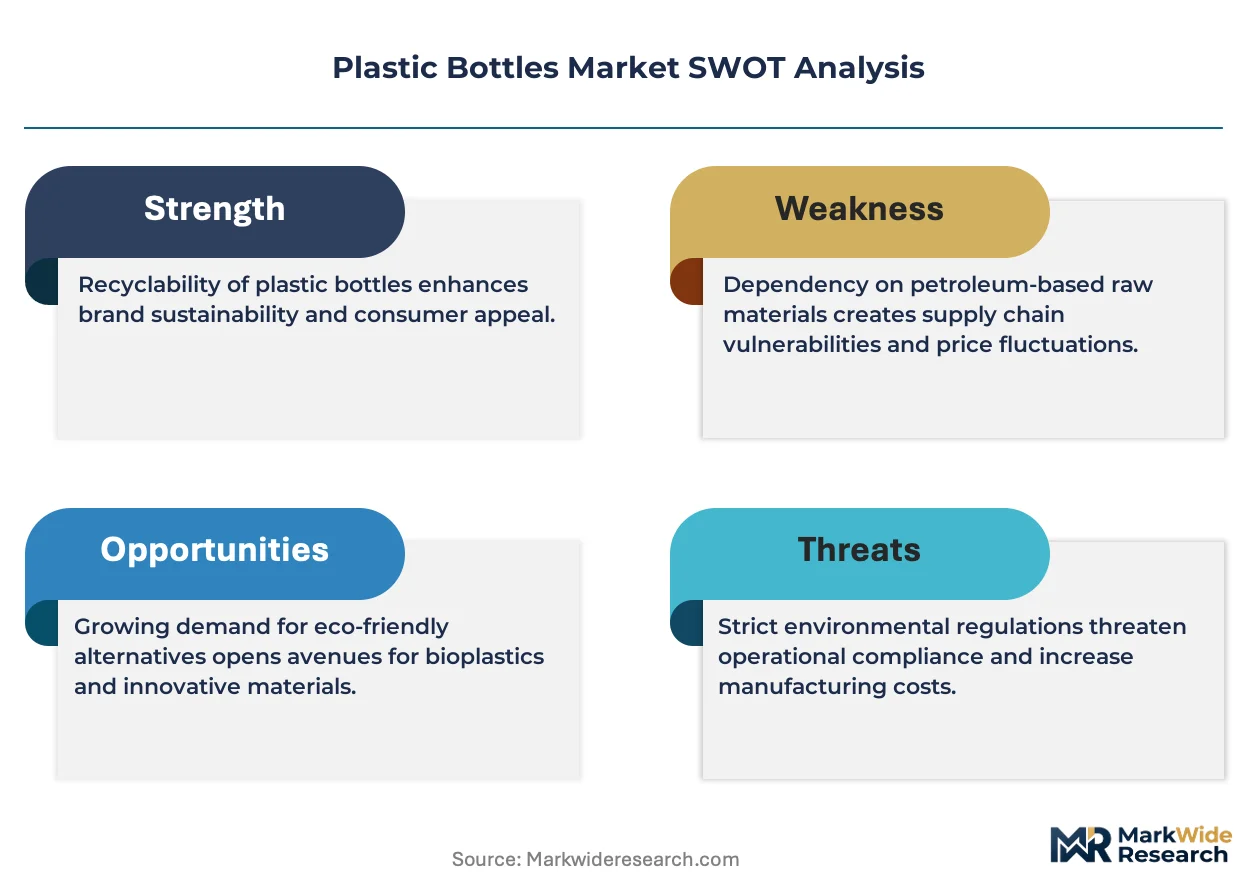
The EU Single-Use Plastics Directive is forcing material transitions toward recycled PET and bio-based alternatives, compressing virgin resin demand while fragmenting aftermarket collection revenue across regional waste management ecosystems.
Growth Catalysts
- Beverage packaging demand:Bottled water and ready-to-drink categories gain shelf space in large-format retail networks, sustaining high-volume consumption in the United States, China, and Germany.
- REACH framework obligations:Extended producer responsibility mandates in European markets accelerate rPET certification adoption and deposit-return scheme expansions.
- E-commerce distribution networks:Direct-to-consumer liquid goods fulfillment requires lightweight, shatter-resistant primary packaging with calibrated drop resistance.
Market Restraints
- rPET feedstock volatility:Post-consumer flake supply concentrates in North American integrated collection-to-resin operations, creating bottleneck risk.
- FDA food contact constraints:Migration limits and resin grade qualifications directly constrain material substitution timelines for beverage applications.
- Glass and aluminum substitution:Premium beverage brands pivot to refillable glass and aseptic carton formats in European markets under deposit-return pressure.
Strategic Opportunities
- Indian institutional channels:Dairy and edible oil distribution through kirana stores and cooperative networks remains underpenetrated by organized blow-molded packaging.
- Pharmaceutical blow-fill-seal integration:Convergence of aseptic processing and single-use bottle formation enables unit-dose sterile packaging for biologics.
- IRA recycling infrastructure credits:United States tax incentives for domestic rPET processing capacity reduce feedstock cost exposure for qualified facilities.
Industry Challenges
- Blow-molding technician scarcity:Extrusion and stretch blow process optimization requires specialized calibration expertise that outpaces vocational training output.
- Legacy dairy equipment incompatibility:HDPE bottle format transitions to rPET require line speed and heat-set modifications that extend commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Bottles Market |
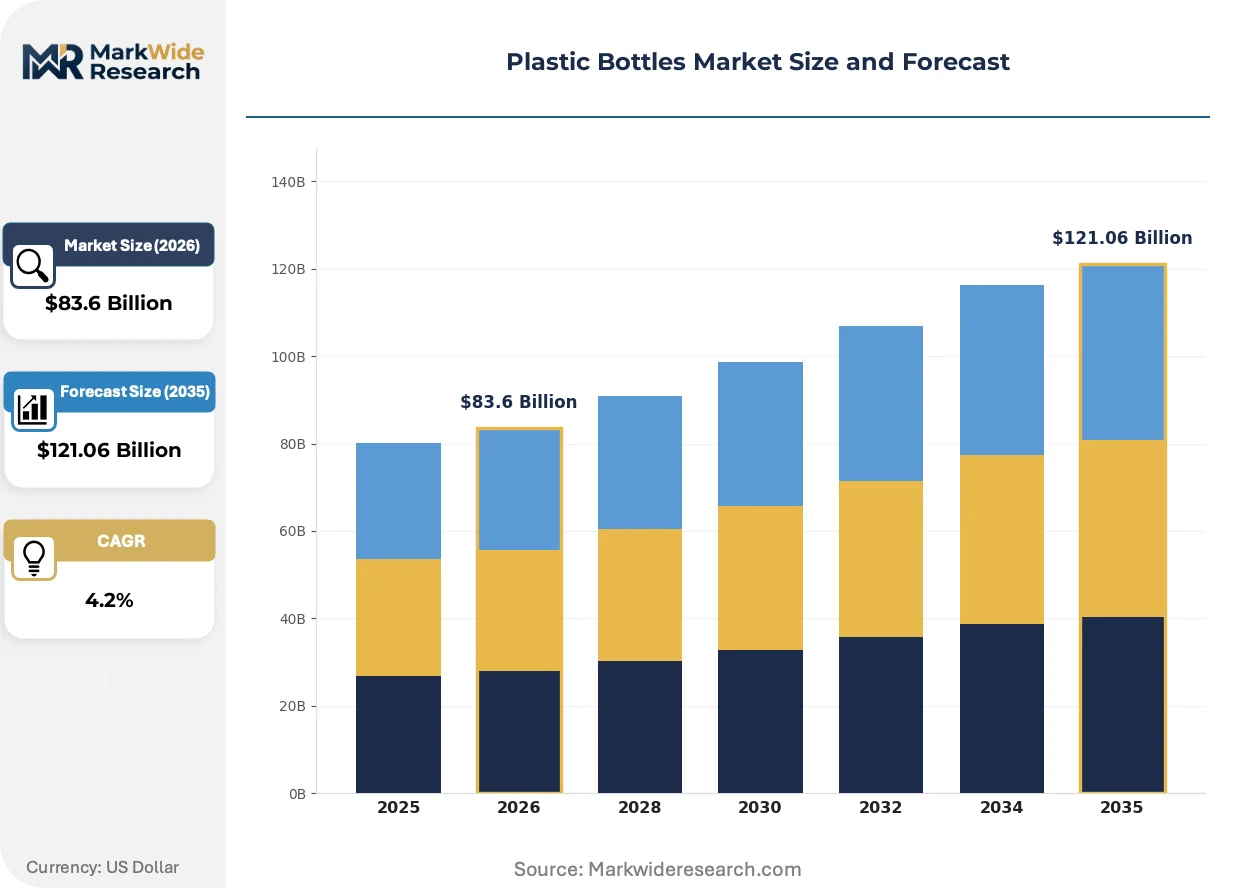
| Market Size in 2026 | $83.6 Billion |
| Market Size in 2035 | $121.06 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: PET, HDPE, PVC, LDPE Closure Type: Screw Cap, Snap Cap, Cork, Flip-Top End Use: Food & Beverage, Personal Care, Household Cleaners, Pharmaceuticals Capacity: 250ml, 500ml, 1L, 2L |
| Companies Covered | Gerresheimer AG, O.Berk Company LLC, Amcor plc, Loews Corp, Alpha Packaging, Inc., Graham Packaging Co Inc., AptarGroup, Inc., Suntory Holdings Limited, Plastipak Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Bottles Market Strategic Shifts
Digital twin simulation and closed-loop chemical recycling are compressing design-to-production cycles while enabling food-grade rPET from contaminated waste streams previously diverted to fiber or landfill.
Digital twin software is virtualizing blow-mold cavity design and resin flow simulation before physical tooling commitment. Beverage converters in Germany and the United States deploy these platforms to reduce prototype iterations and compress time-to-market for seasonal SKUs. The technology is virtualizing capital allocation decisions by replacing physical mold trials with predictive wall-thickness optimization.
REACH chemical safety thresholds and EFSA migration limits are tightening additive approval timelines for recycled content streams. European packaging converters face extended qualification periods for non-clear rPET grades containing legacy colorants or barrier coatings. Pharmaceutical and infant nutrition segments in France and Italy are most affected, accelerating migration toward virgin-equivalent certified resin tiers with documented chain-of-custody.
Retail buyer consolidation is compressing supplier negotiation cycles and unbundling after-sales technical service from resin supply agreements. Large-format grocery and drugstore chains in the United States now demand dedicated packaging engineers embedded at converter sites, replacing traditional distributor-mediated support models. This pattern is most visible in private-label bottled water and household cleaner categories where SKU proliferation requires rapid format adaptation.
Plastic Bottles Market Segmentation
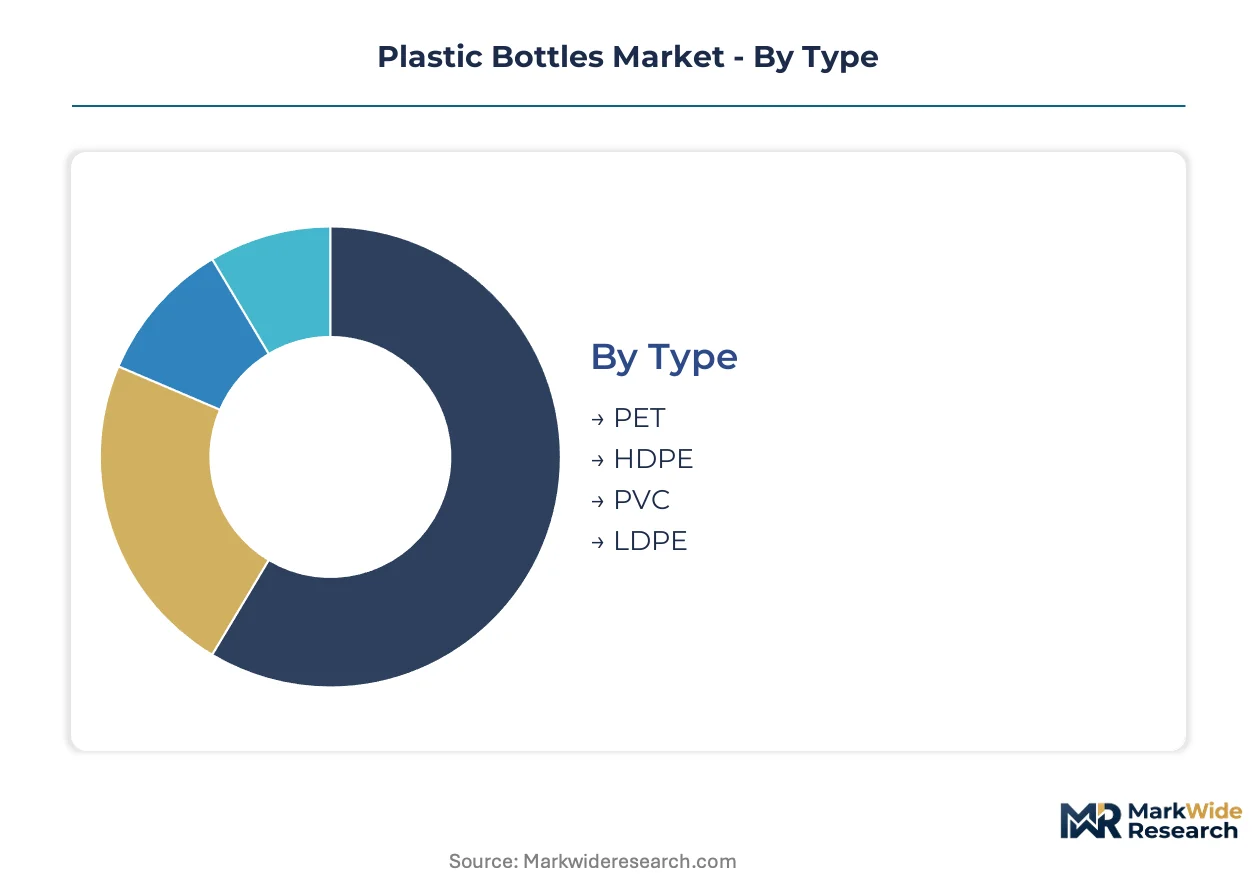
Segmentation in plastic bottles reveals how resin selection, closure engineering, and capacity calibration determine aftermarket service intensity. Technical support requirements vary sharply across pharmaceutical blow-fill-seal lines versus commodity beverage formats.
Type:
After-sales service intensity clusters around resin-specific processing challenges, with rPET qualification support and heat-set optimization commanding premium technical engagement.
- PET:Clear, biaxially oriented polyester delivers superior barrier against oxygen and carbon dioxide loss. Beverage bottlers in Germany and the United States prioritize PET for carbonated soft drinks and bottled water, though FDA migration limits constrain recycled content timelines.
- HDPE:High-density polyethylene offers chemical resistance and opacity for dairy and household cleaner applications. Graham Packaging anchors captive blow-molding capacity for juice and dairy accounts where HDPE remains dominant despite rPET transition pressure.
- PVC:Polyvinyl chloride sustains niche pharmaceutical blister and bottle applications where clarity and sterilization compatibility matter. REACH chemical safety thresholds restrict additive packages in European medical packaging.
- LDPE:Low-density polyethylene serves squeeze bottles and flexible dispensers in personal care segments. EFSA migration limits govern resin grades for cosmetic contact applications in France and Italy.
By volume, PET leads. By growth pace, rPET-certified grades within PET are climbing the fastest as EU Single-Use Plastics Directive mandates compress virgin resin demand.
Closure Type:
Closure engineering determines line speed compatibility and capping torque calibration requirements, with pharmaceutical and infant nutrition segments demanding validated seal integrity protocols.
- Screw Cap:Threaded polypropylene closures dominate beverage and household cleaner segments. Retail buyer consolidation in United States grocery chains now embeds packaging engineers at converter sites for rapid SKU adaptation.
- Flip-Top:Hinged dispensing closures gain preference in on-the-go personal care and sports beverage applications. Convenience features reshape purchasing behavior for shampoo and conditioner formats in Germany.
- Snap Cap:Press-fit closures serve single-serve dairy and juice portions. Legacy dairy equipment incompatibility with rPET heat-set requirements extends commissioning timelines for snap-cap line conversions.
- Cork:Synthetic and natural cork closures retain premium wine and spirits positioning. Deposit-return scheme expansions in European markets pressure substitution toward screw cap for cost efficiency.
By volume, screw cap leads. By growth pace, flip-top formats are expanding most quickly in convenience-driven personal care channels.
End Use:
End-use segmentation maps directly to regulatory jurisdiction, with FDA food contact, EPA recycled content claims, and EFSA migration limits creating divergent compliance pathways.
- Food & Beverage:Bottled water and ready-to-drink categories sustain high-volume consumption. E-commerce distribution networks in China and the United States require lightweight, shatter-resistant primary packaging with calibrated drop resistance.
- Pharmaceuticals:Blow-fill-seal integration enables unit-dose sterile packaging for biologics. CDSCO and FDA regulations constrain resin grade selection for injectable and ophthalmic applications in India and the United States.
- Personal Care:Flip-top and pump-dispense formats dominate shampoo, conditioner, and lotion segments. REACH framework obligations accelerate rPET certification adoption for cosmetic packaging in European markets.
- Household Cleaners:HDPE bottles with chemical-resistant closures serve bleach and detergent applications. Amcor plc leverages global recycling infrastructure to secure post-consumer feedstock for this segment.
By volume, food and beverage leads. By growth pace, pharmaceutical blow-fill-seal applications show the steepest expansion trajectory as aseptic processing converges with single-use bottle formation.
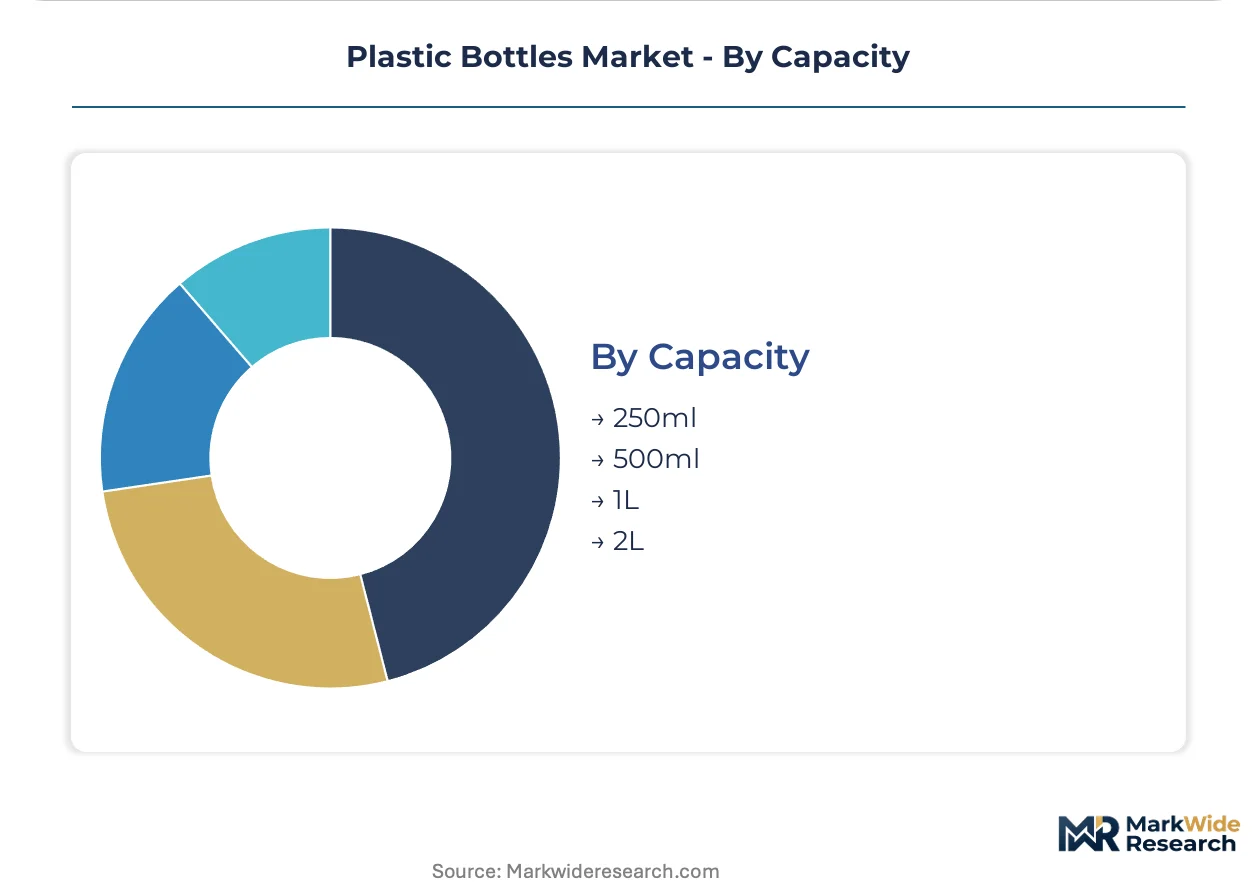
Capacity:
Capacity calibration determines blow-mold cavity design, wall-thickness distribution, and logistics cube efficiency, with digital twin simulation now virtualizing these trade-offs before physical tooling commitment.
- 500ml:Mid-size format dominates single-serve beverage and personal care applications. Plastipak Holdings dominates North American rPET flake supply for this capacity tier through integrated collection-to-resin operations.
- 1L:Standard household and family-size format for juice, dairy, and cleaners. IRA recycling infrastructure credits in the United States reduce feedstock cost exposure for 1L rPET processing facilities.
- 250ml:Travel-size and sample formats serve hospitality and trial-size personal care. Blow-molding technician scarcity constrains extrusion process optimization for small-cavity high-speed lines.
- 2L:Large-format serves value-oriented beverage and bulk cleaner segments. Deposit-return scheme economics in Germany favor standardized 2L PET formats for automated sorting efficiency.
By volume, 500ml leads. By growth pace, 250ml formats are gaining share fastest in travel retail and subscription sampling channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. German beverage bottlers absorb rPET premiums with minimal volume loss, while Indian dairy distributors remain highly price-sensitive to resin cost swings.
United States
Bottled water and ready-to-drink categories sustain high-volume consumption through large-format retail networks. The EPA regulates recycled content claims and waste stream diversion targets, constraining virgin resin timelines. E-commerce distribution hubs in Texas and California require lightweight, shatter-resistant primary packaging with calibrated drop resistance for direct-to-consumer liquid goods fulfillment.
Germany
Deposit-return scheme economics favor standardized 2L PET formats for automated sorting efficiency. The EU Single-Use Plastics Directive and REACH framework impose extended producer responsibility obligations, accelerating rPET certification adoption. Beverage converters in Bavaria deploy digital twin platforms to reduce prototype iterations and compress time-to-market for seasonal SKUs.
China
Large-format retail and e-commerce distribution networks sustain high-volume consumption of bottled water and ready-to-drink categories. SAMR and GB standards govern food contact materials and recycling infrastructure development. Industrial clusters in the Yangtze River Delta concentrate blow-molding capacity for domestic beverage brands expanding into Southeast Asian export markets.
India
Dairy and edible oil distribution through kirana stores and cooperative networks remains underpenetrated by organized blow-molded packaging. FSSAI and CDSCO regulations constrain resin grade selection for food contact and pharmaceutical applications. Western Maharashtra and Gujarat host emerging converter capacity targeting institutional channels with cost-optimized HDPE formats.
Brazil
Household cleaner and personal care segments drive HDPE bottle demand through modern trade expansion. ANVISA governs pharmaceutical packaging migration limits and resin qualifications. Industrial concentration in São Paulo state anchors blow-molding operations serving Mercosur export requirements with calibrated wall-thickness distribution for logistics cube efficiency.
Plastic Bottles Market Competitive Environment
Capability concentration sits with integrated resin-to-bottle operators; scale advantage sits with global converters with multi-continent footprint. The market structure tiers between captive blow-molding specialists tied to beverage accounts and independent converters serving fragmented personal care and pharmaceutical demand. Three archetypes dominate: integrated collection-to-resin operators controlling rPET flake supply, global packaging conglomerates leveraging recycling infrastructure across jurisdictions, and regional specialists optimizing line speed for dairy and juice formats. Competitive moves center on backward integration into post-consumer feedstock collection and capacity expansion in deposit-return scheme geographies.
Among North American integrated operators, Plastipak Holdings Inc. and Graham Packaging Co Inc. exemplify the captive capacity archetype, with the former representing control over collection-to-resin verticals and the latter anchoring dairy and juice account relationships through specialized heat-set optimization. Amcor plc occupies a position as the global infrastructure player, with geographic span enabling rPET feedstock arbitrage across regulatory jurisdictions. These three named entities collectively illustrate how competitive positioning stratifies between feedstock security, account captivity, and geographic diversification.
| Leading Market Players |
|---|
| Gerresheimer AG |
| O.Berk Company LLC |
| Amcor plc |
| Loews Corp |
| Alpha Packaging, Inc. |
| Graham Packaging Co Inc. |
| AptarGroup, Inc. |
| Suntory Holdings Limited |
| Plastipak Holdings Inc. |
| Others |
Value Chain & Pricing Dynamics
North American rPET flake supply concentrates in integrated collection-to-resin operations, anchoring margin pools with converters who control post-consumer feedstock access rather than those who merely process virgin resin. This upstream consolidation forces downstream bottlers to absorb premiums or commit to long-term offtake contracts that lock in supply security.
Pricing Analysis
After-sales technical service contracts and rPET qualification support drive lifetime value for blow-molding equipment and resin supply relationships. Three-tier pricing structure across premium certified-recycled, standard virgin-equivalent, and economy non-certified tiers differentiates based on EFSA migration compliance and chain-of-custody documentation. Cost compression in standard virgin PET tiers is intensifying because EU Single-Use Plastics Directive mandates compress demand timelines. Private-label beverage bottlers in Germany show highest price sensitivity; pharmaceutical blow-fill-seal operators in France accept premium positioning for validated sterile packaging.
Supply Chain Analysis
Post-consumer PET bale supply draws from collection infrastructure concentrated in the United States, Germany, and Japan where deposit-return schemes generate quality-sorted feedstock. Virgin resin production rests on purified terephthalic acid and ethylene glycol inputs sourced from petrochemical complexes in the US Gulf Coast and Middle East. Single-source vulnerability concentrates in North American rPET flake processing where Plastipak Holdings dominates integrated operations. Distribution runs through converter-direct relationships with large-format retail chains, bypassing traditional distributor mediation for high-volume beverage and household cleaner accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated retail chains that now embed packaging engineers at converter sites, fragmenting traditional supplier relationships and compressing negotiation cycles for resin supply agreements.
For Market Incumbents: Build captive rPET feedstock moats through backward integration into post-consumer collection infrastructure or long-term municipal contract locks. Defensive moves center on securing flake supply in deposit-return geographies and investing in FDA food contact certification tiers that delay competitor qualification timelines. Threats emerge from glass and aluminum substitution in European premium beverage segments and bio-based resin entrants targeting EU Green Deal compliance. Capacity expansion in India and Southeast Asia represents the priority lever for volume defense. For New Entrants and Emerging Players: Indian institutional dairy and edible oil channels through kirana stores and cooperative networks represent the most penetrable entry point for organized blow-molded packaging. Pharmaceutical blow-fill-seal integration for biologics unit-dose sterile packaging offers white-space expansion with premium pricing potential. Go-to-market execution should anchor on technical service partnerships with regional dairy equipment retrofitters who manage legacy line conversions. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional converters who built capacity during virgin resin expansion phases and now face rPET transition capital requirements. Long-term viability favors integrated collection-to-resin operators with geographic diversification across EU and North American regulatory jurisdictions. Acquisition targets should prioritize converters with embedded packaging engineer relationships at consolidated retail accounts. The signal to watch is deposit-return scheme expansion announcements in US state legislatures as inflection indicators for feedstock cost compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Post-Consumer Collection | Secures rPET flake supply ahead of EU Single-Use Plastics Directive compliance deadlines. |
| Digital Twin Platform Deployment | Reduces prototype iterations for seasonal beverage SKUs at German and US converters. |
| Pharmaceutical Blow-Fill-Seal Certification | Enables unit-dose sterile packaging entry for biologics with FDA and EMA compliance. |
| Indian Institutional Channel Expansion | Captures underpenetrated dairy and edible oil distribution through kirana store networks. |
| IRA Recycling Infrastructure Credit Qualification | Reduces feedstock cost exposure for US-based rPET processing facilities. |
Study Parameters
A standing panel of blow-molding plant managers, resin procurement leads at beverage bottlers, retail category buyers, aftermarket service technicians, and regulatory affairs directors provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from EPA recycled content filings, EU ECHA substance registrations, FDA food contact notifications, and customs trade data for PET resin imports. Bottom-up capacity assessments at converter sites triangulated against top-down demand modeling from retail channel audits.
Scenario-bracketing framed analytical outputs across conservative, baseline, and accelerated regulatory adoption pathways over the projection horizon. Segmentation dimensions modeled include resin type, closure engineering format, end-use regulatory jurisdiction, capacity tier, and regional collection infrastructure maturity. CAGRs derived from elasticity-adjusted volume projections incorporating rPET certification adoption curves and deposit-return scheme expansion schedules. Forecast inputs incorporated blow-molding line speed constraints and technician training pipeline bottlenecks.
Stress conditions across rPET feedstock price volatility, EU mandate enforcement timing, and glass substitution rates in premium beverage segments were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory implementation schedules and recycling infrastructure buildout rates. Cross-checking against customs data for virgin PET resin trade flows and retail scanner data for private-label bottled water volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Egypt Plastic Bottles Market
Plastic Packaging
HDPE Jug Market
Plastic Packaging
PET Clamshell Market
Plastic Packaging
Advanced-Recycled Polyethylene for E-Commerce Packaging Market
Plastic Packaging
Plastic Tubes Market
Plastic Packaging
Canada Plastic Packaging Market
Plastic Packaging
Asia Pacific Single-Use Plastic Packaging Market
Plastic Packaging
Plastic Water Storage Tank Market
Plastic Packaging
Fluorinated Bottle Market
Plastic Packaging
Plastic Packaging Market
Plastic Packaging
Europe Single-Use Plastic Packaging Market
Plastic Packaging
Global Stretch Films Market
Plastic Packaging
Plastic Carboy Market
Plastic Packaging
Global Plastic Pails Market
Plastic Packaging
North America PET Bottle Market
Plastic Packaging
Asia-Pacific Plastic Bottles and Containers Market