
 Indigo Carmine Market | 2026-2036
Indigo Carmine Market Size, Share, and Industry Trends Forecast 2026-2036
Indigo Carmine Market Outlook
Aftermarket technical service revenue is rewriting profit allocation across the indigo carmine value chain. Dystar leverages its integrated dye manufacturing infrastructure to capture formulation support margins. Sensient Colors LLC anchors North American supply relationships through batch consistency protocols. BASF SE extends its position via pharmaceutical-grade certification depth.
Indigo carmine, or indigotine (E132, C.I. 73015), is a synthetic blue dye produced through sulfonation of indigo with sulfuric acid, yielding a water-soluble sodium salt used for pH indication, surgical lymph node mapping, and food coloration. The powder segment dominates volume due to stability in long-haul distribution and precise dosing for pharmaceutical compounding. Liquid formulations compete in high-throughput food processing where automated dosing systems demand pumpable inputs. Granule grades occupy premium positions in laboratory reagent markets where dust-free handling commands price premiums.
FDA color additive regulations and REACH restrictions on aromatic amine impurities shape batch testing burdens and supplier qualification timelines. India's CDSCO and China's NMPA impose parallel pharmacopeial standards that fragment certification requirements for cross-border dye shipments. Stakeholders must monitor regulatory divergence between pharmaceutical and food-grade specifications to avoid dual-compliance cost traps.
Market Dynamics
Pharmaceutical-grade certification requirements are fragmenting supplier qualification timelines and concentrating procurement among vertically integrated dye manufacturers capable of batch-level traceability.
Growth Catalysts
- REACH aromatic amine thresholds:ECHA purity mandates redirect European pharmaceutical formulators toward certified indigo carmine suppliers with validated impurity testing protocols.
- Surgical lymph node mapping:Oncology centers in India and China expand adoption of indigo carmine for sentinel node visualization during tumor resections.
- CDSCO pharmacopeial alignment:India's tightening color additive standards for parenteral diagnostics create compliance-driven replacement cycles for non-certified dye stocks.
Market Restraints
- Indigo raw material volatility:Petrochemical-derived indigo precursors expose manufacturers to naphthalene and aniline price swings that compress formulation margins.
- Chinese intermediate concentration:Over 60% of sulfonated indigo intermediates originate from Shandong and Jiangsu provinces, creating single-source vulnerability for Western compounders.
- Natural colorant substitution:Spirulina-derived phycocyanin and gardenia blue extracts displace synthetic indigo carmine in clean-label food applications across premium European retail channels.
Strategic Opportunities
- Brazilian pharmaceutical manufacturing:ANVISA's harmonization with USP-NF monograph standards opens import substitution opportunities for GMP-certified indigo carmine suppliers.
- Liquid formulation automation:High-throughput food processors in Germany and Italy demand pumpable dye concentrates compatible with precision dosing systems.
- EU Green Deal chemical sustainability:ECHA's Safe and Sustainable by Design framework incentivizes bio-based indigo carmine process development through reduced regulatory scrutiny timelines.
Industry Challenges
- Dual-grade certification complexity:Manufacturers serving both pharmaceutical and food segments must maintain separate batch records, testing protocols, and audit trails to satisfy FDA color additive and USP-NF requirements simultaneously.
- Analytical chemist scarcity:Specialized expertise in HPLC-based aromatic amine quantification and pharmacopeial method validation remains concentrated among legacy dye houses, constraining new market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indigo Carmine Market |
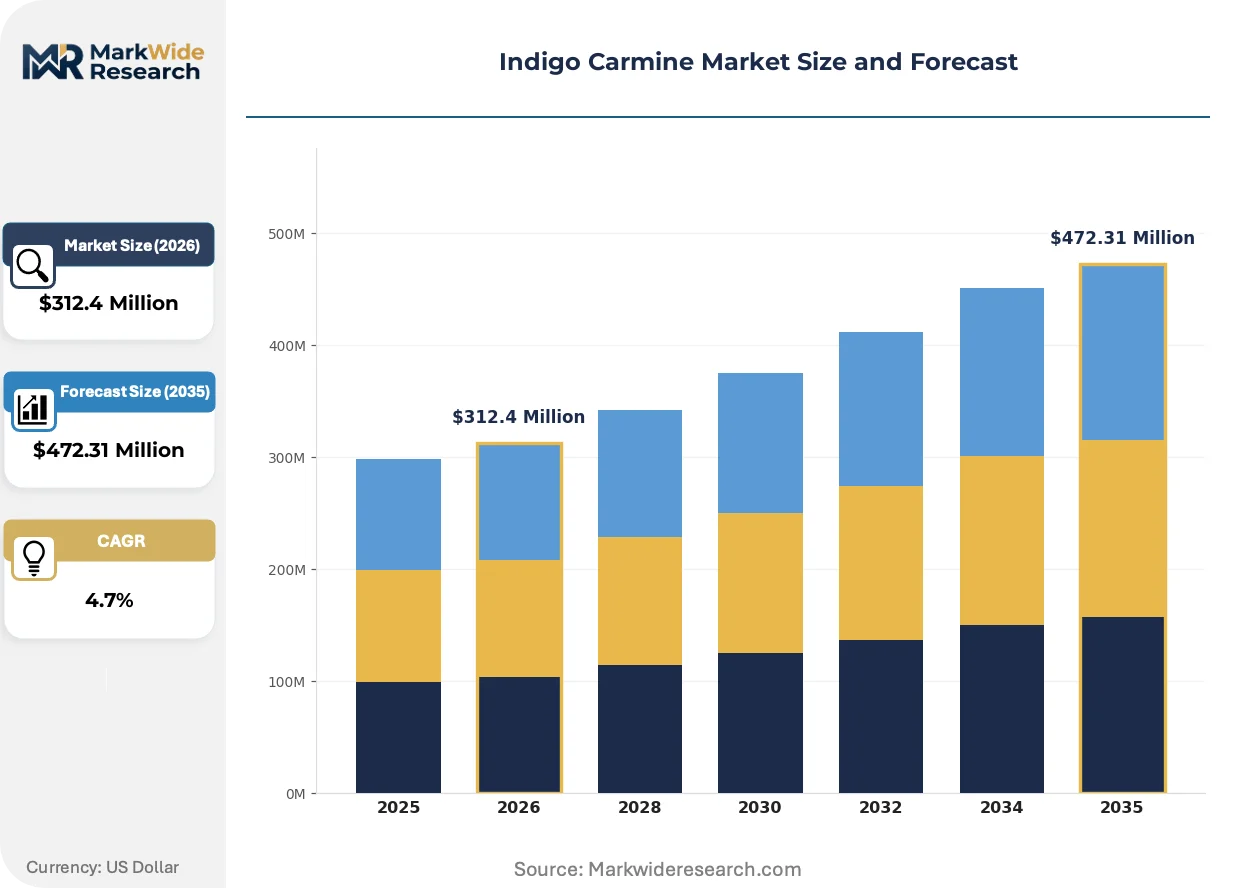
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Paste, Granules Application: Dyes, Food Coloring, Pharmaceuticals, Cosmetics End User: Manufacturers, Laboratories, Healthcare, Food Industry Distribution Channel: Online, Direct Sales, Retail, Distributors |
| Companies Covered | Dystar, Ferro Corporation, Huntsman Corporation, Chinasun Specialty Products Co., Ltd, Sensient Colors LLC, BASF SE, Kraton Corporation, Dynemic Products Ltd, Clariant AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indigo Carmine Market Strategic Shifts
Continuous processing technology and regulatory data digitization are compressing batch release timelines while fragmenting traditional supplier-buyer relationships across the indigo carmine value chain.
Microfluidic sulfonation reactors are migrating from pilot-scale demonstration to commercial dye manufacturing, enabling precise temperature control that reduces ortho-sulfonation byproducts below pharmacopeial thresholds. BASF and Dystar have commissioned modular units at their Ludwigshafen and Singapore facilities respectively. This process intensification is migrating from specialty chemical applications into pharmaceutical-grade colorant production, collapsing traditional batch cycle times from 48 hours to under 6 hours while improving yield consistency.
EMA's revised excipient guidelines now require nitrosamine risk assessments for all synthetic dyes used in parenteral drug products, forcing reformulators to document indigo carmine supply chain contamination controls. The industrial consequence is a bifurcation between suppliers with validated nitrosamine testing capabilities and those restricted to oral dosage or topical applications. Parenteral diagnostic manufacturers in Germany and Switzerland are consolidating procurement onto three qualified suppliers with dedicated nitrosamine-negative production lines.
Specification-driven procurement now dominates pharmaceutical dye buying, with formulators demanding certificate of analysis data packages before sample evaluation rather than after technical qualification. This behavior compresses supplier sales cycles and eliminates traditional relationship-based vendor retention. The shift is most visible among CDMOs in Hyderabad and Mumbai, where procurement teams now mandate ISO 17025-accredited testing for all indigo carmine shipments regardless of supplier history.
Indigo Carmine Market Segmentation
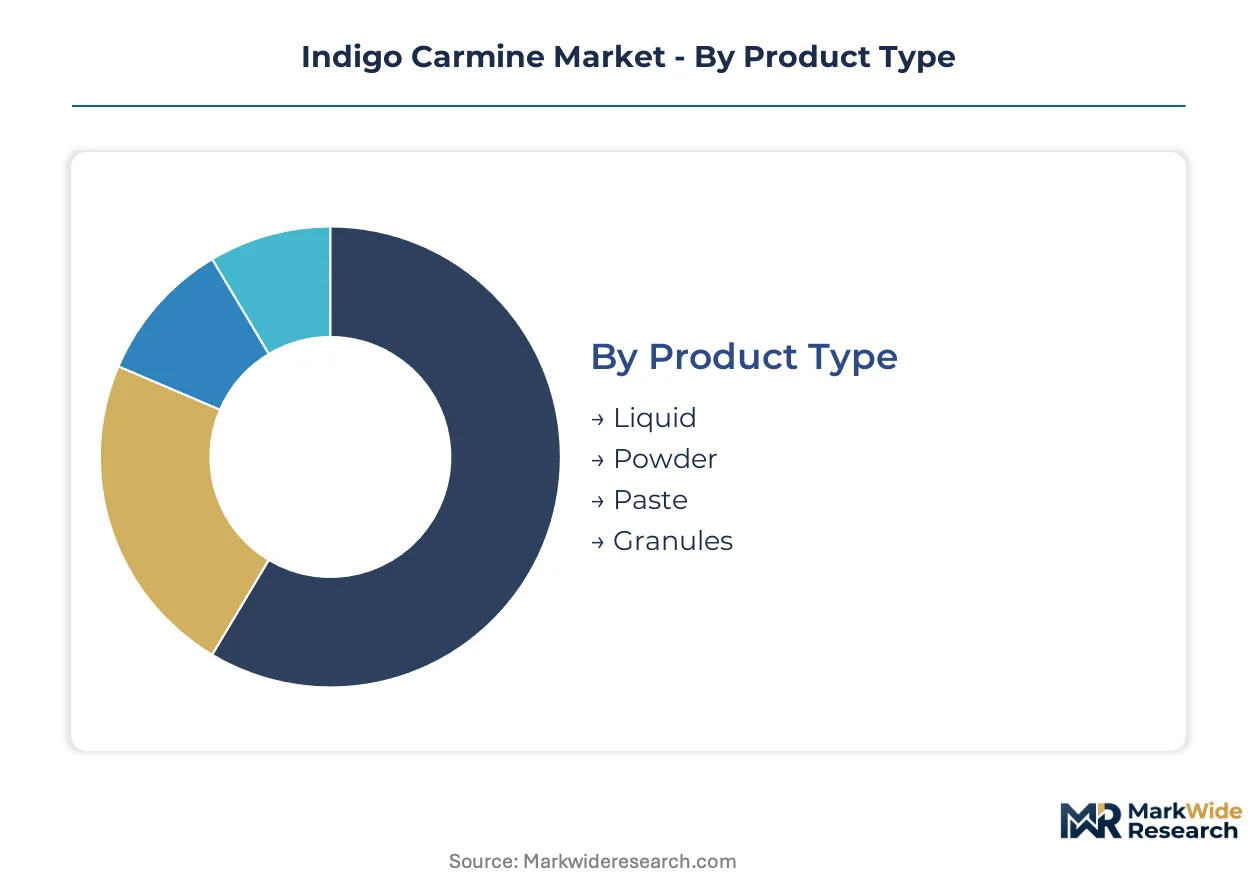
Indigo carmine segmentation reflects divergent purity requirements across pharmaceutical diagnostics, food processing, and industrial dyeing. Formulators select physical formats based on dosing precision needs, regulatory compliance burdens, and supply chain integration depth.
Product Type:
Liquid, powder, paste, and granule formats serve distinct use-case spectra from high-throughput food automation to laboratory reagent handling.
- Powder:The sodium salt crystalline form delivers stability across long-haul distribution networks and enables precise milligram-scale dosing for pharmaceutical compounding. CDSCO-certified manufacturers in Hyderabad and Mumbai standardize on powder for parenteral diagnostic formulations where batch homogeneity is mandatory.
- Liquid:Pumpable concentrates integrate with automated dosing systems in German and Italian food processing plants. EFSA-compliant liquid grades reduce dust exposure during handling but require cold-chain logistics that constrain sourcing radius.
- Paste:Semi-solid consistency suits small-batch cosmetic coloration where manual mixing predominates.
- Granules:Dust-free morphology commands premium positioning in laboratory reagent markets where occupational exposure limits are stringent.
Established volume favors powder; emerging adoption favors liquid.
Application:
Application segmentation tracks regulatory intensity gradients from pharmaceutical-grade certification to food-additive compliance.
- Pharmaceuticals:Parenteral diagnostic applications demand USP-NF monograph conformance and nitrosamine-negative certification. Swissmedic and EMA guidelines now require batch-level traceability for sentinel lymph node mapping dyes used in oncology centers across Germany and Switzerland.
- Food Coloring:E132-coded indigo carmine faces substitution pressure from spirulina-derived phycocyanin in clean-label European retail. FSSAI and FDA color additive regulations impose parallel testing burdens on cross-border shipments.
- Dyes:Industrial textile applications tolerate higher impurity thresholds, sourcing from Shandong and Jiangsu intermediate producers.
- Cosmetics:Topical coloration operates under less stringent purity requirements than parenteral uses, though EU Cosmetics Regulation microplastic restrictions are reshaping formulation choices.
Certification depth separates pharmaceutical from food-grade procurement; dye applications absorb price volatility through specification flexibility.
End User:
End user categories align with batch size, technical service requirements, and regulatory audit frequency.
- Healthcare:Oncology departments and surgical centers in India and China drive demand for lymph node mapping applications. CDSCO and NMPA pharmacopeial alignment is tightening supplier qualification timelines.
- Manufacturers:Pharmaceutical formulators and food processors consolidate procurement onto ISO 17025-accredited suppliers with validated impurity testing protocols.
- Laboratories:Research and quality control facilities prioritize granule grades for dust-free handling and precise weighing.
- Food Industry:High-throughput processors in Germany and Italy specify liquid concentrates compatible with precision dosing infrastructure.
Healthcare procurement is concentrating fastest; food industry volume remains largest.
Distribution Channel:
Channel segmentation reflects customer scale, technical support needs, and geographic concentration of demand.
- Direct Sales:Pharmaceutical manufacturers negotiate long-term supply agreements with certified dye houses for batch-level traceability. BASF and Dystar maintain dedicated account teams for USP-NF and EP-compliant shipments.
- Distributors:Regional chemical distributors serve mid-scale food processors and cosmetic formulators with inventory buffering and local regulatory documentation.
- Online:E-procurement platforms capture laboratory and small-batch cosmetic demand where certificate-of-analysis data packages precede sample evaluation.
- Retail:Limited to artisanal food producers and educational institutions with minimal volume.
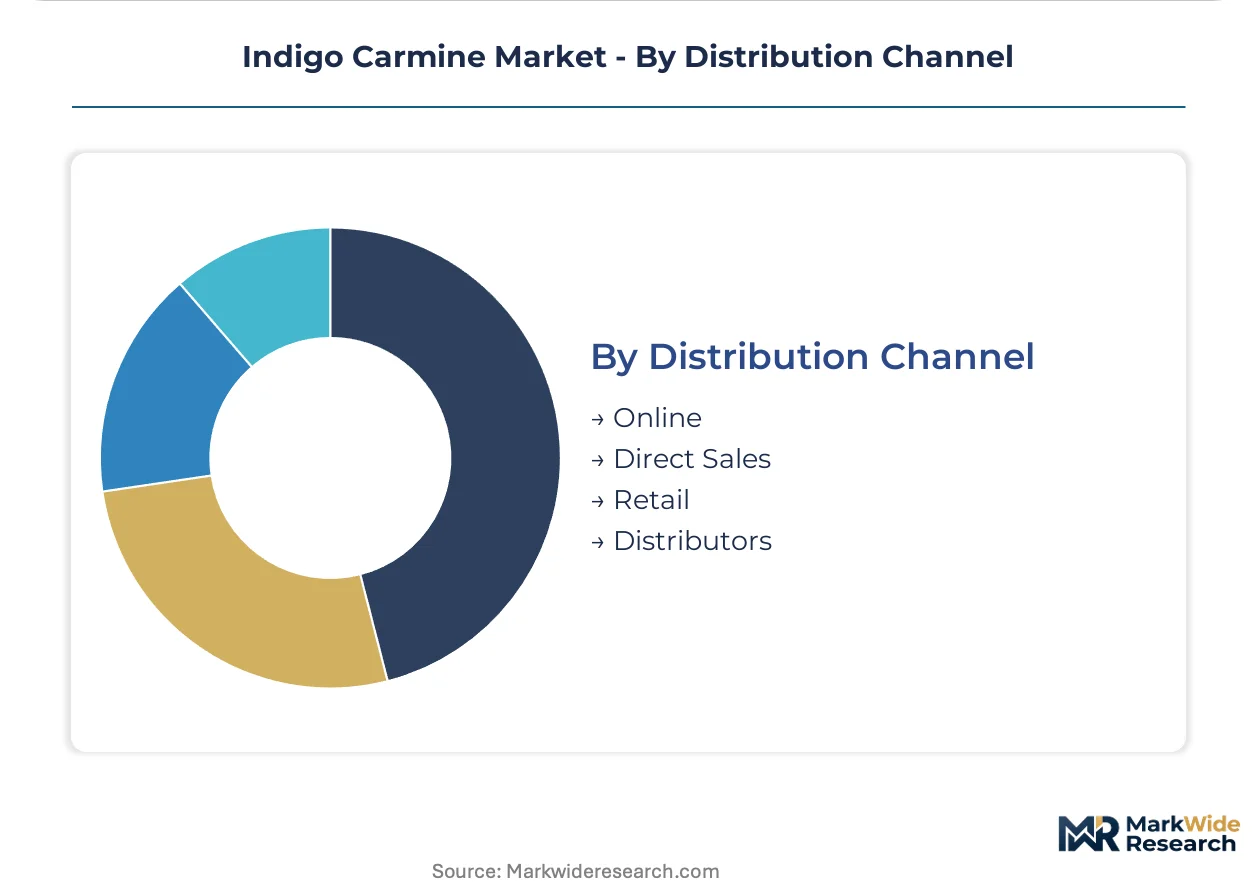
Direct sales anchor pharmaceutical relationships; distributor networks retain food industry penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India consumes indigo carmine predominantly for pharmaceutical diagnostics and surgical marking, while China channels larger volumes into industrial dye intermediates and food processing applications. Germany and Switzerland anchor European demand through parenteral-grade certification requirements. The United States splits procurement across FDA-regulated food additives and USP-NF pharmaceutical formulations.
India
Pharmaceutical manufacturing clusters in Hyderabad and Mumbai drive demand for CDSCO-certified powder grades used in lymph node mapping and diagnostic formulations. India's tightening pharmacopeial alignment with USP-NF standards is accelerating supplier qualification timelines for imported dye stocks. The Telangana and Maharashtra pharmaceutical corridors concentrate procurement among ISO 17025-accredited distributors capable of batch-level traceability documentation.
China
Shandong and Jiangsu provinces manufacture over sixty percent of global sulfonated indigo intermediates, supplying both domestic formulators and Western compounders. NMPA pharmacopeial standards for parenteral diagnostics are diverging from FDA monograph requirements, fragmenting export certification burdens. The Yangtze River Delta chemical corridor is consolidating intermediate production among state-backed enterprises with captive environmental compliance infrastructure.
Germany
EMA nitrosamine risk assessment mandates for parenteral excipients are concentrating procurement onto suppliers with validated contamination controls. German oncology centers in Munich and Heidelberg anchor European demand for sentinel lymph node mapping applications. The Ludwigshafen chemical complex hosts continuous processing installations that compress batch release timelines for pharmaceutical-grade dye output.
Switzerland
Swissmedic guidelines for surgical dyes used in tumor resections exceed EMA baseline requirements, creating premium-tier certification demand. Basel-based pharmaceutical formulators source exclusively from nitrosamine-negative production lines with dedicated audit trails. The Swiss-German border region concentrates GMP-certified warehousing and cold-chain logistics for temperature-sensitive liquid formulations.
United States
FDA color additive regulations split procurement between food-grade E132 applications and USP-NF pharmaceutical certifications with divergent testing protocols. New Jersey and North Carolina pharmaceutical corridors demand batch-level certificate-of-analysis data packages before sample evaluation. The FDA's tightened aromatic amine thresholds for synthetic dyes are redirecting procurement toward vertically integrated manufacturers with in-house HPLC testing capabilities.
Indigo Carmine Market Competitive Environment
Capability concentration sits with one tier; scale advantage sits with another. The market structures around three tiers: multinational chemical conglomerates with pharmaceutical-grade certification depth, regional dye houses with intermediate manufacturing control, and specialized colorant formulators with batch consistency protocols. Two strategic archetypes dominate competitive positioning: backward-integrated manufacturers capturing upstream margin and formulation specialists anchoring technical service relationships. Consolidation moves center on nitrosamine-testing capability acquisition and regional distributor network expansion.
Among European-based chemical conglomerates, BASF SE and Clariant AG occupy positions defined by regulatory certification breadth and continuous processing infrastructure. Sensient Colors LLC anchors North American supply relationships through batch consistency protocols and direct sales teams serving pharmaceutical formulators. Dystar exemplifies the backward-integrated archetype with dye manufacturing infrastructure extending into formulation support services.
| Leading Market Players |
|---|
| Dystar |
| Ferro Corporation |
| Huntsman Corporation |
| Chinasun Specialty Products Co., Ltd |
| Sensient Colors LLC |
| BASF SE |
| Kraton Corporation |
| Dynemic Products Ltd |
| Clariant AG |
| Others |
Value Chain & Pricing Dynamics
Shandong and Jiangsu province intermediate concentration anchors margin capture downstream, with sulfonated indigo precursor pricing transmitting directly to pharmaceutical-grade compounders in Germany and Switzerland. Contract structures stratify procurement power between long-term offtake agreements favored by CDSCO-certified manufacturers and spot purchases absorbing raw material volatility.
Pricing Analysis
Long-term offtake agreements dominate pharmaceutical-grade procurement, with CDSCO and Swissmedic-certified buyers locking in eighteen-to-twenty-four month contracts to secure nitrosamine-negative production lines. Price differentiation rests on certification depth and batch-level traceability documentation, with parenteral-grade suppliers commanding premiums over food-additive tier. Cost compression in liquid formulation grades is intensifying because cold-chain logistics constraints limit sourcing radius and concentrate supplier leverage. Food processors in Germany and Italy show highest price sensitivity, while Swiss oncology centers absorb premium pricing for sentinel node mapping applications.
Supply Chain Analysis
Tariff exposure between China and Western pharmaceutical markets dominates supply chain risk assessment, with ECHA and FDA diverging aromatic amine thresholds fragmenting compliance documentation. Sulfonated indigo intermediates draw from Shandong and Jiangsu provinces in China, with naphthalene and aniline feedstocks tethered to petrochemical pricing cycles. Single-source vulnerability concentrates in Jiangsu province facilities supplying over sixty percent of global pharmaceutical-grade output. Distribution runs through ISO 17025-accredited distributors in Hyderabad and Mumbai for Indian pharmaceutical corridors, with direct sales anchoring Swiss and German oncology center relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Surgical lymph node mapping adoption in Indian and Chinese oncology centers signals early-cycle expansion, with CDSCO and NMPA pharmacopeial alignment accelerating certified dye replacement cycles.
For Market Incumbents: Harden nitrosamine-negative production line certification against EMA and Swissmedic parenteral excipient guidelines, locking in exclusive supply relationships with Basel-based pharmaceutical formulators. Expand backward integration into sulfonated indigo intermediate manufacturing to capture margin pools currently concentrated in Shandong province. Defensive consolidation around analytical chemist expertise in HPLC-based aromatic amine quantification constrains new entrant qualification timelines. For New Entrants and Emerging Players: Brazilian pharmaceutical manufacturing under ANVISA-USP-NF harmonization represents the most penetrable entry point for GMP-certified suppliers lacking established European relationships. Liquid formulation automation demand among German and Italian food processors offers secondary white-space for pumpable concentrate specialists. Partner with regional chemical distributors in São Paulo and Rio de Janeiro to navigate import substitution procurement channels. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale dye houses with validated nitrosamine testing capabilities and existing CDSCO or NMPA certifications, positioned for consolidation into pharmaceutical-grade supply chains. Long-term viability hinges on regulatory certification depth rather than volume scale across the five-to-ten year horizon. Watch ECHA Safe and Sustainable by Design framework implementation as inflection indicator for bio-based process development incentives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Intermediates | Captures margin pools concentrated in Shandong province sulfonated indigo production. |
| Nitrosamine-Negative Production Line Investment | Qualifies suppliers for Swissmedic parenteral excipient guidelines exceeding EMA baselines. |
| Continuous Processing Technology Deployment | BASF and Dystar installations at Ludwigshafen and Singapore compress batch release timelines. |
| Regional Distributor Network Expansion | ANVISA-harmonized Brazilian market opens import substitution for GMP-certified suppliers. |
| Bio-Based Process Development | ECHA Safe and Sustainable by Design framework reduces regulatory scrutiny timelines for qualifying applicants. |
Study Parameters
Desk research of FDA color additive filings, ECHA REACH registration dossiers, and CDSCO pharmacopeial standards preceded structured interviews with pharmaceutical formulators, dye manufacturing plant managers, and oncology procurement leads across India, China, Germany, and Switzerland. Primary fieldwork with BASF and Dystar technical service teams validated batch consistency protocol claims, while secondary triangulation against USP-NF and EP monograph databases anchored purity threshold assumptions. Bottom-up volume modeling across powder, liquid, and granule formats converged with top-down pharmaceutical and food additive market sizing.
Assumptions held fixed include EMA nitrosamine risk assessment mandate continuity and REACH aromatic amine threshold stability, while variables tested included NMPA-FDA pharmacopeial divergence scenarios and natural colorant substitution rates in European retail. Segmentation modeling spanned physical format, application grade tier, and regional regulatory cluster. CAGRs derived from weighted average of historical pharmaceutical diagnostic growth and surgical procedure volume trajectories, with lymph node mapping adoption curves and CDSCO certification timeline compression as industry-specific inputs.
Macroeconomic conditions sit as an overlay; deviation in petrochemical feedstock pricing or China-EU trade friction would shift the trajectory. Forecasts reflect assumptions about regulatory harmonization pace and intermediate supply concentration persistence. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Plastic Pigments Market
Dyes and Pigments
Acrylic Colors Market
Dyes and Pigments
Bismuth Vanadate Pigment Market
Dyes and Pigments
Chlorophyll Color Market
Dyes and Pigments
Iron Oxide Pigments Market
Dyes and Pigments
Pigment Dispersion Resin Market
Dyes and Pigments
Pearlescent Pigments Market
Dyes and Pigments
Global White Inorganic Pigments Market
Dyes and Pigments
Natural Colorants Market
Dyes and Pigments
High Performance Organic Pigments Market
Dyes and Pigments
Global Cosmetic Pigments Market
Dyes and Pigments
Metallic Pigments Market
Dyes and Pigments
Cacao Husk Pigment Market
Dyes and Pigments
Global Thermochromic Materials Market
Dyes and Pigments
Titanium Dioxide Pigment Market
Dyes and Pigments
Carmoisine Market