
 Photochromic Pigments Market | 2026-2036
Photochromic Pigments Market Size, Share, and Industry Trends Forecast 2026-2036
Photochromic Pigments Market Analytics
Software-defined tint control and embedded sensor integration is restructuring how photochromic pigment suppliers capture value, shifting revenue from commodity powder sales toward recurring calibration and performance-monitoring contracts. PPG Industries leverages its coatings chemistry heritage to anchor premium positioning in automotive photochromic applications. Tokuyama Corporation sustains manufacturing scale through captive supply of specialty organometallic intermediates. Vivimed Labs differentiates via concentrated R&D in organic spiropyran derivatives for medical device coatings.
Photochromic pigments are light-sensitive colorants that reversibly change their molecular structure upon ultraviolet exposure, typically employing naphthopyran, spirooxazine, or fulgide chromophores embedded in polymer matrices to modulate visible light transmission between 15% and 85%. Their primary commercial purpose centers on adaptive optical filtration in eyewear lenses, security printing, and responsive architectural glazing. Organic photochromic pigments occupy the dominant share of value generation due to superior fatigue resistance and tunable activation spectra, while UV-activated pigments represent the fastest-growing category as industrial coating formulators seek single-component solutions that eliminate separate primer layers. Powder formulations retain margin concentration in high-specification optical applications where particle size distribution below 5 micrometers governs performance consistency.
FDA ophthalmic device standards and EPA chemical substance evaluations in the United States, alongside REACH authorization requirements administered by ECHA in Europe, collectively elevate compliance costs while restricting certain legacy aromatic amine precursors from new formulations. China's SAMR enforces GB standards for plastics and coatings that incorporate migration limits on photochromic additives in consumer goods, shaping import qualification protocols for foreign suppliers. Stakeholders must monitor evolving regulatory substance restrictions and invest in biocompatible chromophore platforms before compliance deadlines harden competitive access barriers.
Market Dynamics
Software-defined tint control and embedded sensor integration is restructuring how photochromic pigment suppliers capture value, shifting revenue from commodity powder sales toward recurring calibration and performance-monitoring contracts.
Growth Catalysts
- REACH and RoHS compliance requirements:The European Union is tightening permissible substance thresholds, compelling reformulation investments that accelerate biocompatible chromophore platform development across the supply base.
- Eyewear manufacturers:This buyer segment represents the fastest-expanding demand pool as photochromic lens adoption accelerates in prescription and plano categories alike.
- UV-activated pigments:Industrial coating formulators are driving category expansion by seeking single-component solutions that eliminate separate primer layers in automotive and architectural applications.
Market Restraints
- Legacy aromatic amine precursors:ECHA REACH authorization requirements and EPA chemical substance evaluations are restricting these materials from new formulations, forcing costly molecular redesign.
- Specialty organometallic intermediates:Captive supply concentration among Japanese and Korean chemical conglomerates creates input bottleneck risk for Western formulators.
- Inorganic photochromic alternatives:Halide silver-glass systems retain share in high-durability military and aerospace optics, capping organic pigment penetration in premium performance tiers.
Strategic Opportunities
- Medical device coatings:Organic spiropyran derivatives are opening diagnostic and surgical instrument applications where reversible optical switching enables real-time sterility indicators.
- China's domestic optical production:SAMR GB standards enforcement is creating qualified-supplier entry barriers that favor early movers establishing local formulation partnerships.
- Responsive architectural glazing:Building-integrated photovoltaic systems are converging with photochromic interlayers to enable dual-function climate-adaptive facades.
Industry Challenges
- Fatigue resistance engineering:Organic chromophores degrade under repeated UV cycling, requiring specialized polymer matrix stabilization expertise that concentrates among legacy optical polymer houses.
- Particle size distribution control:Sub-5 micrometer consistency specifications for high-specification optical applications demand capital-intensive micronization and classification equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photochromic Pigments Market |
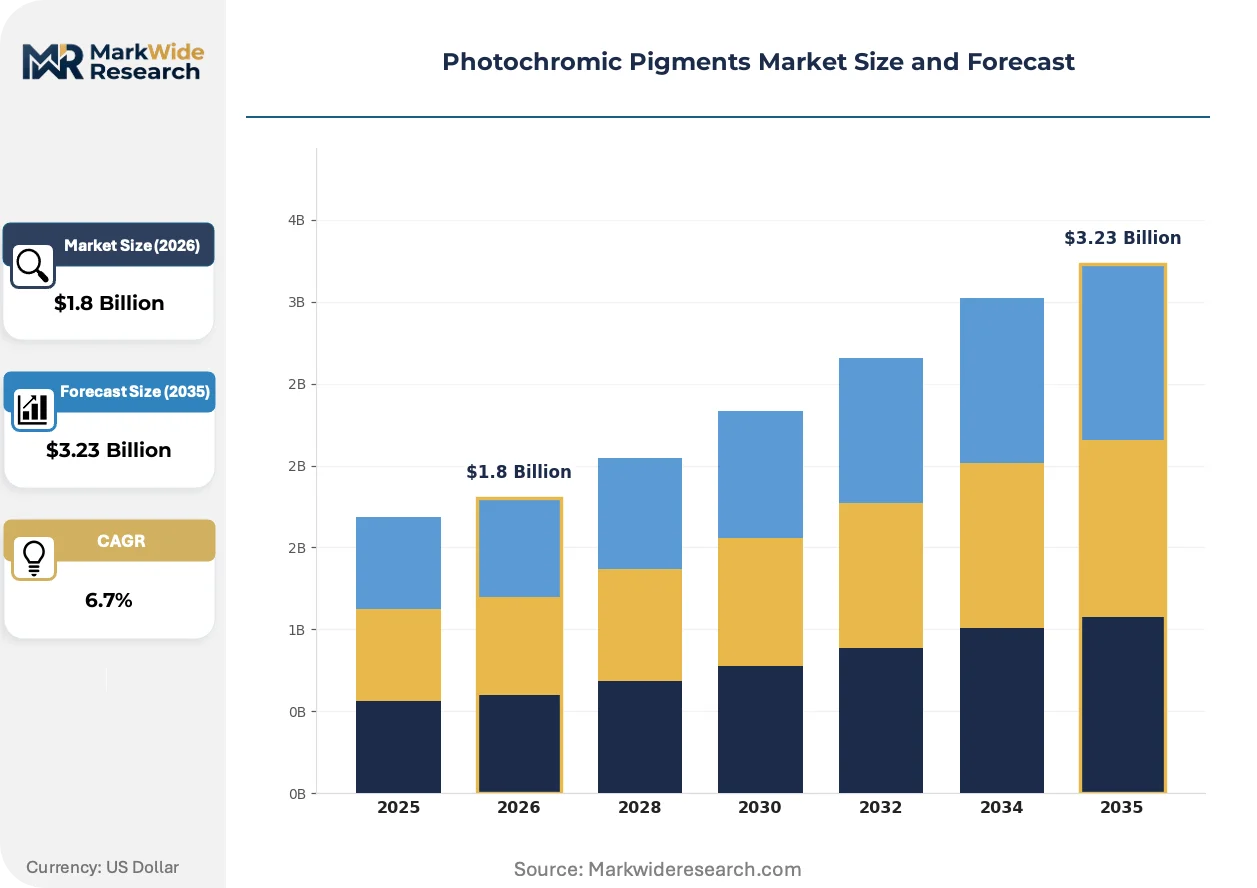
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Photochromic Pigments, Inorganic Photochromic Pigments, Hybrid Photochromic Pigments, UV-Activated Pigments Application: Coatings, Plastics, Textiles, Medical Devices Form: Powder, Liquid, Granules, Paste End User: Automotive, Construction, Consumer Goods, Healthcare |
| Companies Covered | Transitions Optical (EssilorLuxottica), Vivimed Labs, PPG Industries, QCR Solutions Corp, Tokyo Chemical Industry, Tokuyama Corporation, Milliken Chemical, Yamada Chemical, Mitsui Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photochromic Pigments Market Evolving Landscape
Tint modulation systems are fragmenting into componentized architectures that separate chromophore chemistry from sensor integration and control logic, enabling new value-capture models across the stack.
Multi-layer photochromic stacks is modularizing how automotive OEMs specify adaptive glazing, allowing interior and exterior light management to be sourced from different suppliers and calibrated independently. Tier 1 glazing integrators in Germany and Japan are adopting this approach for 2026 model year platforms. The technology is modularizing what had been monolithic pigment-polymer formulations into separable optical engine components.
REACH authorization timelines administered by ECHA are compressing reformulation windows for legacy naphthopyran derivatives, forcing suppliers to pre-register biocompatible alternatives before 2027 sunset dates. Specialty chemical distributors in the Netherlands and Belgium are building compliance documentation services to capture margin from this transition. Medical device coating segments face the steepest recertification burdens.
Performance-based pigment procurement is displacing volume-contract purchasing among major eyewear lens manufacturers, with payment terms now tied to activation speed consistency and fatigue resistance metrics. This restructuring concentrates purchasing power with three dominant lens producers while fragmenting the qualified supplier base. The shift is most visible in China's Zhejiang and Jiangsu optical manufacturing clusters.
Photochromic Pigments Market Segmentation
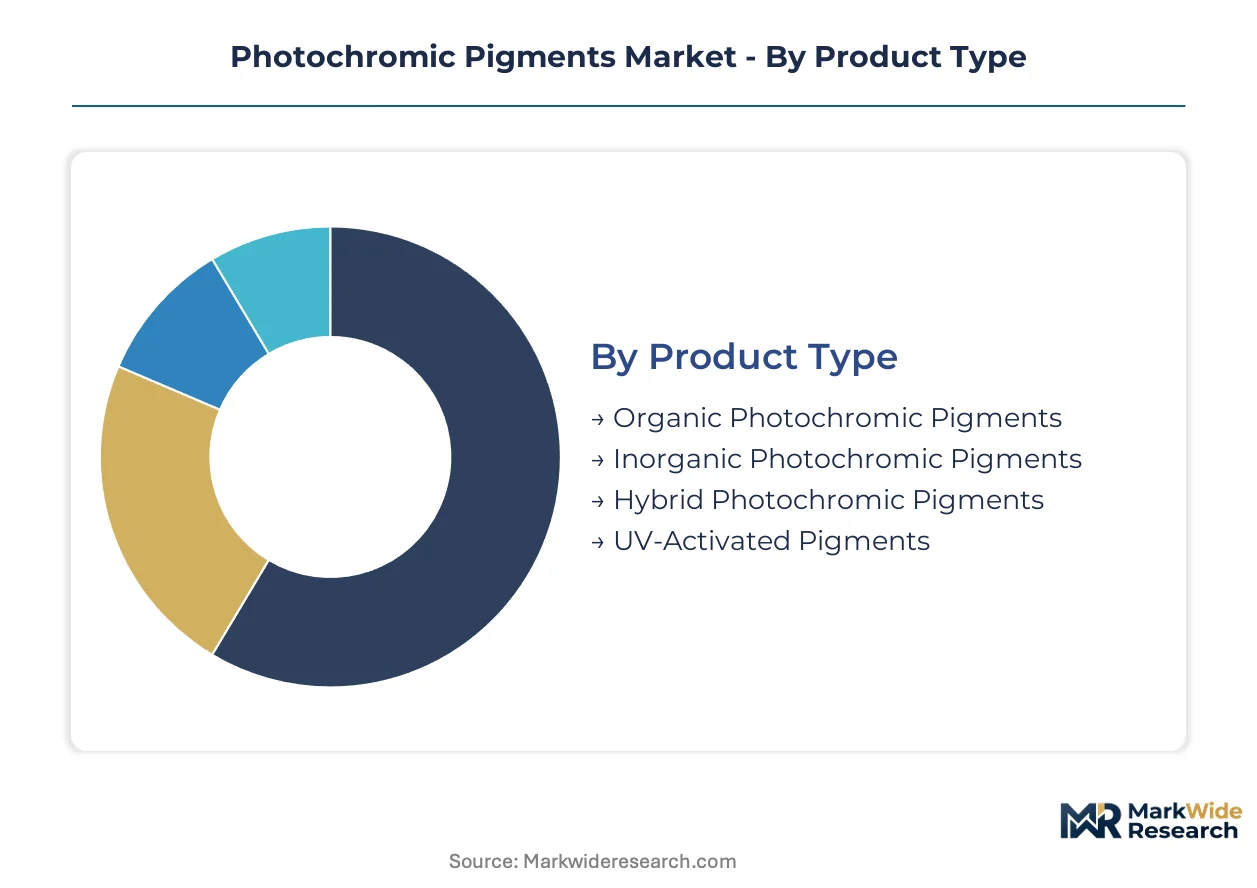
Photochromic pigment suppliers configure their technical service and pricing architectures around four intersecting dimensions that govern formulation complexity, regulatory exposure, and value-capture potential. Each segmentation axis carries distinct margin profiles and qualification barriers that reshape competitive positioning across eyewear, automotive glazing, and responsive materials markets.
Product Type:
Naphthopyran, spirooxazine, and fulgide chromophore chemistries differentiate performance specifications across fatigue resistance, activation spectra, and polymer compatibility matrices.
- Organic Photochromic Pigments:Naphthopyran and spirooxazine chromophores embedded in polymer matrices deliver superior fatigue resistance with tunable activation between 15% and 85% visible light transmission. Eyewear lens manufacturers in China's Zhejiang and Jiangsu clusters concentrate procurement here, though ECHA REACH authorization timelines are compressing reformulation windows for legacy naphthopyran derivatives.
- UV-Activated Pigments:Single-component solutions eliminate separate primer layers in industrial coating applications, attracting automotive and architectural formulators seeking process simplification. Industrial coating formulators across Germany and Japan are driving category expansion by specifying these materials for 2026 model year glazing platforms.
- Inorganic Photochromic Pigments:Halide silver-glass systems retain installed base in military and aerospace optics requiring extreme durability cycles.
- Hybrid Photochromic Pigments:Combined organic-inorganic architectures balance cost and performance for mid-tier consumer applications.
Organic pigments lead on scale; UV-activated pigments lead on momentum.
Application:
End-use specifications dictate polymer matrix selection, migration limit compliance, and optical performance benchmarking protocols.
- Coatings:Automotive OEMs and architectural glazing integrators specify multi-layer photochromic stacks that modularize interior and exterior light management. Tier 1 suppliers in Germany and Japan are adopting componentized architectures for 2026 platforms, enabling independent calibration of optical engine components.
- Plastics:China's SAMR enforces GB standards incorporating migration limits on photochromic additives in consumer goods, shaping import qualification protocols for foreign suppliers targeting domestic optical production expansion.
- Textiles:Responsive apparel applications require wash-fastness engineering that concentrates demand among specialty finish houses.
- Medical Devices:Organic spiropyran derivatives enable real-time sterility indicators on diagnostic and surgical instruments, though FDA ophthalmic device standards and EPA chemical substance evaluations elevate recertification burdens.
Coatings command premium pricing; medical devices offer steepest expansion trajectory.
Form:
Physical state determines dispersion equipment requirements, handling protocols, and integration complexity with customer formulation lines.
- Powder:Sub-5 micrometer particle size distribution specifications govern performance consistency in high-specification optical applications, demanding capital-intensive micronization and classification equipment that concentrates margin among legacy optical polymer houses.
- Liquid:Pre-dispersed concentrates reduce customer processing steps and enable just-in-time delivery models for high-volume coating operations.
- Granules:Masterbatch formats serve plastics compounders seeking direct extrusion integration without additional dispersion steps.
- Paste:High-solids formulations target textile and specialty coating segments requiring precise viscosity control.
Powder retains margin concentration; liquid gains share in automotive supply chains.
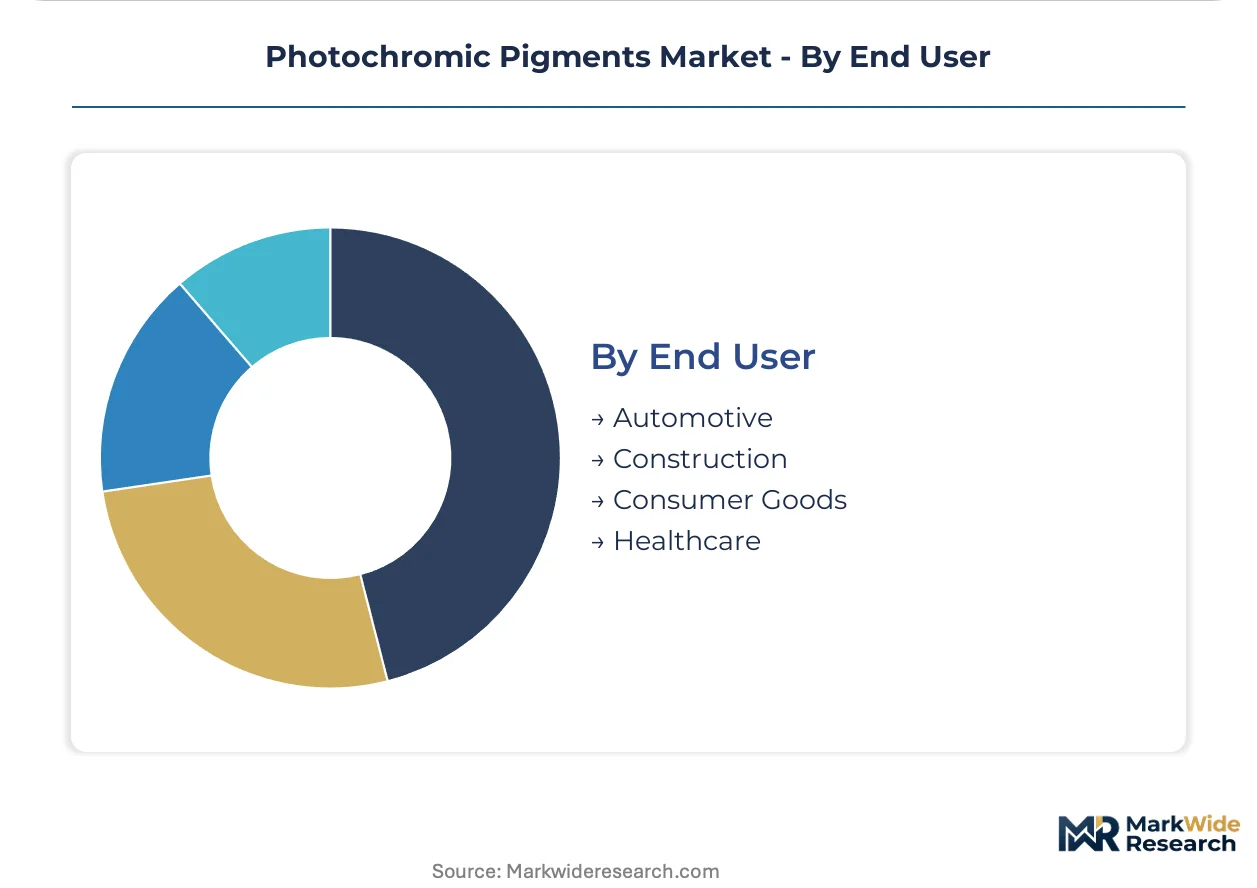
End User:
Industry-specific regulatory frameworks and performance certification requirements fragment procurement specifications and supplier qualification pathways.
- Automotive:Building-integrated photovoltaic convergence with photochromic interlayers enables dual-function climate-adaptive facades, with responsive architectural glazing specifications emerging as a strategic priority for glazing integrators.
- Construction:Climate-adaptive facade systems combine energy generation with dynamic solar control, creating specification overlap with automotive glazing technologies.
- Consumer Goods:Eyewear manufacturers represent the fastest-expanding demand pool as photochromic lens adoption accelerates in prescription and plano categories, with performance-based procurement displacing volume-contract purchasing.
- Healthcare:Biocompatible chromophore platforms face compressed development timelines ahead of compliance deadlines that harden competitive access barriers.
Consumer goods anchors volume; healthcare commands qualification premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's optical manufacturing clusters absorb volume at scale while Germany's automotive glazing integrators command premium specifications, revealing a bifurcation between volume gravity and value concentration across the photochromic pigment supply map.
China
Zhejiang and Jiangsu provinces anchor domestic lens production expansion as SAMR enforces GB standards for plastics migration limits. The regulator's import qualification protocols favor early movers establishing local formulation partnerships. Hangzhou and Suzhou optical manufacturing clusters concentrate procurement for both prescription and plano photochromic lens categories.
Germany
Tier 1 glazing integrators specify multi-layer photochromic stacks for 2026 automotive platforms requiring independent interior and exterior calibration. ECHA REACH authorization timelines compress reformulation windows, forcing pre-registration of biocompatible naphthopyran alternatives before 2027 sunset dates. Stuttgart and Munich automotive engineering centers drive adaptive glazing specification.
United States
FDA ophthalmic device standards and EPA chemical substance evaluations elevate compliance costs for medical coating applications. Performance-based procurement contracts displace volume purchasing among dominant lens manufacturers. Rochester's legacy optical polymer houses retain specialized fatigue resistance stabilization expertise.
Japan
Captive supply of specialty organometallic intermediates concentrates among chemical conglomerates serving domestic formulators. METI industrial standards shape export qualification for high-durability coating applications. Osaka and Nagoya chemical manufacturing bases sustain upstream intermediate production.
Netherlands
Specialty chemical distributors build compliance documentation services to capture margin from REACH transition pressures. Rotterdam and Antwerp logistics hubs facilitate pigment concentrate distribution into German and French coating supply chains. ECHA-administered authorization timelines position Dutch intermediaries as critical reformulation partners.
Photochromic Pigments Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with optical-grade powder formulations concentrating among legacy polymer houses while coating integrators fragment procurement across pre-dispersed liquid suppliers. The vendor base organizes into three strategic archetypes: captive intermediate producers, formulation-integrated specialists, and regional distribution intermediaries. M&A activity targets compliance documentation capabilities in Europe, while capacity expansion concentrates in China's Yangtze River Delta optical clusters.
Among Japanese chemical conglomerates, Tokuyama Corporation and Mitsui Chemicals occupy positions anchored by upstream intermediate control. Transitions Optical exemplifies the brand-integrated model spanning lens design through retail distribution. PPG Industries represents the coatings chemistry heritage path into automotive and industrial applications. Vivimed Labs sits within the specialty derivative tier focused on medical and diagnostic device segments.
| Leading Market Players |
|---|
| Transitions Optical (EssilorLuxottica) |
| Vivimed Labs |
| PPG Industries |
| QCR Solutions Corp |
| Tokyo Chemical Industry |
| Tokuyama Corporation |
| Milliken Chemical |
| Yamada Chemical |
| Mitsui Chemicals |
| Others |
Value Network & Pricing Analysis
Specialty organometallic intermediate pricing indices cascade through three distinct value tiers, with captive supply concentration among Japanese and Korean chemical conglomerates anchoring premium optical-grade powder quotations while Chinese dispersion houses compress mid-tier liquid concentrate margins through capacity expansion.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for liquid concentrate formats, forcing legacy optical polymer houses to defend powder premiums through sub-5 micrometer particle size guarantees. Three-tier pricing structure across premium, standard, and economy levels separates fatigue-resistant naphthopyran derivatives from basic spirooxazine formulations and commodity hybrid blends. Pricing pressure stems from performance-based procurement contracts that tie payment terms to activation speed consistency metrics. Eyewear manufacturers in Zhejiang and Jiangsu clusters exhibit highest price sensitivity, while German automotive glazing integrators absorb premium specifications with limited negotiation leverage.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Antwerp operate as hub-and-spoke nodes for pigment concentrate flows into German and French coating supply chains, with secondary spokes reaching Italian and Spanish formulators. Upstream manufacturing concentrates in China, Japan, and Germany, with specialty organometallic intermediate production anchored in Osaka and Nagoya chemical bases. Raw material dependencies include naphthopyran chromophore precursors, spirooxazine intermediates, and high-purity polymer matrix resins. Single-source vulnerability concentrates in Japanese captive supply of organometallic inputs. Distribution runs through specialty chemical distributors building compliance documentation services for REACH transition support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The photochromic pigments market reads as a late-cycle quality story, with eyewear manufacturers shifting procurement toward fatigue-resistant specifications that reward technical service depth over volume scale.
For Market Incumbents: Deepen backward integration into specialty organometallic intermediates before Japanese and Korean chemical conglomerates tighten captive supply bottlenecks. Pre-register biocompatible naphthopyran alternatives ahead of ECHA REACH authorization timelines to defend formulation partnerships with medical device coating segments. Expand micronization capacity in legacy optical polymer houses to maintain sub-5 micrometer particle size distribution guarantees that command powder premiums. For New Entrants and Emerging Players: Begin with UV-activated pigment formats for automotive and architectural coating formulators seeking single-component solutions that eliminate primer layers. Target China's domestic optical production expansion by establishing local formulation partnerships ahead of SAMR GB standards enforcement hardening import qualification barriers. Lead with compliance documentation services as a differentiated entry wedge for European REACH transition support. For Investors and Strategic Acquirers: Consolidation pressure builds where specialty chemical distributors capture margin from reformulation service demands without owning chromophore chemistry capabilities. Long-term viability favors acquisition targets with biocompatible platform development expertise and established ECHA pre-registration documentation. Watch for inflection signals in performance-based procurement contract penetration rates among China's Zhejiang and Jiangsu optical manufacturing clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organometallic Intermediates | Captive supply of naphthopyran precursors reduces dependency on Japanese chemical conglomerates. |
| Biocompatible Chromophore Platform Development | FDA and ECHA pre-registration opens medical device coating segments with recertification premiums. |
| Sub-5 Micrometer Micronization Capacity Expansion | Particle size distribution guarantees defend powder margins against Chinese liquid concentrate competition. |
| Local Formulation Partnerships in China | SAMR GB standards compliance documentation enables qualified-supplier status in Zhejiang and Jiangsu clusters. |
| Performance-Based Procurement Contract Structuring | Activation speed and fatigue resistance metrics shift revenue toward recurring calibration services. |
Research Methodology
Bottom-up eyewear and automotive coating modeling reconciled against top-down specialty chemical production tracking forms the analytical core of this study. Primary interviews with optical polymer R&D directors, automotive glazing procurement leads, specialty chemical distribution managers, and SAMR compliance consultants combined with secondary validation from ECHA authorization databases, SEC chemical company filings, and Chinese customs trade data. Triangulation across stakeholder perspectives and documentary sources ensures segmentation integrity across chromophore chemistry, application format, and regional regulatory cluster dimensions.
Historical trendline analysis of naphthopyran and spirooxazine derivative pricing trajectories informs projection frameworks across the analysis window. Segmentation modeling incorporates product type, application, physical form, and end-user industry dimensions with specific attention to fatigue resistance engineering requirements and particle size distribution specifications. CAGRs derive from weighted average growth assumptions across UV-activated pigment momentum, organic photochromic pigment scale maintenance, and inorganic alternative niche retention. Forecast inputs include SAMR enforcement timeline assumptions and ECHA pre-registration completion rates.
Several conditions sit outside the modeled scope, including unforeseen ECHA substance restriction accelerations, breakthrough inorganic photochromic durability improvements, and automotive OEM platform standardization cancellations. Forecasts reflect documented assumptions around regulatory compliance deadlines and intermediate supply continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Metal Complex Dyes Market
Dyes and Pigments
Chlorophyll Color Market
Dyes and Pigments
Iridescent Pigments Market
Dyes and Pigments
Special Effect Pigments Market
Dyes and Pigments
Global Organic Pigments Market
Dyes and Pigments
Global Pigments Market
Dyes and Pigments
Color Concentrates Market
Dyes and Pigments
Asia Pacific Hair Colorants Market
Dyes and Pigments
Fluorescent Pigments Market
Dyes and Pigments
Asia-Pacific Pigments Market
Dyes and Pigments
Metallic Pigments Market
Dyes and Pigments
Pearl Pigment Market
Dyes and Pigments
Resin Pigments Market
Dyes and Pigments
Inorganic Pigments Market
Dyes and Pigments
Petroleum-Fuel Dyes and Markers Market
Dyes and Pigments
Acid Violet 43 Market