
 Organic Lake Pigments Market | 2026-2036
Organic Lake Pigments Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Lake Pigments Market Analytics
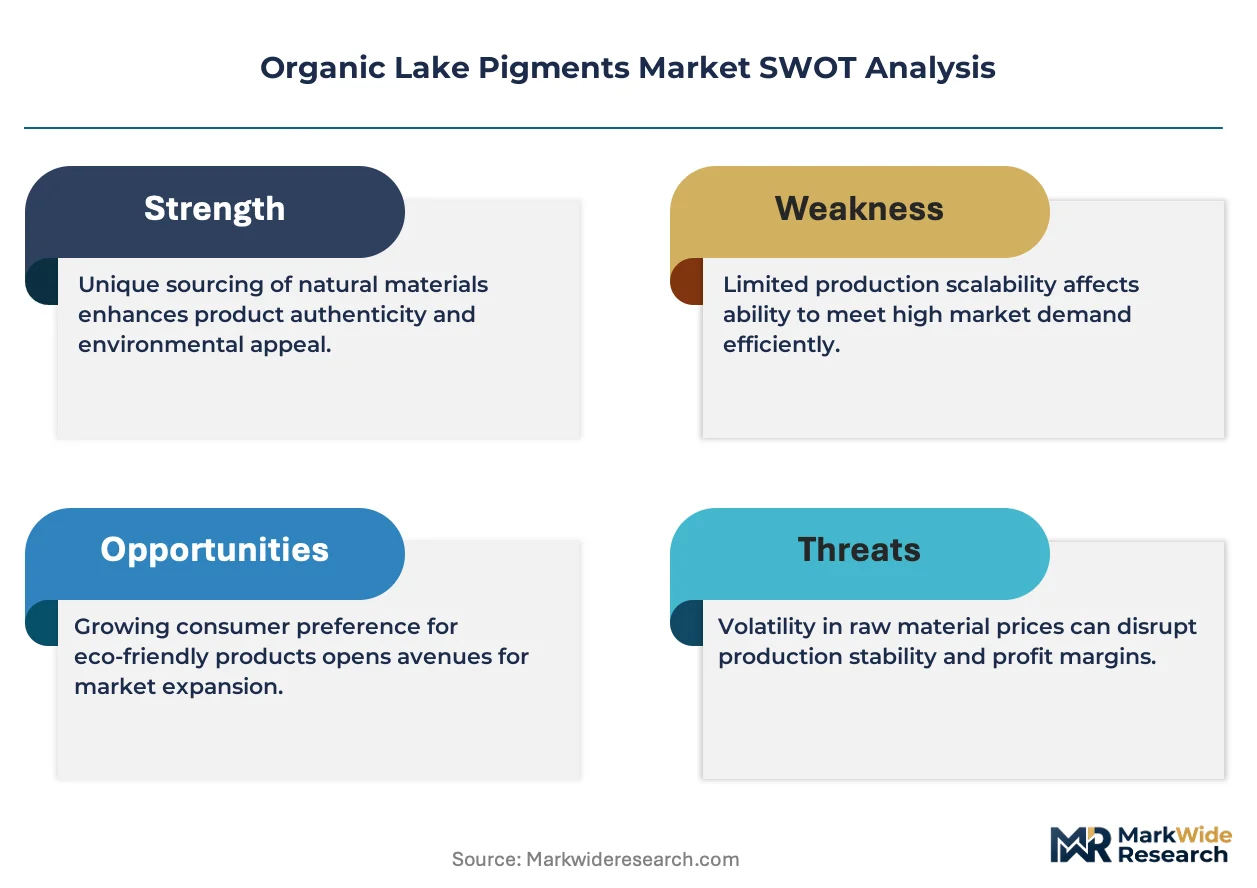
ISO 22000 certification is redrawing competitive boundaries in the organic lake pigments sector. Clariant leverages its integrated pigment production network across European manufacturing sites to sustain supply security for food-grade applications. Heubach GmbH anchors its position through specialized lake pigment portfolios serving pharmaceutical tablet coatings. Sun Chemical competes on color consistency and batch-to-batch stability for high-volume beverage clients.
Organic lake pigments are insoluble colorant complexes formed by precipitating soluble dyes onto approved substrates such as alumina hydrate, yielding particles with controlled particle size distribution and lightfastness ratings. These pigments serve industries requiring stable, non-bleeding coloration where direct dye migration would compromise product integrity or regulatory compliance. Food Colorants command the dominant share of value as beverage manufacturers reformulate away from azo-based synthetics under tightening safety reviews. Cosmetic Colors represent the fastest-expanding segment as indie beauty brands in South Korea and Brazil prioritize vegan-certified, heavy-metal-free color systems. Printing Inks remain a mature, volume-driven category with margin pressure from digital substitution in packaging graphics.
FDA Title 21 CFR regulations govern permissible substrates and certification protocols for lake pigments entering food and drug applications in the United States. EFSA evaluations under the EU food additives program determine acceptable daily intake thresholds and influence reformulation decisions across European confectionery and nutraceutical producers. India's FSSAI notification requirements for imported color additives create compliance friction that domestic manufacturers exploit. Stakeholders must monitor pending substrate approvals and evolving purity specifications rather than assuming existing formulations will retain grandfathered status.
Market Dynamics
REACH substance evaluation and FDA batch certification protocols are restructuring competitive entry barriers, forcing reformulation investments and substrate qualification timelines that favor established pigment houses with captive regulatory affairs teams.
Growth Catalysts
- Clean-label beverage reformulation:Major soft-drink bottlers in North America and Western Europe are eliminating azo dyes from caramel color systems, creating pull-through demand for lake pigment alternatives with equivalent light stability.
- EFSA re-evaluation cycles:Accelerated safety reviews of synthetic colorants under the EU food additives program are compressing grandfathered formulation windows and redirecting R&D budgets toward natural lake complexes.
- India pharmaceutical coating expansion:Domestic tablet and capsule manufacturers are scaling film-coating operations to serve export markets, requiring heavy-metal-free colorant inventories that comply with USP-NF monographs.
Market Restraints
- Alumina hydrate supply concentration:Three specialty chemical producers control the majority of food-grade substrate supply, creating input cost volatility when mining disruptions occur in bauxite-rich geographies.
- FSSAI import notification friction:India's additive approval queue extends certification timelines for foreign pigment suppliers, advantaging domestic manufacturers with pre-registered colorant portfolios.
- Digital printing substitution:Variable-data inkjet systems in flexible packaging are displacing gravure applications that historically consumed high volumes of organic lake pigments.
Strategic Opportunities
- Brazil vegan cosmetics certification:ANVISA-aligned cruelty-free mandates are opening premium positioning for heavy-metal-free lake pigments in lipstick and eye shadow formulations.
- ISO 22000 integration services:Pigment houses that bundle certification consulting with product supply are capturing long-term contracts from mid-sized confectionery exporters.
- Pharmaceutical excipient convergence:Tablet coating pigments formulated with controlled-release polymers are enabling single-step processing that reduces manufacturing line complexity.
Industry Challenges
- Analytical chemist scarcity:Batch-to-batch spectrophotometric matching and heavy-metal testing require specialized technicians that pigment manufacturers struggle to recruit in competitive labor markets.
- Multi-jurisdiction dossier maintenance:Simultaneous compliance with FDA Color Additive Status lists, EFSA food additive specifications, and FSSAI purity standards demands dedicated regulatory staff and recurring third-party testing expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Lake Pigments Market |
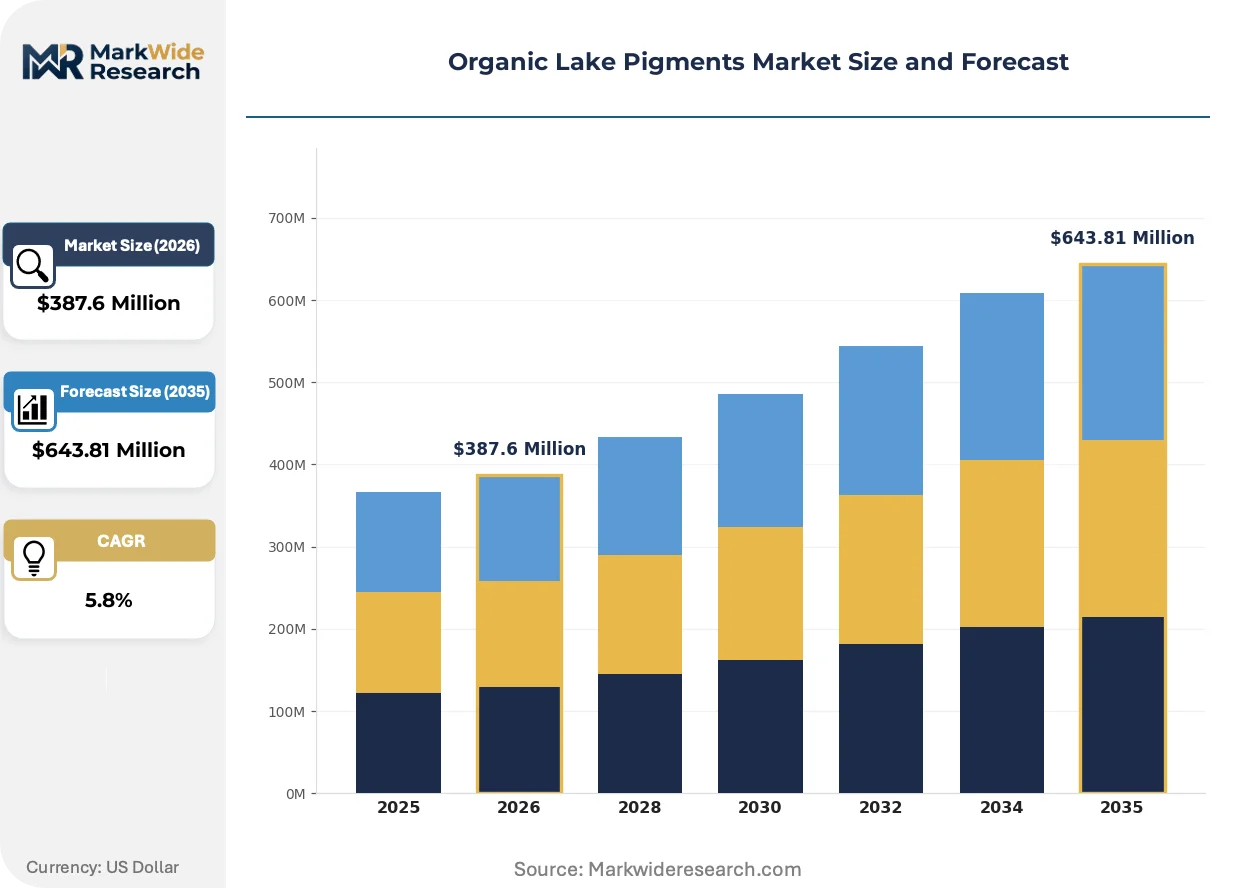
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Colorants, Cosmetic Colors, Textile Dyes, Printing Inks Application: Beverages, Bakery Products, Personal Care, Paints End User: Food Manufacturers, Cosmetics Brands, Textile Producers, Artists Distribution Channel: Online Retail, Specialty Stores, Wholesale Distributors, Direct Sales |
| Companies Covered | Clariant, Heubach GmbH, DIC Corporation, Sun Chemical, Huntsman Corporation, Sudarshan Chemical Industries Limited, artience Co., Ltd., Vipul Organics, BASF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Lake Pigments Market Evolving Landscape
Particle engineering and substrate modification techniques are compressing performance gaps between natural and synthetic colorants, while regulatory data requirements are professionalizing supply relationships beyond commodity transactions.
Encapsulated lake pigment systems with modified starch or gum arabic shells are decomposing the traditional trade-off between water dispersibility and oil-phase stability. Nutraceutical soft-gel manufacturers in Germany and the United States are adopting these complexes for omega-3 and vitamin formulations where bleeding resistance is critical. The technology is decomposing legacy single-substrate formulations by enabling dual-phase compatibility without separate inventory SKUs.
EFSA's systematic re-evaluation of aluminum-containing food additives is tightening acceptable daily intake calculations for lake pigments precipitated on alumina hydrate. European confectionery exporters are reformulating with calcium carbonate or titanium dioxide alternatives where permitted, while awaiting final opinions on residual aluminum thresholds. The policy shift most affects seasonal candy producers who must commit to colorant specifications six months ahead of production cycles.
Beauty brand technical buyers are consolidating supplier relationships around pigment houses that provide complete regulatory dossiers rather than commodity colorants. South Korean indie cosmetics labels now require heavy-metal certificates of analysis, stability data, and vegan certification documentation as standard procurement terms. This behavioral shift concentrates contract value with integrated manufacturers and disadvantages trading houses that lack in-house analytical capabilities.
Organic Lake Pigments Market Segmentation
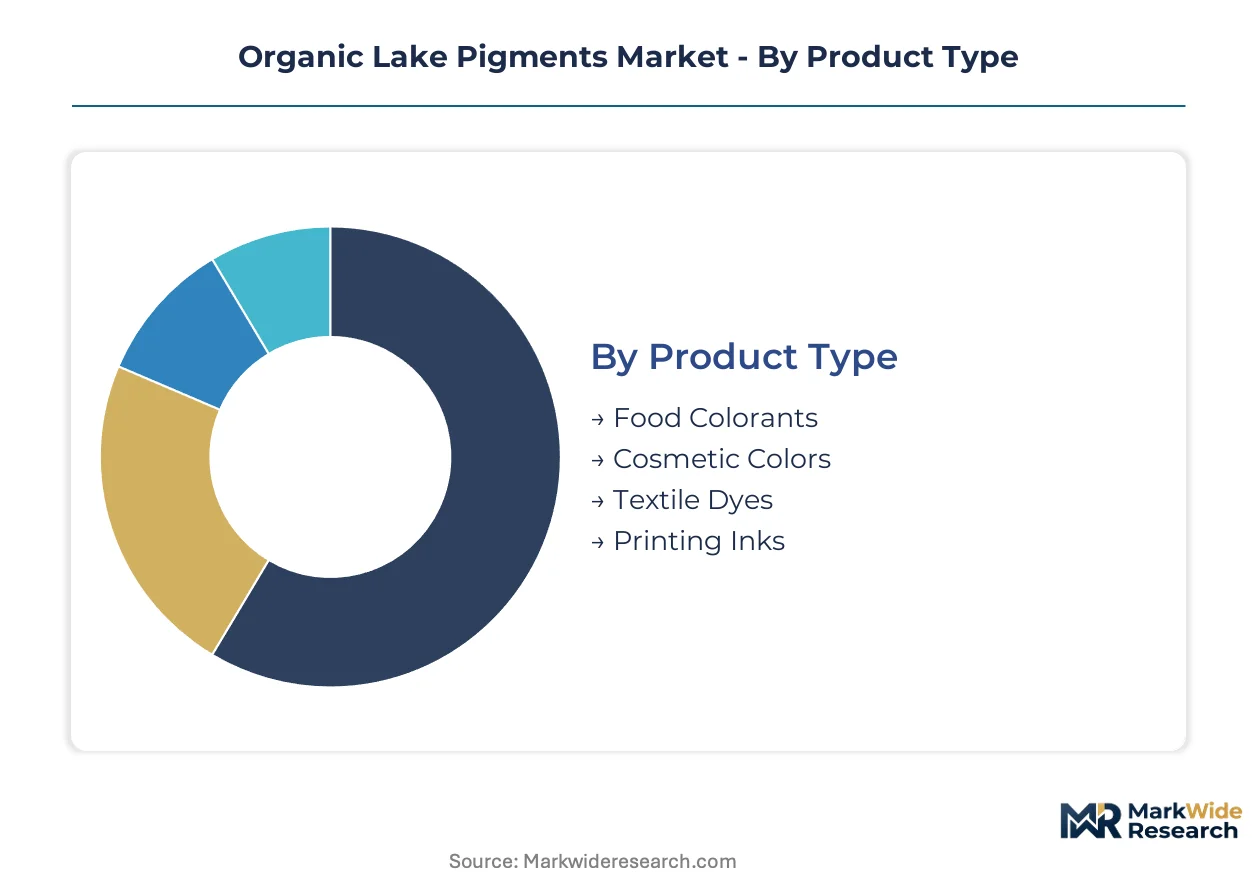
Segmentation in organic lake pigments reveals how substitution pressures and regulatory fragmentation create divergent competitive dynamics across product categories. Understanding these fault lines helps suppliers allocate technical resources and compliance investments where defensibility is strongest.
Product Type:
Substitution pressure varies sharply by product type, with digital alternatives and natural dye systems threatening legacy pigment applications at different velocities.
- Food Colorants:Alumina-hydrate precipitated complexes dominate beverage and confectionery applications where lightfastness and migration resistance are non-negotiable. Reformulation demand concentrates in North American soft-drink bottlers eliminating azo-based caramel alternatives under FDA safety reviews. EFSA aluminum additive re-evaluations are compressing formulation windows for European seasonal candy producers.
- Cosmetic Colors:Heavy-metal-free lake pigments serve lipstick, eye shadow, and pressed powder formulations where vegan certification and ANVISA-aligned cruelty-free mandates open premium positioning. South Korean indie beauty brands now require complete regulatory dossiers as standard procurement terms.
- Textile Dyes:Water-dispersible pigment preparations address synthetic fiber coloration where direct dye bleeding would compromise fabric performance.
- Printing Inks:Gravure and flexographic applications face margin compression from digital inkjet substitution in variable-data packaging graphics.
Food Colorants retain volume leadership; Cosmetic Colors hold the steepest expansion curve.
Application:
Application segments stratify by margin tier, with pharmaceutical-adjacent coatings commanding premium pricing against commoditized industrial uses.
- Beverages:Lake pigments provide stable coloration in acidic formulations where synthetic alternatives face grandfathered status erosion. Clean-label reformulation by major North American bottlers is redirecting R&D budgets toward natural lake complexes with equivalent light stability.
- Bakery Products:Heat-stable colorant systems address fondant, icing, and decorative applications where thermal processing would degrade direct dyes.
- Personal Care:Encapsulated pigment systems with modified starch or gum arabic shells enable dual-phase compatibility for nutraceutical soft-gel manufacturers in Germany and the United States.
- Paints:Industrial coatings applications represent mature demand with limited growth acceleration.
Beverages dominate value capture; Personal Care applications are climbing the fastest.
End User:
End-user concentration patterns reflect supply chain control points, with integrated manufacturers capturing contract value that trading houses cannot access.
- Food Manufacturers:Confectionery and beverage producers drive batch-to-batch consistency requirements that favor pigment houses with captive spectrophotometric matching capabilities.
- Cosmetics Brands:Technical buyers consolidate supplier relationships around integrated manufacturers providing heavy-metal certificates of analysis, stability data, and vegan certification documentation.
- Textile Producers:Synthetic fiber coloration demands water-dispersible systems with controlled particle size distribution.
- Artists:Fine art applications represent niche volume with specialized lightfastness specifications.
Food Manufacturers anchor procurement volume; Cosmetics Brands are gaining share fastest.
Distribution Channel:
Channel structure reflects customer scale and technical service intensity, with direct relationships capturing value that transactional channels cannot sustain.
- Online Retail:E-commerce platforms serve small-batch artisan and educational customers with standardized SKU offerings and limited technical support.
- Specialty Stores:Regional distributors with formulation expertise address mid-sized confectionery exporters requiring ISO 22000 integration services bundled with product supply.
- Wholesale Distributors:Volume-driven intermediaries face margin compression as integrated manufacturers consolidate direct relationships.
- Direct Sales:Pigment houses with captive regulatory affairs teams capture long-term contracts from pharmaceutical coating operations requiring USP-NF monograph compliance.
Direct Sales retain margin leadership; Specialty Stores are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food manufacturers in India and cosmetics formulators in South Korea anchor procurement volumes for heavy-metal-free lake pigments, while pharmaceutical coating operations in Germany and beverage reformulators in the United States drive specification tightening.
India
Domestic tablet and capsule manufacturers scale film-coating operations for export markets, requiring USP-NF monograph compliance. FSSAI notification requirements for imported color additives create compliance friction that domestic manufacturers exploit. Mumbai-Pune pharmaceutical clusters expand local sourcing of food-grade lake pigments to bypass import queues.
Germany
Nutraceutical soft-gel manufacturers adopt encapsulated pigment systems for omega-3 formulations requiring bleeding resistance. EFSA re-evaluation cycles under the EU food additives program compress grandfathered formulation windows. Bavarian confectionery exporters reformulate ahead of seasonal production cycles as residual aluminum thresholds tighten.
United States
Major soft-drink bottlers eliminate azo dyes from caramel color systems, pulling demand for lake pigment alternatives with equivalent light stability. FDA batch certification protocols and Title 21 CFR substrate approvals restructure competitive entry barriers. New Jersey and Pennsylvania pharmaceutical coating hubs require dedicated regulatory affairs teams for Color Additive Status list maintenance.
South Korea
Indie beauty brands consolidate supplier relationships around pigment houses providing complete regulatory dossiers as standard procurement terms. MFDS cosmetic safety evaluations align with ANVISA cruelty-free mandates for premium positioning. Seoul metropolitan area cosmetics clusters drive vegan-certified, heavy-metal-free color system specifications.
Brazil
ANVISA-aligned cruelty-free mandates open premium positioning for heavy-metal-free lake pigments in lipstick and eye shadow formulations. Clean-label cosmetic reformulation accelerates as domestic indie brands target export markets. São Paulo and Rio de Janeiro beauty manufacturing corridors concentrate technical buyer consolidation around integrated pigment suppliers.
Organic Lake Pigments Market Competitive Landscape
Player mix skews toward integrated pigment houses with captive regulatory affairs capabilities and specialized lake pigment portfolios serving pharmaceutical and food-grade applications. Market structure concentrates contract value with manufacturers possessing in-house spectrophotometric matching and heavy-metal testing infrastructure, while trading houses face margin compression. Strategic archetypes include vertically integrated specialty chemical producers, regional pharmaceutical coating specialists, and diversified colorant houses with beverage sector concentration. Dominant competitive moves encompass ISO 22000 certification bundling with product supply and substrate qualification investments to preempt EFSA aluminum additive restrictions.
Among European integrated pigment houses, Clariant and Heubach GmbH occupy positions anchored by specialized lake pigment portfolios and food-grade production networks. Sun Chemical represents the diversified colorant house archetype competing on batch-to-batch stability for high-volume beverage clients. Sudarshan Chemical Industries Limited exemplifies regional pharmaceutical coating specialists expanding local sourcing capabilities to serve export markets with USP-NF compliant inventories.
| Leading Market Players |
|---|
| Clariant |
| Heubach GmbH |
| DIC Corporation |
| Sun Chemical |
| Huntsman Corporation |
| Sudarshan Chemical Industries Limited |
| artience Co., Ltd. |
| Vipul Organics |
| BASF |
| Others |
Value Network & Pricing Analysis
ISO 22000 certification gates both supplier qualification and price differentiation simultaneously, forcing pigment houses to bundle compliance consulting with product supply or surrender margin to trading houses lacking captive regulatory affairs teams. This regulatory overlay compresses procurement options for mid-sized confectionery exporters while concentrating pricing power with integrated manufacturers possessing in-house spectrophotometric matching capabilities.
Pricing Analysis
Cost-plus contracts with alumina hydrate indexation dominate long-term supply agreements between pigment houses and pharmaceutical coating operations. Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial-grade certification levels separates USP-NF compliant inventories from standard food additive specifications. Cost compression in beverage-grade lake pigments intensifies as major North American bottlers consolidate supplier relationships around batch-to-batch stability guarantees. Pharmaceutical coating operations exhibit least price sensitivity due to regulatory switching costs, while gravure printing ink buyers face acute margin pressure from digital substitution.
Supply Chain Analysis
Bauxite mining disruptions in Guinea and Australia concentrate alumina hydrate supply vulnerability for food-grade substrate producers. Pigment manufacturing draws from specialty alumina hydrate, certified dye intermediates, and precipitating agents as core inputs. Single-source vulnerability in pharmaceutical-grade substrate qualification creates supply chain risk when EFSA aluminum additive re-evaluations force reformulation timelines. Distribution runs through direct sales channels for pharmaceutical and large-volume beverage accounts, with specialty distributors serving mid-tier confectionery exporters requiring bundled ISO 22000 integration services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of analytical chemists capable of batch-to-batch spectrophotometric matching and heavy-metal testing creates a capability bottleneck that determines which pigment houses capture long-term contracts versus ceding share to trading houses lacking technical infrastructure.
For Market Incumbents: Consolidate supplier relationships with mid-sized confectionery exporters by bundling ISO 22000 certification consulting with product supply, locking in multi-year contracts before emerging regional players build captive regulatory affairs capabilities. Expand backward integration into alumina hydrate substrate production to preempt input cost volatility from bauxite mining disruptions in Guinea and Australia. Vertical integration of precipitating agent manufacturing reduces exposure to specialty chemical supply concentration. For New Entrants and Emerging Players: Differentiate on vegan-certified, heavy-metal-free cosmetic color systems for South Korean and Brazilian indie beauty brands that now require complete regulatory dossiers as standard procurement terms. Target pharmaceutical coating operations in India where FSSAI import notification friction disadvantages foreign suppliers and domestic manufacturers with pre-registered colorant portfolios capture share. Lead with USP-NF monograph compliance and stability data packages as the go-to-market wedge. For Investors and Strategic Acquirers: EFSA's systematic re-evaluation of aluminum-containing food additives reshapes the acquisition landscape by compressing grandfathered formulation windows and redirecting R&D budgets toward natural lake complexes. Long-term viability favors pigment houses with demonstrated substrate qualification capabilities and captive analytical infrastructure over trading houses facing margin compression. Monitor pending FDA substrate approvals and residual aluminum threshold determinations as the primary inflection signal for portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alumina Hydrate Production | Captive substrate supply insulates margin from bauxite mining disruption in Guinea. |
| ISO 22000 Certification Bundling | Integrated consulting services capture long-term contracts from mid-sized confectionery exporters. |
| Encapsulated Pigment System Development | Modified starch shells enable dual-phase compatibility for German nutraceutical soft-gel manufacturers. |
| Pharmaceutical Excipient Convergence | Controlled-release polymer formulations reduce manufacturing line complexity for tablet coating operations. |
| Regional Production Footprint Expansion | Local sourcing in India bypasses FSSAI import queues and captures pharmaceutical export demand. |
Research Methodology
Initial hypotheses were tested against primary input from pigment manufacturing plant managers, regulatory affairs directors at food and pharmaceutical companies, cosmetics brand technical buyers, and specialty chemical distribution channel partners and refined through secondary validation. Customs and trade data, FDA Color Additive Status lists, EFSA food additive specifications, FSSAI notification records, and SEC filings from publicly traded pigment houses provided foundational triangulation. Bottom-up demand modeling across beverage, confectionery, pharmaceutical coating, and cosmetics applications converged with top-down supply-side capacity assessments.
Variance decomposition across product type, application, end-user concentration, and regional regulatory cluster dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segment-level demand elasticity modeling and supply capacity expansion trajectories. Alumina hydrate price index movements, EFSA re-evaluation timelines, and FSSAI approval queue lengths served as industry-specific forecast inputs alongside substitution elasticity estimates for digital printing technologies.
Material uncertainties — EFSA residual aluminum threshold determinations, FDA pending substrate approvals, and bauxite supply disruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory grandfathering windows and reformulation investment cycles. Practitioners should keep alternative scenarios live as EFSA opinion publication schedules and FSSAI procedural reforms evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Dyestuff (Black Color) Market
Dyes and Pigments
Ponceau 4R Colors Market
Dyes and Pigments
Quinacridone Pigments Market
Dyes and Pigments
France Aluminium Pigments Market
Dyes and Pigments
Inorganic Pigments Market
Dyes and Pigments
Iron Oxide Pigments Market
Dyes and Pigments
Photoluminescent Paints Market
Dyes and Pigments
Chemochromic Material Market
Dyes and Pigments
Europe Natural Dyes and Pigments Market
Dyes and Pigments
Color Retention Agents Market
Dyes and Pigments
Global Cosmetic Pigments Market
Dyes and Pigments
Phosphorescent Pigments Market
Dyes and Pigments
Carmine Market
Dyes and Pigments
Titanium Dioxide Color Market
Dyes and Pigments
Europe Pigments Market
Dyes and Pigments
Basic Violet 10 Market