
 Acid Dyes Market | 2026-2036
Acid Dyes Market Size, Share, and Industry Trends Forecast 2026-2036
Acid Dyes Market Analysis
EU REACH restrictions on hazardous azo compounds is expanding the addressable market for compliant acid dye formulations. Huntsman Corporation leverages its specialty chemicals portfolio to supply low-COD dye systems for European textile mills. Lanxess AG anchors its position through backward integration into dye intermediate production, securing cost advantages in premium grades. DyStar Holding GmbH specializes in bluesign-certified chemistries, competing on sustainability credentials with global apparel brands.
Acid dyes are water-soluble anionic colorants typically synthesized from azo, anthraquinone, or triphenylmethane chromophores, designed to bond with protein fibers such as wool, silk, and nylon through ionic attraction under acidic pH conditions. Industrial dye grades currently dominate volume sales, though premium-grade formulations are capturing margin pools as mills face stricter effluent limits. Textile industry applications lead absolute consumption, while leather industry demand is accelerating fastest in South American and South Asian tannery clusters.
EPA effluent guidelines in the United States, REACH in Europe, and China's MEE discharge standards collectively raise compliance costs for dye users and reshape supplier qualification criteria. ISO 14001 environmental management certification has become a de facto market access requirement for acid dye vendors serving multinational textile brands. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions, as these intersect with water-repellent textile finishes that often share supply chain channels with acid dye formulations.
Market Dynamics
REACH compliance deadlines in Europe and China's MEE discharge standards are compressing formulation timelines for acid dye manufacturers, forcing simultaneous retooling of chemistries and wastewater systems.
Growth Catalysts
- Protein fiber processing expansion:Wool and silk textile clusters in India and Bangladesh are scaling certified dye procurement to meet export brand requirements.
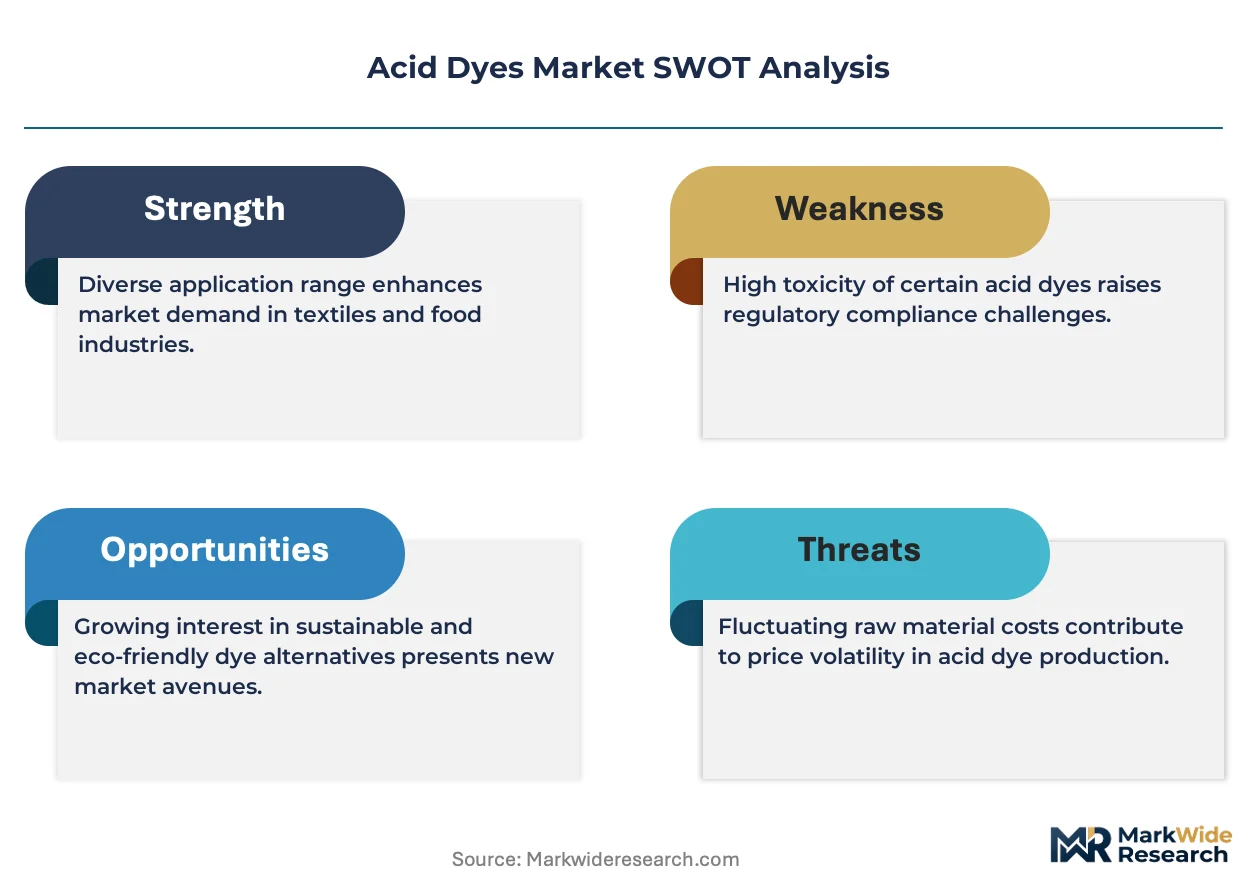
- REACH azo compound restrictions:The European regulation is eliminating non-compliant formulations and redirecting volume toward low-impact alternatives.
- Leather tannery modernization:South American facilities in Brazil and Argentina are adopting acid dye systems for premium hide finishing.
Market Restraints
- Intermediate supply concentration:Anthraquinone and triphenylmethane precursor production clusters in eastern China create geographic vulnerability for non-integrated dye houses.
- Substitution by reactive dyes:Cellulosic fiber processors are migrating to reactive chemistries where protein-synthetic blends permit formulation flexibility.
- COD treatment cost inflation:MEE-mandated effluent standards in China are raising operational expenditure for mills without captive tertiary treatment.
Strategic Opportunities
- Bluesign certification penetration:The Swiss textile safety standard is opening premium positioning for compliant acid dye suppliers in European apparel supply chains.
- Digital textile printing convergence:Inkjet acid dye formulations are capturing niche volume in short-run silk and nylon customization.
- ISO 14001 as market access tool:Environmental management certification is becoming a de facto qualifier for multinational brand supplier lists.
Industry Challenges
- Formulation chemist scarcity:Expertise in low-COD acid dye synthesis is concentrating among legacy European and Japanese technical centers.
- Legacy equipment retrofit timelines:South Asian mills face extended downtime for pH control and effluent system upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acid Dyes Market |
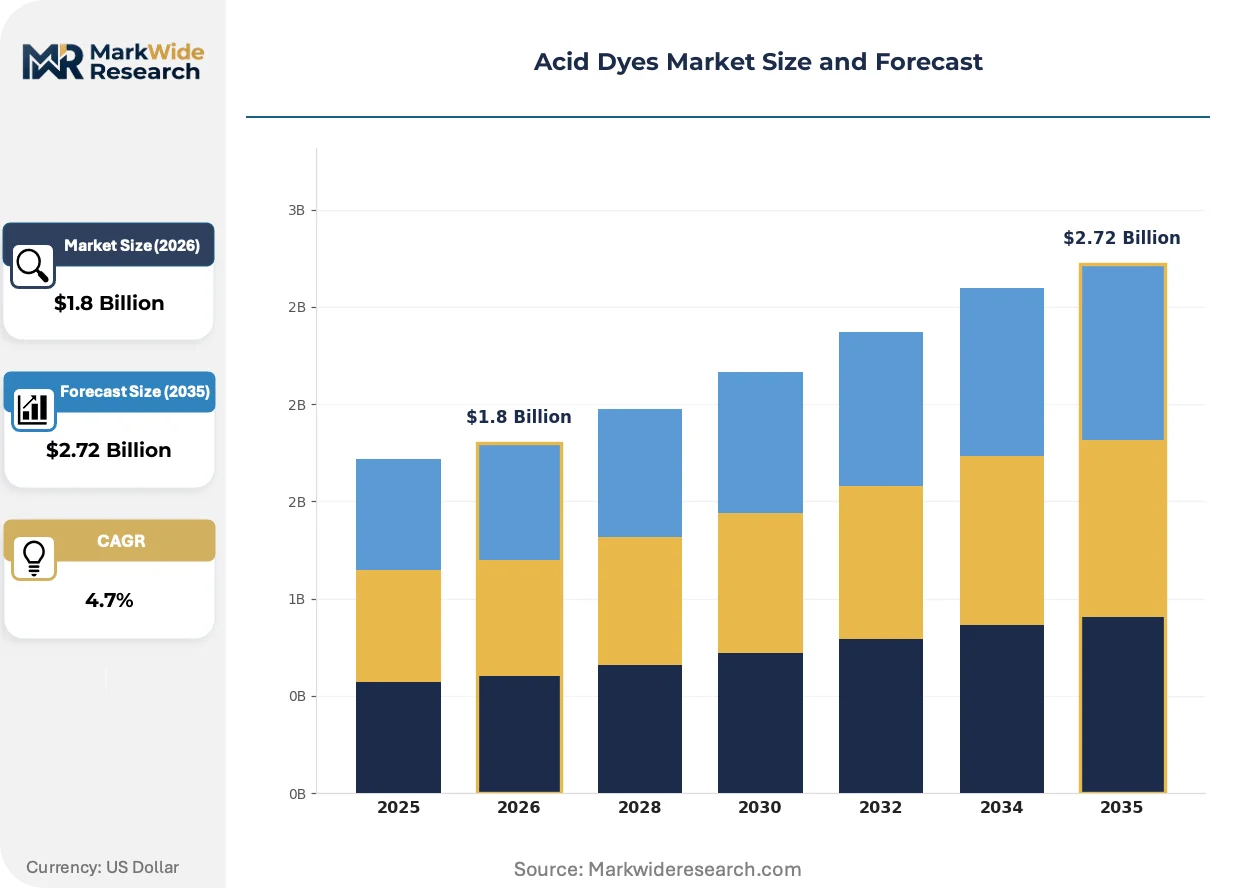
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
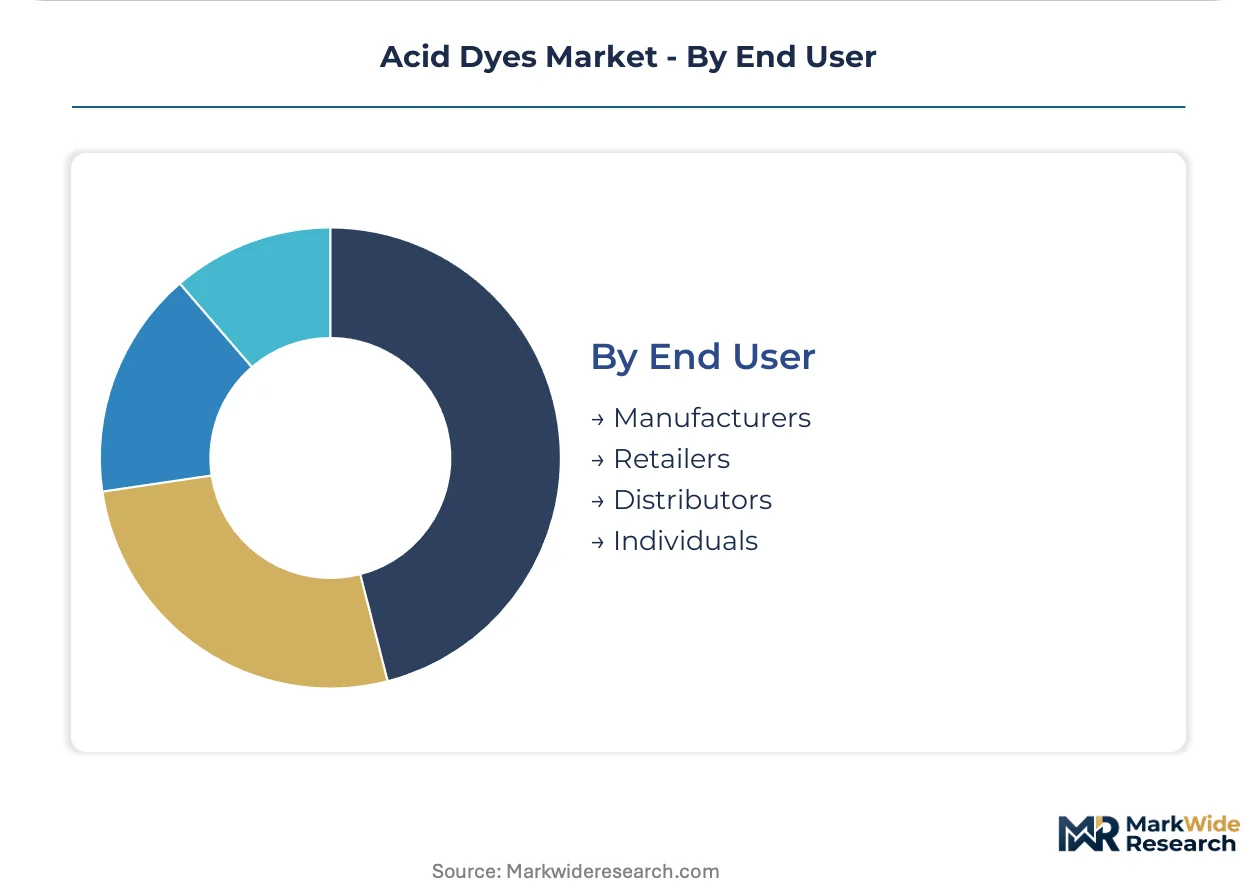
| Segmentation | Product Type: Food Dyes, Industrial Dyes, Textile Dyes, Cosmetic Dyes Grade: Premium, Standard, Economy, Custom Application: Textile Industry, Leather Industry, Paper Industry, Paints & Coatings End User: Manufacturers, Retailers, Distributors, Individuals |
| Companies Covered | Huntsman Corporation, Lanxess AG, Clariant AG, DIC Corporation, Atul Ltd., BASF SE, DyStar Holding GmbH, CHT Group, Archroma Operations LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acid Dyes Market Emerging Trajectories
Acid dye markets are experiencing simultaneous pressure from regulatory chemistry restrictions and digital production methods, compressing traditional formulation-development cycles.
Low-COD acid dye systems are consolidating technical preference among European textile mills facing REACH enforcement and wastewater cost pressures. Mills in Italy and Portugal are adopting these formulations fastest, replacing legacy high-salt chemistries. The shift is consolidating supplier relationships around vendors with captive intermediate production and certified environmental credentials.
China's MEE discharge standards are tightening effluent limits for dye houses in Zhejiang and Jiangsu provinces. The regulation is forcing capital deployment into tertiary treatment or contract processing arrangements. Small and mid-scale acid dye users without scale economics are consolidating into shared effluent facilities or exiting protein fiber segments entirely.
Certification-driven supplier qualification is reshaping procurement patterns for multinational apparel brands. Bluesign and OEKO-TEX certifications are displacing price-only sourcing in European and North American buying offices. The shift is most visible in silk and wool supply chains where brand sustainability commitments face consumer and regulatory scrutiny.
Acid Dyes Market Segmentation
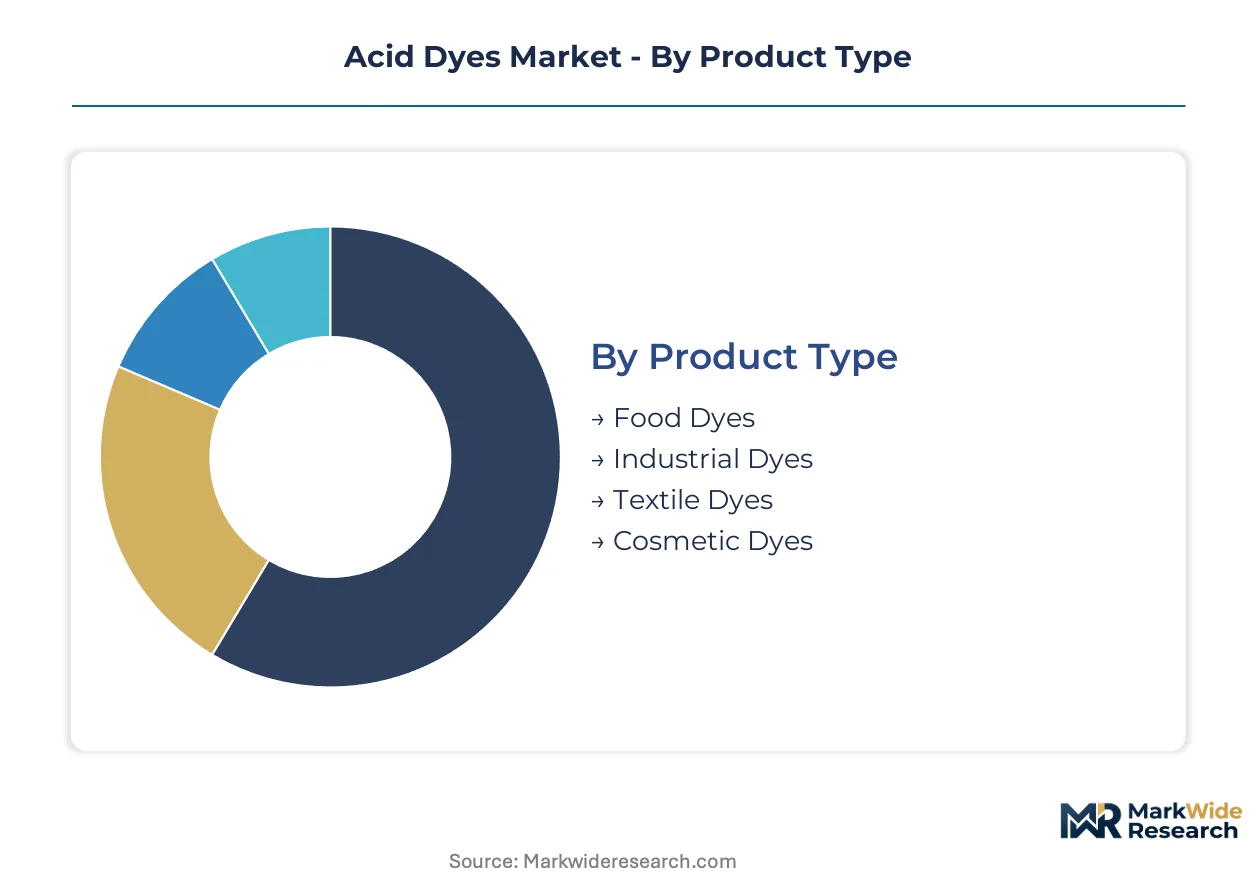
Acid dye procurement patterns diverge sharply across product tiers and end-use specifications, with REACH compliance and MEE discharge standards forcing mills to requalify suppliers by grade and certification level. Mills in Italy, Portugal, and Gujarat are consolidating purchases around fewer, higher-grade formulations to reduce effluent treatment burden.
Product Type:
Upgrade cycles vary by regulatory exposure—food and cosmetic processors face the shortest requalification timelines due to direct consumer contact regulations, while industrial users prioritize cost stability over formulation turnover.
- Food Dyes:These acid dye formulations must meet FDA, EFSA, and FSSAI direct food contact standards with strict purity specifications for heavy metals and aromatic amines. Demand concentrates in confectionery and beverage manufacturing clusters in Switzerland and India, where export certification requirements drive premium grade procurement.
- Industrial Dyes:High-volume formulations for non-consumer applications emphasize batch consistency and bulk pricing over certification tiers. Leather tanneries in Brazil and Argentina are expanding procurement of industrial-grade acid dyes for hide finishing operations.
- Textile Dyes:Protein fiber mills in Italy and Bangladesh drive specification intensity here, with bluesign and OEKO-TEX certification becoming baseline requirements for supplier qualification.
- Cosmetic Dyes:Formulations for personal care applications face EU Cosmetics Regulation and FDA color additive rules with stringent toxicological documentation.
Volume placements concentrate in Industrial Dyes; the faster expansion belongs to Food Dyes.
Grade:
Cost tier stratification reflects the capital intensity of effluent compliance—premium grades absorb tertiary treatment costs upstream, while economy grades push liability downstream to mills without captive processing.
- Premium:Low-COD, low-salt formulations with full bluesign and ISO 14001 documentation. European textile mills facing REACH enforcement are consolidating procurement around these grades to avoid wastewater cost inflation.
- Standard:Mid-tier formulations balancing certification coverage with unit economics. Mills in Portugal and Turkey are the primary volume buyers, upgrading from economy grades as brand sustainability requirements tighten.
- Economy:Basic industrial specifications without environmental certification. Demand is retreating to captive tannery operations in South America and small-scale processors in South Asia lacking export market exposure.
- Custom:Bespoke formulations for specific fiber blends or proprietary color matching. Italian luxury textile houses and Japanese silk processors drive specification complexity here.
Procurement is shifting toward Premium grades in European supply chains; Custom formulations are gaining share fastest in Japanese technical textile segments.
Application:
End-use concentration determines formulation priorities—protein fiber processing demands ionic bonding optimization, while leather applications emphasize lightfastness and rub resistance.
- Textile Industry:Wool and silk processing in Italy, Portugal, and India represents the core volume application, with mills adopting low-COD acid dye systems to meet brand sustainability requirements.
- Leather Industry:Premium hide finishing in Brazilian and Argentine tanneries is accelerating fastest, with acid dyes displacing metal-complex alternatives for environmental compliance.
- Paper Industry:Specialty packaging and decorative applications require acid dyes for precise color control on coated stocks.
- Paints & Coatings:Niche industrial colorant use for specialty coatings where solvent solubility and lightfastness specifications align with acid dye properties.
Absolute consumption remains with Textile Industry; Leather Industry is climbing the fastest as South American tanneries modernize.
End User:
Customer type shapes purchasing behavior—manufacturers demand technical service integration, while distributors prioritize inventory breadth and logistics reliability.
- Manufacturers:Textile mills and tanneries with captive dyeing operations drive formulation customization and direct supplier relationships.
- Distributors:Regional chemical distributors serve mid-scale processors lacking technical procurement capabilities, particularly in South Asian markets.
- Retailers:Direct procurement by large apparel retailers with private label manufacturing is emerging in European sustainability-focused supply chains.
- Individuals:Artisan and small-batch users represent minimal volume but high margin specialty formulations.
Transaction volume concentrates with Manufacturers; Retailer direct procurement is expanding most quickly as brands internalize dye supply chain accountability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Surat and Ahmedabad anchor acid dye procurement in India, where export-oriented textile clusters drive volume uptake of certified formulations for wool and silk processing operations.
India
Wool and silk mills in Surat and Tiruppur scale procurement of bluesign-certified acid dyes to meet European apparel brand requirements. FSSAI regulations on food-grade colorant purity create parallel demand streams for confectionery applications. Gujarat's chemical manufacturing corridor concentrates domestic acid dye production capacity.
China
Zhejiang and Jiangsu province dye houses face MEE discharge standard enforcement that compresses formulation timelines and raises tertiary treatment costs. The dual carbon goals accelerate exit of small-scale producers lacking captive effluent infrastructure. Shaoxing's textile cluster consolidates procurement around fewer compliant suppliers.
Italy
Biella and Prato wool processing districts adopt low-COD acid dye systems fastest among European mills. REACH azo compound restrictions eliminate non-compliant formulations and redirect volume toward certified alternatives. Lombardy's silk finishing houses drive specification intensity for premium-grade chemistries.
Brazil
São Paulo and Rio Grande do Sul tannery clusters modernize hide finishing operations with acid dye systems displacing metal-complex alternatives. ANVISA cosmetic colorant rules create secondary demand from personal care manufacturers. The southern leather corridor represents the fastest-growing regional application segment.
Germany
Leverkusen and Ludwigshafen chemical complexes anchor backward-integrated acid dye production serving European textile mills. ECHA REACH enforcement tightens supplier qualification criteria beyond azo restrictions to encompass broader hazardous substance categories. Baden-Württemberg's technical textile sector drives custom formulation complexity.
Acid Dyes Market Vendor Landscape
The competitive structure tilts toward specialty chemical conglomerates with captive intermediate production. Three to five integrated multinationals command premium-grade supply relationships with certified European mills, while regional formulators serve price-sensitive South Asian volume segments. Strategic archetypes separate into backward-integrated intermediate producers, sustainability-certified specialists, and regional distributors with formulation service capabilities. Dominant competitive moves center on certification portfolio expansion and geographic consolidation of effluent-compliant manufacturing assets.
Among Germany-based chemical conglomerates, Lanxess AG and BASF SE occupy positions anchored by upstream dye intermediate production, while DyStar Holding GmbH exemplifies the sustainability-certified specialist archetype competing on bluesign credentials. Huntsman Corporation represents the integrated multinational model with specialty chemicals portfolio breadth. These three players illustrate how competitive positioning stratifies across certification tiers rather than product specifications alone.
| Leading Market Players |
|---|
| Huntsman Corporation |
| Lanxess AG |
| Clariant AG |
| DIC Corporation |
| Atul Ltd. |
| BASF SE |
| DyStar Holding GmbH |
| CHT Group |
| Archroma Operations LLC |
| Others |
Supply Flow & Price Mechanics
Bluesign-certified procurement mandates from European apparel brands are compressing supplier margins and forcing dye houses to absorb certification costs or exit premium supply chains entirely. This demand-side specification tightening concentrates purchasing power among backward-integrated manufacturers with captive intermediate production.
Pricing Analysis
Yield-per-bath performance anchors value-based pricing for acid dye formulations, with mills paying premiums for chemistries that reduce water and energy consumption per kilogram of fiber processed. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification depth and effluent treatment burden absorbed upstream. Cost compression in economy grades is intensifying because small South Asian mills lack scale to distribute fixed compliance costs. Price-sensitive buyers cluster in industrial tannery segments, while luxury textile houses show lowest sensitivity to unit price.
Supply Chain Analysis
Single-source vulnerability sits with anthraquinone and triphenylmethane intermediate production concentrated in eastern China's Zhejiang and Jiangsu provinces. Dye synthesis draws from petrochemical feedstocks, naphthalene derivatives, and sulfuric acid reagents sourced through regional chemical corridors. Tariff exposure on Chinese intermediates threatens margin stability for European formulators lacking captive supply. Distribution runs through regional chemical distributors serving mid-scale processors, with direct supplier relationships dominating certified-grade procurement by multinational textile brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Acid dye markets are consolidating around integrated producers with captive intermediate supply and certification portfolios. REACH enforcement and China's MEE discharge standards are accelerating exit of non-compliant regional formulators.
For Market Incumbents: Anticipate reactive dye substitution threats in protein-synthetic blend segments by deepening formulation service relationships with Italian and Portuguese wool mills. Backward integration into dye intermediate production in Germany or India secures cost advantages as Chinese supply faces regulatory compression. Prioritize bluesign certification portfolio expansion to defend premium positioning against sustainability-focused competitors. For New Entrants and Emerging Players: Capture white-space opportunity in digital textile printing inkjet formulations for short-run silk and nylon customization, where technical barriers remain lower than conventional dye manufacturing. Brazilian leather tannery modernization offers the most penetrable geographic entry point for industrial-grade acid dye supply. Pursue go-to-market partnerships with regional distributors in South Asia lacking technical service capabilities for certified-grade formulations. For Investors and Strategic Acquirers: The window for entry favors sustainability-certified specialists with bluesign credentials and ISO 14001 documentation. Long-term viability rests on regulatory compliance infrastructure rather than commodity scale. Target acquisition archetypes include mid-scale European formulators with stranded intermediate supply contracts and established brand relationships. Monitor ECHA enforcement actions against hazardous azo compounds as the inflection signal for accelerated market consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dye Intermediates | Lanxess AG and BASF SE secure cost advantages through captive anthraquinone production in German chemical complexes. |
| Bluesign Certification Expansion | DyStar Holding GmbH competes on sustainability credentials with global apparel brands requiring supply chain transparency. |
| Digital Textile Printing Formulation Development | Inkjet acid dye systems capture niche volume in Italian luxury silk customization and Japanese technical textile segments. |
| Shared Effluent Facility Partnerships | Small South Asian mills consolidate into cooperative treatment infrastructure to meet MEE discharge standards without capital burden. |
| Long-term Supply Agreements with Tannery Clusters | Brazilian leather processors in São Paulo and Rio Grande do Sul modernize hide finishing with acid dye systems displacing metal-complex alternatives. |
Methodological Framework
Multi-period observation of REACH compliance timelines, MEE discharge standard enforcement, and certification adoption rates anchored the trend analysis, supplemented by interviews with dye house plant managers, textile procurement leads at European apparel brands, chemical distribution channel partners, and leather tannery technical directors. Secondary validation drew from ECHA regulatory filings, China MEE discharge data, customs trade records, and SEC 10-K disclosures from listed chemical conglomerates. Bottom-up volume estimates from end-use segments triangulated against top-down production capacity assessments.
Input-output matrices mapped dye intermediate supply through formulation to end-use consumption across grade tiers, application segments, and geographic production clusters. Segmentation dimensions modeled include product type, certification grade, end-use industry, and regional regulatory framework. CAGRs were derived from regression analysis of historical procurement patterns projected against regulatory compliance deadlines and brand sustainability commitment timelines. Forecast inputs incorporated textile production capacity expansion in India and Bangladesh, leather tannery modernization rates in Brazil and Argentina, and digital printing adoption curves in European luxury segments.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA expansion of restricted substance lists, China dual carbon policy acceleration, and per- and polyfluoroalkyl substance restrictions intersecting with water-repellent textile finishes. Forecasts reflect documented assumptions about regulatory enforcement intensity and brand procurement policy stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Carmoisine Market
Dyes and Pigments
Global Thermochromic Materials Market
Dyes and Pigments
Acid Violet 43 Market
Dyes and Pigments
Phosphorescent Pigments Market
Dyes and Pigments
Europe Hair Colorants Market
Dyes and Pigments
Laser Sensitive Pigments Market
Dyes and Pigments
Color Concentrates Market
Dyes and Pigments
Organic Pigment Dispersions Market
Dyes and Pigments
South America Hair Colorants Market
Dyes and Pigments
France Aluminium Pigments Market
Dyes and Pigments
Erythrosine Market
Dyes and Pigments
Hair Colorants Market
Dyes and Pigments
North America Hair Colorants Market
Dyes and Pigments
Global Architectural Paint Oxide Market
Dyes and Pigments
Cacao Husk Pigment Market
Dyes and Pigments
Complex Inorganic Color Pigments Market