
 Asia Pacific Hair Colorants Market | 2026-2036
Asia Pacific Hair Colorants Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Hair Colorants Market Outlook
Software-defined color-matching services embedded in salon booking platforms is restructuring how professional hair colorants move through the Asia Pacific channel. L'Oréal S.A. leverages its ModiFace augmented-reality tools to anchor digital consultation workflows in Chinese and Japanese salons. Henkel AG & Co. KGaA competes through Schwarzkopf's professional education academies that sustain stylist loyalty across Southeast Asia. Kao Corporation differentiates via Liese's at-home foam technology, which dominates Japan's retail colorant segment.
Asia Pacific hair colorants comprise oxidative and non-oxidative formulations that deposit or lift pigment through alkaline developers, direct dyes, or acid-based conditioners, typically requiring pH balancing between 8.5 and 10.5 for permanent lift applications. These products serve cosmetic pigmentation needs across consumer and professional segments, with formulation chemistry determining color longevity, gray coverage, and fiber integrity. Permanent colorants command the largest volume share due to graying demographics across Japan and South Korea, though semi-permanent formulations show the fastest trajectory as younger consumers prioritize tonal experimentation over commitment. Cream formulations retain margin concentration in professional channels where mixing precision matters, while powder variants gain traction in India's value-oriented salon tier.
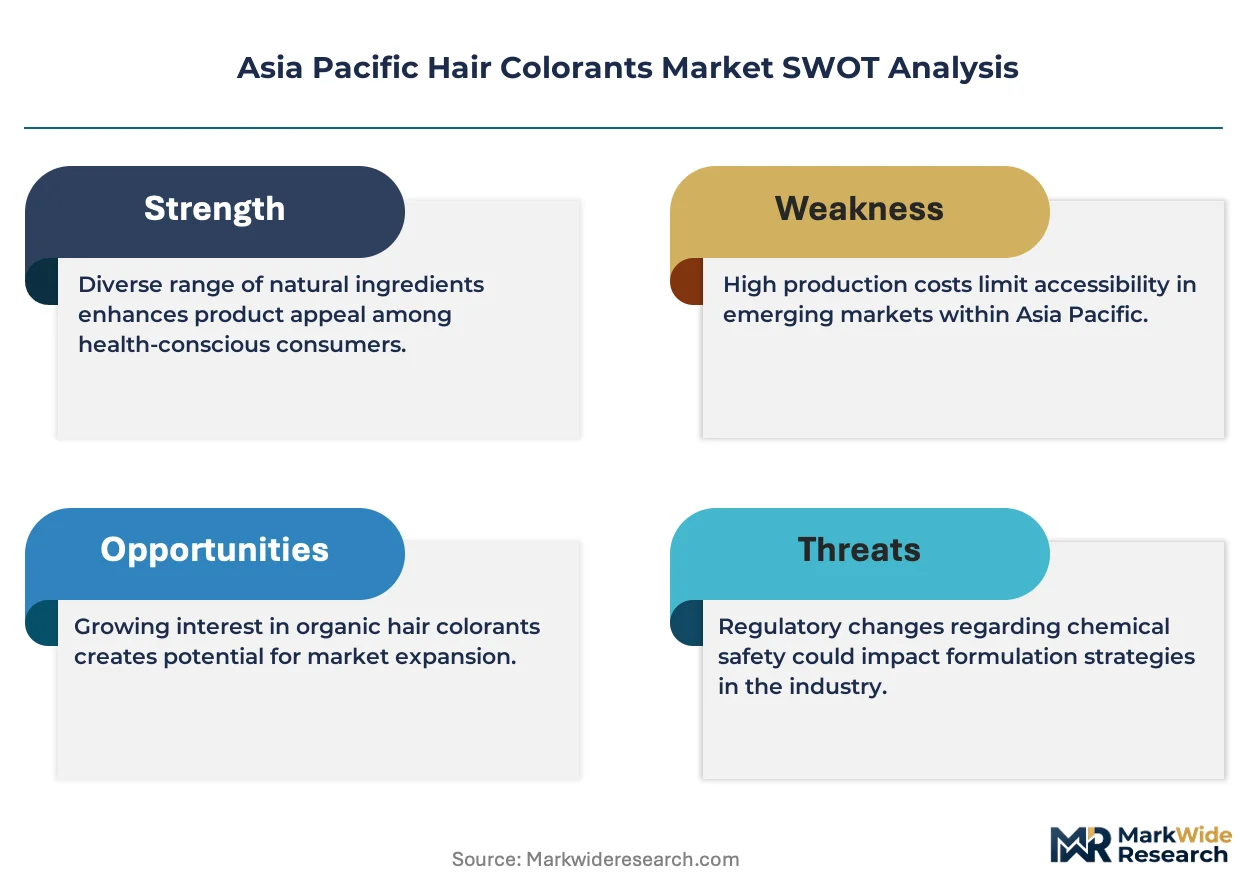
Japan's Ministry of Health, Labour and Welfare classifies certain hair colorants as quasi-drugs, requiring pre-market notification and active-ingredient disclosure that elevates compliance costs for new entrants. India's BIS cosmetic standards and China's NMPA registration pathway for imported colorants together create a fragmented regulatory landscape where multi-country dossier preparation becomes a core capability. Australia's TGA and South Korea's MFDS add further variation in allergen labeling and PPD concentration limits. Stakeholders must monitor regulatory divergence between ASEAN harmonization efforts and country-specific chemical restrictions when allocating R&D and registration budgets.
Market Dynamics
Software-defined color-matching services embedded in salon booking platforms is restructuring how professional hair colorants move through the Asia Pacific channel, compressing traditional distributor margins while elevating formulation houses with digital integration capabilities.
Growth Catalysts
- Graying demographics:Permanent colorant demand accelerates across Japan and South Korea as median population age climbs, sustaining volume in salon-grade oxidative formulations.
- BIS cosmetic safety standards:India's regulatory harmonization with ASEAN cosmetic directives reduces registration duplication costs for multi-country dossier holders.
- Foam technology adoption:At-home application formats expand addressable consumer base beyond professional channel dependency in urban China and Southeast Asia.
Market Restraints
- PPD concentration limits:South Korea's MFDS and Australia's TGA impose stricter para-phenylenediamide thresholds than ASEAN baseline, fragmenting formulation portfolios.
- Quasi-drug compliance costs:Japan's MHLW pre-market notification requirements elevate R&D spend for new active ingredients versus standard cosmetic pathways.
- Professional channel concentration:Tier-one Chinese cities account for disproportionate volume, exposing suppliers to localized demand shocks.
Strategic Opportunities
- Tier-two China penetration:Professional channel infrastructure deepens in Chengdu, Hangzhou, and Xi'an as salon chains expand beyond Beijing-Shanghai-Guangzhou corridor.
- Education academy models:Stylist certification programs build captive demand for proprietary colorant systems across Indonesia and Vietnam.
- Dual carbon alignment:China's MEE low-carbon manufacturing incentives favor waterless powder formulation investments with reduced processing emissions.
Industry Challenges
- Formulation chemist scarcity:Qualified colorant chemists with quasi-drug dossier experience command premium compensation in Tokyo and Osaka markets.
- Multi-regulatory registration timelines:Parallel NMPA, MFDS, and BIS approval pathways extend product launch windows by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Hair Colorants Market |
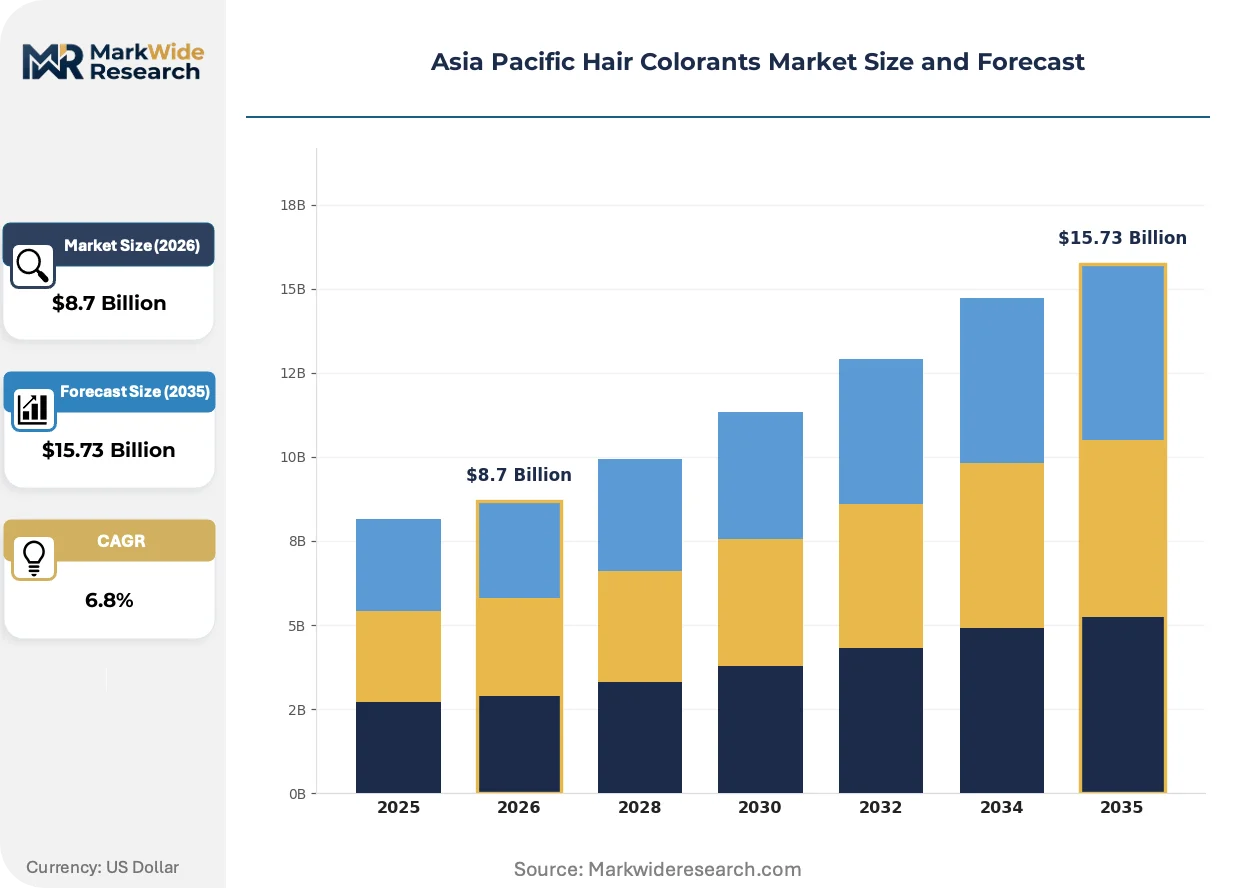
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Permanent, Semi-Permanent, Temporary, Demipermanent Formulation: Cream, Gel, Liquid, Powder Application: Salon, At-Home, Professional, Retail Consumer Gender: Female, Male, Unisex, Others |
| Companies Covered | L'Oréal S.A., Henkel AG & Co. KGaA, Kao Corporation, Procter & Gamble Co., Shiseido Co. Ltd, Godrej Consumer Products Limited, Coty Inc., Hoyu Co., Ltd., Mandom Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Hair Colorants Market Strategic Shifts
Digital consultation workflows are compressing the traditional colorant selection process while elevating precision expectations among professional stylists and at-home consumers alike.
Augmented-retry color visualization is electrifying pre-purchase decision-making in Chinese and Japanese salons. ModiFace-powered tools embedded in WeChat mini-programs let clients preview tonal outcomes before chemical application. This capability is compressing return-visit rates and elevating formulation accuracy requirements for salon-grade suppliers.
Japan's quasi-drug classification system is tightening active-ingredient disclosure standards for oxidative colorants. The MHLW notification pathway now demands full pigment stability data that smaller importers struggle to compile. Professional brands with established regulatory affairs teams in Tokyo are consolidating share as compliance costs rise.
Younger consumers across South Korea and urban China are compressing color commitment cycles, treating semi-permanent application as seasonal fashion rather than maintenance necessity. Direct-to-consumer foam kits and salon-grade gloss services are displacing permanent coverage as the default entry point for new colorant users in Seoul and Shanghai.
Asia Pacific Hair Colorants Market Segmentation
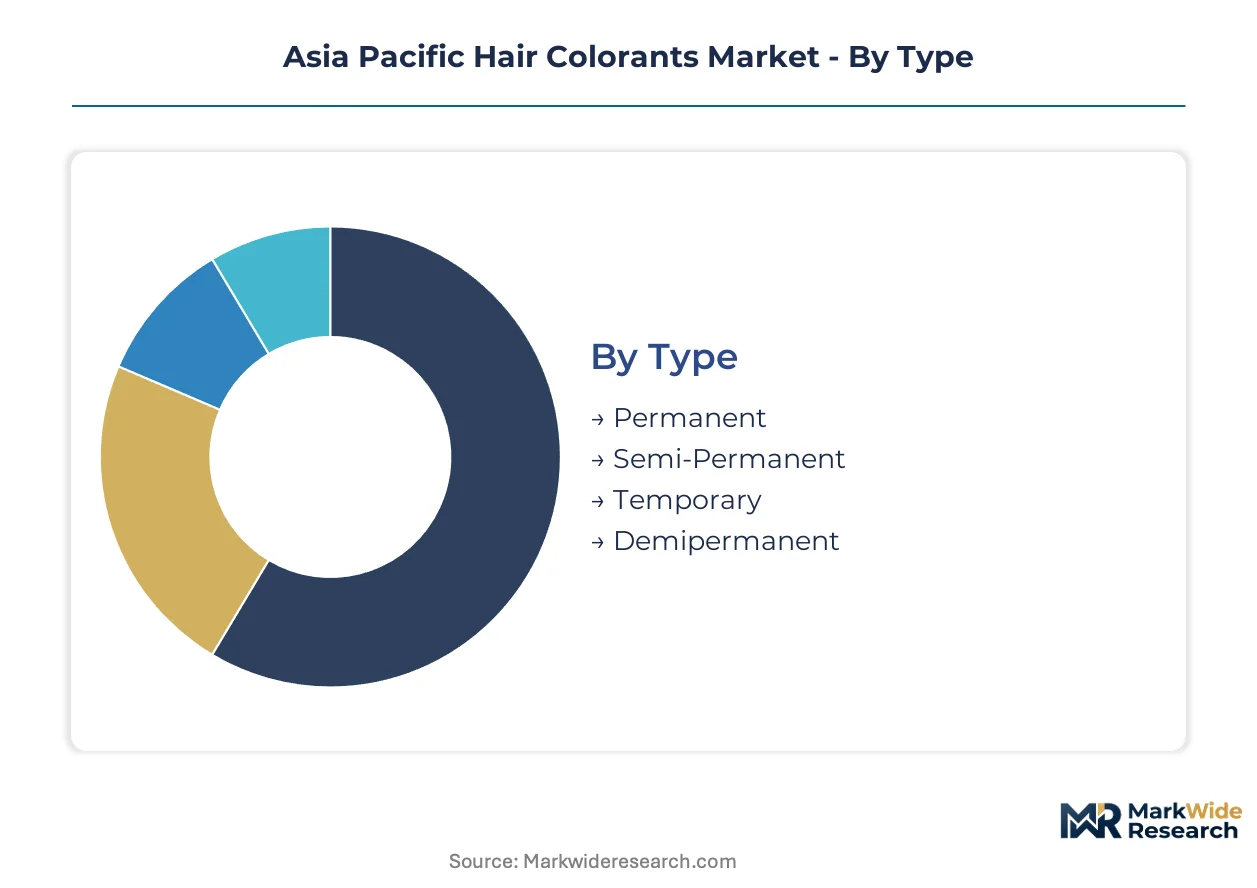
Hair colorant purchasing in Asia Pacific splits across commitment level, application setting, and formulation chemistry, with each axis carrying distinct margin profiles and regulatory obligations. Buyers trade permanence against fiber damage, salon precision against at-home convenience, and cream stability against powder cost efficiency.
Type:
Commitment duration drives formulation chemistry selection and repurchase frequency across the region's aging and youth demographics.
- Permanent:Oxidative formulations with alkaline developers lift natural pigment and deposit synthetic dyes for complete gray coverage. Japan and South Korea sustain concentrated demand as median age climbs, with salon-grade oxidative systems commanding premium positioning in Tokyo and Osaka.
- Semi-Permanent:Direct dye formulations without ammonia or peroxide deposit color on the cuticle layer for 4-12 week longevity. Seoul's younger consumers treat tonal shifts as seasonal fashion, compressing color commitment cycles and elevating gloss-service frequency in Gangnam district salons.
- Temporary:Acidic conditioners and spray pigments coat the hair shaft for single-wash results, serving festival and entertainment industry demand in Bangkok and Mumbai.
- Demipermanent:Low-volume developer formulations with alkaline pH below permanent thresholds offer intermediate longevity for gray blending applications across Southeast Asia's professional channel.
Volume sits with Permanent; growth tilts toward Semi-Permanent.
Formulation:
Physical state determines mixing precision requirements, shelf stability, and manufacturing capital intensity across professional and retail channels.
- Cream:Viscous emulsions with controlled rheology enable precise developer ratios and consistent oxidative reaction kinetics. Professional salons in Shanghai and Beijing specify cream bases for complex multi-tone applications where batch consistency determines client retention.
- Powder:Anhydrous particulate systems reduce shipping weight and water content, aligning with China's MEE low-carbon manufacturing incentives. India's value-oriented salon tier adopts powder for cost-efficient bulk dispensing in Mumbai and Delhi chains.
- Gel:Thixotropic systems with polymer suspensions cling to hair during processing, reducing drip concerns for at-home consumers in Jakarta and Manila.
- Liquid:Low-viscosity solutions enable spray application and rapid saturation, serving temporary color and root-touchup segments in Australia's retail channel.
Cream captures professional margin concentration; powder climbs the fastest on sustainability-linked procurement.
Application:
Channel selection determines service bundling, regulatory pathway, and stylist education requirements across the region's fragmented distribution landscape.
- Salon:Licensed professional application with customized formulation mixing and post-color treatment protocols. Tier-one Chinese cities concentrate volume where digital consultation tools compress color-matching error rates and elevate repeat booking frequency.
- At-Home:Consumer-directed application with pre-calibrated developer systems and instructional packaging. Kao's Liese foam technology dominates Japan's retail segment by reducing application complexity for first-time users.
- Professional:Salon-exclusive product lines with stylist certification requirements and proprietary color systems. Schwarzkopf education academies in Indonesia and Vietnam build captive demand through credential-linked product access.
- Retail:Mass-market distribution through hypermarkets, drugstores, and e-commerce platforms with standardized shade ranges. India's BIS cosmetic safety standards shape formulation disclosure requirements for domestic and imported SKUs.
Salon channel holds volume leadership; at-home formats gain share fastest on foam technology adoption.
Consumer Gender:
Target demographic shapes shade portfolio breadth, marketing spend allocation, and packaging design conventions across Asia Pacific's diverse cultural markets.
- Female:Comprehensive shade ranges from natural coverage to fashion tones with conditioning additives and damage-repair positioning. South Korea's female consumers drive semi-permanent experimentation frequency above regional averages.
- Male:Simplified application systems with natural shade focus and gray-targeted marketing, expanding fastest in China's urban professional segment where male grooming normalization accelerates.
- Unisex:Neutral packaging and universal shade positioning serving shared household purchasing and non-binary consumer preferences in Australia's metropolitan markets.
- Others:Specialized formulations for pediatric, medical, or theatrical applications with modified safety profiles and regulatory considerations.
Female segment anchors current volume; male-targeted offerings represent the steepest expansion trajectory on grooming category maturation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity concentrates in Japan and South Korea, while consumption scales fastest in China's urban corridors and India's metropolitan belts. This production-consumption asymmetry shapes cross-border formulation trade and regulatory dossier complexity.
China
Beijing, Shanghai, and Guangzhou dominate professional channel volume where salon chains deploy digital color-matching tools. NMPA registration requirements for imported colorants extend product launch timelines. Chengdu and Hangzhou emerge as tier-two growth poles as stylist education infrastructure deepens.
Japan
Tokyo and Osaka sustain concentrated demand for salon-grade oxidative formulations among aging demographics. MHLW quasi-drug classification elevates compliance costs for new active ingredients. Kanto region suppliers consolidate share through established regulatory affairs capabilities.
India
Mumbai and Delhi anchor value-oriented salon demand where powder formulations gain traction in chain operations. BIS cosmetic safety standards harmonize with ASEAN directives, reducing multi-country registration duplication. Maharashtra's manufacturing corridor supplies domestic and export markets.
South Korea
Seoul's Gangnam district drives semi-permanent experimentation frequency among younger consumers. MFDS imposes stricter PPD concentration limits than regional baselines, fragmenting formulation portfolios. Busan-Ulsan corridor hosts contract manufacturing for regional brands.
Australia
Sydney and Melbourne concentrate retail channel volume for at-home application formats. TGA allergen labeling requirements exceed ASEAN standards, necessitating market-specific packaging. Professional salon penetration remains shallow relative to Northeast Asian benchmarks.
Asia Pacific Hair Colorants Market Competitive Environment
Top-tier vendors anchor premium salon-grade formulations, while mid-tier specialists compete on at-home convenience and value-oriented professional supply. The vendor base stratifies across three archetypes: multinational beauty conglomerates with digital integration capabilities, regional formulation houses with regulatory dossier expertise, and domestic challengers leveraging local distribution density. Consolidation pressures intensify as compliance costs rise and professional channel digitization accelerates. Capacity expansion and strategic technology licensing represent the dominant competitive vectors.
Among multinational beauty conglomerates, L'Oréal S.A., Henkel AG & Co. KGaA, and Kao Corporation occupy positions that exemplify divergent strategic archetypes. L'Oréal S.A. represents the digital-first approach through augmented-reality consultation tools embedded in salon workflows. Henkel AG & Co. KGaA anchors the professional education model with stylist certification programs that build captive demand. Kao Corporation exemplifies at-home format innovation through foam technology that reduces application complexity for retail consumers.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| Henkel AG & Co. KGaA |
| Kao Corporation |
| Procter & Gamble Co. |
| Shiseido Co. Ltd |
| Godrej Consumer Products Limited |
| Coty Inc. |
| Hoyu Co., Ltd. |
| Mandom Corporation |
| Others |
Value Chain & Pricing Dynamics
China's MEE low-carbon manufacturing mandates gate qualified supply access and premium-tier pricing power, rewarding waterless powder formulation investments while penalizing high-emission cream production lines that face carbon-adjusted cost penalties.
Pricing Analysis
Margin tightening in India's value-oriented salon tier reflects BIS compliance cost absorption and bulk powder procurement scale advantages. Three-tier pricing structure across premium salon-grade, standard retail, and economy unbranded segments separates oxidative formulation complexity levels. Cost-down pressure on cream-based professional products accelerates because Kao's Liese foam technology resets at-home convenience benchmarks. Chain salon buyers in tier-two Chinese cities show highest price sensitivity; Tokyo's quasi-drug certified salons demonstrate lowest.
Supply Chain Analysis
Freight cost differentials between anhydrous powder and water-heavy cream formulations reshape sourcing geography for regional brands. Manufacturing concentrates in Japan, South Korea, and China's eastern seaboard, with Maharashtra's corridor serving India's domestic demand. Formulation chemistry draws from para-phenylenediamine, alkaline developers, and direct dye precursors anchored in petrochemical feedstocks. Single-source vulnerability sits with Japanese quasi-drug regulatory dossier expertise concentrated in Tokyo-Osaka. Distribution runs through professional salon chains, e-commerce platforms, and beauty specialty retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as players pursue captive control over quasi-drug regulatory dossier capabilities to compress multi-country launch timelines.
For Market Incumbents: Cement regulatory affairs dominance by acquiring Tokyo-based dossier specialists with MHLW notification experience, countering margin pressure from digital-native entrants embedding AI color-matching in WeChat workflows. Backward integration into active ingredient synthesis reduces PPD supply volatility exposure. For New Entrants and Emerging Players: Capture tier-two Chinese salon expansion in Chengdu, Hangzhou, and Xi'an where professional education infrastructure lags behind digital tool adoption. India's BIS-harmonized ASEAN pathway offers the most penetrable multi-country registration entry point. Lead with waterless powder sustainability positioning aligned to MEE incentives. For Investors and Strategic Acquirers: MFDS tightening of PPD concentration limits is the leading indicator that formulation portfolio fragmentation will favor specialists with multi-regulatory chemist teams. Long-term viability centers on targets with established quasi-drug pathways across Japan and South Korea. Watch for education academy acquisition activity as captive demand generation strategy.| Strategic Initiative | Industry Significance |
|---|---|
| Quasi-Drug Dossier Acquisition | Compresses Japan MHLW notification timelines versus de novo regulatory builds. |
| Waterless Powder Capacity Expansion | Aligns manufacturing footprints with China's MEE carbon intensity reduction mandates. |
| Professional Education Academy Buildout | Creates stylist certification-linked captive demand in Indonesia and Vietnam. |
| Digital Color-Matching Platform Integration | Embeds augmented-reality tools in WeChat salon booking workflows. |
| Tier-Two China Distribution Partnership | Secures shelf presence in Chengdu and Hangzhou ahead of chain salon consolidation. |
Study Parameters
Document review covered NMPA registration filings, BIS cosmetic safety standards, and MHLW quasi-drug notification databases, complemented by interviews with salon chain procurement directors, formulation R&D leads, regulatory affairs specialists, and beauty distributor principals. Secondary validation drew from customs trade records, ACC beauty chemical sector reports, and SEC 10-K segment disclosures. Bottom-up volume builds and top-down demand triangulation anchored market sizing.
Segment-level value outputs trace formulation type, application channel, and consumer commitment duration across the projection horizon, with CAGRs derived from demographic aging curves and foam technology penetration rates. Modeled inputs include graying population trajectories in Japan and South Korea, plus NMPA approval timeline distributions for imported colorants.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ASEAN regulatory harmonization progress and China's dual carbon policy enforcement intensity. Forecasts reflect documented assumptions on professional channel digitization speed and quasi-drug compliance cost trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Color Retention Agents Market
Dyes and Pigments
Bio Based Pigments and Dyes Market
Dyes and Pigments
Iridescent Pigments Market
Dyes and Pigments
Bismuth Vanadate Pigment Market
Dyes and Pigments
Thermochromic Pigments Market
Dyes and Pigments
Titanium Dioxide Pigment Market
Dyes and Pigments
Inorganic Cosmetics Pigments Market
Dyes and Pigments
Chemochromic Material Market
Dyes and Pigments
Carmine Market
Dyes and Pigments
Acid Violet 43 Market
Dyes and Pigments
Europe Hair Colorants Market
Dyes and Pigments
Zinc Oxide Pigments Market
Dyes and Pigments
Indigo Carmine Market
Dyes and Pigments
Asia-Pacific Feed Pigments Market
Dyes and Pigments
Global Thermochromic Materials Market
Dyes and Pigments
Arylamide Pigments Market