
 Inorganic Cosmetics Pigments Market | 2026-2036
Inorganic Cosmetics Pigments Market Size, Share, and Industry Trends Forecast 2026-2036
Inorganic Cosmetics Pigments Market Outlook
Asset-light toll manufacturing and third-party pigment dispersion leasing is reshaping competitive entry barriers for mid-sized cosmetics brands. Sun Chemical leverages captive supply of surface-treated mica to sustain formulation consistency across European color houses. Merck KGaA anchors premium pearlescent portfolios through tight control over multilayer deposition technology. Lanxess competes on iron oxide purity grades that meet pharmaceutical-adjacent specifications for dermal applications.
Inorganic cosmetics pigments encompass metal oxide, silicate, and sulfate-based colorants engineered for particle sizes between 0.1 and 50 microns, delivering UV opacity, color stability, and skin adhesion in decorative formulations. Titanium dioxide dominates volume across sunscreen and foundation matrices where refractive index and photostability matter most. Ultramarines and iron oxides represent faster-growing premium tiers as clean-label brands reject organic azo dyes. Makeup applications command the widest SKU breadth, though skincare absorption is accelerating as tone-correcting serums embed mineral tints directly into treatment protocols.
REACH in Europe and FDA color additive regulations in the United States jointly constrain allowable lead, arsenic, and mercury traces in cosmetic-grade pigments, forcing reformulation cycles and certificate-of-analysis documentation. BIS in India and China's SAMR are tightening parallel standards for imported mineral feedstocks, reshaping supplier qualification timelines. Stakeholders must monitor evolving heavy-metal test methodologies and pre-approval pigment listings across multiple jurisdictions to avoid batch detention at customs.
Market Dynamics
REACH compliance in Europe is compressing impurity thresholds for heavy metals, forcing pigment houses to rebuild supply chains around certified mineral feedstocks and surface-treatment capabilities. This regulatory compression is redrawing competitive moats around analytical testing infrastructure and certificate-of-analysis documentation systems.
Growth Catalysts
- PLI scheme acceleration:India's production-linked incentive framework for specialty chemicals is expanding domestic titanium dioxide processing capacity. Local BIS certification timelines are shortening as a result.
- Clean-label rejection of azo dyes:Decorative cosmetics brands are reformulating with ultramarines and iron oxides to meet consumer preference for mineral-derived colorants. This shift is pulling through premium pigment grades.
- Sunscreen photostability mandates:Regulatory bodies in Australia and South Korea are tightening UV-filter performance standards. Titanium dioxide with optimized particle size distribution is capturing expanded formulation slots.
Market Restraints
- Ilmenite supply concentration:Titanium feedstock processing concentrates in China and Australia, exposing pigment manufacturers to concentrate pricing volatility and shipping disruptions through the Strait of Malacca.
- Surface-treatment capex barriers:Silane and titanate coating lines require dedicated reactor infrastructure. Mid-sized compounders face capital constraints qualifying for cosmetic-grade dispersion contracts.
- Mercury trace testing complexity:Evolving cold-vapor atomic absorption methodologies across FDA and ECHA jurisdictions are extending batch release timelines and raising analytical service costs.
Strategic Opportunities
- Tone-correcting skincare integration:Treatment serums are embedding iron oxide and titanium dioxide tints directly into active formulations. This application is expanding beyond traditional makeup into dermocosmetic protocols.
- Third-party dispersion leasing:Asset-light toll manufacturing models are lowering entry barriers for Southeast Asian color cosmetics brands seeking REACH-compliant pigment preparations without captive milling infrastructure.
- SAMR pre-approval pathways:China's streamlined cosmetic ingredient listing process is accelerating market access for surface-treated mica grades that meet new GB standards for heavy metal content.
Industry Challenges
- Multilayer deposition technician scarcity:Pearlescent pigment manufacturing requires specialized expertise in vapor-phase coating control. Training pipelines for this precision function remain underdeveloped across European and Asian production clusters.
- Certificate-of-analysis reconciliation:Divergent heavy-metal test methodologies between FDA color additive regulations and REACH annexes are forcing pigment houses to maintain parallel analytical workflows, increasing compliance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inorganic Cosmetics Pigments Market |
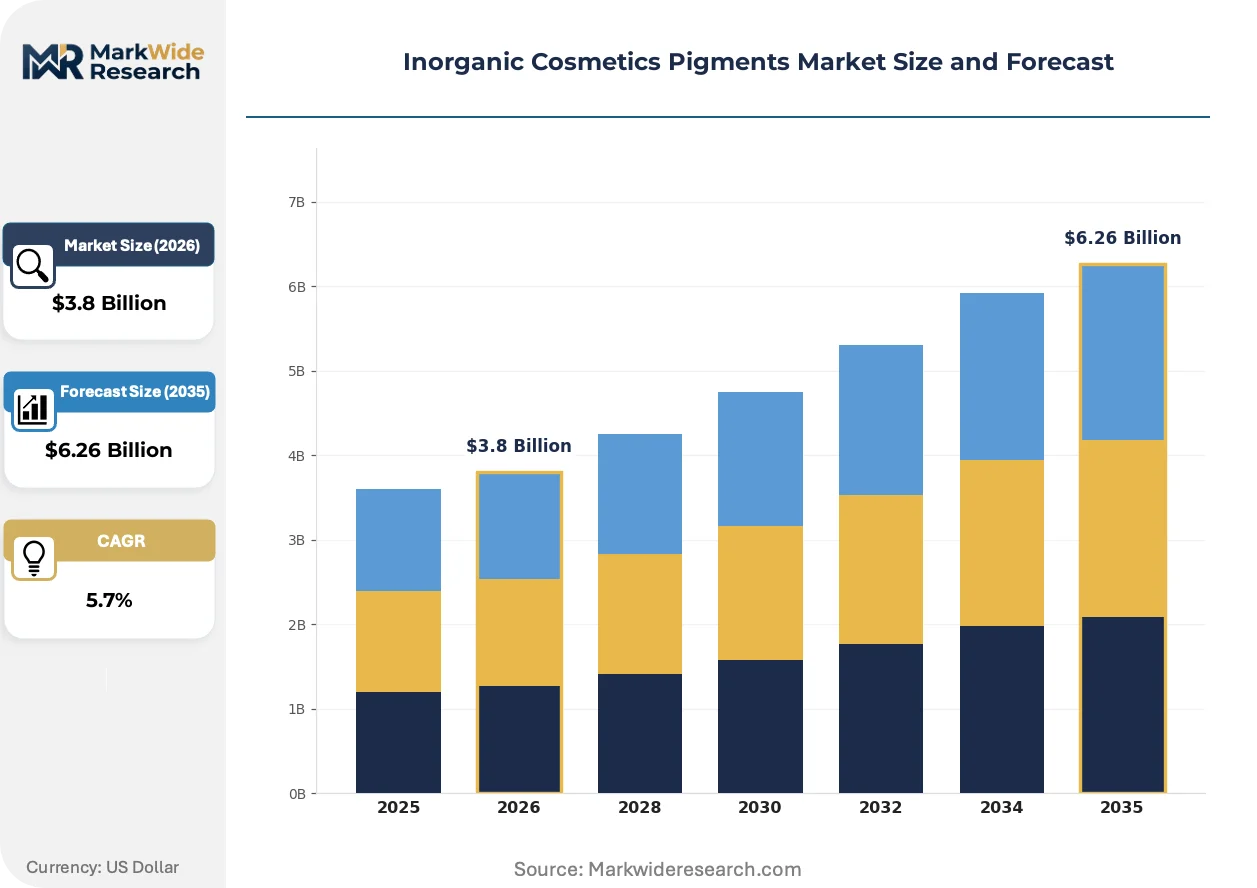
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Iron Oxides, Ultramarines, Titanium Dioxide, Mica Application: Makeup, Skincare, Haircare, Nail Products Form: Powder, Liquid, Paste, Granules Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | ECKART, Kobo Products, Sun Chemical, Lanxess, Geotech International, Merck KGaA, Sudarshan Chemical Industries, The Chemours Company, Sensient Cosmetic Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inorganic Cosmetics Pigments Market Strategic Shifts
Surface chemistry engineering is displacing conventional raw pigment trading as the primary value-capture mechanism in cosmetic colorants. Formulation houses now prioritize dispersion stability and skin-feel optimization over commodity mineral sourcing.
Hybrid inorganic-organic surface treatments are hybridizing conventional pigment performance with biofunctional claims. Silane coupling agents combined with hyaluronic acid grafting enable mineral colorants to deliver moisturization alongside opacity. Korean skincare brands are adopting these grades fastest, compressing traditional supplier qualification cycles from eighteen months to under nine. The technology is hybridizing pigment suppliers into ingredient innovation partners rather than bulk mineral vendors.
ECHA's 2025 REACH revision tightening cadmium and lead thresholds in synthetic mineral pigments is forcing reformulation cycles across European color houses. Industrial consequence includes accelerated migration toward pharmaceutical-grade iron oxide suppliers with existing heavy-metal documentation systems. Decorative cosmetics with darker color saturation requirements—deep reds, blacks, purples—face the steepest substitution pressures as ultramarine and manganese violet capacities strain to absorb displaced volume.
Buyer consolidation among multinational beauty conglomerates is compressing supplier negotiation leverage and unbundling after-sales technical service from base pigment contracts. Procurement teams at L'Oréal, Estée Lauder, and Shiseido are centralizing global pigment sourcing through dedicated category managers, displacing regional purchasing autonomy. This concentration is most visible in North America and Western Europe, where three-year framework agreements with volume commitments now dominate mid-tier colorant procurement.
Inorganic Cosmetics Pigments Market Segmentation
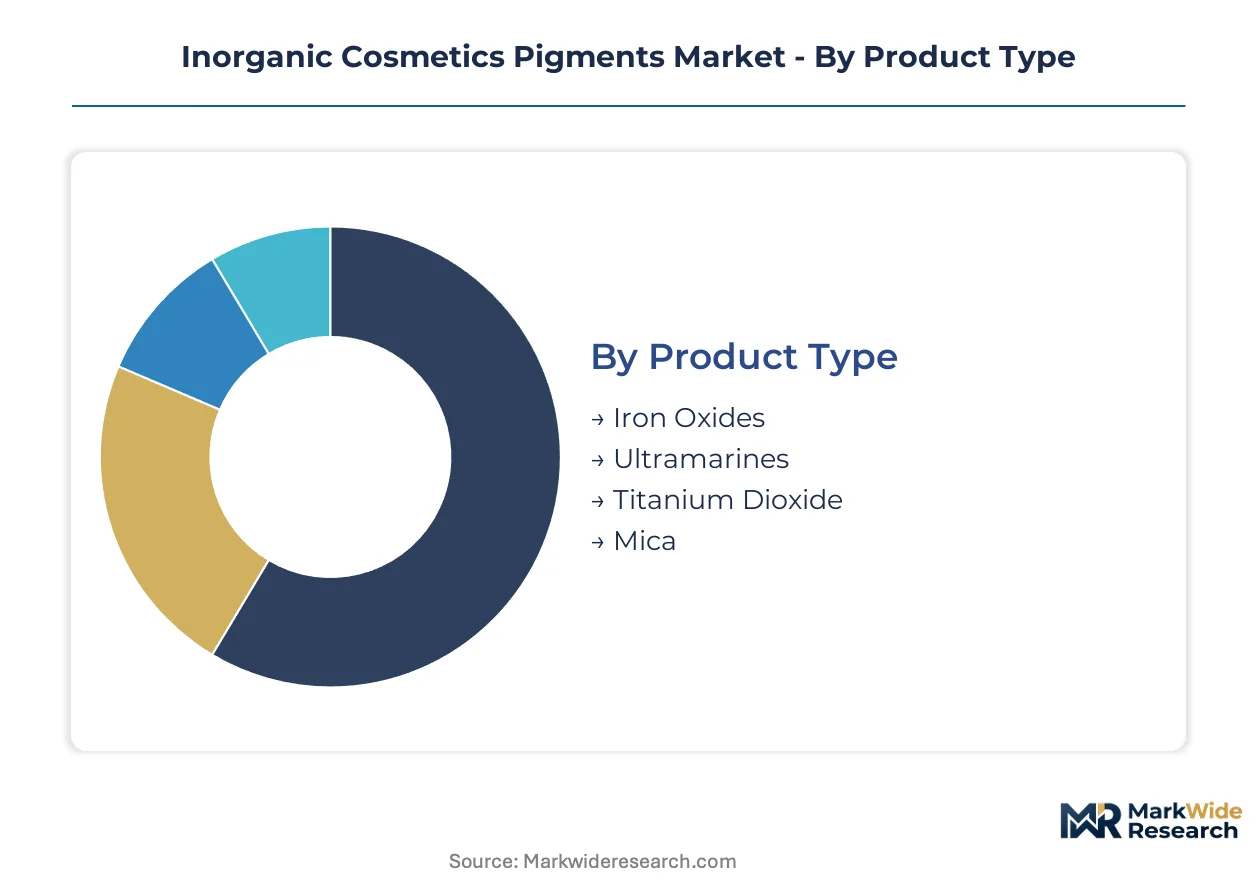
Inorganic cosmetics pigments segment across four dimensions that determine formulation economics and regulatory exposure. Product type dictates mineral sourcing geography and heavy-metal testing burden. Application and form together determine surface-treatment complexity and dispersion infrastructure requirements.
Product Type:
Mature mineral oxides coexist with emerging pearlescent technologies across this category, creating divergent margin profiles and capital intensity.
- Titanium Dioxide:Rutile and anatase crystal structures deliver refractive indices above 2.5, making this the dominant UV-opacifying agent across sunscreen and foundation matrices. Demand concentrates in formulations where photostability mandates from Australia's TGA and South Korea's MFDS are tightening performance thresholds. Ilmenite feedstock sourcing from China and Australia exposes compounders to Strait of Malacca shipping risk.
- Iron Oxides:Synthetic and natural variants span red, yellow, black, and brown chromatic ranges through controlled oxidation-state engineering. Lanxess and pharmaceutical-grade suppliers are capturing expanded volume as ECHA's REACH revisions compress cadmium and lead thresholds, forcing darker shade reformulations toward certified mineral sources.
- Ultramarines:Sodium aluminosilicate structures with entrapped sulfur radical anions deliver intense blue and violet hues unattainable through iron oxide chemistry. Clean-label brands rejecting organic azo dyes are pulling through premium grades despite higher per-kilogram pricing.
- Mica:Potassium aluminum silicate lamellar structures provide pearlescent luster through light interference at platelet surfaces. Surface-treated grades with silane or titanate coatings command formulation slots in premium color cosmetics, though multilayer deposition technician scarcity constrains supply expansion.
Titanium Dioxide retains volume leadership; Ultramarines holds the steepest expansion curve.
Application:
Customer type segmentation separates commodity bulk buyers from specification-driven formulation houses with captive technical service requirements.
- Makeup:Foundations, lipsticks, eyeshadows, and blushes demand the widest SKU breadth across particle size distributions and surface chemistries. Procurement centralization at L'Oréal, Estée Lauder, and Shiseido is compressing supplier negotiation leverage through three-year framework agreements with volume commitments.
- Skincare:Tone-correcting serums and tinted moisturizers are embedding iron oxide and titanium dioxide directly into active treatment protocols. Korean brands adopting hyaluronic acid-grafted mineral grades are compressing supplier qualification cycles from eighteen months to under nine.
- Haircare:Temporary color rinses and permanent dye formulations utilize iron oxides for brown and auburn shade delivery. BIS certification requirements in India are accelerating domestic qualification timelines for mineral feedstocks in salon-professional channels.
- Nail Products:Pearlescent and metallic effects in lacquers and gels rely on surface-treated mica and aluminum platelets. REACH compliance documentation for heavy-metal traces is extending batch release timelines for European nail care manufacturers.
Makeup commands SKU breadth leadership; Skincare exhibits the most rapid application expansion.
Form:
Supply concentration in dispersion infrastructure creates tiered entry barriers between raw pigment trading and value-added preparation services.
- Powder:Raw mineral feedstocks and spray-dried agglomerates serve compounders with captive milling and surface-treatment capabilities. This form dominates inter-company B2B transfers where technical service unbundling from base pigment contracts is accelerating.
- Liquid:Pre-dispersed aqueous or solvent-based slurries eliminate dust exposure and accelerate manufacturing line changeovers. Asset-light toll manufacturing models in Southeast Asia are expanding access to REACH-compliant preparations without captive reactor infrastructure.
- Paste:High-solids dispersions in cosmetic-grade oils and esters target color cosmetics houses seeking optimized skin-feel and rheology control. Silane and titanate coating lines require dedicated reactor investment that mid-sized compounders struggle to justify.
- Granules:Dust-free, free-flowing agglomerates for automated dosing systems in high-volume shampoo and conditioner production. This form is gaining share in haircare manufacturing clusters where OSHA and EU occupational exposure limits are tightening.
Powder retains upstream volume leadership; Liquid dispersion services are climbing the fastest.
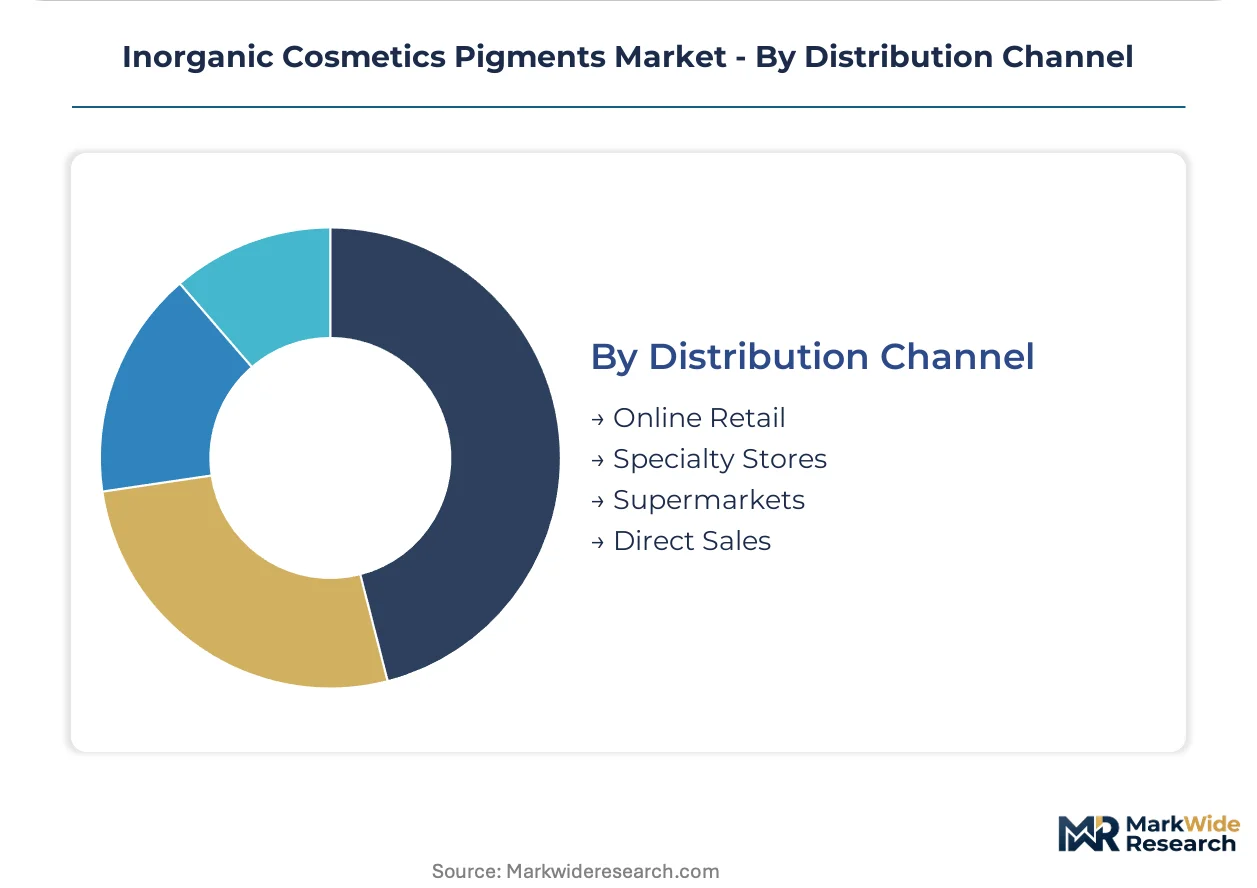
Distribution Channel:
Geography and margin structure segment channel strategy between specification-intensive direct relationships and scale-driven retail intermediation.
- Direct Sales:Long-term supply agreements with technical service attachments dominate procurement at multinational beauty conglomerates. Category managers at centralized global sourcing functions are displacing regional purchasing autonomy across North American and Western European operations.
- Specialty Stores:Regional pigment houses and distributors serving mid-tier color cosmetics brands with smaller batch sizes and faster customization cycles. India's PLI scheme acceleration is expanding domestic titanium dioxide processing capacity accessible through these channels.
- Online Retail:E-commerce platforms for small-batch cosmetic manufacturers and indie beauty brands seeking transparent certification documentation. SAMR pre-approval pathways in China are streamlining ingredient listing processes for surface-treated grades sold through digital channels.
- Supermarkets:Mass-market personal care manufacturers purchasing standardized pigment grades through consolidated procurement functions. Price pressure in this channel is reinforcing supplier consolidation toward scale-efficient producers.
Direct Sales anchors specification-driven procurement; Online Retail is gaining share fastest among emerging brand entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for specialty chemicals is accelerating domestic titanium dioxide processing capacity while REACH compliance in Europe compresses heavy-metal thresholds. Color cosmetics brands in Southeast Asia are expanding mineral-based formulations as regulatory documentation requirements intensify across multiple jurisdictions.
India
Domestic demand for iron oxide and titanium dioxide pigments is concentrating in Mumbai-Pune and Ahmedabad-Vadodara manufacturing corridors. BIS certification timelines are shortening as production-linked incentive frameworks expand specialty chemical capacity. Domestic compounders in Gujarat are qualifying pharmaceutical-grade iron oxide grades for dermocosmetic applications.
Germany
ECHA's 2025 REACH revision tightening cadmium and lead thresholds is forcing reformulation cycles across color houses. Pharmaceutical-grade iron oxide suppliers with existing heavy-metal documentation systems are capturing displaced volume from darker shade formulations. Industrial pigment processing clusters in North Rhine-Westphalia are investing in analytical testing infrastructure.
China
SAMR's streamlined cosmetic ingredient listing process is accelerating market access for surface-treated mineral grades meeting new GB standards. Yangtze River Delta pigment manufacturers are expanding silane and titanate coating capacity. Shanghai-based formulators are embedding pearlescent mica into premium color cosmetics for domestic brands.
United States
FDA color additive regulations constraining lead, arsenic, and mercury traces are extending certificate-of-analysis documentation requirements. New Jersey and Ohio-based dispersion facilities are capturing toll manufacturing contracts from mid-sized cosmetics brands. Procurement centralization at multinational beauty conglomerates is compressing regional supplier negotiation leverage.
South Korea
MFDS tightening of UV-filter performance standards is pulling through titanium dioxide grades with optimized particle size distribution. Seoul-based skincare brands are adopting hyaluronic acid-grafted mineral pigments fastest, compressing supplier qualification cycles. Busan-Ulsan chemical processing clusters are expanding surface-treatment reactor infrastructure.
Inorganic Cosmetics Pigments Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered market positions. Consolidation pressure from multinational beauty conglomerates is compressing mid-tier supplier margins while analytical testing capabilities emerge as differentiated moats. Three archetypes dominate: vertically integrated mineral processors with captive feedstock, surface-treatment specialists with dispersion infrastructure, and pharmaceutical-grade purity suppliers with regulatory documentation systems. Competitive moves center on M&A for analytical testing assets and capacity expansion in silane coating reactor lines.
Among German-headquartered chemical conglomerates, Merck KGaA and Lanxess occupy positions reflecting divergent specialization vectors—multilayer deposition technology control versus pharmaceutical-adjacent iron oxide purity grades. Sun Chemical represents the vertically integrated archetype with captive mica supply sustaining formulation consistency. These three entities exemplify how regulatory documentation capabilities and surface-treatment infrastructure now determine competitive positioning more than raw mineral access alone.
| Leading Market Players |
|---|
| ECKART |
| Kobo Products |
| Sun Chemical |
| Lanxess |
| Geotech International |
| Merck KGaA |
| Sudarshan Chemical Industries |
| The Chemours Company |
| Sensient Cosmetic Technologies |
| Others |
Value Chain & Pricing Dynamics
Strait of Malacca shipping corridors govern titanium feedstock cost dynamics, concentrating supply leverage among Chinese and Australian ilmenite processors while downstream pigment houses differentiate pricing through REACH-compliant certification tiers.
Pricing Analysis
Certification level (REACH/FDA-grade) creates the primary spread between commodity mineral trading and pharmaceutical-adjacent pigment supply. Contract-based long-term offtake dominates procurement at multinational beauty conglomerates, while spot transactions persist for mid-sized compounders. Price differentiation hinges on heavy-metal documentation completeness and surface-treatment complexity, with pharmaceutical-grade iron oxide commanding premiums over technical grades. Cost compression in standard mineral feedstocks is intensifying because BIS certification acceleration in India is expanding qualified domestic capacity. Mass-market personal care manufacturers exhibit highest price sensitivity; premium dermocosmetic brands show lowest.
Supply Chain Analysis
Toll manufacturing concentration in Gujarat, New Jersey, and Busan-Ulsan chemical clusters controls dispersion infrastructure for REACH-compliant pigment preparations. Geographic supply concentrates in China, Australia, and India for ilmenite feedstocks, with Germany and South Korea anchoring surface-treatment reactor capacity. Raw material dependencies center on ilmenite concentrates, silane coupling agents, and titanate coating precursors. Single-source vulnerability runs through Strait of Malacca logistics chokepoints for Asian feedstock shipments. Distribution runs through direct technical-service agreements with formulation houses and specialty distributor networks serving mid-tier brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense against organic azo dye revival and bioengineered colorant platforms, requiring fortified positioning around regulatory documentation moats.
For Market Incumbents: Insulate certificate-of-analysis capabilities through captive analytical testing infrastructure investments in North Rhine-Westphalia and Yangtze River Delta clusters. Backward integration into surface-treated mica supply, following Sun Chemical's captive feedstock model, defends margin position against commodity traders. ECHA's cadmium threshold compression threatens darker shade portfolios; pharmaceutical-grade iron oxide qualification provides shelter.
For New Entrants and Emerging Players: Establish a beachhead in third-party dispersion leasing for Southeast Asian color cosmetics brands lacking captive milling infrastructure. White-space concentrates in tone-correcting skincare serums embedding mineral tints, where Korean adoption curves compress supplier qualification cycles. Go-to-market through online retail channels targeting indie beauty brands seeking transparent REACH documentation accelerates initial traction.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underoptimized cosmetic pigment divisions lacking dedicated surface-treatment reactor lines. Long-term viability across the projection horizon rests on analytical testing asset ownership and SAMR pre-approval pathway execution. Watch for MFDS UV-filter performance standard revisions as inflection signal for titanium dioxide particle-size optimization demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Surface-Treated Mica | Sun Chemical's captive supply model demonstrates formulation consistency defense against commodity traders. |
| Analytical Testing Infrastructure Expansion | ECHA's REACH revision compresses cadmium thresholds, forcing parallel FDA documentation workflows. |
| Third-Party Dispersion Leasing Capacity | Asset-light toll manufacturing lowers entry barriers for Southeast Asian color cosmetics brands. |
| Pharmaceutical-Grade Iron Oxide Qualification | Lanxess captures displaced volume as darker shade reformulations reject contaminated mineral sources. |
| Hyaluronic Acid Grafting Technology | Korean skincare brands compress eighteen-month qualification cycles to under nine months. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with pigment procurement managers, technical R&D directors at formulation houses, regulatory affairs leads, and specialty distributor principals; and secondary validation through ECHA REACH annexes, FDA color additive regulations, BIS certification databases, and SAMR cosmetic ingredient listings. Bottom-up triangulation across product-type volume estimates and top-down cross-checks against customs trade flows anchored the analytical framework.
Forecast inputs span titanium dioxide crystal structure grades, iron oxide chromatic ranges, surface-treatment complexity tiers, and regional regulatory cluster adoption curves. CAGRs were derived from segment-level growth rate reconciliation across makeup, skincare, haircare, and nail product applications. Industry-specific inputs include PLI scheme capacity expansion timelines in India and MFDS UV-filter performance threshold trajectories in South Korea.
Stress conditions across ilmenite concentrate pricing volatility, Strait of Malacca shipping disruption scenarios, and heavy-metal testing methodology divergence were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions around regulatory enforcement intensity and clean-label brand formulation commitment durability. Cross-checking against SAMR and BIS certification issuance rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Oil-Dispersible Colors Market
Dyes and Pigments
Lithol Rubine BK Market
Dyes and Pigments
LAMEA Optical Brighteners Market
Dyes and Pigments
Color Retention Agents Market
Dyes and Pigments
Asia-Pacific Feed Pigments Market
Dyes and Pigments
Riboflavin Pigment Market
Dyes and Pigments
Acid Dyes Market
Dyes and Pigments
Global Thermochromic Paint Market
Dyes and Pigments
Bismuth Vanadate Pigment Market
Dyes and Pigments
Global Paper Dyes Market
Dyes and Pigments
Mulch Colorants Market
Dyes and Pigments
Pigment Dispersion Resin Market
Dyes and Pigments
Bio Based Pigments and Dyes Market
Dyes and Pigments
Brilliant Black BN Colors Market
Dyes and Pigments
Carmine Market
Dyes and Pigments
Europe Natural Dyes and Pigments Market