
 Petroleum-Fuel Dyes and Markers Market | 2026-2036
Petroleum-Fuel Dyes and Markers Market Size, Share, and Industry Trends Forecast 2026-2036
Petroleum-Fuel Dyes and Markers Market Outlook
Direct procurement channels between dye manufacturers and national oil companies is narrowing as governments mandate certified markers for tax-stamped fuels. Innospec leverages its integrated additive-dye portfolio to anchor long-term supply contracts with Middle Eastern refiners. DuPont sustains technology leadership through proprietary solvent dye formulations that meet stringent thermal stability requirements. John Hogg Technical Solutions specializes in custom color-matching systems for forensic fuel tracing applications.
Petroleum-fuel dyes and markers comprise synthetic organic colorants and chemical tracers formulated at concentrations between 5 and 50 ppm to distinguish fuel grades, detect adulteration, and enable excise verification. These additives must resist thermal degradation above 200°C and remain stable through hydrotreating and pipeline transport. Solvent dyes dominate volume consumption due to their complete miscibility in hydrocarbons and compatibility with existing injection systems. Azo dyes occupy the fastest-expanding niche as low-cost alternatives for heating oil and marine diesel marking where premium performance specifications are relaxed.
EPA fuel additive registration requirements under 40 CFR Part 79 and EU REACH chemical authorization govern product entry across North American and European markets. India's BIS certification for petroleum product quality and CDSCO oversight of chemical imports create layered compliance barriers for new entrants. Stakeholders must monitor evolving national marker programs, as governments shift from voluntary dye schemes toward mandatory molecular tagging with prosecution-grade forensic standards.
Market Dynamics
Government-mandated molecular tagging programs are compressing dye procurement timelines as excise authorities demand prosecution-grade forensic standards for tax-stamped fuels. This regulatory tightening is forcing reformulators to redesign thermal stability specifications and certify batch traceability through national oil company audit trails.
Growth Catalysts
- EU F-Gas Regulation:Tightening purity standards for dye formulations are accelerating R&D investment in low-volatility solvent systems that withstand hydrotreating above 200°C.
- India PLI scheme:Petroleum sector infrastructure incentives are expanding domestic blending capacity and creating captive demand for azo-based heating oil markers.
- Forensic fuel tracing:Adulteration detection mandates across marine diesel bunkering are pulling custom color-matching systems into port authority inspection protocols.
Market Restraints
- Naphthalene feedstock volatility:Azo dye precursor costs fluctuate with crude aromatics pricing, squeezing margin structures for economy-grade heating oil markers.
- REACH authorization bottlenecks:ECHA substance evaluation timelines extend 18-36 months, delaying new dye entry into European refined product markets.
- Biomarker substitution threat:DNA-encoded molecular tags are capturing share in high-security excise applications where dye-based systems face thermal degradation limits.
Strategic Opportunities
- Saudi Arabia refining expansion:Greenfield complex construction is creating first-mover advantage for integrated additive-dye suppliers with local technical service presence.
- Pipeline injection automation:Convergence of inline spectrometry with programmable logic controllers enables real-time concentration verification at custody transfer points.
- Indonesia tax stamp digitization:QR-code integration with physical dye markers is opening hybrid authentication contracts with state-owned Pertamina.
Industry Challenges
- Certification timeline compression:BIS and CDSCO parallel approval requirements for India-bound imports force duplicate stability testing and documentation.
- Legacy injection system incompatibility:Refinery skid upgrades to accommodate precision-blended marker concentrations demand capital allocation against tight turnaround windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Petroleum-Fuel Dyes and Markers Market |
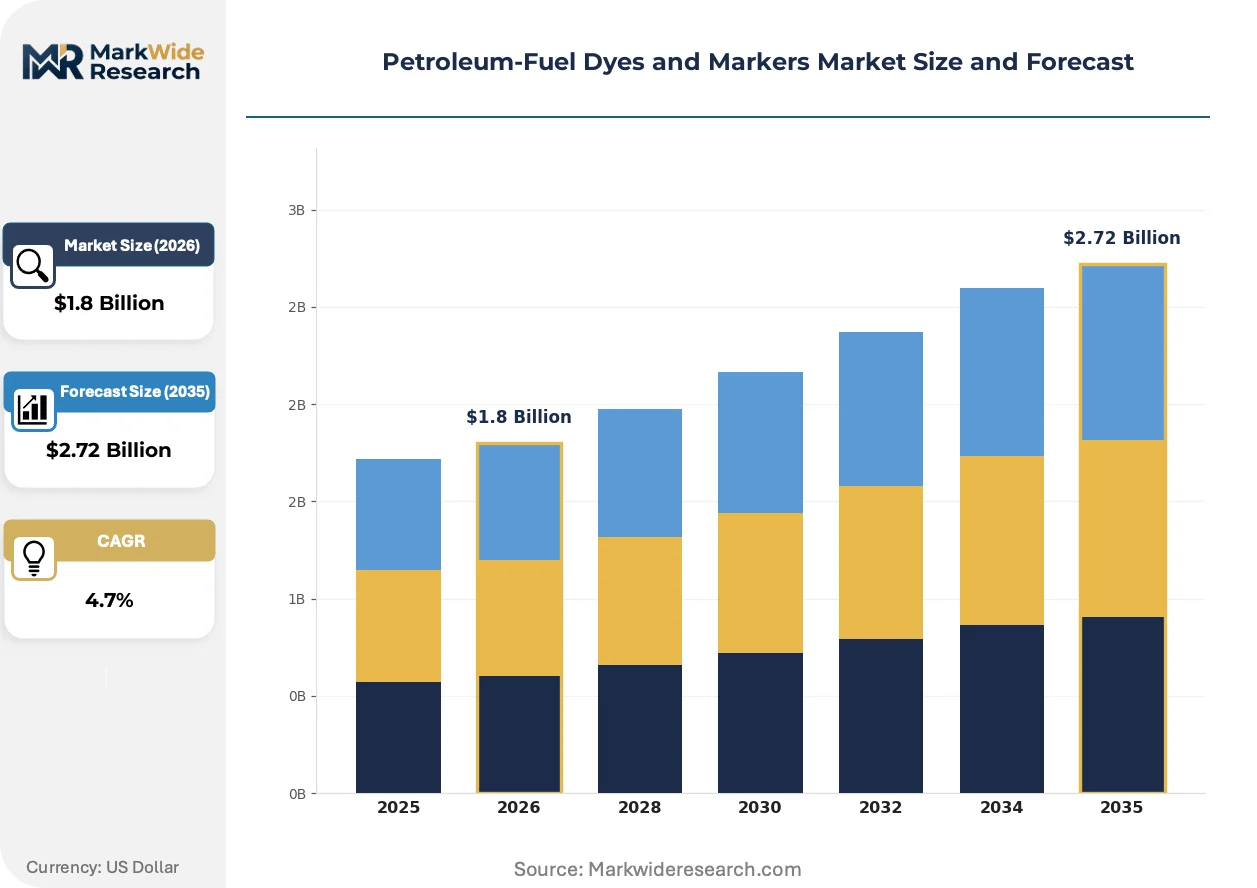
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent Dyes, Azo Dyes, Pigment Dyes, Fluorescent Dyes Application: Diesel Fuel, Gasoline, Jet Fuel, Heating Oil Delivery Mode: Bulk Delivery, Canister, Drums, Packs End User: Oil Refinery, Fuel Distributor, Transportation, Industrial Sector |
| Companies Covered | John Hogg Technical Solutions, DuPont, Innospec, United Color Manufacturing, Pylam Products Company, The Dow Chemical Company, Authentix, AkzoNobel, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Petroleum-Fuel Dyes and Markers Market Strategic Shifts
Multi-spectral detection hardware and AI-enabled batch authentication are compressing the verification cycle from laboratory analysis to field-portable screening. These capabilities are redefining competitive differentiation around forensic reliability rather than color intensity alone.
Quantum dot nanocrystal tracers with distinct emission signatures under UV-Vis excitation are rendering obsolete traditional single-dye forensic protocols that rely on chromatographic separation. National oil companies in the Middle East are piloting these systems at marine loading terminals. The technology is enabling simultaneous grade identification and adulterant fingerprinting without sample preparation.
REACH chemical authorization under ECHA's sunset date mechanism is forcing reformulators to substitute anthraquinone-based solvent dyes with alternative chromophore structures. The industrial consequence is a 24-month qualification cycle for new molecular architectures. Marine diesel and heating oil segments are responding fastest, relaxing colorfastness specifications to accommodate interim dye candidates.
Direct long-term contracting between dye manufacturers and national oil companies is displacing distributor-mediated spot purchasing across Asian refining hubs. Procurement teams at Indian Oil and Bharat Petroleum are consolidating volumes into five-year framework agreements with technical service attachments. This pattern is most visible in Mumbai and Vadodara, where excise enforcement intensity has tightened marker performance guarantees.
Petroleum-Fuel Dyes and Markers Market Segmentation
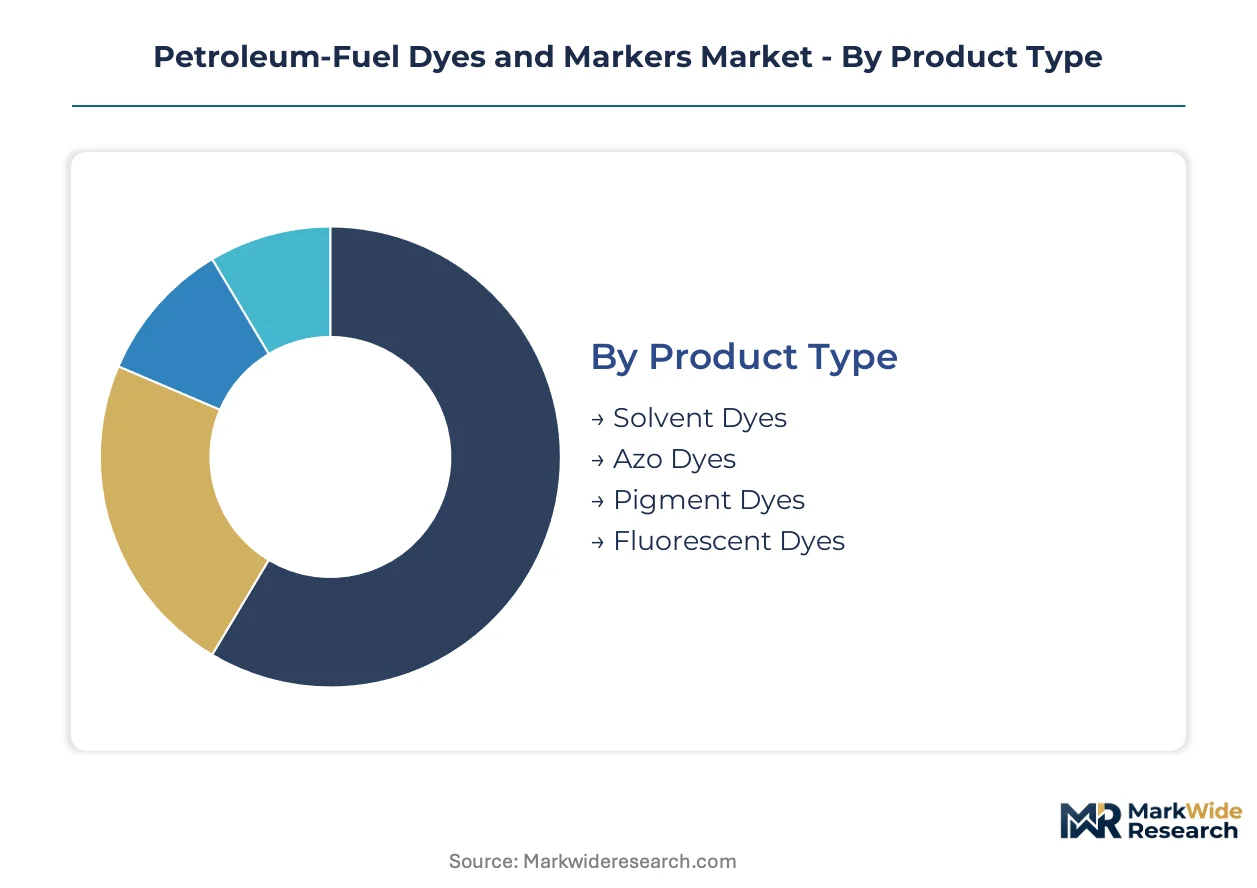
Segmentation in petroleum-fuel dyes and markers reflects divergent technical service requirements across product chemistries and delivery formats. Refinery procurement teams prioritize thermal stability specifications and forensic traceability guarantees over unit pricing alone.
Product Type:
After-sales service intensity varies sharply across dye chemistries, with solvent systems demanding continuous technical support for injection calibration and stability monitoring.
- Solvent Dyes:These hydrocarbon-miscible organic colorants dissolve completely in refined products without particulate residue. Indian Oil and Bharat Petroleum specify solvent dye systems for high-volume gasoline marking under five-year framework agreements with embedded technical service attachments.
- Azo Dyes:Cost-optimized nitrogen-containing chromophores tolerate relaxed thermal specifications in heating oil and marine diesel applications. India's PLI scheme for petroleum infrastructure is accelerating captive demand for azo-based markers as domestic blending capacity expands.
- Pigment Dyes:Insoluble particulate colorants suspended in carrier solvents for specialized forensic applications requiring distinct visual identification under field conditions.
- Fluorescent Dyes:UV-excitable tracers enabling rapid adulterant detection through handheld spectrometry at marine bunkering terminals.
Solvent dyes hold the largest share; momentum sits with azo dyes as cost-sensitive heating oil marking expands.
Application:
Application-driven segmentation aligns dye selection with specific fuel performance envelopes and regulatory exposure profiles.
- Diesel Fuel:Tax-stamped automotive diesel requires prosecution-grade forensic markers resistant to hydrotreating above 200°C. EU F-Gas Regulation compliance is forcing reformulation toward low-volatility solvent systems with extended thermal stability.
- Gasoline:High-throughput gasoline marking at pipeline injection points demands real-time concentration verification through inline spectrometry.
- Jet Fuel:Aviation turbine kerosene marking operates under stringent purity standards with zero tolerance for thermal degradation products that could compromise engine performance.
- Heating Oil:Relaxed colorfastness specifications in residential and industrial heating applications accommodate interim dye candidates during REACH authorization transitions.
Diesel fuel commands the dominant volume position; heating oil is climbing the fastest as European heating oil marking programs expand.
Delivery Mode:
Delivery format selection reflects refinery infrastructure maturity and capital allocation priorities for injection system upgrades.
- Bulk Delivery:Tanker-truck or pipeline transfer of undiluted dye concentrates for continuous injection at refinery custody transfer points. Saudi Aramco's greenfield refining complexes specify bulk delivery with automated blending skids.
- Canister:Pre-measured single-use containers for small-batch fuel marking at remote distribution terminals.
- Drums:Standard 200-liter steel containers serving mid-scale fuel distributors with periodic blending requirements.
- Packs:Flexible pouch or bag-in-box formats for portable field deployment in forensic verification applications.
Bulk delivery dominates refinery-scale procurement; packs are gaining share fastest as port authority inspection protocols proliferate.
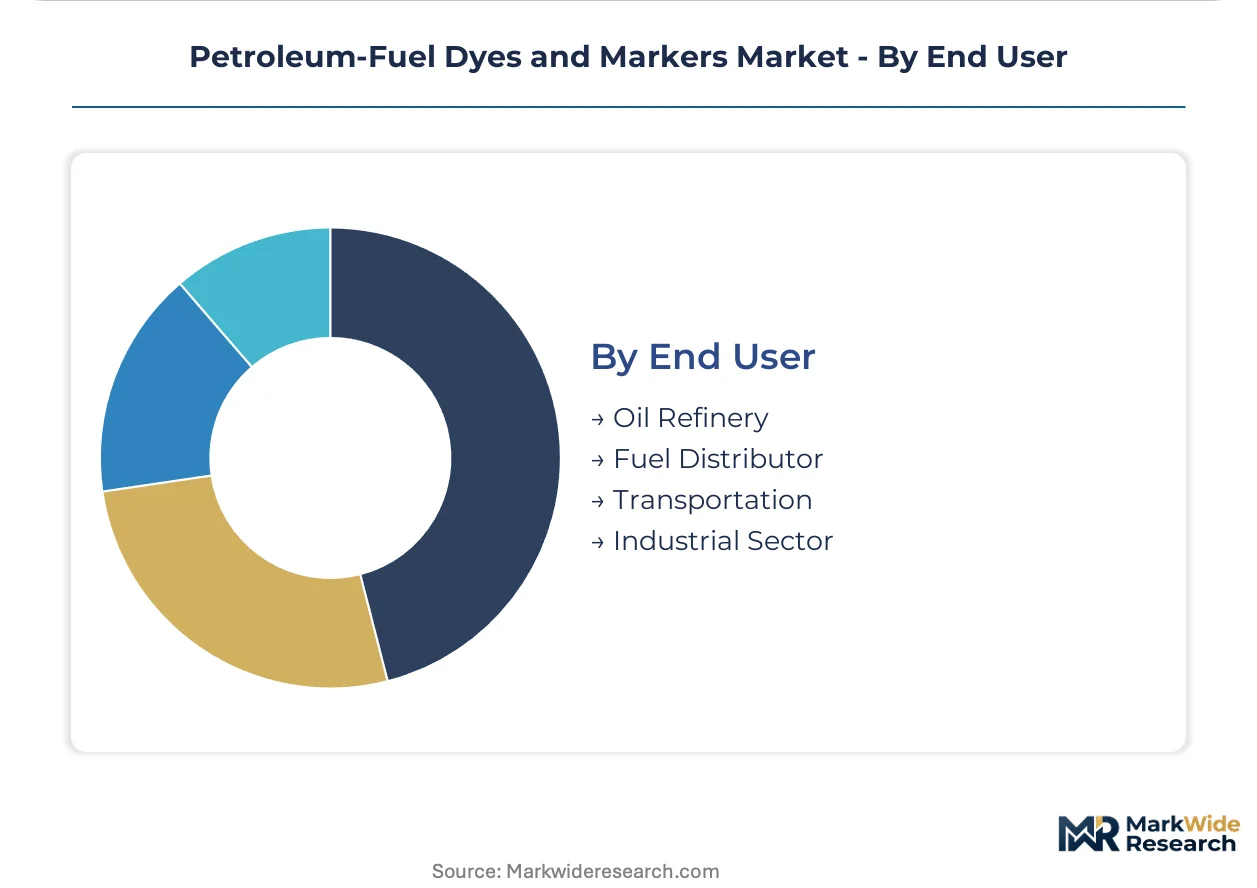
End User:
End-user segmentation captures divergent procurement authority and technical specification ownership across the fuel value chain.
- Oil Refinery:Integrated refining complexes with captive additive injection infrastructure and direct dye manufacturer contracting. National oil companies in the Middle East are consolidating volumes into long-term supply agreements with technical performance guarantees.
- Fuel Distributor:Midstream terminals and wholesale distributors responsible for tax-stamped fuel certification at custody transfer to retail networks.
- Transportation:Fleet operators and marine bunkering services requiring adulteration verification at point of consumption.
- Industrial Sector:Manufacturing facilities with captive fuel storage subject to excise audit and forensic traceability requirements.
Oil refineries anchor procurement volume; fuel distributors represent the steepest expansion trajectory as tax stamp digitization spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jamnagar refinery complex in Gujarat anchors India's fuel marking infrastructure, processing over 1.2 million barrels daily and driving concentrated demand for azo-based heating oil markers. Pipeline networks connecting Rotterdam to the Rhine corridor and the Fujairah bunkering hub in the UAE shape procurement patterns across Europe and the Middle East.
United States
EPA registration requirements under 40 CFR Part 79 govern dye additive entry, while Gulf Coast refineries in Texas and Louisiana expand forensic marker programs for marine diesel bunkering. Houston's concentration of blending facilities drives bulk delivery contracting with automated injection skids.
Germany
REACH authorization timelines extending 18-36 months delay new solvent dye formulations, yet the country's hydrotreating capacity above 200°C demands premium thermal stability specifications. The Rhine-Ruhr industrial corridor hosts reformulation facilities adapting to ECHA sunset date mechanisms.
India
BIS certification and CDSCO import oversight create layered compliance barriers, while the PLI scheme accelerates domestic blending capacity in Mumbai and Vadodara. Indian Oil and Bharat Petroleum consolidate volumes into five-year framework agreements with technical service attachments.
Saudi Arabia
Greenfield refining complex construction at Jazan and Ras Tanura creates first-mover advantage for integrated additive suppliers with local technical presence. The country's national oil company mandates prosecution-grade forensic standards for tax-stamped fuel exports.
Indonesia
State-owned Pertamina pilots QR-code integration with physical dye markers as tax stamp digitization spreads across Java and Sumatra distribution terminals. Port authority inspection protocols at Tanjung Priok pull custom color-matching systems into bunkering verification.
Petroleum-Fuel Dyes and Markers Market Competitive Environment
On the supply side, the industry is consolidating around three strategic tiers: integrated chemical conglomerates with captive additive portfolios, specialized dye manufacturers with forensic certification capabilities, and regional blenders serving cost-sensitive heating oil segments. Competitive dynamics center on long-term contracting with national oil companies and qualification cycles for thermal stability certification. M&A activity targets forensic technology assets, while capacity expansion concentrates near Middle Eastern greenfield refining complexes.
Within the integrated chemical tier, BASF SE and The Dow Chemical Company exemplify scale-driven positions spanning solvent dye formulations to pipeline injection systems. Innospec anchors the specialized additive segment, its technical service presence qualifying it for Middle Eastern refinery contracts. DuPont occupies a position defined by proprietary chromophore architectures meeting stringent hydrotreating specifications. John Hogg Technical Solutions represents the forensic specialization vector, its custom color-matching systems serving port authority inspection protocols.
| Leading Market Players |
|---|
| John Hogg Technical Solutions |
| DuPont |
| Innospec |
| United Color Manufacturing |
| Pylam Products Company |
| The Dow Chemical Company |
| Authentix |
| AkzoNobel |
| BASF SE |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in China's naphthalene feedstock sector is compressing azo dye precursor margins and forcing Indian blenders to renegotiate annual offtake terms. This utilization slack ripples through solvent dye formulations, tilting bargaining power toward national oil companies with multi-year framework mandates.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement contracts. Premium solvent dyes command spreads based on REACH certification status and thermal stability above 200°C; economy azo markers compete on volume scale alone. Cost compression in the heating oil segment is intensifying because naphthalene feedstock volatility squeezes reformulator margins. Fuel distributors exhibit highest price sensitivity, while Middle Eastern refiners prioritize forensic reliability over unit cost.
Supply Chain Analysis
Contract manufacturing concentration rests with German specialty chemical houses and Indian custom synthesis facilities serving azo dye precursors. Raw material flows draw from Chinese naphthalene crackers, German anthraquinone refiners, and Saudi aromatic feedstock streams. Single-source vulnerability concentrates around ECHA-authorized solvent dye intermediates where sunset date mechanisms threaten supply continuity. Distribution runs through refinery-adjacent blending terminals with automated injection skids.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as tax stamp digitization fragments procurement authority between national oil companies, port authorities, and fuel distributors. Each stakeholder tier demands distinct technical service attachments, opening niche positioning for specialized suppliers.
For Market Incumbents: Harden forensic certification moats by embedding quantum dot tracer capabilities into existing solvent dye portfolios. DNA-encoded molecular tags threaten dye-based systems in high-security excise applications; backward integration into naphthalene feedstock streams defends margin structures against aromatic volatility.
For New Entrants and Emerging Players: Pursue hybrid authentication contracts where QR-code integration with physical dye markers creates switching costs for state-owned distributors. Indonesia's Pertamina pilot programs and India's PLI scheme infrastructure incentives represent the most penetrable entry points. Lead with portable spectrometry-enabled verification systems rather than commodity colorants.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across forensic tracer sub-segments as multi-spectral detection hardware and AI-enabled batch authentication compress verification cycles. Long-term viability favors asset-light reformulators with ECHA pre-authorization status over capital-heavy greenfield capacity. Monitor ECHA substance evaluation timeline compression as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Naphthalene Feedstock | Secures precursor supply against Chinese aromatic volatility for azo dye manufacturers. |
| Forensic Certification Investment | Qualifies suppliers for prosecution-grade standards mandated by Saudi Aramco export protocols. |
| Long-term Supply Agreement | Locks in five-year frameworks with Indian Oil and Bharat Petroleum as spot purchasing narrows. |
| Joint Venture for Local Blending | Captures PLI scheme incentives in Mumbai and Vadodara infrastructure expansion zones. |
| Technology Licensing for Quantum Dot Tracers | Enables simultaneous grade identification and adulterant fingerprinting at marine loading terminals. |
Study Parameters
Cross-validation between refinery procurement director interviews and customs/trade data anchors the qualitative findings. Primary fieldwork engaged technical service managers at additive suppliers, excise enforcement officers at port authorities, and CDSCO chemical import regulators. Secondary sources encompassed ECHA substance evaluation databases, BIS petroleum product quality circulars, and SEC filings from integrated chemical conglomerates. Bottom-up volume estimates triangulated against top-down excise revenue projections.
Calibration against historical thermal stability qualification cycles shaped the analytical framework. Segmentation dimensions span dye chemistry type, fuel application, delivery mode, and end-user procurement authority. CAGRs were derived from elasticity-adjusted demand curves across the projection horizon. Forecast inputs incorporated REACH authorization timeline probabilities and PLI scheme capacity buildout schedules.
Macroeconomic conditions sit as an overlay; deviation in crude aromatic pricing and hydrotreating capacity utilization would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and molecular tag substitution rates. Quarterly review of ECHA sunset date announcements and national oil company tender awards is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Riboflavin Pigment Market
Dyes and Pigments
Asia-Pacific Feed Pigments Market
Dyes and Pigments
Pigment Additive Film Market
Dyes and Pigments
Brilliant Blue FCF Colors Market
Dyes and Pigments
Plastic Pigments Market
Dyes and Pigments
Chemochromic Material Market
Dyes and Pigments
Titanium Dioxide Pigment Market
Dyes and Pigments
Photoluminescent Paints Market
Dyes and Pigments
Brilliant Black BN Colors Market
Dyes and Pigments
Indigo Carmine Market
Dyes and Pigments
Global Thermochromic Materials Market
Dyes and Pigments
Global Pigments Market
Dyes and Pigments
High Performance Pigments Market
Dyes and Pigments
Algal Pigments Market
Dyes and Pigments
LAMEA Optical Brighteners Market
Dyes and Pigments
Acid Orange Market