
 Phthalocyanine Pigments Market | 2026-2036
Phthalocyanine Pigments Market Size, Share, and Industry Trends Forecast 2026-2036
Phthalocyanine Pigments Market Intelligence
The phase-out of lead chromate pigments due to toxicity concerns is repositioning phthalocyanines as a primary alternative for high-performance yellow and green shades. BASF leverages its extensive chemical synthesis capabilities to offer a broad portfolio for automotive and industrial coatings. Sudarshan Chemical Industries Limited competes on manufacturing scale and cost-efficiency, particularly in the Asian market. DIC Corporation specializes in high-purity pigments for demanding printing ink applications.
Phthalocyanine pigments are synthetic organic colorants based on a macrocyclic aromatic compound structure, typically complexed with a copper ion. Their primary function is to deliver exceptional lightfastness, chemical stability, and high tinting strength in applications requiring durable color. The blue pigment variants, particularly Pigment Blue 15, dominate the product landscape due to their versatility and cost-effectiveness. Demand from the plastics and paints end-user segments is expanding, driven by masterbatch production for consumer goods and architectural coatings.
Regulatory frameworks like the European Union's REACH legislation and the United States EPA's Toxic Substances Control Act govern the chemical safety and market access for these pigments. In China, compliance with GB standards for consumer products and coatings is mandatory for all manufacturers. Navigating the shift toward water-based formulations and non-halogenated pigments will be a critical decision point for producers.
Market Dynamics
The primary force shaping the market is the regulatory-driven displacement of heavy-metal-based colorants. The phase-out of substances like lead chromate under legislation such as the EU's REACH regulation is compelling end-users in automotive and industrial coatings to adopt phthalocyanine pigments as a primary high-performance alternative.
Growth Catalysts
- Automotive Sector Requirements:The automotive industry’s demand for coatings with superior lightfastness, chemical resistance, and vibrant color palettes for OEM and refinish applications directly stimulates consumption of durable phthalocyanine formulations.
- Regulatory Substitution:The European Union's REACH regulation, by restricting the use of toxic legacy pigments, creates a mandatory substitution pathway, positioning compliant phthalocyanine blues and greens as essential colorants.
- Manufacturing in China:China’s extensive production base for consumer electronics, textiles, and plastics provides a concentrated and high-volume demand center for pigments used in masterbatches, inks, and coatings.
Market Restraints
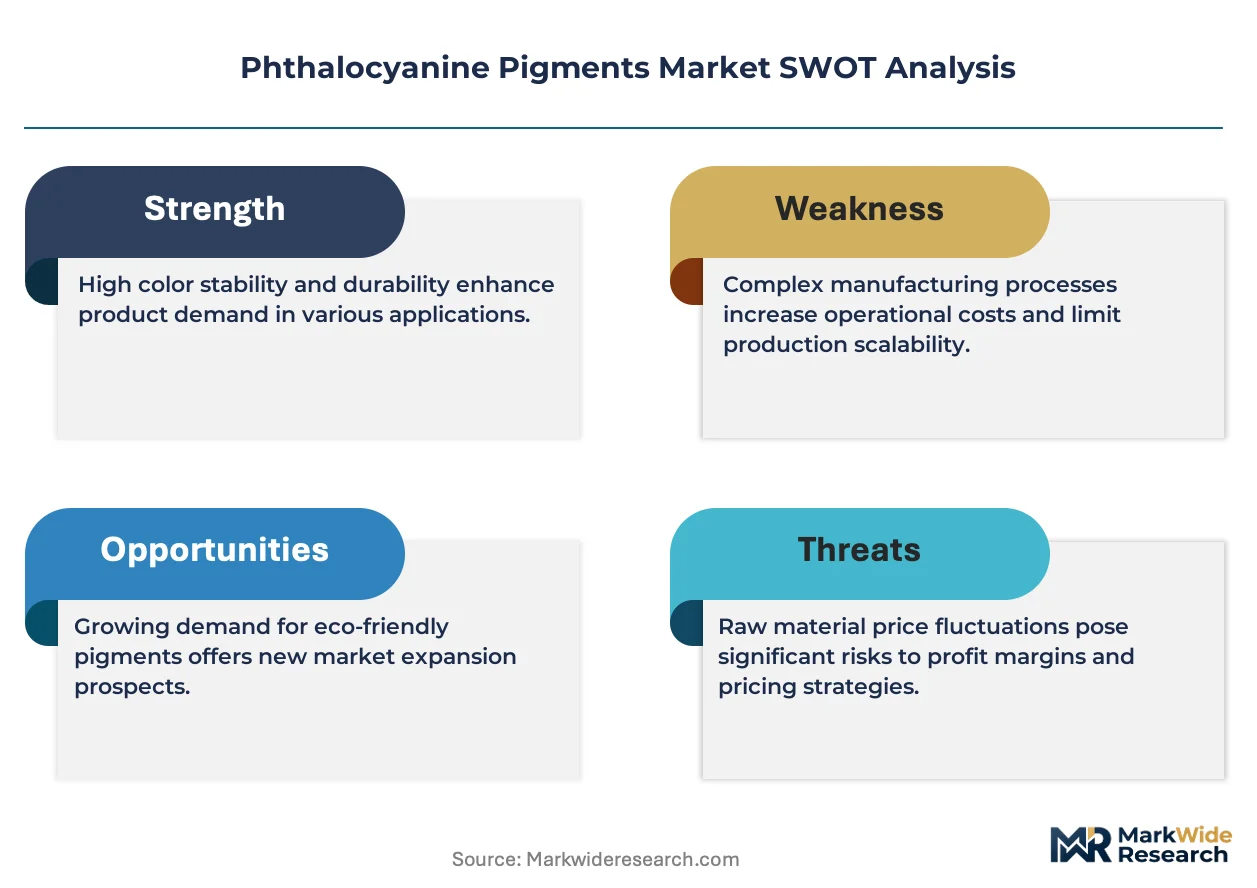
- Raw Material Volatility:The cost structure is highly sensitive to price fluctuations of key precursors, including copper and phthalic anhydride, which can compress manufacturer margins and create pricing instability for end-users.
- Substitution in Yellows:While dominant in blues and greens, phthalocyanine chemistry faces technical limitations and competition from other high-performance pigments in achieving specific bright yellow and red shades.
- Complex Registration Processes:Gaining market access requires navigating lengthy and costly chemical evaluation processes under frameworks like the US EPA's Toxic Substances Control Act (TSCA), creating barriers to entry.
Strategic Opportunities
- Non-Halogenated Formulations:Developing and commercializing non-halogenated green phthalocyanine pigments offers a significant opportunity to meet growing market and regulatory demand for more environmentally benign colorant options.
- High-Purity Electronic Grades:There is an emerging application space for high-purity, specialized phthalocyanine grades as functional materials in organic electronics, including sensors and near-infrared (NIR) absorbing applications.
- Water-Based Systems:Formulating stable, high-performance pigment dispersions optimized for water-based paint and ink systems addresses a critical technological shift away from solvent-borne formulations across multiple end-use industries.
Industry Challenges
- Capital for Formulation Shifts:Migrating production from solvent-based to water-based pigment preparations requires significant capital investment in new milling equipment, dispersion technology, and quality control systems to ensure particle size and stability.
- Divergent Global Standards:Manufacturers face the operational challenge of ensuring products comply with a complex and non-harmonized patchwork of chemical regulations, including EU REACH, US TSCA, and China's GB standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phthalocyanine Pigments Market |
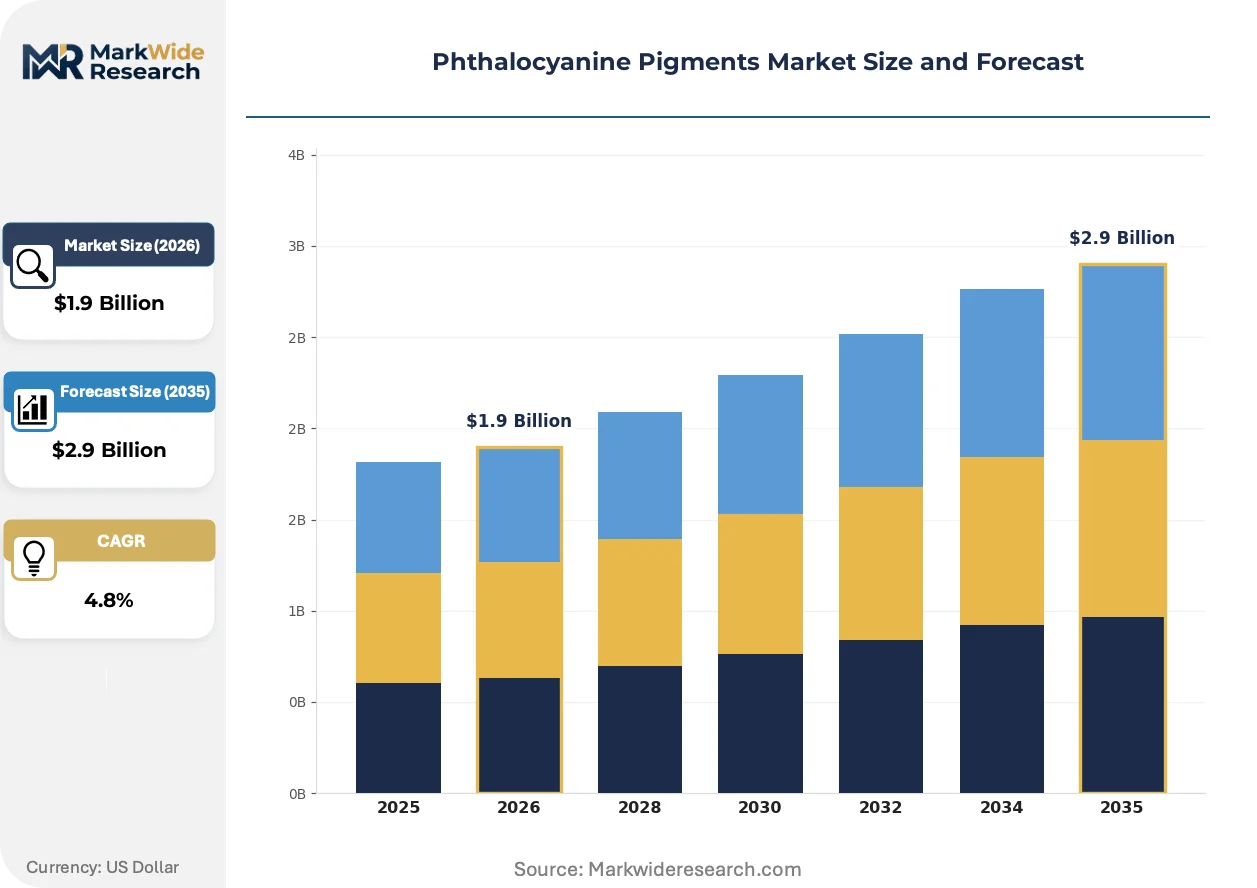
| Market Size in 2026 | $1.9 Billion |
| Market Size in 2035 | $2.9 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Green, Blue, Red, Yellow End User: Paints, Plastics, Inks, Textiles Application: Coatings, Printing, Masterbatches, Dyes Form: Powder, Liquid, Granule, Paste |
| Companies Covered | Sudarshan Chemical Industries Limited, Yabang Chemical, BASF, Pidilite Industries, Meghmani Organics Limited, Clariant International, Heubach Group, Eckart, DIC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phthalocyanine Pigments Market Strategic Shifts & Innovations
The market's evolution is defined by a push toward functional and sustainable pigments. Innovation is focused on enhancing performance beyond color, such as improving UV stability and thermal resistance, while simultaneously reformulating products to meet stricter global environmental and safety regulations.
Nanoparticle-sized phthalocyanine pigments offer superior transparency and dispersion stability. High-end printing ink and plastics masterbatch producers are adopting these grades to achieve higher color strength and process efficiency. This advanced material science is converging with polymer development to create self-colored resins that require fewer additives, streamlining manufacturing for consumer goods.
China's GB standards for coatings, plastics, and textiles are becoming a major force in product development. These regulations impose strict limits on heavy metals, volatile organic compounds (VOCs), and other hazardous substances. The toy and consumer electronics sectors are most directly affected, compelling pigment suppliers to certify their products and offer specific low-VOC formulations for the Chinese market.
A preference for ready-to-use liquid colorant dispersions is altering procurement patterns. This shift reduces the need for end-users, particularly small-to-medium-sized paint manufacturers, to invest in their own milling and dispersion equipment. The trend is most visible in the European architectural coatings market, where consistency and ease of use are prioritized.
Phthalocyanine Pigments Market Segmentation
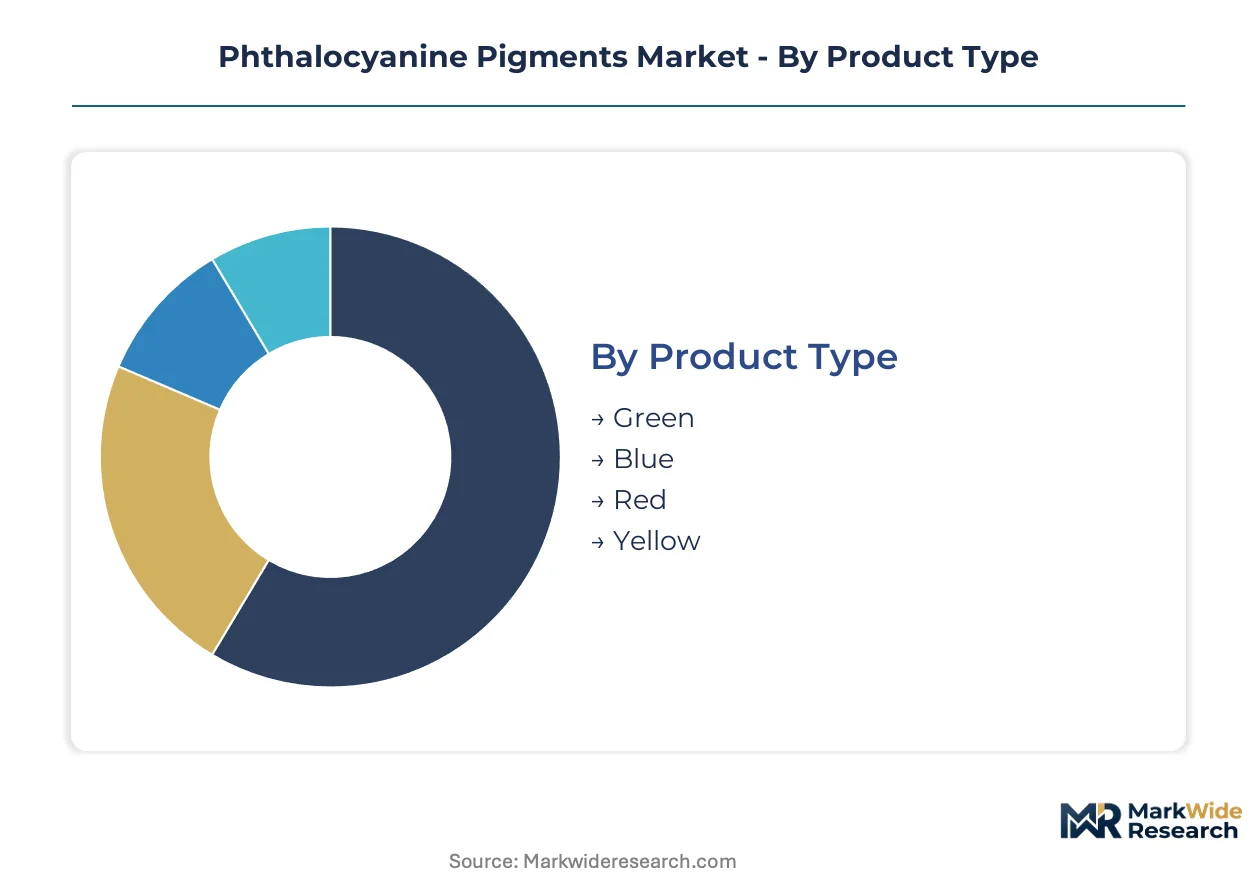
Understanding the distinct segments within the phthalocyanine pigments market is essential for identifying specific demand drivers and competitive landscapes. This detailed breakdown reveals how different product types, end-user industries, applications, and physical forms contribute to the overall market dynamics.
Product Type:
Buyer decisions in product type are primarily driven by the desired hue, color intensity, and performance characteristics for the final application.
- Blue:Copper phthalocyanine blue pigments, particularly Pigment Blue 15, offer exceptional tinting strength, lightfastness, and chemical resistance. These versatile pigments dominate the product landscape due to their widespread use in paints, plastics, and printing inks.
- Green:Copper phthalocyanine green pigments provide stable, vibrant green shades with high durability and thermal stability. Regulatory shifts, such as the EU's REACH regulation, are compelling manufacturers to adopt compliant green formulations as alternatives to restricted legacy pigments.
- Red:Phthalocyanine red pigments are less common due to technical limitations in achieving bright red shades with the same performance as blues and greens. These variants serve niche applications requiring specific color properties.
- Yellow:Phthalocyanine yellow pigments face significant competition from other high-performance organic pigments that offer superior brightness and cost-effectiveness.
Volume sits with Blue pigments; growth tilts toward Green formulations.
End User:
The end-user landscape for phthalocyanine pigments is shaped by diverse industry requirements for color durability and regulatory compliance.
- Paints:The paints sector utilizes phthalocyanine pigments for their superior lightfastness and weather resistance in architectural, automotive, and industrial coatings. Demand from China's construction and manufacturing industries significantly influences this segment.
- Plastics:Phthalocyanine pigments are incorporated into plastic masterbatches for coloring consumer goods, packaging, and automotive components, requiring excellent heat stability and dispersion. Masterbatch production for consumer electronics and textiles drives demand.
- Inks:The printing ink industry values these pigments for their high tinting strength and permanence in various printing processes. DIC Corporation specializes in high-purity pigments for demanding printing ink applications.
- Textiles:Textile applications use phthalocyanine pigments for dyeing and printing fabrics, where colorfastness to washing and light exposure is critical.
Paints and Plastics segments collectively account for the largest consumption volume.
Application:
Application segments dictate the required dispersion properties and processing compatibility for phthalocyanine pigments.
- Coatings:Coatings applications, particularly in the automotive and industrial sectors, demand phthalocyanine pigments for their high performance in terms of durability, UV stability, and chemical resistance. The automotive sector’s need for vibrant, long-lasting colors is a primary driver.
- Masterbatches:Phthalocyanine pigments are widely used in masterbatches, which are concentrated pigment mixtures for coloring plastics efficiently. This application requires excellent dispersion characteristics and thermal stability.
- Printing:Printing applications, encompassing graphic arts and packaging, leverage phthalocyanine pigments for their strong color, permanence, and compatibility with various ink systems.
- Dyes:While primarily pigments, some phthalocyanine derivatives can function as dyes, particularly in textile and specialty applications.
Specialized coatings and masterbatches are seeing expanded use for high-performance applications.
Form:
The physical form of phthalocyanine pigments influences ease of integration and processing efficiency for manufacturers.
- Powder:Powdered phthalocyanine pigments are the traditional and most common form, offering high pigment concentration and flexibility for various dispersion processes. Manufacturers require specialized milling equipment to integrate these effectively.
- Liquid:Liquid pigment dispersions offer ready-to-use solutions, reducing processing steps and capital investment for end-users, particularly in the European architectural coatings market. This form provides consistent color strength and easier handling.
- Granule:Granular forms of phthalocyanine pigments offer improved handling characteristics, reduced dust, and better flow properties compared to powders. These are often preferred in specific masterbatch production.
- Paste:Pigment pastes provide a semi-liquid form that can be easier to incorporate into certain formulations, especially in printing inks and textile applications.
Liquid dispersions offer convenience and consistency, driving their adoption in architectural coatings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's extensive chemical industrial zones, such as those along the Yangtze River Delta, drive significant concentration for phthalocyanine pigment production and consumption. These zones foster integrated supply chains for precursors and finished colorants. This industrial clustering supports high-volume manufacturing for diverse end-use sectors.
China
Demand for phthalocyanine pigments in China stems from its extensive production of consumer electronics, textiles, and plastics masterbatches. China's GB standards for coatings and consumer products mandate specific pigment formulations. Jiangsu province houses numerous chemical manufacturers, boosting local pigment output for domestic and export markets.
Germany
German demand for phthalocyanine pigments originates from its robust automotive coatings sector and high-performance industrial paints. The EU's REACH legislation mandates compliant pigment formulations, influencing product development. Chemical parks in Ludwigshafen support advanced pigment research and production for specialty applications.
United States
The United States market utilizes phthalocyanine pigments for architectural coatings, automotive refinish, and plastics in consumer goods. The US EPA's Toxic Substances Control Act (TSCA) governs chemical safety and market access for these colorants. The Gulf Coast region hosts petrochemical facilities, providing raw materials for pigment synthesis and distribution.
India
India's market for phthalocyanine pigments is driven by its expanding construction paints sector, textile dyeing industries, and packaging inks. BIS standards increasingly influence product quality and safety for industrial chemicals. Gujarat's chemical manufacturing hubs, like Ankleshwar, are expanding production capacity for diverse pigment grades.
Phthalocyanine Pigments Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, reflecting varied performance requirements and cost structures. The market exhibits a tiered structure, with global chemical giants focusing on high-performance formulations. Regional players often compete on cost-efficiency and localized supply chains. Strategic archetypes include integrated chemical producers, pigment specialists, and niche formulators. Capacity expansion and portfolio diversification are dominant competitive moves.
Within the integrated chemical producer tier, BASF represents a global leader leveraging extensive synthesis capabilities for broad portfolio offerings. DIC Corporation exemplifies a specialist in high-purity pigments, particularly for demanding printing ink applications. Sudarshan Chemical Industries Limited, an India-based manufacturer, occupies a position focused on manufacturing scale and cost-efficiency, especially across Asian markets. These firms navigate complex regulatory landscapes while innovating for sustainable and high-performance colorant solutions.
| Leading Market Players |
|---|
| Sudarshan Chemical Industries Limited |
| Yabang Chemical |
| BASF |
| Pidilite Industries |
| Meghmani Organics Limited |
| Clariant International |
| Heubach Group |
| Eckart |
| DIC Corporation |
| Others |
Cost & Logistics Intelligence
Copper commodity price fluctuations directly influence the cost structure of phthalocyanine pigments, cascading into tiered pricing for end-users. This volatility affects manufacturer margins and creates instability across different product grades.
Pricing Analysis
Premium pricing for short lead times rewards rapid delivery of specialty phthalocyanine pigments. The dominant pricing model combines long-term contract-based offtake for major buyers with per-unit transactional sales for smaller volumes. Price differentiation stems from pigment quality grade, such as high-purity electronic grades, and volume scale. Cost compression intensifies in standard grades due to raw material volatility, making small-to-medium paint manufacturers highly price-sensitive.
Supply Chain Analysis
Single-source vulnerability sits with China for key phthalic anhydride precursors. Geographic supply concentrates in China and India for high-volume production, while Germany specializes in advanced formulations. The supply chain relies heavily on copper and phthalic anhydride. Regulatory restriction, particularly divergent global standards like EU REACH and China's GB standards, presents a structural risk. Distribution runs through direct sales channels for major industrial consumers and specialized chemical distributors for smaller end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The phthalocyanine pigments market is witnessing a vertical-integration race, as major players pursue upstream control over key raw material synthesis. This strategy aims to secure supply and manage cost volatility for critical precursors like phthalic anhydride.
For Market Incumbents: Acquire specialized dispersion technology assets to enhance water-based pigment preparations. Invest in developing non-halogenated green formulations to counter regulatory shifts under REACH and GB standards. Expand R&D efforts into high-purity electronic grades, leveraging existing chemical synthesis capabilities. This mitigates the threat from emerging substitute technologies and regulatory-driven displacement.
For New Entrants and Emerging Players: Specialized chemical distributors offer a pathway into underpenetrated markets for high-purity phthalocyanine grades. Target niche applications in organic electronics and water-based architectural coatings, particularly among small-to-medium paint manufacturers in Europe. Focus on offering ready-to-use liquid pigment dispersions, reducing capital investment for end-users. This provides a clear go-to-market angle against established powder suppliers.
For Investors and Strategic Acquirers: The window for entry favors specialist pigment formulators positioned for sustainability transitions. Long-term viability hinges on companies developing compliant, high-performance solutions for the next decade. Identify acquisition targets with proven expertise in non-halogenated green pigments or advanced water-based dispersion technologies. The signal to watch is accelerating adoption of nanoparticle-sized phthalocyanine pigments in high-end plastics masterbatches.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Expands volume output to meet rising demand from China's manufacturing base. |
| Green Manufacturing Transition | Addresses regulatory pressure for non-halogenated and low-VOC pigment formulations. |
| Long-term Supply Agreement | Secures stable access to critical precursors like copper and phthalic anhydride. |
| Joint Venture | Accelerates development and commercialization of advanced water-based dispersion technologies. |
| Portfolio Diversification | Captures emerging opportunities in high-purity organic electronics applications. |
Research Approach
Multi-period observation of raw material price indices, regulatory compliance filings, and patent applications anchored the trend analysis. Primary research involved interviews with chemical plant managers, R&D directors, and procurement leads at automotive OEMs. Secondary validation drew from EU REACH registration data, US EPA TSCA filings, and industry trade association reports, enabling robust triangulation.
An input-output matrix framework modeled market dynamics across the analysis window. Segmentation dimensions included product type, end-user industry, application, and physical form, alongside regional production hubs. Compound annual growth rates were derived from historical data and projected market drivers. Key forecast inputs included raw material availability and regulatory policy changes.
Caveats apply where geopolitical events or rapid technological shifts in alternative colorants could materially shift the outlook. Forecasts reflect assumptions regarding regulatory stability and raw material pricing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Inorganic Cosmetics Pigments Market
Dyes and Pigments
Europe Pigments Market
Dyes and Pigments
Global Thermochromic Materials Market
Dyes and Pigments
Europe Hair Colorants Market
Dyes and Pigments
Quinacridone Pigments Market
Dyes and Pigments
Micronized Color Powder Market
Dyes and Pigments
Europe Natural Dyes and Pigments Market
Dyes and Pigments
Cacao Husk Pigment Market
Dyes and Pigments
Complex Inorganic Color Pigments Market
Dyes and Pigments
Methylene Blue Market
Dyes and Pigments
Color Concentrates Market
Dyes and Pigments
Dyes and Pigments Market
Dyes and Pigments
High Performance Pigments Market
Dyes and Pigments
Asia-Pacific Feed Pigments Market
Dyes and Pigments
Global Pigments Market
Dyes and Pigments
Bismuth Vanadate Pigment Market