
 Europe Hair Colorants Market | 2026-2036
Europe Hair Colorants Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Hair Colorants Market Foresight
Clean-label and ammonia-free premium tiers is redrawing competitive boundaries across Europe. L'Oréal S.A. anchors its position through extensive professional salon networks spanning Paris and Milan. Henkel AG & Co. KGaA differentiates via Schwarzkopf's specialized oxidation dye technology leadership. Kao Corporation leverages its Japanese botanical R&D pipeline to compete in the natural-positioned segment.
Europe hair colorants comprise oxidative and non-oxidative formulations containing dye intermediates, coupling agents, and alkalizing bases typically at pH 9.0-11.0, designed to deposit or lift natural melanin for cosmetic hair pigmentation. Permanent oxidation dyes dominate value pools due to higher per-application pricing and repeat purchase frequency in professional channels. Semi-permanent formulations capture growing share among home-use customers seeking lower-commitment color refresh cycles. Cream-based delivery systems lead formulation preferences for controlled application and reduced scalp irritation risk.
REACH enforcement through ECHA and the EU Green Deal's chemical sustainability targets are tightening permissible aromatic amine thresholds and accelerating reformulation cycles across manufacturers. EMA-aligned cosmetic safety assessments and Germany's BfR dye substance evaluations shape national market access conditions. France's ANSM monitors professional-grade product labeling standards. Stakeholders must track evolving substance restriction lists and professional certification requirements to anticipate compliance-driven portfolio shifts.
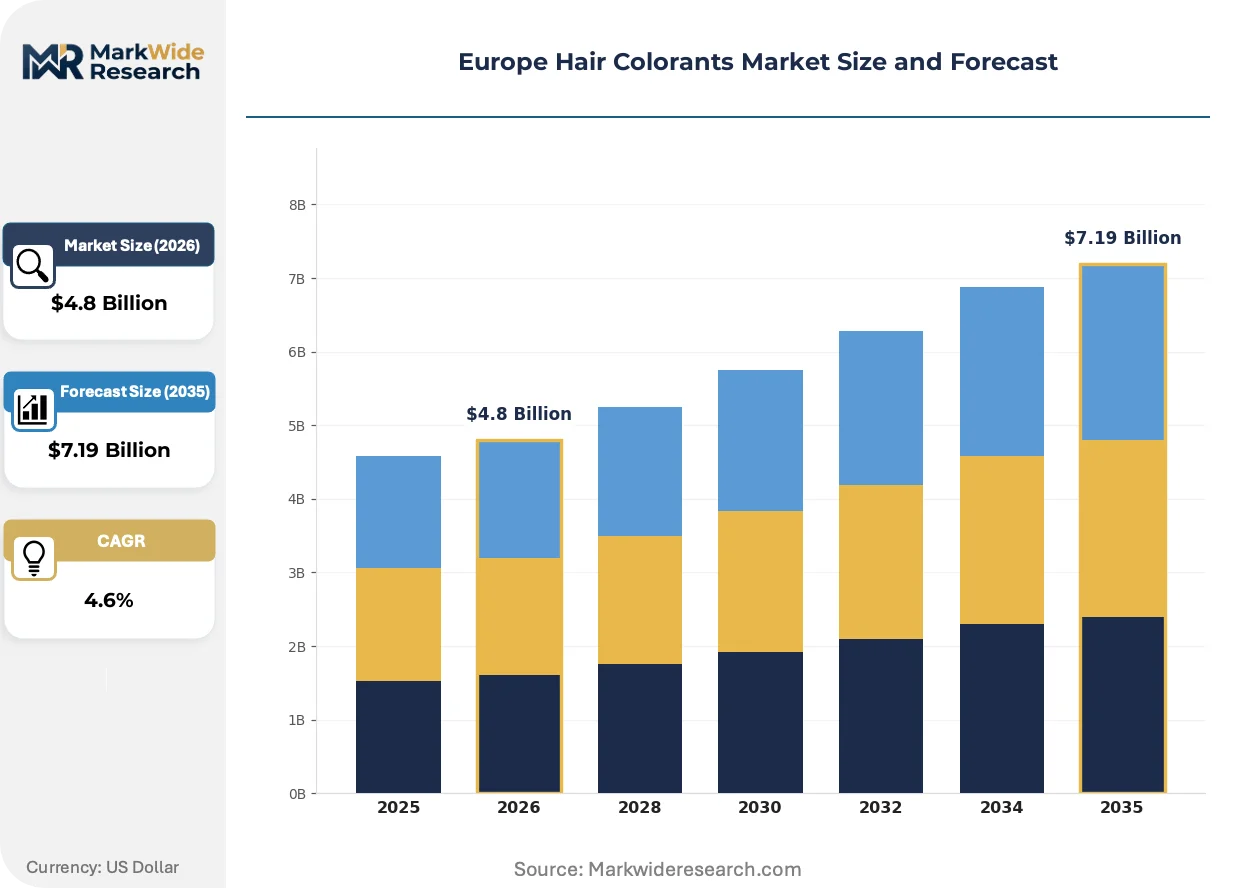
Market Dynamics
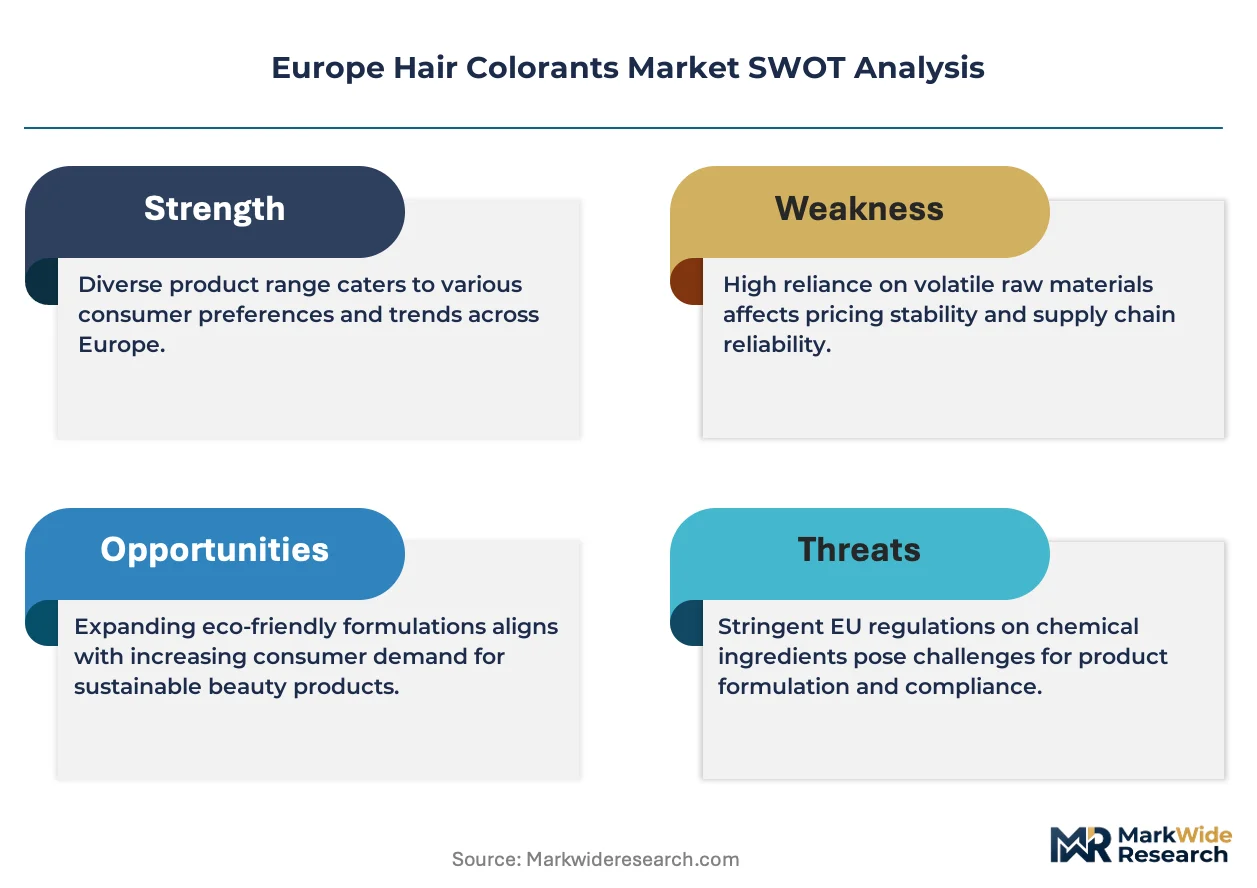
REACH substance restrictions and the EU Green Deal are forcing accelerated reformulation cycles across European hair colorant manufacturers, compressing time-to-market for ammonia-free and clean-label portfolios.
Growth Catalysts
- Professional salon premiumization:High-service channels in France and Germany absorb advanced oxidation dye systems with superior gray coverage and scalp comfort profiles.
- Botanical ingredient R&D pipelines:Japanese-derived plant-based colorant technologies are penetrating European natural-positioned segments through specialized import partnerships.
- ECHA enforcement tightening:REACH aromatic amine threshold reductions are creating first-mover advantages for compliant reformulators ahead of mandatory compliance deadlines.
Market Restraints
- Precursor chemical cost volatility:p-Phenylenediamine and toluene-2,5-diamine sulfate feedstock prices fluctuate with Asian petrochemical supply disruptions.
- Western European demand concentration:Metropolitan clusters in Paris, Milan, and Frankfurt absorb disproportionate volume, leaving peripheral markets underdeveloped.
- Technical performance gaps:Ammonia-free alkaline systems struggle to match lifting power of traditional formulations above three shade levels.
Strategic Opportunities
- Eastern European salon network expansion:Poland and Czech Republic professional channels remain underpenetrated relative to Western European service density benchmarks.
- EU Green Deal chemical sustainability incentives:Carbon footprint reduction mandates favor bio-based dye intermediate investments with preferential financing terms.
- Direct-to-consumer subscription models:Home-use semi-permanent color refresh cycles align with personalized replenishment algorithms and shade-matching apps.
Industry Challenges
- Cosmetic chemist talent scarcity:Formulation expertise bridging color science, toxicology, and regulatory compliance commands premium compensation in Germany and France.
- EMA safety assessment timelines:Novel dye substance approvals face extended evaluation periods, delaying portfolio refresh cycles.
- Legacy salon software integration:Professional inventory management systems resist seamless connectivity with manufacturer reorder platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Hair Colorants Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Permanent, Semi-Permanent, Temporary, Highlights Formulation: Cream, Gel, Spray, Liquid Customer Type: Professional, Home Use, Unisex, Kids Distribution Channel: Retail, Online, Specialty Stores, Supermarkets |
| Companies Covered | Kao Corporation, Core Equity Holdings (Provalliance), L'Oréal S.A., Laboratorios Phergal S.A., Eugène Perma Professional, Henkel AG & Co. KGaA, Revlon, Inc., Umberto Giannini Hair Cosmetics Ltd, Coty Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Hair Colorants Market Shifts & Advancements
Formulation chemistry, regulatory compliance architecture, and channel economics are converging to reshape competitive positioning across European hair colorant supply chains.
Micro-encapsulated dye delivery systems are miniaturizing active ingredient payloads for controlled release during oxidation processing. Professional colorists in Milan and Barcelona adopt these systems for precision root touch-up applications. The technology is compressing service time windows while maintaining color deposit consistency.
REACH authorization requirements for aromatic amine derivatives are tightening substance evaluation protocols through ECHA. Manufacturers face mandatory substitution planning for restricted intermediates ahead of sunset date deadlines. Semi-permanent and direct dye categories absorb disproportionate R&D investment as oxidation dye reformulation costs escalate.
Salon-exclusive professional brands face disintermediation pressure from authorized online retailers and subscription box services. Stylists in metropolitan France and Germany report client leakage to home-use premium tiers with virtual consultation support. Channel conflict resolution requires renegotiated territorial distribution agreements and service-bundled pricing structures.
Europe Hair Colorants Market Segmentation
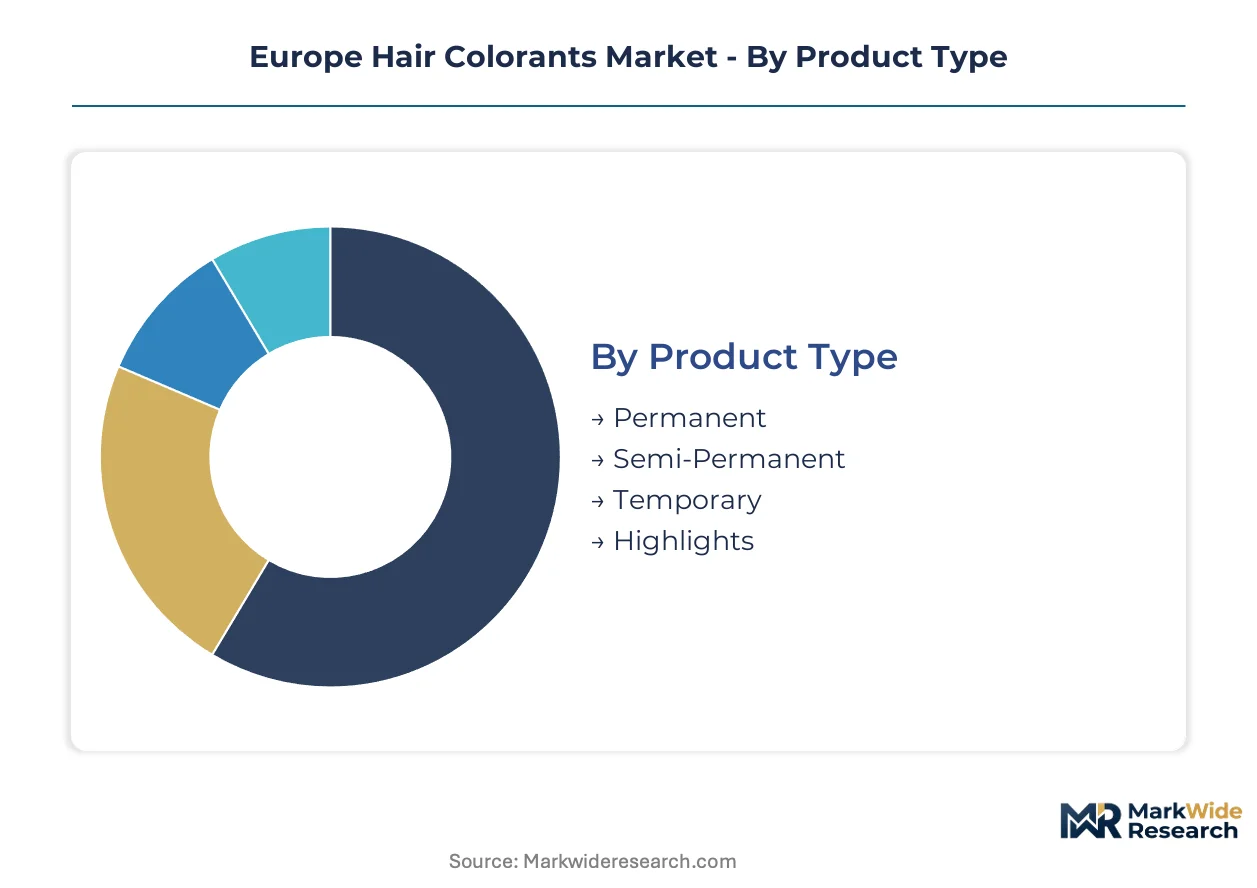
Segmentation reveals how substitution pressures and channel economics fragment purchasing behavior across European hair colorant categories. Professional salon networks and home-use digital channels now compete for overlapping consumer cohorts with divergent service expectations.
Product Type:
Substitution pressure from lower-commitment formats is reshaping value capture across product tiers, with permanent formulations facing the strongest challenge from semi-permanent alternatives in metropolitan markets.
- Permanent:Oxidative dye systems containing p-phenylenediamine and coupling agents penetrate hair cortex for lasting melanin replacement. Paris and Frankfurt professional salons absorb premium ammonia-free variants as REACH aromatic amine restrictions tighten formulation standards.
- Semi-Permanent:Direct dye molecules deposit on cuticle layers without oxidation, enabling gentler color refresh cycles. Milan and Barcelona stylists report rising client preference for these systems among younger demographics seeking frequent shade experimentation without structural damage.
- Temporary:Surface-coating colorants wash out within 1-3 shampoos, serving festival and fashion-event demand clusters.
- Highlights:Sectional bleaching and toning systems target dimensional color effects through foil or cap application methods.
Permanent oxidation dyes anchor the volume base while semi-permanent direct dyes gain share at the steepest rate.
Formulation:
Cost tier differentiation separates professional-grade cream systems from mass-market spray alternatives, with gel formats occupying the contested middle ground.
- Cream:Viscous emulsion bases enable controlled sectioning and scalp protection during prolonged processing. German professional channels favor cream delivery for gray coverage precision, while French home-use consumers select tube formats for root touch-up convenience.
- Gel:Thixotropic systems cling to vertical hair sections without dripping, suited for self-application and hard-to-reach coverage.
- Spray:Aerosol or pump-dispersed colorants target temporary root concealing and quick gray masking between salon appointments.
- Liquid:Low-viscosity solutions penetrate rapidly for all-over color saturation in shorter processing windows.
Cream formulations command the premium price tier while spray alternatives expand most quickly in convenience-oriented retail channels.
Customer Type:
Application setting determines performance requirements and price elasticity, with professional service density varying sharply across Western and Eastern European geographies.
- Professional:Salon-administered oxidation systems demand colorist certification and inventory investment in developer volumes and mixing ratios. French ANSM labeling requirements and Germany's BfR dye evaluations shape product access conditions for licensed stylists.
- Home Use:Consumer-directed kits include pre-measured components and instructional support through shade-matching applications. Subscription algorithms in UK and Netherlands markets personalize replenishment timing based on root growth rates.
- Unisex:Neutral-positioned formulations target male gray coverage and fashion color demand without gendered packaging segmentation.
- Kids:Temporary and semi-permanent systems with reduced sensitization risk serve costume and play-oriented use cases.
Professional channels anchor the value pool while home-use digital subscriptions climb the fastest among customer segments.
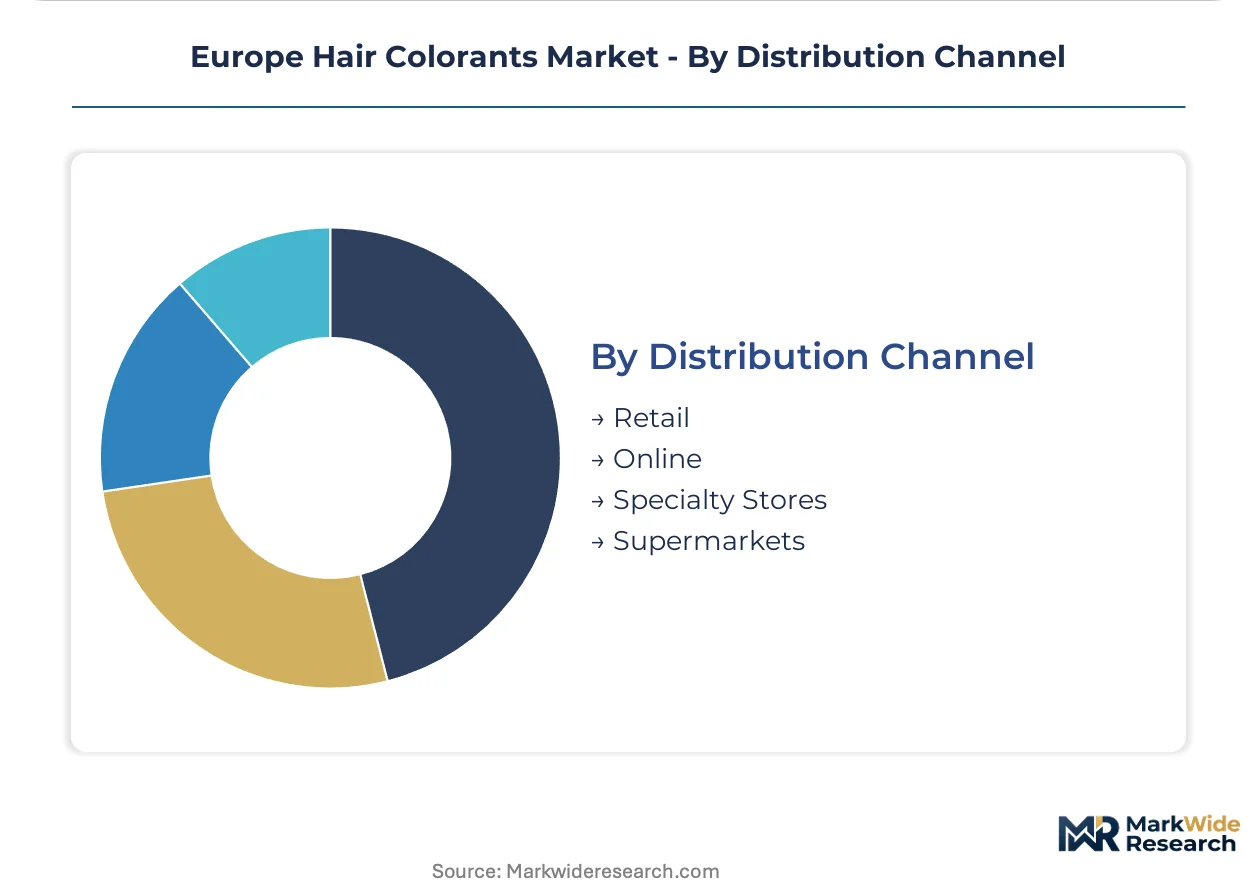
Distribution Channel:
Volume concentration in retail and online channels is displacing specialty store foot traffic, with supermarket placement driving impulse purchase conversion.
- Retail:Mass-market permanent and semi-permanent kits occupy dedicated aisle space with shade chart displays. German drugstore chains and French parapharmacy networks maintain trained beauty advisors for color consultation.
- Online:Direct-to-consumer platforms and authorized e-tailers bypass territorial distribution agreements, creating channel conflict with salon-exclusive brands. Virtual try-on tools reduce shade selection error rates.
- Specialty Stores:Professional-only supply outlets serve licensed colorists with bulk developer volumes and technical education programming.
- Supermarkets:High-frequency shopping destinations capture unplanned purchases through end-cap placement and promotional pricing.
Retail chains anchor the volume base while online direct-to-consumer channels gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European hair colorant trade flows reflect a net import position in dye intermediates alongside strong export capacity in finished professional formulations. Western European metropolitan clusters concentrate consumption, while Eastern European markets absorb cross-border salon service expansion and direct-to-consumer digital penetration.
Germany
Professional salon density in Frankfurt and Munich drives premium oxidation dye absorption, with stylists prioritizing ammonia-free systems for gray coverage precision. BfR dye substance evaluations under REACH shape national market access conditions for colorant manufacturers. The North Rhine-Westphalia chemical corridor hosts reformulation R&D facilities responding to ECHA aromatic amine threshold reductions.
France
Parisian salon networks anchor Western European demand for high-service color applications, with client retention tied to personalized shade matching and scalp comfort profiles. ANSM professional-grade labeling requirements enforce strict ingredient disclosure standards for licensed colorists. The Île-de-France cluster absorbs disproportionate volume of imported Japanese botanical colorant technologies through specialized distribution partnerships.
United Kingdom
Home-use digital subscription models in London and Manchester personalize semi-permanent color replenishment through root-growth algorithms and virtual consultation tools. UK REACH retains EU substance restriction frameworks post-Brexit, maintaining alignment with ECHA authorization timelines. Southeast England distribution hubs facilitate cross-border e-commerce fulfillment into Irish and Benelux markets.
Italy
Milan and Barcelona stylists adopt micro-encapsulated dye delivery systems for precision root touch-up applications, compressing service windows while maintaining deposit consistency. CE marking requirements govern cosmetic safety assessments for professional colorant imports. The Lombardy manufacturing belt supplies cream-based formulation packaging to Central European private label programs.
Poland
Warsaw and Krakow professional channels remain underpenetrated relative to Western European service density benchmarks, creating expansion opportunities for salon network investors. Polish chemical regulations transpose REACH substance restrictions with national enforcement through the Chief Sanitary Inspectorate. The Silesian industrial zone hosts contract manufacturing facilities serving German and Austrian brand owners seeking cost-competitive production.
Europe Hair Colorants Market Competitive Landscape
Listed leaders compete with private specialists across formulation technology and channel access dimensions. Three-tier concentration characterizes the structure: multinational beauty conglomerates anchor premium professional tiers, mid-cap regional formulators occupy service-bundled niches, and private equity-backed salon chains control vertical distribution. Strategic archetypes include oxidation dye technology specialists, botanical-positioned natural segment entrants, and direct-to-consumer platform operators. Competitive moves center on reformulation R&D partnerships with Asian ingredient suppliers and territorial exclusivity renegotiations with professional salon networks.
Within the multinational conglomerate tier, L'Oréal S.A. and Henkel AG & Co. KGaA exemplify divergent strategic positioning. The Paris-based S.A. structure anchors extensive professional salon networks spanning metropolitan France and Italy, while the Düsseldorf-based KGaA occupies oxidation dye technology leadership through specialized alkalizing base formulations. Kao Corporation represents the Asia-origin archetype, leveraging Japanese botanical R&D pipelines to compete in European natural-positioned segments through import partnerships rather than local manufacturing.
| Leading Market Players |
|---|
| Kao Corporation |
| Core Equity Holdings (Provalliance) |
| L'Oréal S.A. |
| Laboratorios Phergal S.A. |
| Eugène Perma Professional |
| Henkel AG & Co. KGaA |
| Revlon, Inc. |
| Umberto Giannini Hair Cosmetics Ltd |
| Coty Inc. |
| Others |
Supply & Pricing Matrix
REACH substance authorization through ECHA gates both supplier qualification and price differentiation across European hair colorant tiers, with aromatic amine compliance costs separating premium reformulators from commodity importers while professional salon buyers absorb certified premiums.
Pricing Analysis
Professional salon networks anchor three-tier pricing structure across premium, standard, and economy levels in European hair colorants. Price differentiation rests on ECHA compliance certification and botanical ingredient sourcing tier, with ammonia-free formulations commanding substantial premiums over conventional oxidation systems. Cost compression in economy home-use kits is intensifying because Asian feedstock volatility feeds through to p-phenylenediamine derivatives. Mass-market retail buyers exhibit highest price sensitivity, while licensed colorists in Paris and Frankfurt prioritize performance and scalp safety over per-unit cost.
Supply Chain Analysis
Port congestion on Asia-Europe container lanes elevates inbound logistics costs for Japanese botanical dye intermediates and Chinese coupling agent feedstocks. Manufacturing concentration centers on Germany, France, and Italy for finished formulations, with Poland emerging as contract manufacturing hub for German brand owners. Raw material dependencies include p-phenylenediamine from Asian petrochemical corridors, alkalizing bases from North Rhine-Westphalia chemical clusters, and plant-derived colorants from Japanese R&D pipelines. Single-source vulnerability pervades aromatic amine precursor supply. Distribution runs through professional salon supply houses, mass-market retail chains, and direct-to-consumer platforms with divergent margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European hair colorant markets reward defensive positioning through regulatory entrenchment, where REACH compliance timelines and ECHA authorization requirements create switching costs that lock in professional salon relationships and deter rapid competitive entry.
For Market Incumbents: Shield professional channel exclusivity by renegotiating territorial distribution agreements before authorized e-tailers erode salon loyalty further. Accelerate backward integration into bio-based dye intermediate production to capture EU Green Deal preferential financing and insulate margin structures from Asian petrochemical volatility. Counter home-use subscription encroachment through service-bundled pricing that embeds virtual consultation and root-growth algorithm support.
For New Entrants and Emerging Players: Digital-native home-use consumers in the United Kingdom and Netherlands represent the most penetrable white-space target, where subscription algorithm personalization remains underdeveloped relative to shade-matching sophistication. Polish and Czech Republic professional channels offer second-mover expansion corridors with lower salon density and lighter incumbent saturation. Pursue botanical-positioned natural segment entry through Japanese import partnerships rather than capital-intensive local R&D facilities.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across semi-permanent direct dye manufacturing as micro-encapsulation technology commoditizes. Long-term viability over the next decade favors acquisition targets with established ECHA compliance dossiers and locked professional salon distribution rather than pure-play digital challengers. Watch EMA safety assessment timeline acceleration as the critical inflection signal for portfolio refresh cycle competitiveness.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Reformulation Partnership | ECHA authorization timelines favor early movers with completed substitution dossiers ahead of sunset dates. |
| Professional Salon Network Expansion | Eastern European service density gaps in Warsaw and Krakow absorb Western European brand extension. |
| Bio-Based Dye Intermediate Investment | EU Green Deal carbon footprint mandates unlock preferential financing for botanical R&D pipelines. |
| Direct-to-Consumer Subscription Launch | Root-growth algorithms and virtual shade-matching reduce client leakage from salon-exclusive tiers. |
| Backward Integration into Precursor Supply | Captive p-phenylenediamine sourcing insulates margin compression from Asian petrochemical volatility. |
Research Methodology
Initial hypotheses were tested against primary input from professional salon colorists, cosmetic chemists at German and French formulation houses, procurement leads at retail drugstore chains, and regulatory affairs specialists navigating ECHA authorization timelines, then refined through secondary validation against REACH substance restriction databases, ANSM professional labeling standards, BfR dye evaluations, customs trade flow records, and Nielsen retail audit data across the analysis window, with bottom-up volume builds triangulated against top-down value estimates.
Variance decomposition across product type, formulation chemistry, customer application setting, and distribution channel shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate synthesis rather than single-point extrapolation. Industry-specific forecast inputs incorporated ECHA aromatic amine threshold reduction schedules and professional salon service density differentials between Western and Eastern European metropolitan clusters.
Underlying assumptions cover sustained REACH enforcement intensity, stable Asia-Europe container lane capacity, and continued professional salon channel preference for ammonia-free systems, with deviation risk concentrated in EMA safety assessment timeline delays and p-phenylenediamine feedstock supply disruptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Global Cosmetic Pigments Market
Dyes and Pigments
Arylamide Pigments Market
Dyes and Pigments
Pigment Dispersion Resin Market
Dyes and Pigments
Color Retention Agents Market
Dyes and Pigments
Micronized Color Powder Market
Dyes and Pigments
Inorganic Color Pigments Market
Dyes and Pigments
Bismuth Vanadate Pigment Market
Dyes and Pigments
Ponceau 4R Colors Market
Dyes and Pigments
Erythrosine Market
Dyes and Pigments
Phthalocyanine Pigments Market
Dyes and Pigments
Phosphorescent Pigments Market
Dyes and Pigments
North America Hair Colorants Market
Dyes and Pigments
Quinacridone Pigments Market
Dyes and Pigments
Bio Based Pigments and Dyes Market
Dyes and Pigments
France Aluminium Pigments Market
Dyes and Pigments
Complex Inorganic Color Pigments Market