
 Global Pigments Market | 2026-2036
Global Pigments Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pigments Market Outlook
The gap between premium and commodity pigment tiers is restructuring competitive economics as specialty grades command formulation partnerships while bulk titanium dioxide trades on cost curves. Tronox Holdings Plc leverages vertical integration across mineral sands and chloride-route TiO2 to sustain margin capture. BASF SE anchors its position through high-performance organic pigments for automotive coatings. Sudarshan Chemical Industries Ltd. competes in effect pigments for plastics and cosmetics with India-based manufacturing scale.
Pigments are finely ground insoluble particles, typically 0.1–10 micrometers in diameter, that impart color through selective light absorption and scattering in binders, plastics, or printing vehicles. Their primary commercial purpose spans decorative coatings, functional UV protection, and brand differentiation across consumer and industrial goods. Inorganic pigments, led by titanium dioxide and iron oxides, dominate volume due to opacity and weatherability in construction and automotive coatings. Organic pigments capture faster value growth in high-chroma plastics and electronics applications where heat stability and regulatory compliance command premium positioning. Special effect pigments concentrate margin pools in automotive and luxury packaging segments where visual differentiation drives formulation lock-in.
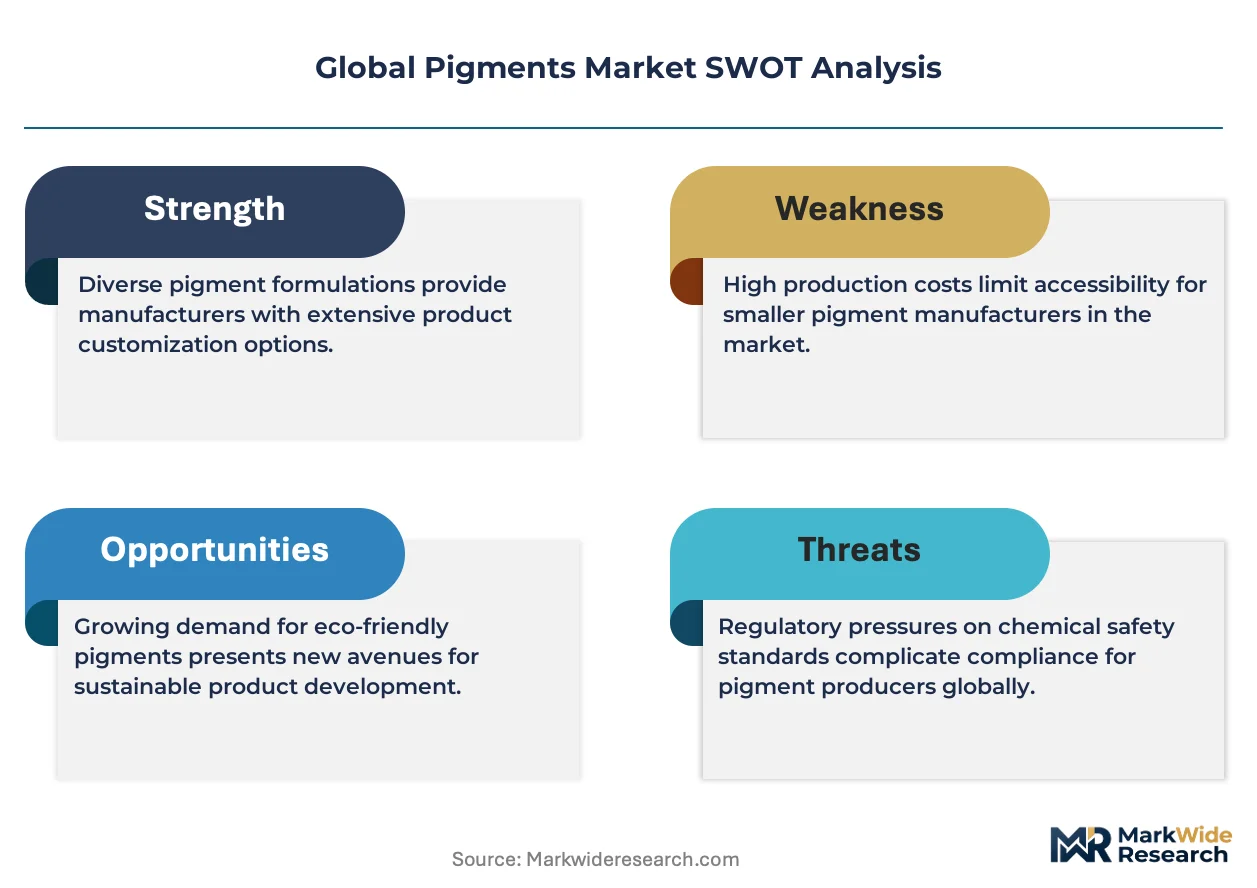
REACH in Europe, EPA regulations under the Toxic Substances Control Act in the United States, and China's MEE environmental compliance standards are tightening permissible heavy metal content and VOC emissions across pigment manufacturing and downstream formulation. These frameworks redirect demand toward aqueous and low-VOC formulation types while raising barriers for unqualified producers. Stakeholders must monitor regulatory divergence across the EU, US, and China to anticipate reformulation costs and raw material qualification timelines.
Market Dynamics
Waterborne coating formulations are compressing solvent-borne pigment demand as automotive OEMs accelerate compliance-driven reformulation across manufacturing clusters.
Growth Catalysts
- REACH Phase-Down:European automotive coatings mandates are redirecting volume toward low-VOC aqueous systems, expanding qualified pigment supplier rosters.
- India Construction:Infrastructure build-out in Gujarat and Maharashtra is concentrating titanium dioxide consumption in decorative coatings.
- Chloride-Route TiO2:Superior opacity and weatherability in automotive clearcoats is displacing sulfate-route material in premium formulations.
Market Restraints
- Ilmenite Concentration:Mineral sands supply clusters in Western Australia and South Africa create feedstock vulnerability for chloride-route producers.
- High-Performance Organic Synthesis:Multi-step azo and phthalocyanine chemistry requires capex-heavy dedicated reactors, limiting new entrant scale.
- Heavy Metal Substitution:Lead chromate and cadmium pigment bans under EPA TSCA and REACH Annex XVII are forcing reformulation costs without direct replacements.
Strategic Opportunities
- Brazil Underpenetration:Decorative coatings per capita consumption lags China by 60%, creating whitespace for iron oxide and TiO2 volume expansion.
- Photovoltaic Encapsulants:Fluoropolymer and ceramic pigments for solar backsheet UV stability represent an emerging specification channel.
- EU Green Deal Procurement:Public infrastructure tenders with embodied carbon scoring favor locally manufactured inorganic pigments.
Industry Challenges
- Colorimetric Talent Scarcity:Formulation chemists with dual expertise in dispersion rheology and regulatory compliance command premium compensation, constraining R&D bandwidth.
- Raw Material Qualification Timelines:Automotive OEM pigment approval cycles extend 18-24 months, freezing supplier switches despite cost advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pigments Market |
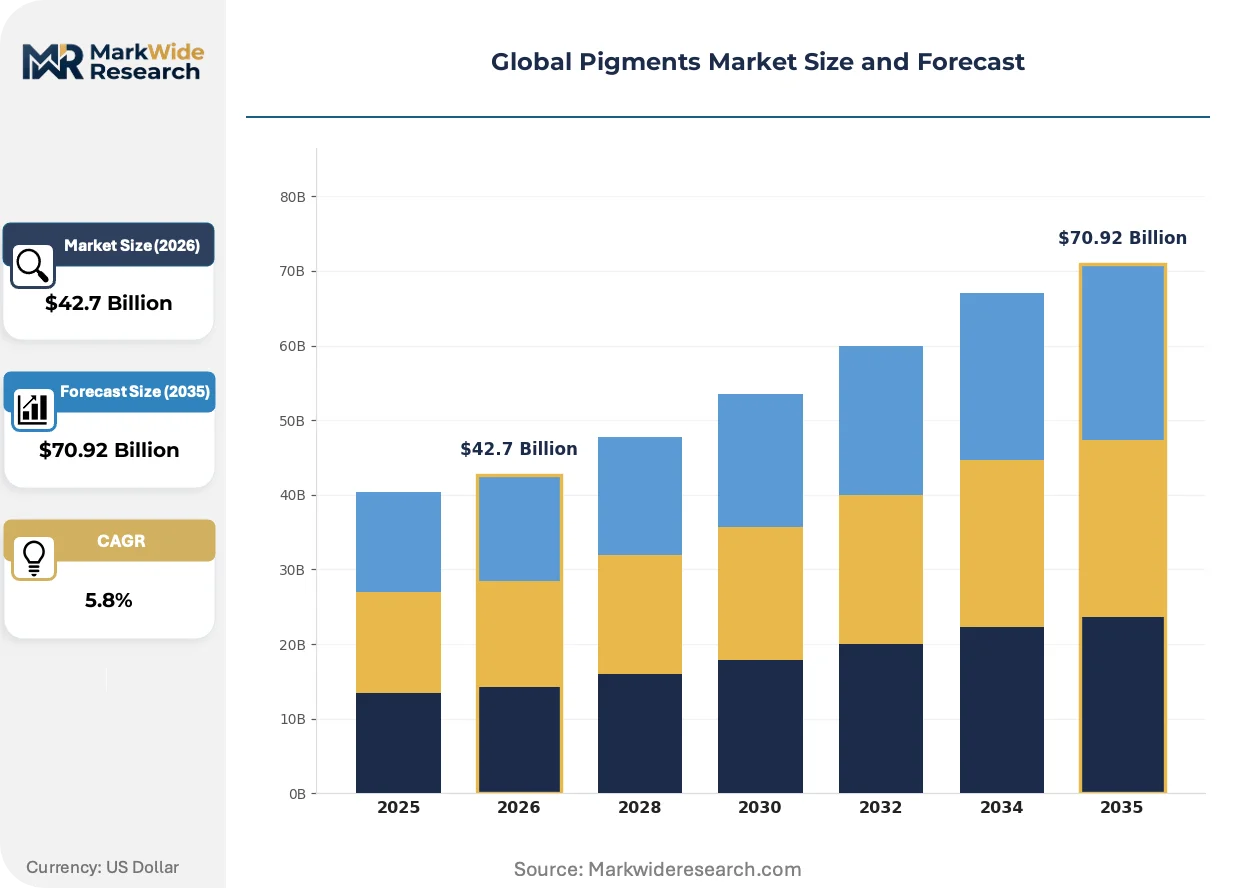
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $70.92 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Pigments, Inorganic Pigments, Special Effect Pigments, Optical Brighteners Application: Coatings, Plastics, Printing Ink, Construction Materials End User: Automotive, Consumer Goods, Electronics, Textiles Formulation Type: Aqueous, Solvent-Based, Powdered, Granular |
| Companies Covered | Tronox Holdings Plc, Kronos Worldwide, Inc., Venator Materials PLC, DIC Corporation, BASF SE, Clariant AG, Lanxess AG, Chemours Company, Sudarshan Chemical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pigments Market Strategic Shifts
Formulation science is pivoting toward bio-based dispersants and nano-scale particle engineering as sustainability metrics penetrate procurement scorecards.
Waterborne high-solids polyurethane dispersions with integrated pigment grinding are overtaking conventional solvent-borne alkyd systems in automotive refinish. Collision repair networks in Germany and Japan are adopting these systems to meet workshop VOC limits. The shift is compressing demand for solvent-compatible organic pigment grades while expanding qualified aqueous pigment portfolios.
China's MEE environmental compliance standards for heavy metal discharge are tightening effluent limits at titanium dioxide and iron oxide production facilities. Pigment manufacturers in Shandong and Sichuan provinces are retrofitting wastewater treatment or relocating to industrial parks with centralized processing. The regulation is accelerating consolidation among smaller sulfate-route TiO2 producers unable to absorb compliance costs.
Coatings procurement by automotive Tier-1 suppliers is consolidating specifications around approved vendor lists with dual-source requirements. Purchasing managers at German and US automotive suppliers are reducing qualified pigment suppliers from 8-10 to 3-4 per color index to simplify supply assurance audits. This concentration is most visible in effect pigments for luxury vehicle exteriors, where formulation lock-in extends across multiple model generations.
Global Pigments Market Segmentation
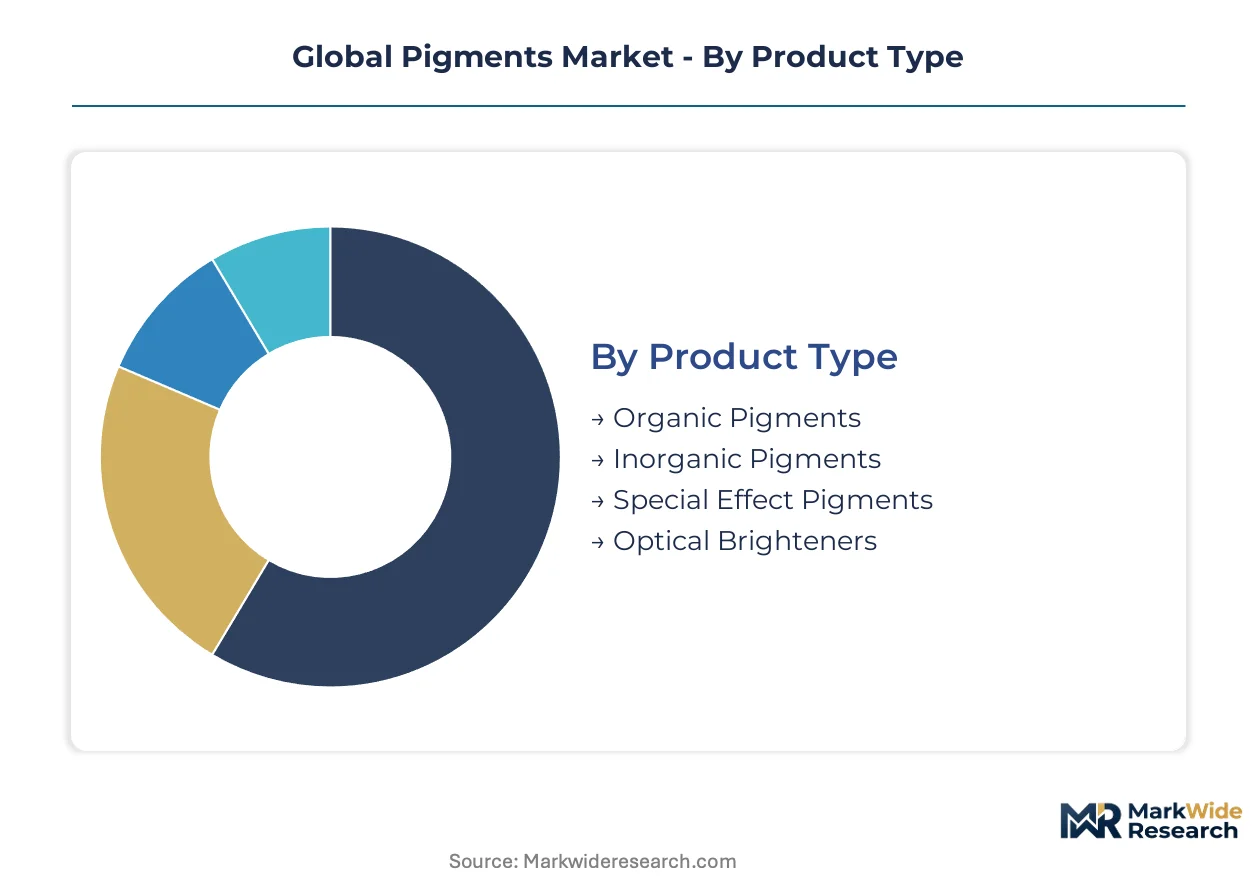
Pigment selection hinges on opacity requirements, thermal stability, and regulatory compliance across downstream formulations. Segmentation reveals how titanium dioxide dominates volume in construction while organic pigments capture premium positioning in automotive and electronics.
Product Type:
Standalone pigment grades serve direct compounding applications, whereas surface-treated variants embed into pre-dispersed masterbatches for automated dosing systems.
- Inorganic Pigments:Titanium dioxide and iron oxide formulations deliver superior weatherability and UV opacity in exterior architectural coatings. Demand clusters in Gujarat and Maharashtra construction corridors where decorative coatings specifications favor sulfate-route TiO2 for cost-sensitive projects.
- Organic Pigments:Azo and phthalocyanine chemistries provide high-chroma coloration with lower density than mineral alternatives. Automotive OEMs in Germany specify these grades for waterborne basecoat systems under REACH-compliant formulations.
- Special Effect Pigments:Pearlescent and interference pigments create visual depth through layered mica or aluminum flake substrates.
- Optical Brighteners:Stilbene derivatives absorb UV radiation and emit blue-white fluorescence for paper and textile applications.
Inorganic pigments lead volumes today; organic pigments are gaining share fastest.
Application:
Cost tier stratification separates commodity volume plays from specification-driven premium channels.
- Coatings:Architectural and automotive formulations consume over half of global TiO2 output, with waterborne systems displacing solvent-borne alternatives under EPA and MEE compliance deadlines.
- Plastics:Masterbatch concentration and heat stability requirements favor cadmium-free organic pigments in polyolefin and engineering resin compounding.
- Printing Ink:Publication gravure and packaging flexo applications drive demand for high-strength pigment dispersions with low millbase viscosity.
- Construction Materials:Concrete coloration and stucco finishes utilize iron oxide pigments for earth-tone palettes with alkali resistance.
Coatings command the largest value pool; plastics applications are climbing the fastest.
End User:
Customer procurement maturity separates long-term formulation partnerships from spot-market purchasing.
- Automotive:OEM specification lock-in extends 18-24 months for approved pigment lists, with German and Japanese manufacturers consolidating suppliers to 3-4 per color index.
- Consumer Goods:Packaging and cosmetic applications prioritize regulatory compliance for heavy metal content under FDA and REACH Annex XVII restrictions.
- Electronics:Display and semiconductor manufacturing require ultra-high purity pigments with controlled particle size distribution.
- Textiles:Dyeing and printing operations favor pigment dispersions compatible with continuous processing equipment.
Automotive end-use dominates premium pricing; electronics represents the steepest expansion trajectory.
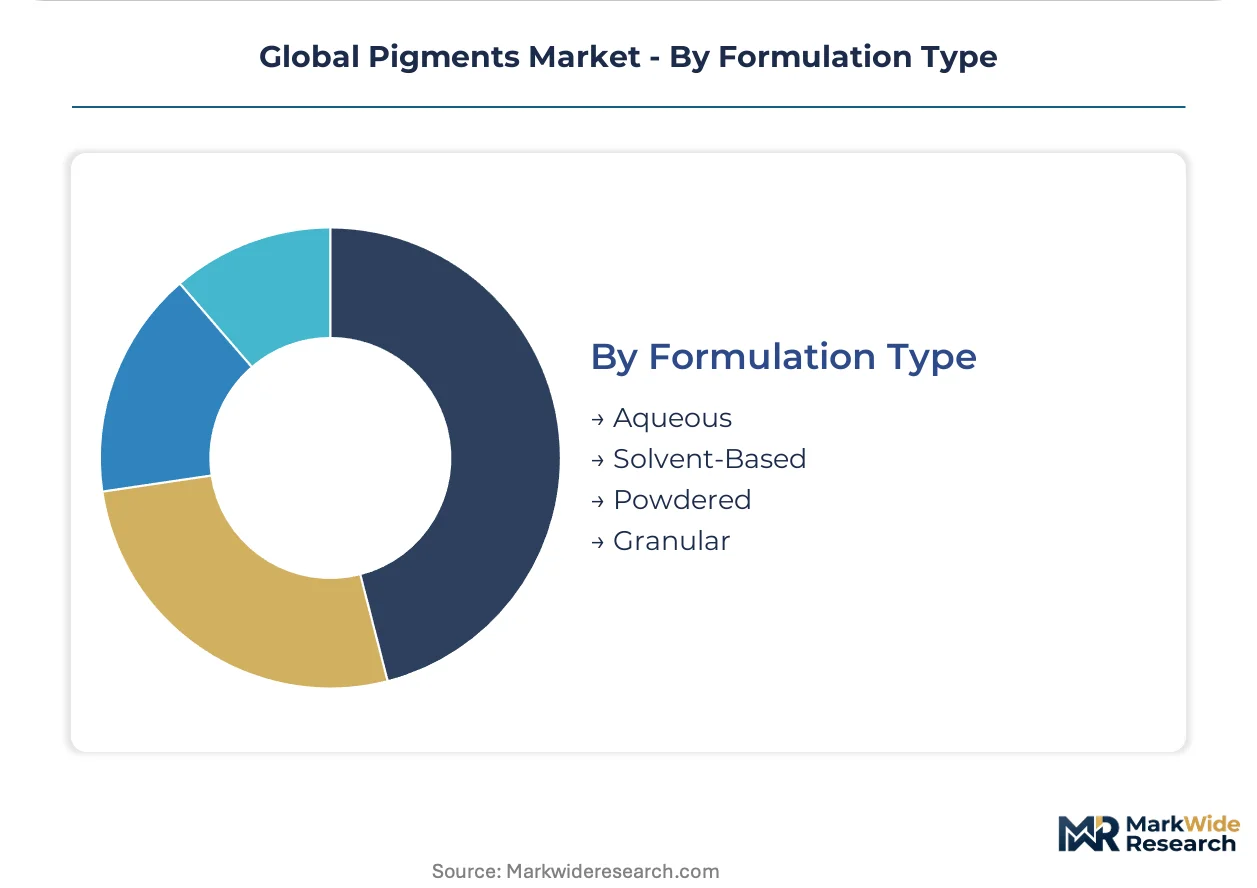
Formulation Type:
Supply concentration in aqueous systems is accelerating as environmental regulations compress solvent-borne alternatives.
- Aqueous:Waterborne dispersions with integrated grinding technology serve automotive refinish and industrial maintenance coatings meeting VOC limits.
- Solvent-Based:Conventional alkyd and polyurethane systems retain niche demand in aerospace and marine applications where corrosion resistance trumps emissions compliance.
- Powdered:Dry pigment grades enable custom compounding in plastics masterbatch operations with controlled dust exposure.
- Granular:Low-dust agglomerated forms improve handling safety and dosing accuracy in automated coating production lines.
Aqueous formulations lead volume conversion; granular formats are expanding most quickly in automated manufacturing environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates premium automotive pigment demand while China dominates titanium dioxide volume, creating divergent competitive dynamics across the value chain.
China
Shandong and Sichuan provinces host sulfate-route TiO2 production clusters serving domestic construction coatings. MEE environmental compliance standards are tightening heavy metal discharge limits, forcing facility relocations to centralized industrial parks. Manufacturers in these provinces face consolidation pressure as smaller producers absorb compliance costs.
Germany
Automotive OEMs in Stuttgart and Munich specify high-performance organic pigments for waterborne basecoat systems. REACH Phase-Down mandates redirect volume toward low-VOC aqueous formulations, expanding qualified supplier rosters. Collision repair networks adopt waterborne high-solids polyurethane dispersions to meet workshop emissions limits.
India
Gujarat and Maharashtra infrastructure build-out concentrates titanium dioxide consumption in decorative coatings. BIS standards govern pigment quality for construction applications. Manufacturing clusters in these states serve both domestic demand and export markets for iron oxide colorants.
United States
EPA regulations under the Toxic Substances Control Act restrict heavy metal content in architectural coatings. Automotive manufacturing corridors in Michigan and Ohio drive demand for chloride-route TiO2 in premium clearcoat formulations. Formulation chemists face qualification timelines extending 18-24 months for OEM approval.
Brazil
Decorative coatings per capita consumption lags China by significant margins, creating volume expansion whitespace for iron oxide and TiO2 suppliers. ANVISA governs heavy metal limits in consumer goods applications. São Paulo and Rio de Janeiro construction markets concentrate pigment distribution infrastructure.
Global Pigments Market Competitive Environment
Top-tier vendors anchor premium formulation partnerships, while commodity producers compete on chloride-route and sulfate-route cost curves. The market structure stratifies across mineral sands-integrated TiO2 specialists, high-performance organic pigment houses, and regional effect pigment manufacturers. Strategic archetypes include backward-integrated mineral sands operators, multi-step synthesis organic pigment specialists, and mica-substrate effect pigment producers. Competitive moves center on captive feedstock security and automotive OEM specification lock-in.
Among publicly traded chemical conglomerates, BASF SE and Clariant AG exemplify the premium organic pigment tier through formulation partnerships with automotive OEMs. Tronox Holdings Plc anchors the mineral sands-integrated archetype with captive ilmenite supply chains. Sudarshan Chemical Industries Ltd. occupies a position within the India-based effect pigment specialization cluster serving plastics and cosmetics applications.
| Leading Market Players |
|---|
| Tronox Holdings Plc |
| Kronos Worldwide, Inc. |
| Venator Materials PLC |
| DIC Corporation |
| BASF SE |
| Clariant AG |
| Lanxess AG |
| Chemours Company |
| Sudarshan Chemical Industries Ltd. |
| Others |
Value Chain & Pricing Dynamics
Formulation chemists with dual expertise in dispersion rheology and regulatory compliance cluster in Germany's Stuttgart-Munich corridor, commanding premium compensation that widens the spread between qualified aqueous pigment grades and commodity sulfate-route alternatives.
Pricing Analysis
Bundled technical service contracts with integrated colorimetric support separate premium organic pigment suppliers from unbundled commodity titanium dioxide traders. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and automotive OEM approval status. Cost compression in sulfate-route TiO2 is intensifying because Chinese MEE environmental compliance is forcing facility relocations. Spot-market buyers in Indian decorative coatings prove most price-sensitive; German automotive OEMs with locked supplier rosters show least sensitivity.
Supply Chain Analysis
Single-source vulnerability sits with Western Australian and South African ilmenite clusters feeding chloride-route TiO2 production. Mineral sands extraction draws from Australia, South Africa, and Madagascar; pigment synthesis feeds from Chinese sulfate-route and German organic specialty operations. Feedstock concentration creates tariff exposure as trade policy shifts. Distribution runs through automotive Tier-1 approved vendor lists with dual-source mandates and construction coatings masterbatch channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where REACH Phase-Down and EPA TSCA mandates continuously reformulate demand toward low-VOC aqueous systems.
For Market Incumbents: Acquire captive mineral sands reserves to secure chloride-route TiO2 feedstock against ilmenite concentration risk. Expand aqueous pigment grinding capacity in Gujarat to capture Indian infrastructure build-out. Lock in automotive OEM specification partnerships before 18-24 month approval cycles freeze supplier switches. For New Entrants and Emerging Players: Bio-based dispersant technology offers a technology-first wedge into sustainability-driven procurement scorecards. Target Brazilian decorative coatings whitespace where per capita consumption lags established markets. Pursue photovoltaic encapsulant pigment specifications as solar backsheet demand emerges. For Investors and Strategic Acquirers: Specialty chemical conglomerates with automotive coatings portfolios are the most active acquirer in this space. Five-to-ten year viability hinges on regulatory compliance infrastructure rather than commodity scale. Monitor EU Green Deal embodied carbon scoring in public infrastructure tenders as inflection signal for local manufacturing premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mineral Sands | Captive ilmenite supply secures chloride-route TiO2 margin capture against feedstock volatility. |
| Aqueous Formulation Capacity Expansion | Gujarat and Maharashtra facilities capture Indian construction coatings volume under BIS standards. |
| Automotive OEM Specification Lock-in | German and Japanese approved vendor list consolidation creates multi-generation formulation partnerships. |
| Green Manufacturing Transition | MEE compliance retrofit in Shandong and Sichuan determines survival for sulfate-route producers. |
| Joint Venture for Effect Pigments | Mica-substrate partnerships with cosmetics and plastics compounders access premium margin pools. |
Study Parameters
Multiple input streams — technical discussions with automotive OEM procurement leads and plant managers, regulatory filings with ECHA and EPA, trade data from customs authorities — were reconciled against SEC disclosures from mineral sands-integrated producers and specialty chemical houses. Primary engagement spanned formulation chemists at German Tier-1 suppliers, distribution channel partners in Indian construction corridors, and R&D directors at effect pigment specialists. Secondary validation drew from Cefic chemical industry reports, ACC sustainability disclosures, and REACH Annex XVII restriction updates. Bottom-up volume modeling triangulated against top-down value chain assessments.
Data-stream reconciliation anchored projections across the analysis window to segment-specific growth trajectories. Modeled dimensions spanned pigment chemistry type, formulation technology, end-use industry, and regional production hub. CAGRs derived from regression analysis of historical volume elasticities against regulatory compliance deadlines and automotive production forecasts. Chloride-route capacity utilization rates and aqueous formulation adoption curves served as industry-specific demand inputs.
The model holds under stable regulatory enforcement timelines; deviation in REACH implementation speed or EPA TSCA expansion would shift reformulation-driven demand. Forecasts embed assumptions about mineral sands supply continuity and automotive OEM supplier consolidation trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Metallic Pigments Market
Dyes and Pigments
Complex Inorganic Color Pigments Market
Dyes and Pigments
Global Paint Pigments Market
Dyes and Pigments
Material Color Matching Booth Market
Dyes and Pigments
North America Hair Colorants Market
Dyes and Pigments
Plastic Pigments Market
Dyes and Pigments
Light Interference Pigments Market
Dyes and Pigments
Organic Pigment Dispersions Market
Dyes and Pigments
Global Thermochromic Materials Market
Dyes and Pigments
Europe Natural Dyes and Pigments Market
Dyes and Pigments
Hair Colorants Market
Dyes and Pigments
Acid Violet 43 Market
Dyes and Pigments
Petroleum-Fuel Dyes and Markers Market
Dyes and Pigments
Global Paper Dyes Market
Dyes and Pigments
South America Hair Colorants Market
Dyes and Pigments
Ultramarine Pigments Market