
 Aluminum Pigments Market | 2026-2036
Aluminum Pigments Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Pigments Market Analysis
A capital-intensity divergence between integrated metal processors and specialty chemical formulators is rotating competitive advantage toward upstream control of atomization and milling infrastructure. ECKART GmbH leverages captive atomization capacity to sustain margin stability across European automotive coating supply chains. Silberline Manufacturing Co., Inc. anchors its position through specialized leafing pigment technology leadership in North American industrial coatings. Hefei Sunrise Aluminium Pigments Co., Ltd. competes on manufacturing scale, dominating cost-sensitive plastics applications across Asia-Pacific markets.
Aluminum pigments are metallic flake powders manufactured through controlled ball milling of atomized aluminum in mineral spirits or solvent carriers, with particle sizes ranging from sub-micron to coarse grades depending on optical performance requirements; their primary industrial purpose is to impart metallic luster, hiding power, and reflective properties to coatings, inks, and polymer compounds. Non-leafing pigments occupy the largest volume share within product type segmentation, as their uniform dispersion characteristics suit waterborne automotive basecoats where leafing chemistry faces compatibility constraints. Physical vapor deposition technology leads technology segmentation for premium cosmetic and electronics applications, while milling remains the workhorse process for industrial coatings where cost efficiency governs procurement decisions.
EPA VOC regulations and REACH restrictions on solvent-borne formulations are forcing coating manufacturers to reformulate aluminum pigment dispersions for lower-emission delivery systems. ECHA classification criteria for aluminum powder hazards further shape handling standards and product registration requirements across European supply chains. China's GB standards on industrial coatings and SAMR product safety oversight add compliance layers for both domestic producers and import brands. Stakeholders must monitor regulatory divergence between low-VOC mandates in mature markets and cost-driven solvent tolerance in emerging economies when allocating R&D and regional production assets.
Market Dynamics
Automotive OEMs in Germany and Japan are expanding metallic coating specifications for electric vehicle bodies, creating sustained pull for high-performance aluminum pigments while REACH compliance and EPA VOC regulations simultaneously tighten formulation standards across major manufacturing regions.
Growth Catalysts
- EV Body Coating Specifications:German and Japanese automotive OEMs are mandating expanded metallic finishes for electric vehicle exteriors, driving specification upgrades across premium and mass-market EV platforms.
- REACH Phase-In Restrictions:ECHA classification criteria for aluminum powder hazards are accelerating reformulation investments toward compliant waterborne and powder coating systems.
- Physical Vapor Deposition:PVD technology adoption in cosmetics and electronics applications is opening premium price tiers for ultra-thin flake geometries with superior optical clarity.
Market Restraints
- Atomized Aluminum Feedstock Volatility:Primary aluminum ingot price swings and energy cost spikes at smelters transmit directly into pigment manufacturing economics, compressing margin stability for non-integrated formulators.
- Solvent-Borne System Decline:EPA VOC regulations and REACH solvent restrictions are structurally shrinking addressable market for traditional mineral spirit dispersions, forcing stranded asset risk on legacy production lines.
- Substitution by Effect Pigments:Pearlescent and interference pigments from mica substrates are capturing share in mid-tier decorative coatings where metallic luster requirements tolerate reduced brilliance.
Strategic Opportunities
- India Industrial Coatings Expansion:BIS standards harmonization and domestic manufacturing incentives under PLI schemes are creating import substitution openings for localized aluminum pigment production.
- Powder Coating Convergence:Binder technology advances enabling direct powder incorporation of aluminum flakes without pre-dispersion are unlocking architectural and appliance coating segments previously closed to metallic effects.
- China Eastern Manufacturing Corridor:SAMR product safety oversight and domestic supplier scale advantages in Jiangsu and Zhejiang provinces are accelerating plastics and packaging application capture from import brands.
Industry Challenges
- Formulation Chemist Shortage:Specialized expertise in waterborne aluminum pigment stabilization and flake surface chemistry modification is concentrating at integrated suppliers, constraining independent formulator R&D velocity.
- Multi-Jurisdiction Registration Burden:Divergent hazard classification between ECHA, EPA, and China's MEE notification requirements is extending product launch timelines and inflating compliance overhead for cross-border portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Pigments Market |
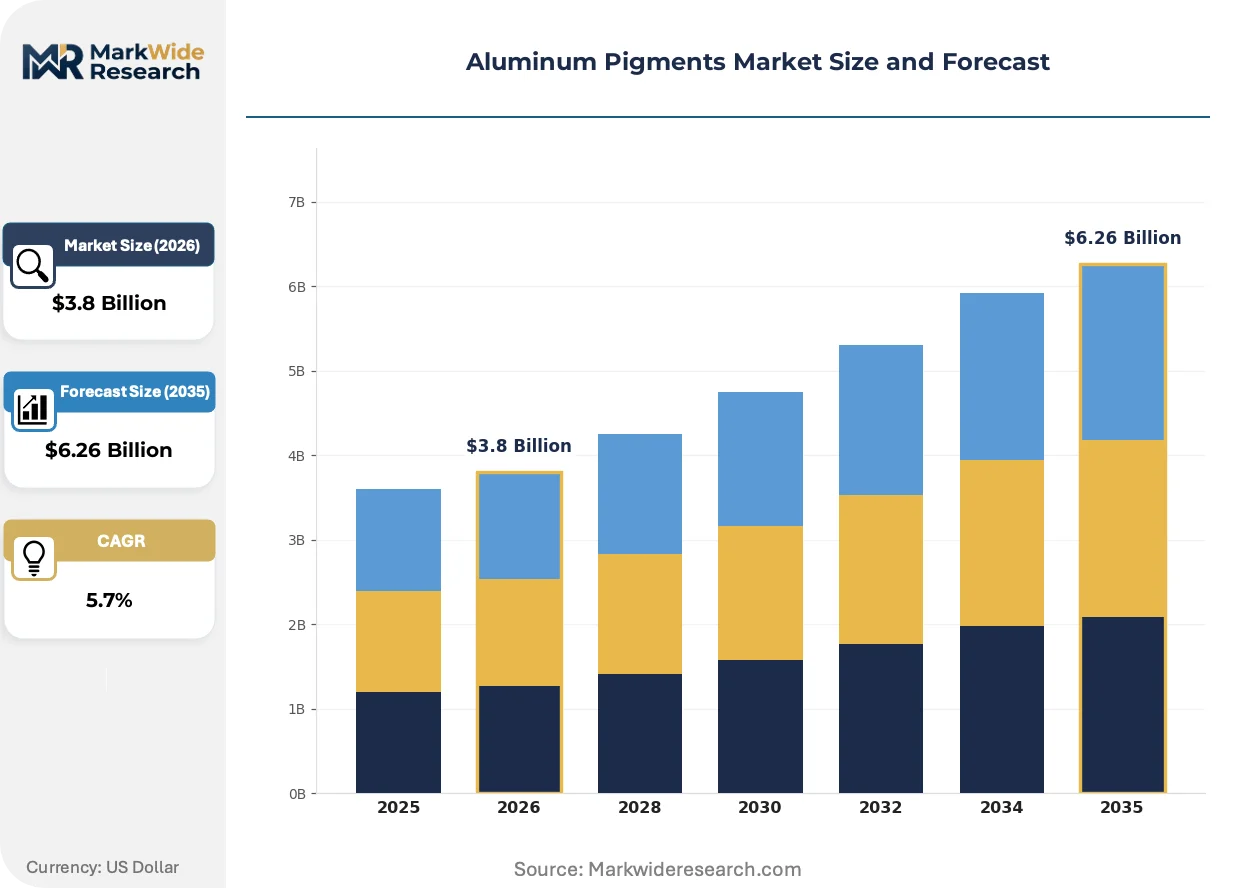
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Leafing Pigments, Non-Leafing Pigments, Coatings, Inks Technology: Physical Vapor Deposition, Chemical Vapor Deposition, Milling, Coating Application: Automotive Coatings, Plastics, Construction Materials, Consumer Goods End Use Industry: Automotive, Aerospace, Packaging, Electronics |
| Companies Covered | Carl Schlenk AG, Silberline Manufacturing Co., Inc., ECKART GmbH, Toyal America, Inc., BASF SE, Asahi Kasei Corporation, ALTANA, Hefei Sunrise Aluminium Pigments Co., Ltd., Metaflake Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Pigments Market Emerging Trajectories
Formulation chemistry and manufacturing process control are converging to enable metallic effects in emission-compliant delivery systems, with particle engineering and surface modification technologies advancing in parallel with regulatory tightening.
Sub-micron aluminum flake production is miniaturizing. Controlled atmosphere ball milling with ceramic grinding media now achieves D50 particle sizes below 5 micrometers for cosmetic and electronics applications. Premium skincare brands and smartphone chassis manufacturers are specifying these ultra-fine grades for mirror-like finishes without visible texture. This particle size compression is miniaturizing the boundary between decorative coatings and functional thin-film applications.
REACH restrictions on solvent-borne aluminum pigment systems are tightening across European supply chains. ECHA's updated classification criteria for aluminum powder hazards are forcing reformulation investments and specialized handling infrastructure. Waterborne automotive basecoat manufacturers in Germany and France are accelerating qualification programs for non-leafing pigment dispersions compatible with existing electrodeposition primer systems.
Automotive coating procurement is consolidating specification authority at OEM central engineering centers, displacing historical tier-1 supplier formulation autonomy. German and Japanese manufacturers now mandate direct pigment qualification against proprietary performance matrices. This centralization is most visible in EV platform launches where metallic color consistency across multiple assembly plants requires locked formulation parameters.
Aluminum Pigments Market Segmentation
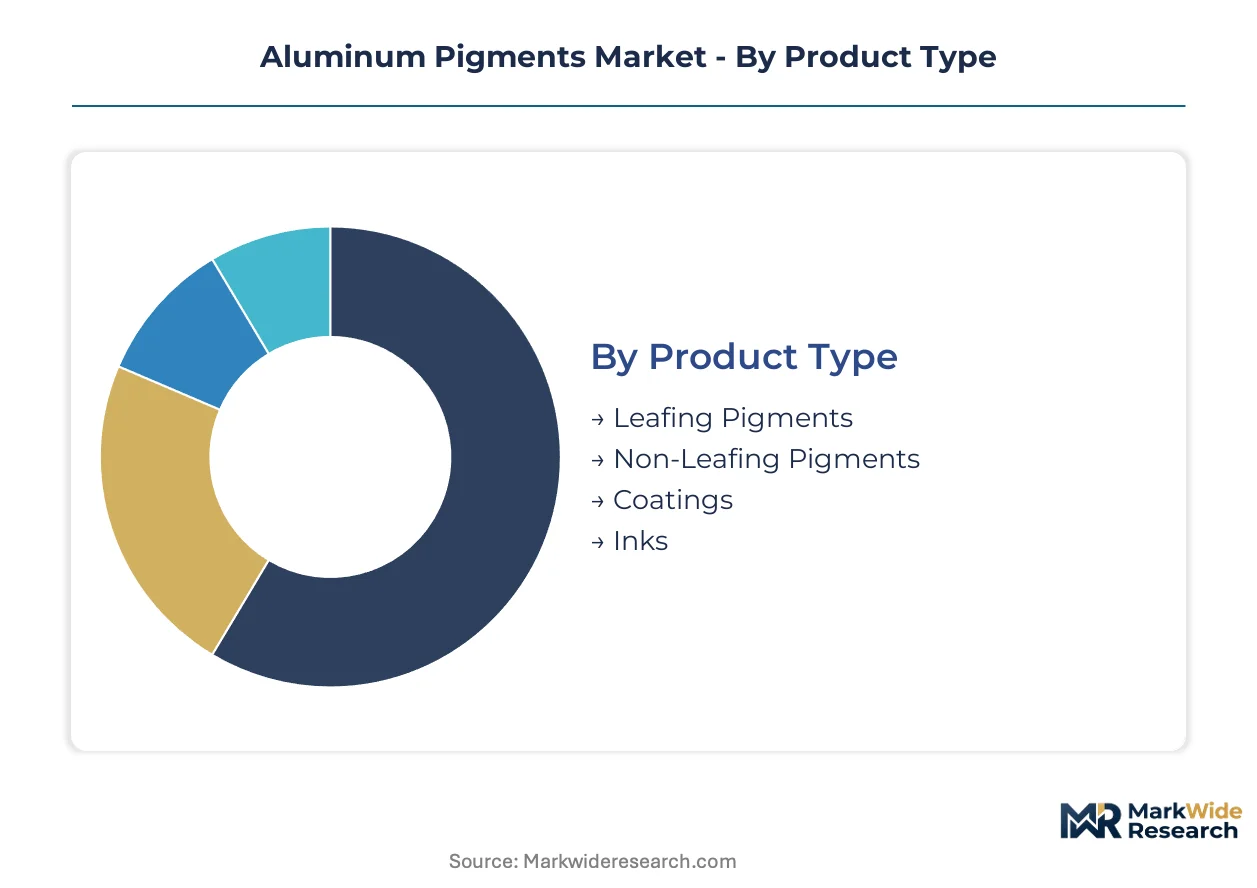
Aluminum pigment procurement channels diverge sharply by segment. Automotive OEMs centralize specifications through direct supplier qualification, while plastics and packaging buyers route through distributor networks serving fragmented compounders.
Product Type:
Channel mix varies by leafing chemistry. Non-leafing dispersions flow through waterborne coating system houses, while leafing grades concentrate in solvent-borne industrial channels.
- Non-Leafing Pigments:Uniform dispersion in waterborne systems suits automotive basecoat applications where electrodeposition primer compatibility is mandatory. German and Japanese EV manufacturers are expanding qualification programs for these grades across multi-plant coating operations.
- Leafing Pigments:Surface-oriented flake alignment creates bright metallic effects in protective industrial coatings. Demand clusters in North American maintenance coatings where solvent tolerance persists despite regulatory pressure.
- Coatings:Pre-dispersed paste and slurry formulations reduce handling complexity for mid-tier applicators.
- Inks:Fine particle grades serve narrow-web flexographic and gravure printing for decorative packaging.
By volume, Non-Leafing Pigments leads. By growth pace, Coatings is ahead as dispersion outsourcing accelerates among smaller formulators.
Technology:
Cost tier stratification separates premium deposition methods from commodity milling operations serving price-sensitive industrial coatings.
- Milling:Ball milling of atomized aluminum in mineral spirits remains the dominant production method for industrial-grade flake. Chinese suppliers in Jiangsu and Zhejiang provinces leverage scale economies to capture plastics and packaging demand from import brands.
- Physical Vapor Deposition:Vacuum deposition produces ultra-thin flakes with superior optical clarity for cosmetic and electronics applications. Premium skincare brands and smartphone chassis manufacturers specify these grades for mirror finishes without visible texture.
- Chemical Vapor Deposition:Gas-phase synthesis enables precise thickness control for specialized optical applications.
- Coating:Surface encapsulation technologies improve weatherability and chemical resistance in exterior architectural applications.
Milling commands volume leadership. PVD claims the steepest expansion trajectory as electronics and cosmetics specifications tighten.
Application:
Customer type concentration drives channel selection. Automotive central engineering teams dictate specifications directly, while construction and consumer goods buyers rely on regional distributor inventories.
- Automotive Coatings:Metallic basecoats and clearcoat systems for vehicle exteriors require locked formulation parameters across multiple assembly plants. German OEMs now mandate direct pigment qualification against proprietary performance matrices.
- Plastics:Masterbatch integration for polymer compounds serves packaging, appliance, and consumer durable segments. China's eastern manufacturing corridor dominates this application through domestic supplier scale advantages.
- Construction Materials:Coil coatings and architectural finishes specify weather-resistant flake grades for exterior durability.
- Consumer Goods:Cosmetic packaging and personal care applications drive sub-micron particle demand.
Automotive Coatings holds volume dominance. Plastics is expanding most quickly as polymer compounders upgrade metallic effect capabilities.
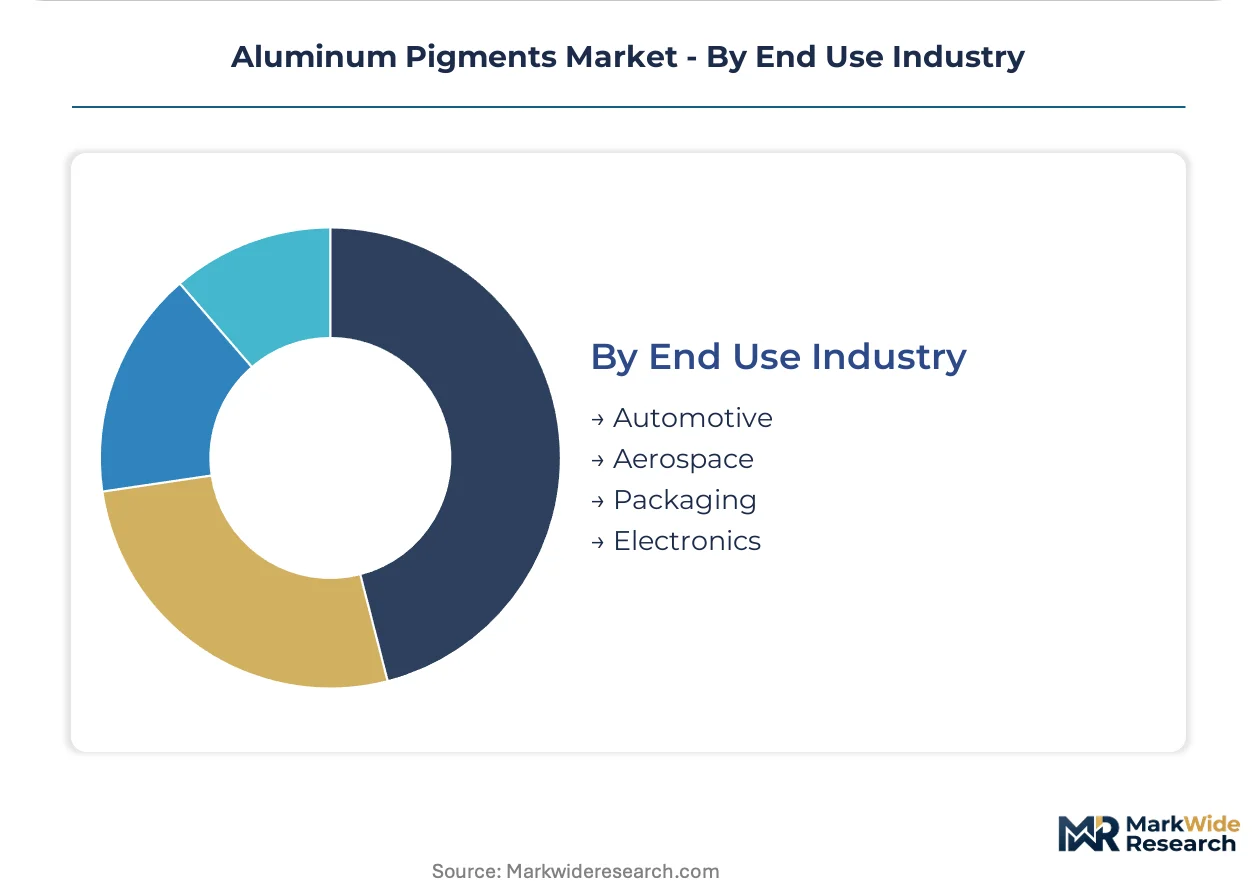
End Use Industry:
Supply concentration aligns with geographic manufacturing clusters. Automotive and electronics anchor developed market demand, while packaging growth concentrates in Asia-Pacific manufacturing corridors.
- Automotive:EV platform launches in Germany and Japan are expanding metallic coating specifications across premium and mass-market electric vehicle bodies. REACH compliance and EPA VOC regulations are forcing simultaneous reformulation investments.
- Packaging:Flexible packaging and rigid container applications for food, beverage, and personal care products. China's domestic suppliers are capturing share from import brands in this cost-sensitive segment.
- Aerospace:Protective coatings for airframe and component applications requiring corrosion resistance and weight optimization.
- Electronics:Smartphone chassis, laptop housings, and wearable device finishes specify ultra-thin PVD flakes.
Automotive leads by volume. Electronics is gaining share fastest as device manufacturers specify premium metallic finishes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China's eastern manufacturing corridor exhibit extreme price elasticity, squeezing margins on commodity pigment grades, while German automotive OEMs prioritize specification compliance over cost, creating a demand-elasticity contrast that shapes regional competitive positioning.
China
Domestic suppliers in Jiangsu and Zhejiang provinces dominate plastics and packaging applications through manufacturing scale advantages. SAMR product safety oversight and GB standards on industrial coatings add compliance layers for import brands competing in this cost-sensitive environment. The Yangtze River Delta manufacturing cluster captures share from international pigment suppliers in masterbatch integration for polymer compounds.
Germany
Automotive OEMs mandate direct pigment qualification against proprietary performance matrices for EV platform launches. REACH compliance and ECHA classification criteria for aluminum powder hazards force reformulation investments toward waterborne systems. The Bavaria and Baden-Württemberg automotive engineering corridors concentrate specification authority at central engineering centers, displacing tier-1 supplier formulation autonomy.
United States
EPA VOC regulations structurally shrink addressable market for traditional mineral spirit dispersions, forcing stranded asset risk on legacy production lines. Silberline Manufacturing anchors specialized leafing pigment technology leadership in North American industrial coatings. The Great Lakes manufacturing region maintains solvent tolerance in maintenance coatings despite regulatory pressure, sustaining demand for conventional pigment grades.
Japan
METI industrial standards and automotive OEM metallic coating specifications for electric vehicle bodies drive premium pigment demand. JIS standards harmonize with German qualification protocols, enabling cross-platform pigment approvals. The Kanto and Kansai automotive clusters expand metallic finish mandates across mass-market EV platforms, creating specification pull for high-performance grades.
India
BIS standards harmonization and PLI scheme domestic manufacturing incentives create import substitution openings for localized aluminum pigment production. CDSCO notification requirements for industrial chemical imports extend launch timelines for cross-border portfolios. The Maharashtra and Gujarat industrial corridors attract capacity investments targeting plastics compounding and coil coating applications.
Aluminum Pigments Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the aluminum pigments market. Integrated metal processors with captive atomization capacity command margin stability across volatile feedstock cycles, while specialty chemical formulators compete through formulation expertise and application-specific qualification relationships. Three archetypes define competitive positioning: upstream-integrated pigment manufacturers, specialized leafing technology specialists, and scale-driven regional suppliers serving cost-sensitive segments. Capacity expansion in Asia-Pacific manufacturing corridors and strategic partnerships for waterborne dispersion technology represent the dominant competitive moves reshaping market structure.
Within the integrated tier, ECKART GmbH exemplifies upstream control over atomization and milling infrastructure sustaining margin stability across European automotive supply chains. Silberline Manufacturing Co., Inc. occupies a position representing specialized leafing pigment technology leadership in North American industrial coatings. Hefei Sunrise Aluminium Pigments Co., Ltd. anchors the scale-driven archetype, competing on manufacturing scale to dominate cost-sensitive plastics applications across Asia-Pacific markets. These three companies collectively illustrate the capital-intensity divergence rotating competitive advantage toward infrastructure control versus formulation specialization.
| Leading Market Players |
|---|
| Carl Schlenk AG |
| Silberline Manufacturing Co., Inc. |
| ECKART GmbH |
| Toyal America, Inc. |
| BASF SE |
| Asahi Kasei Corporation |
| ALTANA |
| Hefei Sunrise Aluminium Pigments Co., Ltd. |
| Metaflake Ltd. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between atomized aluminum suppliers and integrated pigment manufacturers lock in feedstock access and price visibility across volatile primary metal cycles. These arrangements concentrate bargaining power with upstream metal processors in Germany and China while exposing non-integrated formulators to spot market volatility.
Pricing Analysis
After-sales technical service and reformulation support drive lifetime value in automotive coating qualifications. Three-tier pricing structure across premium PVD grades, standard waterborne dispersions, and economy solvent-borne pastes reflects certification tier and volume scale. Cost compression in commodity milling grades is intensifying because Chinese suppliers in Jiangsu and Zhejiang provinces are capturing plastics applications through manufacturing scale. Plastics compounders exhibit extreme price sensitivity, while German automotive OEMs prioritize REACH-compliant qualification over cost.
Supply Chain Analysis
Inventory cycles for atomized aluminum feedstock extend lead times during energy price spikes at primary smelters. Supply concentrates in China, Germany, and the United States for integrated pigment manufacturing, with the Yangtze River Delta and Bavaria hosting captive atomization infrastructure. Raw material flows draw from primary aluminum ingot markets, ceramic grinding media suppliers, and mineral spirits distributors. Single-source vulnerability in atomized aluminum feedstock creates structural risk during smelter curtailments. Distribution runs through direct OEM qualification channels for automotive coatings and regional distributor networks for plastics masterbatch integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating at German and Japanese automotive OEM central engineering centers, displacing tier-1 supplier formulation autonomy and squeezing margin capture opportunities for independent pigment formulators.
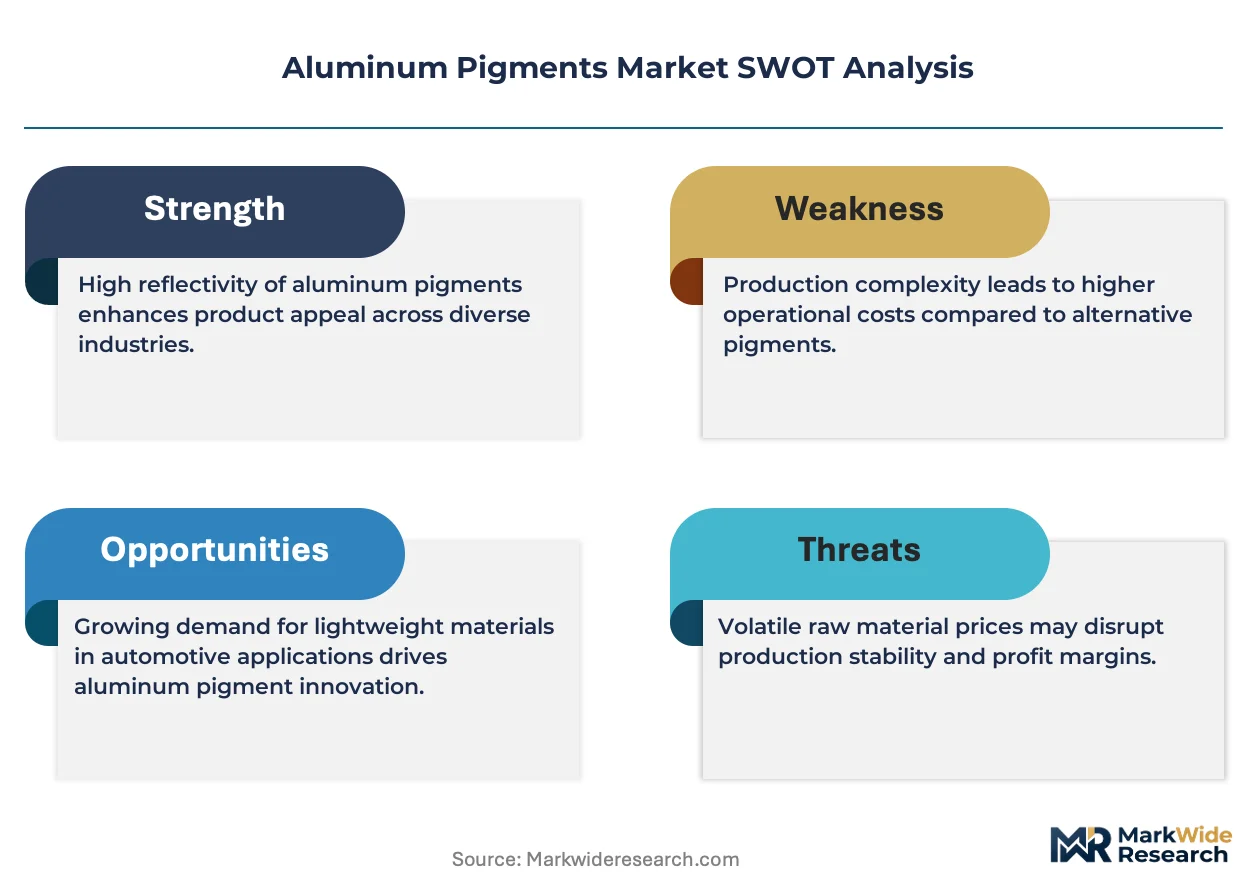
For Market Incumbents: Compound captive atomization capacity through backward integration into primary aluminum supply or milling infrastructure acquisition in China's eastern manufacturing corridor. ECKART GmbH's margin stability model demonstrates how upstream control insulates against feedstock volatility. Prioritize waterborne dispersion R&D to capture reformulation mandates from REACH and EPA VOC regulatory tightening. For New Entrants and Emerging Players: Differentiate on powder coating direct-incorporation technology for architectural and appliance segments previously closed to metallic effects. India's Maharashtra and Gujarat industrial corridors present the most penetrable geography under BIS standards harmonization and PLI manufacturing incentives. Pursue qualification partnerships with domestic coil coating formulators seeking import substitution. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated suppliers with locked automotive OEM qualification relationships spanning multiple EV platform launches. Five-to-ten year viability favors upstream-integrated archetypes over pure-play formulators exposed to solvent-borne system decline. Monitor ECHA classification criteria evolution as the signal for accelerated waterborne transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Atomization | Captive aluminum powder production secures margin stability against LME volatility. |
| Waterborne Dispersion Capacity Expansion | REACH and EPA compliance mandates accelerate qualification programs at German OEMs. |
| Powder Coating Technology Partnership | Binder advances unlock architectural segments for direct flake incorporation. |
| India Localization Investment | BIS harmonization and PLI incentives create import substitution openings. |
| Sub-micron PVD Scale-Up | Cosmetics and electronics specifications drive premium pricing for ultra-thin grades. |
Methodological Framework
Desk research of customs trade data, SEC filings from coating system houses, and ECHA registration databases preceded structured interviews with automotive OEM coating specification engineers, pigment plant managers, plastics masterbatch procurement leads, and waterborne formulation R&D directors. Primary fieldwork with German and Chinese suppliers validated secondary estimates of atomization capacity and milling output. Bottom-up volume modeling triangulated against top-down end-use industry consumption estimates.
Variance decomposition across product type, technology method, application segment, and end-use industry dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation with macroeconomic drivers including EV production forecasts and regulatory phase-in timelines. Modeled inputs incorporated REACH restriction implementation schedules, primary aluminum smelter energy cost trajectories, and powder coating adoption curves.
Forecasts assume regulatory continuity in EU REACH, US EPA VOC, and China GB standards regimes; material policy shifts would require re-modeling of solvent-borne system decline rates and waterborne qualification timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Cadmium Pigments Market
Dyes and Pigments
Middle East and Africa Hair Colorants Market
Dyes and Pigments
Reactive Dyes Market
Dyes and Pigments
Acrylic Colors Market
Dyes and Pigments
Methylene Blue Market
Dyes and Pigments
Acid Violet 43 Market
Dyes and Pigments
Global Aluminum Anodizing Dyes Market
Dyes and Pigments
Global Cosmetic Pigments Market
Dyes and Pigments
North America Hair Colorants Market
Dyes and Pigments
Thermochromic Labels Market
Dyes and Pigments
Colorants Market
Dyes and Pigments
Iridescent Pigments Market
Dyes and Pigments
Laser Sensitive Pigments Market
Dyes and Pigments
Global Paint Pigments Market
Dyes and Pigments
Natural Colorants Market
Dyes and Pigments
Lithol Rubine BK Market