
 Dyestuff (Black Color) Market | 2026-2036
Dyestuff (Black Color) Market Size, Share, and Industry Trends Forecast 2026-2036
Dyestuff (Black Color) Market Foresight
Automotive OEM specifications for deep-black exterior finishes is collapsing legacy volume from standard textile dyeing, forcing pigment houses to rebalance capacity toward coatings-grade production. BASF SE leverages its integrated precursor network in Ludwigshafen to secure feedstock for automotive black pigments. DyStar Group anchors its position through reactive black specialization across Asian textile hubs. Lanxess AG competes on technical-grade aniline black for industrial rubber and plastics compounding.
Dyestuff (Black Color) comprises synthetic organic colorants engineered to absorb visible light across the spectrum, with carbon black, aniline black, and reactive black variants distinguished by particle size, jetness index, and dispersion stability in target substrates. These materials serve to impart opacity, UV protection, and aesthetic depth across coatings, fibers, and polymer matrices. Reactive black dyes command premium positioning in textile applications due to covalent bonding with cellulose fibers, while aniline black retains dominance in leather finishing and industrial coatings where solvent resistance proves critical. Powder formulations sustain broader geographic distribution than liquid alternatives, though paste concentrates capture margin pools in automated dosing systems at large textile manufacturers.
EPA oversight of benzidine-derivative dyes under the Toxic Substances Control Act constrains certain azo-based black formulations in US commerce, while REACH Annex XVII restrictions on aromatic amines reshape European import specifications. China's MEE enforcement of wastewater discharge standards for dye intermediates is forcing capacity consolidation in Zhejiang Longsheng Group Co's home province. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and reformulation costs.
Market Dynamics
Automotive OEMs are forcing a structural reallocation of black pigment capacity from textile dyeing to coatings-grade production, collapsing legacy volume commitments and rewiring supplier priorities across the value chain.
Growth Catalysts
- REACH Annex XVII aromatic amine limits:European formulators are redirecting investment toward waterborne black dye systems that eliminate restricted intermediates, opening margin pools for compliant producers.
- Automotive exterior palette darkening:OEM specifications for deep-black finishes with enhanced jetness indices are pulling capacity away from commodity textile grades toward high-performance pigment dispersions.
- Zhejiang-Jiangsu chemical cluster concentration:China's integrated intermediate-to-dye production corridors supply the majority of global reactive black capacity, anchoring cost-competitive export supply.
Market Restraints
- Petroleum-derived precursor volatility:Aniline and naphthalene feedstock costs swing with crude oil benchmarks, compressing margin stability for aniline black producers.
- Single-province supply concentration:Zhejiang province hosts disproportionate reactive black intermediate capacity, creating geographic vulnerability to localized environmental enforcement actions.
- Aqueous system performance gaps:Waterborne black pigments still lag solvent-based alternatives in gloss retention and substrate adhesion for industrial coatings applications.
Strategic Opportunities
- India technical textile expansion:The country's PLI scheme for man-made fiber apparel is generating pull for reactive black dyes in denim and activewear segments.
- Bio-based carbon black development:Pyrolysis of agricultural waste and tire recycling streams offers pathway to renewable black pigment feedstocks for sustainability-positioned brands.
- Automated dosing system integration:Paste concentrate formats capture service revenue pools at large textile manufacturers seeking closed-loop color kitchens.
Industry Challenges
- Colorimetric formulation expertise scarcity:Jetness optimization and dispersion stability engineering require specialized knowledge that aging workforce demographics are depleting.
- Multi-jurisdiction compliance synchronization:Divergent EPA benzidine-derivative restrictions, REACH aromatic amine limits, and MEE wastewater standards force parallel formulation tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dyestuff (Black Color) Market |
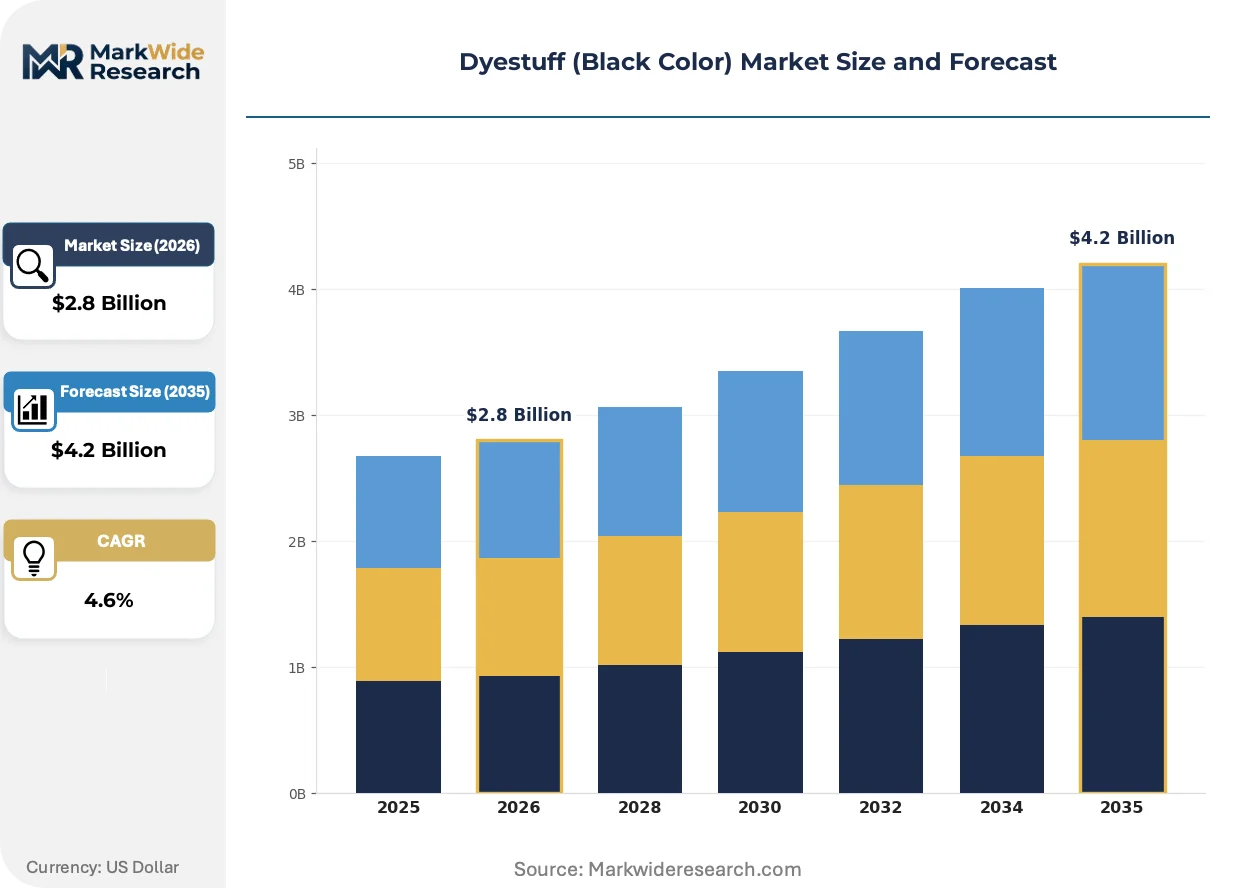
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Azo Dyes, Aniline Black, Reactive Black, Direct Black Application: Textiles, Coatings, Plastics, Papers End User: Textile Manufacturers, Paint Producers, Plastic Industries, Paper Mills Form: Liquid, Powder, Granular, Paste |
| Companies Covered | BASF SE, DyStar Group, Clariant AG, Huntsman Corporation, Lanxess AG, Archroma, Kiri Industries Limited, Sumitomo Chemical Company Ltd, Zhejiang Longsheng Group Co, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dyestuff (Black Color) Market Shifts & Advancements
Formulation science is splitting between high-performance automotive specifications and cost-optimized textile grades, with regulatory chemistry constraints forcing parallel development tracks that reshape competitive capabilities.
Surface-functionalized carbon black is bifurcating the market between commodity furnace blacks and dispersion-optimized grades engineered for waterborne automotive clearcoats. Tier 1 coatings suppliers are qualifying these modified pigments at accelerated timelines to meet OEM sustainability scorecards. The technology is bifurcating supplier tiers, separating integrated producers with precursor control from compounders dependent on merchant carbon black.
ECHA's restriction of polycyclic aromatic hydrocarbons in consumer articles is forcing leather finishers to abandon certain aniline black formulations and validate alternative nitrogen-based black dyes. Tanneries serving EU automotive upholstery contracts face reformulation timelines compressed by certification renewal cycles. Italian and Spanish leather clusters are absorbing disproportionate compliance costs as they serve luxury automotive seating programs.
Specification-driven vendor consolidation is concentrating textile procurement at vertically integrated dye houses capable of guaranteeing batch-to-batch Delta E consistency. Automated shade matching and digital color communication are displacing traditional lab dip approval workflows at large garment manufacturers. Bangladesh and Vietnam apparel exporters are most exposed to this transition as they serve fast-fashion replenishment programs with compressed lead times.
Dyestuff (Black Color) Market Segmentation
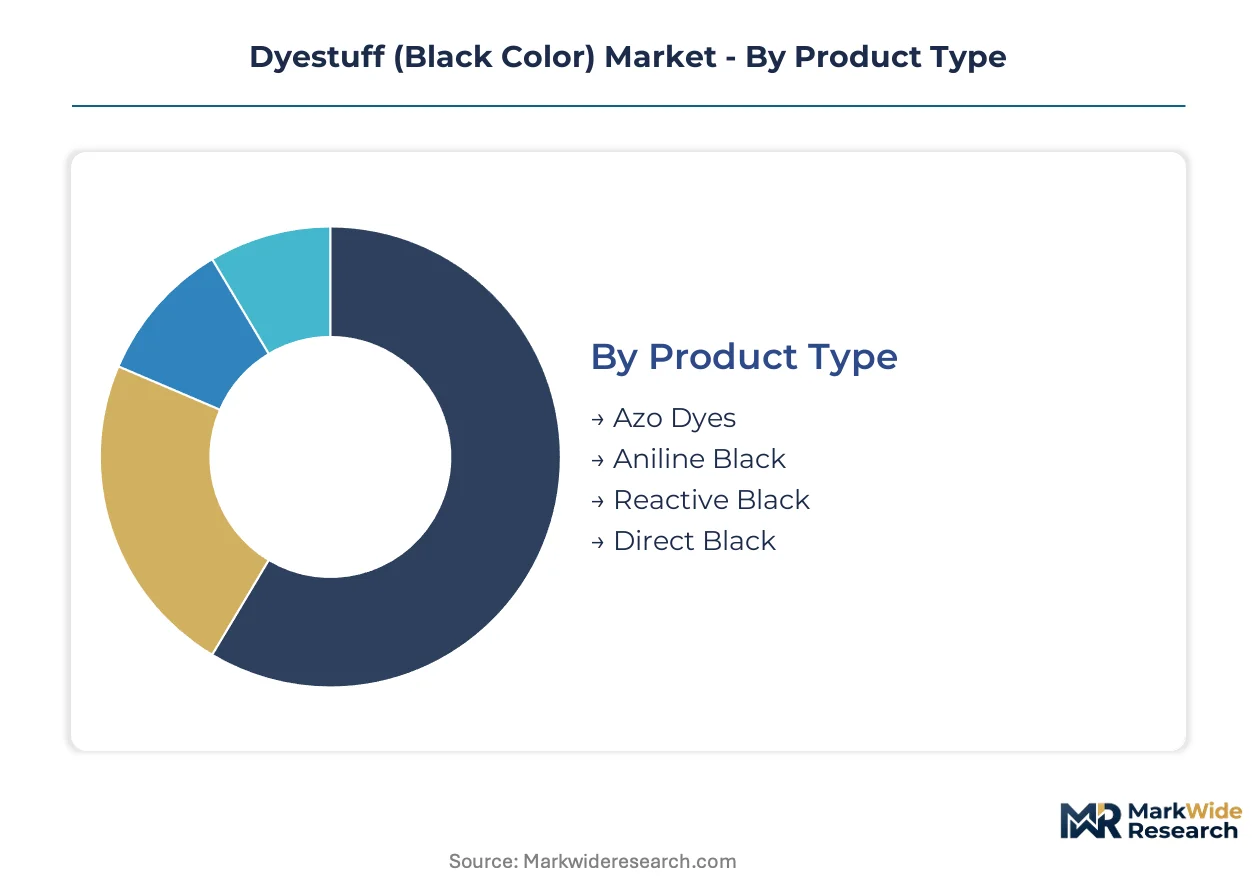
Black dyestuff procurement splits sharply between commodity textile volumes and specification-driven coatings grades, with margin capture diverging across molecular architectures and physical delivery formats. Suppliers must position simultaneously for cost-optimized cellulose dyeing and jetness-critical automotive pigment dispersions.
Product Type:
Premium pricing concentrates in reactive and aniline black variants where covalent bonding chemistry and solvent resistance command formulation value.
- Reactive Black:These dyes form permanent covalent bonds with cellulose fibers through nucleophilic substitution reactions, delivering wash-fastness that commands premium positioning in denim and activewear manufacturing. Demand clusters in Bangladesh and Vietnam garment export zones where brands enforce Delta E color consistency across replenishment cycles.
- Aniline Black:Oxidative polymerization of aniline hydrochloride yields this pigment with exceptional solvent resistance and lightfastness, preserving dominance in leather finishing and industrial coatings. Italian and Spanish tanneries serving EU automotive upholstery contracts absorb disproportionate reformulation costs as ECHA polycyclic aromatic hydrocarbon restrictions force validation of alternative nitrogen-based formulations.
- Azo Dyes:Cost-optimized chromophores for commodity textile dyeing where EPA benzidine-derivative restrictions under the Toxic Substances Control Act constrain certain molecular architectures in US commerce.
- Direct Black:Salt-containing dyes for simplified cellulose application without fixation chemistry, capturing volume in budget textile segments.
The dominant share belongs to Reactive Black, while Aniline Black is closing the gap fastest as automotive coatings specifications intensify.
Application:
Automotive exterior palette darkening is collapsing legacy textile volume commitments toward coatings-grade pigment dispersions with enhanced jetness indices.
- Coatings:Automotive OEM specifications for deep-black finishes with superior gloss retention are pulling capacity from commodity grades. Surface-functionalized carbon black variants engineered for waterborne clearcoats separate integrated producers with precursor control from compounders dependent on merchant supply.
- Textiles:Reactive black dyes serve cotton, viscose, and lyocell fibers across denim, knitwear, and home textile segments. Zhejiang and Jiangsu province chemical clusters supply the majority of global capacity, anchoring cost-competitive export supply to Bangladesh and Vietnam garment manufacturers.
- Plastics:Masterbatch and compound applications for automotive interior trim, electronics housings, and packaging where dispersion stability determines processing throughput.
- Papers:Specialty packaging and decorative laminate applications with moderate performance requirements.
Coatings commands the steepest expansion trajectory as OEM sustainability scorecards accelerate qualification timelines for waterborne systems.
End User:
Procurement sophistication varies sharply between automated color kitchen operators and manual dosing facilities, determining format preference and service revenue capture.
- Paint Producers:Tier 1 automotive coatings suppliers qualify dispersion-optimized pigments at compressed timelines to meet jetness and gloss specifications. REACH Annex XVII aromatic amine limits redirect investment toward waterborne systems that eliminate restricted intermediates.
- Textile Manufacturers:Large garment exporters in Bangladesh and Vietnam deploy automated shade matching and digital color communication, displacing traditional lab dip workflows. Specification-driven vendor consolidation concentrates procurement at vertically integrated dye houses capable of guaranteeing batch-to-batch consistency.
- Plastic Industries:Masterbatch compounders and OEMs seeking UV protection and aesthetic depth across interior and exterior polymer applications.
- Paper Mills:Packaging and specialty paper producers with standardized color matching requirements.
Paint Producers hold the dominant position, while Textile Manufacturers are gaining share fastest through digital color kitchen investments.
Form:
Physical delivery format determines geographic reach and margin capture, with paste concentrates securing service revenue at automated facilities.
- Powder:Dry formulations sustain broader geographic distribution through lower transport costs and extended shelf stability. Standard packaging for commodity textile dyeing across developing manufacturing bases.
- Paste:Concentrated dispersions capture margin pools at large textile manufacturers operating closed-loop color kitchens with automated dosing systems. Service revenue attaches to technical support and inventory management.
- Liquid:Ready-to-use solutions for small-batch processors lacking dispersion equipment, carrying premium pricing for convenience.
- Granular:Dust-free handling formats for occupational health compliance in high-volume dye houses.
Powder retains the dominant share, while Paste is climbing the fastest as automation penetrates large textile manufacturing facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zhejiang and Jiangsu provinces command disproportionate black dyestuff intermediate capacity, creating geographic vulnerability to localized environmental enforcement. Automotive coatings specifications in Germany and the United States are pulling technical-grade pigment demand away from legacy textile markets.
China
Reactive black dye production concentrates in Zhejiang Longsheng Group's home province where MEE wastewater discharge enforcement is forcing capacity consolidation. The country's dual carbon goals are accelerating pyrolysis-based carbon black pilot projects using agricultural waste feedstocks. Chemical clusters in Shaoxing and Hangzhou supply the majority of global reactive black intermediates to Bangladesh and Vietnam garment manufacturers.
Germany
BASF SE leverages its Ludwigshafen integrated precursor network to secure aniline feedstock for automotive black pigments serving OEM sustainability scorecards. REACH Annex XVII aromatic amine limits are redirecting formulation investment toward waterborne systems that eliminate restricted intermediates. The country's technical-grade pigment houses face compressed qualification timelines from Tier 1 coatings suppliers.
United States
EPA oversight of benzidine-derivative dyes under the Toxic Substances Control Act constrains certain azo-based black formulations in domestic commerce. Automotive exterior palette darkening is pulling procurement toward high-performance carbon black dispersions with enhanced jetness indices. Southeast textile dye houses serving denim brands are absorbing reformulation costs to maintain US market access.
India
The PLI scheme for man-made fiber apparel is generating pull for reactive black dyes in denim and activewear segments. Kiri Industries Limited anchors domestic production of dye intermediates serving technical textile exporters. Gujarat and Maharashtra chemical corridors are expanding capacity to capture share from Zhejiang-Jiangsu supply concentration.
Italy
Leather finishers in the Arzignano and Santa Croce clusters face ECHA polycyclic aromatic hydrocarbon restrictions forcing validation of alternative nitrogen-based black dyes. Tanneries serving luxury automotive seating programs absorb disproportionate compliance costs compressed by certification renewal cycles. The country's specialty chemical houses are qualifying bio-based carbon black for sustainability-positioned brand contracts.
Dyestuff (Black Color) Market Competitive Landscape
Concentration sits with integrated chemical conglomerates possessing captive precursor supply and specialized pigment houses serving specification-driven coatings segments. The market structure separates three tiers: multinational diversified chemical groups with backward integration into aniline and naphthalene feedstocks, regional dye specialists concentrated in Asian textile hubs, and emerging bio-based carbon black developers targeting sustainability scorecards. Dominant competitive moves include capacity reallocation from commodity textile grades toward automotive coatings specifications, and strategic partnerships between pigment houses and Tier 1 coatings suppliers to compress qualification timelines.
Among integrated chemical conglomerates, BASF SE and Lanxess AG exemplify the precursor-integrated archetype with in-house aniline production networks. DyStar Group represents the Asia-anchored textile specialist positioned across Bangladesh and Vietnam garment manufacturing zones. Zhejiang Longsheng Group Co occupies a position within the Chinese state-influenced chemical cluster tier serving global reactive black demand.
| Leading Market Players |
|---|
| BASF SE |
| DyStar Group |
| Clariant AG |
| Huntsman Corporation |
| Lanxess AG |
| Archroma |
| Kiri Industries Limited |
| Sumitomo Chemical Company Ltd |
| Zhejiang Longsheng Group Co |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day inventory cycles at Bangladeshi garment exporters compress procurement leverage against Zhejiang-Jiangsu supply concentration, amplifying pricing power for integrated dye houses while squeezing margin buffers at merchant compounders dependent on spot aniline feedstock.
Pricing Analysis
REACH Annex XVII dictates the pricing tier structure across European procurement, separating compliant waterborne formulations from restricted aromatic amine systems. Three-tier pricing stratifies across automotive coatings-grade, technical textile-grade, and commodity direct dye tiers, with jetness index certification commanding substantial premia. Cost compression in commodity reactive black runs through petroleum-derived naphthalene volatility, while paint producers demonstrate lowest price sensitivity due to specification-locked supply agreements.
Supply Chain Analysis
China anchors global reactive black intermediate production, with Zhejiang and Jiangsu provinces supplying the majority of aniline and naphthalene derivatives feeding Bangladesh and Vietnam garment manufacturing. Feedstock dependencies rest on crude oil benchmarks, coal-tar distillation outputs, and petroleum-derived aromatic precursors. Single-province concentration creates acute vulnerability to MEE wastewater enforcement actions. Distribution runs through integrated chemical conglomerates with captive precursor networks and specialized regional dye houses serving specification-driven coatings segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive OEM sustainability scorecards are accelerating a technological inflection toward waterborne pigment systems, compressing qualification timelines and collapsing legacy textile capacity commitments toward coatings-grade production.
For Market Incumbents: Compound backward integration into aniline feedstocks to secure margin stability against petroleum precursor volatility, while reallocating capacity from commodity textile grades toward automotive coatings specifications with enhanced jetness indices. BASF SE's Ludwigshafen precursor network exemplifies this defensive posture against merchant compounder erosion. For New Entrants and Emerging Players: Anchor in India's technical textile expansion under the PLI scheme for man-made fiber apparel, where reactive black demand in denim and activewear segments offers penetrable white space. Bio-based carbon black development through agricultural waste pyrolysis provides differentiated positioning for sustainability-positioned brand contracts. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because specification-driven vendor concentration favors vertically integrated dye houses with batch-to-batch Delta E consistency capabilities. Target acquisition archetypes include regional specialists with automated color kitchen integration and captive intermediate supply. The signal to watch is accelerated Tier 1 coatings supplier qualification timelines for waterborne systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aniline Feedstocks | BASF SE's Ludwigshafen network secures margin stability against petroleum volatility. |
| Capacity Reallocation to Coatings-Grade Pigments | Automotive OEM specifications pull production from commodity textile dyeing. |
| Bio-Based Carbon Black Development | Pyrolysis of agricultural waste targets sustainability scorecard compliance. |
| Automated Color Kitchen Integration | Paste concentrate formats capture service revenue at large textile manufacturers. |
| REACH-Compliant Waterborne Formulation Investment | ECHA aromatic amine limits redirect European procurement toward compliant systems. |
Research Methodology
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings across this analysis. Conversations with plant managers at Zhejiang-Jiangsu chemical clusters, procurement leads at Tier 1 automotive coatings suppliers, technical R&D directors at pigment houses, and distribution channel partners in Bangladesh and Vietnam informed supply-side dynamics. Secondary validation drew from MEE wastewater discharge records, REACH Annex XVII regulatory updates, SEC 10-K filings of listed chemical conglomerates, and customs/trade data tracking reactive black intermediate flows. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates.
Sensitivity analysis around petroleum feedstock volatility and regulatory enforcement intensity shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, application end-use, physical delivery format, and regional production hub clustering. CAGRs derive from slope analysis of historical trajectory and elasticity-adjusted forward demand curves. Industry-specific forecast inputs incorporate automotive OEM platform launch schedules and textile automation penetration rates at Bangladeshi and Vietnamese garment exporters.
Material uncertainties — MEE enforcement intensity in Zhejiang, REACH expansion to additional aromatic amine categories, and bio-based carbon black scale-up timelines — sit outside the modeled envelope. Forecasts reflect documented assumptions about feedstock cost stability and qualification timeline compression. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Global Thermochromic Paint Market
Dyes and Pigments
Pearl Pigment Market
Dyes and Pigments
Photochromic Pigments Market
Dyes and Pigments
North America Hair Colorants Market
Dyes and Pigments
High Performance Organic Pigments Market
Dyes and Pigments
Brilliant Black BN Colors Market
Dyes and Pigments
Global Organic Pigments Market
Dyes and Pigments
Acid Dyes Market
Dyes and Pigments
Fluorescent Brightening Agents Market
Dyes and Pigments
Copper Chromite Black Pigment Market
Dyes and Pigments
Inorganic Color Pigments Market
Dyes and Pigments
Asia Pacific Hair Colorants Market
Dyes and Pigments
Indigo Carmine Market
Dyes and Pigments
Global Thermochromic Materials Market
Dyes and Pigments
Pearlescent Pigments Market
Dyes and Pigments
Chlorophyll Color Market