
 Prescription Bottles Market | 2026-2036
Prescription Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Prescription Bottles Market Analytics
Hospital procurement of unit-dose prescription bottles is collapsing toward centralized buying consortia that negotiate multi-year supply agreements. Berry Global leverages its North American manufacturing footprint to service these consolidated buyers with high-volume injection-molded formats. Amcor anchors its position through backward integration into resin compounding, securing supply stability for child-resistant closures. Gerresheimer differentiates via glass-alternative polymer expertise, targeting temperature-sensitive biologics that require barrier-grade packaging.
Prescription bottles are rigid primary containers, typically injection- or blow-molded from polyethylene terephthalate, high-density polyethylene, or amber glass, designed to store oral solid and liquid medications while protecting against moisture, light, and unauthorized access. Plastic formats dominate current volume owing to cost efficiency and design flexibility for compliance-enhancing features like desiccant integration. Child-resistant closures command premium positioning as liability exposure drives pharmacy preference for certified opening mechanisms. The online retailer end-user channel represents the fastest-growing demand vector, fueled by direct-to-patient dispensing models that require ship-ready, tamper-evident packaging with extended shelf-life protection.
The US FDA enforces 16 CFR 1700 for child-resistant packaging, while the EU F-Gas Regulation indirectly shapes material choices by pressuring converters toward lower-carbon production pathways. India's CDSCO mandates increasing localization of pharmaceutical packaging to support domestic drug security objectives. Stakeholders must monitor evolving serialization requirements across FDA, EMA, and emerging-market regulators to align capital allocation with compliance-driven format transitions.
Market Dynamics
Hospital pharmacy consolidation into centralized buying consortia is compressing supplier margins while demanding multi-year volume commitments with embedded serialization compliance. This procurement concentration forces converters to absorb upfront capital costs for track-and-trace infrastructure while locking in pricing structures that limit pass-through of resin volatility.
Growth Catalysts
- Unit-dose dispensing mandates:Hospital systems in the United States are expanding unit-dose packaging to reduce medication errors, directly lifting demand for single-use prescription bottles with integrated compliance features.
- India's CDSCO localization push:Domestic pharmaceutical packaging requirements are accelerating local production capacity for prescription bottles serving generic drug exports.
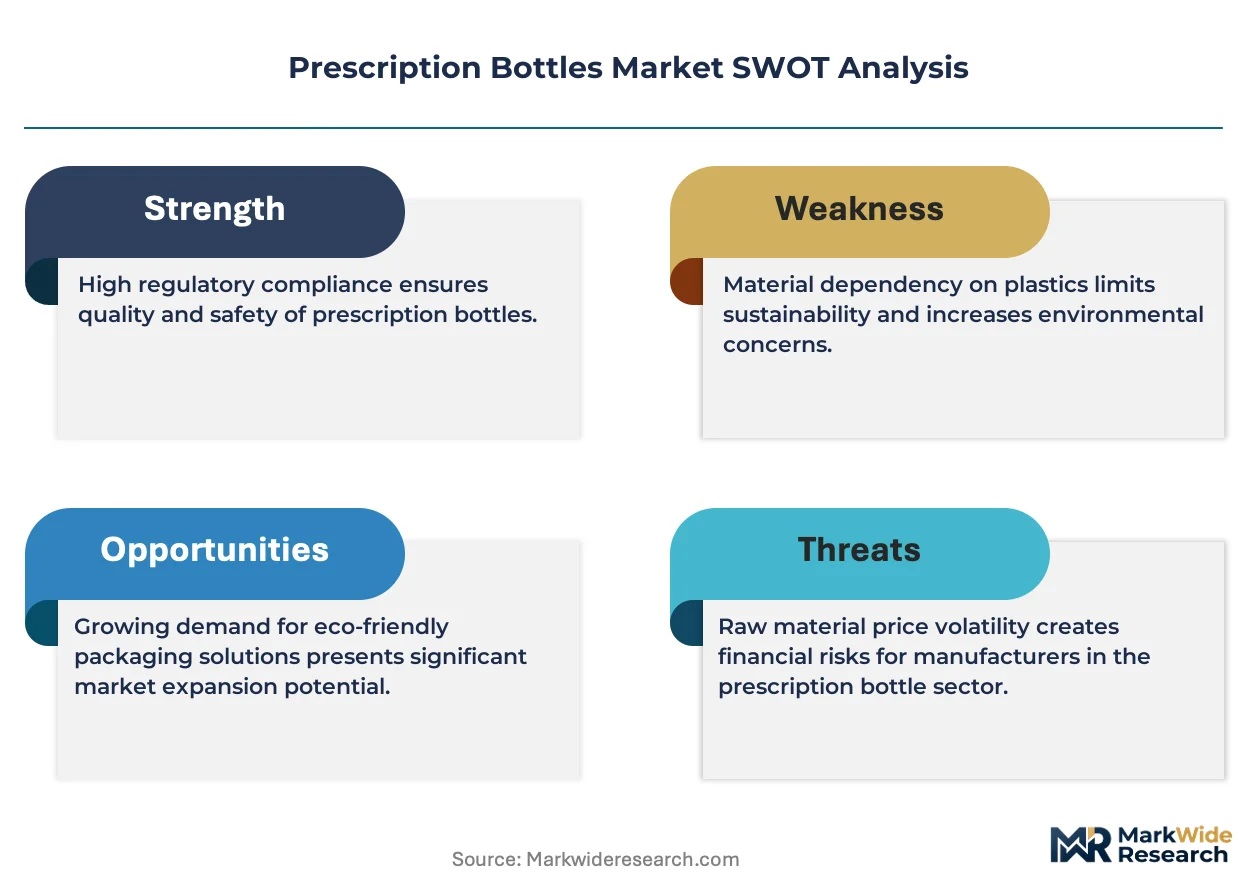
- Biologics cold-chain expansion:Temperature-sensitive biologics require barrier-grade polymer containers with desiccant integration, creating specification premiums for advanced formats.
Market Restraints
- Resin price volatility:Polyethylene terephthalate and high-density polyethylene feedstock costs fluctuate with crude oil indices, compressing converter margins on fixed-price hospital contracts.
- Glass substitution ceiling:Amber glass retains preference for light-sensitive compounds in compounding pharmacies, limiting polymer penetration in specialty segments.
- EMA serialization complexity:European traceability requirements demand capital-intensive aggregation infrastructure that smaller converters cannot amortize across limited volume bases.
Strategic Opportunities
- Direct-to-patient pharmacy channels:Online retailers require ship-ready, tamper-evident bottles with extended shelf-life protection, opening specification opportunities for moisture-barrier innovations.
- EU F-Gas Regulation alignment:Lower-carbon production pathways earn preferential positioning with European pharmaceutical manufacturers facing Scope 3 disclosure pressures.
- Child-resistant closure certification:US FDA 16 CFR 1700 compliance creates differentiation premiums as liability exposure drives pharmacy preference for certified opening mechanisms.
Industry Challenges
- Serialization integration timelines:FDA DSCSA deadlines force simultaneous hardware deployment and software validation, straining engineering resources at mid-tier converters.
- Multi-material recycling complexity:Desiccant-integrated bottles combine incompatible polymers with silica gel inserts, complicating post-consumer waste stream management under emerging extended producer responsibility frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prescription Bottles Market |
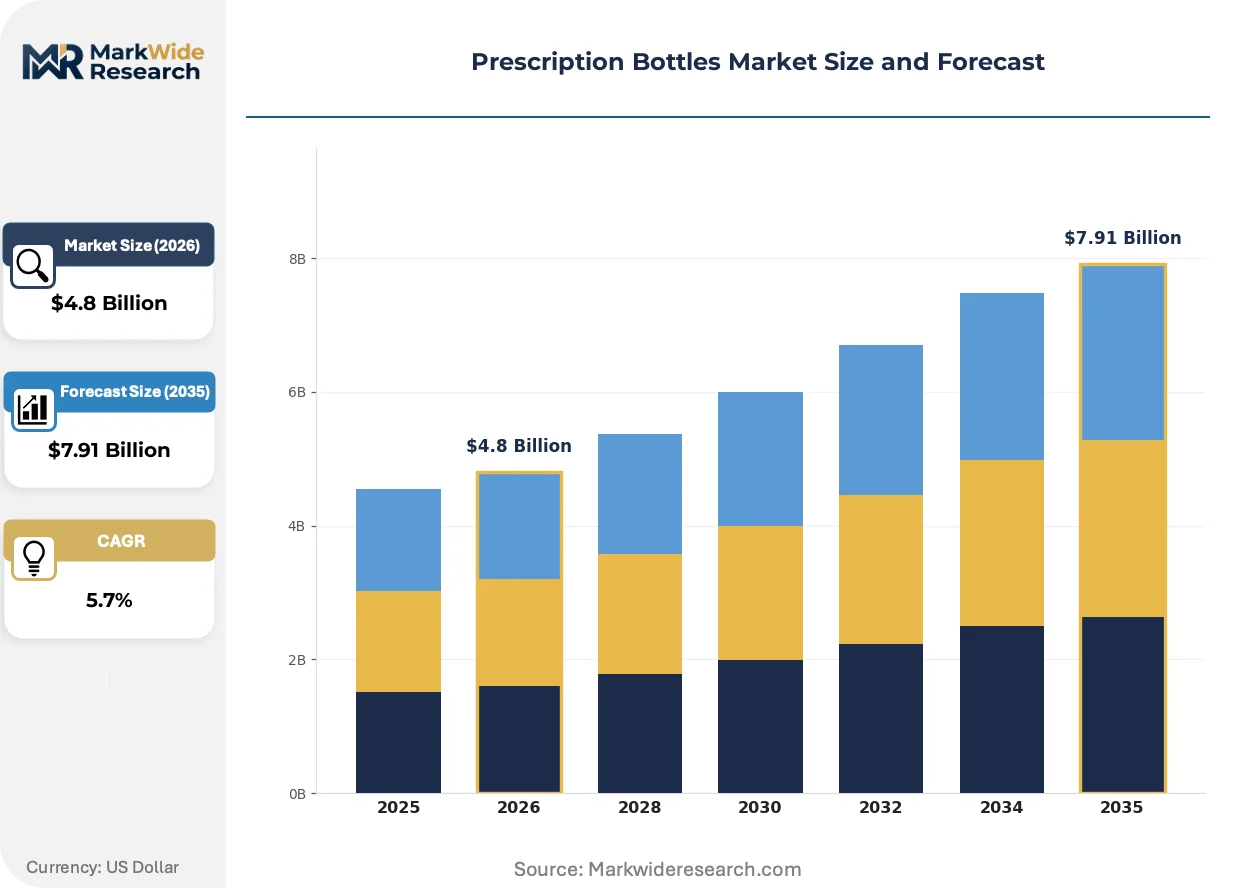
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Glass, Aluminum, Biodegradable Closure Type: Child-Resistant, Tamper-Evident, Screw Cap, Flip Top Size: 30 ml, 60 ml, 100 ml, 250 ml End User: Pharmacies, Hospitals, Clinics, Online Retailers |
| Companies Covered | Berry Global, Amcor, Gerresheimer, AptarGroup, Comar, ALPLA, Drug Plastics, Thornton Plastics, Berk Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prescription Bottles Market Evolving Landscape
Material science advances and regulatory serialization mandates are converging to reshape container specifications, with converters racing to embed compliance features without sacrificing cost efficiency or recyclability credentials.
Barrier-grade polymer formulations incorporating ethylene vinyl alcohol coextrusion layers are fragmenting the traditional glass-polymer boundary for oxygen-sensitive formulations. Specialty pharmacies serving rheumatology and oncology biologics are adopting these formats at accelerating pace. The technology is fragmenting procurement categories that previously defaulted to glass, creating new specification battles between resin compounders.
The EU F-Gas Regulation is pressuring converters toward fluorinated gas-free production processes for barrier treatments. Industrial consequence includes accelerated adoption of plasma-enhanced chemical vapor deposition as an alternative to conventional fluorination. German and Swiss pharmaceutical packaging buyers are now requiring carbon footprint disclosures that disadvantage legacy fluorination methods.
Hospital buying consortia are consolidating annual bottle procurement into single-source agreements with embedded price collars. Independent pharmacies and long-term care facilities are being displaced from direct supplier relationships, instead accessing product through group purchasing organization formularies. This concentration is most visible in United States metropolitan hospital networks, where three consortia now control majority volume allocation.
Prescription Bottles Market Segmentation
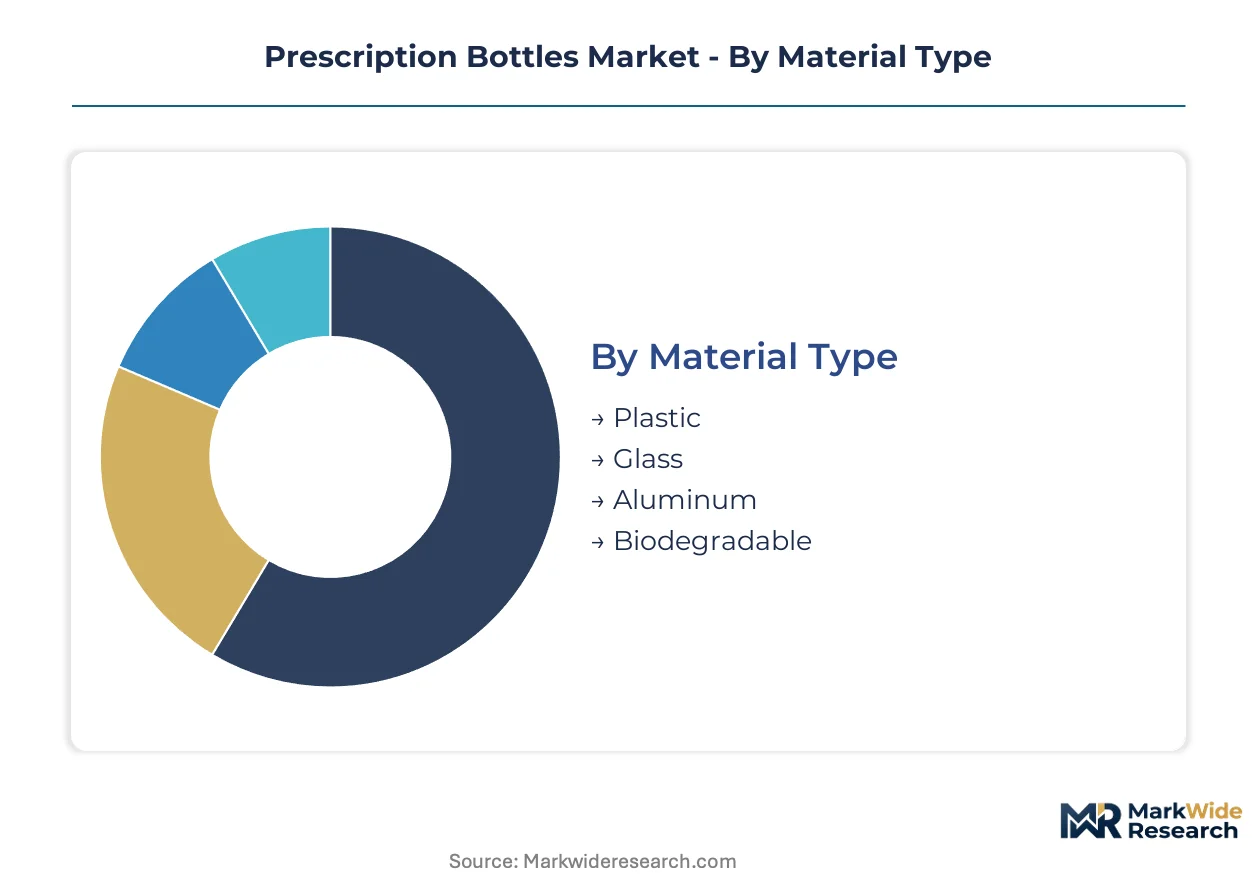
Prescription bottle segmentation reflects divergent compliance burdens across material and closure categories. Regulatory frameworks in the United States, Europe, and India each privilege different technical specifications, fragmenting procurement standards and forcing converters to maintain parallel production lines.
Material Type:
FDA 16 CFR 1700 child-resistance testing and EU F-Gas Regulation carbon-footprint disclosures create divergent material hierarchies across jurisdictions.
- Plastic:Injection- and blow-molded polyethylene terephthalate and high-density polyethylene dominate hospital pharmacy procurement through cost efficiency and design flexibility for desiccant integration. Demand concentrates in India where CDSCO localization mandates accelerate domestic converter capacity for generic drug exports.
- Glass:Amber glass retains specification for light-sensitive compounds in compounding pharmacies and specialty biologics, though barrier-grade polymer coextrusion is fragmenting this category. German and Swiss buyers now require carbon disclosures that disadvantage energy-intensive glass production.
- Aluminum:Lightweight collapsible tubes serve topical and ophthalmic formulations requiring complete light and air exclusion.
- Biodegradable:PLA and PHA formulations attract pilot programs from European manufacturers facing Scope 3 disclosure pressures under CSRD.
Plastic handles the majority of throughput; biodegradable formats are gaining share fastest as regulatory disclosure requirements tighten.
Closure Type:
Cost tiers separate certified child-resistant mechanisms from commodity screw-cap alternatives, with liability exposure driving pharmacy procurement preferences.
- Child-Resistant:Push-and-turn mechanisms certified to US FDA 16 CFR 1700 command premium positioning as hospital systems standardize on error-reducing formats. Berry Global and Amcor compete through captive resin compounding and high-volume injection molding capacity.
- Tamper-Evident:Ring-break and shrink-band designs serve direct-to-patient dispensing models from online retailers requiring ship-ready integrity verification. Moisture-barrier integration creates specification premiums in this channel.
- Screw Cap:Commodity polypropylene closures dominate long-term care and institutional settings where child access is managed through dispensing protocols rather than packaging design.
- Flip Top:Hinged-lid convenience formats target geriatric and arthritic patient populations in retail pharmacy segments, though they rarely achieve child-resistant certification.
Child-resistant closures capture the highest margin tier; tamper-evident formats are expanding most quickly through e-commerce pharmacy channels.
Size:
Volume scale determines automation economics, with high-speed lines optimized for 100 ml formats while smaller sizes require changeover-intensive batch production.
- 100 ml:Standard oral solid dispensing format for 30-day maintenance therapies, dominating hospital consortia procurement through line efficiency and palletization optimization. Centralized buying agreements lock in multi-year volume commitments at this specification.
- 30 ml:Unit-dose and pediatric liquid formulations drive demand for precision-dosing compatibility. US hospital systems expanding unit-dose packaging to reduce medication errors directly lift demand for this format.
- 60 ml:Intermediate capacity serves specialty pharmacy 14-day supplies and veterinary compounding applications.
- 250 ml:Bulk institutional formats for long-term care facilities and clinical trial supply chains.
100 ml handles the majority of throughput; 30 ml is climbing the fastest as unit-dose mandates spread through US hospital networks.
End User:
Customer type dictates packaging complexity, with institutional buyers standardizing on certified formats while direct-to-patient channels demand ship-ready, shelf-life-extended specifications.
- Pharmacies:Retail and hospital pharmacy chains drive volume through centralized procurement, with three US consortia now controlling majority allocation. Child-resistant certification and embedded serialization compliance are non-negotiable specifications.
- Online Retailers:Direct-to-patient dispensing models require tamper-evident, moisture-barrier packaging with extended shelf-life protection. Gerresheimer targets this channel through glass-alternative polymer expertise for temperature-sensitive biologics.
- Hospitals:Inpatient dispensing increasingly shifts to unit-dose formats, reducing demand for traditional multi-dose bottles in acute care settings.
- Clinics:Physician-dispensed samples and specialty infusion centers generate fragmented, low-volume demand across variable specifications.
Pharmacies handle the majority of throughput; online retailers show the steepest expansion trajectory as direct-to-patient models displace traditional dispensing channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports prescription bottles to North American and European pharmaceutical manufacturers as domestic generic drug production scales. Hospital pharmacy consolidation in the United States drives demand for unit-dose formats with embedded serialization. European regulatory pressure on carbon footprints reshapes material specifications across the value chain.
United States
Hospital buying consortia now control majority volume allocation through multi-year supply agreements with embedded price collars. FDA DSCSA deadlines force converters to deploy track-and-trace infrastructure simultaneously with software validation. The Philadelphia-Baltimore corridor hosts concentrated injection-molding capacity serving these consolidated procurement channels.
Germany
Pharmaceutical manufacturers demand carbon footprint disclosures that disadvantage energy-intensive glass production and legacy fluorination methods. The EU F-Gas Regulation accelerates adoption of plasma-enhanced chemical vapor deposition as an alternative barrier treatment. The Rhine-Main industrial cluster anchors converter investment in lower-carbon production pathways.
India
CDSCO localization mandates accelerate domestic converter capacity for generic drug exports to regulated markets. Domestic pharmaceutical packaging requirements tighten as export volumes rise to North America and Europe. The Mumbai-Pune corridor concentrates blow-molding capacity serving both local drug manufacturers and international buyers.
Switzerland
Swissmedic oversight maintains stringent quality standards for barrier-grade polymer containers serving temperature-sensitive biologics. Swiss pharmaceutical packaging buyers require carbon disclosures that reshape supplier selection criteria. The Basel-Lake Geneva corridor hosts specialty converters targeting high-specification biologics packaging.
Japan
PMDA serialization requirements align with international traceability standards while maintaining distinctive domestic packaging norms. METI industrial policy supports converter investment in high-barrier polymer formulations for oxygen-sensitive formulations. The Osaka-Kobe manufacturing belt concentrates pharmaceutical packaging expertise serving domestic and export markets.
Prescription Bottles Market Competitive Landscape
Player mix skews toward diversified packaging conglomerates with captive resin supply and specialized pharmaceutical converters with barrier-grade polymer expertise. The structure concentrates around three strategic archetypes: resin-integrated volume producers, glass-alternative polymer specialists, and regional injection-molding fabricators. Competitive moves center on backward integration into resin compounding and geographic expansion to capture India-based generic drug export demand.
Among North American diversified packaging conglomerates, Berry Global and Amcor exemplify the resin-integrated volume archetype. Gerresheimer anchors the glass-alternative polymer specialist tier with barrier-grade expertise for temperature-sensitive biologics. These three companies represent distinct competitive positions: volume scale with captive supply, material science differentiation, and regulatory compliance depth.
| Leading Market Players |
|---|
| Berry Global |
| Amcor |
| Gerresheimer |
| AptarGroup |
| Comar |
| ALPLA |
| Drug Plastics |
| Thornton Plastics |
| Berk Company |
| Others |
Value Network & Pricing Analysis
High-volume injection-molding capacity utilization above 85 percent in the Philadelphia-Baltimore corridor anchors supply concentration and sets price floors that smaller converters cannot undercut. Hospital buying consortia exploit this scale asymmetry to extract multi-year price collars while locking out independent pharmacies from direct supplier relationships.
Pricing Analysis
Barrier-grade polymer coextrusion commands 40-60 percent premiums over conventional HDPE formats, while amber glass maintains residual pricing power in compounding pharmacy segments. Three-tier pricing structure across premium barrier-grade, standard child-resistant, and economy screw-cap levels reflects certification grade and volume scale. Cost compression in standard formats is intensifying because resin volatility cannot pass through fixed-price hospital contracts. Long-term care facilities exhibit highest price sensitivity; biologics specialty pharmacies show least.
Supply Chain Analysis
Inventory cycles stretch 8-12 weeks for desiccant-integrated bottles due to multi-material assembly complexity and serialization hardware lead times. Manufacturing concentrates in the United States, India, and Germany, with each hub serving distinct regulatory compliance clusters. Feedstock draws from polyethylene terephthalate and high-density polyethylene resin markets tethered to crude oil indices. Single-source vulnerability concentrates in fluorinated barrier treatment capacity facing EU F-Gas Regulation phaseout. Distribution runs through group purchasing organization formularies that displace direct pharmacy-supplier relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around FDA 16 CFR 1700 certification and DSCSA serialization creates formidable defensive moats. Switching costs for hospital consortia are substantial given embedded track-and-trace infrastructure and multi-year contract lock-in.
For Market Incumbents: Fortify captive resin compounding positions to absorb polyethylene terephthalate volatility that threatens fixed-price hospital contract profitability. Deepen backward integration into desiccant manufacturing to capture specification premiums in barrier-grade formats. Emerging biologics polymer specialists pose substitution threats in temperature-sensitive segments. For New Entrants and Emerging Players: Differentiate on carbon-neutral production pathways to exploit EU F-Gas Regulation compliance gaps among legacy fluorination-dependent incumbents. White-space concentrates in online retailer channels requiring ship-ready tamper-evident formats with extended shelf-life protection. India's CDSCO localization mandates offer the most penetrable geography for export-oriented capacity. Go-to-market leverage rests on direct relationships with direct-to-patient pharmacy platforms bypassing GPO intermediaries. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among resin-integrated volume producers serving hospital consortia through embedded multi-year supply agreements. Long-term viability favors converters with parallel FDA and EMA serialization compliance infrastructure. Acquisition target archetype: mid-tier barrier-grade polymer specialists with untapped biologics channel relationships. Signal to watch: CDSCO localization enforcement intensity as proxy for India-based export volume sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Amcor and Berry Global anchor margin stability through captive polyethylene terephthalate supply. |
| Plasma-Enhanced Chemical Vapor Deposition Adoption | German converters satisfy EU F-Gas Regulation carbon disclosure requirements without fluorinated gases. |
| Unit-Dose Format Capacity Expansion | US hospital systems reduce medication errors through 30 ml single-use bottle standardization. |
| Direct-to-Patient Channel Partnership | Gerresheimer targets online retailer demand with glass-alternative polymer expertise for biologics. |
| CDSCO Localization Compliance Investment | Mumbai-Pune corridor converters capture generic drug export growth to North America and Europe. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with packaging procurement managers at hospital buying consortia, regulatory affairs directors at pharmaceutical manufacturers, and converter operations executives; and secondary validation through FDA DSCSA guidance documents, EMA serialization requirements, CDSCO localization circulars, and trade flow data from resin market monitors. Bottom-up capacity assessments at 40-plus converter facilities triangulated against top-down pharmaceutical packaging demand models.
Across the projection horizon, the analytical framework modeled volume and value trajectories by material type, closure mechanism, bottle size, and end-user channel. CAGRs were derived from regression-based demand elasticity estimates against pharmaceutical production indices. Forecast inputs incorporated unit-dose dispensing mandate adoption curves and biologics cold-chain expansion rates.
Forecasts assume regulatory continuity in FDA DSCSA, EU F-Gas Regulation, and CDSCO localization regimes; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
US Clinical Trial Packaging Market
Pharmaceutical Packaging
Europe Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Global Biodegradable Pharmaceutical Packaging Market
Pharmaceutical Packaging
Pharmaceutical Plastic Pots Market
Pharmaceutical Packaging
Active and Intelligent Packaging in Pharmaceutical Market
Pharmaceutical Packaging
Europe Pharmaceutical Packaging Materials Market
Pharmaceutical Packaging
India Pharmaceutical Packaging Market
Pharmaceutical Packaging
Pharmaceutical Vials Market
Pharmaceutical Packaging
Pharmacy Repackaging Systems Market
Pharmaceutical Packaging
Dispensing Pharmacy Packaging Machine Market
Pharmaceutical Packaging
China Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
Pharmaceutical Unit Dose Packaging Market
Pharmaceutical Packaging
Cartoning Machines for Pharmaceutical Industry Market
Pharmaceutical Packaging
Pharmaceutical Ampoules Market
Pharmaceutical Packaging
Pharma Packaging Films Market
Pharmaceutical Packaging
Pharmaceutical Bottles Market