
 Global Returnable Plastic Crates Market | 2026-2036
Global Returnable Plastic Crates Market Size, Share, and Industry Trends Forecast 2026-2036
Global Returnable Plastic Crates Market Outlook
Closed-loop pooling networks is reconfiguring how returnable plastic crates circulate between processors, distributors, and retail backrooms. Schoeller Allibert leverages its European manufacturing footprint to sustain high-volume supply agreements with grocery chains. Brambles Limited anchors the Asia-Pacific region through CHEP's pooled equipment model, while ORBIS Corporation specializes in automotive-grade crate designs that compete on durability metrics.
Returnable plastic crates are injection-molded or thermoformed containers, typically fabricated from polypropylene or high-density polyethylene, engineered for 50-100 use cycles in closed-loop logistics systems. Their primary purpose is to protect perishables and industrial components through standardized dimensions that optimize truck and warehouse cube utilization. Collapsible crates are capturing margin pools in backhaul-intensive applications where empty container volume determines freight economics. High-density polyethylene grades dominate agricultural exports due to moisture resistance, while polypropylene formulations lead in automotive sequencing where dimensional stability under load matters.
The EPA's sustainable materials management priorities and the EU Green Deal's packaging waste directives are tightening material recovery obligations across North America and Europe. China's GB standards for plastic logistics equipment and its dual carbon goals are accelerating domestic remanufacturing requirements. India's BIS certification mandates and PLI scheme incentives for sustainable packaging are reshaping import substitution patterns. Stakeholders must monitor regulatory divergence between jurisdictions that mandate recycled content thresholds versus those prioritizing durability standards.
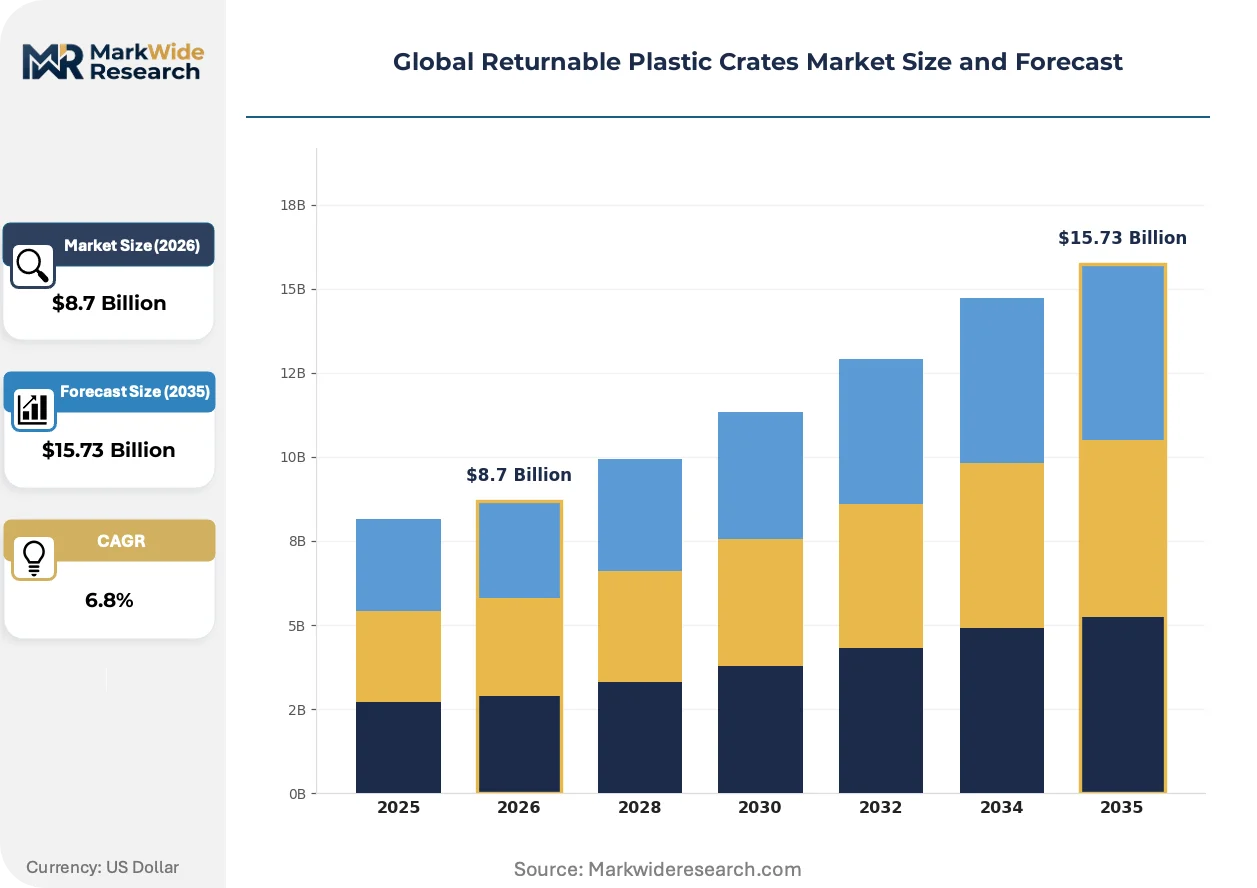
Market Dynamics
Closed-loop pooling networks are compressing asset utilization cycles across fresh produce supply chains. Germany's Packaging Act mandates single-use plastic restrictions that force supermarket chains into long-term crate leasing agreements rather than spot purchases.
Growth Catalysts
- EU Green Deal packaging waste directives:The EU Green Deal mandates recycled content thresholds in logistics equipment, compelling retailers to replace cardboard with returnable plastic crates in perishable distribution.
- Agricultural export corridors:China's cold-chain infrastructure expansion creates demand for moisture-resistant HDPE crates in domestic produce distribution and cross-border shipments to Southeast Asian markets.
- Injection-molding automation:Advanced robotic molding cells reduce unit production costs for collapsible crate designs, making pooled equipment economically viable for mid-tier distributors.
Market Restraints
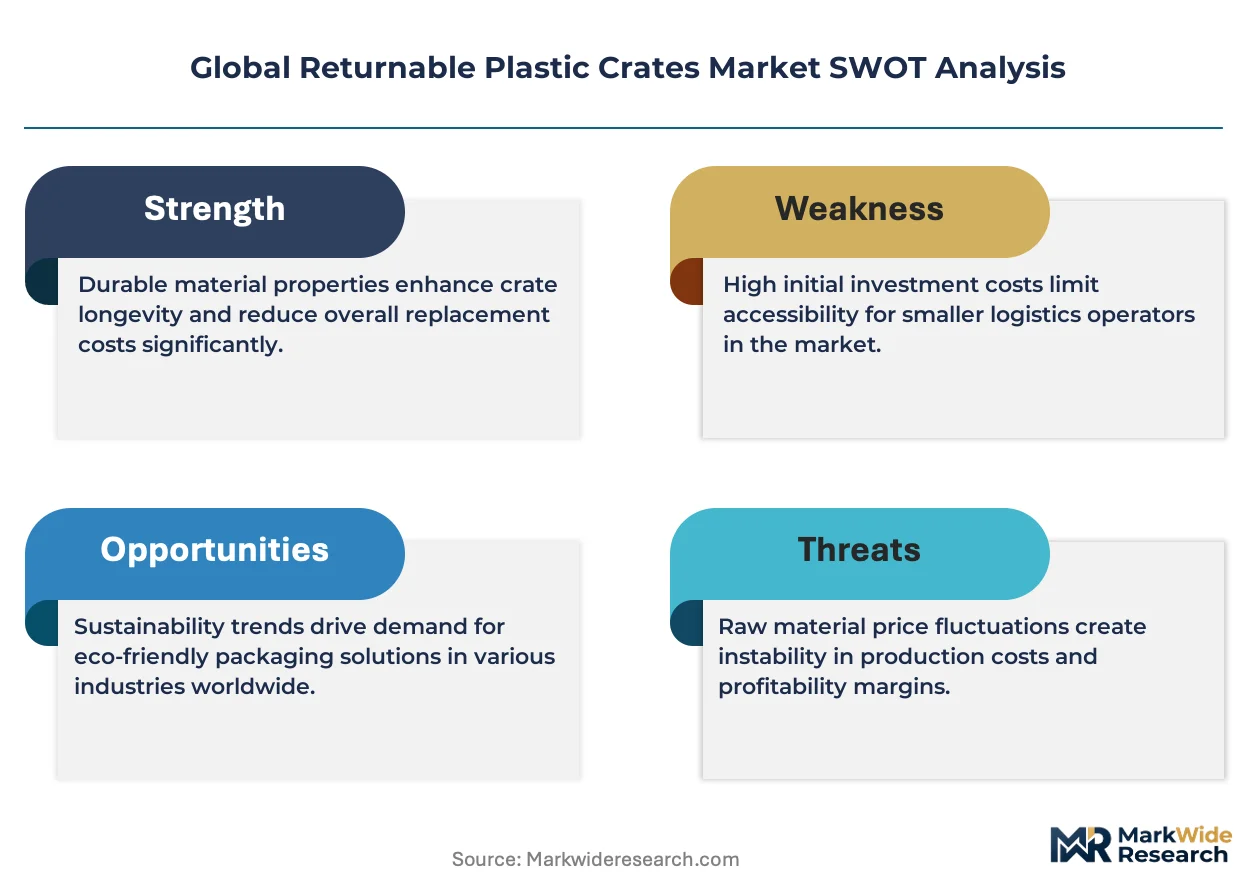
- Petrochemical input volatility:Polypropylene and high-density polyethylene resin prices fluctuate with crude oil markets, compressing margins for crate manufacturers locked into multi-year pooling contracts.
- Regional supply concentration:European crate production clusters in Germany and the Netherlands, creating freight cost penalties for southern European distributors seeking just-in-time replenishment.
- Cardboard substitution resilience:Lightweight corrugated alternatives retain cost advantages in single-use export applications where return logistics are uneconomical.
Strategic Opportunities
- India's PLI scheme incentives:India's Production-Linked Incentive scheme for sustainable packaging offers tariff advantages for domestic crate manufacturing, reducing import dependence from Chinese suppliers.
- Pharmaceutical cold-chain compliance:Temperature-validated crate designs with integrated data loggers penetrate vaccine distribution networks requiring GDP-compliant logistics equipment.
- Blockchain-IoT convergence:Distributed ledger tracking combined with embedded sensors enables usage-based pricing models that monetize crate cycle data.
Industry Challenges
- Remanufacturing skill scarcity:Crate washing, inspection, and repair operations require specialized polymer welding technicians that pool operators struggle to recruit in sufficient numbers.
- BIS certification timelines:India's Bureau of Indian Standards approval process for plastic logistics equipment extends 14-18 months, delaying market entry for new product designs.
- Legacy WMS integration:Warehouse management systems at regional distributors lack API connectivity to modern pooling platforms, forcing manual reconciliation of crate movements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Returnable Plastic Crates Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stackable Crates, Collapsible Crates, Bins, Totes End User: Retail, Food & Beverage, Automotive, Agriculture Material: Polypropylene, High-Density Polyethylene, Recycled Plastics, Bioplastics Distribution Channel: Direct Sales, Distributors, Online Retail, Exporters |
| Companies Covered | Brambles Limited, Schoeller Allibert, Myers Industries Inc., Rehrig Pacific Company Inc., DS Smith PLC, ORBIS Corporation, Supreme Industries Limited, Monoflo International, IPL Plastics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Returnable Plastic Crates Market Strategic Shifts
Digital tracking infrastructure is virtualizing asset visibility across multi-party logistics networks. Material science advances and regulatory tightening are simultaneously reshaping crate specifications and competitive positioning.
Embedded RFID and NFC sensors are virtualizing crate location and condition monitoring in real time. Pharmaceutical distributors and premium produce exporters adopt these smart containers fastest, paying telemetry premiums for temperature and shock data. This virtualization compresses insurance costs and liability disputes in high-value cold chains.
REACH substance restrictions and the EU F-Gas Regulation are eliminating certain plasticizers and blowing agents from crate manufacturing processes. Producers reformulate polypropylene compounds to maintain impact resistance without restricted additives. Automotive sequencing applications face the tightest compliance deadlines, accelerating supplier qualification timelines.
Supermarket chains are consolidating crate procurement through preferred pooling partnerships rather than fragmented spot buying. Germany's REWE and France's Carrefour negotiate multi-year equipment service agreements that bundle washing, maintenance, and replacement. This concentration shifts margin pools from manufacturing to logistics service providers.
Global Returnable Plastic Crates Market Segmentation
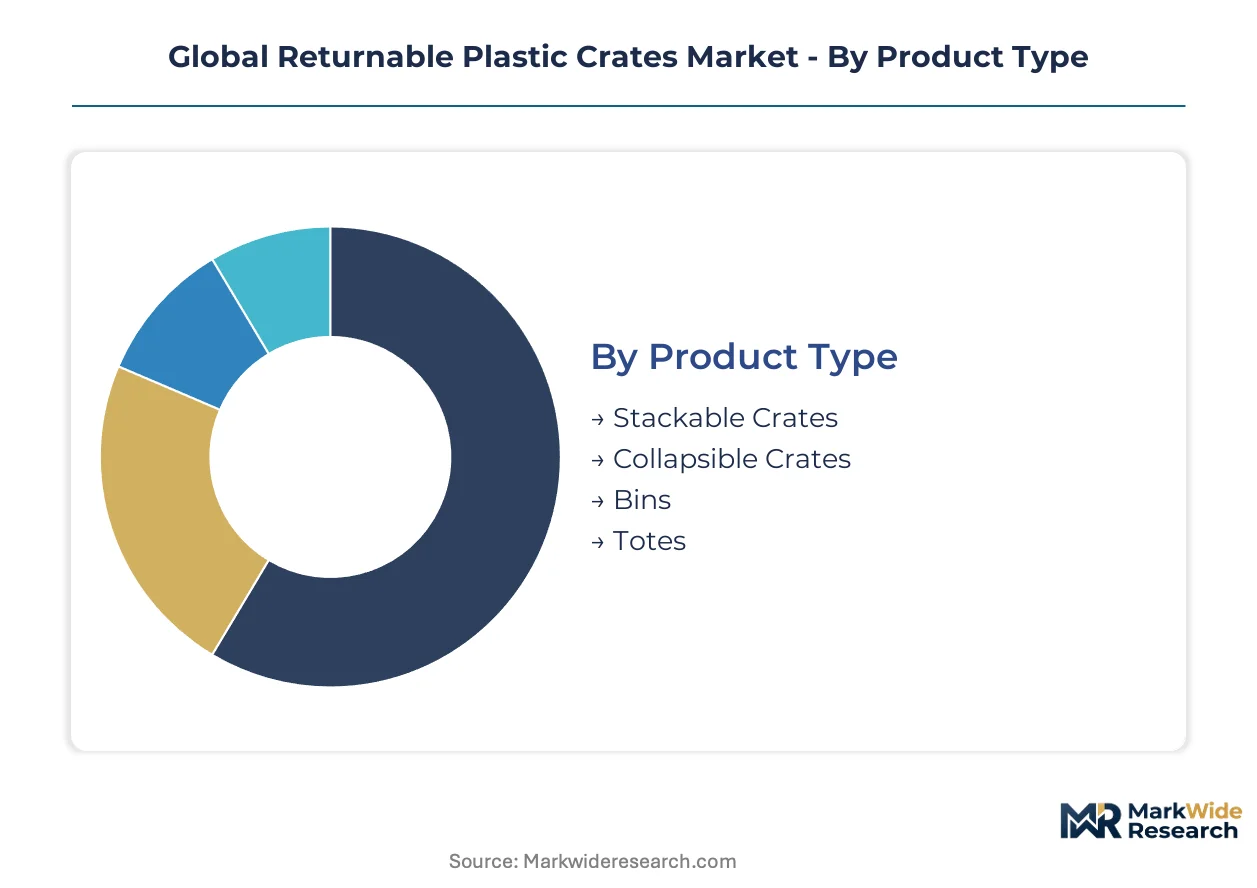
Returnable plastic crate procurement splits across four intersecting dimensions that determine unit economics and logistics performance. Product geometry dictates backhaul efficiency. Material selection locks in durability specifications and regulatory compliance pathways. End-use verticals impose divergent handling protocols. Distribution channel choice reflects customer scale and service intensity requirements.
Product Type:
Mature designs dominate high-volume produce movement while emerging formats capture automation-intensive applications.
- Stackable Crates:Fixed-wall polypropylene containers with nesting ratios of 2:1 to 4:1 optimize warehouse cube utilization in automated storage and retrieval systems. European supermarket chains standardize on 600x400mm Euro dimensions for cross-dock compatibility. Germany's Packaging Act mandates single-use substitution in fresh produce, cementing stackable formats as the default procurement choice for REWE and Carrefour logistics networks.
- Collapsible Crates:Folding side-wall designs reduce return shipment volume by 70-80% versus rigid alternatives, transforming freight economics in backhaul-constrained agricultural corridors. China's cold-chain expansion into Xinjiang and Yunnan provinces drives demand for HDPE collapsible models that withstand temperature cycling from field heat to refrigerated transport.
- Bins:Large-format bulk containers handle 500-1000kg payloads for industrial ingredient movement and post-harvest aggregation.
- Totes:Smaller handheld containers serve pick-to-cart operations in pharmaceutical distribution and premium produce handling.
Stackable crates retain volume leadership; collapsible formats hold the steepest expansion curve.
End User:
Cost tier stratification separates capital-intensive pooling contracts from transactional equipment purchases.
- Retail:Supermarket chains negotiate multi-year equipment service agreements bundling washing, maintenance, and telemetry. France's anti-waste regulations and Germany's Packaging Act force grocers into closed-loop pooling rather than spot buying, concentrating procurement among Schoeller Allibert and CHEP network operators.
- Food & Beverage:Processors demand temperature-validated crates with integrated data loggers for dairy, meat, and prepared meal distribution. FDA food contact compliance and EU F-Gas Regulation restrictions on blowing agents reshape material formulation requirements for this segment.
- Automotive:Sequencing operations require dimensional stability under load with precise tolerances for robotic handling.
- Agriculture:Field-to-export corridors in China and India favor moisture-resistant HDPE grades for produce aggregation.
Retail commands the highest service premiums; agriculture generates the largest unit volumes.
Material:
Supply concentration in petrochemical feedstocks creates margin exposure that recyclate and biopolymer alternatives seek to displace.
- Polypropylene:Copolymer grades deliver impact resistance across temperature ranges from -20°C to 60°C, dominating automotive sequencing and pharmaceutical applications. REACH substance restrictions on plasticizers force compound reformulation without sacrificing drop-test performance.
- High-Density Polyethylene:Moisture impermeability and UV stability make HDPE the default for agricultural export crates exposed to field conditions and maritime humidity. China's GB standards for plastic logistics equipment specify HDPE performance benchmarks for domestic cold-chain infrastructure.
- Recycled Plastics:Post-industrial and post-consumer feedstocks face EU Green Deal recycled content mandates in logistics equipment.
- Bioplastics:Polylactic acid and bio-polyethylene variants target premium positioning where carbon footprint disclosure carries procurement weight.
Polypropylene and HDPE jointly hold volume leadership; recycled content formulations are climbing fastest on regulatory compulsion.
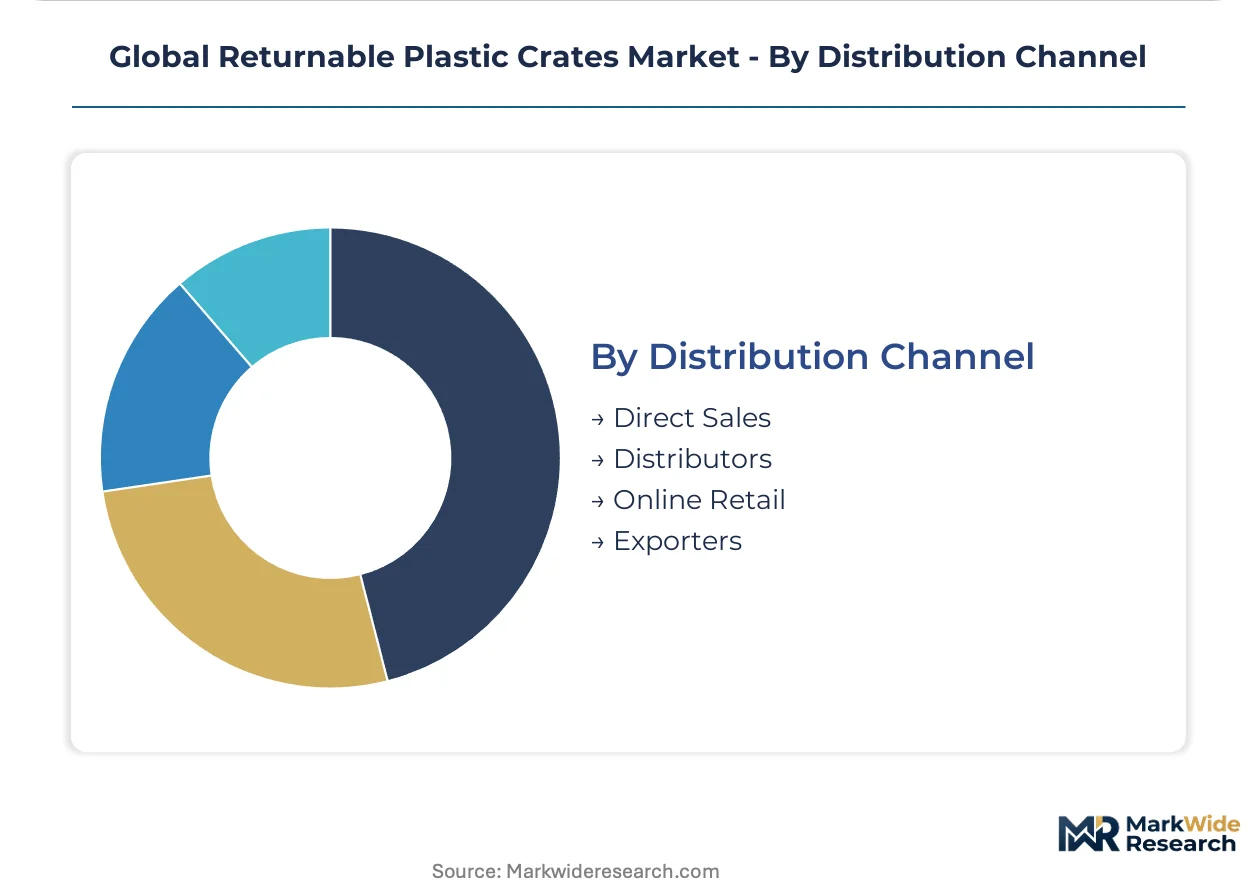
Distribution Channel:
Customer scale determines whether direct relationships or intermediated channels deliver optimal service economics.
- Direct Sales:Manufacturers maintain captive sales forces for national supermarket chains and automotive OEMs requiring customized crate specifications and pooling platform integration. Brambles Limited anchors Asia-Pacific volume through CHEP's direct equipment service agreements.
- Distributors:Regional warehousing and technical support networks serve mid-tier food processors and agricultural cooperatives lacking internal logistics engineering capabilities.
- Online Retail:Digital procurement platforms capture spot purchases for replacement volumes and small-lot specialty formats.
- Exporters:Cross-border traders manage certification complexity for India's BIS mandates and China's GB standards on behalf of foreign manufacturers.
Direct sales capture the highest-margin pooling contracts; distributors intermediate the broadest geographic coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain terminals anchor European produce logistics, while China's Ningbo-Zhoushan port complex handles agricultural export containerization. India's Jawaharlal Nehru Port Trust processes inbound polymer feedstocks for domestic crate manufacturing.
Germany
Supermarket chains REWE and Edeka negotiate multi-year pooling contracts for fresh produce distribution. The Packaging Act mandates single-use plastic restrictions in retail logistics. Manufacturing clusters in North Rhine-Westphalia produce Euro-standard 600x400mm stackable crates for cross-border supermarket replenishment.
China
Agricultural export corridors through Xinjiang and Yunnan drive demand for collapsible HDPE crates in temperature-cycled logistics. GB standards for plastic logistics equipment specify performance benchmarks under the dual carbon policy framework. Cold-chain infrastructure expansion in Chengdu-Chongqing concentrates domestic produce distribution equipment procurement.
United States
Pharmaceutical distributors adopt temperature-validated crates with integrated data loggers for vaccine cold chains. FDA food contact compliance requirements reshape material formulations for dairy and meat logistics. Midwest automotive sequencing operations in Michigan and Ohio specify dimensional-stability crates for robotic handling systems.
India
Agricultural cooperatives in Maharashtra and Gujarat aggregate produce for export to Middle Eastern markets. The PLI scheme for sustainable packaging offers tariff advantages for domestic HDPE crate manufacturing. BIS certification timelines of 14-18 months delay new product entry for foreign suppliers.
France
Carrefour's logistics network consolidates procurement through preferred pooling partnerships rather than fragmented spot buying. Anti-waste regulations force grocers into closed-loop equipment service agreements. The Île-de-France region hosts washing and repair facilities serving northern European supermarket chains.
Global Returnable Plastic Crates Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in the manufacturing stack. The market structure concentrates around pooled equipment operators with captive logistics networks and independent molders serving spot-purchase customers. Three archetypes dominate: closed-loop pooling platforms, injection-molding specialists with automotive-grade capabilities, and regional fabricators serving agricultural cooperatives. Competitive moves center on strategic partnerships with supermarket chains and geographic expansion into cold-chain corridors.
Within the pooling platform tier, Brambles Limited and Schoeller Allibert exemplify equipment-service models that bundle washing, maintenance, and replacement under multi-year agreements. ORBIS Corporation occupies a position among durability-focused specialists serving industrial sequencing applications. These three anchors represent divergent strategic positions: Brambles Limited leverages Asia-Pacific infrastructure through CHEP's direct service agreements; Schoeller Allibert sustains European manufacturing scale for grocery chain supply contracts; ORBIS Corporation focuses on load-bearing performance metrics that automotive OEMs specify for just-in-time parts delivery.
| Leading Market Players |
|---|
| Brambles Limited |
| Schoeller Allibert |
| Myers Industries Inc. |
| Rehrig Pacific Company Inc. |
| DS Smith PLC |
| ORBIS Corporation |
| Supreme Industries Limited |
| Monoflo International |
| IPL Plastics Inc. |
| Others |
Value Chain & Pricing Dynamics
North Rhine-Westphalia's injection-molding clusters concentrate polypropylene and high-density polyethylene conversion capacity, granting German manufacturers leverage in multi-year pooling contract negotiations with supermarket chains across Europe.
Pricing Analysis
Three-tier pricing structure across premium telemetry-enabled, standard pooled, and economy spot-purchase levels dominates procurement. Price differentiation hinges on volume scale and after-sales service bundling, with national grocery chains capturing steepest discounts. Cost compression in the economy tier is intensifying because resin volatility squeezes independent molders. Agricultural cooperatives exhibit highest price sensitivity; pharmaceutical distributors show lowest due to GDP compliance requirements.
Supply Chain Analysis
Export-control regimes on advanced polymer additives under REACH substance restrictions limit certain plasticizer flows into European manufacturing. Supply concentrates in Germany, the Netherlands, and China, with feedstock conversion resting on naphtha cracking and recycled pellet streams. Single-source vulnerability runs through Middle Eastern petrochemical exporters. Distribution runs through CHEP's pooled equipment networks and Schoeller Allibert's direct service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense against corrugated fiberboard resilience in single-use export corridors where return logistics prove uneconomical.
For Market Incumbents: Pre-empt cardboard substitution by embedding RFID telemetry into standard crate tiers, collapsing the premium-mid pricing gap. Secure backward integration into recycled polymer feedstocks to buffer resin volatility. Lock in multi-year washing and maintenance contracts with REWE and Carrefour before regulatory tightening accelerates.
For New Entrants and Emerging Players: Mid-tier agricultural distributors in India's Maharashtra and Gujarat corridors represent the most penetrable entry point, bypassing BIS certification delays through joint ventures with domestic fabricators. Target pharmaceutical cold-chain compliance as the go-to-market angle, offering temperature-validated designs with integrated data loggers that incumbent pooling platforms lack.
For Investors and Strategic Acquirers: Long-term, this sits as a circular infrastructure play because regulatory mandates for recycled content and single-use substitution create durable demand tailwinds. Acquisition targets should cluster around regional washing and repair operators with polymer welding technician benches. Watch India's PLI scheme disbursement velocity as the inflection signal for domestic manufacturing competitiveness.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Feedstocks | Captures margin pools from EU Green Deal recycled content mandates while insulating against petrochemical volatility. |
| Telemetry Platform Integration | Enables usage-based pricing models that monetize crate cycle data for pharmaceutical and premium produce clients. |
| Regional Washing Network Expansion | Addresses remanufacturing skill scarcity while capturing service revenue from supermarket chain outsourcing. |
| Joint Venture in India PLI Corridors | Bypasses BIS certification timelines while accessing tariff advantages for domestic HDPE crate production. |
| Automotive Sequencing Certification | Opens ORBIS-dominated industrial segment through dimensional stability guarantees for robotic handling systems. |
Study Parameters
Initial hypotheses were tested against primary input from pooling platform operations directors, polymer compound R&D leads, supermarket chain procurement managers, and agricultural cooperative logistics heads, and refined through secondary validation against EU F-Gas Regulation filings, EPA sustainable materials management reports, China's GB standards documentation, and customs trade data for plastic logistics equipment. Bottom-up crate shipment modeling and top-down cold-chain infrastructure investment tracking were triangulated to anchor volume estimates.
Demand-supply balance framing structured the analytical approach across the projection horizon. Segmentation dimensions modeled include product geometry, material formulation, end-use vertical, and distribution channel intensity. CAGRs were derived from weighted average of historical pooling contract growth and forward infrastructure investment pipelines. Industry-specific forecast inputs incorporated EU Packaging Act implementation trajectories and China's dual carbon policy enforcement cadence.
Practitioners should monitor petrochemical input volatility, BIS certification processing speeds, and REACH substance restriction expansion for early signals of forecast deviation. Material shifts in single-use substitution regulatory timelines or cold-chain infrastructure buildout rates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Plastic Medicine Bottles Market
Plastic Packaging
Transparent Plastic Packaging Market
Plastic Packaging
PLA Cup Market
Plastic Packaging
Plastic Keg Market
Plastic Packaging
Plastic Films Market
Plastic Packaging
Plastic Corrugated Sheets Market
Plastic Packaging
Plastic Vials Market
Plastic Packaging
PET Clamshell Market
Plastic Packaging
China Plastic Packaging Market
Plastic Packaging
Plastic Aerosol Packaging Market
Plastic Packaging
Asia-Pacific Plastic Bottles and Containers Market
Plastic Packaging
US Plastic Packaging Market
Plastic Packaging
Plastic Cutlery Market
Plastic Packaging
Plastic-Free Packs Market
Plastic Packaging
Mexico Plastic Packaging Market
Plastic Packaging
Packaging Industry in South Africa Market