
 Plastic T-Shirt Bags Market | 2026-2036
Plastic T-Shirt Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic T-Shirt Bags Market Analytics
Recycled polyethylene is consolidating its position as the dominant feedstock for cost-sensitive bag production across Asia-Pacific contract manufacturers. Novolex leverages vertical integration across resin sourcing and blown film extrusion to sustain margin stability. ProAmpac competes through specialized printed bag offerings for branded retail clients. Advance Polybag, Inc. anchors its position in heavy-duty HDPE formats for grocery and bulk retail channels.
Plastic T-shirt bags are single-use carry sacks manufactured via blown film extrusion, typically ranging from 0.5 to 3.0 mils in thickness, with die-cut handles integrated during the sealing and cutting phase. These bags serve primarily as lightweight, low-cost packaging for point-of-sale merchandise transport across retail and food service environments. HDPE grades dominate volume production due to their stiffness-to-weight ratio and compatibility with high-speed converting equipment. Biodegradable material formulations represent the fastest-expanding segment as municipal composting infrastructure spreads across regulated jurisdictions. E-commerce end-use demand is maturing rapidly as fulfillment centers shift toward paper-based alternatives for last-mile delivery.
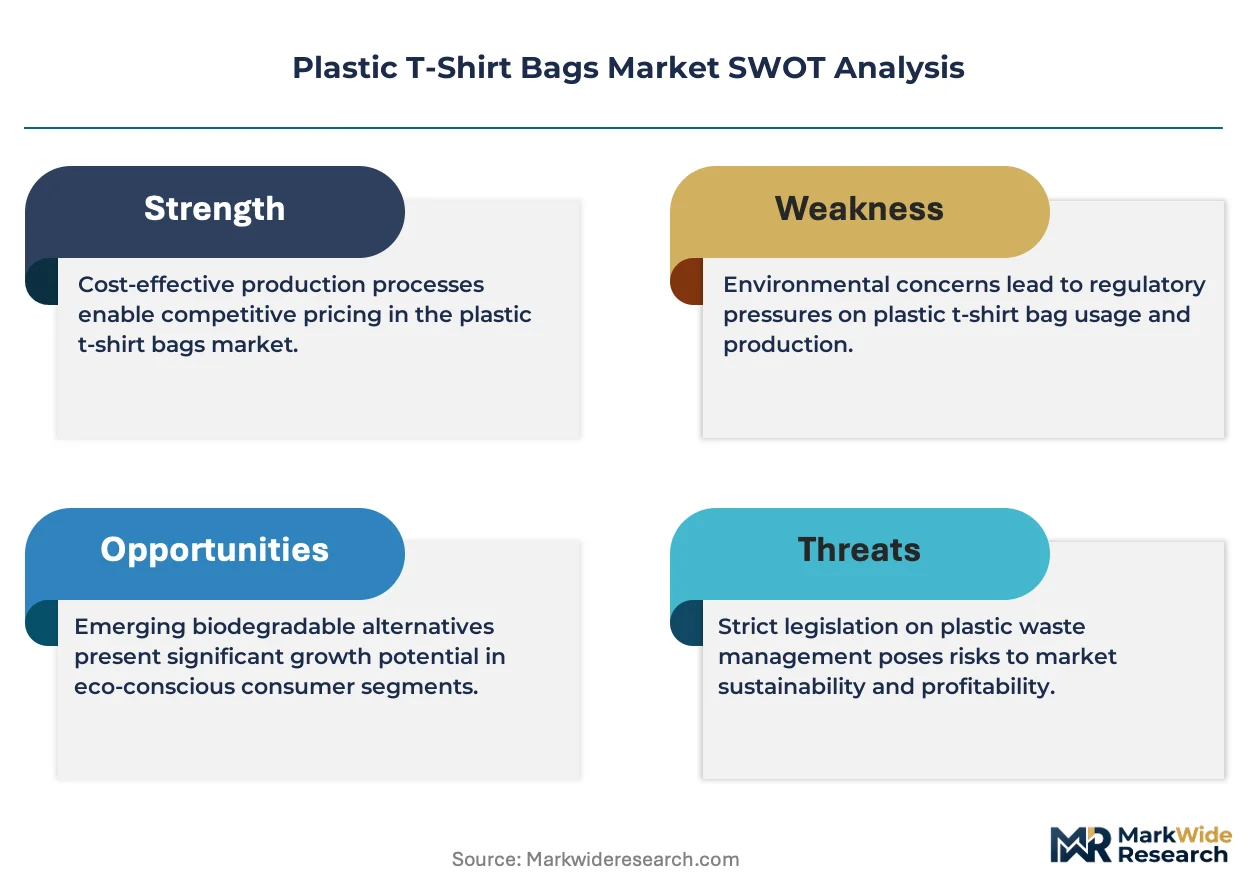
The EPA regulates manufacturing emissions from polyethylene film extrusion facilities under Clean Air Act provisions, while state-level bag bans in California and New York directly constrain single-use plastic distribution. The EU Packaging and Packaging Waste Regulation mandates minimum recycled content thresholds that reshape import eligibility for non-European suppliers. Stakeholders must monitor evolving extended producer responsibility frameworks to determine whether regional manufacturing relocation or material reformulation delivers superior compliance economics.
Market Dynamics
Biodegradable resin formulations are forcing a wholesale reconfiguration of raw material procurement across blown film extrusion operations, as municipal composting infrastructure spreads and brand owners face compliance deadlines.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Minimum recycled content thresholds are pulling post-consumer polyethylene back into film-grade supply chains, creating captive demand for rHDPE processors.
- India and Southeast Asian manufacturing clusters:Cost-competitive production scales are absorbing regional checkout volume growth as modern retail formats penetrate tier-2 and tier-3 cities.
- Heavy-duty HDPE formats:Grocery and bulk retail channels are specifying thicker gauge specifications for reusable-intent carry bags, extending per-unit resin consumption.
Market Restraints
- Crude-linked polyethylene feedstock volatility:Naphtha and ethylene price swings compress margin predictability for non-integrated converters lacking captive resin supply.
- California and New York state-level bag bans:Direct constraints on single-use plastic distribution eliminate entire checkout bag categories in high-volume retail corridors.
- Paper-based alternatives for last-mile delivery:E-commerce fulfillment centers are piloting fiber-based mailers and satchels that displace polyolefin carry sacks in premium logistics channels.
Strategic Opportunities
- Composting infrastructure gaps in secondary Indian cities:Early deployment of certified biodegradable formulations ahead of municipal waste segregation mandates creates first-mover positioning.
- Printed bag specialization for branded retail:High-definition flexographic and digital printing capabilities unlock private-label partnerships with fast-fashion and quick-service restaurant chains.
- Extended producer responsibility frameworks:Fee-modulated compliance systems in EU member states reward domestic manufacturing with lower eco-modulation levies versus import sourcing.
Industry Challenges
- Blown film extrusion technician scarcity:Specialized die and bubble control expertise is aging out of the workforce faster than vocational programs replenish qualified operators.
- Biodegradable certification timeline compression:ASTM D6400 and EN 13432 testing protocols require 6-12 month validation cycles that delay product launches behind regulatory enforcement dates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic T-Shirt Bags Market |
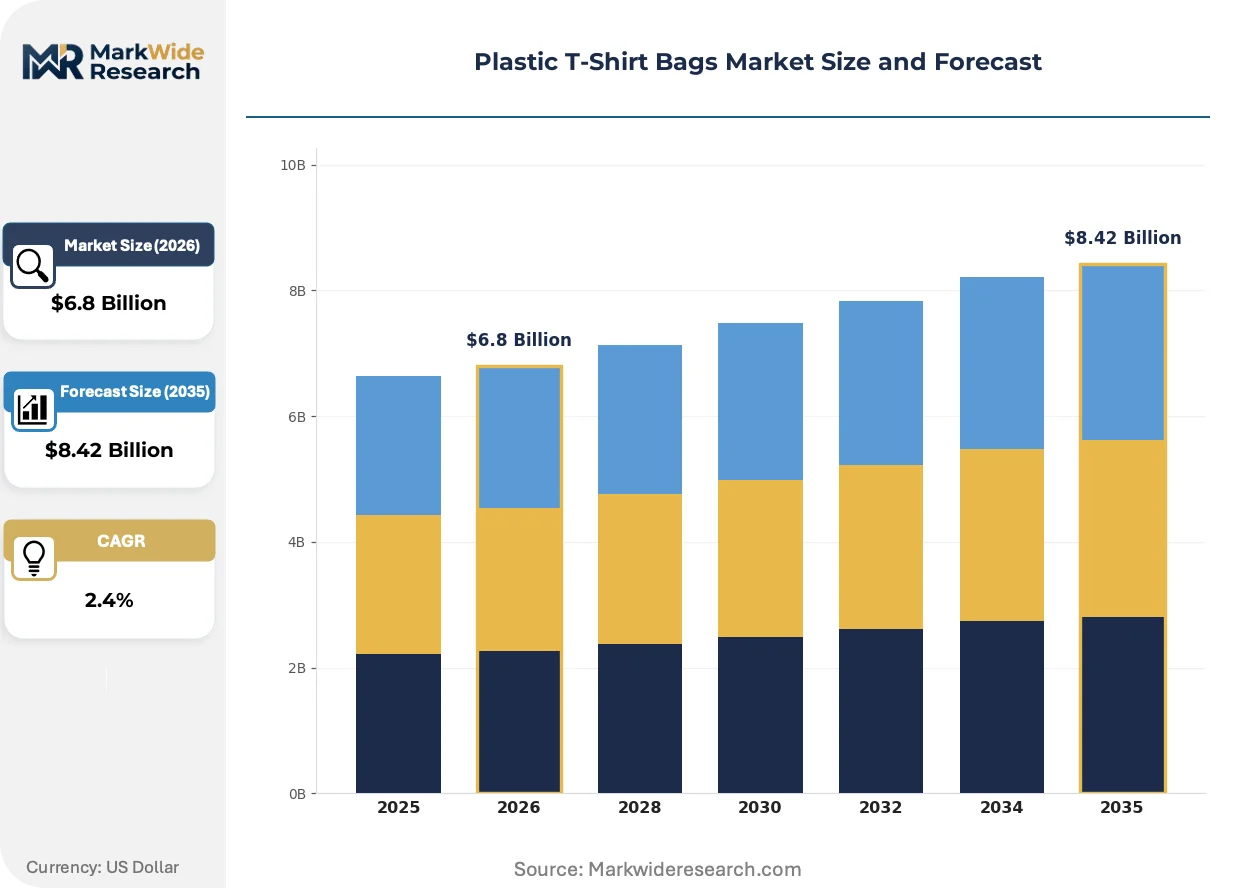
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $8.42 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
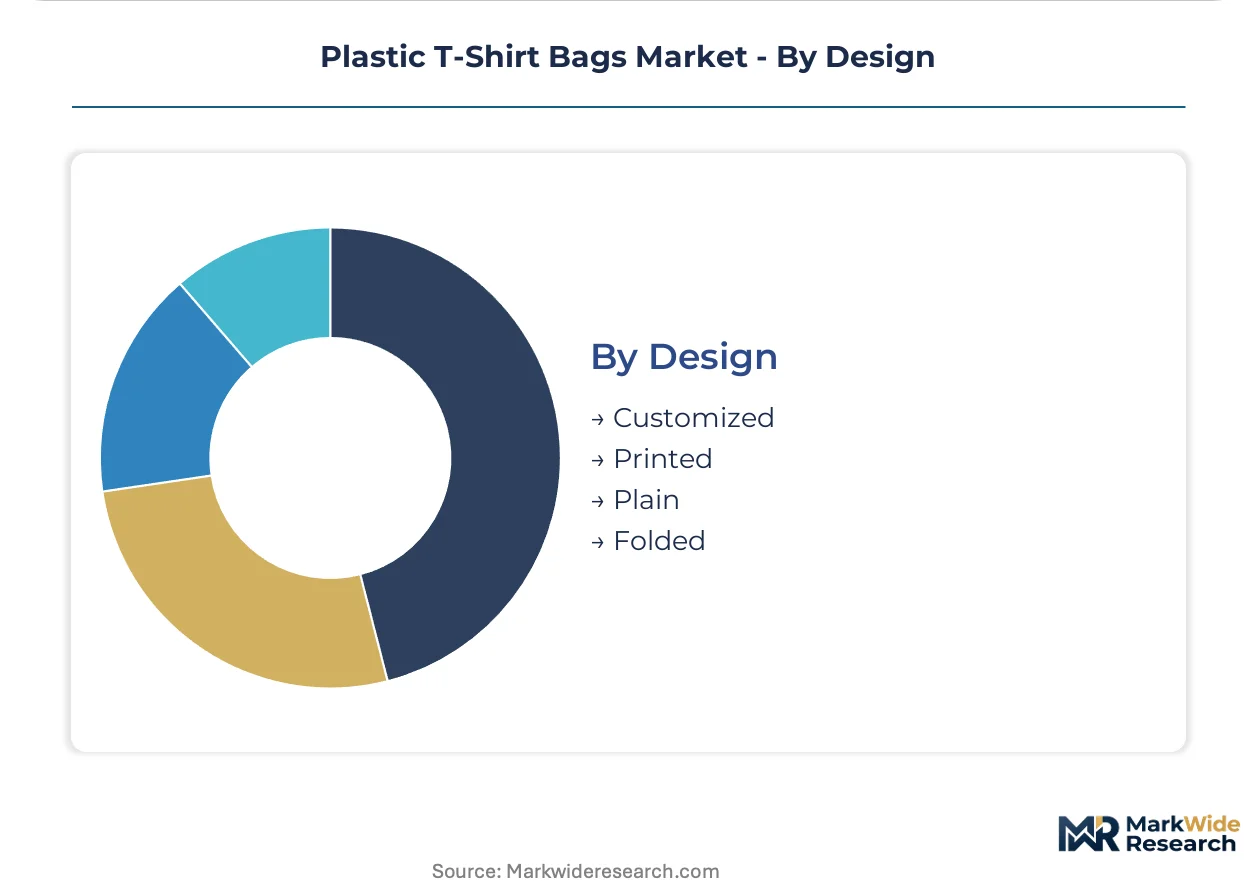
| Segmentation | Material Type: LDPE, HDPE, Biodegradable, Recycled Plastic End User: Retail, Food Service, Grocery, E-Commerce Thickness: Heavy Duty, Standard, Light Duty, Ultra-Light Design: Customized, Printed, Plain, Folded |
| Companies Covered | Novolex, ProAmpac, Advance Polybag, Inc., International Plastics Inc., BioBag Americas Inc., Heritage Bag Company, AplasticBag.com, Artek Packaging, FF-Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic T-Shirt Bags Market Evolving Landscape
Material science advances and regulatory chemistry restrictions are converging to redefine acceptable performance specifications for point-of-sale carry packaging across regulated jurisdictions.
Starch-blended and PLA-modified polyethylene formulations are absorbing the compliance burden from jurisdictions with aggressive organic waste diversion targets. Quick-service restaurant chains and specialty grocery banners are piloting these materials at 10-15% price premiums over conventional HDPE. The technology is absorbing volume from converters without in-house compostable certification capabilities, compressing their addressable market in regulated corridors.
REACH restrictions on intentionally added microplastics are extending to film-grade polymer additives across EU member states. Industrial consequence includes reformulation of slip agents and anti-block compounds used in high-speed bag conversion. European retail banners are responding by demanding full material disclosure from Asian contract manufacturers, shifting supplier qualification criteria toward certified additive transparency.
Consolidated procurement by retail banner groups is compressing supplier counts and extending contract durations. National grocery chains are displacing regional distributors with direct mill relationships that bundle bag supply with broader flexible packaging categories. This pattern is most visible in India's organized retail expansion, where Reliance Retail and DMart are standardizing specifications across hundreds of storefronts.
Plastic T-Shirt Bags Market Segmentation
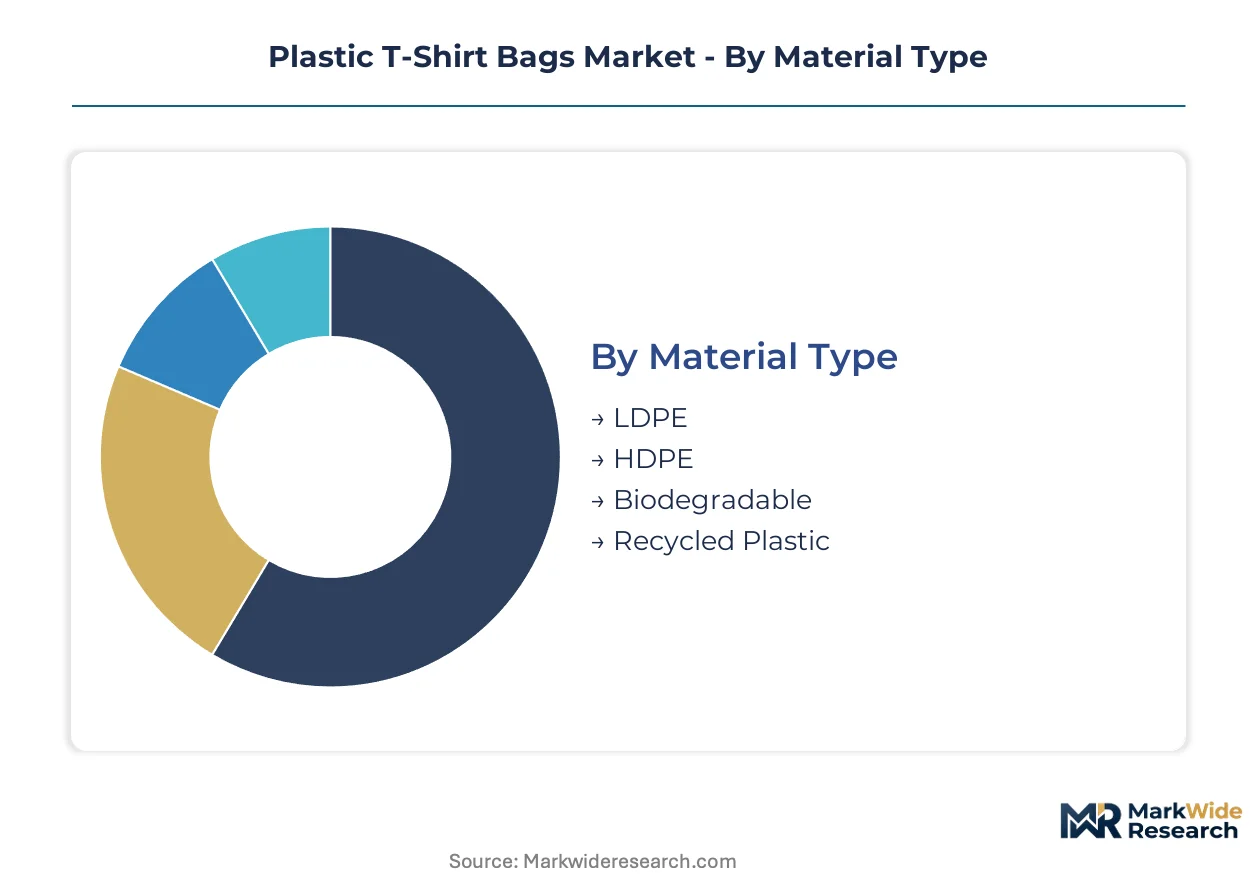
Material selection and thickness specifications determine compliance eligibility and cost structures across regulated retail corridors. End-use channel requirements and design capabilities further differentiate supplier positioning in contract manufacturing relationships.
Material Type:
Upgrade cycles from virgin to certified recycled and biodegradable formulations are shortening as municipal composting infrastructure spreads and EPR frameworks harden compliance deadlines.
- HDPE:High-density polyethylene delivers superior stiffness-to-weight ratios for heavy-load grocery applications. Demand concentrates in India's organized retail expansion where Reliance Retail and DMart standardize specifications across hundreds of storefronts, though state-level bans in Maharashtra and Karnataka constrain addressable volume.
- Biodegradable:Starch-blended and PLA-modified formulations absorb compliance burdens from jurisdictions with aggressive organic waste diversion targets. Quick-service restaurant chains in the EU pilot these materials at price premiums over conventional HDPE, compressing market access for converters lacking ASTM D6400 or EN 13432 certification capabilities.
- LDPE:Low-density polyethylene dominates flexible printed bag applications requiring high clarity and seal strength.
- Recycled Plastic:Post-consumer rHDPE volumes are climbing as EU Packaging and Packaging Waste Regulation mandates pull material back into film-grade supply chains.
Volume placements concentrate in HDPE; the faster expansion belongs to Biodegradable.
End User:
Customer type determines specification tolerance and contract duration, with banner-group procurement consolidating supplier relationships.
- Grocery:Heavy-duty formats with reinforced handles and thicker gauges serve reusable-intent carry requirements. India's tier-2 and tier-3 city modern retail penetration absorbs regional checkout volume growth as DMart and Reliance Retail displace traditional kirana stores.
- E-Commerce:Fulfillment center specifications are diverging sharply—paper-based alternatives displace polyolefin sacks in premium last-mile channels while cost-sensitive bulk shipments retain plastic. Amazon and Flipkart pilot fiber mailers that threaten volume retention in logistics corridors.
- Retail:Fast-fashion and specialty banners demand high-definition flexographic printing for branded carry experiences.
- Food Service:Quick-service restaurant chains specify grease-resistant formulations for hot-food transport.
Grocery anchors current volume; E-Commerce presents the steepest channel trajectory divergence.
Thickness:
Margin structures stratify across performance tiers as regulatory minimums and reusable-intent marketing reshape gauge specifications.
- Heavy Duty:Gauges exceeding 2.0 mils support multi-use positioning and bulk retail load requirements. California and New York bag ban exemptions for reusable-intent specifications extend addressable market for converters capable of certified durability testing.
- Standard:1.0-2.0 mil specifications balance cost and performance for mainstream grocery checkout applications.
- Light Duty:Sub-1.0 mil formats face elimination under escalating minimum gauge regulations across Indian states and EU member territories.
- Ultra-Light:Below 0.5 mil specifications retreat to unregulated informal retail channels with limited growth visibility.
Heavy Duty specifications gain share through reusable positioning; Light Duty faces regulatory compression.
Design:
Print capability and format flexibility determine private-label partnership access and contract value capture.
- Printed:High-definition flexographic and digital printing unlocks branded retail relationships. Fast-fashion banners and quick-service restaurant chains specify Pantone-matched colors and QR-integrated designs that command specification premiums.
- Customized:Die-cut handle shapes, gusset configurations, and size gradations serve specialty retail format requirements.
- Plain:Unprinted commodity formats compete on resin cost and conversion efficiency alone.
- Folded:Pre-creased and interleaved formats accelerate cashier throughput in high-volume supermarket environments.
Printed designs capture relationship value; Plain formats retreat to undifferentiated wholesale channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Checkout volume growth concentrates in India and Southeast Asian manufacturing clusters where cost-competitive production scales rapidly. Modern retail expansion in tier-2 and tier-3 cities absorbs regional bag consumption. Regulatory fragmentation across state and national boundaries creates divergent compliance pathways for resin procurement and finished goods distribution.
United States
State-level bag bans in California and New York eliminate entire checkout bag categories in high-volume retail corridors. The EPA regulates manufacturing emissions from polyethylene film extrusion facilities under Clean Air Act provisions. Houston and Dallas manufacturing clusters serve domestic grocery and food service channels with heavy-duty HDPE formats.
Germany
EU Packaging and Packaging Waste Regulation mandates minimum recycled content thresholds that reshape import eligibility for non-European suppliers. REACH restrictions on intentionally added microplastics extend to film-grade polymer additives. The Ruhr industrial region hosts blown film extrusion operations supplying branded retail banners across Central Europe.
India
Reliance Retail and DMart standardize specifications across hundreds of storefronts, displacing traditional kirana stores in tier-2 and tier-3 cities. State-level bans in Maharashtra and Karnataka constrain addressable volume for conventional HDPE formats. Ahmedabad and Surat manufacturing clusters scale cost-competitive production for domestic organized retail expansion.
Vietnam
Export-oriented contract manufacturers supply EU and North American retail banners with certified recycled and biodegradable formulations. The country's central bank monitors foreign exchange volatility affecting resin import costs. Ho Chi Minh City and Binh Duong industrial zones concentrate blown film extrusion capacity serving international procurement offices.
Brazil
Quick-service restaurant chains and supermarket banners drive specification standardization across Latin America's largest consumer market. ANVISA regulates food-contact film additives for food service applications. São Paulo state anchors domestic manufacturing capacity with distributors serving Rio de Janeiro and Minas Gerais retail corridors.
Plastic T-Shirt Bags Market Competitive Landscape
Capacity expansion dominates the current landscape as converters add blown film lines to capture organized retail procurement consolidation. The vendor base stratifies across integrated resin-to-film operators, specialized printed bag converters, and regional commodity suppliers. Three archetypes prevail: vertically integrated resin producers with captive film extrusion, brand-focused specialists with high-definition printing capabilities, and scale-driven contract manufacturers serving banner-group procurement. Geographic expansion and material reformulation represent the dominant competitive moves as players position for biodegradable certification requirements and extended producer responsibility frameworks.
Among North American integrated operators, Novolex leverages upstream control over resin sourcing and blown film extrusion. ProAmpac occupies a position within the specialty printed bag tier, serving branded retail relationships. Advance Polybag, Inc. anchors the heavy-duty HDPE segment for grocery and bulk retail channels. These three exemplify how competitive positioning stratifies across material control, print capability, and performance specification depth.
| Leading Market Players |
|---|
| Novolex |
| ProAmpac |
| Advance Polybag, Inc. |
| International Plastics Inc. |
| BioBag Americas Inc. |
| Heritage Bag Company |
| AplasticBag.com |
| Artek Packaging |
| FF-Packaging |
| Others |
Value Network & Pricing Analysis
Captive resin supply through backward integration into ethylene and naphtha sourcing anchors both cost predictability and pricing power for converters serving banner-group procurement. Novolex and integrated Asian operators leverage in-house polyethylene production to buffer margin compression from crude-linked feedstock volatility that squeezes non-integrated competitors in India and Vietnam.
Pricing Analysis
Volume placements in plain commodity formats compete on resin cost alone, while margin capture concentrates in certified biodegradable and high-definition printed tiers. Price differentiation separates ASTM D6400-certified compostable grades from conventional HDPE by certification burden and testing timeline, with quick-service restaurant chains absorbing 10-15% premiums for compliance-ready supply. Cost compression in standard gauge specifications is intensifying as Reliance Retail and DMart consolidate procurement across hundreds of storefronts. Price-sensitive kirana store distributors in India's informal retail channels resist any premium over baseline HDPE, while EU retail banners prioritize certified additive transparency over unit cost.
Supply Chain Analysis
Polyethylene resin supply rests on naphtha crackers concentrated in Saudi Arabia, South Korea, and the US Gulf Coast, with Asian converters drawing heavily from Middle Eastern ethylene exports. Blown film extrusion operations hinge on imported masterbatch additives from German and Japanese specialty chemical producers, particularly for compostable formulations requiring EN 13432-compliant slip agents. Single-source vulnerability in certified biodegradable resin supply creates bottlenecks as municipal composting mandates spread. Distribution runs through banner-group direct mill relationships that displace regional wholesale channels, with national grocery chains bundling bag supply with broader flexible packaging categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biodegradable certification capacity constitutes the binding constraint propping pricing power for compliant converters, as testing protocol backlogs extend qualification timelines beyond regulatory enforcement dates.
For Market Incumbents: Anticipate state-level ban expansion by securing reusable-intent durability certification for heavy-duty formats that qualify for California and New York exemptions. Defensive consolidation through acquisition of regional printed-bag specialists preserves access to fast-fashion and quick-service restaurant relationships as banner-group procurement compresses supplier counts. Backward integration into rHDPE processing captures EU Packaging and Packaging Waste Regulation compliance premiums before import eligibility rules harden. For New Entrants and Emerging Players: Launch via certified biodegradable supply to quick-service restaurant chains in EU corridors where incumbent converters lack ASTM D6400 or EN 13432 capabilities. White-space targets include composting infrastructure gaps in secondary Indian cities ahead of municipal waste segregation mandates, and high-definition flexographic printing for specialty grocery banners in Vietnam's export manufacturing zones. Go-to-market positioning centers on additive transparency documentation that satisfies REACH restriction compliance for European retail procurement offices. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated packaging conglomerates seeking biodegradable certification capabilities and regional production footprints in India or Southeast Asia. Long-term viability favors converters with captive resin supply and established banner-group relationships over commodity-dependent regional players. The signal to watch is EU eco-modulation levy implementation timing, which would accelerate manufacturing relocation economics for non-European suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Certification Investment | ASTM D6400 and EN 13432 qualifications unlock EU quick-service restaurant procurement corridors. |
| Backward Integration into rHDPE Processing | Post-consumer recycled content capabilities satisfy EU Packaging and Packaging Waste Regulation minimum thresholds. |
| High-Definition Flexographic Printing Scale-Up | Pantone-matched and QR-integrated designs command specification premiums from fast-fashion banners. |
| Heavy-Duty Format Durability Testing | Reusable-intent certification preserves market access under California and New York state-level bag bans. |
| Direct Mill Relationships with Banner Groups | Reliance Retail and DMart procurement consolidation rewards suppliers bundling bag and flexible packaging supply. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with blown film extrusion plant managers, procurement leads at organized retail banners, distribution channel partners, and technical R&D directors specializing in compostable formulations. Secondary validation drew from EPA Clean Air Act enforcement records, EU Packaging and Packaging Waste Regulation implementation documents, Indian state-level ban notifications, and SEC 10-K disclosures from integrated polyethylene producers. Bottom-up capacity and production estimates triangulated against top-down consumption models derived from retail checkout volume and organized retail expansion metrics.
Data-stream reconciliation across resin procurement, converting capacity, and end-use channel demand generated volume and value outputs across the analysis window. Segmentation modeling incorporated material type, thickness specification, end-use channel, and design capability dimensions, with regional regulatory cluster treatment for EU, US state-level, and Indian state-level compliance pathways. CAGRs were derived from trend extrapolation of checkout volume growth, retail format penetration rates, and substitution dynamics from paper-based alternatives. Industry-specific forecast inputs included blown film extrusion line addition announcements and municipal composting infrastructure deployment timelines.
Feedstock price volatility, regulatory enforcement acceleration, and biodegradable resin supply bottlenecks are the dominant revision risks to modeled outputs. Forecasts reflect assumptions regarding banner-group procurement consolidation speed and EU eco-modulation levy implementation scope. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Clear Plastic Boxes Market
Plastic Packaging
Brazil Plastic Bottles Market
Plastic Packaging
Plastic Films Market
Plastic Packaging
Plastic Canister Market
Plastic Packaging
Latin America Single-Use Plastic Packaging Market
Plastic Packaging
Mexico Plastic Bottles Market
Plastic Packaging
Sugarcane Based PET Bottles Market
Plastic Packaging
US Lubricant Contaminated HDPE Container Waste Market
Plastic Packaging
Plastic Shrink Wrap Market
Plastic Packaging
GCC Plastic Packaging Market
Plastic Packaging
MENA Thermoform Plastic Packaging Market
Plastic Packaging
United States Plastic Packaging Films Market
Plastic Packaging
Advanced-Recycled Polyethylene for E-Commerce Packaging Market
Plastic Packaging
Compostable Plastic Packaging Material Market
Plastic Packaging
Plastic Ready Meal Trays Market
Plastic Packaging
Asia Pacific Single-Use Plastic Packaging Market