
 Global Plastic Bottle Recycling Market | 2026-2036
Global Plastic Bottle Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Global Plastic Bottle Recycling Market Foresight
Food-grade rPET certification is reorganizing competitive tiers across the Global Plastic Bottle Recycling Market. Indorama Ventures Public Company Limited leverages its integrated polyester chain to secure long-term supply agreements with major bottlers. Veolia Environnement S.A. anchors its position through municipal collection contracts and sorting infrastructure density in Western Europe. TOMRA Sorting GmbH dominates sensor-based bottle detection technology, giving equipment buyers higher purity yields at commercial scale.
Global Plastic Bottle Recycling encompasses the collection, sorting, cleaning, and reprocessing of post-consumer bottles into resin flakes or pellets suitable for remanufacturing, typically requiring contamination levels below specified thresholds for mechanical reprocessing. The primary purpose is to displace virgin polymer demand in packaging and fiber applications while reducing landfill and ocean leakage. Polyethylene Terephthalate commands the largest volume share due to established beverage bottle collection streams and mature mechanical recycling economics. Chemical Recycling is gaining structural traction for colored, multi-layer, and degraded feedstocks that mechanical routes cannot valorize profitably. Deposit Return Systems generate the highest-quality input streams, creating margin concentration for operators with access to these channels.
The EU Green Deal and its Packaging and Packaging Waste Regulation set binding recycled content minimums that reshape procurement mandates for converters across member states. EPA guidelines in the United States influence state-level recycling rate targets and extended producer responsibility frameworks. FDA food-contact approvals for post-consumer rPET determine which recyclers can access premium beverage packaging contracts. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate where compliance investments will unlock market access versus where fragmented standards inflate operational complexity.
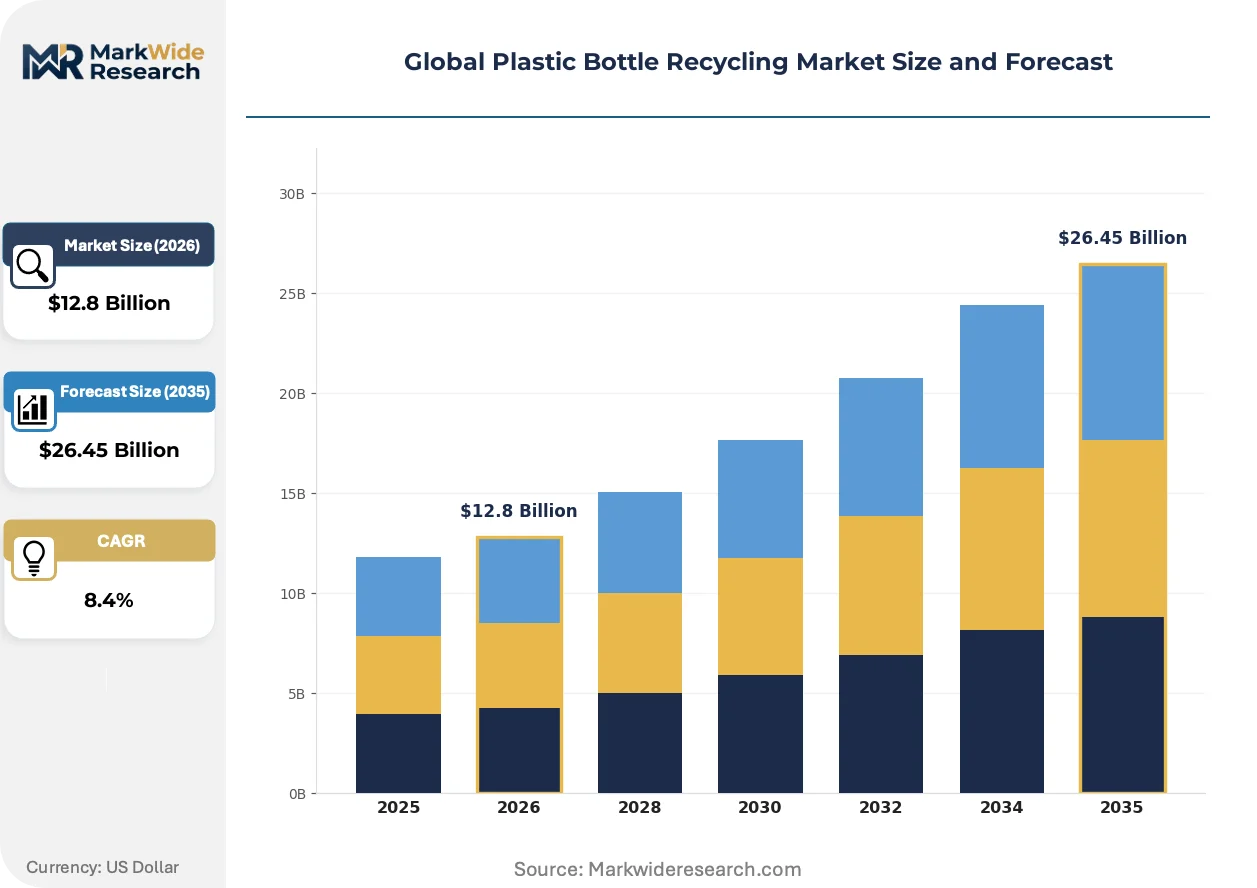
Market Dynamics
Deposit return infrastructure concentration in Germany and Nordic systems is creating a two-tier feedstock quality landscape, separating premium bottle-to-bottle recyclers from commodity flake operators dependent on curbside collection with higher contamination baselines.
Growth Catalysts
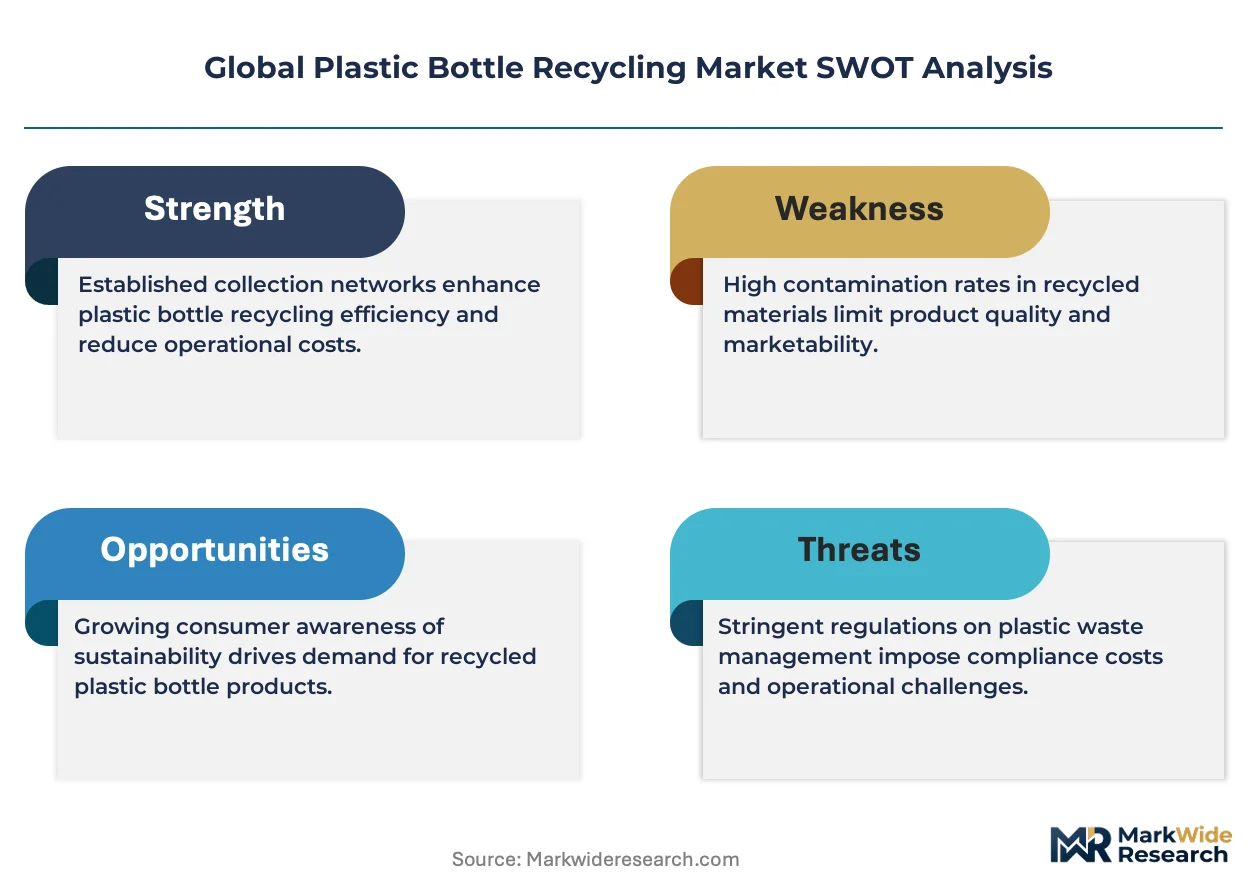
- EU Green Deal Packaging Waste Regulation:Binding recycled content minimums for beverage bottles force brand procurement teams to secure long-term rPET offtake, pulling investment into food-grade purification capacity.
- Chemical recycling pyrolysis:Degradation-tolerant processing of colored and multi-layer PET streams unlocks feedstock volumes that mechanical routes discard, expanding addressable supply by 15-20% in pilot deployments.
- Germany:Deposit return system density and sorting automation investments produce the continent's highest-purity baled feedstock, concentrating margin capture for operators with licensed access to these channels.
Market Restraints
- Baled PET price volatility:Tight correlation with virgin resin pricing and seasonal collection variation compresses recycler margins when oil markets soften, particularly for non-integrated operators lacking backward polymer control.
- China import restrictions:Post-National Sword policies eliminated a major export destination for mixed plastic bales, forcing Western collectors to absorb lower-value domestic processing or pay for landfill diversion.
- Mechanical recycling degradation:Intrinsic viscosity loss through repeated thermal cycling limits food-grade reprocessing to 2-3 loops before downcycling to fiber applications, capping premium market penetration.
Strategic Opportunities
- India:Underdeveloped organized collection infrastructure and emerging EPR frameworks create first-mover advantage for deposit system pilots in Maharashtra and Gujarat beverage corridors.
- Digital watermark integration:Convergence of invisible marker technology with AI-driven sorting lines enables brand-specific bottle identification, unlocking closed-loop takeback programs with traceability premiums.
- US FDA Letter of No Objection acceleration:Streamlined food-contact approval pathways for novel purification technologies reduce time-to-market for advanced mechanical recyclers targeting premium bottler contracts.
Industry Challenges
- Food-grade rPET certification timelines:Extended validation protocols for novel decontamination technologies delay commercial deployment, locking out capital-intensive projects from premium contract bidding windows.
- Optical sorting technician scarcity:Specialized calibration and maintenance skills for near-infrared and X-ray fluorescence detection systems outpace vocational training pipeline development in established European recycling hubs.
- Legacy washing line reconfiguration:Retrofitting caustic soda-based cleaning infrastructure for hot-caustic or superheated steam food-grade standards requires extended downtime and capital allocation that mid-cap operators struggle to sequence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Plastic Bottle Recycling Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $26.45 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Plastic Type: Polyethylene Terephthalate, High-Density Polyethylene, Polyvinyl Chloride, Polypropylene, Polystyrene Recycling Technology: Mechanical Recycling, Chemical Recycling, Thermal Processing, Enzymatic Recycling, Pyrolysis End Use Industry: Packaging, Construction, Textile Manufacturing, Automotive Components, Consumer Goods Collection Channel: Municipal Waste Collection, Deposit Return Systems, Curbside Collection, Buy-Back Centers, Informal Collection |
| Companies Covered | Indorama Ventures Public Company Limited, Plastipak Holdings Inc., Veolia Environnement S.A., Loop Industries Inc., Phoenix Technologies International LLC, TOMRA Sorting GmbH, Closed Loop Partners, Suez SA, Evergreen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Plastic Bottle Recycling Market Shifts & Advancements
Advanced detection and purification technologies are fragmenting the historical mechanical recycling monopoly, creating parallel processing tracks for different feedstock quality tiers and end-use specifications.
Chemical recycling via glycolysis and methanolysis is bifurcating the rPET landscape into two quality strata. Beverage multinationals with circular commitments are contracting dedicated offtake from these plants for colored and degraded feedstocks. This technology is compressing the addressable market for commodity mechanical recyclers while enabling premium pricing for operators with molecular purification capabilities.
EU Green Deal implementation timelines are tightening across member states, with the Packaging and Packaging Waste Regulation mandating specific recycled content thresholds that escalate through 2030. National transposition variations are creating compliance complexity for converters operating across Belgium, France, and Italy simultaneously. Large bottlers are responding by consolidating supplier relationships with pan-European recyclers capable of certifying multi-jurisdictional compliance.
Brand-led procurement consortiums are displacing spot-market flake purchasing with multi-year supply agreements tied to specific collection geography and carbon footprint verification. Major beverage and personal care manufacturers in the Netherlands and Denmark are requiring mass-balance documentation from recyclers. This contractual shift is most visible in the premium bottled water segment, where rPET content serves as explicit consumer-facing differentiation.
Global Plastic Bottle Recycling Market Segmentation
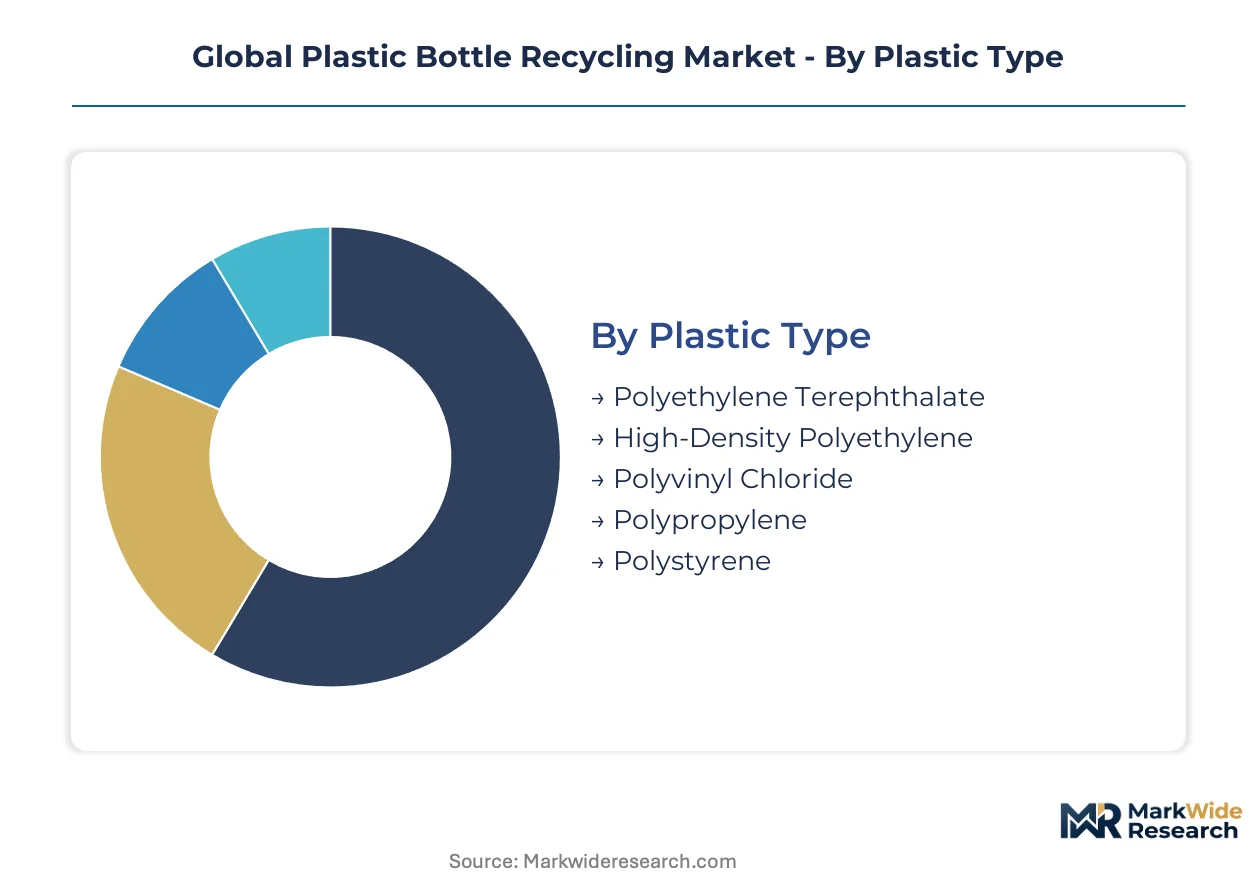
Segmentation in plastic bottle recycling determines which purification standards apply, which regulators certify output, and where margin pools concentrate. Feedstock source and polymer type together dictate whether mechanical or chemical routes deliver viable unit economics.
Plastic Type:
EU Green Deal thresholds for beverage packaging apply differentially across polymers, with only PET currently achieving food-grade mechanical recycling at commercial scale. FDA and EFSA approvals cluster heavily on specific resin grades, creating regulatory moats for compliant operators.
- Polyethylene Terephthalate:Dominant beverage bottle polymer with established collection density and mature mechanical recycling infrastructure. Demand concentrates in Germany and the Netherlands where deposit return systems generate baled feedstock with contamination rates below 2%, enabling direct food-grade reprocessing without intermediate downcycling steps.
- High-Density Polyethylene:Milk and detergent bottle polymer requiring distinct sorting lines due to density separation physics. Milk bottle applications in the United Kingdom and France are pulling food-grade HDPE capacity investments as dairy processors face retailer pressure for recycled content commitments.
- Polyvinyl Chloride:Limited beverage presence due to chlorine content complicating thermal reprocessing. Construction pipe applications in Italy and Spain absorb most recovered volume.
- Polypropylene:Caps and closures polymer often co-mingled with PET bales, demanding advanced optical sorting for separation. Automotive battery casing applications in Japan and South Korea provide secondary demand outlets.
- Polystyrene:Minimal bottle packaging share; expanded foam food service dominates recovered streams. Insulation board manufacturing in Belgium and Austria consumes available flake supply.
Established volume favors Polyethylene Terephthalate; emerging adoption favors High-Density Polyethylene as dairy and personal care brands accelerate recycled content procurement.
Recycling Technology:
Technology choice hinges on feedstock degradation state and end-use purity requirements, with capital intensity varying tenfold between mechanical flake lines and chemical depolymerization plants.
- Mechanical Recycling:Dominant route for clear PET bottles with intact molecular weight, producing flake or pellet through washing, sorting, and extrusion. Capacity concentrates in Germany, Belgium, and Austria where automated sorting infrastructure achieves 99.5% polymer purity thresholds required for food-contact approval.
- Chemical Recycling:Glycolysis and methanolysis routes rebuild degraded or colored PET to virgin-equivalent quality. Pilot deployments in France and the Netherlands are processing feedstock that mechanical operators discard, with beverage multinationals contracting dedicated offtake at premiums to commodity flake.
- Thermal Processing:Energy recovery and syngas generation for contaminated or multi-layer streams lacking mechanical valorization pathways. Waste-to-energy integration in Sweden and Denmark provides outlet for residual fractions.
- Enzymatic Recycling:Biological depolymerization using engineered enzymes targeting PET crystalline regions. Laboratory-scale operations in Japan and California are advancing toward pilot throughput validation.
- Pyrolysis:Thermal decomposition of mixed plastics to synthetic crude or monomer feedstock. Commercial units in Germany and the United Kingdom process colored PET and polyolefin blends excluded from mechanical circuits.
Mechanical Recycling commands current margin pools; Chemical Recycling is climbing the fastest as brand circular commitments outstrip food-grade mechanical supply.
End Use Industry:
Application specifications determine contamination tolerance and certification burden, with packaging demanding the most stringent decontamination validation.
- Packaging:Beverage, food, and personal care containers requiring FDA or EFSA food-contact approval. Brand procurement in Germany, France, and the Netherlands is consolidating around multi-year rPET supply agreements with mass-balance traceability.
- Construction:Pipes, insulation, and geotextiles accepting lower purity grades with reduced regulatory scrutiny. Infrastructure spending in Poland and Romania is absorbing non-food-grade flake output.
- Textile Manufacturing:Polyester fiber and filament production from downcycled PET with relaxed viscosity requirements. Carpet and apparel applications in Turkey and India provide demand depth for degraded mechanical outputs.
- Automotive Components:Interior trim and under-hood applications requiring specific thermal and mechanical properties. Tier-1 supplier specifications in Germany and the United States are incorporating recycled content targets.
- Consumer Goods:Durable products including furniture and electronics housings with moderate purity thresholds. Retailer private-label commitments in the United Kingdom are pulling recycled polypropylene and HDPE into non-food applications.
Packaging extracts the highest price premiums; Construction provides volume absorption for downcycled outputs.
Collection Channel:
Channel economics determine feedstock quality tiers, with automated deposit systems generating bales that command 15-30% price premiums over curbside material.
- Municipal Waste Collection:Mixed residential waste streams requiring extensive post-collection sorting. Germany and Austria operate the most advanced automated facilities, achieving PET capture rates above 90% from commingled inputs.
- Deposit Return Systems:Reverse vending machines and manual collection points producing single-polymer bales with minimal contamination. Nordic systems in Norway, Sweden, and Denmark achieve the highest bottle-to-bottle recycling rates globally through this channel concentration.
- Curbside Collection:Source-separated or single-stream residential pickup with variable contamination baselines. France and Belgium are retrofitting sorting lines with AI-driven detection to upgrade curbside output quality.
- Buy-Back Centers:Voluntary drop-off locations with manual sorting and weight-based compensation. Informal sector integration in India and Brazil leverages this channel for PET bottle aggregation.
- Informal Collection:Independent waste picker networks recovering post-consumer bottles from dumpsites and public spaces. Mumbai and São Paulo municipal programs are formalizing these channels through registration and fair-price guarantees.
Deposit Return Systems dominate premium feedstock supply; Informal Collection is expanding most quickly in emerging markets as EPR frameworks recognize picker network integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Feedstock quality tiers concentrate recycling margin capture in systems with dense deposit return infrastructure. Germany and Nordic markets generate premium bale streams that command sustained price premiums over curbside-dependent regions.
Germany
Beverage brand compliance investments and automated sorting density anchor the continent's highest-purity PET supply. The EU Green Deal's packaging waste directives drive converter procurement consolidation around domestic recyclers with multi-jurisdictional certification capabilities. North Rhine-Westphalia hosts the densest concentration of food-grade mechanical reprocessing lines.
United States
State-level extended producer responsibility frameworks in California and Oregon reshape collection economics away from landfill-dependent models. FDA Letter of No Objection pathways for novel purification technologies determine which recyclers access premium bottler contracts. The Southeast corridor attracts chemical recycling pilot investments targeting colored and multi-layer feedstock streams.
France
Dairy processor recycled content commitments pull food-grade HDPE capacity expansion alongside established PET infrastructure. National transposition of EU Packaging and Packaging Waste Regulation mandates escalates converter compliance timelines through 2030. The Lyon-Grenoble cluster concentrates chemical recycling pilot deployments for degraded polymer valorization.
India
Emerging EPR frameworks in Maharashtra and Gujarat beverage corridors create first-mover positioning for organized collection system pilots. Municipal programs in Mumbai formalize informal picker networks through registration and fair-price guarantees. Ahmedabad and Surat industrial zones absorb downcycled flake output for textile fiber applications.
Netherlands
Brand-led procurement consortiums displace spot-market purchasing with multi-year supply agreements tied to carbon footprint verification. Mass-balance documentation requirements from beverage and personal care manufacturers consolidate supplier relationships with pan-European recyclers. Rotterdam-Antwerp logistics infrastructure enables feedstock arbitrage across Belgian and German sorting networks.
Global Plastic Bottle Recycling Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Global Plastic Bottle Recycling Market. Integrated polyester producers with backward polymer control capture margin stability during virgin resin price volatility. Specialized equipment manufacturers dominate sensor-based detection technology. Municipal contractors anchor regional feedstock access through collection infrastructure density. Capacity expansion and strategic partnerships represent the dominant competitive moves as brand circular commitments outstrip certified food-grade supply.
Within the integrated producer tier, Indorama Ventures Public Company Limited and Plastipak Holdings Inc. exemplify archetypes combining resin manufacturing with recycling capacity. Veolia Environnement S.A. and Suez SA occupy positions anchored through municipal collection contracts and sorting infrastructure density in Western European markets. TOMRA Sorting GmbH represents the equipment specialization vector, with sensor-based bottle detection technology delivering purity yields at commercial scale.
| Leading Market Players |
|---|
| Indorama Ventures Public Company Limited |
| Plastipak Holdings Inc. |
| Veolia Environnement S.A. |
| Loop Industries Inc. |
| Phoenix Technologies International LLC |
| TOMRA Sorting GmbH |
| Closed Loop Partners |
| Suez SA |
| Evergreen |
| Others |
Supply & Pricing Matrix
Food-grade rPET displacement of virgin PET resin simultaneously redraws supply geography toward deposit-system corridors and compresses pricing premiums for mechanical recyclers lacking molecular purification capabilities. EU Green Deal mandates force beverage brands to absorb cost differentials, while oil-price volatility transmits directly into bale feedstock benchmarks.
Pricing Analysis
The EU Green Deal's Packaging and Packaging Waste Regulation dictates the pricing tier structure across the Global Plastic Bottle Recycling Market. Three-tier pricing stratifies across food-grade bottle-to-bottle, non-food packaging, and fiber-grade downcycled outputs. Price differentiation centers on EFSA certification status and deposit-system feedstock provenance. Cost compression in commodity flake tiers is intensifying because chemical recycling pilots capture previously discarded colored streams. Small converters dependent on spot-market sourcing exhibit highest price sensitivity; integrated bottlers with long-term offtake agreements demonstrate lowest.
Supply Chain Analysis
Just-in-time feedstock delivery dominates mechanical recycling operations, while chemical recyclers maintain strategic stockpiles of degraded polymer awaiting batch processing. Supply concentrates in Germany, Belgium, and the Netherlands where automated sorting infrastructure achieves 99.5% purity thresholds. Raw material flows draw from municipal collection contracts, deposit return system operators, and informal picker networks in emerging markets. Single-source vulnerability concentrates in TOMRA equipment dependency for optical sorting calibration. Distribution runs through pan-European logistics corridors anchored on Rotterdam-Antwerp port infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Beverage brand procurement consolidation into multi-year supply agreements has shifted buyer power toward large bottlers, fragmenting spot-market liquidity and squeezing mid-cap recyclers without certified capacity.
For Market Incumbents: Shield food-grade certification moats through accelerated FDA Letter of No Objection submissions for novel decontamination technologies. Chemical recycling entrants threaten mechanical operators with molecular purification capabilities; backward integration into deposit return system contracts secures captive feedstock access against bale price volatility. For New Entrants and Emerging Players: Post-consumer traceability service layers remain underdeveloped by incumbents focused on volume throughput. Target India and Brazil informal collection formalization programs where EPR frameworks create first-mover positioning. Go-to-market through brand-led procurement consortiums requiring mass-balance documentation premiums. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mechanical recyclers in Germany and Benelux holding FDA-approved capacity but lacking chemical recycling optionality. Five-to-ten year viability hinges on molecular purification technology access. Monitor EU member state transposition timelines for Packaging and Packaging Waste Regulation as inflection signal for compliance investment urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Food-Grade Certification Investment | FDA Letter of No Objection unlocks premium bottler contracts with multi-year pricing floors. |
| Deposit System Contract Securement | Municipal and reverse vending agreements in Germany provide contamination-rate advantages. |
| Chemical Recycling Pilot Deployment | Glycolysis capacity in France and Netherlands processes feedstock mechanical routes discard. |
| Informal Collection Formalization | Picker network registration in Maharashtra creates EPR-compliant supply for textile fiber outlets. |
| Digital Watermark Integration | AI-driven sorting lines with invisible marker technology enable brand-specific closed-loop programs. |
Research Methodology
A standing panel of recycling plant managers, municipal collection contract officers, beverage brand procurement leads, and optical sorting technicians provided ongoing calibration across primary interview rounds. Secondary validation drew from EU Packaging and Packaging Waste Regulation filings, EPA state-level EPR framework documents, FDA food-contact approval databases, and customs trade data on baled PET flows. Bottom-up capacity modeling triangulated against top-down brand recycled content commitment aggregation.
Consistency checks validated volume and value outputs against external benchmarks including deposit system operator throughput disclosures and recycler SEC filings. Segmentation modeling spanned plastic type, recycling technology, end-use industry, and collection channel dimensions across the analysis window. CAGRs derived from logistic adoption curves for chemical recycling penetration and linear projection for mechanical capacity expansion. Industry-specific inputs included EFSA certification timeline distributions and informal collection formalization rates in emerging markets.
Underlying assumptions cover EU member state regulatory transposition schedules, oil-price correlation with virgin PET benchmarks, and chemical recycling scale-up velocity, with deviation risk concentrated in FDA approval pathway delays for novel purification technologies. Revision becomes warranted when deposit return system expansion rates in target geographies cross materiality thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Middle East and Africa Plastic Packaging Market
Plastic Packaging
Transparent Plastic Packaging Market
Plastic Packaging
United Arab Emirates Plastic Packaging Market
Plastic Packaging
Injection Molded Plastics Market
Plastic Packaging
Plastic Cutlery Market
Plastic Packaging
Plastic Tubes Market
Plastic Packaging
South Africa Plastic Packaging Market
Plastic Packaging
Plastic Corrugated Sheets Market
Plastic Packaging
Global Molded Plastic Packaging Market
Plastic Packaging
Plastic Keg Market
Plastic Packaging
Plastic Tumblers Market
Plastic Packaging
Canada Plastic Packaging Market
Plastic Packaging
Recycled Plastic Envelope Market
Plastic Packaging
Compostable Plastic Packaging Material Market
Plastic Packaging
South America Polyethylene Terephthalate (PET) Market
Plastic Packaging
Asia-Pacific Plastic Bottles and Containers Market