
 Plastic Cans Market | 2026-2036
Plastic Cans Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Cans Market Analytics
Skilled blow-molding technicians is collapsing across Central European manufacturing hubs, tightening output capacity for multilayer barrier cans. Amcor plc leverages captive resin compounding to insulate margin pools from feedstock volatility. Plastipak Holdings, Inc. anchors North American beverage conversions through dedicated preform-to-can production lines. ALPLA specializes in integrated injection-stretch-blow systems that shorten lead times for personal care brands.
Plastic cans are cylindrical containers fabricated from polyethylene terephthalate, polypropylene, or multilayer barrier polymers through extrusion blow molding or injection stretch blow molding, designed to store solids, liquids, or pressurized contents with oxygen and moisture protection. Reusable formats lead in food packaging as institutional buyers prioritize returnable logistics systems, while single-use variants dominate beverage applications where lightweighting drives freight economics. Collapsible designs represent the fastest-growing size-adjacent category as chemical distributors seek empty-container volume reduction for reverse logistics efficiency.
The EU's REACH framework and F-Gas Regulation constrain fluorinated barrier chemistries, redirecting R&D toward plasma-enhanced deposition and bio-based polyester alternatives. The US FDA maintains extractables testing protocols that delay new polymer approvals for acidic food contact. China's GB standards mandate recycled content thresholds that reshape import eligibility for virgin-resin-heavy suppliers. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded formulation investments as compliance timelines tighten.
Market Dynamics
Metal substitution in beverage packaging is accelerating as brands retrofit filling lines for polymer-based containers, while the EU's Single-Use Plastics Directive forces rapid reformulation toward recycled content and mono-material designs.
Growth Catalysts
- REACH and F-Gas Regulation constraints:Fluorinated barrier chemistries face phase-down timelines across Europe, redirecting R&D investment toward plasma-enhanced deposition technologies that enable compliant high-barrier cans.
- Beverage brand line retrofits:German bottlers are converting carbonated soft drink and beer filling equipment to handle PET and multilayer polymer cans at commercial scale.
- Lightweighting economics:Freight cost compression from reduced tare weight drives institutional procurement shifts away from aluminum and steel alternatives in long-haul distribution networks.
Market Restraints
- Resin feedstock volatility:Crude-linked polyethylene terephthalate and polypropylene pricing swings compress margin predictability for converters without captive compounding capabilities.
- Central European technician scarcity:Skilled blow-molding operator availability is collapsing across Czech and Polish manufacturing hubs, constraining multilayer barrier can output expansion.
- Extractables testing protocols:US FDA acidic food contact approval timelines delay new polymer introductions by 18-36 months, freezing formulation innovation for tomato and citrus applications.
Strategic Opportunities
- China GB standards compliance:Recycled content thresholds for imported packaging materials create first-mover advantage for suppliers with post-consumer resin integration.
- Chemical distributor collapsible formats:Empty-container volume reduction for reverse logistics represents the fastest-growing adjacent category as industrial buyers prioritize returnable systems.
- Personal care stretch-blow integration:Injection-stretch-blow molding system adoption shortens lead times for cosmetic and aerosol brands seeking cylindrical polymer alternatives.
Industry Challenges
- Multilayer delamination certification:Sorting infrastructure incompatibility with non-mono-material designs blocks circular economy claims and complicates EPR compliance documentation.
- Legacy metal can line integration:Filling equipment originally engineered for aluminum and steel requires costly mechanical and control system modifications to handle polymer wall flexibility and seal profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Cans Market |
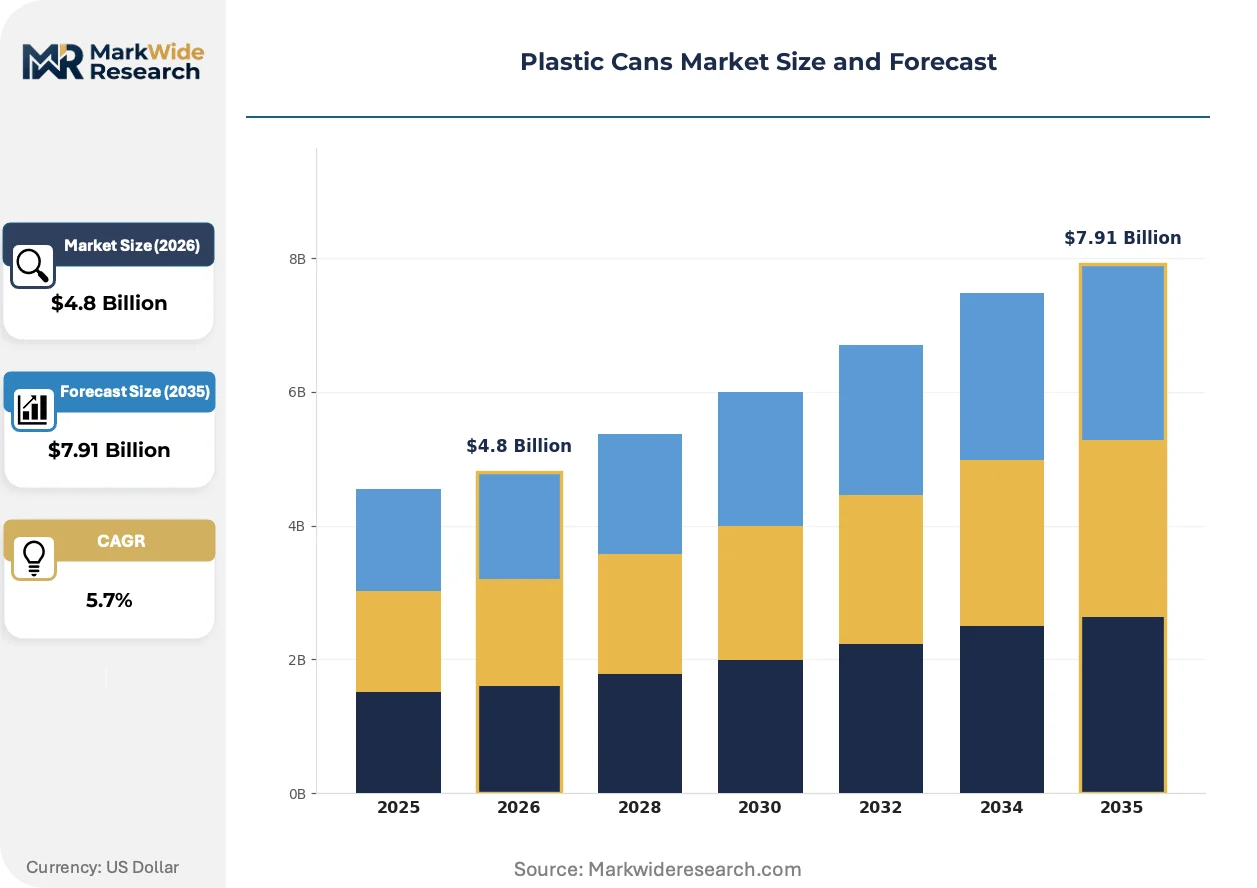
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Use, Reusable, Collapsible, Stackable Application: Food Packaging, Beverages, Chemicals, Personal Care Size: Small, Medium, Large, Extra Large Distribution Channel: Online Retail, Supermarkets, Wholesale, Specialty Stores |
| Companies Covered | Amcor plc, Plastipak Holdings, Inc., ALPLA, Berry Global, Inc., Sonoco Products Company, Alpha Packaging, Inc., CKS Packaging, Sealed Air Corporation, Huhtamaki, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Cans Market Evolving Landscape
Barrier technology development is splitting along two paths as regulatory pressure intensifies, with plasma deposition and bio-based alternatives competing to replace legacy fluorinated chemistries in oxygen-sensitive applications.
Plasma-enhanced barrier deposition is bifurcating the high-performance segment from conventional multilayer coextrusion. Beverage brands in Germany and Austria are piloting silicon oxide-coated PET cans for beer and sparkling water. This technology is bifurcating equipment investment strategies between early plasma adopters and resin-heavy incumbents.
The EU's Single-Use Plastics Directive mandates 25% recycled content in PET beverage containers by 2025, with mechanical recycling compatibility requirements. Food contact notification pathways under EFSA are clogging as novel polyester formulations queue for safety assessments. Personal care and household chemical segments are accelerating mono-material polypropylene adoption to bypass sorting complexity.
Institutional procurement patterns are consolidating around returnable logistics systems with track-and-trace accountability. Food service distributors in France and Benelux are specifying reusable plastic can formats with embedded RFID for container deposit schemes. Chemical distributors in the Rhine-Ruhr corridor are switching to collapsible designs that reduce empty backhaul volume by 70%.
Plastic Cans Market Segmentation
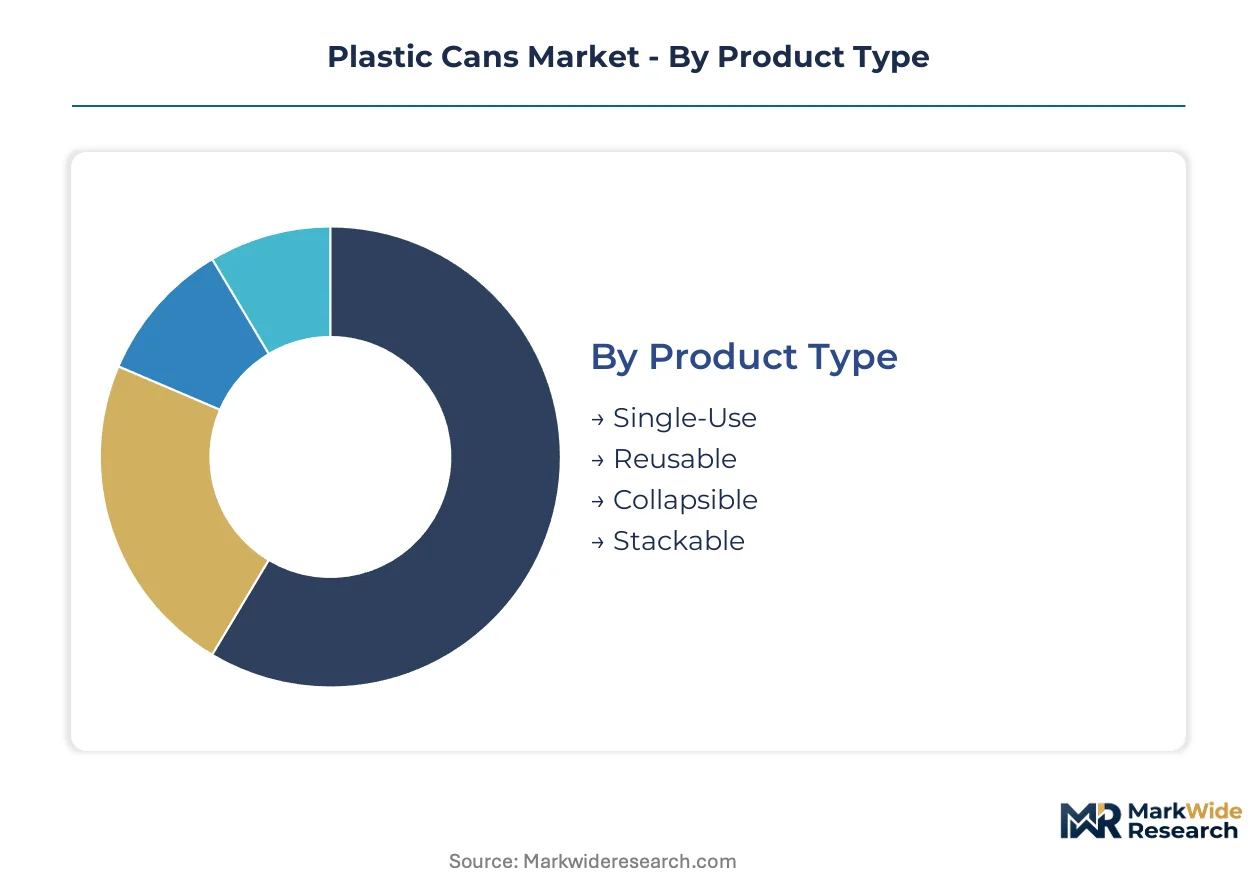
Segmentation in plastic cans reveals how substitution pressure from metal containers varies sharply by durability and barrier requirements. Understanding these fault lines helps suppliers allocate compounding capacity and R&D investment toward formats where polymer economics outperform aluminum and steel.
Product Type:
Substitution pressure from metal cans intensifies for formats that can match aluminum's lightweighting without sacrificing barrier performance or reuse cycles.
- Single-Use:PET and multilayer polypropylene cans engineered for one-way beverage distribution dominate current volume. German bottlers retrofitting carbonated soft drink lines toward polymer cans are concentrating procurement here, though EU Single-Use Plastics Directive recycled content mandates are forcing rapid reformulation.
- Reusable:High-density polyethylene and reinforced polypropylene designs withstand 50+ wash cycles for institutional food service logistics. French and Benelux distributors specify embedded RFID track-and-trace systems for container deposit schemes, creating technology pull ahead of regulatory mandates.
- Collapsible:Silicone-valve or concertina-wall designs reduce empty backhaul volume by 70% for chemical distributors in the Rhine-Ruhr corridor.
- Stackable:Interlocking base geometries optimize pallet density for dry goods and powder chemicals in long-haul distribution networks.
Single-use formats anchor the volume base while collapsible designs gain share at the steepest rate as reverse logistics economics reshape chemical distributor procurement.
Application:
Cost tier stratification separates commodity beverage conversions from premium barrier applications where polymer cans command margin premiums over metal.
- Food Packaging:Mono-material polypropylene and post-consumer recycled PET containers for tomato paste, sauces, and ready meals require oxygen barrier parity with steel. US FDA extractables testing protocols delay acidic food contact approvals by 18-36 months, freezing innovation for citrus and tomato segments.
- Beverages:Carbonated soft drinks, beer, and sparkling water represent the largest addressable pool for aluminum substitution. Austrian and German brands pilot silicon oxide-coated PET cans via plasma-enhanced deposition to achieve shelf-life parity without fluorinated chemistries banned under REACH and F-Gas Regulation.
- Chemicals:Industrial lubricants, agrochemicals, and cleaning solvents demand UN-certified stacking strength and chemical resistance. Collapsible formats are expanding most quickly as distributors prioritize empty-container volume reduction.
- Personal Care:Injection-stretch-blow molded polypropylene cans for cosmetics and aerosol alternatives shorten lead times versus aluminum extrusion. ALPLA's integrated systems capture share among brands seeking cylindrical polymer alternatives to metal.
Beverage applications anchor the volume base while personal care climbs the fastest as stretch-blow integration compresses time-to-market for cosmetic brands.
Size:
Volume concentration patterns reflect pallet optimization economics and retail shelf standardization across European and North American markets.
- Small:100-250ml formats for single-serve beverages and travel-size personal care dominate convenience retail. German discounters are standardizing on 200ml PET can formats for energy drinks.
- Medium:330-500ml containers match legacy aluminum can footprints for beverage line retrofit compatibility. This tier captures the steepest expansion trajectory as filling equipment conversions accelerate.
- Large:750ml-1L designs for household chemicals and cooking oils compete with tinplate alternatives on cost per liter.
- Extra Large:2-5L industrial and institutional formats for food service and chemical distribution leverage stackable geometries for warehouse efficiency.
Medium sizes anchor the volume base while small formats gain share fastest as single-serve consumption patterns reshape beverage packaging.
Distribution Channel:
Customer type fragmentation separates bulk institutional procurement from fragmented retail and direct-to-consumer pathways with diverging service requirements.
- Online Retail:Direct-to-consumer shipments demand damage-resistant designs and dimensional optimization for parcel networks. Amazon and specialized chemical distributors are specifying ISTA-certified stackable formats.
- Supermarkets:Mass retail shelf-ready packaging requires 360-degree printable surfaces and standardized pallet footprints. German and French chains are piloting reusable plastic can deposit schemes for dry goods.
- Wholesale:Cash-and-carry and distributor networks for food service and industrial chemicals prioritize unit cost and pallet efficiency over aesthetic finish.
- Specialty Stores:Premium beverage and personal care boutiques specify custom shapes and metallized finishes that compete with aluminum's visual premium.
Supermarkets anchor the volume base while online retail expands most quickly as e-commerce penetration reshapes packaging damage tolerance specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH and the EU's Single-Use Plastics Directive anchor European demand patterns, while China's GB standards and the US FDA extractables protocols reshape competitive access across the three dominant geographies.
Germany
Beverage brands in Bavaria and North Rhine-Westphalia retrofit carbonated soft drink and beer filling lines for PET and multilayer polymer cans. The country's F-Gas Regulation implementation accelerates phase-down timelines for fluorinated barrier chemistries, redirecting investment toward plasma-enhanced deposition. The Rhine-Ruhr chemical distribution corridor drives fastest adoption of collapsible formats for reverse logistics efficiency.
United States
Tomato paste and citrus sauce packagers face 18-36 month FDA extractables testing delays for new polymer food contact approvals. The FDA's acidic food contact protocols freeze innovation timelines for high-barrier applications. Midwest converters concentrate capacity for institutional food service reusable formats with embedded RFID track-and-trace systems.
China
GB standards mandate recycled content thresholds that reshape import eligibility for virgin-resin-heavy foreign suppliers. The country's national packaging regulator enforces mechanical recycling compatibility requirements that favor mono-material designs. Yangtze River Delta converters expand post-consumer resin integration to capture first-mover compliance advantage.
France
Food service distributors in Paris and the Île-de-France region specify reusable plastic can formats with embedded RFID for container deposit schemes. The country's implementation of EU Single-Use Plastics Directive recycled content mandates forces rapid reformulation of PET beverage containers. Benelux-border logistics hubs pilot returnable logistics systems with track-and-trace accountability.
Austria
Sparkling water and beer brands pilot silicon oxide-coated PET cans via plasma-enhanced deposition to achieve shelf-life parity without banned fluorinated chemistries. The country's alignment with REACH and F-Gas Regulation constraints positions Vienna-area R&D clusters at the forefront of barrier technology substitution. Alpine beverage bottlers concentrate procurement for medium-format 330-500ml containers matching legacy aluminum footprints.
Plastic Cans Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive resin compounding and dedicated preform-to-can production lines separating margin-stable players from feedstock-exposed converters. The structure concentrates around three archetypes: integrated resin compounders with backward polymer control, dedicated preform-to-can specialists with filling line retrofit partnerships, and injection-stretch-blow integrators serving personal care acceleration. Dominant competitive moves include strategic partnerships with beverage brands for line retrofit coordination and geographic expansion through regional compounding asset acquisition.
Among integrated packaging conglomerates, Amcor plc exemplifies the resin-compounding archetype through captive polymer production, while Plastipak Holdings, Inc. occupies a position within the dedicated preform-to-can specialist tier. ALPLA anchors the injection-stretch-blow integration segment for personal care and cosmetic applications. These three represent the strategic pattern visible across the competitive set: control over upstream resin supply, dedicated production line architectures, or shortened lead-time systems for brand velocity.
| Leading Market Players |
|---|
| Amcor plc |
| Plastipak Holdings, Inc. |
| ALPLA |
| Berry Global, Inc. |
| Sonoco Products Company |
| Alpha Packaging, Inc. |
| CKS Packaging |
| Sealed Air Corporation |
| Huhtamaki |
| Others |
Value Network & Pricing Analysis
Metal-to-polymer substitution in beverage filling lines simultaneously redistributes production capacity toward Central European compounding hubs and compresses pricing power for virgin-resin-heavy suppliers without post-consumer integration. This dual restructuring forces converters to choose between backward integration into captive resin production or margin erosion from feedstock volatility.
Pricing Analysis
Long-term offtake contracts dominate procurement between German beverage brands and multilayer barrier can suppliers, insulating converters from spot resin volatility while locking in volume commitments. Price differentiation hinges on recycled content certification tiers under EU Single-Use Plastics Directive compliance and captive compounding capabilities that insulate margin pools. Cost compression in standard-grade PET cans is intensifying because Yangtze River Delta converters with integrated post-consumer resin lines are expanding export eligibility. Institutional food service buyers exhibit highest price sensitivity due to returnable logistics system investments, while personal care brands prioritize lead-time reliability over unit cost.
Supply Chain Analysis
Germany and the Czech Republic anchor blow-molding output for multilayer barrier cans, while China concentrates post-consumer resin integration capacity under GB standards compliance mandates. Raw material flows draw from Saudi Arabian polyethylene terephthalate feedstock, US Gulf Coast polypropylene, and European bio-based polyester pilot plants. Single-source vulnerability concentrates in fluorinated barrier chemistry suppliers facing REACH and F-Gas Regulation phase-down timelines. Distribution runs through Rhine-Ruhr chemical distribution corridors for collapsible formats and dedicated preform-to-can production lines for beverage brand direct supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plastic cans represent an early-cycle expansion story as aluminum substitution accelerates across European beverage filling lines, with regulatory tailwinds from EU recycled content mandates creating structural demand pull ahead of supply capacity.
For Market Incumbents: Fortify margin stability through captive resin compounding investments in Central European manufacturing hubs, offsetting feedstock volatility that erodes converters without backward polymer control. Prioritize EFSA food contact notification queue positioning to unblock acidic food applications currently frozen by US FDA extractables protocols. Defend market position against emerging plasma-enhanced deposition specialists by locking in beverage brand line retrofit partnerships.
For New Entrants and Emerging Players: EFSA fast-track certification for bio-based polyester alternatives creates entry pathway into oxygen-sensitive beverage segments where fluorinated chemistries face regulatory phase-down. Target collapsible format production for Rhine-Ruhr chemical distributors seeking empty-container volume reduction, the fastest-growing adjacent category with limited incumbent specialization. Pursue direct-to-brand partnerships with Austrian and German sparkling water bottlers piloting silicon oxide-coated PET cans.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed preform-to-can specialists lacking post-consumer resin integration, presenting consolidation targets for buyers seeking GB standards compliance advantage. Five-to-ten year viability hinges on mechanical recycling compatibility certification as sorting infrastructure investments mature. Monitor EFSA food contact notification approval velocity as inflection indicator for innovation pipeline unlock in acidic food segments.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Resin Compounding | Insulates converters from crude-linked PET and PP pricing swings. |
| Plasma-Enhanced Deposition Technology Licensing | Enables REACH-compliant barrier performance without fluorinated chemistries. |
| Post-Consumer Resin Integration Expansion | Secures eligibility under China's GB standards recycled content thresholds. |
| Beverage Brand Line Retrofit Partnerships | Locks in volume commitments during German carbonated soft drink conversions. |
| RFID-Embedded Reusable Format Development | Captures institutional procurement shift toward track-and-trace logistics systems. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with blow-molding plant managers, beverage brand procurement leads, chemical distributor logistics heads, and EFSA regulatory affairs specialists; and secondary validation through customs and trade data, European Plastics Association reports, SEC 10-K filings from integrated packaging conglomerates, and FDA food contact notification databases. Bottom-up capacity modeling triangulated against top-down demand segmentation across product type, application, and regional regulatory clusters.
Across the analysis window, forecasts applied analytical frameworks modeling substitution elasticity by end-use, regulatory compliance tier, and production technology archetype. Segmentation dimensions included durability format, barrier technology type, filling line compatibility grade, and regional recycled content mandate stringency. CAGRs derived from trend extrapolation of beverage brand retrofit timelines and chemical distributor collapsible format adoption curves, with sensitivity testing for resin feedstock volatility and technician availability constraints.
Decision-makers should treat outputs as directional under assumptions of sustained EU Single-Use Plastics Directive enforcement and stable Central European manufacturing labor availability; material deviation would warrant model refresh. Forecasts reflect base-case regulatory trajectories and technology adoption curves. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Latin America Single-Use Plastic Packaging Market
Plastic Packaging
UVI Stretch Films Market
Plastic Packaging
Global Returnable Plastic Crates Market
Plastic Packaging
Plastic Films Market
Plastic Packaging
Plastic Bottles Market
Plastic Packaging
PET Jars Market
Plastic Packaging
Plastic Ready Meal Trays Market
Plastic Packaging
Plastic Battery Containers Market
Plastic Packaging
PET Preforms Market
Plastic Packaging
China Plastic Bottles Market
Plastic Packaging
South America Polyethylene Terephthalate (PET) Market
Plastic Packaging
Mushroom Plastics Market
Plastic Packaging
Global Plastic Pails Market
Plastic Packaging
Thermoforming Plastic Market
Plastic Packaging
Mexico Plastic Packaging Market
Plastic Packaging
Plastic Packaging Market