
 Canada Plastic Packaging Market | 2026-2036
Canada Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Plastic Packaging Market Intelligence
Ontario's manufacturing belt is rewriting capacity dynamics for domestic converters. Winpak Ltd. leverages its Winnipeg-based extrusion network to supply barrier films for protein packaging. TC Transcontinental Inc. anchors Quebec's flexible packaging segment through its Montreal-area printing and lamination complex. Amcor Group competes across rigid and flexible formats with technical service teams stationed in Toronto and Vancouver.
Canada plastic packaging encompasses thermoformed, extruded, and molded polymer structures designed to contain, protect, and preserve goods through distribution and retail channels. Polyethylene films dominate fresh produce and frozen food applications due to puncture resistance and heat-sealability at thicknesses ranging from 25 to 150 microns. The material dimension shows PET gaining share in beverage bottles as rPET collection infrastructure expands under extended producer responsibility frameworks. Flexible packaging leads volume in the food and beverage end-user segment, while healthcare-grade polystyrene trays command premium pricing for surgical kit sterilization.
Health Canada enforces the single-use plastics prohibition regulations, while the Canadian Council of Ministers of the Environment coordinates extended producer responsibility programs that mandate minimum recycled content in select packaging categories. The Canadian Food Inspection Agency maintains migration limits for food-contact substances that influence resin selection and multilayer construction. Stakeholders must monitor provincial EPR rollout timelines and recycled-content verification protocols to secure shelf space with major grocery banners.
Market Dynamics
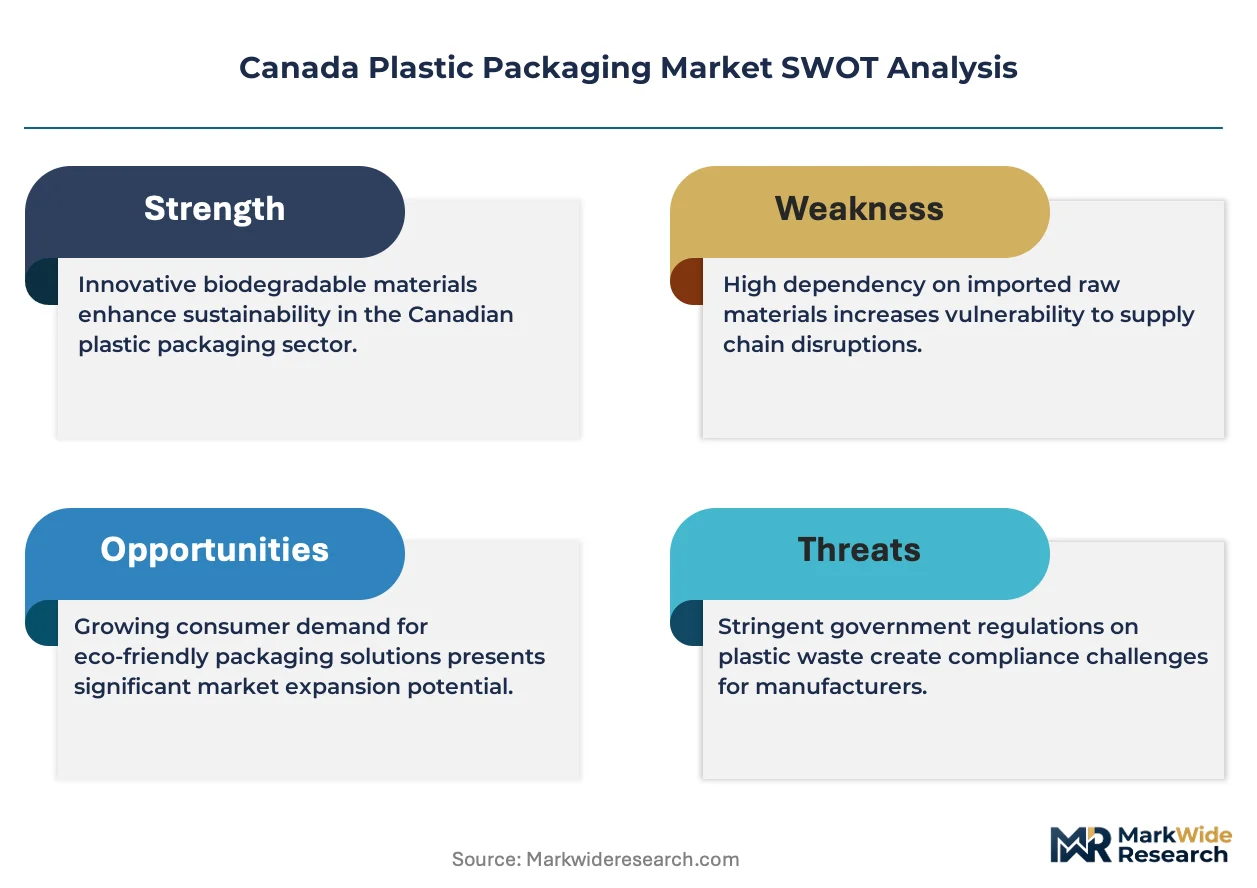
Health Canada's single-use plastics prohibition is compressing virgin resin demand while redirecting procurement toward recycled-content alternatives, forcing converters to requalify formulations and rebuild supplier relationships across Ontario and Quebec.
Growth Catalysts
- Extended Producer Responsibility mandates:Provincial programs in British Columbia and Ontario mandate minimum recycled content thresholds, creating guaranteed offtake for post-consumer resin streams and stabilizing feedstock economics for domestic reclaimers.
- Protein packaging automation:Central Canadian meat and poultry processors are retrofitting lines for high-speed form-fill-seal operations, driving specification of puncture-resistant polyethylene films at 75-125 micron thicknesses.
- Greater Toronto Area corridor concentration:Contract packaging clusters along Highway 401 are consolidating demand for barrier laminates, creating scale efficiencies that attract technical service investment from multinational film suppliers.
Market Restraints
- rPET feedstock scarcity:Collection infrastructure gaps in Atlantic provinces limit flake supply, forcing Ontario blow molders to import baled material from US Great Lakes states at elevated logistics cost.
- Multilayer film incompatibility:Current mechanical recycling streams cannot separate EVOH and nylon barrier layers, rendering post-industrial trim waste from snack packaging non-recyclable under existing sortation technology.
- Health Canada migration testing timelines:Novel resin approvals for food-contact applications require 18-24 month evaluation cycles, delaying commercialization of bio-based alternatives from domestic polymer developers.
Strategic Opportunities
- Prairie agricultural film recovery:Alberta and Saskatchewan silage wrap and grain bag collection programs remain underdeveloped, representing untapped volume for mechanical recycling investment.
- Healthcare sterilization tray conversion:Polystyrene rigid formats face substitution pressure from PETG alternatives that withstand gamma irradiation, opening technical service relationships with surgical kit assemblers.
- Digital watermark integration:HolyGrail 2.0 sorting technology deployment at Quebec materials recovery facilities could unlock flexible packaging circularity previously blocked by identification failures.
Industry Challenges
- Extrusion technician scarcity:Winnipeg and Montreal converter hubs report 15-20% vacancy rates for blown film operators with coextrusion die experience, compressing effective capacity utilization.
- Legacy lamination asset stranding:Solvent-based adhesive systems face air emissions compliance costs under provincial environmental regulations, requiring capital deployment toward water-based or solventless replacement lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Plastic Packaging Market |
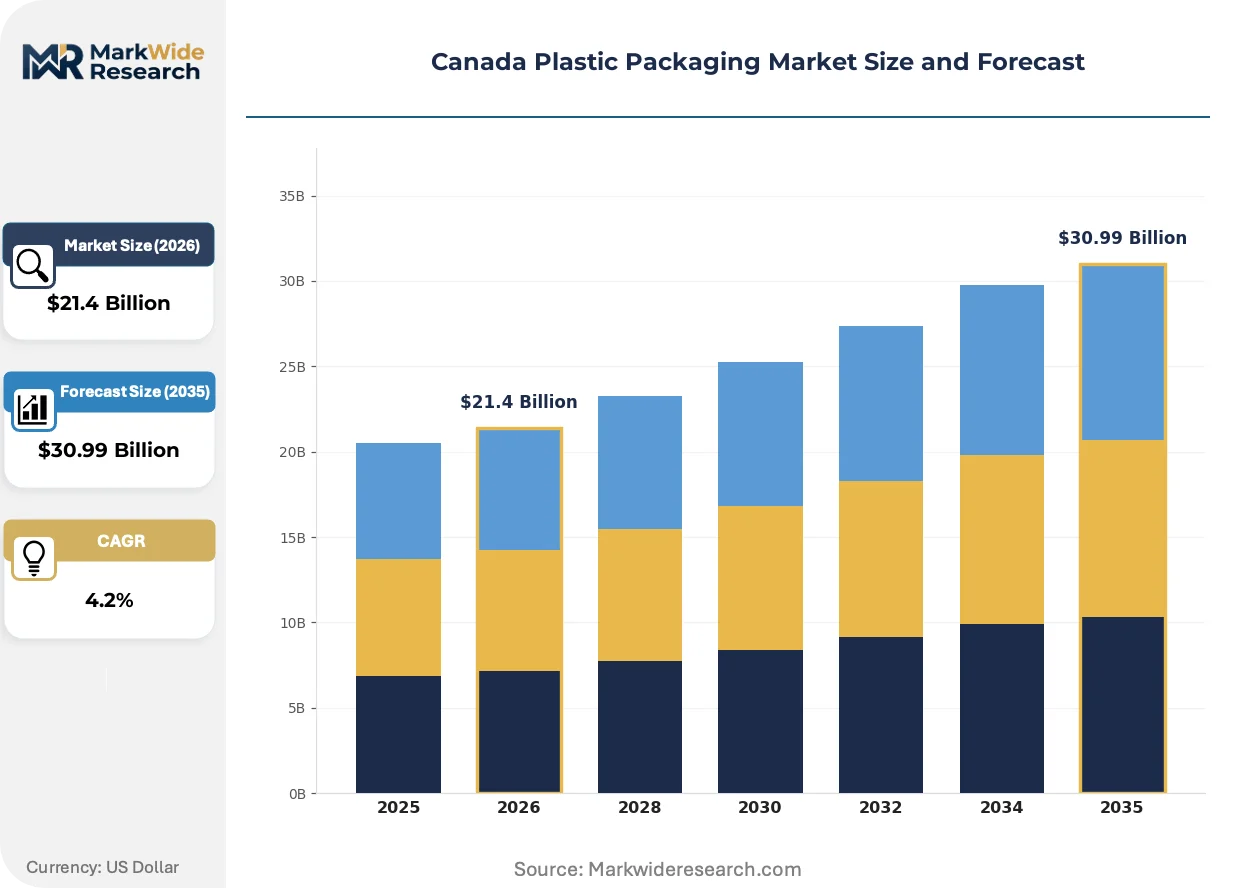
| Market Size in 2026 | $21.4 Billion |
| Market Size in 2035 | $30.99 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Bags, Containers, Films Material: Polyethylene, Polypropylene, Polystyrene, PET End User: Food & Beverage, Personal Care, Household Products, Healthcare Packaging Type: Flexible, Rigid, Resealable, Protective |
| Companies Covered | Sealed Air Corporation, TC Transcontinental Inc., Amcor Group, Silgan Holdings Inc., Sonoco Products Company, Winpak Ltd., CCL Industries Inc., Sigma Plastics Group, Berry Global Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Plastic Packaging Market Strategic Shifts & Innovations
Material science advances and regulatory compliance requirements are converging to reshape specification standards across rigid and flexible formats, with particular intensity in food-contact and healthcare applications.
Mono-material polyethylene structures are migrating from niche sustainability demonstrations to mainstream frozen food specifications. Major Canadian grocery banners now require store-dropoff recyclable packaging for private-label frozen vegetable lines by 2027. This migration from multilayer barrier constructions toward simplified polymer streams is compressing technical differentiation margins for specialty film converters.
Health Canada's single-use plastics prohibition regulations are accelerating substitution timelines for cutlery, stir sticks, and checkout bags. Retail distributors are advancing compliance deadlines by 12-18 months ahead of enforcement to secure shelf space positioning. The quick-service restaurant segment faces the most compressed requalification schedule, with national chains retrofitting supply agreements to incorporate certified compostable alternatives.
Direct converter relationships are displacing traditional distributor intermediaries in the Ontario contract packaging corridor. Large protein processors now negotiate annual volume commitments directly with Winnipeg and Montreal extrusion facilities, extracting price transparency and technical collaboration previously mediated by regional resin brokers. This concentration is most visible in the Greater Toronto Area, where three processors account for a disproportionate share of barrier film procurement.
Canada Plastic Packaging Market Segmentation
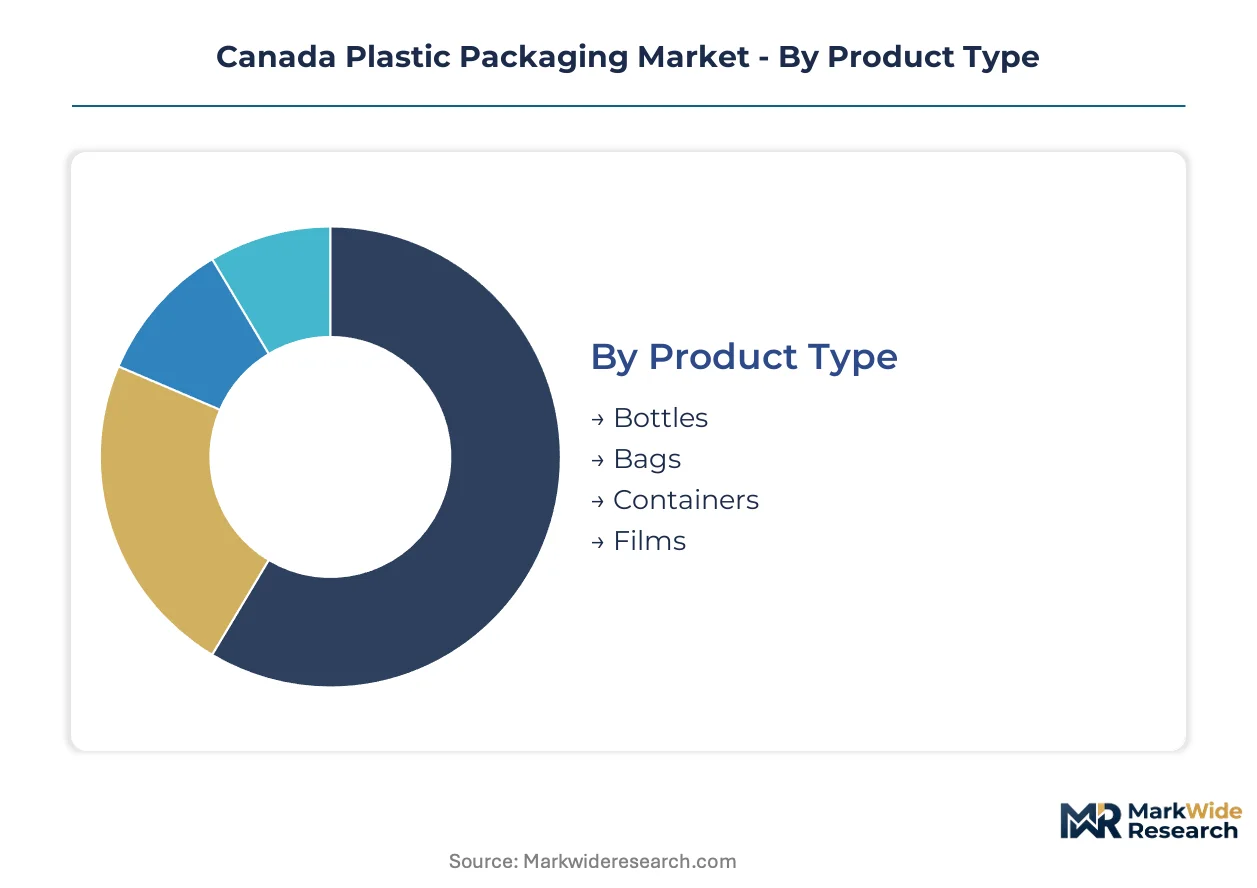
Segmentation reveals how Health Canada's single-use plastics prohibition and extended producer responsibility mandates are reshaping procurement patterns across Ontario and Quebec. Understanding these category boundaries helps converters align capacity investments with where demand is concentrating.
Product Type:
Volume concentration across product categories reflects the dominance of food processing automation in Ontario's manufacturing belt and the automation of protein packaging lines.
- Bottles:PET formats lead beverage applications as rPET collection infrastructure expands under provincial extended producer responsibility frameworks. Blow molders in Ontario face feedstock scarcity from Atlantic collection gaps, forcing import reliance from US Great Lakes states.
- Films:Polyethylene barrier structures at 75-125 micron thicknesses anchor protein packaging specifications for central Canadian meat and poultry processors. The Greater Toronto Area corridor concentrates annual volume commitments negotiated directly with Winnipeg and Montreal extrusion facilities.
- Bags:Checkout bag substitution under Health Canada prohibition regulations is accelerating compostable alternative qualification timelines.
- Containers:Thermoformed polystyrene trays face sterilization-grade substitution pressure from PETG alternatives in healthcare kit assembly.
Films command the established base. The steepest expansion runs through bottles as rPET infrastructure matures.
Material:
Resin selection dynamics are governed by migration testing protocols from Health Canada and the mechanical recycling compatibility constraints of existing sortation infrastructure.
- Polyethylene:Linear low-density and high-density grades dominate fresh produce and frozen food specifications for puncture resistance and heat-sealability. Mono-material PE structures are migrating from sustainability demonstrations to mainstream frozen vegetable private-label requirements.
- PET:Virgin and recycled-content grades gain beverage bottle share as British Columbia and Ontario mandate minimum recycled content thresholds. Collection infrastructure gaps in Atlantic provinces limit domestic flake supply.
- Polypropylene:Clarified homopolymer and copolymer grades serve healthcare sterilization trays requiring gamma irradiation resistance.
- Polystyrene:Crystal and high-impact grades face substitution pressure in surgical kit applications from PETG alternatives.
Polyethylene retains volume leadership. PET is climbing the fastest as recycled-content mandates harden.
End User:
Customer-type segmentation exposes how direct converter relationships are displacing traditional distributor intermediaries in contract packaging procurement.
- Food & Beverage:Flexible packaging leads volume across protein, frozen food, and fresh produce segments. Three major Ontario processors account for disproportionate barrier film procurement through direct annual volume commitments.
- Healthcare:Sterilization-grade rigid formats command premium pricing for surgical kit applications. Health Canada migration testing timelines delay novel resin commercialization for food-contact alternatives.
- Personal Care:Tube and bottle specifications are adapting to single-use plastics prohibition compliance deadlines advanced by retail distributors.
- Household Products:Trigger sprayers and rigid containers face requalification pressure under provincial environmental regulations targeting solvent-based adhesive systems.
Food & Beverage anchors procurement volume. Healthcare delivers the steepest margin expansion.
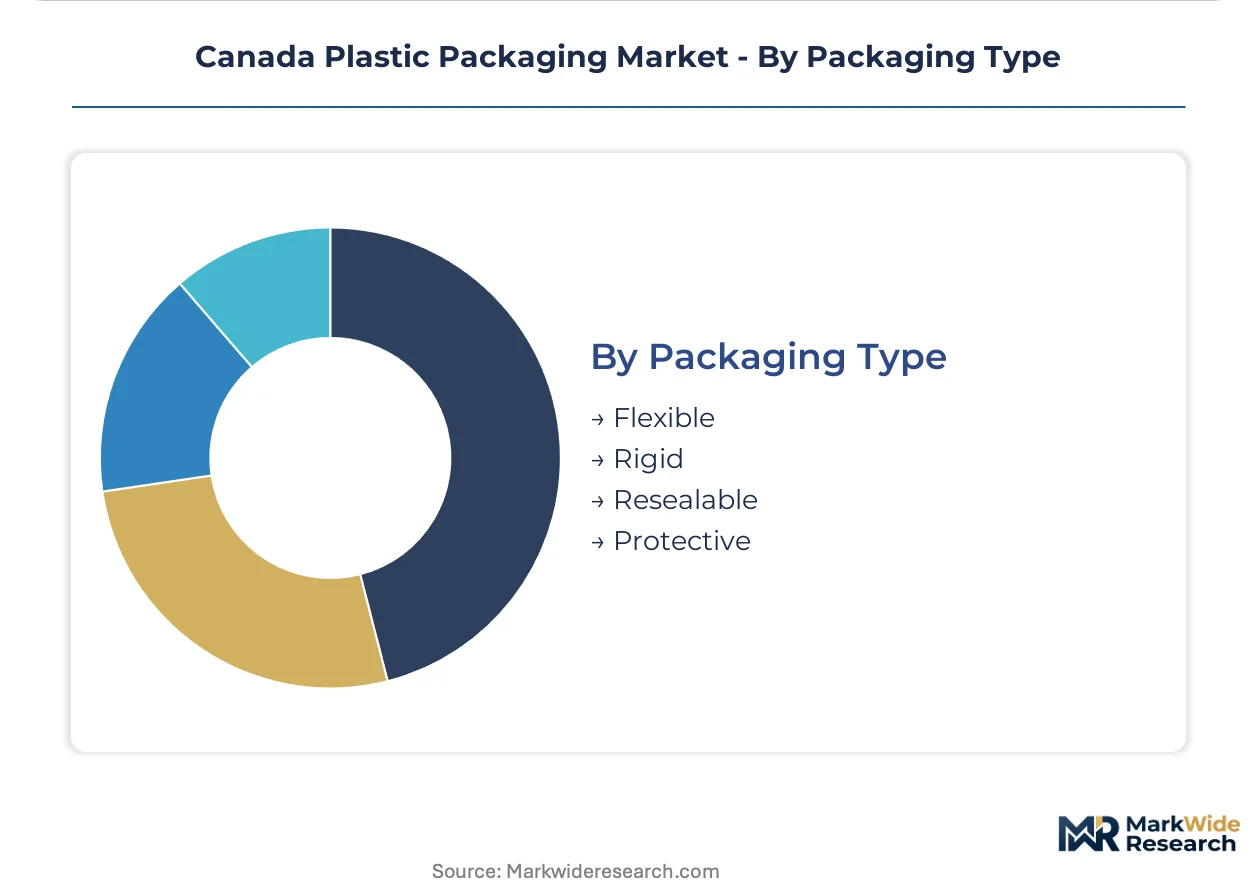
Packaging Type:
Structural format selection determines recycling pathway eligibility under emerging digital watermark sortation deployment at Quebec materials recovery facilities.
- Flexible:Multilayer barrier laminates face circularity constraints from EVOH and nylon layer incompatibility with mechanical recycling streams. Mono-material polyethylene migration is compressing technical differentiation margins for specialty converters.
- Rigid:Thermoformed and blow-molded structures offer established recycling pathways where collection infrastructure exists. PET bottle formats benefit from expanding rPET collection under extended producer responsibility programs.
- Resealable:Zipper and slider mechanisms add polymer complexity that complicates mechanical recycling sortation.
- Protective:Foam and molded pulp substitution pressure intensifies under single-use plastics prohibition scope expansion.
Flexible formats dominate current volume. Rigid packaging is gaining share fastest as recycling infrastructure investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converter capacity clusters along the Windsor-Quebec City corridor, with extrusion assets concentrated within 200 kilometers of the US border. Health Canada regulations and provincial extended producer responsibility programs are redrawing procurement geography.
Ontario
Protein processors in the Greater Toronto Area are negotiating direct annual volume commitments with extrusion facilities. The province's extended producer responsibility mandate requires minimum recycled content thresholds in select packaging categories. Windsor and London host thermoforming clusters serving automotive and food-contact applications.
Quebec
Montreal-area printing and lamination complexes anchor flexible packaging supply for eastern Canadian food processors. The province's materials recovery facilities are piloting digital watermark sortation technology. Quebec City converters specialize in barrier films for dairy and ready-meal segments.
British Columbia
Beverage bottlers in the Lower Mainland face rPET feedstock constraints despite mature collection infrastructure. The province leads national extended producer responsibility implementation with recycled-content mandates. Vancouver serves as the western hub for technical service teams from multinational film suppliers.
Alberta
Agricultural film recovery programs for silage wrap and grain bags remain underdeveloped relative to volume generated. The province's petrochemical corridor supplies virgin polyethylene resin to Prairie converters. Calgary-based distributors mediate procurement relationships between local processors and national film suppliers.
Atlantic Canada
Collection infrastructure gaps limit domestic rPET flake supply, forcing blow molders to import baled material from external sources. Regional processors face elevated logistics costs relative to central Canadian competitors. Halifax serves as the distribution node for barrier film supply to Maritime food processors.
Canada Plastic Packaging Market Key Industry Players
Integrated multinationals and domestic specialists split the market along capability and scale vectors. The vendor base concentrates around barrier film expertise and rigid container manufacturing, with consolidation pressure intensifying as direct procurement relationships displace distributor intermediaries. Two strategic archetypes dominate: full-service converters with extrusion-through-converting assets, and focused specialists in healthcare sterilization or agricultural film segments. Competitive moves center on capacity expansion in the Greater Toronto Area corridor and strategic partnerships to secure rPET feedstock.
Within the integrated converter tier, Winpak Ltd. and TC Transcontinental Inc. exemplify the extrusion-to-converting model with Prairie and Montreal manufacturing footprints. Amcor Group occupies a position spanning rigid and flexible formats with technical service presence in Toronto and Vancouver. These three anchors represent the scale-driven end of a market where mid-tier players face pressure to differentiate through barrier technology or healthcare certification.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| TC Transcontinental Inc. |
| Amcor Group |
| Silgan Holdings Inc. |
| Sonoco Products Company |
| Winpak Ltd. |
| CCL Industries Inc. |
| Sigma Plastics Group |
| Berry Global Inc. |
| Others |
Cost & Logistics Intelligence
The Greater Toronto Area's contract packaging corridor concentrates annual volume commitments for barrier films, granting direct procurement leverage to protein processors while compressing margins for distributors caught between extrusion facilities and end-user specifications. This geographic clustering of demand against dispersed Prairie and Montreal supply creates asymmetric pricing power that favors large converters with technical service presence.
Pricing Analysis
Health Canada's single-use plastics prohibition dictates the pricing tier structure across recycled-content and virgin resin categories. Pricing stratifies across premium barrier laminates, standard mono-material polyethylene, and economy-grade checkout bag substitutes based on migration certification status and recycled-content verification. Cost compression in standard-tier frozen food specifications is intensifying because major grocery banners mandate store-dropoff recyclable packaging. Quick-service restaurant chains exhibit the highest price sensitivity due to compressed requalification schedules, while healthcare sterilization tray buyers prioritize gamma irradiation certification over unit economics.
Supply Chain Analysis
Extended payment terms from Ontario protein processors now stretch to 90-120 days, forcing Winnipeg and Montreal extrusion facilities to utilize supply-chain finance facilities backed by resin distributor credit lines. Virgin polyethylene feedstock draws from Alberta's petrochemical corridor, while rPET flake sources from US Great Lakes states due to Atlantic Canada collection gaps. Single-source vulnerability concentrates in barrier film coextrusion capacity along the Windsor-Quebec City corridor. Distribution runs through direct converter relationships that displace regional resin brokers in the Greater Toronto Area.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment around Health Canada migration testing and extended producer responsibility compliance creates structural barriers to new resin qualification.
For Market Incumbents: Build switching-cost moats by embedding technical service teams within Ontario protein processor facilities to capture direct annual volume commitments before requalification windows close. Deepen backward integration into rPET flake procurement through offtake agreements with US Great Lakes reclaimers to offset Atlantic supply gaps. Prioritize water-based adhesive lamination line conversion ahead of provincial air emissions enforcement.
For New Entrants and Emerging Players: Atlantic Canada's collection infrastructure gaps represent the most penetrable geography for mechanical recycling investment targeting imported bale processing. Agricultural film recovery programs in Alberta and Saskatchewan offer white-space volume with limited incumbent presence. Enter through toll-processing arrangements with Prairie converters to bypass capital-intensive extrusion asset requirements.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because direct procurement relationships are compressing distributor margins and stranding legacy lamination assets. Target mid-tier converters with healthcare sterilization certifications and barrier technology IP. Watch for Health Canada migration testing timeline acceleration as the signal for bio-based resin commercialization inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| rPET Feedstock Security Agreement | Locks in flake supply from US Great Lakes states before Ontario mandates tighten. |
| Mono-Material PE Line Conversion | Qualifies for major grocery banner private-label frozen vegetable specifications by 2027. |
| Healthcare Sterilization Certification | Captures premium pricing from surgical kit assemblers substituting PETG for polystyrene. |
| Digital Watermark Sortation Partnership | Unlocks flexible packaging circularity through Quebec materials recovery facility pilot deployment. |
| Prairie Agricultural Film Collection Network | Secures underdeveloped silage wrap and grain bag volume for mechanical recycling scale. |
Research Approach
Desk research of Health Canada regulatory filings, provincial extended producer responsibility program documentation, and industry association technical standards preceded structured interviews with blown film extrusion operators, protein processor procurement directors, materials recovery facility managers, and resin distributor account executives. Secondary validation drew from customs trade data, SEC filings of listed packaging converters, and Canadian Council of Ministers of the Environment policy trackers. Bottom-up capacity assessments across Ontario and Quebec manufacturing facilities were triangulated against top-down demand estimates from food processing automation investment disclosures.
Forecast assumptions held Health Canada's single-use plastics prohibition enforcement timeline and provincial recycled-content mandate phase-ins as fixed boundary conditions across the projection horizon. The analytical framework modeled volume and value across product type, material grade, end-user segment, and packaging format dimensions. CAGRs were computed from regression analysis of historical resin price elasticity and processor procurement volume trends, with specific inputs including protein packaging line automation retrofit schedules and rPET collection infrastructure buildout curves.
Practitioners should monitor Health Canada migration testing backlog duration and US Great Lakes rPET bale export tariff developments for early signals of forecast deviation. Macroeconomic contraction in central Canadian food processing, regulatory acceleration of bio-based resin approval pathways, or breakthroughs in multilayer film delamination technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Reusable Plastic Water Bottles Market
Plastic Packaging
South Africa Plastic Packaging Market
Plastic Packaging
Plastic Corrugated Sheets Market
Plastic Packaging
Plastic Bottles Market
Plastic Packaging
Packaging Industry in South Africa Market
Plastic Packaging
Europe Plastic Packaging Market
Plastic Packaging
Thailand Rigid Plastic Packaging Market
Plastic Packaging
Plastic Canister Market
Plastic Packaging
Asia Pacific Plastic Bottles Market
Plastic Packaging
Indonesia Plastic Packaging Market
Plastic Packaging
Malaysia and Thailand Thermoformed Plastic Market
Plastic Packaging
China Plastic Bottles Market
Plastic Packaging
Polypropylene Corrugated Packaging Market
Plastic Packaging
Saudi Arabia Plastic Packaging Market
Plastic Packaging
Transparent Plastic Packaging Market
Plastic Packaging
France Plastic Bottles Market