
 Polyethylene Mailers Market | 2026-2036
Polyethylene Mailers Market Size, Share, and Industry Trends Forecast 2026-2036
Polyethylene Mailers Market Analytics
E-commerce fulfillment centers are redrawing demand patterns in the polyethylene mailers space, pulling volume away from traditional wholesale distributors. Sealed Air Corporation leverages its global manufacturing footprint to serve high-velocity fulfillment networks. Pregis LLC differentiates through protective packaging specialization that extends into padded mailer formats. Intertape Polymer Group Inc. anchors North American supply with integrated film extrusion and converting assets.
Polyethylene mailers are lightweight shipping envelopes manufactured from low-density polyethylene (LDPE) or linear low-density polyethylene (LLDPE) film, typically ranging from 1.5 to 3.0 mils in thickness, designed to resist moisture and tearing during transit. Bubble mailers represent the fastest-growing product type as protective requirements intensify for electronics and cosmetics shipments. Self-seal closure formats dominate operational workflows by reducing packing labor time in high-throughput distribution centers.
The EU Packaging and Packaging Waste Regulation shapes recycled content mandates across European supply chains, while the EPA guides state-level recycling infrastructure in the United States and China's SAMR enforces GB standards for plastic product labeling. Stakeholders must monitor how diverging compliance timelines across these jurisdictions affect raw material sourcing strategies and cross-border product certification requirements.
Market Dynamics
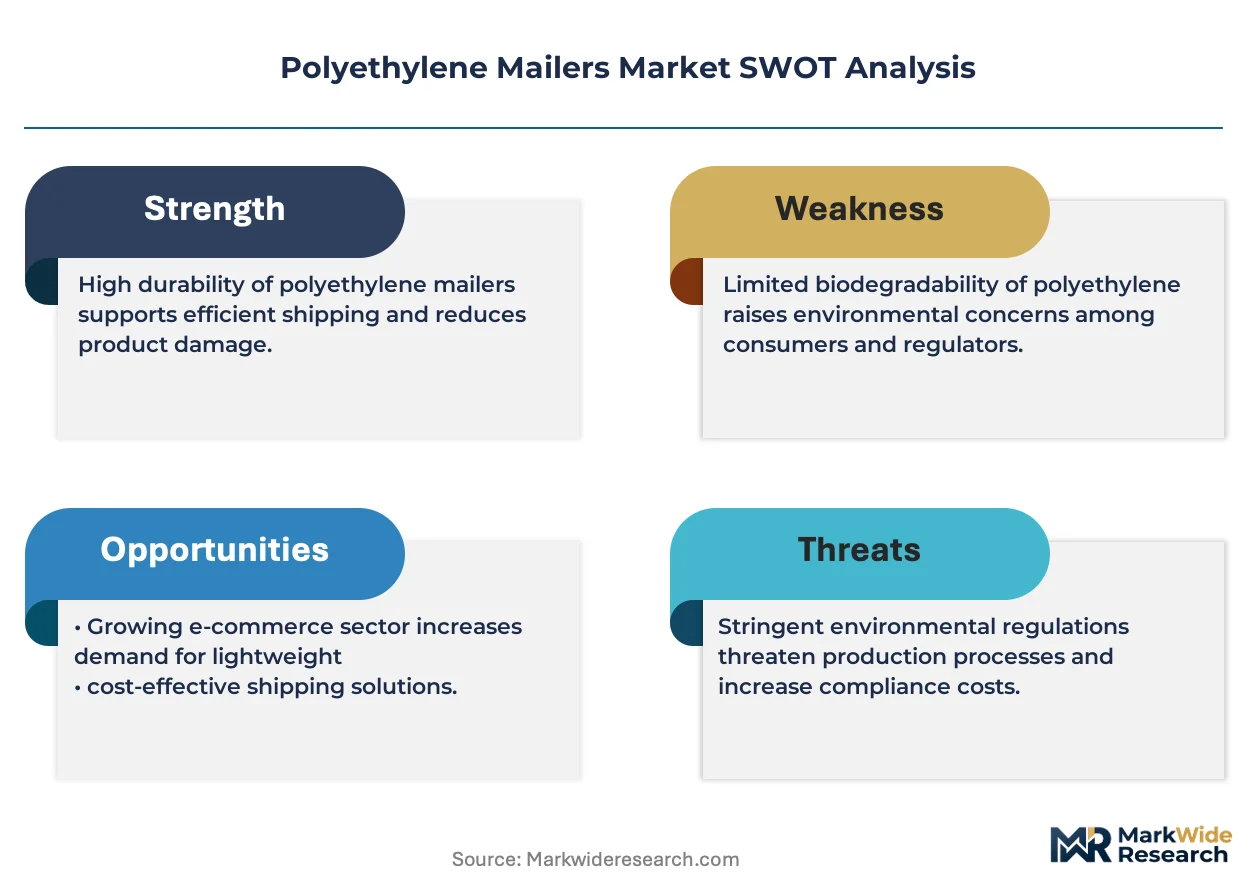
The EU Packaging and Packaging Waste Regulation is forcing polyethylene mailer manufacturers to reengineer film formulations around recycled content thresholds, compressing margins for converters lacking backward integration into post-consumer resin streams.
Growth Catalysts
- E-commerce fulfillment velocity:High-throughput distribution centers in Germany and China are standardizing self-seal bubble mailer formats to reduce packing labor time per unit.
- REACH compliance adaptation:European converters investing in chemical recycling pathways for LDPE feedstock are securing preferential supplier status with major retail logistics networks.
- Electronics protection requirements:Smartphone and tablet shipments are pulling padded mailer specifications toward thicker multi-layer film constructions with enhanced puncture resistance.
Market Restraints
- Post-consumer resin price volatility:rLDPE pellet costs fluctuate with municipal collection infrastructure reliability, squeezing converters dependent on external recycled feedstock supply.
- Linear film extrusion capacity concentration:Integrated resin-to-mailer producers in the US Gulf Coast control critical blown film asset bases, limiting independent converter expansion options.
- Mechanical recycling contamination limits:Adhesive residues from self-seal closures degrade recycled polyethylene quality, constraining closed-loop circularity claims.
Strategic Opportunities
- Indian cross-border retail expansion:Mumbai and Bangalore fulfillment hubs are scaling imported packaging specifications, creating demand for certified export-grade mailer constructions.
- Advanced film-to-film recycling:Chemical depolymerization of polyethylene mailers back to virgin-equivalent resin is converging with pyrolysis capacity buildouts in the Netherlands.
- SAMR labeling compliance services:Third-party certification support for GB standard plastic product declarations is emerging as a value-added channel for converters serving Chinese export markets.
Industry Challenges
- Multi-jurisdiction certification timelines:Parallel EU PPWR, EPA state-level, and SAMR compliance pathways are fragmenting quality assurance team capacity at mid-scale converters.
- Blown film technician scarcity:Specialized extrusion die maintenance and gauge control expertise is concentrating at legacy packaging hubs, constraining new facility ramp speeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyethylene Mailers Market |
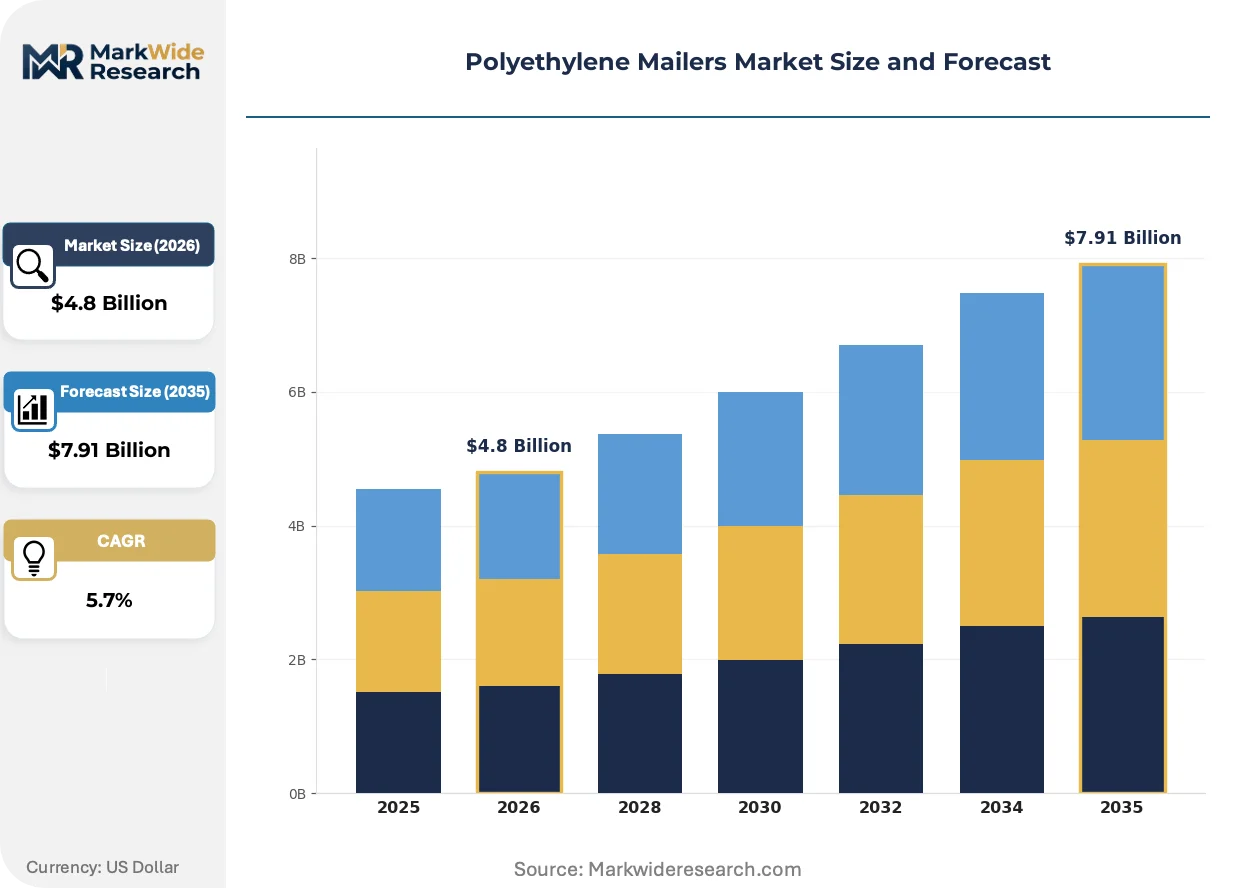
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Mailers, Padded Mailers, Bubble Mailers, Poly Mailers Size: Small, Medium, Large, Extra Large Color: Clear, Black, White, Custom Closure Type: Self-Seal, Adhesive, Snap, Zipper |
| Companies Covered | Sealed Air Corporation, Pregis LLC, Intertape Polymer Group Inc., PAC Worldwide Corporation, ProAmpac LLC, PolyPak Packaging, Associated Bag, Ampac Services Inc., Laddawn, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyethylene Mailers Market Evolving Landscape
Active film formulation research is bifurcating the polyethylene mailer supply base between mechanical recycling-optimized and chemical recycling-compatible resin streams, with divergent capital requirements for each pathway.
Co-extruded barrier films incorporating post-industrial recycled content are bifurcating performance tiers in the protective mailer segment. Electronics fulfillment centers in Shenzhen and Austin are specifying these constructions for moisture-sensitive component shipments. The technology is bifurcating supplier capabilities between integrated resin producers and film converters dependent on merchant feedstock.
The EU Green Deal's packaging waste reduction targets are accelerating design-for-recycling mandates across European supply chains. Mailer constructions must now demonstrate mono-material compatibility to qualify for extended producer responsibility fee reductions. German logistics operators are responding by consolidating procurement around certified recyclable film specifications.
Direct-to-fulfillment-center contracting is displacing traditional wholesale distributor relationships in North American polyethylene mailer procurement. Amazon, Walmart, and Target distribution networks are negotiating multi-year supply agreements with film extruders. This pattern is most visible in the Ohio and Pennsylvania warehouse clusters serving eastern US population centers.
Polyethylene Mailers Market Segmentation
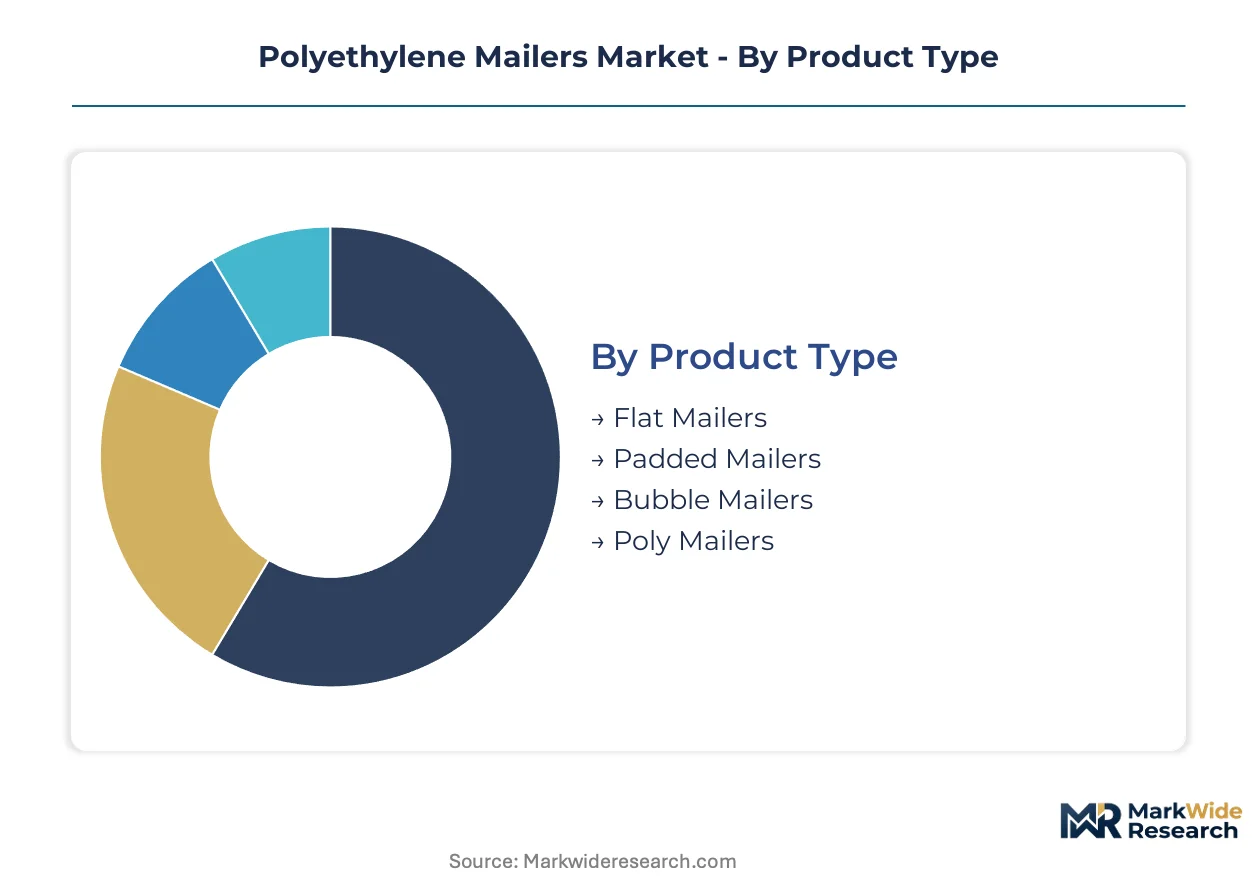
Segmentation in polyethylene mailers reveals how procurement specifications diverge between domestic parcel networks and cross-border retail channels. Understanding these divides helps converters align film formulations with the operational constraints of each logistics tier.
Product Type:
Domestic e-commerce fulfillment centers in the United States and Germany favor flat mailers for cost efficiency, while export-oriented hubs in China specify padded and bubble variants to withstand longer transit cycles.
- Flat Mailers:Single-layer LDPE or LLDPE constructions ranging from 1.5 to 2.0 mils thickness, optimized for apparel and soft goods. Demand concentrates in high-velocity US distribution centers serving fashion retail, where pack-out speed trumps protective performance.
- Bubble Mailers:Co-extruded films laminated to air-retention bubble layers, typically 3.0 to 4.5 mils total thickness. Electronics fulfillment in Shenzhen and Austin specifies these for moisture-sensitive component shipments, with specifications tightening around puncture resistance metrics.
- Padded Mailers:Fiber-based or foam-lined constructions offering intermediate protection between flat and bubble formats. European pharmaceutical distributors specify these for temperature-stable medical device shipments under REACH compliance frameworks.
- Poly Mailers:Standard polyethylene envelopes without additional cushioning, serving bulk document and textile shipments. Indian cross-border retail expansion in Mumbai and Bangalore is pulling import demand for certified export-grade poly mailer constructions.
Flat mailers hold the largest share; momentum sits with bubble mailers as electronics protection requirements intensify.
Size:
Cost tier alignment shapes size procurement patterns, with small formats commanding premium per-unit pricing for jewelry and cosmetics while large formats run on volume-discounted enterprise contracts.
- Small:Dimensions typically under 6x9 inches, serving jewelry, cosmetics, and pharmaceutical sample shipments. German luxury e-commerce platforms specify small padded mailers with tamper-evident closures for high-value goods.
- Medium:9x12 to 10x13 inch range capturing the bulk of apparel and consumer electronics shipments. Chinese fulfillment networks standardize medium bubble mailers for smartphone and tablet exports to European markets.
- Large:14.5x19 inch and similar formats for bulk apparel, home goods, and multi-item orders. US big-box retail distribution centers negotiate large-format poly mailers on multi-year supply agreements with integrated film extruders.
- Extra Large:Oversized constructions for bedding, outerwear, and irregular-shaped goods. Limited adoption outside specialty retail due to dimensional weight pricing penalties in parcel carrier rate cards.
Medium sizes dominate procurement volume; extra large formats are expanding most quickly as home goods e-commerce penetration deepens.
Color:
Application-driven color selection separates internal logistics visibility requirements from consumer-facing brand presentation needs.
- Clear:Transparent LDPE enabling contents verification without opening. Customs and security screening operations in cross-border channels favor clear mailers for expedited clearance protocols.
- White:Standard opaque format for generic e-commerce fulfillment, offering neutral substrate for thermal transfer labeling. White mailers constitute the baseline specification for most automated sortation systems.
- Black:Opaque constructions for privacy-sensitive shipments including pharmaceuticals and personal care products. Black mailers are gaining share fastest in subscription box and direct-to-consumer pharmacy channels.
- Custom:Brand-specific Pantone-matched colors and printed designs. Premium retailers in France and the United Kingdom specify custom mailers as unboxing experience investments, with minimum order quantities constraining mid-scale converter participation.
White mailers hold the largest share; black formats are climbing the fastest as privacy regulations tighten around visible pharmaceutical shipments.
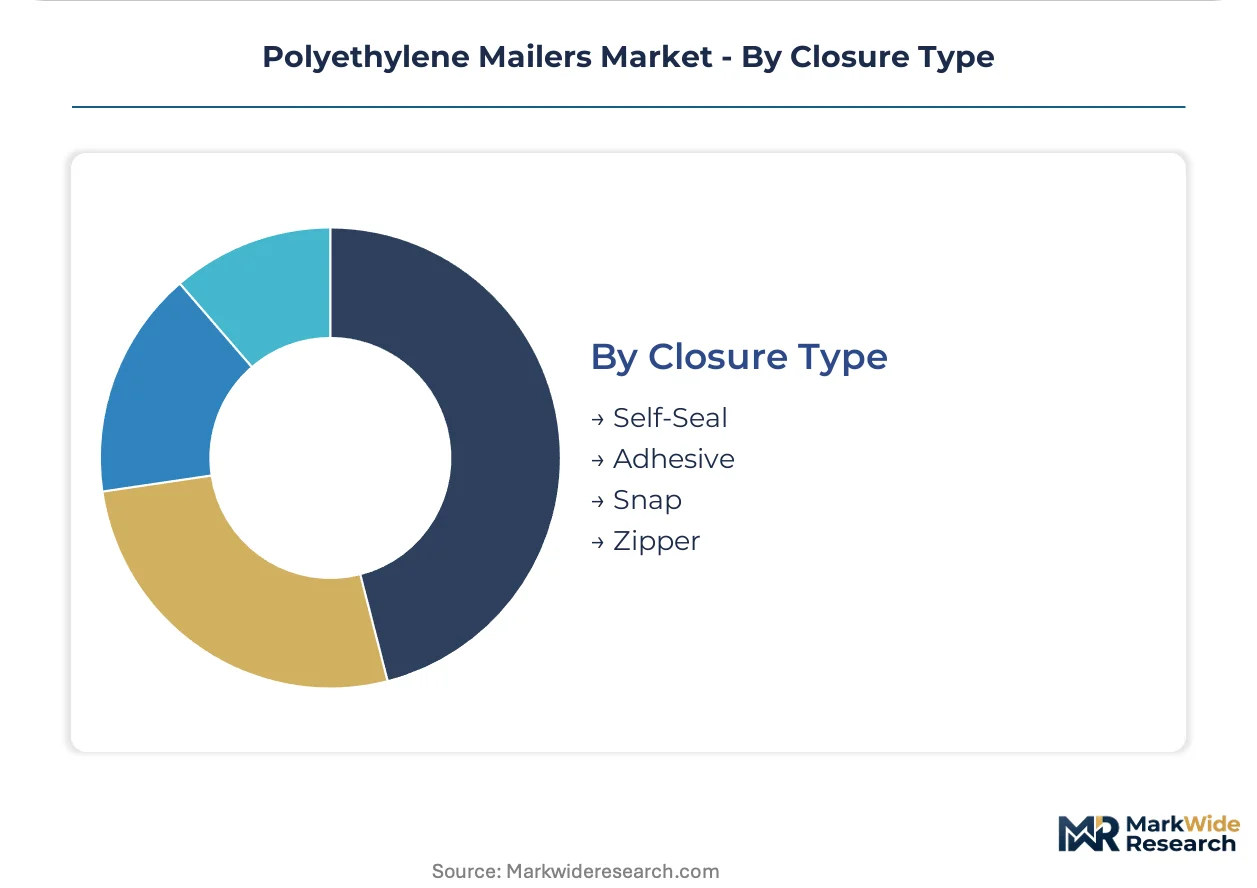
Closure Type:
Customer type segmentation separates high-throughput automated facilities requiring self-seal speed from low-volume operations tolerating slower adhesive or mechanical closure methods.
- Self-Seal:Pressure-sensitive adhesive strips with release liners, enabling single-motion pack-out. Amazon and Walmart distribution networks standardized self-seal bubble mailers to reduce packing labor time per unit below 12 seconds.
- Adhesive:Wet-glue or hot-melt applications requiring separate application equipment. Legacy wholesale distributors and small-scale e-commerce operations continue specifying adhesive closures where labor cost structures permit slower throughput.
- Snap:Mechanical interlocking closures for reusable or returnable mailer applications. German circular economy pilots specify snap-closure mailers for closed-loop apparel rental and return programs under EU Green Deal packaging waste reduction targets.
- Zipper:Track-and-slider or press-to-close mechanisms for multi-use access. Limited polyethylene mailer adoption due to cost premiums; zipper closures concentrate in premium reusable shipping bag segments competing with polyethylene formats.
Self-seal closures hold the largest share; snap closures are gaining share fastest as reusable packaging pilots expand under extended producer responsibility frameworks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German fulfillment centers export padded mailer specifications to Central European cross-border retail networks, while Chinese manufacturers supply bubble mailer constructions to electronics distributors across Southeast Asia and North America.
United States
Ohio and Pennsylvania warehouse clusters negotiate multi-year supply agreements with integrated film extruders for large-format poly mailers serving Amazon, Walmart, and Target distribution networks. The EPA guides state-level recycling infrastructure development that affects post-consumer resin availability for converters. Dallas-Fort Worth fulfillment hubs are standardizing self-seal closure formats to reduce packing labor time below twelve seconds per unit.
Germany
Luxury e-commerce platforms in Berlin specify small padded mailers with tamper-evident closures for high-value jewelry and cosmetics shipments. The EU Packaging and Packaging Waste Regulation mandates recycled content thresholds that compress margins for converters lacking backward integration into post-consumer resin streams. Hamburg logistics operators are consolidating procurement around certified recyclable film specifications to qualify for extended producer responsibility fee reductions.
China
Shenzhen electronics fulfillment centers specify co-extruded barrier films with enhanced puncture resistance for moisture-sensitive component shipments to European markets. The SAMR enforces GB standards for plastic product labeling that affect export certification requirements. Yangtze River Delta manufacturing bases are scaling chemical recycling-compatible resin streams to serve cross-border retail channels.
India
Mumbai and Bangalore fulfillment hubs are scaling imported packaging specifications for certified export-grade mailer constructions serving cross-border retail expansion. The country's national packaging regulator oversees quality standards for polyethylene products entering international trade lanes. Gujarat film extrusion clusters are ramping capacity to supply domestic e-commerce growth while reducing import dependency.
Netherlands
Rotterdam distribution networks serve as the entry point for recycled polyethylene feedstock moving into European mailer production. The EU Green Deal's packaging waste reduction targets accelerate design-for-recycling mandates across Dutch supply chains. Eindhoven chemical recycling facilities are converging pyrolysis capacity with film-to-film depolymerization for virgin-equivalent resin output.
Polyethylene Mailers Market Competitive Landscape
Player mix skews toward integrated resin-to-mailer producers and specialized protective packaging converters. The supply base concentrates around blown film extrusion assets in legacy packaging hubs, with mid-scale converters facing capacity constraints. Two strategic archetypes dominate: vertically integrated multinational suppliers with captive resin production, and regional specialists focused on padded and bubble mailer formats. Competitive moves center on backward integration into post-consumer resin streams and direct-to-fulfillment-center contracting that displaces traditional wholesale distributor relationships.
Within the integrated multinational tier, Sealed Air Corporation and Pregis LLC exemplify divergent positioning strategies. Sealed Air leverages its global manufacturing footprint to anchor high-velocity fulfillment network relationships across multiple geographies. Pregis occupies a position emphasizing protective packaging specialization that extends into padded mailer constructions. Intertape Polymer Group Inc. represents the North American supply anchor with integrated film extrusion and converting assets serving domestic distribution center procurement.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Pregis LLC |
| Intertape Polymer Group Inc. |
| PAC Worldwide Corporation |
| ProAmpac LLC |
| PolyPak Packaging |
| Associated Bag |
| Ampac Services Inc. |
| Laddawn |
| Others |
Value Network & Pricing Analysis
Blown film extrusion scale economies in the US Gulf Coast and Yangtze River Delta anchor polyethylene mailer cost structures, concentrating pricing power among integrated resin-to-mailer producers while compressing margins for merchant feedstock-dependent converters.
Pricing Analysis
Mechanical recycling-optimized resin streams command modest premiums over virgin LDPE equivalents, while chemical recycling-compatible formulations sit at the premium tier awaiting pyrolysis capacity scale. Price differentiation hinges on recycled content certification grade under EU PPWR thresholds and volume scale in multi-year fulfillment center contracts. Cost compression in standard flat mailers is intensifying because post-consumer resin price volatility squeezes converters lacking backward integration into collection infrastructure. High-velocity e-commerce fulfillment centers exhibit lowest price sensitivity, prioritizing pack-out speed and supply security over per-unit cost.
Supply Chain Analysis
Strategic stockpiling of LLDPE pellets dominates procurement behavior among integrated producers, while just-in-time resin purchasing constrains independent converters exposed to spot market swings. Raw material supply concentrates in the United States, China, and Saudi Arabia as primary LDPE/LLDPE production hubs. Feedstock sourcing draws from naphtha crackers, ethane-based steam crackers, and emerging chemical recycling facilities. Single-source vulnerability around adhesive release liner supply creates chokepoint risk for self-seal closure formats. Distribution runs through direct-to-fulfillment-center contracting that displaces traditional wholesale distributor relationships in North American procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Packaging and Packaging Waste Regulation is accelerating a technology inflection toward recycled-content film formulations, compressing timelines for converter adaptation and rewarding early movers with preferential supplier status.
For Market Incumbents: Consolidate backward integration into post-consumer resin streams through chemical recycling partnerships or captive collection infrastructure to defend margin position against feedstock price volatility. Secure direct contracting relationships with Amazon, Walmart, and Target distribution networks to lock out merchant converter competition. Prioritize blown film technician retention programs to mitigate capability scarcity constraining new facility ramp speeds.
For New Entrants and Emerging Players: Lead with certified export-grade mailer constructions targeting Mumbai and Bangalore fulfillment hubs scaling cross-border retail specifications. Penetrate the Indian domestic market through Gujarat film extrusion cluster partnerships, leveraging local capacity expansion to reduce import dependency. Pursue SAMR labeling compliance services as a value-added channel for converters serving Chinese export markets.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated resin-to-mailer producers with captive post-consumer feedstock streams over merchant-dependent converters facing margin compression. Five-to-ten year viability rests on chemical recycling infrastructure deployment and direct-to-fulfillment-center channel control. Watch for EU PPWR compliance timeline acceleration as the signal indicating margin structure inflection toward integrated players.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Post-Consumer Resin | Captive rLDPE supply secures margin stability under EU PPWR recycled content mandates. |
| Direct-to-Fulfillment-Center Contracting | Multi-year agreements with Amazon and Walmart distribution networks displace wholesale distributor intermediation. |
| Chemical Recycling Capacity Buildout | Pyrolysis facilities in the Netherlands enable virgin-equivalent resin output for premium mailer segments. |
| Design-for-Recycling Certification | Mono-material compatibility qualifies German logistics operators for extended producer responsibility fee reductions. |
| Blown Film Technician Training Programs | Specialized extrusion die maintenance expertise concentrates at legacy packaging hubs, constraining competitor expansion. |
Research Methodology
The analysis maps flat mailer, bubble mailer, padded mailer, and poly mailer sub-sectors, each validated through procurement directors at e-commerce fulfillment centers, blown film extrusion plant managers, and chemical recycling facility operators. Primary interviews with logistics network planners and regulatory compliance officers combined with secondary validation against customs trade data, SEC 10-K filings from integrated packaging producers, and EU PPWR implementation guidance documents. Bottom-up volume modeling across product types, sizes, colors, and closure formats triangulated with top-down market sizing from resin consumption disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including product type, size tier, color specification, closure mechanism, and end-use logistics channel. CAGRs were derived from elasticity-adjusted demand projections incorporating e-commerce penetration trajectories and regulatory compliance cost pass-through assumptions. Forecast inputs included blown film capacity utilization rates and post-consumer resin price indices.
Forecasts assume regulatory continuity in EU PPWR, EPA state-level, and SAMR enforcement regimes; material policy shifts would require re-modeling of recycled content cost structures and cross-border certification requirements. Revision becomes warranted when chemical recycling capacity deployment or fulfillment center automation adoption crosses thresholds that alter resin demand elasticity or labor substitution patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
China Plastic Bottles Market
Plastic Packaging
Plastic Canister Market
Plastic Packaging
Plastic Cutlery Market
Plastic Packaging
Canada Plastic Packaging Market
Plastic Packaging
Russia Plastic Packaging Market
Plastic Packaging
China Plastic Packaging Market
Plastic Packaging
Plastic T-Shirt Bags Market
Plastic Packaging
Thermoformed Plastic Trays Market
Plastic Packaging
Philippines Plastics Market
Plastic Packaging
Europe Blow Molded Plastic Market
Plastic Packaging
PET Preforms Market
Plastic Packaging
Poland Plastic Bottles Market
Plastic Packaging
Middle East and Africa Single-Use Plastic Packaging Market
Plastic Packaging
South Africa Flexible Plastic Packaging Market
Plastic Packaging
North America Single-Use Plastic Packaging Market
Plastic Packaging
Banding Stretch Film Market