
 North America Ostomy Drainage Bags Market | 2026-2036
North America Ostomy Drainage Bags Market Size, Share, and Industry Trends Forecast 2026-2036
North America Ostomy Drainage Bags Market Analytics
Modular two-piece systems with separate skin barriers and detachable pouches is broadening patient choice across the North America Ostomy Drainage Bags Market. Coloplast leverages its silicone-based adhesive platforms to sustain premium positioning in home care channels. Hollister anchors its competitive stance through hydrocolloid barrier specialization and deep distribution in long-term care facilities.
Ostomy drainage bags are medical-grade collection devices, typically fabricated from multi-layer plastic films or silicone composites with integrated odor-control filters and drainage ports, designed to securely capture effluent from surgically created stomas. Two-piece configurations command structural attention due to their flexibility in barrier replacement and pouch exchange, while one-piece designs retain cost advantages in high-volume hospital procurement. Material selection increasingly favors hydrocolloid skin barriers for extended wear time and reduced peristomal complications, with PVC alternatives facing displacement amid biocompatibility scrutiny.
FDA 510(k) premarket notification requirements and Health Canada's Medical Device License framework govern market entry, with both regulators intensifying scrutiny of adhesive dermatitis claims and wear-duration labeling. The MDR-aligned transition in Canadian standards and ongoing FDA quality system inspections shape manufacturing investment priorities. Stakeholders must monitor evolving reimbursement codes from CMS and provincial health plans, as coverage determinations for advanced barrier materials directly influence patient access and manufacturer pricing power.
Market Dynamics
Home care migration is compressing hospital procurement volumes while elevating reimbursement complexity for extended-wear barrier systems across North America. FDA 510(k) clearance timelines and provincial coverage determinations now determine competitive entry sequencing more than manufacturing scale.
Growth Catalysts
- Aging Demographics:The United States Census Bureau projects substantial expansion in the 65-plus population requiring ostomy procedures, concentrating demand in Medicare-reimbursed home care channels.
- CMS Reimbursement Expansion:Coverage determinations for advanced hydrocolloid barriers under Medicare Part B are reducing out-of-pocket burdens and accelerating patient upgrades from standard PVC alternatives.
- Silicone Adhesion Chemistry:Next-generation soft silicone platforms enable 7-day wear protocols that cut peristomal dermatitis incidence and lower total supply costs for long-term users.
Market Restraints
- Medical-Grade Film Supply Concentration:Three specialty polymer suppliers dominate multi-layer coextruded films for odor-barrier layers, creating input cost volatility when resin allocations tighten.
- Health Canada Licensing Friction:MDR-aligned transition requirements for quality system documentation are extending device approval timelines by 8-14 months versus historical averages.
- Adhesive Dermatitis Liability Exposure:Wear-duration claims face intensifying post-market surveillance, forcing conservative labeling that undermines premium pricing for extended-wear products.
Strategic Opportunities
- Mexico Manufacturing Footprint:FDA-registered maquiladora facilities offer tariff-advantaged export capacity into the United States with 30-40% labor cost differentials versus domestic production.
- Pediatric Ostomy Subspecialization:Underserved neonatal and adolescent segments lack sized-appropriate barrier systems, creating white space for anatomically customized product lines.
- Direct-to-Patient Subscription Models:E-commerce platforms with insurance pre-verification are bypassing durable medical equipment distributors, capturing margin and adherence data simultaneously.
Industry Challenges
- Biocompatibility Testing Backlogs:ISO 10993 cytotoxicity and sensitization studies face 16-20 week queues at accredited laboratories, compressing product launch windows.
- Legacy ERP Integration:Home care distributors operate on 1990s-era inventory systems that cannot track lot-level UDI compliance for FDA traceability mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Ostomy Drainage Bags Market |
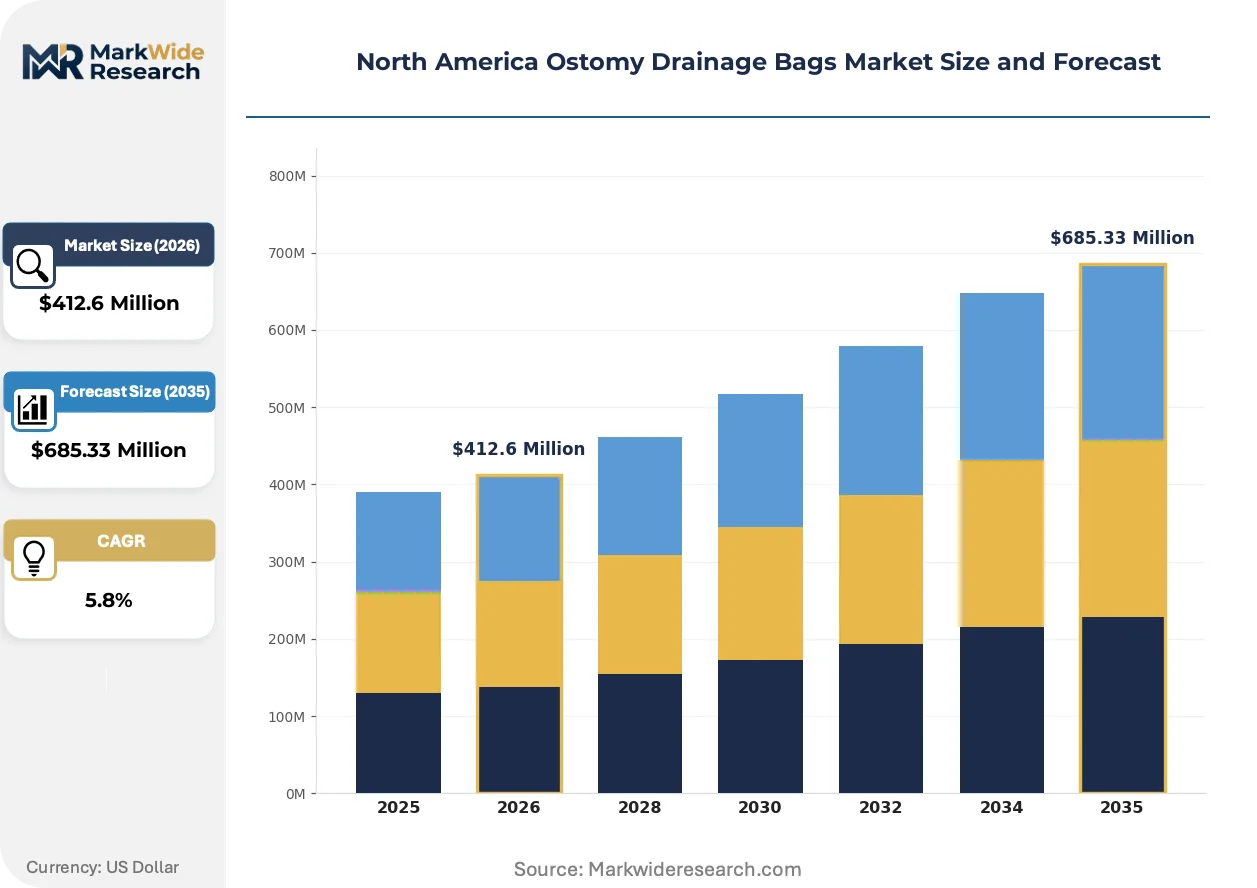
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $685.33 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: One-Piece, Two-Piece, Urostomy, Colostomy Material: Plastic, Silicone, Hydrocolloid, PVC End User: Hospitals, Home Care, Rehabilitation Centers, Long-Term Care Facilities Feature: Odor Control, Drainage Port, Skin Barriers, Transparent |
| Companies Covered | Coloplast, ConvaTec Group, B. Braun Melsungen, Hollister, Salts Healthcare, Alcare, Flexicare Medical, Welland Medical, Dansac, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Ostomy Drainage Bags Market Evolving Landscape
Digital health integration and materials science advances are reconfiguring how ostomy systems are prescribed, monitored, and reimbursed across North American care pathways.
Soft silicone adhesive platforms are modularizing the traditional one-piece versus two-piece architecture debate by enabling hybrid configurations with detachable barriers and reusable baseplates. Home care patients in Ontario and California are piloting these systems through provincial technology assessment programs. The structural consequence is compressing SKU proliferation while extending replacement intervals beyond legacy hydrocolloid limits.
FDA's intensified scrutiny of adhesive dermatitis claims under 21 CFR 878.5900 is forcing manufacturers to substantiate wear-duration labeling with clinical validation data. Health Canada has mirrored this posture through MDR-aligned post-market surveillance requirements. Premium barrier suppliers are responding by funding independent dermatology studies to defend 5-7 day wear protocols against generic competition.
Patients are consolidating supply procurement through integrated specialty pharmacies that bundle barrier systems with stoma nursing consultations and insurance pre-authorization. This channel shift is displacing traditional durable medical equipment distributors in metropolitan markets like Chicago and Toronto. The behavioral pivot is most pronounced among Medicare Advantage enrollees seeking care coordination benefits.
North America Ostomy Drainage Bags Market Segmentation
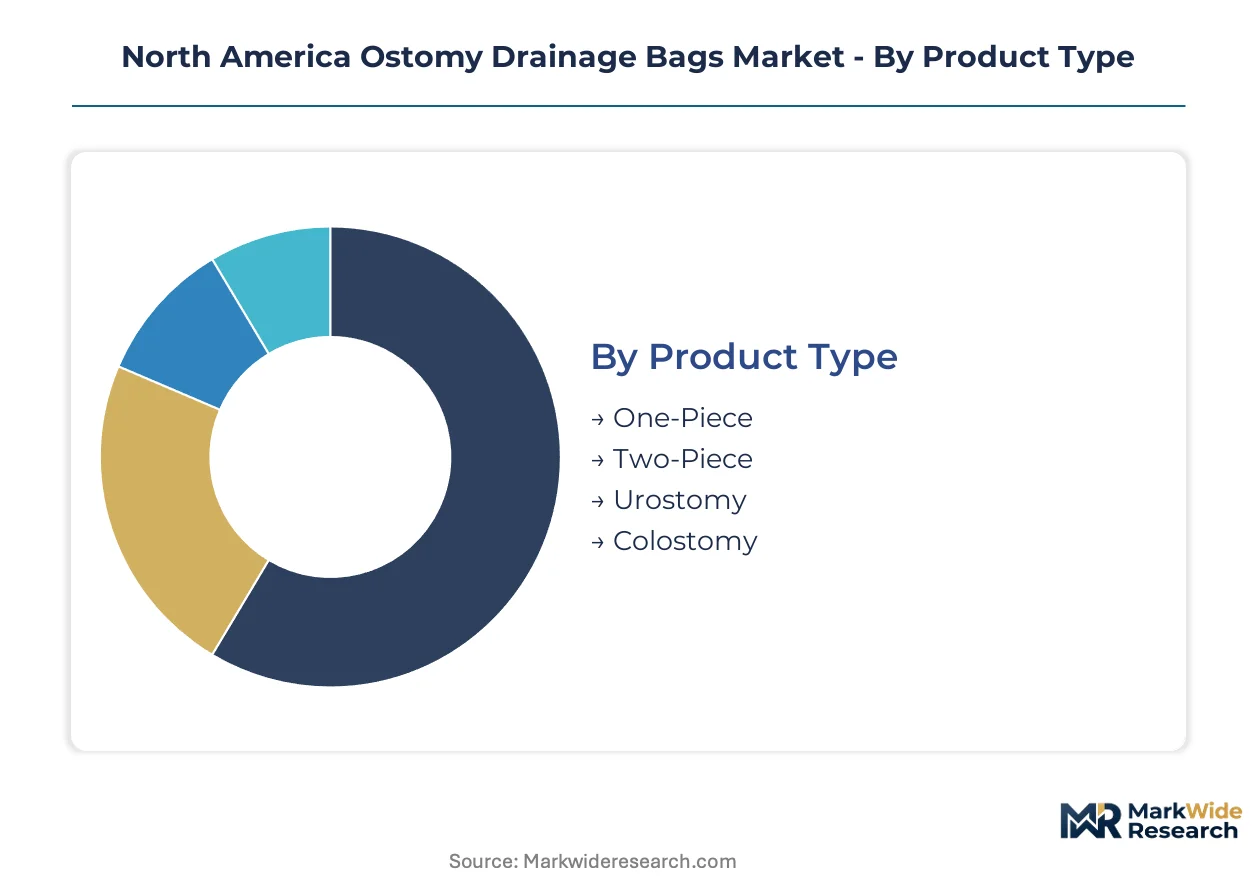
Segmentation in ostomy drainage bags determines reimbursement pathways, manufacturing investment priorities, and competitive positioning across North American distribution channels. Each dimension—product architecture, material chemistry, care setting, and functional feature—carries distinct regulatory and margin implications.
Product Type:
Two-piece systems demand the heaviest upfront tooling investment for modular barrier-pouch interfaces, while one-piece platforms concentrate volume in standardized hospital procurement.
- One-Piece:Integrated skin barrier and collection pouch formed from single-molded hydrocolloid or silicone composite. Demand clusters in acute care settings across Texas and Florida where discharge speed outweighs customization needs.
- Two-Piece:Detachable coupling mechanism permits independent barrier replacement and pouch rotation. Home care patients in Medicare Advantage plans across California and Ontario drive preference for the flexibility to swap components on different schedules.
- Urostomy:Specialized night drainage adapters and anti-reflux valves manage continuous urine flow. Spinal cord injury rehabilitation centers in the US Veterans Health Administration constitute concentrated demand.
- Colostomy:Closed-end pouches with integrated gas filters address solid waste management. Long-term care facilities in Quebec and Illinois standardize on these for immobile residents.
Most installed capacity flows through One-Piece systems. Expansion is steepest in Two-Piece configurations.
Material:
Raw material selection governs biocompatibility certification costs, with silicone platforms requiring the most extensive ISO 10993 testing protocols.
- Plastic:Multi-layer coextruded polyethylene and polypropylene films form odor-barrier substrates. Hospital procurement in Arizona and Michigan prioritizes these for cost containment in high-turnover environments.
- Silicone:Soft, platinum-cured elastomer adhesives enable extended 5-7 day wear protocols. Home care subscribers in British Columbia and Massachusetts absorb premium pricing for reduced dermatitis incidence.
- Hydrocolloid:Carboxymethyl cellulose and pectin matrices absorb moisture while maintaining adhesion. Skilled nursing facilities across Ohio standardize on these for moderate-wear applications.
- PVC:Legacy chlorinated polymer construction faces displacement amid FDA scrutiny of plasticizer leaching. Remaining demand concentrates in price-sensitive Medicaid channels.
Silicone commands the highest unit economics. Hydrocolloid retains the broadest reimbursement coverage.
End User:
Channel economics diverge sharply: institutional buyers negotiate annual contracts while home care patients trigger recurring revenue through subscription models.
- Hospitals:Centralized value analysis committees drive standardization toward one-piece, plastic-based platforms. Level I trauma centers in Pennsylvania and Georgia generate procedure-linked demand spikes.
- Home Care:Medicare Part B reimbursement and provincial coverage in Ontario determine patient out-of-pocket exposure. Direct-to-patient platforms in Illinois and Texas are consolidating this fragmented channel.
- Rehabilitation Centers:Transitional care settings require adaptive sizing for post-surgical weight fluctuation. Spinal cord and colorectal specialty units in Colorado and Alberta concentrate demand.
- Long-Term Care Facilities:Nursing home operators prioritize staff efficiency through extended-wear systems with minimal intervention. For-profit chains across Florida and Quebec drive volume.
Revenue per patient runs highest in Home Care. Patient volume concentrates in Hospitals.
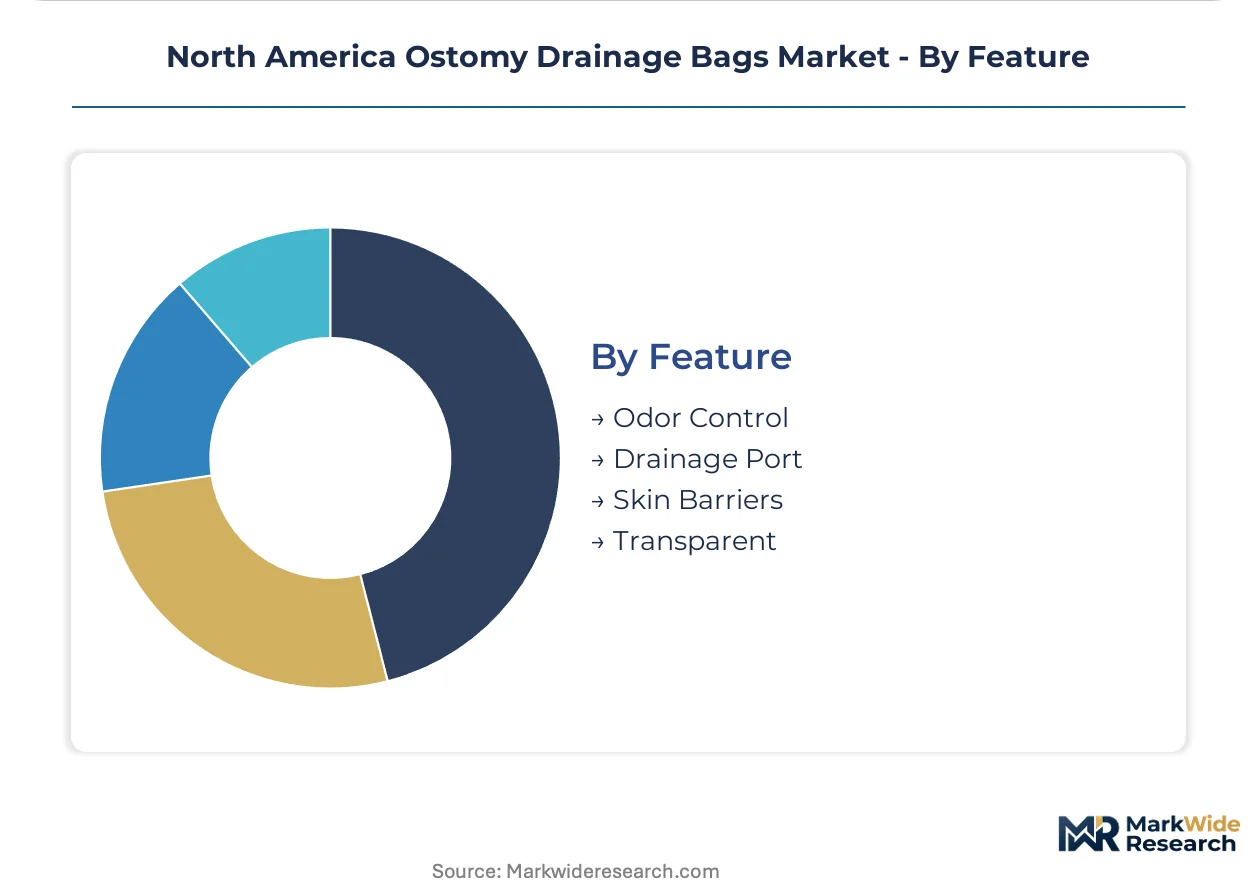
Feature:
Functional differentiation determines premium positioning, with odor control filtration requiring the most specialized manufacturing capability.
- Odor Control:Activated carbon or zeolite-impregnated membranes neutralize effluent gases. Social reintegration priorities among working-age ostomates in California and New York sustain willingness to pay.
- Drainage Port:Integrated valve mechanisms permit liquid emptying without pouch removal. Urostomy patients in Ontario's provincial home care program require these for overnight management.
- Skin Barriers:Molded hydrocolloid or silicone rings protect peristomal tissue. Pediatric and geriatric segments in Texas and Alberta drive demand for hypoallergenic formulations.
- Transparent:Clear film construction permits visual effluent monitoring without pouch removal. Post-acute surgical units in Michigan and British Columbia specify these for early complication detection.
Most product development resources flow toward Odor Control. Fastest feature adoption is occurring in Skin Barriers with silicone chemistry.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The ostomy drainage bag industry traces its North American commercial roots to post-World War II medical device manufacturing clusters in the US Midwest and Ontario, where adhesive chemistry expertise from industrial tape production transferred into healthcare applications.
United States
Medicare Part B reimbursement expansion and aging demographics in Florida and Arizona sustain the continent's largest procedure volumes. FDA 510(k) premarket notification requirements govern commercial entry timelines for new barrier chemistries. Home care distributors in Chicago and Houston are consolidating procurement through direct-to-patient subscription platforms.
Canada
Provincial technology assessment programs in Ontario and British Columbia pilot extended-wear silicone systems through public coverage expansion. Health Canada's MDR-aligned licensing transition extends quality system documentation requirements. Manufacturing concentration in Toronto-Waterloo corridor serves both domestic demand and tariff-advantaged export to US markets.
Mexico
FDA-registered maquiladora facilities in Tijuana and Juárez offer 30-40% labor cost differentials versus US domestic production for export-bound capacity. Mexico's national pharmaceutical regulator COFEPRIS maintains alignment with FDA quality system expectations. Border state industrial parks attract contract manufacturing investment from multinational device firms seeking North American market access.
North America Ostomy Drainage Bags Market Competitive Landscape
Premium-margin players sit above commodity-margin players across adhesive chemistry and wear-duration dimensions. The vendor base clusters around three tiers: integrated multinational device conglomerates with full ostomy portfolios, mid-scale specialists focused on barrier innovation, and regional contract manufacturers serving private-label demand. Consolidation pressure runs highest among distributors as direct-to-patient channels bypass traditional durable medical equipment intermediaries. Capacity expansion and strategic partnerships represent the dominant competitive vectors.
Within the integrated multinational tier, Coloplast and Hollister exemplify divergent specialization strategies—one anchored in silicone adhesive platforms, the other in hydrocolloid barrier systems. ConvaTec Group occupies a position bridging these chemistries with hybrid material approaches. These three entities collectively represent the premium-tier competitive anchor against which mid-scale specialists and private-label fabricants define their market positions.
| Leading Market Players |
|---|
| Coloplast |
| ConvaTec Group |
| B. Braun Melsungen |
| Hollister |
| Salts Healthcare |
| Alcare |
| Flexicare Medical |
| Welland Medical |
| Dansac |
| Others |
Value Network & Pricing Analysis
Backward integration into silicone adhesive chemistry anchors both supply security and premium pricing power for barrier manufacturers serving Medicare-reimbursed home care channels across the United States and Ontario. Captive production of hydrocolloid matrices and platinum-cured elastomer platforms insulates tier-one suppliers from resin allocation volatility while supporting 5-7 day wear-duration claims that command reimbursement advantages.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates silicone-based extended-wear systems from hydrocolloid mid-tier offerings and legacy PVC alternatives. Price differentiation rests on ISO 10993 biocompatibility certification tiers and FDA 510(k) clearance status, with Medicare Advantage enrollees absorbing premium out-of-pocket exposure for dermatitis-reduction benefits. Cost compression in economy-tier PVC segments is intensifying because Medicaid procurement committees prioritize unit cost over wear duration. Hospital value analysis committees exhibit highest price sensitivity; home care subscription patients demonstrate lowest sensitivity when insurance pre-verification reduces cash burdens.
Supply Chain Analysis
Direct-to-patient e-commerce platforms with insurance pre-authorization bypass traditional durable medical equipment distributors in metropolitan markets like Chicago and Houston. Manufacturing concentration in the Toronto-Waterloo corridor, Tijuana maquiladora parks, and Ohio medical device clusters feeds North American demand. Raw material dependencies include multi-layer coextruded polyethylene films, platinum-cured silicone elastomers, and carboxymethyl cellulose matrices. Single-source vulnerability in specialty polymer resin allocations from three dominant suppliers creates input cost volatility when hospital procurement volumes spike. Distribution runs through integrated specialty pharmacies consolidating barrier systems with stoma nursing consultations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in ostomy drainage bags hinges on silicone chemistry substitution accelerating premium-tier capture from legacy hydrocolloid and PVC alternatives. Extended-wear protocols reduce per-patient supply consumption while sustaining higher unit economics.
For Market Incumbents: Anchor defensive positioning through captive silicone adhesive production and FDA 510(k) portfolio depth against emerging entrants with abbreviated regulatory pathways. Deepen hospital system partnerships in Level I trauma centers to lock in discharge-protocol standardization. Invest in Ontario and British Columbia provincial technology assessment pilot programs to secure public coverage expansion for next-generation barrier systems. For New Entrants and Emerging Players: Soft silicone hybrid configurations with detachable baseplates offer technology-first wedge positioning against entrenched one-piece and two-piece architectures. Pediatric ostomy subspecialization presents the most penetrable white space, with neonatal and adolescent sizing gaps unaddressed by incumbent SKU proliferation. Target direct-to-patient subscription channels in Texas and Illinois where insurance pre-verification platforms consolidate fragmented home care procurement. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale barrier specialists because Health Canada MDR-aligned licensing friction extends approval timelines and strands sub-scale competitors without quality system documentation capacity. Platform consolidation around silicone chemistry expertise and direct-to-patient channel control offers 5-10 year viability as Medicare Advantage penetration deepens. Watch CMS coverage determinations for advanced barrier materials as the critical inflection signal for premium-tier pricing power expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Premarket clearance for silicone adhesive platforms accelerates Medicare reimbursement eligibility in home care channels. |
| Hospital System Partnership | Level I trauma center standardization agreements lock in discharge-protocol volumes and barrier chemistry preferences. |
| Reimbursement Strategy | CMS coverage determination alignment for extended-wear protocols directly influences patient upgrade economics. |
| Software Companion Development | Digital stoma monitoring applications integrate with specialty pharmacy platforms to capture adherence data. |
| CE Marking Pathway | MDR-aligned documentation for Health Canada licensing enables tariff-advantaged export from Ontario manufacturing. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each national market. The analysis combines structured interviews with hospital purchasing committee members, GPO contracts managers, biomedical engineers, and home care stoma nurses with secondary validation from FDA 510(k) filings, Health Canada medical device license databases, CMS Medicare reimbursement schedules, and provincial technology assessment records. Bottom-up demand modeling from procedure volumes and top-down market sizing from manufacturer capacity disclosures undergo triangulation for convergence.
Granularity-level modeling distinguishes product architecture, material chemistry, care setting, and functional feature dimensions across the projection horizon. Segmentation analysis captures one-piece versus two-piece configurations, silicone versus hydrocolloid versus PVC substrates, hospital versus home care versus long-term care channels, and odor control versus drainage port versus skin barrier feature sets. CAGRs derive from fitted growth curves anchored to aging demographic projections and reimbursement policy trajectories. Forecast inputs include Medicare Advantage enrollment shifts and provincial coverage expansion timelines for extended-wear systems.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA adhesive dermatitis claim scrutiny and resin allocation volatility from specialty polymer suppliers. Projections reflect assumptions around CMS reimbursement stability and Health Canada MDR transition pacing. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Plastic Syringes Market
Medical Supplies
Medical Gloves Market
Medical Supplies
Medical Bags Market
Medical Supplies
Endoscope Tip Protectors Market
Medical Supplies
Asia-Pacific Insulin Syringe Market
Medical Supplies
Asia-Pacific Human Fibrin Glue Market
Medical Supplies
Anesthesia Syringes and Needles Market
Medical Supplies
Global Surgical Pledgets Market
Medical Supplies
Skin Tac Market
Medical Supplies
Micro Vials Market
Medical Supplies
Sterilization Box Market
Medical Supplies
United Kingdom Hospital Supplies Market
Medical Supplies
Pressure Relief Mattress Market
Medical Supplies
Global Enema Bags Market
Medical Supplies
Hydrocolloid Sponges Market
Medical Supplies
Medical Tapes and Bandages Market