
 Single Use Safety Lancet Market | 2026-2036
Single Use Safety Lancet Market Size, Share, and Industry Trends Forecast 2026-2036
Single Use Safety Lancet Market Insights
The FDA's updated sharps safety guidance is recalibrating the cost-of-entry calculus for disposable blood-drawing devices. Becton Dickinson and Company leverages its integrated manufacturing footprint to sustain pricing power across hospital and homecare channels. Terumo Corporation anchors its position through specialized needle engineering capabilities that differentiate its safety-trigger mechanisms from commodity alternatives.
A single use safety lancet is a sterile, spring-loaded or manually activated puncture device engineered to draw capillary blood volumes between 0.5 microliters and 75 microliters, incorporating an irreversible safety shield or retraction feature to prevent needlestick injuries after activation. Its primary commercial purpose is enabling safe, standardized capillary blood collection for glucose monitoring, hemoglobin testing, and rapid diagnostic assays across clinical and non-clinical settings. Automatic lancets dominate unit volumes in diabetes management applications where patient self-operation demands one-hand activation, while adjustable depth lancets command margin premiums in pediatric and geriatric segments requiring customized puncture control. Point-of-care testing channels are shifting toward fixed-depth disposable configurations to reduce variability in rapid diagnostic workflows.
The FDA enforces Class II medical device controls and sharps injury prevention standards that shape product design specifications and 510(k) clearance pathways for safety-engineered lancets. The EU MDR and OSHA Bloodborne Pathogens Standard impose parallel compliance burdens on manufacturers seeking access to European and US occupational health markets. Stakeholders must monitor evolving reimbursement codes for safety-engineered devices and anticipate how homecare expansion will reshape channel economics between direct sales and pharmacy distribution.
Market Dynamics
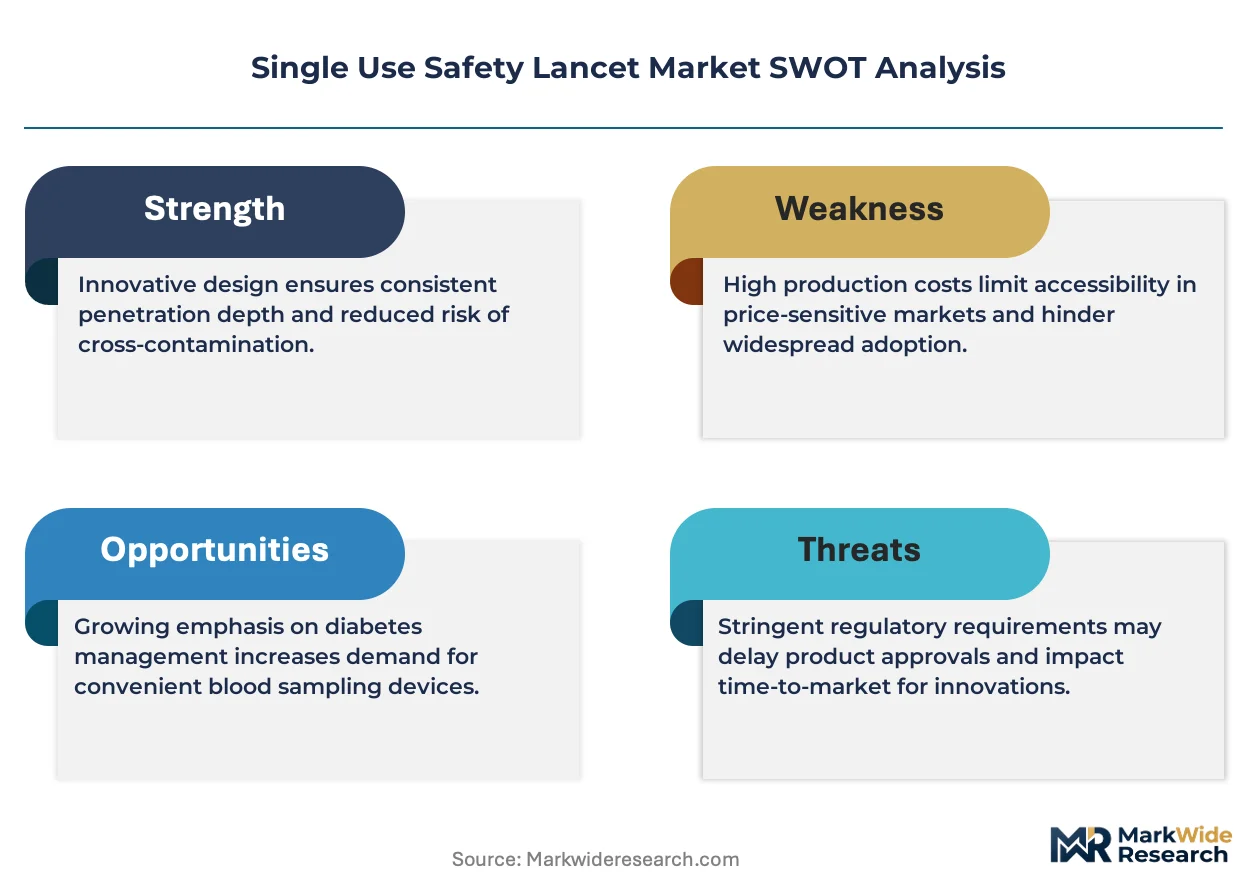
The FDA's sharpened sharps injury prevention focus is elevating compliance thresholds for new entrants while concentrating procurement among established manufacturers with integrated safety-engineering capabilities.
Growth Catalysts
- OSHA Bloodborne Pathogens Standard:Mandates for safety-engineered devices in US healthcare settings are accelerating hospital procurement of retractable and shielded lancet configurations.
- Homecare glucose monitoring:Patient self-testing regimes are expanding unit demand beyond clinical settings into pharmacy and direct-to-patient channels.
- Capillary microsampling:Point-of-care diagnostic workflows are standardizing on fixed-depth disposable lancets to reduce hemolysis variability in rapid testing.
Market Restraints
- Medical-grade polymer costs:Specialized polypropylene and polycarbonate resins for sterile housing production face petrochemical price volatility.
- Spring mechanism precision:Tolerance requirements for consistent puncture depth limit supplier options to specialized metal-forming subcontractors.
- EU MDR transition:Extended conformity assessment timelines for Class IIa devices are delaying market access for revised product lines.
Strategic Opportunities
- Pediatric depth customization:Adjustable-depth platforms for neonatal and infant hemoglobin testing command margin premiums in underserved segments.
- Pharmacy distribution bypass:Direct-to-patient subscription models for chronic glucose monitoring are disintermediating traditional hospital supply chains.
- IRA preventive care expansion:Enhanced Medicare reimbursement for home-based diabetes management devices is widening addressable patient populations.
Industry Challenges
- Biocompatibility testing timelines:ISO 10993 cytotoxicity and sensitization studies for new polymer formulations extend development cycles by 12-18 months.
- Legacy device sterilization:Ethylene oxide transition to electron beam or gamma alternatives requires capital-intensive facility requalification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single Use Safety Lancet Market |
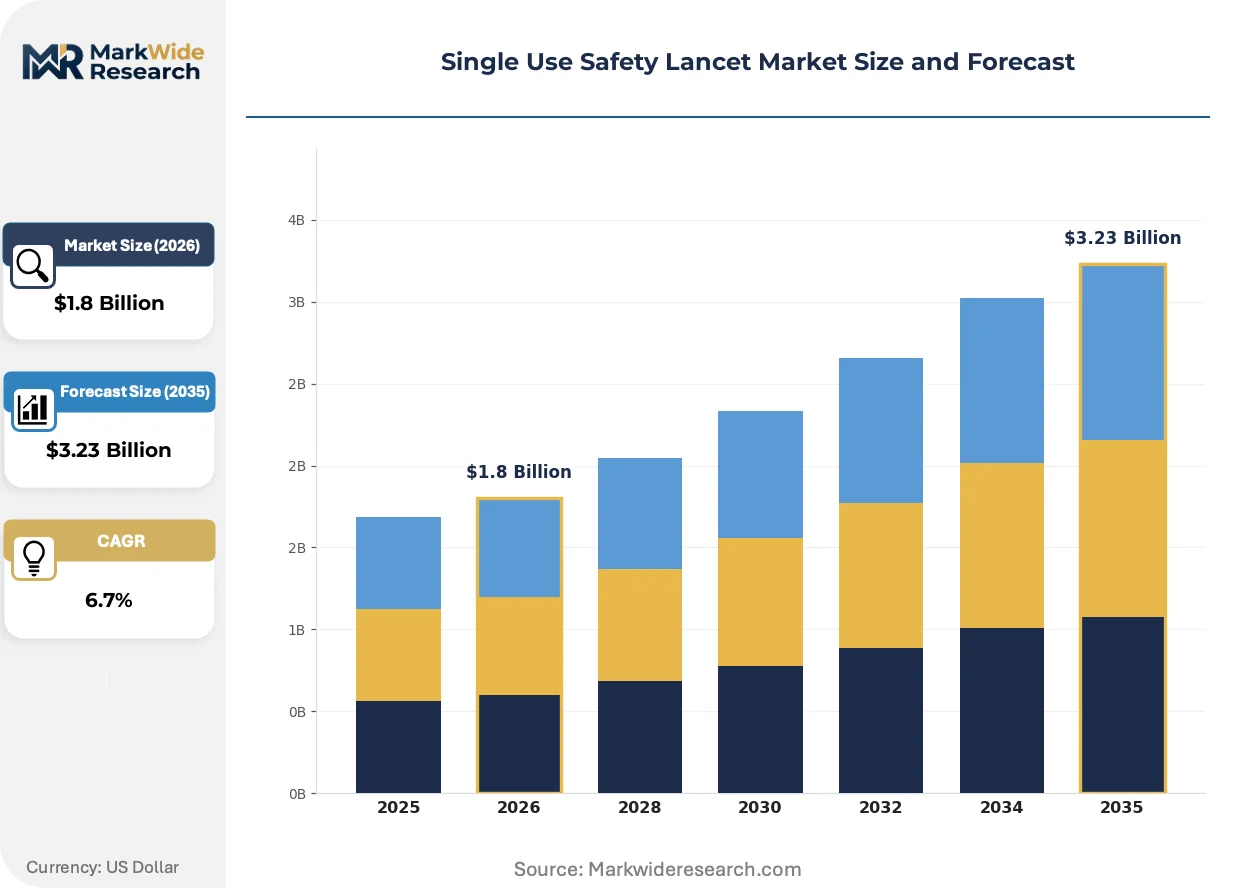
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Lancets, Manual Lancets, Adjustable Depth Lancets, Fixed Depth Lancets End User: Hospitals, Clinics, Homecare, Blood Banks Application: Diabetes Management, Blood Sampling, Laboratory Testing, Point-of-Care Testing Distribution Channel: Online Retail, Pharmacy, Medical Supply Stores, Direct Sales |
| Companies Covered | Becton Dickinson and Company, F. Hoffmann-La Roche AG, Terumo Corporation, B. Braun SE, Abbott Laboratories, Greiner Bio-One International GmbH, Owen Mumford Ltd, Cardinal Health, Sarstedt AG & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single Use Safety Lancet Market Trends and Innovations
Spring-loaded activation mechanisms are converging with miniaturized electronics to create feedback-enabled lancet systems that reshape patient adherence and clinical workflow standardization.
Passive safety shielding is automating needle retraction upon capillary contact, eliminating separate activation steps. Homecare patients with limited dexterity are adopting these configurations fastest. The technology is automating compliance with OSHA sharps injury prevention requirements while reducing training burdens for self-monitoring regimes.
EU MDR Article 10 technical documentation requirements are mandating expanded clinical evidence for legacy lancet designs. Manufacturers are consolidating product portfolios to focus resources on highest-volume SKUs. The regulation is compressing available supplier options in European hospital procurement.
Hospital buyers are consolidating safety-engineered device contracts under single-source agreements with integrated glucose monitoring ecosystem providers. Independent lancet distributors are losing shelf space to bundled diagnostic platform vendors. This concentration is most visible in United States integrated delivery networks negotiating enterprise-wide diabetes management contracts.
Single Use Safety Lancet Market Segmentation
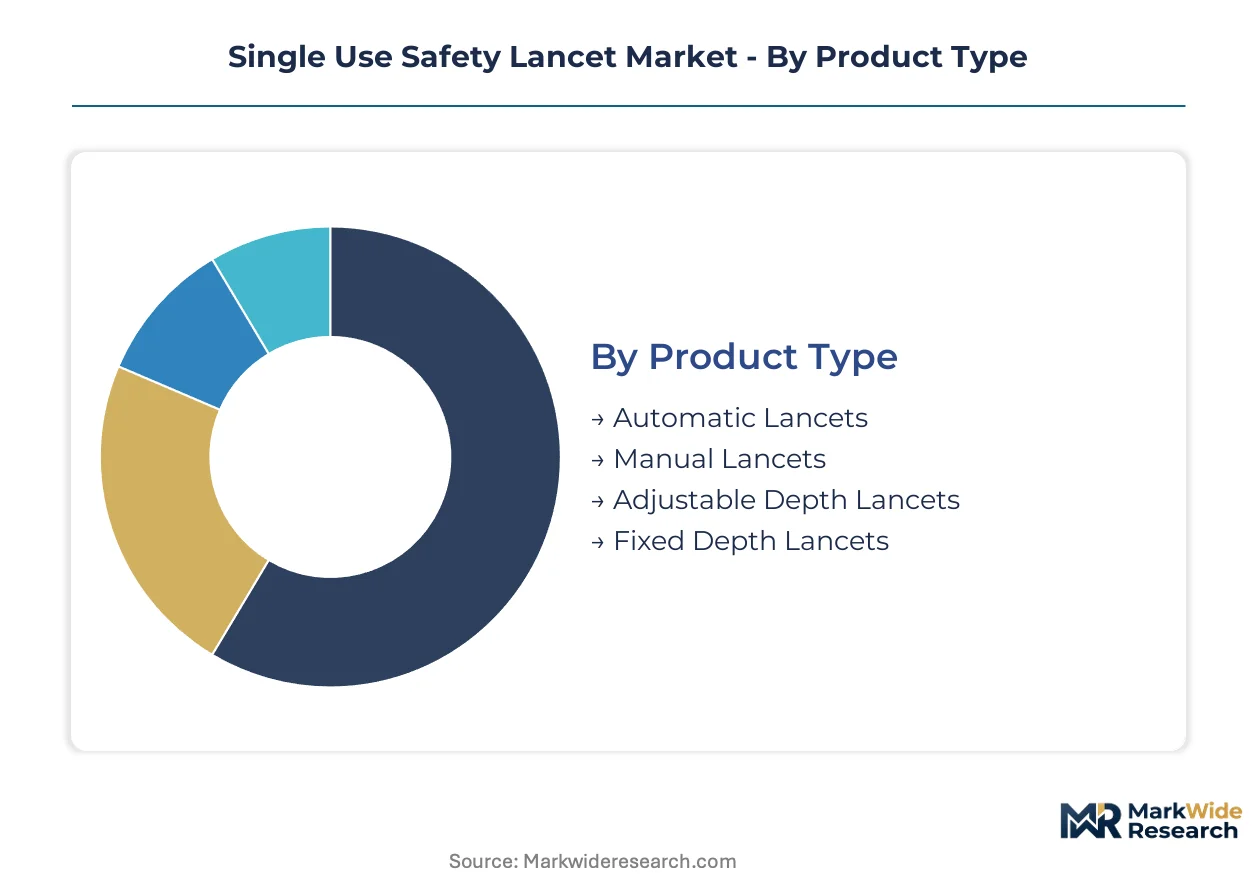
Segmentation in the single use safety lancet market reveals how procurement criteria diverge between institutional buyers and self-monitoring patients. Product specifications, channel access, and reimbursement pathways create distinct competitive arenas that manufacturers must navigate simultaneously.
Product Type:
Patient dexterity and clinical workflow requirements drive purchasing decisions across activation mechanisms and depth control features.
- Automatic Lancets:Spring-loaded devices with one-hand activation dominate diabetes self-monitoring applications where patients require simplified operation. Demand concentrates in United States pharmacy and direct-to-patient channels driven by Medicare reimbursement expansion for home-based glucose management.
- Adjustable Depth Lancets:Variable puncture control mechanisms accommodate neonatal, pediatric, and geriatric skin thickness variations. Pediatric hemoglobin testing programs in hospital systems command margin premiums for customized depth platforms.
- Manual Lancets:Thumb-press activation devices with lower unit costs serve cost-sensitive clinical environments.
- Fixed Depth Lancets:Standardized puncture configurations reduce variability in rapid diagnostic workflows at point-of-care sites.
Volume sits with automatic lancets; growth tilts toward adjustable depth platforms.
End User:
Procurement authority and reimbursement eligibility reshape channel economics across care settings.
- Homecare:Patient-directed purchasing through pharmacy and online channels is expanding fastest as self-monitoring glucose regimes displace clinical visits. IRA preventive care provisions are widening Medicare reimbursement for home-based diabetes devices.
- Hospitals:Integrated delivery networks negotiate enterprise-wide safety-engineered device contracts under OSHA Bloodborne Pathogens Standard compliance mandates. United States hospital procurement concentrates among manufacturers with 510(k) clearance pathways.
- Clinics:Outpatient facilities balance cost containment with safety feature requirements for capillary blood collection.
- Blood Banks:High-volume screening operations prioritize sterility assurance and needlestick prevention in donor settings.
Procurement authority rests with hospitals; patient volume expansion favors homecare.
Application:
Diagnostic workflow standardization requirements determine lancet configuration selection across testing modalities.
- Diabetes Management:Capillary glucose monitoring represents the dominant volume application, with automatic lancets standardizing self-testing protocols. FDA Class II device controls shape product specifications for this indication.
- Point-of-Care Testing:Rapid diagnostic workflows in emergency and outpatient settings demand fixed-depth disposable configurations to minimize hemolysis variability. United States point-of-care expansion is accelerating procurement of safety-engineered devices.
- Blood Sampling:General capillary collection for hematology and chemistry panels.
- Laboratory Testing:Central lab quality control and confirmatory testing applications.
Unit scale concentrates in diabetes management; workflow standardization drives point-of-care adoption.
Distribution Channel:
Channel selection reflects patient access preferences and institutional contracting patterns.
- Pharmacy:Retail and mail-order pharmacy networks serve the expanding homecare patient population with reimbursement-eligible lancet configurations. United States pharmacy benefit managers are consolidating safety-engineered device formularies.
- Direct Sales:Manufacturer-to-patient subscription models for chronic glucose monitoring are disintermediating traditional supply chains. Direct channels capture margin premiums while reducing distributor overhead.
- Online Retail:E-commerce platforms serve cash-pay patients and supplement institutional procurement.
- Medical Supply Stores:Specialty distributors serve small clinic and long-term care facility accounts.
Institutional volume flows through pharmacy; subscription direct sales are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States demand concentrates procurement authority for safety-engineered lancets, with Medicare reimbursement expansion and OSHA compliance mandates reshaping channel economics across hospital and homecare settings.
United States
Diabetes prevalence and IRA preventive care provisions drive homecare glucose monitoring adoption. FDA Class II device controls and 510(k) clearance pathways elevate compliance costs for new entrants. Boston and Minneapolis medical device clusters concentrate safety-engineering R&D for retractable lancet mechanisms.
Germany
Hospital procurement consolidation under EU MDR Article 10 technical documentation requirements favors established manufacturers with integrated quality systems. REACH chemical safety regulations shape polymer selection for sterile housing production. Baden-Württemberg's precision engineering corridor hosts specialized metal-forming subcontractors for spring mechanism components.
Japan
Aging demographics and self-monitoring glucose regime expansion propel pharmacy channel demand. PMDA medical device regulations align with ISO 13485 quality management standards for market access. Tokyo-Osaka industrial corridor concentrates needle engineering capabilities for miniaturized safety-trigger systems.
China
Domestic diabetes management device production scales under NMPA Class II medical device registration requirements. Dual carbon goals accelerate ethylene oxide sterilization facility transitions to electron beam alternatives. Yangtze River Delta manufacturing hubs integrate automatic lancet assembly for regional hospital procurement.
India
Point-of-care diagnostic workflow expansion in tier-2 cities drives fixed-depth disposable lancet consumption. CDSCO medical device rules and BIS standards for sterile medical products shape import substitution strategies. Gujarat and Maharashtra pharmaceutical clusters localize capillary blood collection device assembly for South Asian markets.
Single Use Safety Lancet Market Competitive Landscape
United States producers anchor the premium tier with integrated glucose monitoring ecosystems; Japanese and German specialists hold positions in precision needle engineering and safety mechanism fabrication. The vendor structure concentrates procurement authority among manufacturers with 510(k) clearance pathways and EU MDR conformity assessment capabilities. Three archetypes dominate: diversified medical device conglomerates with hospital contracting scale, specialized safety-engineering firms with proprietary retraction technologies, and regional assemblers serving cost-sensitive pharmacy channels. Competitive moves center on enterprise-wide diabetes management contract consolidation and direct-to-patient subscription model deployment.
Within the diversified conglomerate tier, Becton Dickinson and Company and Abbott Laboratories represent integrated ecosystem providers with hospital and homecare channel presence. Terumo Corporation exemplifies the precision engineering specialist archetype, occupying a position defined by specialized needle fabrication capabilities. These three anchors illustrate how regulatory compliance scale and manufacturing integration separate procurement winners from commodity competitors in safety-engineered lancet supply.
| Leading Market Players |
|---|
| Becton Dickinson and Company |
| F. Hoffmann-La Roche AG |
| Terumo Corporation |
| B. Braun SE |
| Abbott Laboratories |
| Greiner Bio-One International GmbH |
| Owen Mumford Ltd |
| Cardinal Health |
| Sarstedt AG & Co. KG |
| Others |
Pricing and Supply Chain Analysis
Precision metal-forming specialists in Baden-Württemberg command wage premiums that widen spreads between premium safety-engineered lancets and economy manual alternatives. Labor-cost differentials between German spring-mechanism subcontractors and Asian assembly operations create three-tier pricing structure across premium, standard, and economy levels.
Pricing Analysis
Volume concentrates in automatic lancets with thin margins; adjustable-depth platforms capture margin premiums through pediatric customization. Price differentiation hinges on FDA 510(k) clearance tier and spring-mechanism precision grade. Cost compression in economy manual lancets is intensifying because of petrochemical resin volatility. Hospital procurement committees show lowest price sensitivity; cash-pay pharmacy patients exhibit highest.
Supply Chain Analysis
ISO 13485 certification and FDA facility inspection records gate supplier eligibility for sterile device assembly. Manufacturing concentrates in Germany, Japan, and China for spring components and final assembly. Raw material dependencies include medical-grade polypropylene, stainless steel for precision springs, and ethylene oxide or electron beam sterilization services. Single-source vulnerability sits with specialized metal-forming subcontractors for consistent puncture-depth tolerance. Distribution runs through pharmacy benefit manager formularies and direct-to-patient subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where EU MDR technical documentation burdens and sterilization facility requalification costs force weaker assemblers toward exit.
For Market Incumbents: Deepen backward integration into precision spring manufacturing to capture margin currently flowing to Baden-Württemberg subcontractors. Anchor hospital contracting scale through bundled glucose monitoring ecosystem offerings that displace independent lancet distributors. Threat from emerging Asian assemblers with NMPA registration but lacking EU MDR conformity assessment capabilities demands proactive GPO relationship lock-in.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in adjustable-depth neonatal configurations offers white-space entry with margin headroom. Pediatric hemoglobin testing programs in United States hospital systems represent the most penetrable segment given underserved customization demand. Go-to-market angle: direct sales to long-term care facilities bypassing consolidated pharmacy benefit manager formularies.
For Investors and Strategic Acquirers: The window for entry favors specialized safety-engineering firms with proprietary passive shielding patents but limited channel scale. Long-term viability hinges on 510(k) clearance pathway access and EU MDR Article 10 technical documentation capabilities. Signal to watch: CMS reimbursement code expansion for home-based diabetes management devices as volume inflection trigger.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates hospital procurement eligibility under Class II device controls. |
| EU MDR Conformity Assessment | Unlocks European integrated delivery network contracting opportunities. |
| Hospital System Partnership | Secures enterprise-wide safety-engineered device contract consolidation. |
| Backward Integration into Springs | Captures margin from precision metal-forming subcontractors in Germany. |
| Direct-to-Patient Subscription Launch | Disintermediates pharmacy benefit managers for chronic glucose monitoring. |
Research Methodology
Independent corroboration across hospital purchasing committee interviews, GPO contracts managers, and biomedical engineers underwrites the qualitative findings. Primary fieldwork engaged regulatory affairs leads at sterile device manufacturers and pharmacy benefit manager formulary directors. Secondary validation drew from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement contract repositories, and EU MDR notified body assessment records. Bottom-up unit demand modeling triangulated against top-down market sizing across activation mechanism, depth control, and end-use segments.
Rate-of-change decomposition separated volume growth from pricing trajectory across the projection horizon. Segmentation dimensions modeled include product type, end user setting, application workflow, and distribution channel structure. CAGRs were derived from normalized growth curve fitting against historical diabetes prevalence trends and reimbursement expansion patterns. Industry-specific forecast inputs incorporated OSHA Bloodborne Pathogens Standard compliance timelines and IRA preventive care provision implementation.
Inputs from FDA 510(k) clearance databases and EU MDR notified body registries were available through the study window; gaps in real-time hospital procurement contract terms introduce uncertainty bands around pricing trajectory assumptions. Forecasts reflect documented assumptions regarding Medicare reimbursement stability and polymer feedstock price normalization. A model refresh is warranted upon material change in FDA sharps injury prevention guidance or EU MDR Article 10 technical documentation requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Sharps Containers Market
Medical Supplies
Surgical Amniotics Market
Medical Supplies
Bleeding Control Kit Market
Medical Supplies
Medical and Industrial Gloves Market
Medical Supplies
Emergency Transfer Vacuum Mattress Market
Medical Supplies
Plasma Collection Containers Market
Medical Supplies
Global Swab and Viral Transport Medium Market
Medical Supplies
Disposable Specimen Container Market
Medical Supplies
North America Hospital Supplies Market
Medical Supplies
Americas Safety Lancet Market
Medical Supplies
Medical Gloves Market
Medical Supplies
Drainage Bottles Market
Medical Supplies
Enteral Syringes Market
Medical Supplies
Compression Socks Market
Medical Supplies
Global IV Tubing Sets and Accessories Market
Medical Supplies
Resuscitation Masks Market