
 Asia-Pacific Fats and Oil Market | 2026-2036
Asia-Pacific Fats and Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Fats and Oil Market Outlook
Downstream refining and specialty fat formulation is reshaping margin distribution across the Asia-Pacific Fats and Oil Market. Wilmar International leverages integrated palm oil processing complexes across Indonesia and Malaysia to sustain cost advantages in bulk olein and stearin output. Cargill competes through its soy crush and lecithin extraction network, while Fuji Oil specializes in confectionery fats and cocoa butter equivalents for Japanese and Southeast Asian chocolate manufacturers.
Asia-Pacific fats and oils encompass triglyceride-based lipids derived from oilseed crushing, fruit pulp extraction, and animal rendering, with specifications spanning iodine values from 45 to 130 and slip melting points between 20°C and 55°C for tailored functional performance in food and industrial applications. Vegetable oils dominate volume throughput, anchored by palm oil's cost position and soy oil's protein-meal coproduct economics, while biofuels application represents the fastest-expanding end-use channel as Indonesia and Malaysia enforce higher biodiesel blending mandates. Margarine and shortening categories face structural pressure from clean-label reformulation requirements, pushing margin pools toward premium bakery and pastry fat solutions.
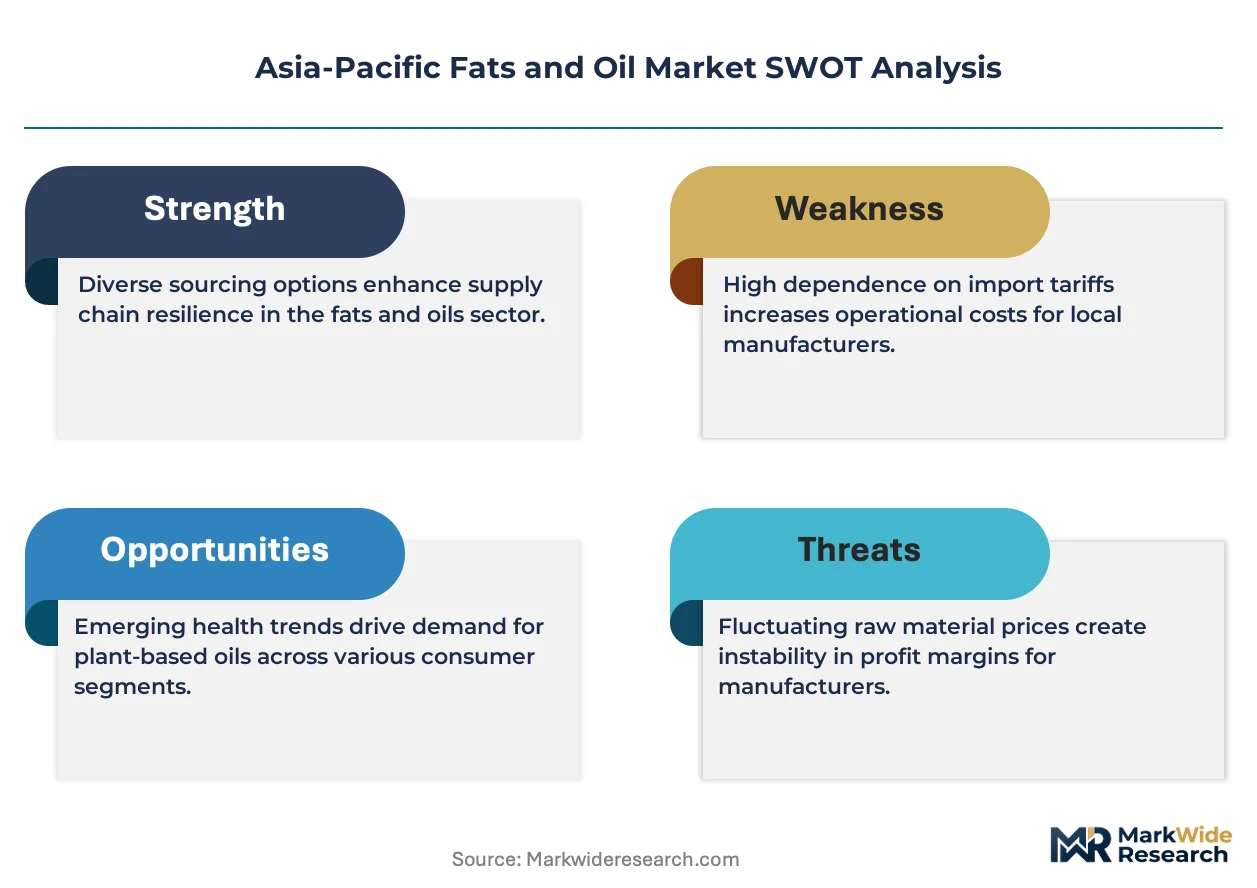
FSSAI trans-fat regulations in India, Indonesia's BPDPKS biodiesel subsidy framework, and Malaysia's MSPO sustainability certification collectively constrain product formulations and market access across the region. Compliance with these overlapping standards raises formulation complexity for exporters serving multiple national markets. Stakeholders must monitor blending mandate revisions and sustainability audit protocols to anticipate procurement cost shifts and qualify for preferential supply contracts.
Market Dynamics
Indonesia's BPDPKS biodiesel subsidy framework is redirecting palm oil flows from food manufacturing toward fuel blending, tightening edible oil supply chains and elevating feedstock competition across Southeast Asian refineries.
Growth Catalysts
- Biodiesel blending mandates:Indonesia's B35 and Malaysia's B20 programs are absorbing rising palm oil volumes, stimulating crushing capacity expansion and backward integration into plantation assets.
- India:FSSAI trans-fat limits below 2% are forcing packaged food manufacturers toward interesterified blends and high-oleic formulations, creating reformulation service demand.
- Specialty fats:Cocoa butter equivalents and confectionery coatings for Japanese chocolate processors are capturing premium margins as clean-label requirements intensify.
Market Restraints
- Input cost volatility:Crude palm oil prices swing with Malaysian ringgit fluctuations and El Niño weather patterns, compressing refinery margins and hedging effectiveness.
- Supply concentration risk:Indonesian and Malaysian producers control over 85% of global palm oil trade, creating single-source dependency for Indian and Chinese buyers.
- Technical limitation:Partially hydrogenated oils remain entrenched in traditional South Asian bakery applications due to cost and functionality gaps in enzymatic interesterification.
Strategic Opportunities
- Vietnam:Underdeveloped oilseed crushing infrastructure and rising processed food consumption create greenfield investment potential for integrated soy-palm facilities.
- MSPO certification:Malaysia's sustainability standard is unlocking preferential supply contracts with EU and Japanese buyers seeking deforestation-free documentation.
- High-oleic sunflower and canola:These oils are penetrating premium frying and snack segments as alternatives to palm olein in Australia and South Korea.
Industry Challenges
- Interesterification expertise:Shortages of process engineers capable of enzymatic fat modification are delaying trans-fat reformulation timelines for mid-tier Indian refiners.
- Capex intensity:Fractionation and refining equipment upgrades for specialty fat production require capital outlays that strain balance sheets outside integrated plantation groups.
- Dual certification burden:Simultaneous compliance with MSPO, RSPO, and FSSAI audit protocols is extending product qualification cycles by 8-14 months for multi-market suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Fats and Oil Market |
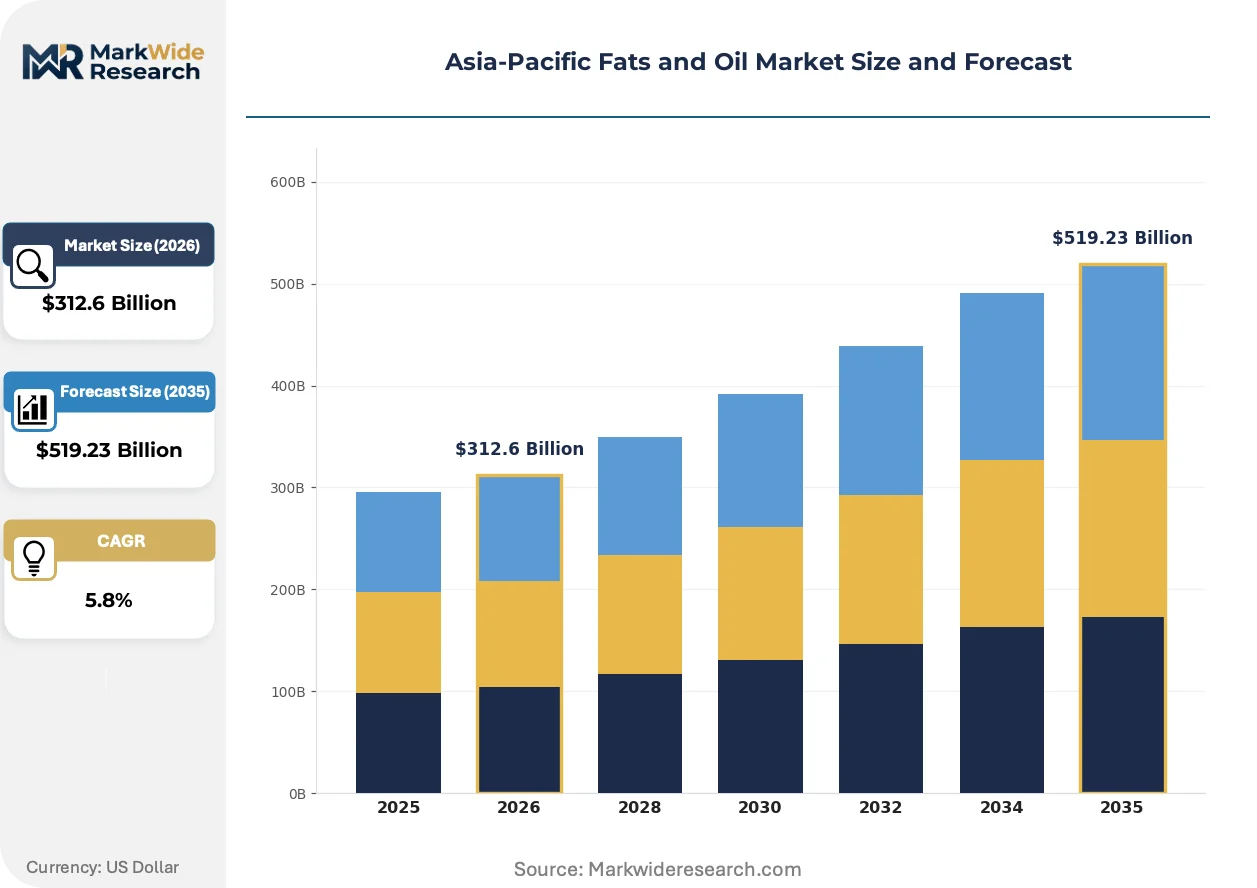
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $519.23 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetable Oils, Animal Fats, Margarine, Shortening End Use Industry: Food Processing, Biofuels, Cosmetics, Pharmaceuticals Distribution Channel: Wholesale, Retail, Online, Direct Sales Application: Cooking, Industrial Use, Baking, Dressings |
| Companies Covered | Wilmar International, Cargill, Archer Daniels Midland Company, Bunge Limited, Sime Darby Plantation, Fuji Oil, IOI Corporation Berhad, Olam International, Golden Agri-Resources, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Fats and Oil Market Strategic Shifts
Processing technology and sustainability verification are converging to redefine value capture in Asia-Pacific fats and oils, with digital traceability and enzymatic modification displacing conventional chemical routes.
Enzymatic interesterification is migrating from niche European applications to mainstream Southeast Asian refineries. Malaysian and Indonesian producers are retrofitting stirred-tank reactors with immobilized lipase systems to produce trans-free bakery fats. This migration from chemical to biocatalytic processing is compressing hydrogenation capacity valuations and elevating enzyme supplier influence in equipment specification decisions.
Malaysia's MSPO and Indonesia's ISPO sustainability frameworks are tightening deforestation liability across supply chains. Processors must now document fresh fruit bunch origin down to plantation block level to access Japanese and South Korean import permits. The confectionery segment faces the steepest compliance burden, as cocoa butter equivalent formulations require segregated handling certificates that add documentation costs.
Food manufacturers are consolidating supplier relationships around integrated plantation-refiner groups capable of certifying full chain of custody. Direct contracting with Wilmar, Sime Darby, and Musim Mas is displacing spot market purchases for packaged goods producers in India and Southeast Asia. This concentration is most visible in Indonesia, where instant noodle and margarine producers are locking in three-year supply agreements to secure BPDPKS subsidy eligibility and price stability.
Asia-Pacific Fats and Oil Market Segmentation
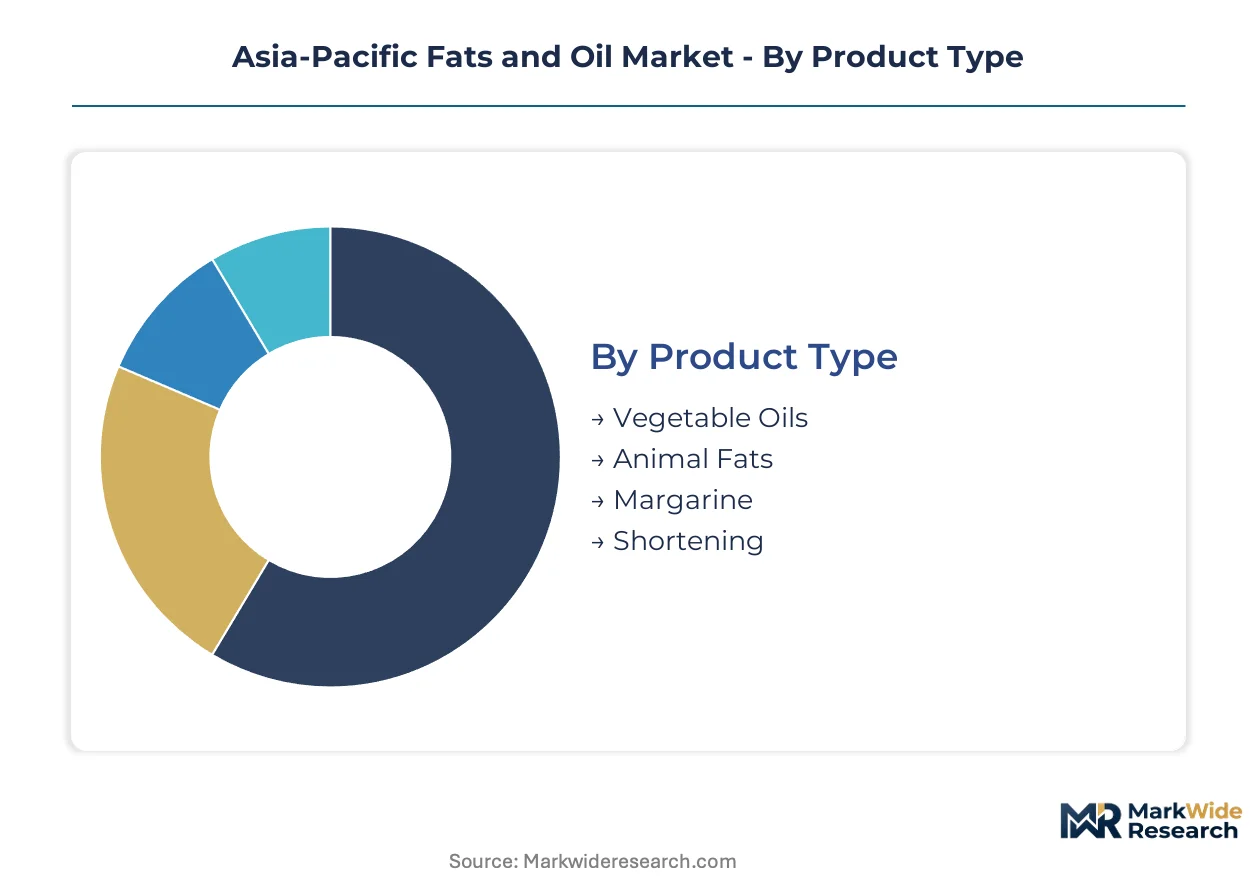
Segmentation in Asia-Pacific fats and oils reveals how divergent end-use requirements fragment procurement strategies across food manufacturing, energy policy, and personal care formulations. Each dimension exposes distinct margin pools and compliance burdens that reshape supplier relationships.
Product Type:
Mature commodity categories dominate volume flows while specialty formulations capture expanding premium tiers.
- Vegetable Oils:Triglyceride-based lipids from oilseed crushing and fruit pulp extraction span iodine values of 45-130 for tailored functional performance. Palm oil anchors Indonesian and Malaysian export flows under BPDPKS subsidy frameworks, while soy oil leverages protein-meal coproduct economics across Indian crush facilities. Vegetable Oils retain volume leadership; Margarine holds the steepest expansion curve amid trans-fat reformulation mandates.
- Animal Fats:Rendered tallow and lard supply bakery and confectionery applications requiring specific slip melting points between 35°C and 55°C. Australian and New Zealand processors dominate tallow exports to Southeast Asian soap manufacturers seeking saponification consistency.
- Margarine:Water-in-fat emulsions face structural pressure from FSSAI trans-fat limits below 2%, pushing Indian manufacturers toward interesterified blends and high-oleic sunflower bases.
- Shortening:Plasticized fat systems for laminated dough and frying applications remain entrenched in traditional South Asian bakeries despite enzymatic interesterification gaps.
Vegetable Oils retain volume leadership; Margarine holds the steepest expansion curve amid trans-fat reformulation mandates.
End Use Industry:
Application-driven specifications split procurement between commodity scale and certified traceability requirements.
- Food Processing:Packaged goods manufacturers across Indonesia and India consolidate supplier relationships around integrated plantation-refiner groups capable of certifying full chain of custody. Instant noodle and margarine producers are locking in three-year supply agreements to secure BPDPKS subsidy eligibility.
- Biofuels:Indonesia's B35 and Malaysia's B20 blending mandates are absorbing rising palm oil volumes, stimulating crushing capacity expansion and backward integration into plantation assets. Biofuels represents the fastest-growing end-use channel as policy enforcement tightens.
- Cosmetics:Oleochemical derivatives for surfactant and emollient production require segregated handling certificates that add documentation costs, particularly for Malaysian MSPO-compliant supply chains.
- Pharmaceuticals:Refined glycerin and fatty acid excipients face the steepest compliance burden, with Japanese and South Korean import permits demanding plantation block-level traceability.
Food Processing commands the largest procurement volumes; Biofuels shows the steepest expansion trajectory as blending mandates escalate.
Distribution Channel:
Channel selection correlates directly with buyer scale and certification complexity rather than traditional cost-service tradeoffs.
- Wholesale:Bulk olein and stearin flows move through integrated processor networks serving refineries and food manufacturers with direct vessel-to-facility logistics.
- Retail:Branded bottled oils compete on price transparency in Indian and Indonesian urban markets, with private label penetration rising in Australian supermarket chains.
- Online:Specialty fats and organic-certified oils reach small-scale foodservice operators and artisanal bakeries through platform aggregators in Vietnam and Thailand.
- Direct Sales:Confectionery fat formulations and cocoa butter equivalents require dedicated account management for Japanese chocolate processors seeking clean-label documentation.
Wholesale channels retain volume leadership; Direct Sales channels gain share fastest as traceability requirements intensify.
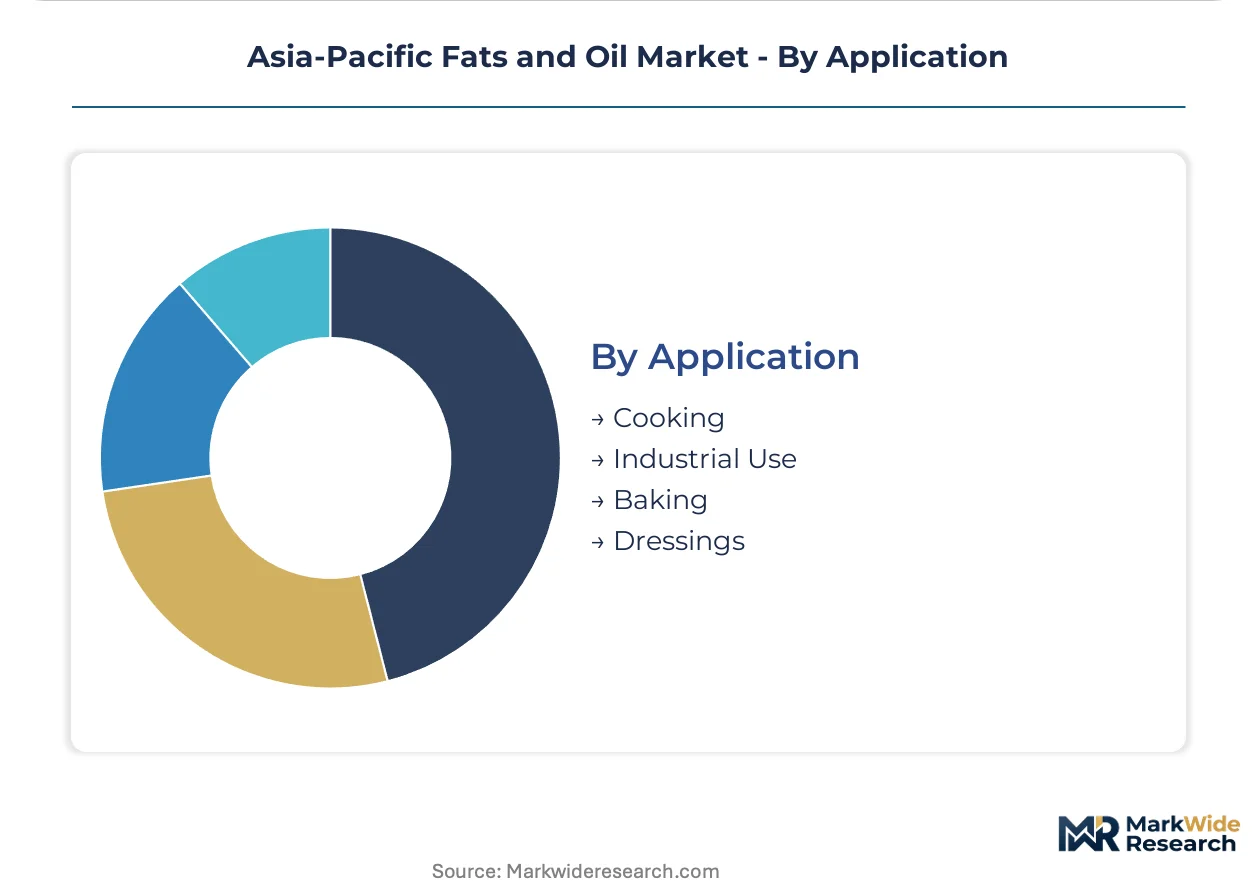
Application:
Functional performance specifications diverge sharply between thermal stability demands and cold-process compatibility.
- Cooking:High-oleic sunflower and canola oils penetrate premium frying segments in Australia and South Korea as alternatives to palm olein, driven by clean-label positioning.
- Industrial Use:Biodiesel feedstock procurement concentrates around Indonesian BPDPKS-eligible supply chains, with refiners prioritizing fatty acid methyl ester yield optimization.
- Baking:Trans-free bakery fat production is migrating from chemical hydrogenation to enzymatic interesterification across Malaysian and Indonesian stirred-tank retrofits.
- Dressings:Cold-process emulsions favor high-oleic oils with extended oxidative stability, particularly in Japanese and South Korean mayonnaise manufacturing.
Cooking applications retain volume leadership; Industrial Use climbs the fastest as biodiesel policy enforcement tightens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Asia-Pacific diverge sharply between fuel-blending economies and food-processing centers, with Indonesia and Malaysia channeling palm oil toward biodiesel while India and Japan prioritize edible oil reformulation.
Indonesia
BPDPKS biodiesel subsidies and B35 blending mandates absorb over one-third of domestic palm oil output, tightening edible oil availability for regional food manufacturers. The government's mandatory domestic market obligation requires exporters to supply local refineries before international sales. Java's refining corridor around Surabaya and Jakarta hosts integrated plantation-to-biodiesel complexes that dominate regional oleochemical flows.
India
FSSAI trans-fat regulations below 2% are accelerating interesterified blend adoption across packaged food and bakery segments. The regulator's phased enforcement timeline pushes mid-tier refiners toward enzymatic modification capacity. Maharashtra and Gujarat house India's largest oilseed crushing clusters, where soy-protein meal economics sustain crush margins despite volatile palm oil import parity.
China
Soybean import dependence exceeding 85% shapes procurement strategies around South American supply contracts and strategic reserve accumulation. SAMR food safety standards on oil oxidation markers constrain recycled frying oil reuse in foodservice. Shandong and Jiangsu provinces concentrate the country's crushing and refining infrastructure, with Qingdao port handling the majority of soybean import discharge.
Japan
Confectionery fat demand from chocolate manufacturers drives premium cocoa butter equivalent imports, with clean-label documentation requirements exceeding regional norms. METI industrial standards on fat crystallization behavior constrain supplier qualification to specialty refiners. Osaka and Nagoya anchor the Kansai and Chubu industrial zones where Fuji Oil and domestic compounders formulate tailored bakery and chocolate coatings.
Vietnam
Rising processed food consumption and underdeveloped oilseed crushing infrastructure create procurement dependence on Malaysian and Indonesian refined olein imports. The government's agricultural modernization programs target domestic soybean and peanut cultivation expansion. Ho Chi Minh City's food manufacturing belt drives regional demand for bulk frying oils and shortening, with Da Nang emerging as a secondary distribution node for central region processors.
Asia-Pacific Fats and Oil Market Competitive Environment
Capability concentration sits with integrated plantation-refiner groups; scale advantage sits with diversified agribusiness conglomerates with multi-oilseed processing networks. The market structures around three tiers: captive plantation operators controlling upstream supply, merchant refiners serving spot and contract markets, and specialty compounders targeting confectionery and bakery formulations. Dominant competitive moves include backward integration into plantation assets and enzymatic interesterification technology licensing for trans-fat compliance.
Within the integrated plantation-refiner tier, Wilmar International and Sime Darby Plantation exemplify upstream-downstream control strategies that secure BPDPKS subsidy eligibility and supply chain traceability. Cargill occupies a position among diversified agribusiness operators with multi-origin oilseed sourcing networks spanning South American soy and Southeast Asian palm. Fuji Oil represents the specialty compounder archetype, with formulation expertise directed toward Japanese and regional confectionery fat specifications. These three anchors illustrate how competitive positioning fragments across upstream resource control, global merchant scale, and application-specific technical service.
| Leading Market Players |
|---|
| Wilmar International |
| Cargill |
| Archer Daniels Midland Company |
| Bunge Limited |
| Sime Darby Plantation |
| Fuji Oil |
| IOI Corporation Berhad |
| Olam International |
| Golden Agri-Resources |
| Others |
Value Chain & Pricing Dynamics
Surabaya's integrated plantation-to-biodiesel corridor concentrates Indonesian palm oil processing capacity, translating upstream BPDPKS subsidy capture into downstream pricing leverage over Indian and Chinese buyers competing for constrained edible oil flows.
Pricing Analysis
Long-term offtake contracts dominate procurement between integrated plantation-refiner groups and packaged food manufacturers, with three-year supply agreements locking in BPDPKS subsidy eligibility and insulating buyers from Malaysian ringgit volatility. Three-tier pricing structure across MSPO-certified premium, standard-grade bulk olein, and economy-tier biodiesel feedstock reflects certification grade and volume scale differentiation. Cost compression in standard-grade edible oils is intensifying because Indonesian domestic market obligations redirect supply toward fuel blending. Small-scale foodservice operators show highest price sensitivity, while Japanese confectionery manufacturers absorb premium tiers for cocoa butter equivalent formulations with segregated handling documentation.
Supply Chain Analysis
Fresh fruit bunch supply draws from Indonesian and Malaysian plantation belts, with crushing capacity expansion feeding both biodiesel methyl ester production and fractionated olein-stearin output. Malaysian ringgit fluctuations and El Niño weather patterns introduce commodity price volatility that strains refinery hedging effectiveness. Distribution runs through integrated processor networks serving direct vessel-to-facility logistics for bulk flows, supplemented by platform aggregators reaching artisanal bakeries in Vietnam and Thailand for specialty fats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific fats and oils are approaching a platform-economics inflection as digital traceability systems and enzymatic modification technology create interoperability standards that favor integrated plantation-refiner groups over merchant spot-market players.
For Market Incumbents: Harden BPDPKS subsidy eligibility through backward integration into plantation block-level certification, while accelerating enzymatic interesterification licensing to defend against mid-tier Indian refiners acquiring trans-fat reformulation capability. Lock in three-year direct sales contracts with instant noodle and margarine producers to preempt spot market displacement by Wilmar and Sime Darby.
For New Entrants and Emerging Players: Vietnam's underdeveloped oilseed crushing infrastructure offers greenfield entry for integrated soy-palm facilities serving Ho Chi Minh City's food manufacturing belt. Target premium high-oleic sunflower and canola segments in Australian and South Korean frying applications where clean-label positioning commands margin premiums unavailable in commodity palm olein.
For Investors and Strategic Acquirers: Long-term, this sits as a sustainability-certification play because MSPO and ISPO compliance is becoming a hard constraint for EU and Japanese import permits rather than a voluntary premium. Monitor BPDPKS blending mandate revisions as the inflection signal for edible oil supply tightening and refinery margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Assets | BPDPKS subsidy eligibility requires documented fresh fruit bunch origin down to plantation block level. |
| Enzymatic Interesterification Licensing | Immobilized lipase systems enable trans-free bakery fat production for FSSAI-compliant Indian formulations. |
| MSPO Certification Investment | Malaysian sustainability standard unlocks preferential supply contracts with EU and Japanese buyers. |
| Direct Sales Channel Expansion | Confectionery fat formulations require dedicated account management for Japanese chocolate processors. |
| Joint Venture in Vietnamese Crushing | Underdeveloped oilseed infrastructure creates procurement dependence on Malaysian and Indonesian imports. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across this study, combining structured interviews with refinery operations managers, plantation sustainability officers, FSSAI regulatory compliance leads, and Indian packaged food procurement directors with secondary validation from BPDPKS subsidy disclosures, MSPO audit protocols, Malaysian Palm Oil Board trade statistics, and FSSAI trans-fat enforcement timelines. Bottom-up volume modeling triangulated against top-down value projections anchored the analysis.
Calibration against historical blending mandate implementation rates and enzymatic capacity installation curves shaped the projection framework across product type, end-use industry, distribution channel, and application segments. CAGRs derived from segmented growth rate differentials incorporated biodiesel policy enforcement intensity, reformulation service demand elasticity, and specialty fat premium capture dynamics.
The forecast holds incumbent behavior within observed patterns; aggressive moves by integrated plantation groups or sudden BPDPKS subsidy suspension would shift outcomes beyond modeled ranges. Cross-checking against Malaysian Palm Oil Board production statistics and Indian solvent extractors association import data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Tapioca Market
Ingredients
Organic Edible Oil Market
Ingredients
Mexico Avocado Oil Market
Ingredients
Red Orange Anthocyanin Extract Ingredients Market
Ingredients
Cocoa Derivatives Market
Ingredients
Diastatic Malt Market
Ingredients
Global Egg Yolk Oil Market
Ingredients
Freeze-Dried Pea Isolates Market
Ingredients
Asia-Pacific Gelatin Market
Ingredients
Caramel Malt Market
Ingredients
Tuberose Extract Market
Ingredients
Africa Fats and Oil Market
Ingredients
Mallow Glycolic Extract Market
Ingredients
Protein Extracts from Single Cell Protein and Other Conventional Sources Market
Ingredients
Yeast and Yeast Extract Market
Ingredients
Starch Market