
 Salt Content Reduction Ingredients Market | 2026-2036
Salt Content Reduction Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
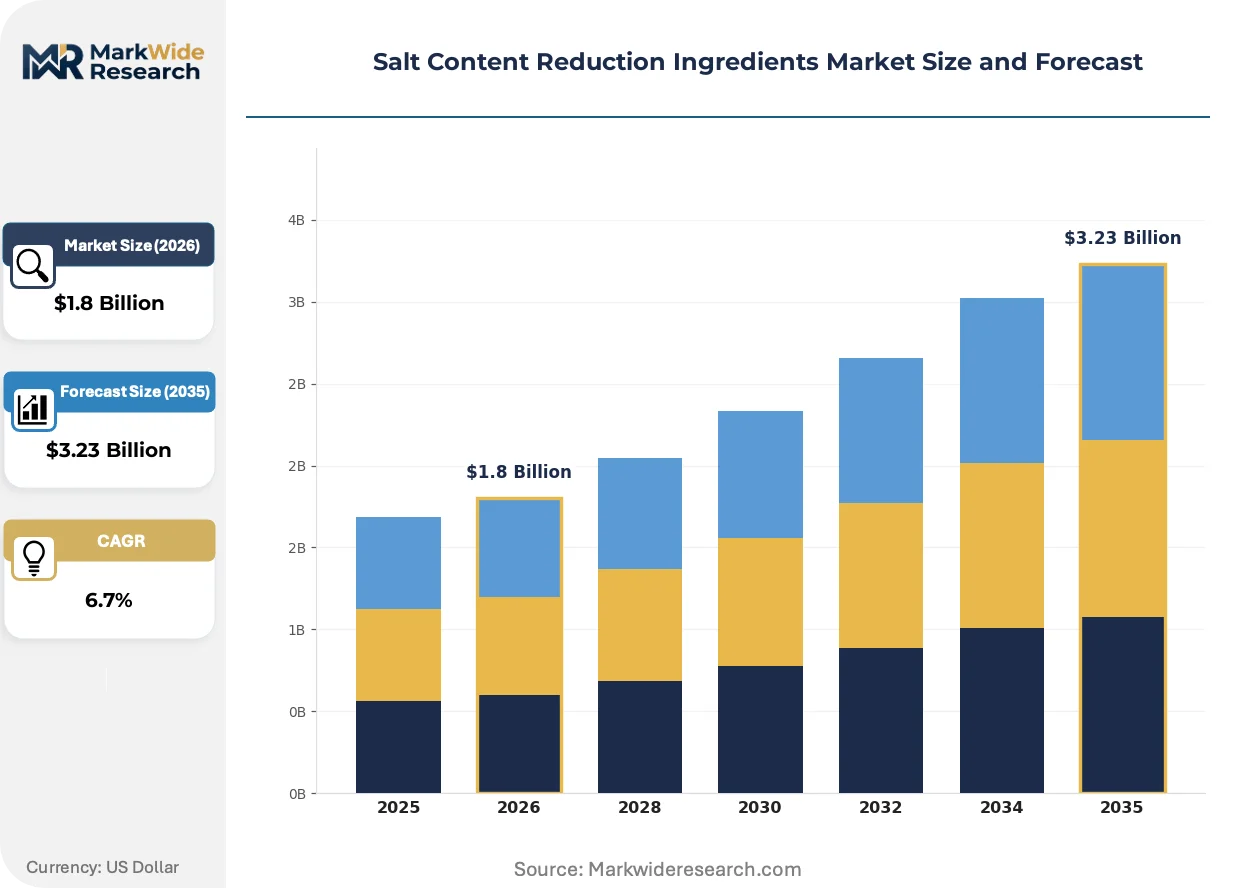
Salt Content Reduction Ingredients Market Outlook
Consolidation among multinational food manufacturers is recalibrating procurement priorities across the salt reduction supply base. Cargill Incorporated leverages its integrated agricultural supply chain to control potassium chloride sourcing costs for North American processed food clients. Kerry Group anchors its position through flavor masking technologies that offset bitterness in reduced-sodium formulations. Ajinomoto competes on umami science, extending its amino acid portfolio into clean-label applications for Asian and European food manufacturers.
Salt content reduction ingredients comprise functional compounds and systems engineered to replicate or enhance sensory salt perception while lowering sodium chloride levels, typically formulated with potassium chloride, yeast-derived peptides, glutamate compounds, and mineral blends processed through spray-drying or fermentation pathways. Their primary commercial purpose is enabling food producers to achieve regulatory sodium thresholds without sacrificing palatability or shelf stability. Flavor enhancers and yeast extracts command the deepest margin pools as brands prioritize clean-label positioning over commodity salt substitutes. Powder and liquid forms dominate industrial volumes, though granule formats are gaining traction in dry seasoning blends for snack applications.
The FDA's voluntary sodium reduction targets and WHO sodium intake guidelines are pressuring reformulation timelines across packaged food categories. EFSA's sodium benchmarks and the EU's nutrition claims framework shape product positioning and label eligibility for European manufacturers. China's NMPA and national health standards are tightening sodium disclosure requirements for processed foods sold through domestic retail channels. Stakeholders must monitor divergence between voluntary industry commitments and binding regulatory deadlines to calibrate R&D spending and regional market entry sequencing.
Market Dynamics
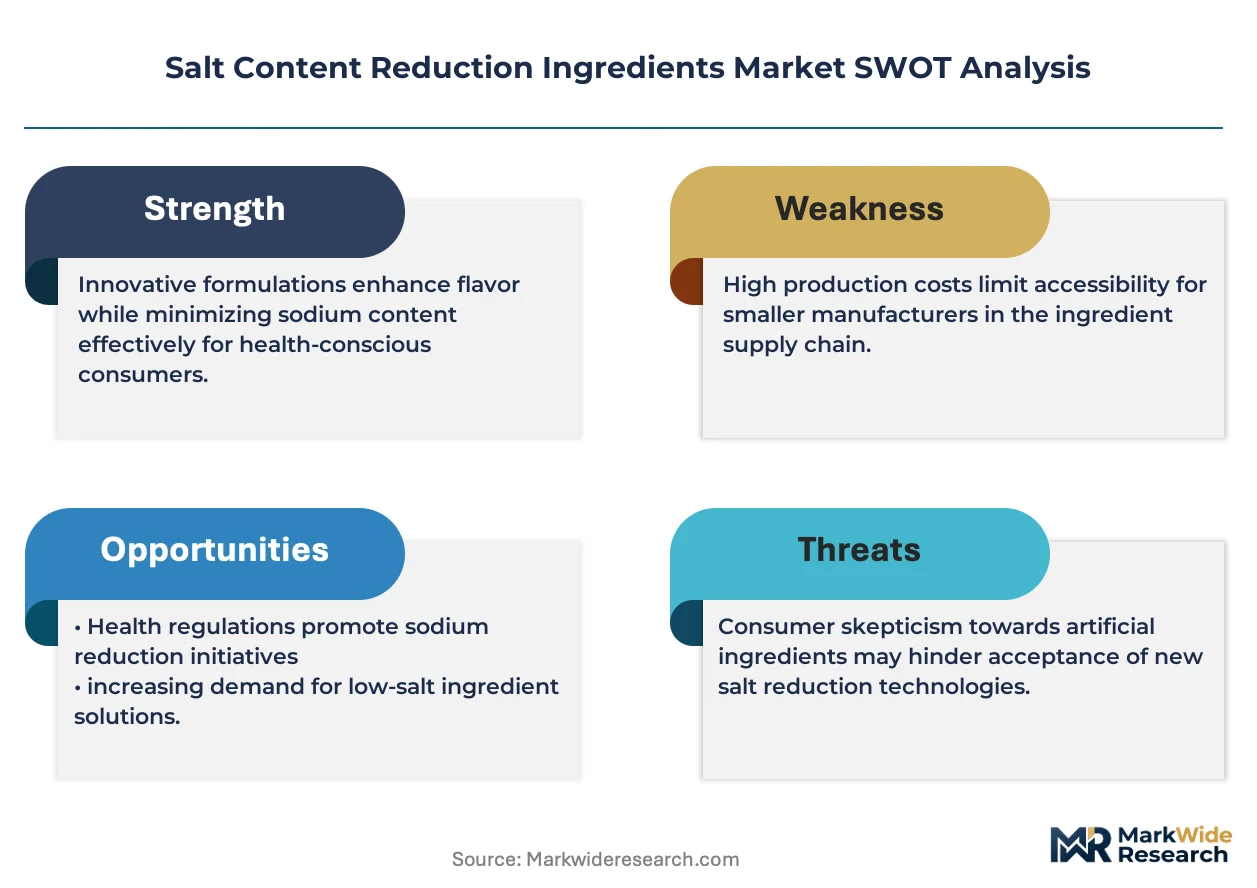
Regulatory sodium ceilings are compressing reformulation timelines across processed food categories, forcing ingredient suppliers to deliver functional salt alternatives that maintain sensory performance without sacrificing clean-label positioning or manufacturing throughput.
Growth Catalysts
- FDA voluntary sodium reduction targets:Packaged food manufacturers in the United States face phased sodium benchmarks for bread, cheese, and processed meats, accelerating procurement of potassium chloride blends and yeast extract systems.
- Clean-label yeast extracts:Fermentation-derived peptide technologies replicate umami depth without E-number additives, winning shelf placement in European retail channels where EFSA nutrition claims determine label eligibility.
- German BfR enforcement timelines:Federal ministries mandate sodium reduction across retail bakery and meat categories, concentrating demand for mineral salt reformulations in Central European processing facilities.
Market Restraints
- Potassium chloride supply concentration:Agricultural potassium sourcing clusters in Canadian and Russian potash mining corridors, exposing ingredient formulators to fertilizer market volatility and export restriction risk.
- Bitter aftertaste masking costs:Potassium-based salts require companion flavor technologies to suppress metallic off-notes, adding formulation complexity and raw material layering that commodity sodium chloride avoids.
- EU nutrition claims framework friction:Strict sodium threshold definitions for "reduced salt" positioning create compliance gaps where reformulated products miss label eligibility despite meaningful sodium reduction.
Strategic Opportunities
- China NMPA disclosure tightening:Processed food sodium labeling requirements for domestic retail channels create first-mover advantage for suppliers offering integrated reformulation services alongside ingredient supply.
- Snack seasoning granule formats:Dry seasoning applications for extruded snacks and savory crackers represent underpenetrated volume for salt reduction ingredients historically optimized for wet processing lines.
- WHO guideline alignment:National health agencies in Southeast Asian markets are adopting WHO sodium intake benchmarks, opening regulatory tailwinds for clean-label ingredient portfolios in emerging processed food sectors.
Industry Challenges
- Fermentation scale-up expertise:Yeast extract production requires specialized bioprocess engineering talent that food ingredient suppliers compete for against pharmaceutical and industrial biotechnology sectors.
- Dual certification timelines:Simultaneous pursuit of organic certification and sodium-reduction nutrition claims extends product launch cycles by twelve to eighteen months in European retail channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Salt Content Reduction Ingredients Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavor Enhancers, Potassium Chloride, Yeast Extracts, Amino Acids Application: Processed Foods, Snacks, Sauces, Dairy Products End User: Food Manufacturers, Restaurants, Catering Services, Retailers Form: Powder, Liquid, Granule, Tablet |
| Companies Covered | Tate & Lyle, Kerry Group, Fufeng Group, Angel Yeast, DSM Nutritional Products, Ajinomoto, Givaudan, Innophos Holdings, Cargill Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Salt Content Reduction Ingredients Market Strategic Shifts
Active reformulation across bakery, meat, and savory snack categories is reshaping ingredient R&D priorities, with sensory science and mineral processing converging to solve the palatability-shelf stability trade-off that has stalled prior sodium reduction waves.
Clean-label yeast extracts derived from torula and saccharomyces fermentation are integrating into reduced-sodium bread and processed meat formulations at accelerated rates. European packaged food manufacturers adopt these systems to replace hydrolyzed vegetable proteins and artificial flavor enhancers. The technology is integrating sensory performance with regulatory compliance, compressing the historical gap between clean-label positioning and sodium target achievement.
EFSA sodium benchmarks and the EU nutrition claims framework are tightening eligibility thresholds for reduced-sodium product positioning. Manufacturers must now document sodium reduction percentages against category-specific reference values to access favorable label claims. Bakery and chilled processed meat segments in Germany, France, and the Netherlands face the steepest compliance curves, driving co-development partnerships between food brands and ingredient suppliers.
Food manufacturers are consolidating supplier relationships around integrated reformulation service models rather than commodity ingredient transactions. Technical service teams from salt reduction ingredient suppliers now embed directly into client pilot plants to accelerate sensory optimization. This pattern concentrates procurement volume with capable full-service suppliers and marginalizes pure-play mineral salt traders lacking application expertise.
Salt Content Reduction Ingredients Market Segmentation
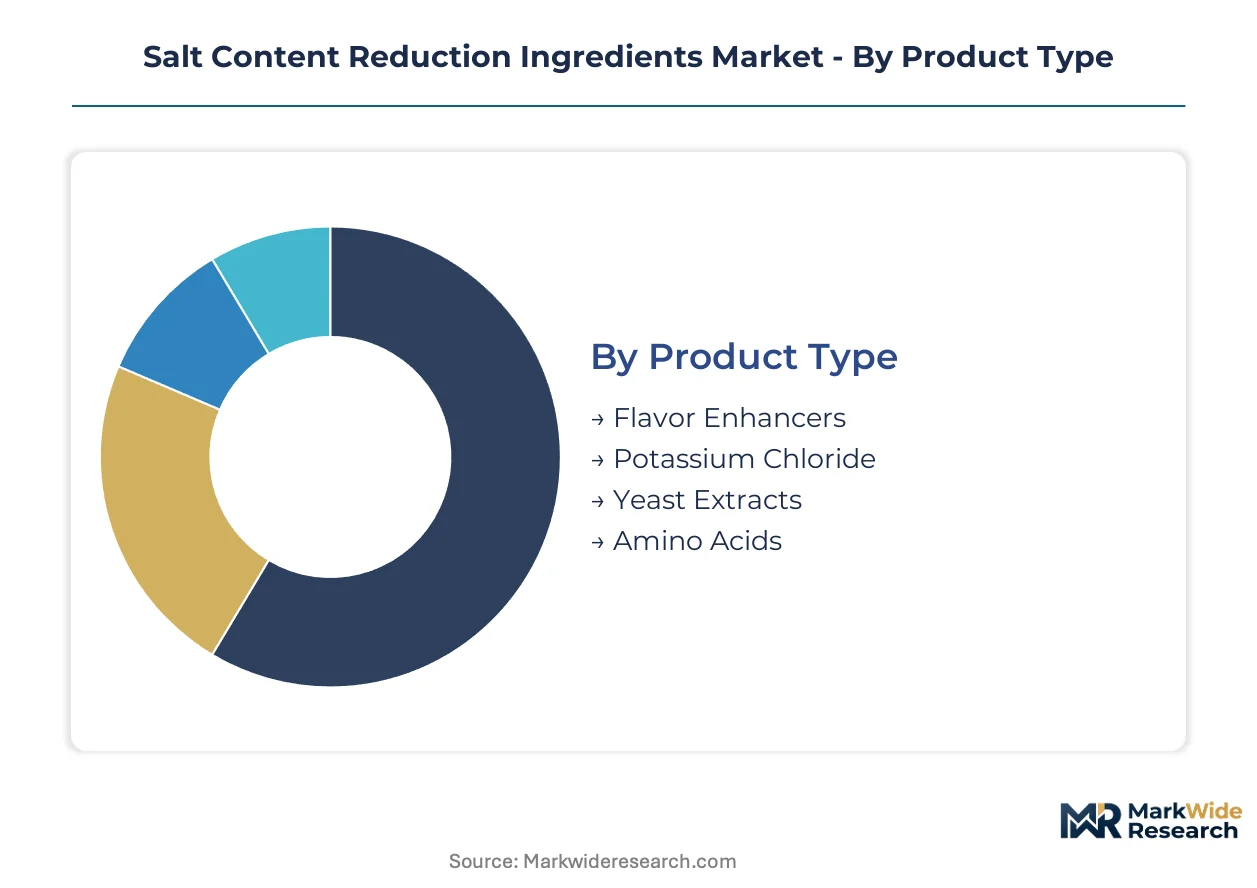
Salt reduction ingredients fragment across functional chemistries and delivery formats that dictate manufacturing compatibility and clean-label positioning. Procurement patterns diverge sharply between commodity mineral salts and fermentation-derived premium systems.
Product Type:
Yeast extracts command premium pricing while potassium chloride anchors industrial volumes across reformulation programs.
- Flavor Enhancers:Glutamate-based and nucleotide systems amplify salt perception through umami pathway activation. Snack seasoning houses in Germany and the Netherlands specify these for extruded product lines where sodium targets are most stringent.
- Potassium Chloride:The dominant mineral salt substitute processed through crystallization and anti-caking treatments. North American processed meat facilities consume the largest volumes, though bitter masking requirements add companion ingredient costs that erode its commodity advantage.
- Yeast Extracts:Fermentation-derived peptide concentrates from torula and saccharomyces strains. European bakery manufacturers favor these for EFSA-compliant clean-label positioning without E-number additives.
- Amino Acids:Purified L-glutamate and glycine derivatives for targeted sensory modulation. Asian sauce formulators integrate these into reduced-sodium soy and fish sauce variants.
Today's leader: Potassium Chloride. Tomorrow's challenger: Yeast Extracts.
Application:
Reformulation intensity varies by processing heat load and shelf stability requirements.
- Processed Foods:Chilled meats and canned goods where sodium serves microbial control functions. Replacement systems must replicate both taste and preservation performance.
- Snacks:Dry seasoning applications for extruded and baked products. Surface deposition of salt reduction ingredients demands granule format compatibility with tumble drum equipment.
- Sauces:High-moisture emulsions where potassium chloride solubility and yeast extract dispersibility determine batch consistency.
- Dairy Products:Cheese and fermented milk applications with complex protein matrices that complicate sodium displacement without texture degradation.
Processed Foods generate the steepest procurement volumes. Snacks are climbing the fastest as dry seasoning technology matures.
End User:
Customer sophistication separates specification-driven manufacturers from price-sensitive foodservice operators.
- Food Manufacturers:Multinational packaged goods companies with dedicated reformulation teams and direct supplier technical service relationships.
- Restaurants:Chain operators with centralized procurement and menu nutrition disclosure obligations driving sodium reduction commitments.
- Catering Services:Institutional feeding contracts with health-sector clients imposing sodium limits through procurement specifications.
- Retailers:Private-label developers seeking parity with branded reduced-sodium lines through co-manufacturer partnerships.
Food Manufacturers set ingredient performance standards. Retailers are expanding fastest as private-label reformulation accelerates.
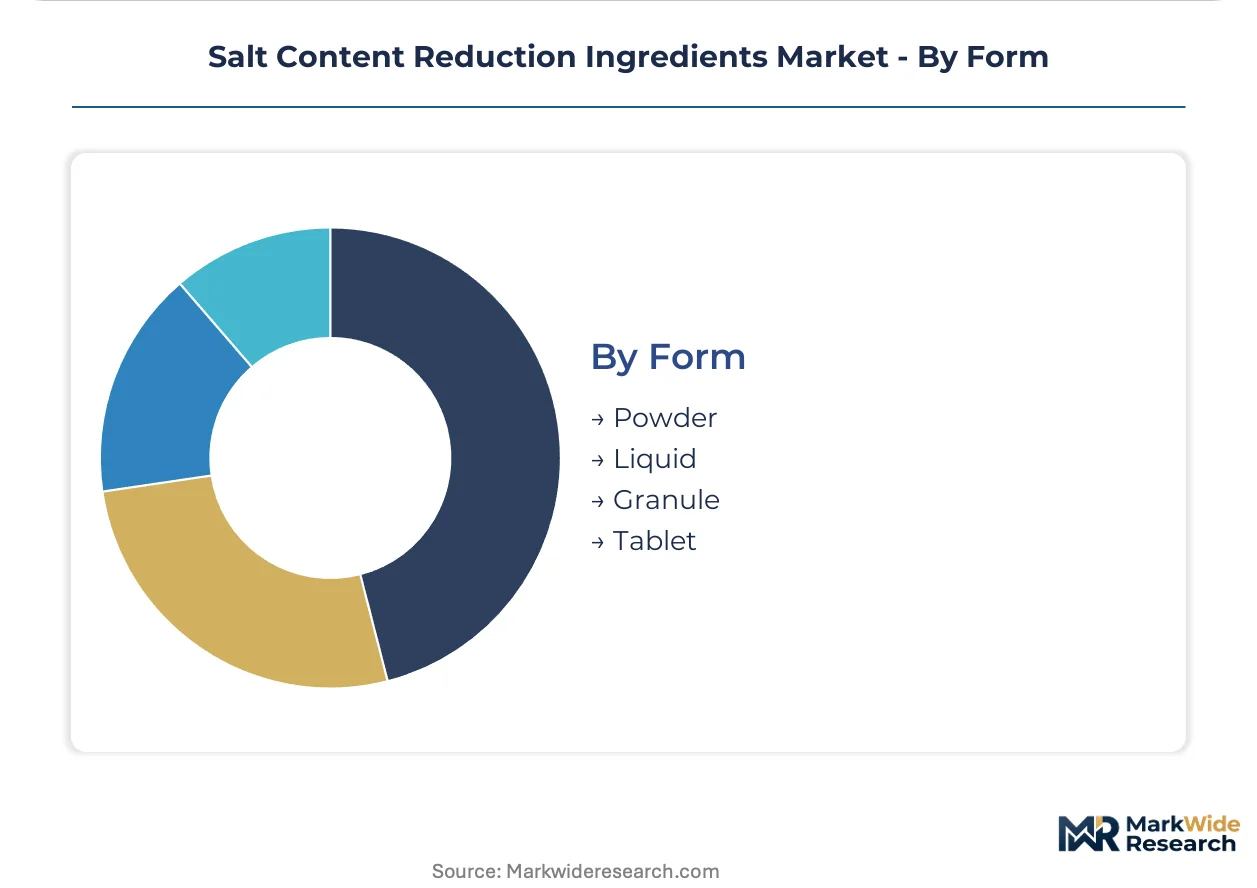
Form:
Physical state determines handling infrastructure and dissolution kinetics in target applications.
- Powder:Spray-dried mineral blends and yeast extracts for dry mix incorporation. Dominates bakery premix and seasoning base production.
- Liquid:Concentrated yeast autolysates and amino acid solutions for wet processing lines. Preferred in sauce and processed meat brine injection systems.
- Granule:Agglomerated potassium chloride with controlled particle size for dry seasoning adherence. Snack manufacturers specify these for tumble drum uniformity.
- Tablet:Compressed mineral salts for controlled dissolution in specific batch processes. Limited adoption outside specialized pharmaceutical-food crossover applications.
Powder maintains format leadership. Granule formats are expanding most quickly as snack seasoning demand intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany enforces stricter sodium reduction timelines than the United States, while China's regulatory disclosure requirements are tightening faster than Japan's voluntary industry commitments.
Germany
The BfR mandates phased sodium ceilings across retail bakery and chilled meat categories. Federal ministries coordinate with EFSA benchmarks to determine label eligibility for reduced-salt claims. Processing clusters in North Rhine-Westphalia and Bavaria drive procurement of potassium chloride blends and yeast extract systems for reformulation programs.
United States
FDA voluntary targets compress procurement timelines for bread, cheese, and processed meat manufacturers. The agency's phased sodium benchmarks determine reformulation urgency across packaged food categories. Midwestern meat processing facilities and California-based bakery operations anchor North American demand for mineral salt substitutes.
China
NMPA disclosure requirements for processed food sodium labeling intensify procurement from domestic retail channel suppliers. National health standards align with WHO intake guidelines to shape manufacturer reformulation obligations. Yangtze River Delta food processing corridors concentrate demand for integrated reformulation services alongside ingredient supply.
Netherlands
EFSA nutrition claims framework enforcement creates compliance pressure for snack seasoning and sauce manufacturers. Sodium threshold definitions for reduced-salt positioning determine product label eligibility in European retail channels. Randstad region flavor houses and seasoning compounders drive technical service partnerships with ingredient suppliers.
Japan
METI coordinates industry-wide sodium reduction commitments through processed food manufacturer associations. National health ministry guidelines align with WHO benchmarks to shape consumer-facing product positioning. Kanto region soy sauce and seasoning manufacturers integrate amino acid-based sensory modulation into traditional fermentation product lines.
Salt Content Reduction Ingredients Market Competitive Environment
European specialists anchor the premium fermentation-derived tier; North American agricultural processors hold the mineral salt substitute segment. The supplier base fragments across integrated multinational food ingredient divisions and focused biotechnology specialists. Three archetypes dominate: agricultural supply chain controllers, fermentation technology platforms, and flavor science integrators. Capacity expansion in yeast extract bioprocessing and strategic partnerships for regional reformulation services represent the dominant competitive vectors.
Among the fermentation-derived specialists, Angel Yeast and Fufeng Group exemplify the scale-driven bioprocessing archetype, while Kerry Group occupies a position within the integrated flavor technology tier. Cargill Incorporated anchors the agricultural supply chain controller segment through upstream mineral sourcing integration. These three company profiles illustrate the strategic divergence between commodity mineral salt supply and premium clean-label fermentation systems.
| Leading Market Players |
|---|
| Tate & Lyle |
| Kerry Group |
| Fufeng Group |
| Angel Yeast |
| DSM Nutritional Products |
| Ajinomoto |
| Givaudan |
| Innophos Holdings |
| Cargill Incorporated |
| Others |
Value Chain & Pricing Dynamics
Procurement consolidation among multinational packaged food manufacturers is compressing ingredient supplier margins and forcing supply base restructuring toward integrated service models with embedded technical support.
Pricing Analysis
Capacity additions in Chinese yeast extract bioprocessing facilities are reshaping price floors for fermentation-derived salt reduction systems. Three-tier pricing structure across premium clean-label, standard mineral blend, and economy commodity tiers stratifies by certification grade and flavor masking complexity. Cost compression in potassium chloride sourcing is intensifying because fertilizer market volatility feeds through Canadian and Russian potash corridors. Food manufacturers with dedicated reformulation teams exhibit lowest price sensitivity; commodity-driven foodservice operators remain most price-sensitive.
Supply Chain Analysis
Clean-label certification and EFSA nutrition claims qualification gating concentrate procurement decisions on documented sodium reduction percentages against reference values. Agricultural potassium supply clusters in Canada, Russia, and Belarus; fermentation capacity centers on China, Germany, and the United States. Raw material dependencies span potash mining outputs, torula and saccharomyces feedstocks, and specialized peptide extraction equipment. Single-source vulnerability in Canadian potash rail corridors exposes formulators to logistics disruption. Distribution runs through integrated technical service partnerships rather than commodity spot transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in yeast extract portfolios where clean-label premiums offset bioprocessing scale-up costs, while potassium chloride traders face structural compression from agricultural commodity cyclicality.
For Market Incumbents: Lock in long-term offtake agreements with North American meat processing facilities before FDA sodium benchmarks tighten procurement timelines. Deepen backward integration into torula yeast fermentation capacity to defend against Chinese bioprocessing scale-ups. Prioritize certification investment in dual organic and reduced-sodium nutrition claims to extend product launch cycles into defensible competitive moats.
For New Entrants and Emerging Players: Capture snack seasoning granule applications where dry processing technology gaps create white-space opportunities outside established wet-line supplier relationships. Target Southeast Asian processed food manufacturers adopting WHO sodium guidelines with integrated reformulation service models. Lead with sensory science partnerships rather than commodity mineral salt trading to bypass incumbent agricultural supply chain control.
For Investors and Strategic Acquirers: Asymmetric upside sits with fermentation technology platforms possessing scalable bioprocess engineering talent pipelines. Five-to-ten year viability favors yeast extract specialists over commodity potassium chloride traders facing fertilizer market volatility. Acquisition target archetype: mid-cap clean-label ingredient suppliers with EFSA-compliant portfolios and embedded technical service capabilities. Signal to watch: divergence between voluntary industry sodium commitments and binding regulatory deadline acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Yeast Extract Bioprocessing Scale-Up | Captures EFSA-compliant clean-label positioning without E-number additives in European retail channels. |
| Backward Integration into Potash Sourcing | Secures agricultural potassium supply corridors against Canadian and Russian export restriction exposure. |
| Integrated Reformulation Service Partnerships | Embeds technical teams directly into client pilot plants to accelerate sensory optimization timelines. |
| Dual Certification Investment Program | Extends organic and reduced-sodium nutrition claims eligibility across European private-label portfolios. |
| Snack Seasoning Granule Format Development | Unlocks underpenetrated dry processing applications for tumble drum equipment compatibility. |
Study Parameters
Multiple input streams — executive interviews with ingredient supplier technical directors, procurement leads at multinational food manufacturers, and regulatory affairs specialists — were reconciled against secondary validation from EFSA benchmark documentation, FDA sodium target filings, and customs trade data for potassium chloride flows. Primary fieldwork captured bottom-up volume estimates from processing facility clusters in Germany, the United States, and China. Top-down triangulation applied national health agency sodium reduction timelines against category-specific reformulation intensity assumptions.
Historical shipment data cross-referenced against expert panel input on regulatory acceleration scenarios shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product chemistry tier, application heat load requirement, end-user sophistication level, and regional regulatory enforcement pattern. CAGRs derived from category-specific procurement growth rates indexed to sodium ceiling implementation schedules. Forecast inputs incorporated yeast extract bioprocessing capacity expansion pipelines and potash mining corridor export policy trajectories.
Potassium fertilizer market volatility, regulatory deadline acceleration beyond WHO guideline adoption baselines, and fermentation scale-up talent competition are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions on clean-label penetration curves and mineral salt substitution elasticities. A model refresh is warranted upon material change in binding sodium reduction enforcement timelines across major processed food categories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Canada Sodium Reduction Ingredients Market
Ingredients
Broccoli Powder Market
Ingredients
Carrot Fiber Market
Ingredients
Europe Dairy Ingredients Market
Ingredients
Clean Label Flour Market
Ingredients
Pea Peptones Market
Ingredients
Corn Oil Market
Ingredients
Europe Amino Acid Market
Ingredients
Asia-Pacific Agar Market
Ingredients
United States Wheat Protein Market
Ingredients
Food Botanicals Market
Ingredients
Vegetable Extract Market
Ingredients
Hydrolysed Vegetable Protein (HVP) Market
Ingredients
Global Fresh Compressed Yeast Market
Ingredients
Global Amaranth Oil Market
Ingredients
Marine Peptides Market