
 Grape Skin Extract Market | 2026-2036
Grape Skin Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Grape Skin Extract Market Outlook
Functional beverage brands is collapsing as a buyer archetype while pharmaceutical formulators gain procurement share in grape skin extract offtake. Polyphenolics anchors its position through captive vineyard partnerships in California's Central Valley. Nutra Green Biotechnology competes on anthocyanin standardization for European nutraceutical clients. Sabinsa Corporation extends its reach via backward integration into grape pomace sourcing networks across India and China.
Grape skin extract comprises polyphenolic compounds—primarily resveratrol, proanthocyanidins, and anthocyanins—recovered from Vitis vinifera pomace through solvent extraction or supercritical CO2 processing, yielding standardized powders with 5-95% polyphenol content for antioxidant applications. Powder formats dominate volume offtake due to blending flexibility in capsule and tablet manufacturing, while liquid extracts capture premium positioning in functional beverage formulations where solubility drives formulation economics. Dietary supplements remains the most mature application segment with established supply contracts, whereas cosmetics applications are expanding fastest as brands incorporate grape-derived polyphenols for topical antioxidant positioning.
FDA dietary supplement cGMP rules, EFSA novel food assessments, and REACH chemical registration requirements collectively elevate extraction purity standards and restrict market access for non-compliant suppliers. These frameworks push manufacturers toward solvent residue testing, organic certification, and chain-of-custody documentation. Stakeholders must monitor evolving botanical drug guidance from FDA and pending EU Green Deal bioeconomy incentives that could redirect agricultural waste streams toward higher-value extract production.
Market Dynamics
Clean-label ingredient mandates and botanical traceability requirements are compressing supplier margins while favoring vertically integrated extractors with captive vineyard networks and certified organic processing capabilities.
Growth Catalysts
- Functional beverage innovation:California and New York brands are accelerating polyphenol fortification in ready-to-drink formats, driving standardized anthocyanin procurement.
- REACH chemical registration:European purity requirements are filtering out non-compliant suppliers, concentrating volume with certified extractors holding ECHA-compliant documentation.
- Supercritical CO2 extraction:This solvent-free processing technology is expanding capacity for high-resveratrol concentrates targeting pharmaceutical formulators.
Market Restraints
- Vitis vinifera pomace supply volatility:Wine production fluctuations in California and France create raw material availability swings that destabilize extractor input costs.
- EFSA novel food assessment timelines:Extended safety evaluation periods for new polyphenol applications delay product launches and freeze working capital.
- Synthetic resveratrol competition:Fermentation-derived alternatives from Chinese biotech suppliers are capturing price-sensitive nutraceutical contracts.
Strategic Opportunities
- EU Green Deal bioeconomy incentives:Agricultural waste valorization subsidies could redirect Italian and Spanish vineyard pomace toward premium extract production.
- Cosmeceutical topical applications:European and South Korean skincare brands are expanding grape-derived antioxidant procurement for anti-aging serum formulations.
- Direct-to-practitioner distribution:Functional medicine clinicians in the United States are creating pull-through demand for clinical-grade resveratrol protocols.
Industry Challenges
- Organic certification documentation:Multi-year conversion timelines for vineyard partners and batch-level traceability systems strain operational bandwidth.
- Polyphenol standardization chemistry:Analytical method harmonization across HPLC and UV-Vis protocols creates quality assurance complexity for contract manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grape Skin Extract Market |
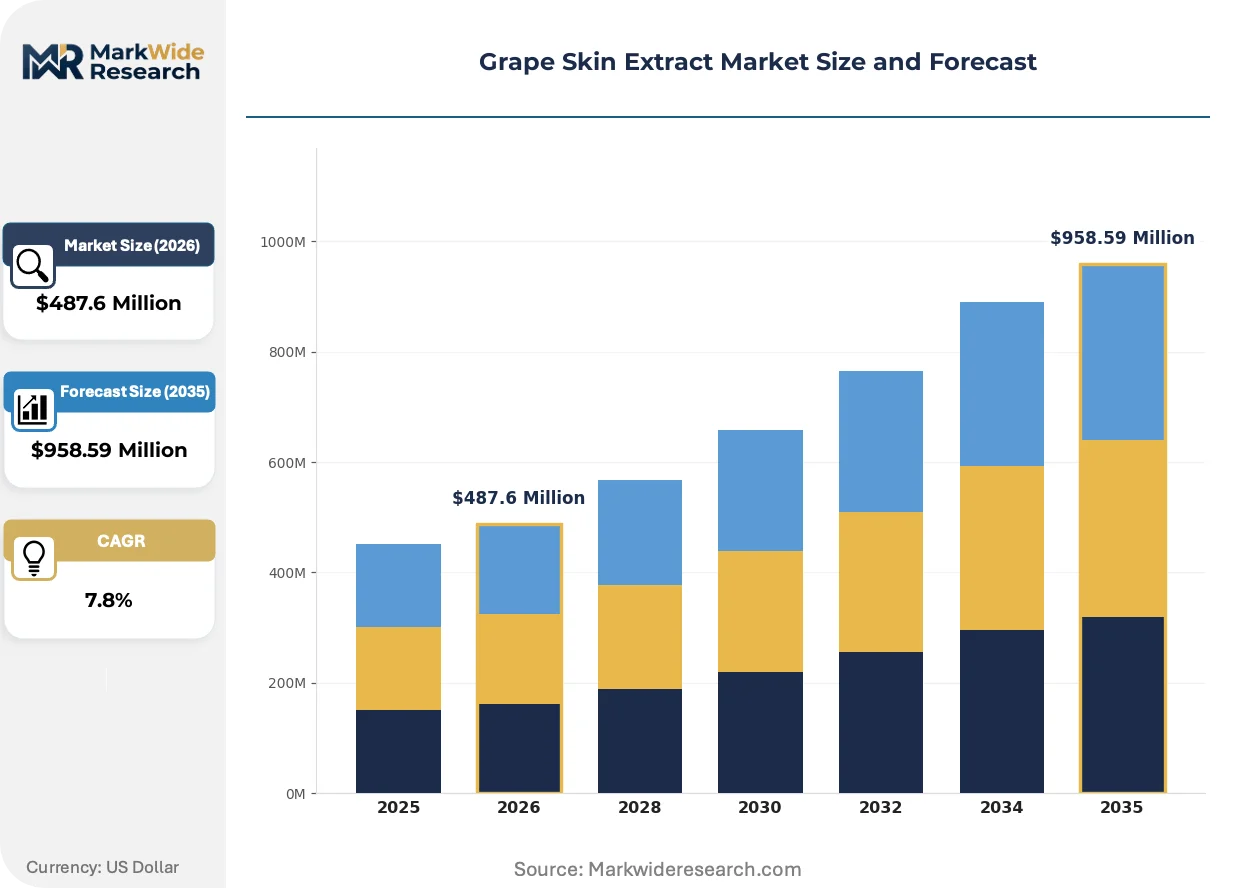
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $958.59 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Capsule, Oil Application: Cosmetics, Dietary Supplements, Food & Beverage, Pharmaceuticals End User: Manufacturers, Retail Consumers, Formulators, Healthcare Providers Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Wholesale |
| Companies Covered | Naturex, Indena, Polyphenolics, Botanic Innovations, Nutra Green Biotechnology, Xi'an Greena Biotech, Hunan Nutramax, Sabinsa Corporation, Prinova Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grape Skin Extract Market Strategic Shifts
Extraction technology convergence and regulatory data requirements are reshaping competitive capabilities, with solvent residue testing and chain-of-custody systems becoming baseline operational infrastructure rather than differentiators.
Supercritical CO2 extraction systems are decomposing the historical cost advantage of ethanol-based solvent processing. Dietary supplement manufacturers in the United States are retrofitting facilities at accelerated pace. This technology compression is enabling pharmaceutical-grade purity claims that command premium positioning in clinical nutrition channels.
EFSA novel food assessment protocols are tightening safety data requirements for botanical polyphenol concentrates. European nutraceutical brands are restructuring formulation pipelines to accommodate 18-24 month evaluation windows. Powder extract suppliers with existing approved ingredient dossiers are capturing displaced volume from newer market entrants.
Clean-label certification preferences are rotating procurement authority from procurement officers to quality assurance directors. United States functional beverage brands are mandating organic and non-GMO verification as table stakes. This validation-driven buying pattern is compressing supplier rosters to vertically integrated extractors with certified vineyard partnerships.
Grape Skin Extract Market Segmentation
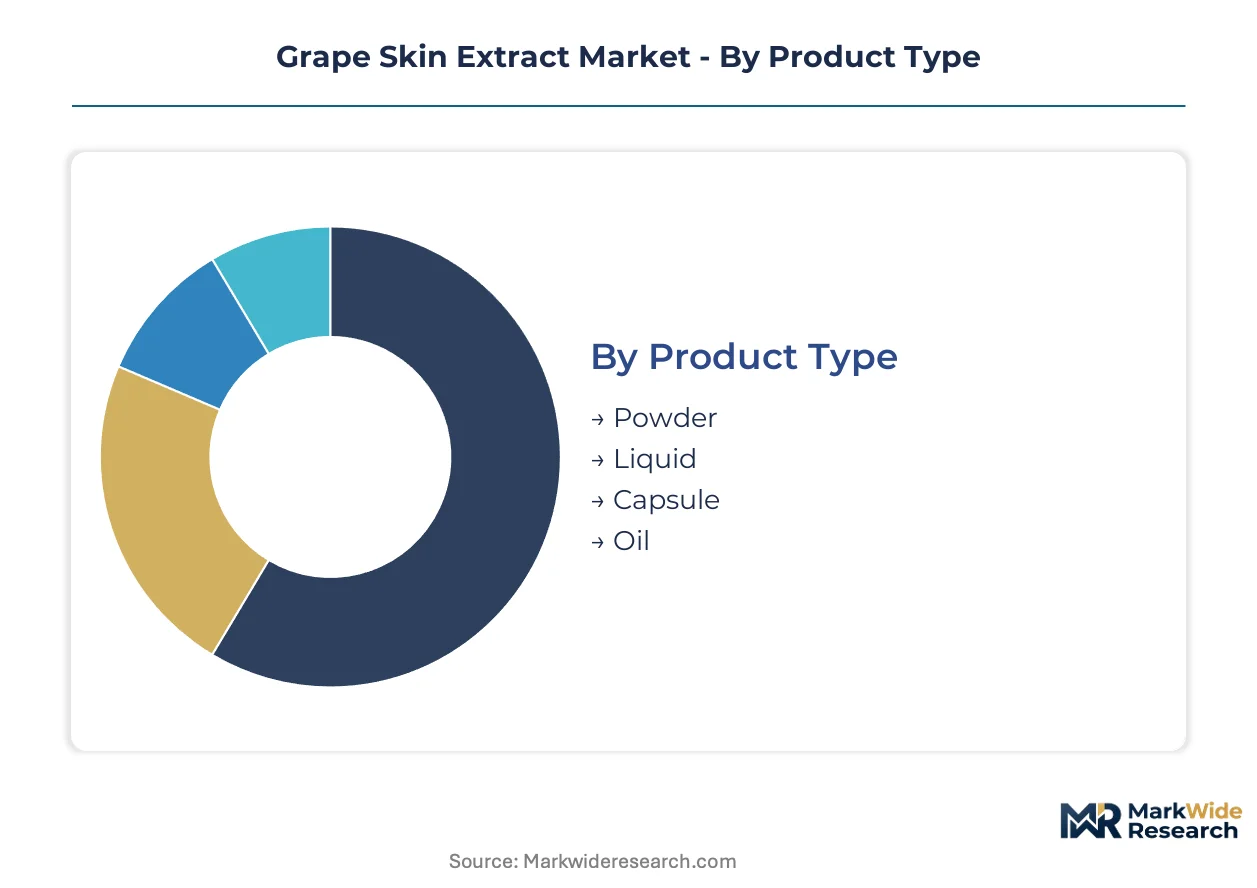
Channel configuration determines how grape skin extract flows from California vineyards to end-use applications. Powder and liquid formats diverge sharply in procurement pathways, with dietary supplement manufacturers and cosmetics formulators operating on distinct sourcing rhythms.
Product Type:
Powder extracts move through wholesale and direct sales channels to capsule manufacturers, while liquid formats concentrate in specialty stores serving beverage innovators.
- Powder:Spray-dried polyphenol concentrates with 50-95% standardization dominate contract manufacturing. Dietary supplement producers in the United States source bulk powder through direct sales agreements with California extractors. REACH-compliant documentation requirements favor suppliers with solvent residue testing capabilities.
- Liquid:Hydroalcoholic or glycerin-based extracts with enhanced solubility for functional beverage integration. New York and California beverage brands procure through specialty ingredient distributors demanding organic certification. EFSA novel food assessment timelines delay new liquid formulation launches.
- Capsule:Pre-encapsulated resveratrol and anthocyanin blends for finished supplement brands. Online retail channels serve retail consumers directly, bypassing wholesale distribution layers.
- Oil:Lipid-soluble polyphenol concentrates for topical cosmeceutical applications. South Korean and European skincare formulators source through specialty stores with batch-level traceability mandates.
By volume, powder leads. By growth pace, liquid is expanding most quickly.
Application:
Margin structures vary across applications, with cosmetics commanding premium positioning and dietary supplements operating on volume-scale economics.
- Cosmetics:Topical antioxidant serums and anti-aging formulations leverage grape-derived proanthocyanidins for oxidative stress protection. South Korean beauty brands and European dermocosmetic lines drive procurement through specialty chemical distributors.
- Dietary Supplements:Capsule and tablet formats for cardiovascular and longevity positioning constitute the most mature revenue base. United States clinical nutrition channels favor supercritical CO2-extracted resveratrol with pharmaceutical-grade purity claims.
- Food & Beverage:Polyphenol fortification in ready-to-drink products and functional snacks. California beverage innovation clusters source anthocyanin concentrates for clean-label antioxidant positioning.
- Pharmaceuticals:Investigational drug applications and clinical-grade resveratrol protocols. FDA botanical drug guidance shapes documentation requirements for suppliers targeting formulators.
Dietary supplements anchor current revenue. Cosmetics is gaining share fastest.
End User:
Procurement authority shifts based on volume scale, with manufacturers holding contract negotiation leverage and healthcare providers driving specification standards.
- Manufacturers:Capsule, tablet, and beverage producers with multi-ton annual offtake. California-based dietary supplement manufacturers negotiate long-term supply agreements with Central Valley vineyard partners.
- Retail Consumers:Direct purchasers of finished supplement products through online channels. Amazon and direct-to-consumer brands bypass traditional distribution intermediaries.
- Formulators:Cosmetics and nutraceutical product development labs with small-batch, high-specification requirements. European and South Korean skincare R&D facilities prioritize organic-certified extracts.
- Healthcare Providers:Functional medicine clinicians prescribing clinical-grade resveratrol protocols. United States integrative medicine practices create pull-through demand for standardized polyphenol dosing.
Manufacturers dominate volume procurement. Healthcare providers are expanding fastest.
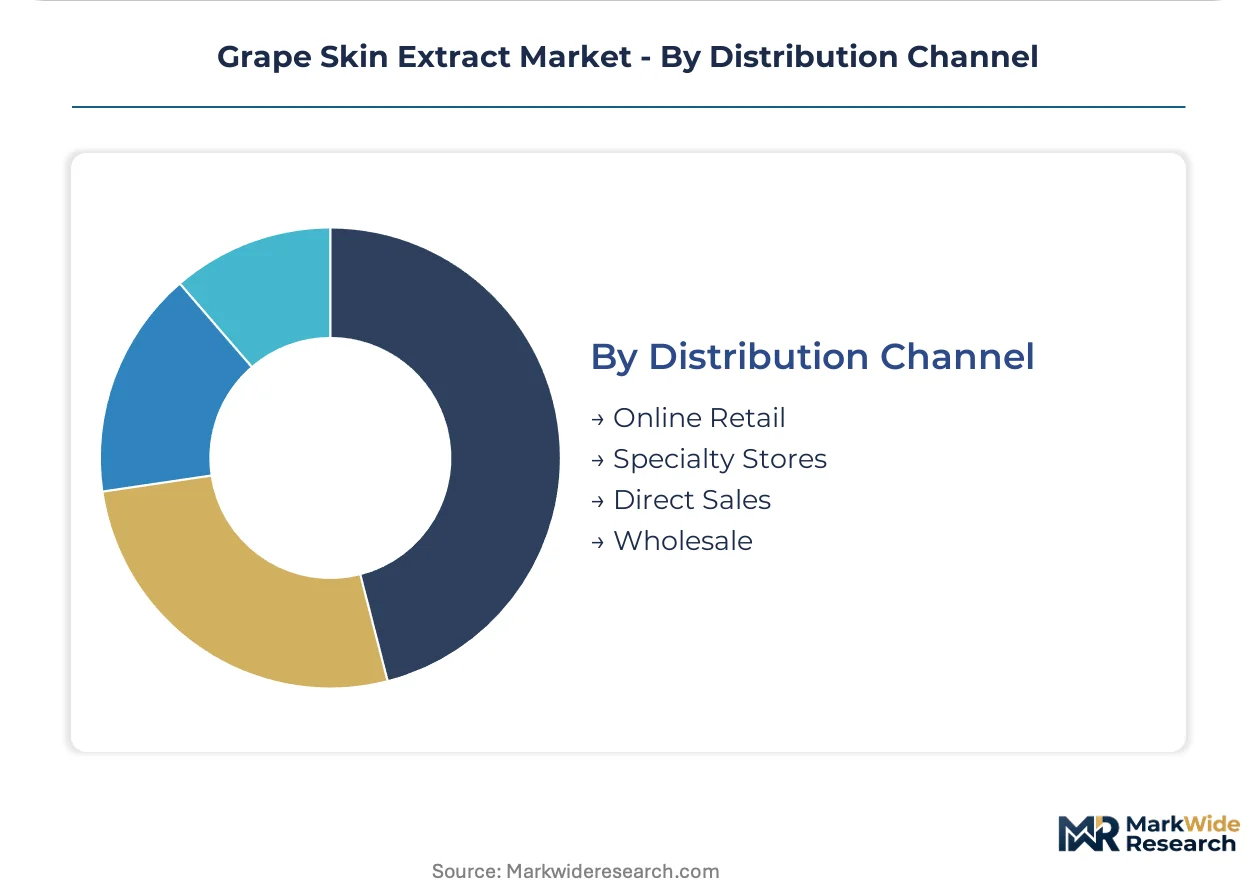
Distribution Channel:
Channel selection correlates with buyer sophistication, with direct sales serving established manufacturers and online retail capturing emerging brand formation.
- Online Retail:E-commerce platforms serving retail consumers and small formulators. Amazon and specialized nutraceutical marketplaces compress margins through price transparency.
- Specialty Stores:Ingredient distributors with technical sales support for cosmetics and beverage applications. New York and Los Angeles hubs concentrate premium extract sourcing.
- Direct Sales:Manufacturer-to-manufacturer contracts with volume commitments and quality specifications. California dietary supplement producers favor captive vineyard partnerships.
- Wholesale:Bulk distributors serving mid-tier capsule and tablet manufacturers. Price competition from Chinese synthetic resveratrol suppliers pressures natural extract positioning.
Direct sales leads by volume. Online retail is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Oakland's refrigerated cargo terminals anchor California's grape skin extract export corridor, connecting Central Valley processing facilities to Asian nutraceutical markets through direct transpacific routes.
United States
Functional beverage innovation in California and New York drives anthocyanin procurement for clean-label antioxidant positioning. FDA dietary supplement cGMP rules tighten purity documentation requirements for contract manufacturers. The Central Valley vineyard belt concentrates extraction capacity through captive pomace supply agreements with wine producers.
France
Bordeaux and Burgundy wine regions generate substantial Vitis vinifera pomace feedstock for polyphenol recovery operations. REACH chemical registration through ECHA filters non-compliant suppliers from European supply chains. The Languedoc-Roussillon corridor hosts specialized extractors serving pharmaceutical-grade resveratrol formulators.
Italy
Tuscan and Piedmont vineyard networks supply raw material for premium proanthocyanidin concentrates targeting cosmeceutical applications. EU Green Deal bioeconomy incentives redirect agricultural waste streams toward higher-value extract production. The Veneto region clusters supercritical CO2 processing capacity for solvent-free extraction.
China
Shandong and Xinjiang wine regions expand pomace collection infrastructure for domestic extract manufacturing. SAMR food additive regulations govern polyphenol concentrate approvals for beverage fortification. Zhengzhou-based biotech suppliers develop fermentation-derived resveratrol alternatives competing on price-sensitive nutraceutical contracts.
South Korea
Seoul-based skincare brands accelerate grape-derived antioxidant procurement for anti-aging serum formulations. MFDS cosmetic ingredient safety assessments shape documentation requirements for topical polyphenol applications. The Busan-Ulsan industrial corridor concentrates contract manufacturing for K-beauty export markets.
Grape Skin Extract Market Competitive Environment
Concentration sits with vertically integrated extractors holding captive vineyard partnerships and certified organic processing capabilities. The supplier base fragments between multinational botanical specialists and regional pomace processors. Three archetypes dominate: vineyard-integrated extractors with backward control over raw material, technology-focused processors deploying supercritical CO2 systems, and standardization specialists serving pharmaceutical formulators. Capacity expansion and strategic vineyard partnerships constitute the primary competitive moves, with extractors securing multi-year pomace supply agreements to stabilize input costs.
Among vineyard-integrated specialists, Polyphenolics anchors the California Central Valley position through captive supply networks. Nutra Green Biotechnology exemplifies the standardization-focused archetype serving European nutraceutical clients with anthocyanin-certified extracts. Sabinsa Corporation occupies a position spanning Indian and Chinese sourcing networks for grape pomace procurement. These three represent distinct strategic postures within a market where documentation capabilities and organic certification increasingly determine procurement authority.
| Leading Market Players |
|---|
| Naturex |
| Indena |
| Polyphenolics |
| Botanic Innovations |
| Nutra Green Biotechnology |
| Xi'an Greena Biotech |
| Hunan Nutramax |
| Sabinsa Corporation |
| Prinova Group |
| Others |
Value Chain & Pricing Dynamics
Central Valley extraction capacity utilization above 85 percent anchors price floors for California-origin grape skin extract, compressing marginal producers while rewarding vineyard-integrated operators with captive pomace supply. This scale concentration simultaneously elevates procurement thresholds for REACH-compliant documentation and organic certification, filtering non-compliant suppliers from contract negotiations with dietary supplement manufacturers.
Pricing Analysis
Volume-discount tiering structures stratify across pharmaceutical-grade, nutraceutical-grade, and cosmetic-grade purity levels, with supercritical CO2-extracted resveratrol commanding premium positioning over ethanol-based alternatives. Price differentiation hinges on organic certification status and ECHA-compliant solvent residue documentation, with synthetic resveratrol from Chinese fermentation suppliers intensifying cost compression in price-sensitive nutraceutical contracts. Dietary supplement manufacturers exhibit highest price sensitivity due to margin pressure from Amazon-driven retail transparency, while pharmaceutical formulators prioritize batch consistency over unit economics.
Supply Chain Analysis
Vitis vinifera pomace availability through the Port of Oakland underwrites California's extraction dominance, with secondary concentration in Bordeaux-Languedoc corridors and emerging Shandong processing clusters. Raw material supply draws from wine production fluctuations, seasonal harvest timing, and multi-year vineyard partnership agreements, creating input cost volatility that destabilizes non-integrated processors. Single-source vulnerability concentrates in California's drought-exposed Central Valley vineyard belt. Distribution runs through direct manufacturer contracts for powder extracts, specialty ingredient distributors for liquid formats serving beverage innovators, and online retail channels bypassing wholesale intermediaries for finished capsule products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where EFSA novel food dossiers and FDA botanical drug guidance create multi-year switching costs that protect incumbent documentation capabilities. Network effects compound through certified vineyard partnerships that lock in multi-ton annual offtake agreements.
For Market Incumbents: Compound defensive positioning by securing additional captive vineyard partnerships in California's Central Valley and Veneto regions, while accelerating supercritical CO2 capacity additions to outpace ethanol-based cost structures. Synthetic resveratrol competition from Zhengzhou biotech suppliers threatens price-sensitive nutraceutical contracts; counter by deepening backward integration into organic-certified pomace sourcing and investing in pharmaceutical-grade purity claims that command clinical nutrition channel premiums. For New Entrants and Emerging Players: Clinical-grade resveratrol protocols for functional medicine practitioners represent an underserved service layer where incumbent extractors under-serve small-batch, high-specification requirements. South Korean cosmeceutical formulators and direct-to-practitioner distribution channels in United States integrative medicine practices offer the most penetrable entry points. Pursue a go-to-market angle built on batch-level traceability systems and rapid EFSA novel food assessment navigation that displaces slower incumbent response timelines. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vineyard-integrated extractors with certified organic processing capabilities and existing ECHA-compliant documentation infrastructure. Long-term viability over a multi-year horizon rests on regulatory data asset accumulation rather than extraction technology alone. Acquisition targets should display supercritical CO2 deployment, captive raw material agreements, and approved ingredient dossiers. Monitor SAMR food additive regulation timelines in China and pending EU Green Deal bioeconomy subsidy disbursements as inflection indicators for supply-side capacity reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Vineyard Partnership Expansion | Secures multi-year pomace supply agreements with Central Valley wine producers, stabilizing input cost volatility against drought and harvest fluctuation risks. |
| Supercritical CO2 Capacity Buildout | Enables pharmaceutical-grade purity claims for clinical nutrition channels, displacing ethanol-based competitors in high-margin resveratrol concentrate segments. |
| EFSA Novel Food Dossier Investment | Accelerates approved ingredient status for European nutraceutical brands, capturing volume displaced from entrants facing 18-24 month evaluation windows. |
| Direct-to-Practitioner Distribution Channel | Creates pull-through demand from functional medicine clinicians prescribing standardized polyphenol protocols, bypassing price-compressed retail supplement channels. |
| Organic Certification Infrastructure | Satisfies clean-label mandates from California and New York beverage brands, compressing supplier rosters to vertically integrated extractors with batch-level traceability. |
Study Parameters
The analysis maps powder extract, liquid extract, capsule, and oil sub-sectors, each validated through extraction technology providers, dietary supplement procurement directors, cosmetics formulators, and vineyard operations managers. Primary interviews with California-based contract manufacturers, European nutraceutical brand R&D leads, and South Korean skincare product development teams combined with secondary validation from FDA cGMP guidance documents, EFSA novel food assessment registers, ECHA REACH compliance databases, and SAMR food additive regulation filings. Bottom-up segment sizing triangulated against top-down trade flow analysis through the Port of Oakland and European customs data.
Consistency checks validated volume and value outputs against external benchmarks including vineyard pomace recovery rates, supercritical CO2 processing capacity utilization, and regional wine production statistics. The analytical framework modeled product type, application, end user, and distribution channel dimensions across the projection horizon, with CAGRs derived from regression analysis of historical procurement patterns and forward-looking regulatory timeline assumptions. Industry-specific inputs included EFSA novel food approval velocity, REACH registration completion rates, and synthetic resveratrol price index movements.
Forecasts assume regulatory continuity in FDA dietary supplement cGMP enforcement, EFSA novel food assessment protocols, and REACH chemical registration requirements; material policy shifts would require re-modeling of market access assumptions and supplier compliance cost structures. Practitioners should keep alternative scenarios live as EU Green Deal bioeconomy incentive disbursement schedules and SAMR polyphenol concentrate approval timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Bean Ingredients Market
Ingredients
Thinned Starch Market
Ingredients
Torula Yeast Market
Ingredients
Roasted Grain Ingredients Market
Ingredients
Buckwheat Groat Flour Market
Ingredients
Europe BBQ Charcoal Market
Ingredients
Cocoa Market
Ingredients
Medium-Chain Triglyceride (MCT) Fat Market
Ingredients
North America Algae Omega-3 Ingredients Market
Ingredients
Australia Soy Protein Market
Ingredients
Cooking Coconut Milk Market
Ingredients
Fruit Concentrate Market
Ingredients
North America Sodium Reduction Ingredients Market
Ingredients
Protein Hydrolysate Market
Ingredients
All Purpose Flour Market
Ingredients
Textured Soy Flour Market