
 Soluble Fibers Market | 2026-2036
Soluble Fibers Market Size, Share, and Industry Trends Forecast 2026-2036
Soluble Fibers Market Analysis
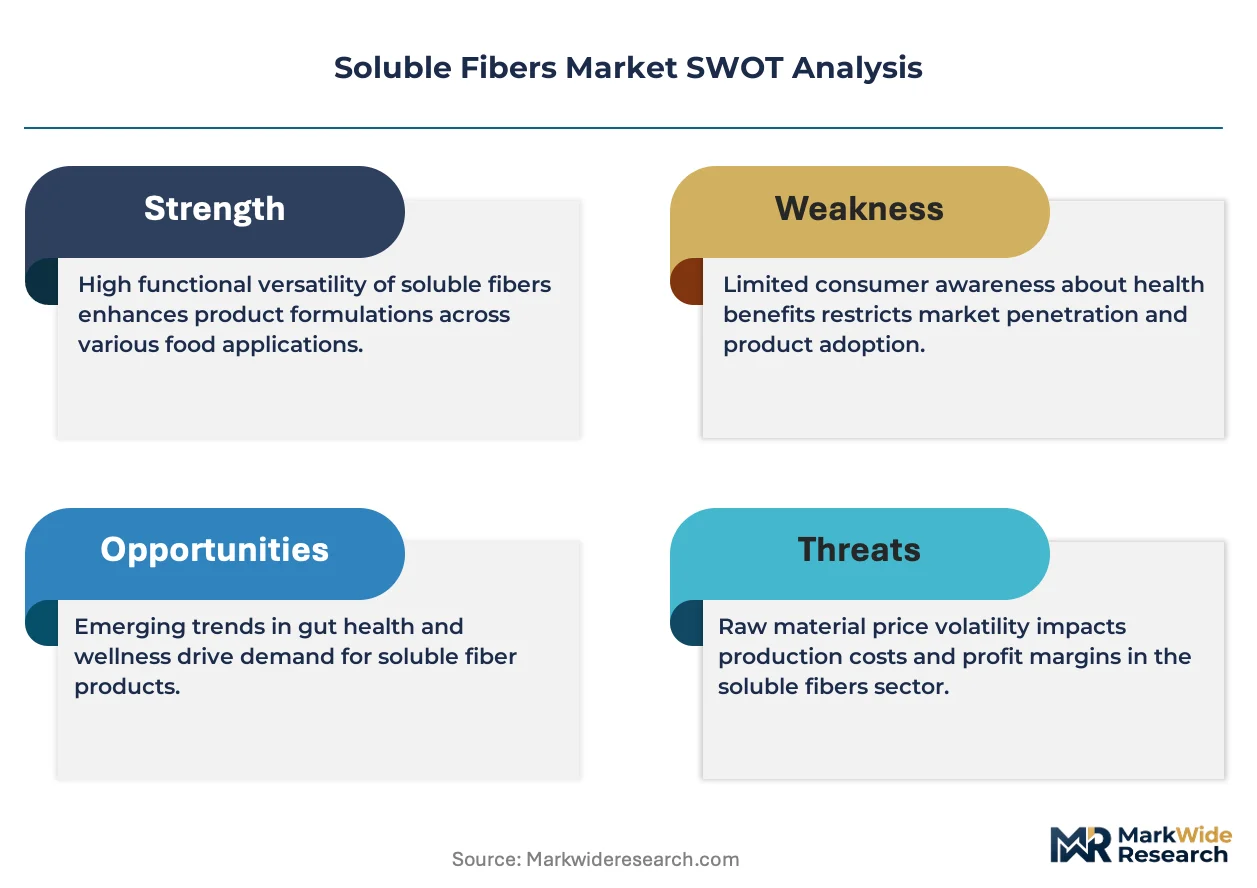
China is rewriting capacity dynamics for soluble fiber extraction as domestic processors scale chicory root and guar bean processing clusters. Cargill Inc. leverages its North American grain processing network to secure corn-derived fiber feedstocks. Tate & Lyle PLC anchors European supply through its specialized polydextrose and resistant starch operations. Roquette Frères dominates plant-based soluble fiber innovation with its pea and potato protein-fiber integration expertise.
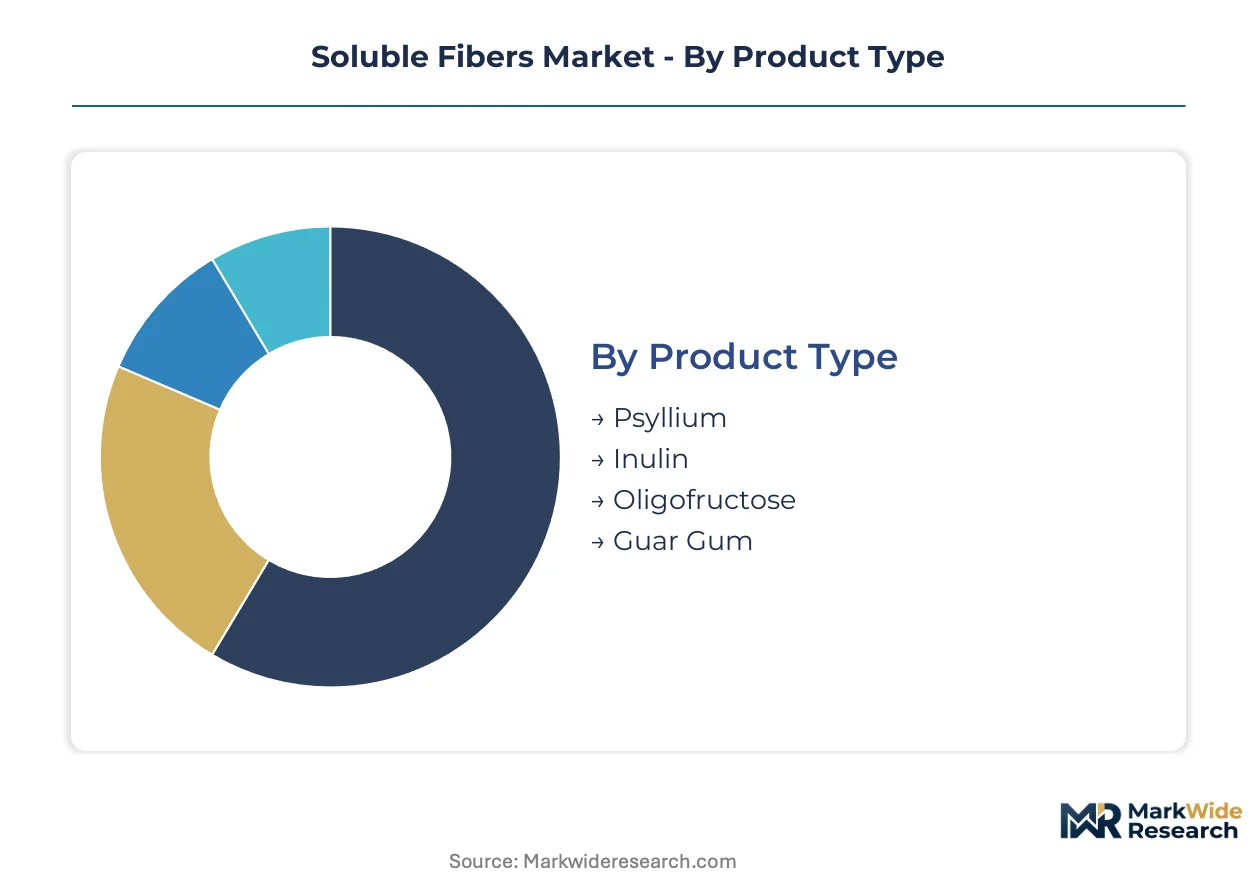
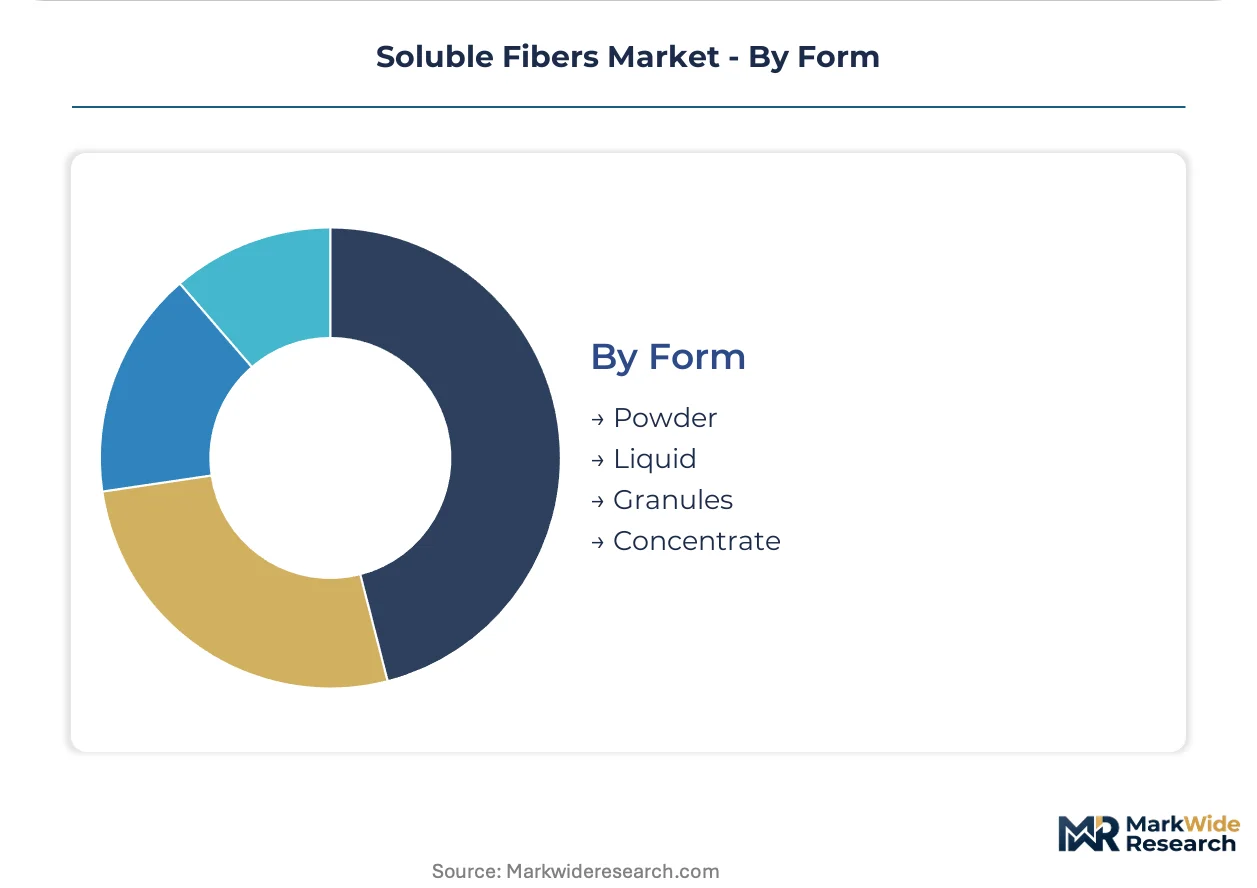
Soluble fibers are non-digestible carbohydrates that dissolve in water to form viscous gels, typically comprising beta-glucans, pectins, gums, and resistant oligosaccharides with molecular weights ranging from 500 to over 2,000,000 Daltons; manufacturers extract these through enzymatic hydrolysis, wet milling, or aqueous processing for incorporation into foods, supplements, and pharmaceutical delivery systems. Inulin from chicory roots commands the largest product type volume pool due to established extraction infrastructure and broad GRAS status, while psyllium generates premium pricing through its cholesterol-lowering health claims in regulated markets. Powder form maintains manufacturing dominance due to shelf stability and ease of blending into dry mixes, though liquid concentrates are gaining traction in beverage applications requiring clean-label solubility.
The FDA's Nutrition Facts labeling rules and the EFSA health claims framework collectively determine which soluble fiber structures qualify for approved physiological benefit statements, directly constraining product development pipelines in the United States and European Union. BIS standards in India and China's GB food safety standards add further compliance layers for exporters targeting Asia-Pacific formulation contracts. Stakeholders must monitor evolving regulator positions on novel fiber sources to preempt reformulation costs and secure preemptive approval for emerging plant-derived candidates.
Market Dynamics
The FDA's Nutrition Facts labeling revision has compressed formulation timelines as manufacturers race to qualify novel fiber sources for approved health claims before enforcement deadlines.
Growth Catalysts
- Digestive Health Positioning:Functional food brands in the United States are expanding inulin fortification to secure cholesterol-reduction claims under FDA guidelines.
- Clean-Label Beverage Demand:Liquid soluble fiber concentrates are displacing synthetic stabilizers in European juice and dairy formulations seeking EFSA-compliant natural positioning.
- Chicory Root Processing Scale-Up:Chinese processors are expanding wet-milling capacity for inulin extraction to serve domestic bakery and dairy reformulation contracts.
Market Restraints
- Input Cost Volatility:Guar bean prices fluctuate with monsoon-dependent Indian harvests, squeezing margin structures for hydrocolloid-dependent manufacturers.
- Supply Concentration Risk:European resistant starch output clusters in Benelux grain processing corridors, creating single-point vulnerability for North American formulators.
- Regulatory Friction:China's GB food safety standards impose novel fiber approval timelines that delay product launches by 18-24 months versus domestic markets.
Strategic Opportunities
- Pharmaceutical Delivery Systems:Soluble fiber gels are penetrating controlled-release tablet formulations as excipient alternatives to synthetic polymers.
- Precision Fermentation:Microbial beta-glucan production via enzymatic bioconvergence offers supply security independent of agricultural harvest cycles.
- India's PLI Scheme:Food processing incentives under India's production-linked investment framework are attracting chicory and guar fractionation joint ventures.
Industry Challenges
- Analytical Methodology Gaps:ISO-standardized fiber quantification protocols lag behind novel extraction technologies, forcing manufacturers to maintain dual testing workflows.
- Formulation Integration Complexity:High-molecular-weight pectins require reworked hydration sequences that conflict with legacy dairy processing equipment in Midwest US plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soluble Fibers Market |
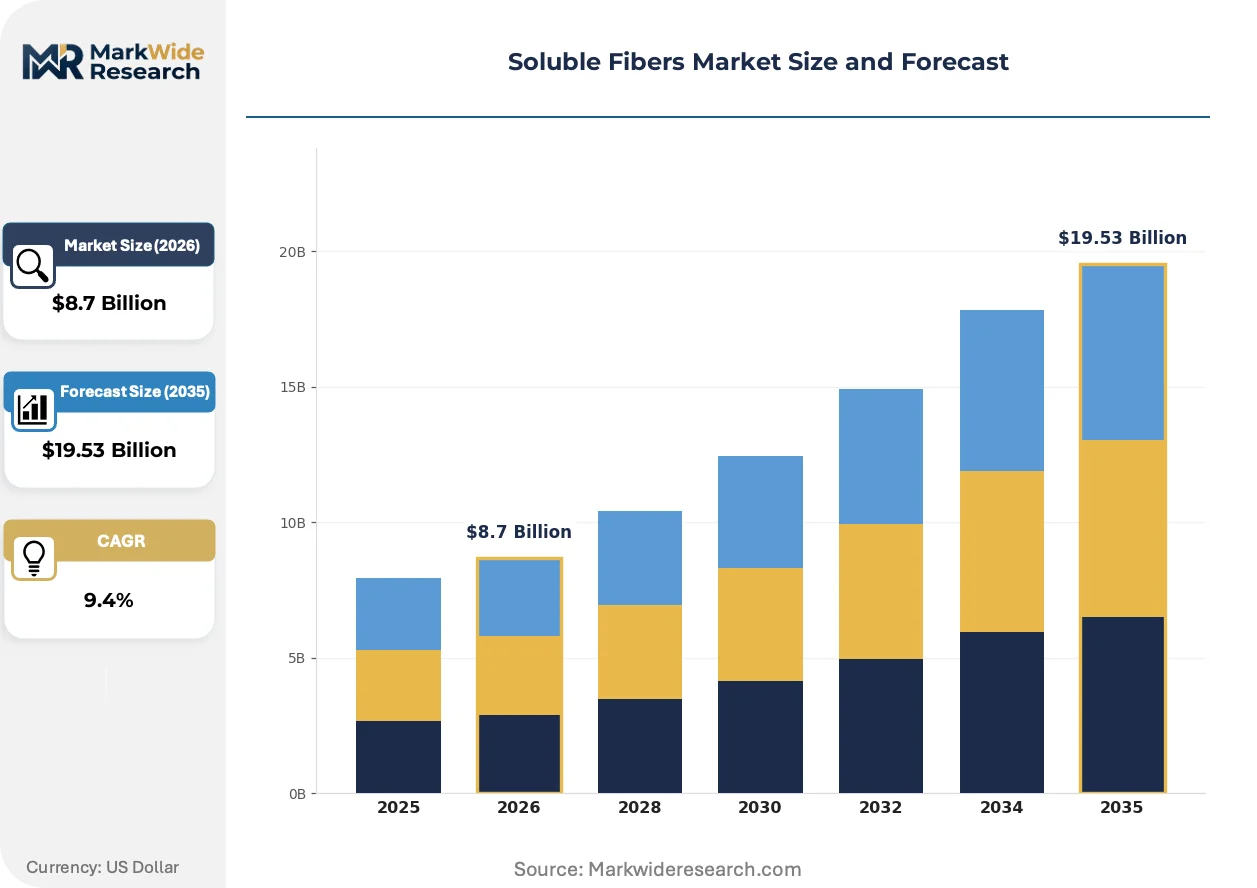
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Psyllium, Inulin, Oligofructose, Guar Gum Application: Food & Beverages, Dietary Supplements, Pharmaceuticals, Animal Feed Source: Plants, Fruits, Legumes, Vegetables Form: Powder, Liquid, Granules, Concentrate |
| Companies Covered | Archer Daniels Midland Company, Cargill Inc., Ingredion Inc., Tate & Lyle PLC, Roquette Frères, Südzucker AG, Cosucra Groupe Warcoing, BENEO GmbH, Nexira SAS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soluble Fibers Market Emerging Trajectories
Enzymatic extraction technologies and regulatory claim frameworks are compressing product development cycles while reshaping procurement relationships between ingredient suppliers and finished goods manufacturers.
Near-infrared spectroscopy coupled with machine learning algorithms is digitizing real-time fiber content verification during wet-milling operations. Major grain processors in Iowa and Illinois are deploying these systems to reduce batch-to-batch variability. The technology is digitizing quality assurance workflows, compressing laboratory turnaround from days to minutes and enabling just-in-time release decisions.
EFSA's evolving health claims framework is tightening evidentiary standards for cholesterol-reduction and glycemic-response statements. Manufacturers must now submit human intervention trials rather than extrapolated biomarker data. European bakery and cereal brands are responding by consolidating supplier relationships with processors holding pre-approved dossiers.
Direct ingredient sourcing from regional extraction facilities is shortening supply chains for North American functional food brands. Large CPG buyers are establishing preferred supplier agreements with Midwest corn fiber processors rather than relying on distributor intermediaries. This pattern is most pronounced in sports nutrition and meal-replacement segments where lot traceability requirements have intensified.
Soluble Fibers Market Segmentation
Soluble fiber procurement patterns diverge sharply across end-use specifications, with pharmaceutical-grade purity commanding fundamentally different supply chains than commodity food fortification. Understanding these segment boundaries enables suppliers to align extraction investments with margin structures and regulatory pathways.
Product Type:
Digestive health positioning and cholesterol-management claims span distinct molecular architectures with varying extraction economics and regulatory dossier requirements.
- Inulin:Long-chain fructan polymers extracted primarily from chicory roots through hot-water diffusion and spray-drying. Established GRAS status and broad formulation compatibility anchor demand in United States functional dairy and bakery applications seeking prebiotic positioning.
- Psyllium:Mucilaginous seed husk from Plantago ovata containing arabinoxylan polysaccharides that form viscous gels at low concentrations. Premium pricing persists in regulated markets where FDA-approved cholesterol-reduction claims justify higher ingredient costs in heart-health cereals and supplements.
- Oligofructose:Shorter-chain fructooligosaccharides produced through partial enzymatic hydrolysis of inulin or sucrose transfructosylation. Clean-label sweetness reduction drives incorporation into reduced-sugar European confectionery and beverage formulations.
- Guar Gum:Galactomannan polysaccharide from Cyamopsis tetragonoloba seeds requiring milling and hydration-controlled processing. Hydrocolloid functionality in gluten-free baked goods and dairy alternatives sustains procurement despite Indian monsoon-dependent supply volatility.
Established volume favors inulin; emerging adoption favors psyllium.
Application:
Formulation complexity and claim substantiation burden stratify procurement relationships across end-use categories.
- Food & Beverages:Largest consumption segment spanning dairy alternatives, baked goods, and fortified beverages where texture modification and prebiotic labeling drive inclusion. United States brands reformulating for FDA-compliant fiber declarations on Nutrition Facts panels concentrate procurement.
- Pharmaceuticals:Controlled-release tablet excipients and laxative formulations require pharmacopeial-grade material with validated heavy metal and microbial specifications. European contract manufacturers dominate demand for compendial-grade psyllium and pectin derivatives.
- Dietary Supplements:Capsule and powder formats emphasizing digestive wellness and metabolic support. Direct-to-consumer brands in North America favor branded prebiotic blends with clinical trial backing over commodity fiber isolates.
- Animal Feed:Gut health modulation in poultry and swine production utilizing lower-purity fiber fractions excluded from human food channels. Asian compound feed manufacturers drive volume in this specification tier.
Pharmaceutical-grade material captures highest per-kilogram margins; food fortification delivers volume scale.
Source:
Raw material provenance determines extraction chemistry, sustainability positioning, and supply security profile.
- Plants:Chicory roots and cereal grains dominate industrial inulin and beta-glucan production through wet-milling infrastructure concentrated in Belgium, the Netherlands, and Iowa.
- Fruits:Apple and citrus pectin extraction yields high-methoxyl gelling agents for confectionery and pharmaceutical applications, with Italian and Spanish processors anchoring European supply.
- Legumes:Guar bean fractionation in Rajasthan and Gujarat supplies hydrocolloid markets, while pea fiber co-products from protein isolation gain traction in clean-label formulations.
- Vegetables:Sugar beet and Jerusalem artichoke offer regional inulin alternatives with shorter supply chains for European formulators seeking reduced transport emissions.
Root-crop extraction infrastructure holds cost advantage; fruit-derived pectin commands premium positioning.
Form:
Physical presentation dictates handling economics, dissolution kinetics, and equipment compatibility across manufacturing environments.
- Powder:Dominant format for dry-mix applications with extended shelf stability and pneumatic conveying compatibility. Midwest US grain processors optimize bulk density and flowability for automated bakery and cereal manufacturing lines.
- Liquid:Pre-hydrated concentrates gaining share in beverage applications requiring clean-label solubility without dusting or clumping issues. European juice manufacturers favor liquid inulin for seamless integration into pasteurized formulations.
- Granules:Intermediate particle size for controlled-release supplement tablets and animal feed premixes where uniform dispersion matters.
- Concentrate:High-solids preparations reducing transport costs for regional beverage and dairy processors with on-site dilution capabilities.
Powder maintains manufacturing dominance; liquid concentrates are climbing the fastest in beverage reformulation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Antwerp-Bruges liquid bulk terminals anchor European chicory root inulin imports, while Iowa's rail-linked grain processing corridors distribute corn-derived fibers across North American manufacturing networks.
United States
Functional food brands in Chicago and Minneapolis drive inulin procurement for FDA-compliant fiber fortification claims. The Nutrition Facts labeling revision compels reformulation timelines by 2026 enforcement deadlines. Midwest wet-milling clusters in Iowa and Illinois deploy near-infrared spectroscopy for real-time fiber verification.
China
Domestic bakery and dairy processors scale chicory root and guar bean extraction for reduced-sugar product lines. GB food safety standards impose 18-24 month novel fiber approval timelines that delay launches versus domestic markets. Shandong Province processors expand wet-milling capacity to serve regional reformulation contracts.
Germany
EFSA's tightened cholesterol-reduction claim standards force human intervention trial submissions rather than biomarker extrapolation. North Rhine-Westphalia and Bavaria host resistant starch processing infrastructure serving European cereal and bakery brands. Benelux grain corridors create single-point supply vulnerability for North American formulators.
India
Compound feed manufacturers in Gujarat and Rajasthan drive guar gum fractionation for poultry gut health modulation. The PLI scheme production-linked incentives attract chicory and guar joint ventures for food processing scale-up. Monsoon-dependent harvests in Rajasthan generate input cost volatility for hydrocolloid supply chains.
Belgium
Chicory root inulin extraction infrastructure concentrates in Flanders through established hot-water diffusion and spray-drying operations. EFSA health claims framework compliance anchors European prebiotic positioning for dairy and bakery applications. The Port of Antwerp-Bruges handles bulk inulin concentrate flows to UK and German formulators.
Soluble Fibers Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream. The market structures around consolidated grain processors with captive extraction infrastructure and fragmented specialty fiber purveyors serving pharmaceutical-grade specifications. Three archetypes dominate: agribusiness conglomerates with backward-integrated feedstock control, European family-owned processors with legacy chicory expertise, and Asian contract manufacturers scaling regional bean fractionation. Competitive moves concentrate on preferred supplier agreements with CPG buyers and enzymatic extraction technology licensing.
Among North American agribusiness operators, Cargill Inc. and Archer Daniels Midland Company exemplify scale-driven platform integration with grain processing network leverage. Tate & Lyle PLC occupies a position within the European specialized carbohydrate tier, anchoring polydextrose and resistant starch supply relationships. Roquette Frères represents the family-owned processor archetype with plant-based innovation positioning.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill Inc. |
| Ingredion Inc. |
| Tate & Lyle PLC |
| Roquette Frères |
| Südzucker AG |
| Cosucra Groupe Warcoing |
| BENEO GmbH |
| Nexira SAS |
| Others |
Supply Flow & Price Mechanics
Shandong Province's wet-milling clusters dictate downstream pricing leverage for inulin concentrates serving Chinese bakery reformulation contracts. Capacity additions here compress spot premiums for regional buyers while FDA enforcement timelines in the United States accelerate contract negotiations for qualifying fiber sources.
Pricing Analysis
Volume-discount tiering separates pharmaceutical-grade psyllium from commodity inulin and feed-grade fractions. Certification under FDA GRAS or EFSA health claims frameworks commands 40-60% premia over unqualified material. Cost compression in standard-grade inulin intensifies as Chinese processors scale chicory root extraction. Compound feed manufacturers exhibit highest price sensitivity; pharmaceutical excipient buyers show least elasticity due to validated supplier requirements.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now characterize preferred supplier agreements with North American CPG buyers, straining working capital for Midwest grain processors. Raw material flows concentrate in Belgium, China, and India—chicory roots, guar beans, and corn feedstocks respectively. Logistics chokepoints at the Port of Antwerp-Bruges create single-point vulnerability for European inulin distribution. Distribution runs through direct procurement relationships rather than distributor intermediaries for traceability-critical segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against precision-fermented beta-glucans, which threaten to displace plant-derived fibers in pharmaceutical and premium food applications.
For Market Incumbents: Entrench FDA GRAS dossiers for novel fiber sources ahead of enforcement deadlines. Secure backward integration into chicory root cultivation in Belgium and Iowa to capture margin from volatile Indian guar supplies. Precision-fermentation entrants threaten premium positioning; enzymatic extraction licensing defends technology differentiation.
For New Entrants and Emerging Players: Establish a beachhead in liquid soluble fiber concentrates for European clean-label beverage reformulation. India's PLI scheme incentives offer lowest-capital entry for guar fractionation joint ventures. Target pharmaceutical-grade pectin from Italian citrus processors where EFSA compliance creates barrier-protected niches.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors enzymatic extraction specialists with validated regulatory dossiers over commodity processors. Five-to-ten year viability hinges on health claim approval pipelines rather than capacity scale. Acquisition targets should demonstrate pre-approved EFSA or FDA fiber status. Watch for precision-fermentation beta-glucan cost parity as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Extraction Licensing | Tate & Lyle and Roquette leverage proprietary hydrolysis to secure preferred supplier status with reformulating CPG brands. |
| Backward Integration into Feedstock Cultivation | Cargill's Iowa chicory root contracts reduce exposure to Indian monsoon volatility for hydrocolloid-dependent manufacturers. |
| Precision Fermentation Scale-Up | Microbial beta-glucan production offers supply security independent of agricultural harvest cycles and geographic concentration. |
| Regulatory Dossier Pre-Approval | EFSA's tightened evidentiary standards force consolidation around processors holding validated human intervention trial data. |
| Direct Procurement Relationship Building | Sports nutrition brands in Minneapolis bypass distributors to secure lot traceability for FDA-compliant fiber declarations. |
Methodological Framework
Operator-level perspectives from extraction plant managers, procurement leads at functional food manufacturers, regulatory affairs directors, and pharmaceutical excipient buyers anchored the qualitative base. Secondary validation drew from FDA GRAS notifications, EFSA health claims register entries, USDA crop production surveys, and customs trade data for chicory root and guar bean flows. Bottom-up capacity modeling triangulated against top-down demand segmentation across the analysis window.
Scenario-bracketing around regulatory enforcement timing and precision-fermentation cost curves bounded the forecast envelope. Segmentation dimensions included molecular architecture, purity grade, end-use application, and regional regulatory cluster. CAGRs were derived from installed capacity trajectories and reformulation pipeline visibility. Input cost volatility for Indian guar and Belgian chicory root featured as sensitivity variables.
Stress conditions across monsoon failure frequency, FDA approval timeline delays, and EFSA claim rejection rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about enzymatic extraction yield improvements and health claim substantiation success rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Date Syrup Market
Ingredients
Red Orange Anthocyanin Extract Ingredients Market
Ingredients
United States Corn Glucose Market
Ingredients
Baobab Ingredient Market
Ingredients
Asia-Pacific Lipids Market
Ingredients
PHO Oils Market
Ingredients
Soy Flour Market
Ingredients
Sunflower Protein Market
Ingredients
Oat Fiber Market
Ingredients
Rooster Comb Extract Market
Ingredients
United Kingdom Protein Market
Ingredients
Cocoa Liquor Market
Ingredients
Sea Buckthorn Berry Extract Market
Ingredients
Curcuma Longa (Turmeric) Root Extract Market
Ingredients
Bean Flour Market
Ingredients
Pork Skin Gelatin Market