
 Africa Plant Protein Ingredients Market | 2026-2036
Africa Plant Protein Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Plant Protein Ingredients Market Outlook
South African ingredient processors is pivoting toward extruded protein texturization to serve pan-African meat-alternative brands. Cargill Incorporated leverages its oilseed processing footprint in Durban to supply defatted soy flour across Southern Africa. Kerry Group PLC sustains formulation partnerships with bakery and snack producers in Lagos and Casablanca. Archer Daniels Midland Company anchors regional supply through its port-adjacent storage and blending facilities.
Plant protein ingredients comprise fractionated, concentrated, or isolated proteins extracted from legumes, grains, seeds, and nuts, typically achieving protein contents of fifty to ninety percent dry weight through aqueous extraction, enzymatic treatment, or mechanical separation; these ingredients function as emulsifiers, gelling agents, and nutritional fortifiers in formulated foods, nutritional supplements, and animal nutrition. Soy protein dominates African volume due to established crushing infrastructure and cost-positioning in animal feed and bakery applications, while pea protein isolates command premium positioning in nutritional supplements targeting health clubs and nutraceutical companies. Rice protein from grains occupies a smaller but growing niche in hypoallergenic formulations for infant nutrition and specialized dietary products.
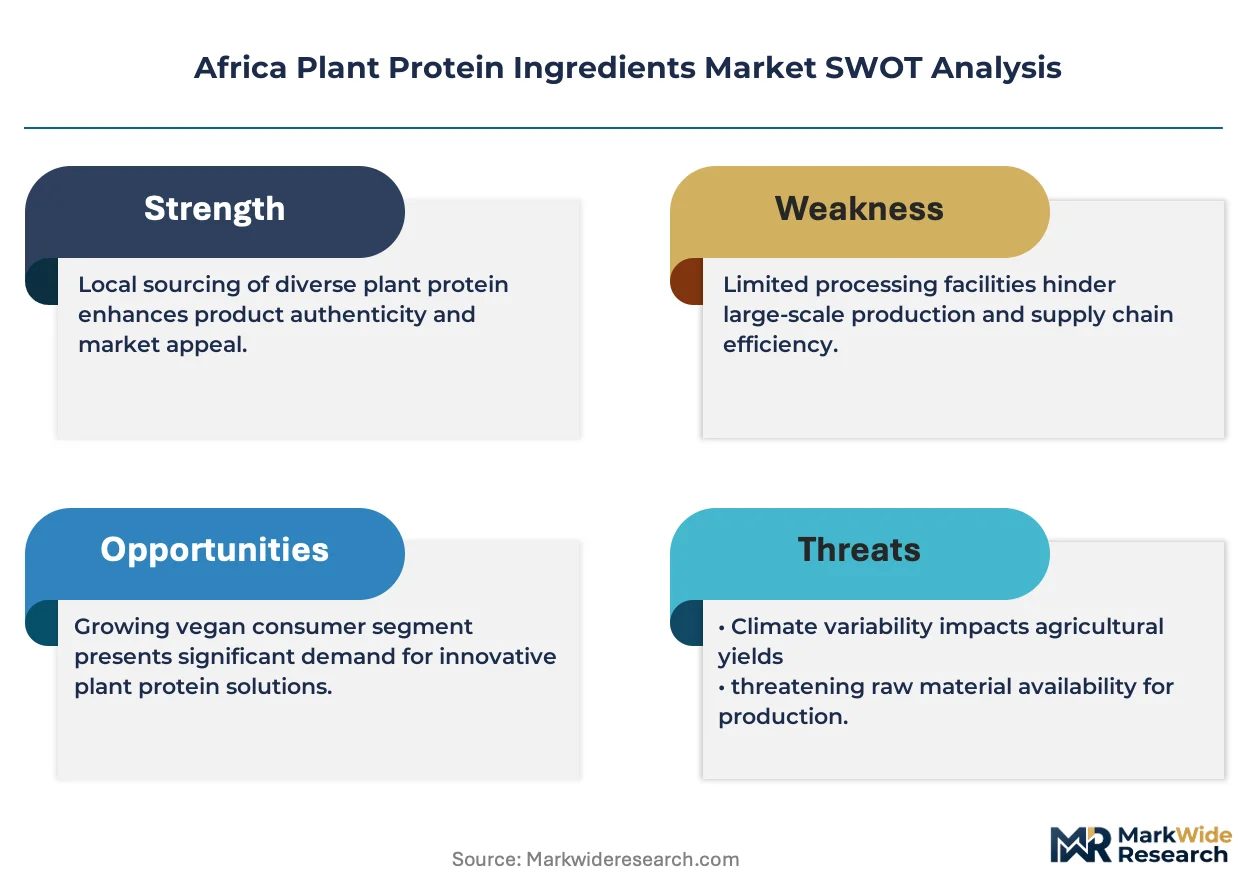
South Africa's Department of Health enforces food fortification standards that mandate micronutrient delivery in staple foods, directly shaping protein ingredient specifications for mass-market applications. Kenya's Bureau of Standards and Nigeria's National Agency for Food and Drug Administration and Control impose progressively stricter contaminant thresholds and labeling requirements that filter market access for imported concentrates. Ethiopia's Food and Drug Authority is developing plant protein quality benchmarks that will determine which suppliers qualify for government nutrition programs. Stakeholders must monitor how harmonization pressures across these national regulators reshape certification costs and procurement criteria for cross-border ingredient trade.
Market Dynamics
Clean-label verification mandates from South Africa's Department of Health are compressing formulation timelines while forcing processors to requalify entire supply chains for micronutrient fortification compliance.
Growth Catalysts
- Urban protein transition:Nairobi and Addis Ababa consumers are redirecting household food budgets toward legume-derived concentrates, creating pull-through demand for pea and soy protein isolates in retail channels.
- Food fortification mandates:South Africa's Department of Health regulations on staple food micronutrient delivery are mandating protein ingredient specifications that favor verified, traceable supply chains.
- Extrusion technology adoption:Pan-African meat-alternative brands are sourcing texturized vegetable proteins from regional processors, expanding addressable volume for defatted soy flour and concentrate applications.
Market Restraints
- Soy supply concentration:Crushing infrastructure and oilseed processing capacity cluster around Durban and select coastal hubs, exposing buyers to port congestion and logistics chokepoints.
- Pea protein input costs:Yellow pea cultivation faces competition from subsidized cereal programs across East African agricultural zones, compressing raw material availability for isolate production.
- Cross-border regulatory friction:Kenya's Bureau of Standards and Nigeria's National Agency for Food and Drug Administration and Control impose divergent contaminant thresholds that fragment procurement criteria for imported concentrates.
Strategic Opportunities
- Ethiopian nutrition program access:The Ethiopian Food and Drug Authority is developing plant protein quality benchmarks that will determine supplier eligibility for government procurement contracts.
- Hypoallergenic infant nutrition:Rice protein from grains occupies an underpenetrated niche in specialized dietary products for allergy-sensitive pediatric formulations.
- Health club channel expansion:Nutraceutical companies serving gym and fitness segments in Lagos and Casablanca are requesting premium-positioned isolate grades with enhanced amino acid profiles.
Industry Challenges
- Clean-label certification timelines:Verification protocols for ingredient traceability and micronutrient content are extending qualification cycles for new supplier onboarding.
- Extrusion equipment capex:Texturization capacity expansion requires specialized twin-screw extruders with die configurations optimized for high-moisture meat analog production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Plant Protein Ingredients Market |
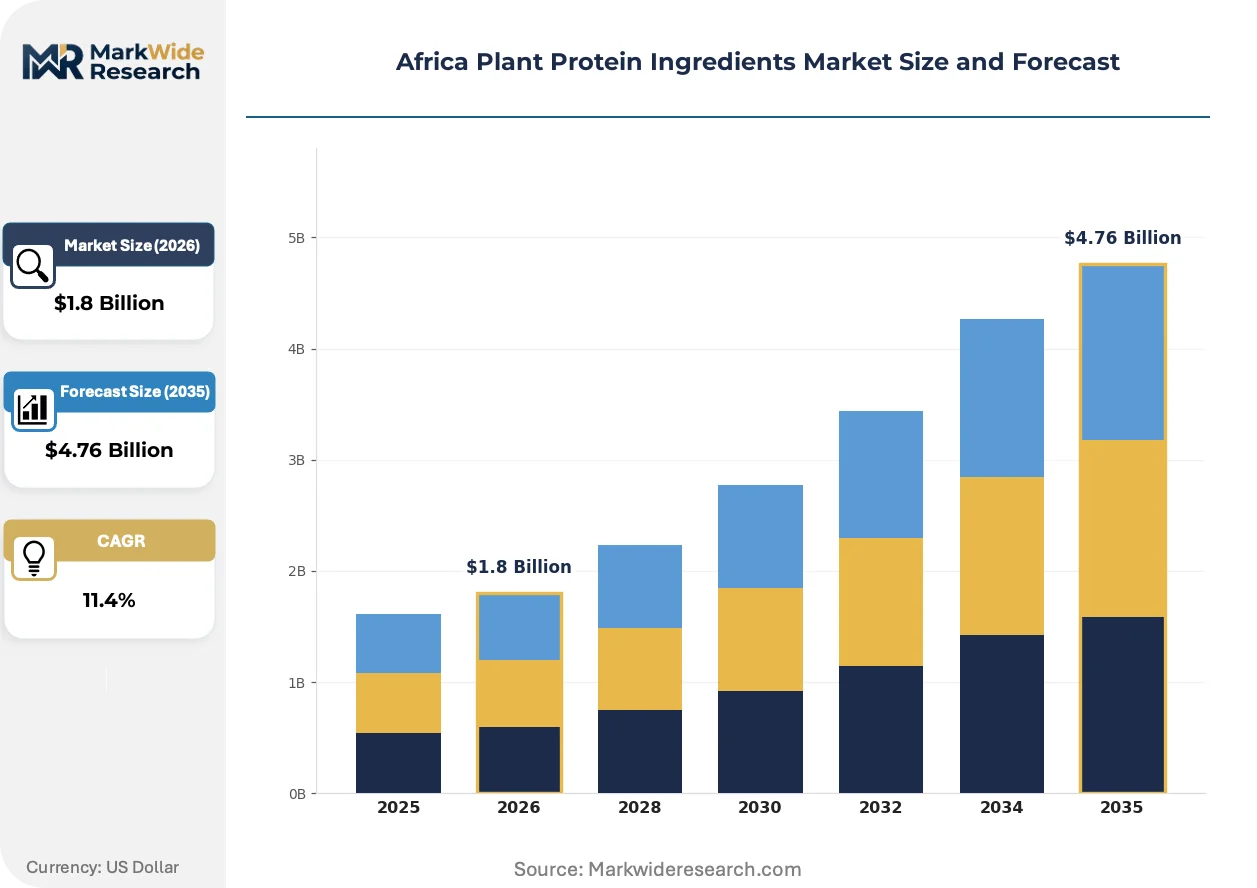
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pea Protein, Soy Protein, Rice Protein, Hemp Protein Application: Food & Beverages, Nutritional Supplements, Animal Feed, Bakery Products Source: Legumes, Grains, Seeds, Nuts End User: Food Manufacturers, Health Clubs, Nutraceutical Companies, Restaurants |
| Companies Covered | Cargill Incorporated, Kerry Group PLC, Wilmar International Ltd, International Flavors & Fragrances Inc, Archer Daniels Midland Company, DuPont de Nemours Inc, Axiom Foods Inc, Glanbia PLC, Amesi Group, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Plant Protein Ingredients Market Strategic Shifts
Extrusion and enzymatic processing advances are rewriting how African formulators achieve texture and functionality in plant-based applications, while regulatory divergence across national food authorities is fragmenting compliance architectures.
High-moisture extrusion technology is rewriting the competitive terrain for meat-analog texture development. Bakery and snack producers in Lagos are adopting these systems to replicate muscle fiber structures without animal-derived binders. The structural consequence is compressing reliance on imported textured vegetable protein while enabling regional processors to capture value previously lost to offshore suppliers.
South Africa's Department of Health fortification standards are tightening micronutrient delivery specifications for mass-market staples. Ingredient processors must now document protein content, amino acid completeness, and anti-nutritional factor levels through accredited laboratories. Bakery applications face the steepest compliance burden as reformulation cycles compress to meet verification deadlines.
Health-conscious consumers in Nairobi fitness clubs are switching protein sourcing preferences from dairy-derived to legume-based concentrates. Nutraceutical distributors are responding by unbundling bulk isolate sales into portion-controlled retail formats. This behavioral shift is most visible in urban Kenyan channels where gym-affiliated supplement shops now stock pea protein as a standard inventory line.
Africa Plant Protein Ingredients Market Segmentation
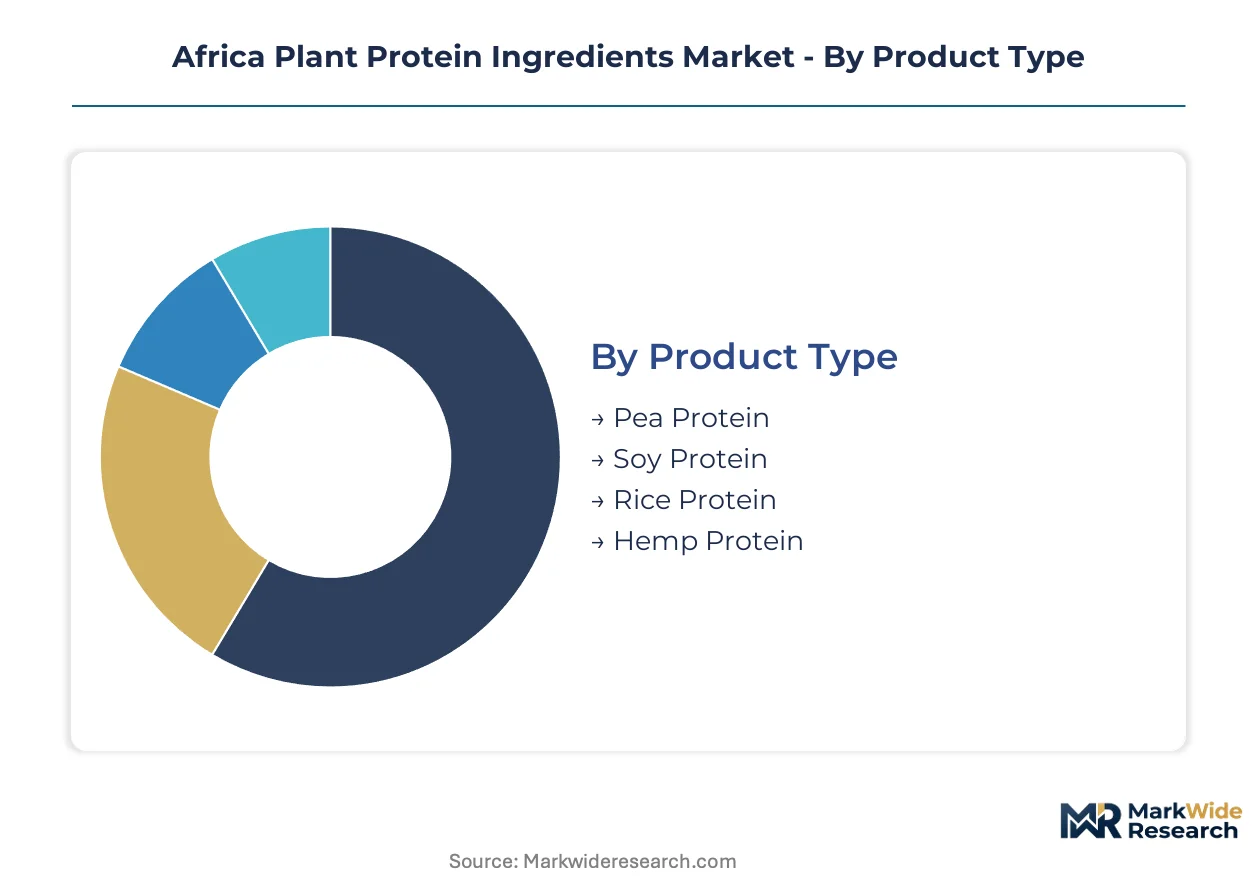
Plant protein ingredient procurement across Africa fragments along functional specifications, regulatory compliance tiers, and end-use performance requirements. Buyers in Lagos, Nairobi, and Johannesburg source isolates, concentrates, and texturized forms through distinct qualification pathways shaped by national food authority mandates.
Product Type:
Soy protein dominates installed crushing capacity across Durban and coastal processing hubs, while pea protein investments concentrate in newer isolate facilities serving premium nutritional channels.
- Pea Protein:Yellow pea isolates achieve protein concentrations of eighty to ninety percent dry weight through aqueous extraction and membrane filtration. Demand concentrates in Nairobi health clubs and Addis Ababa nutraceutical distributors where consumers prioritize legume-derived amino acid profiles over soy alternatives.
- Soy Protein:Defatted flour, concentrate, and isolate grades leverage established oilseed processing infrastructure. South African bakery manufacturers and pan-African meat-alternative brands absorb the majority of regional soy protein volume through Cargill's Durban supply network.
- Rice Protein:Hypoallergenic brown rice isolates serve specialized infant nutrition formulations with protein contents of seventy to eighty percent.
- Hemp Protein:Cold-pressed seed cake yields protein-fiber blends with lower purity but functional appeal in premium wellness positioning.
Soy protein absorbs the bulk of installed capacity; pea protein is expanding most quickly.
Application:
Cost tier differentiation separates mass-market fortification applications from premium isolate grades commanding three to five times the per-kilogram price.
- Food & Beverages:Dairy alternatives, meat analogs, and beverage fortification require emulsifying and gelling functionalities. South Africa's Department of Health micronutrient mandates shape protein specifications for mass-market staple applications.
- Nutritional Supplements:Isolates with enhanced leucine content and complete amino acid scoring target gym-affiliated retail in Lagos and Casablanca. Kerry Group PLC formulates portion-controlled retail formats for this channel.
- Animal Feed:Defatted soy meal from oilseed crushing supplies poultry and aquaculture operations across Southern Africa.
- Bakery Products:Protein enrichment in bread and snack applications faces the steepest South African fortification compliance burdens.
Food & Beverages captures the largest volume commitment; Nutritional Supplements climbs the fastest.
Source:
Raw material geography determines supply security, with legume cultivation competing against subsidized cereal programs in East African agricultural zones.
- Legumes:Pea and bean proteins dominate African volume through established cultivation in Ethiopia and Kenya. Yellow pea availability faces pressure from government grain support programs.
- Grains:Rice protein extraction from milled fractions serves hypoallergenic positioning with limited regional processing infrastructure.
- Seeds:Hemp and sunflower proteins occupy niche wellness applications with import-dependent supply chains.
- Nuts:Almond and peanut protein concentrates remain underdeveloped due to aflatoxin regulatory thresholds in Nigeria and Kenya.
Legumes anchor regional supply; Seeds gain share fastest through wellness positioning.
End User:
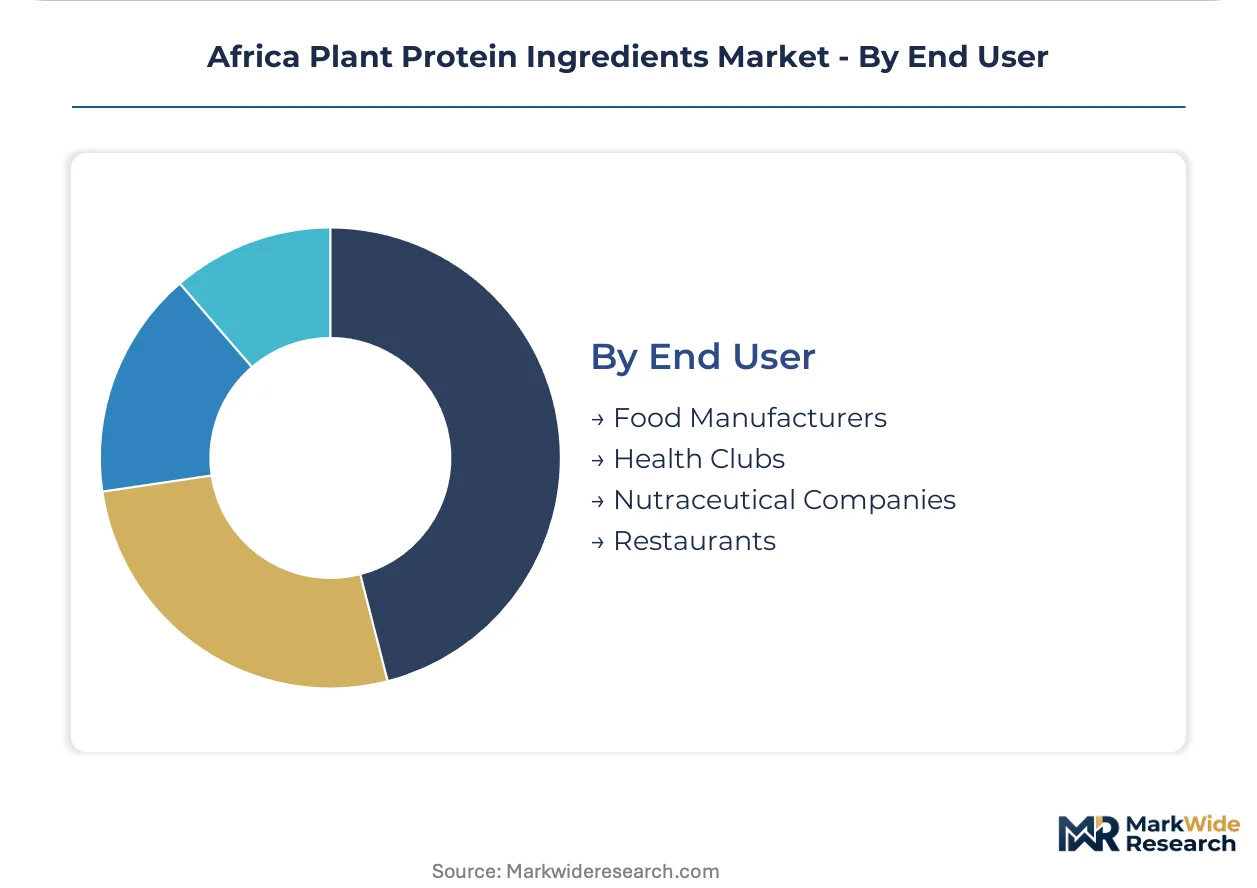
Customer type dictates formulation support requirements, with food manufacturers demanding full technical service and health clubs accepting standardized retail formats.
- Food Manufacturers:Industrial buyers in Lagos and Johannesburg require extrusion-compatible texturized proteins and documented micronutrient content for South African fortification compliance.
- Health Clubs:Gym-affiliated supplement shops in Nairobi and Addis Ababa stock portion-controlled pea protein isolates as standard inventory lines.
- Nutraceutical Companies:Formulators request certificate-of-analysis documentation and amino acid profiling for premium positioning.
- Restaurants:Limited-service and fast-casual operators trial plant-based menu items with texturized vegetable protein from regional extrusion facilities.
Food Manufacturers absorb the bulk of procurement volume; Health Clubs is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yellow pea cultivation in Ethiopia's highland zones anchors East African raw material flows for isolate production, while South Africa's oilseed crushing infrastructure around Durban supplies defatted soy flour across Southern African markets.
South Africa
Urban consumers in Johannesburg and Cape Town are redirecting household food budgets toward legume-derived concentrates for meat-alternative applications. The Department of Health enforces food fortification standards that mandate micronutrient delivery in staple foods, directly shaping protein ingredient specifications for mass-market bakery and snack producers. Cargill Incorporated leverages its oilseed processing footprint in Durban to supply defatted soy flour across the subcontinent.
Nigeria
Bakery and snack manufacturers in Lagos are expanding formulations with pea and soy protein isolates to meet rising demand for protein-enriched retail products. The National Agency for Food and Drug Administration and Control imposes progressively stricter contaminant thresholds and labeling requirements that filter market access for imported concentrates. Kerry Group PLC sustains formulation partnerships with producers in Lagos for portion-controlled retail formats targeting health-conscious urban consumers.
Kenya
Nairobi health clubs and gym-affiliated supplement shops are switching protein sourcing preferences from dairy-derived to legume-based concentrates, creating pull-through demand for pea protein isolates. The Bureau of Standards imposes divergent contaminant thresholds that fragment procurement criteria for imported concentrates compared to neighboring markets. Urban consumers in Nairobi are driving the fastest channel expansion for nutraceutical companies serving fitness segments.
Ethiopia
Addis Ababa nutraceutical distributors are prioritizing legume-derived amino acid profiles over soy alternatives for premium nutritional supplement positioning. The Food and Drug Authority is developing plant protein quality benchmarks that will determine supplier eligibility for government nutrition program procurement contracts. Yellow pea cultivation in Ethiopian agricultural zones faces competition from subsidized cereal programs, compressing raw material availability for isolate production.
Morocco
Casablanca-based nutraceutical companies are requesting premium-positioned isolate grades with enhanced amino acid profiles for health club channel expansion. National food safety regulators align with broader regional harmonization pressures that reshape certification costs for cross-border ingredient trade. Kerry Group PLC maintains formulation partnerships with bakery and snack producers in Casablanca for clean-label verification compliance.
Africa Plant Protein Ingredients Market Competitive Environment
Global majors compete with regional champions across supply chain control and formulation service capabilities. The vendor base clusters around oilseed processing infrastructure in coastal hubs and newer isolate facilities serving premium nutritional channels. Three archetypes dominate: integrated agribusiness conglomerates with crushing and fractionation assets, specialized ingredient formulators with technical service capabilities, and regional trading houses with port-adjacent storage and blending facilities. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure qualified supply for fortification-compliant formulations.
Within the integrated agribusiness tier, Cargill Incorporated and Archer Daniels Midland Company exemplify players with established oilseed processing footprints and port-adjacent logistics capabilities. Kerry Group PLC occupies a position among specialized formulators with technical service partnerships across Lagos, Casablanca, and Nairobi. These three companies represent distinct strategic positions: crushing-integrated supply security, formulation-led customer intimacy, and regional distribution scale.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Kerry Group PLC |
| Wilmar International Ltd |
| International Flavors & Fragrances Inc |
| Archer Daniels Midland Company |
| DuPont de Nemours Inc |
| Axiom Foods Inc |
| Glanbia PLC |
| Amesi Group |
| Others |
Value Chain & Pricing Dynamics
South African fortification mandates for micronutrient delivery in staple foods are compressing procurement timelines and forcing ingredient buyers to absorb premium pricing for verified, traceable supply chains with documented amino acid completeness.
Pricing Analysis
Technical service bundling separates premium-positioned suppliers from commodity traders, with formulation support, extrusion compatibility testing, and certificate-of-analysis documentation commanding 15-25% markups over unbundled isolate sales. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale, with health club channels in Lagos and Nairobi absorbing the least price-sensitive demand while mass-market bakery applications face acute cost compression. Pricing pressure stems from yellow pea input scarcity competing against subsidized cereal programs in Ethiopian and Kenyan agricultural zones. Animal feed manufacturers purchasing defatted soy meal represent the most price-sensitive segment, while nutraceutical companies sourcing enhanced leucine isolates tolerate premium positioning.
Supply Chain Analysis
Reverse-logistics infrastructure for returns and quality disputes remains underdeveloped across African protein ingredient channels, with most suppliers absorbing rejection costs rather than establishing systematic refurbishment flows. Supply concentrates in South Africa, Ethiopia, and Nigeria, with crushing infrastructure clustering around Durban and isolate production scaling in Addis Ababa highland zones. Raw material flows draw from yellow pea cultivation in Ethiopian agricultural belts, oilseed crushing in South African coastal hubs, and imported concentrate blending in Lagos port facilities. Single-source vulnerability runs through Durban's oilseed processing corridor, where port congestion propagates delays across Southern African markets. Distribution runs through regional trading houses with port-adjacent storage, direct mill relationships with food manufacturers, and nutraceutical distributors serving health club retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Extrusion equipment capacity constraints and qualified isolate production bottlenecks are propping pricing premiums across the analysis window, with demand growth outpacing regional texturization infrastructure expansion.
For Market Incumbents: Extend technical service capabilities into extrusion process optimization and high-moisture meat analog formulation support to lock in bakery and snack manufacturer relationships before regional competitors scale comparable capabilities. Defend position by securing backward integration into yellow pea cultivation contracts in Ethiopian highland zones, insulating against raw material competition from government grain subsidy programs. Certification investment in South African Department of Health compliance documentation represents the critical lever for maintaining mass-market access. For New Entrants and Emerging Players: The gap between premium isolate grades with enhanced amino acid profiles and economy-tier defatted soy flour creates entry space for mid-market concentrate positioning targeting pan-African meat-alternative brands. Underpenetrated rice protein extraction for hypoallergenic infant nutrition formulations offers the most penetrable application segment, with limited regional processing infrastructure and escalating regulatory thresholds for aflatoxin-sensitive nut alternatives. A go-to-market angle anchored to Ethiopian government nutrition program qualification provides procurement contract visibility and volume commitments. For Investors and Strategic Acquirers: The window for entry favors specialized ingredient formulators with technical service partnerships across multiple African commercial hubs rather than pure trading plays or undifferentiated crushing assets. Long-term viability rests on securing qualified supply positions ahead of harmonized regulatory standards across Kenya, Nigeria, and South Africa compressing market access for non-compliant suppliers. The acquisition target archetype combines extrusion capabilities with established clean-label verification protocols. The signal to watch is Ethiopian Food and Drug Authority plant protein quality benchmark publication, which will determine supplier eligibility for government procurement and trigger consolidation among unprepared trading houses.| Strategic Initiative | Industry Significance |
|---|---|
| Extrusion Capacity Expansion | High-moisture texturization equipment captures value previously lost to offshore textured vegetable protein suppliers. |
| Backward Integration into Cultivation | Yellow pea contract farming in Ethiopian highland zones secures isolate production feedstock against cereal subsidy competition. |
| Clean-Label Certification Investment | South African Department of Health fortification compliance documentation maintains mass-market bakery channel access. |
| Technical Service Partnership Expansion | Formulation support capabilities in Lagos and Casablanca lock in nutraceutical and snack manufacturer relationships. |
| Hypoallergenic Product Line Development | Rice protein extraction for infant nutrition addresses underpenetrated pediatric dietary formulation demand. |
Study Parameters
Document review covered trade flow databases, national food authority regulatory filings, and oilseed processing capacity disclosures, complemented by interviews with ingredient procurement managers at pan-African food manufacturers, extrusion equipment specialists, and nutraceutical distribution executives in Nairobi and Lagos. Secondary validation drew from South African Department of Health fortification standards documentation, Ethiopian Food and Drug Authority draft quality benchmarks, and Kenya Bureau of Standards contaminant threshold publications. Bottom-up volume estimates from crushing facility utilization rates and isolate production capacity were triangulated against top-down demand projections from food manufacturer formulation surveys.
Segment-level value outputs were generated through price-point modeling across premium isolate, standard concentrate, and economy flour tiers, with application splits reflecting bakery, nutritional supplement, and meat-alternative end-use demand. CAGRs were derived from trend extrapolation of urban protein transition rates in East African commercial hubs and extrusion technology adoption curves among regional processors. Forecast inputs incorporated yellow pea cultivation area competition from subsidized cereal programs and port logistics congestion indices for Durban supply corridors.
Inputs from national regulator consultation drafts and oilseed processor capacity disclosures were available through the study window; gaps in real-time Ethiopian agricultural yield data and informal cross-border trade volumes introduce uncertainty bands around East African supply projections. Forecasts reflect documented assumptions regarding regulatory harmonization timelines and infrastructure investment commitments. Practitioners should monitor Ethiopian Food and Drug Authority benchmark finalization and South African fortification verification deadline extensions for early signals of competitive access restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Plant Protein Ingredients Market
Ingredients
Stabilized Starch Market
Ingredients
South America Lipid Market
Ingredients
Dill Seed Oil Market
Ingredients
Global Distillers Corn Oil Market
Ingredients
Confectionery Ingredients Market
Ingredients
Soy Peptones Market
Ingredients
North America Soy Protein Concentrate Market
Ingredients
Dry Brewing Ingredients Market
Ingredients
Global Amaranth Oil Market
Ingredients
Mung Bean Starch Market
Ingredients
Xylooligosaccharide Market
Ingredients
Europe Malt Extract Market
Ingredients
Carotenes Market
Ingredients
Global Dry Yeast Market
Ingredients
Plant Based Ingredients Market