
 Oyster Peptide Market | 2026-2036
Oyster Peptide Market Size, Share, and Industry Trends Forecast 2026-2036
Oyster Peptide Market Insights
Asset-light toll manufacturing and contract peptide synthesis is tilting competitive dynamics toward firms that avoid heavy fermentation capex. Hubei Nutratide biotech Co., Ltd leverages in-house enzymatic hydrolysis to sustain margin control across powder and capsule outputs. Maruha Nichiro Corporation anchors premium positioning through cold-chain marine sourcing from Japanese coastal waters. Seagarden Group AS specializes in Nordic freeze-dried formats that occupy the pharmacy channel across Scandinavian markets.
Oyster peptides comprise low-molecular-weight protein fragments derived from enzymatic hydrolysis of Crassostrea species, typically yielding fractions under 10 kDa with standardized zinc and taurine content for bioactive delivery in supplement matrices. The hydrolyzed peptides category dominates current volume owing to direct incorporation into functional beverage bases and sachet powders, while liquid formats in ready-to-drink applications represent the fastest-expanding margin pool as convenience positioning accelerates. Nutraceuticals as an application segment leads absolute value, though cosmetics-grade peptide isolates are deepening their share as Korean and Chinese derma brands reformulate around marine-derived actives.
China's SAMR enforces GB standards on health-food peptide claims and manufacturing hygiene, while Japan's MHLW through FOSHU and PMDA frameworks conditions market entry on documented physiological efficacy. The EU EFSA novel food consultation pathway and REACH-aligned substance registration create dual compliance thresholds for Asian exporters targeting European nutritional labels. Stakeholders must monitor evolving peptide-specific maximum residue limits and novel food rulings across their priority jurisdictions to preempt supply chain disruption.
Market Dynamics
Enzymatic hydrolysis technology is compressing production timelines while China's SAMR tightens health-food registration, forcing exporters toward third-party ISO certification and tilting competitive advantage toward asset-light toll manufacturers with established enzymatic capabilities.
Growth Catalysts
- FOSHU Framework Expansion:Japan's MHLW is broadening approved health claims for marine-derived peptides, accelerating SKU development by domestic nutraceutical formulators seeking physiological efficacy documentation.
- Coastal Processing Cluster Density:Shandong and Zhejiang provinces concentrate enzymatic hydrolysis infrastructure, reducing raw material transit losses for Crassostrea sourcing and enabling just-in-time powder production.
- Marine-Derived Actives Pivot:Korean and Chinese derma brands are reformulating cosmetic matrices around oyster peptide isolates, creating pull-through demand for standardized zinc-taurine fractions in topical applications.
Market Restraints
- Crassostrea Supply Volatility:Wild oyster harvest fluctuations in East Asian coastal waters create input cost instability for hydrolyzed peptide processors without captive aquaculture contracts.
- Dual Compliance Thresholds:EU EFSA novel food consultation pathways and REACH-aligned substance registration impose overlapping technical barriers for Asian exporters targeting European nutritional labels.
- Plant Protein Substitution:Fermented pea and rice protein isolates are capturing share in functional beverage bases, pressuring oyster peptide positioning in mid-tier supplement matrices.
Strategic Opportunities
- Pharmacy Channel Penetration:Nordic markets demonstrate unmet demand for freeze-dried marine peptides in professional healthcare retail, with Swedish and Norwegian pharmacy chains expanding shelf space for immune-support SKUs.
- Ready-to-Drink Convenience Pivot:Liquid peptide formats in single-serve applications are capturing margin pools as Japanese and South Korean consumers shift from powder sachets toward on-the-go consumption.
- ISO Certification Arbitrage:China's NMPA registration tightening is creating competitive separation for exporters holding third-party ISO 22000 and HACCP credentials, enabling premium positioning in cross-border e-commerce channels.
Industry Challenges
- Enzymatic Hydrolysis Talent Scarcity:Specialized biochemists capable of optimizing fractionation below 10 kDa molecular weight thresholds command premium compensation, constraining capacity expansion for mid-tier processors.
- GB Standard Interpretation Variance:Inconsistent provincial enforcement of China's SAMR manufacturing hygiene requirements creates compliance timeline uncertainty for multi-facility operators.
- Cold-Chain Integrity Costs:Premium marine sourcing from Japanese coastal waters requires sustained refrigeration investment through distribution, compressing margins for brands without integrated logistics control.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oyster Peptide Market |
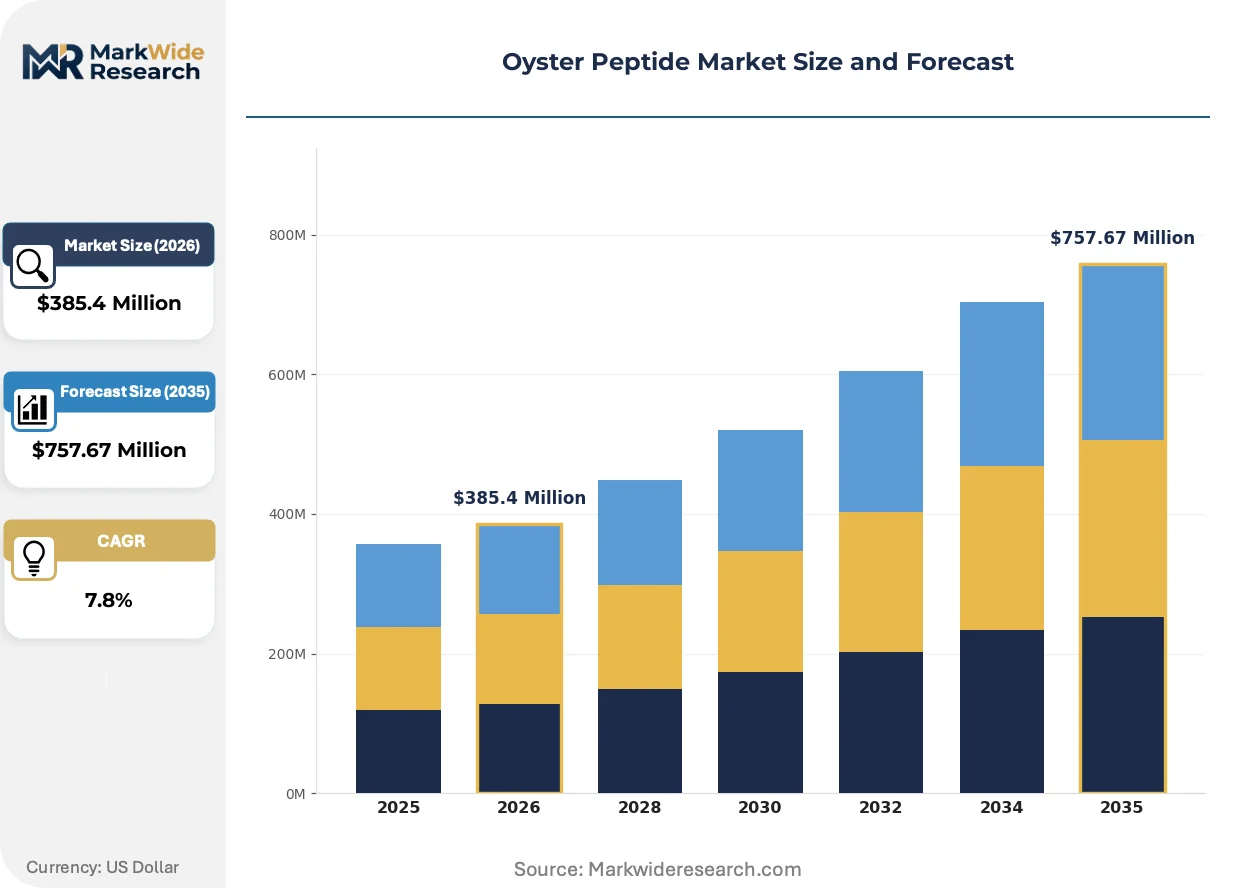
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $757.67 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzed Peptides, Powder, Capsules, Liquid Application: Dietary Supplements, Functional Foods, Cosmetics, Nutraceuticals End User: Healthcare Providers, Nutritional Labels, Research Institutions, Retail Customers Form: Ready-to-Drink, Solid, Gel, Freeze-Dried |
| Companies Covered | SmartPEP, Huzhou Purestar Biochem Co., Ltd, Xuchang Shangke Chemical Co., Ltd, Hubei Nutratide biotech Co., Ltd, Zhongshi Duqing (Shandong) Biotech Co., Ltd, Maruha Nichiro Corporation, Fujifilm Wako Pure Chemical Corporation, Seagarden Group AS, XI AN CHEN LANG BIO TECH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oyster Peptide Market Trends and Innovations
Peptide extraction methodologies are converging with precision fermentation and enzymatic engineering, enabling standardized bioactive fractions that meet divergent regulatory requirements across nutraceutical and cosmetic end-uses while compressing traditional batch-to-batch variability.
Membrane filtration technology is migrating from batch ultrafiltration toward continuous tangential flow systems, enabling real-time molecular weight cutoff adjustment below 10 kDa. Japanese toll manufacturers are adopting these systems at pilot scale. The shift is compressing capital intensity per kilogram of peptide output while improving taurine retention consistency.
REACH-aligned substance registration requirements are forcing Asian exporters to reconstruct supply chain documentation for zinc and taurine content verification. The industrial consequence is a bifurcation between integrated processors with in-house testing laboratories and traders dependent on third-party certificates. Cosmetic-grade peptide isolates face the steepest documentation burden, with Korean derma brands accelerating supplier audits to preempt ECHA scrutiny.
Buyer concentration among nutraceutical formulators is consolidating procurement decisions toward specification-grade contracts with defined bioactivity thresholds. Direct supplier relationships are displacing spot-market peptide purchasing in Japan and South Korea. This pattern is most visible in immune-support SKU development, where finished goods manufacturers demand certificate-of-analysis continuity across multi-year supply agreements.
Oyster Peptide Market Segmentation
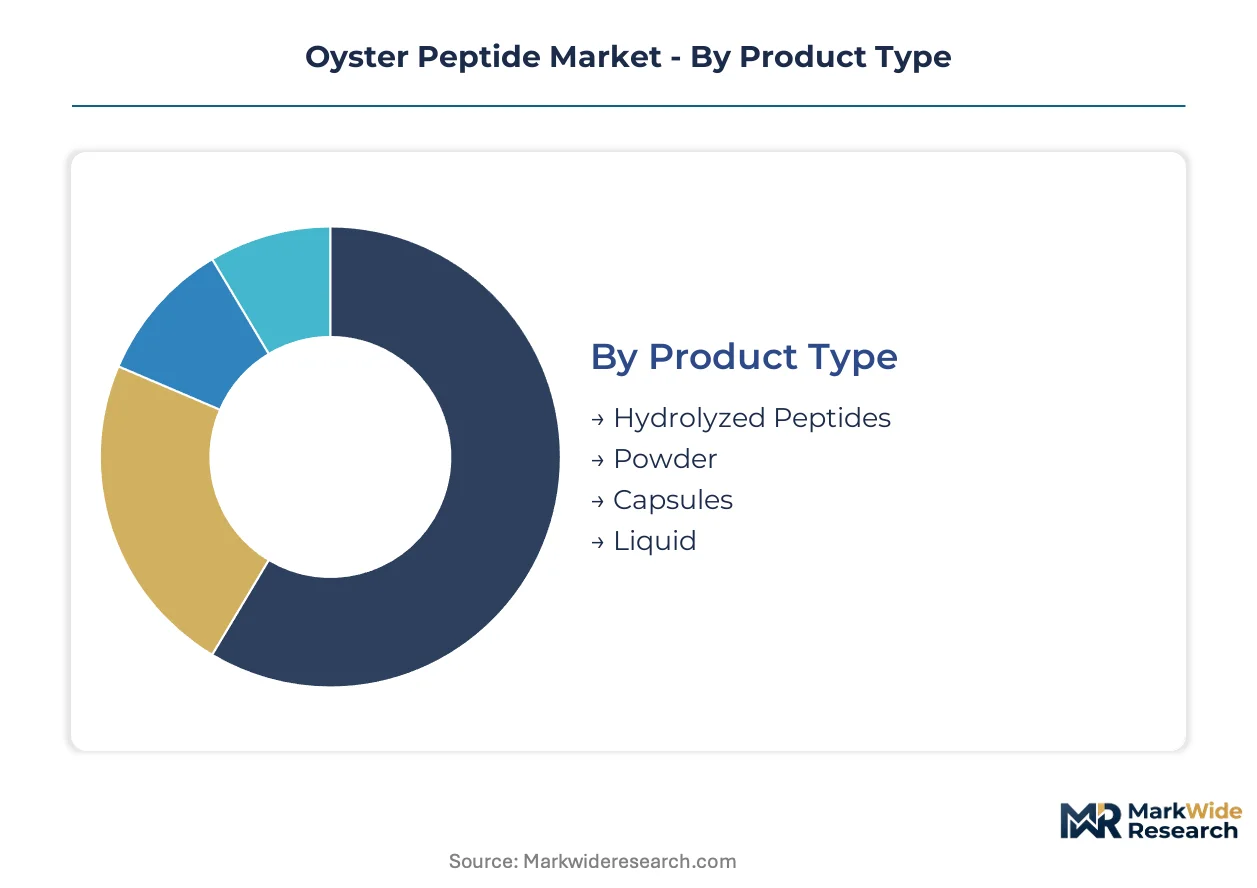
Oyster peptide manufacturers face divergent technical requirements across product formats, with enzymatic hydrolysis parameters and stability protocols varying sharply between powder sachets and liquid ready-to-drink applications. Segment-specific formulation expertise determines margin capture in this market.
Product Type:
After-sales service intensity varies dramatically across formats, with liquid formulations demanding cold-chain technical support and powder products requiring dissolution troubleshooting for nutraceutical formulators.
- Hydrolyzed Peptides:Low-molecular-weight fractions under 10 kDa produced through controlled enzymatic hydrolysis of Crassostrea species. Demand concentrates among Japanese and South Korean nutraceutical formulators developing immune-support SKUs, with procurement tilting toward toll manufacturers offering certificate-of-analysis continuity.
- Liquid:Ready-to-drink peptide suspensions requiring pH stabilization and taurine retention through aseptic processing. Japanese and South Korean consumers are shifting from powder sachets toward on-the-go consumption, expanding margin pools for convenience-positioned brands with integrated distribution control.
- Powder:Spray-dried peptide concentrates for functional beverage bases and sachet applications.
- Capsules:Hard-shell gelatin or vegetable-based delivery systems for standardized dosing.
Hydrolyzed peptides holds the largest share; momentum sits with liquid formats.
Application:
Cost tier differentiation separates pharmaceutical-grade peptide isolates from commodity nutraceutical inputs, with cosmetic applications commanding premium pricing for documented bioactivity thresholds.
- Nutraceuticals:Standardized zinc-taurine peptide fractions for physiological efficacy claims under Japan's FOSHU framework. Korean and Japanese formulators dominate procurement, with direct supplier relationships displacing spot-market purchasing for immune-support SKU development.
- Cosmetics:Marine-derived actives for topical matrices requiring REACH-aligned substance registration and zinc content verification. Korean derma brands are reformulating around these isolates, accelerating supplier audits to preempt ECHA scrutiny.
- Dietary Supplements:Capsule and tablet formats for wellness positioning.
- Functional Foods:Peptide incorporation into fortified beverage and food matrices.
Nutraceuticals captures the largest share; cosmetics is climbing the fastest.
End User:
Volume concentration among finished goods manufacturers is consolidating procurement toward specification-grade contracts with defined molecular weight thresholds.
- Nutritional Labels:Finished goods manufacturers specifying peptide bioactivity thresholds and certificate-of-analysis continuity. Procurement decisions in Japan and South Korea are consolidating toward multi-year supply agreements with integrated processors.
- Healthcare Providers:Professional channel distribution through pharmacy chains in Nordic markets, with Swedish and Norwegian retailers expanding shelf space for immune-support SKUs.
- Research Institutions:Academic and clinical trial peptide sourcing for efficacy studies.
- Retail Customers:Direct-to-consumer e-commerce peptide purchasing.
Nutritional labels holds the largest share; healthcare providers shows the steepest expansion trajectory.
Form:
Supply concentration in coastal processing clusters shapes format availability, with Shandong and Zhejiang infrastructure favoring powder and freeze-dried outputs over liquid bottling.
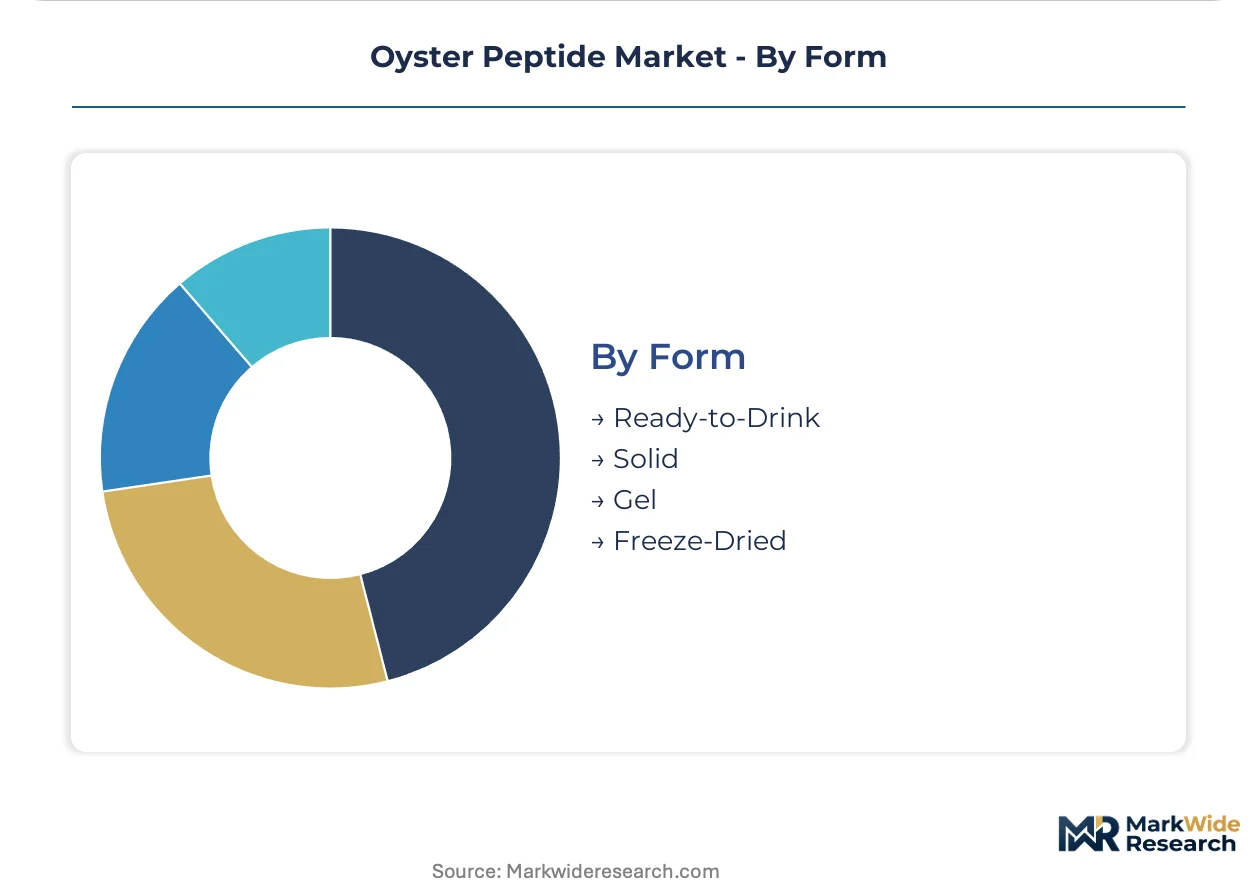
- Freeze-Dried:Lyophilized peptide matrices preserving bioactive integrity for pharmacy channel distribution. Seagarden Group AS occupies this segment across Scandinavian professional healthcare retail.
- Ready-to-Drink:Single-serve liquid applications requiring aseptic filling and cold-chain integrity. Japanese toll manufacturers are adopting continuous tangential flow systems at pilot scale to compress capital intensity.
- Solid:Tablet and capsule compressed formats.
- Gel:Semi-solid topical delivery systems.
Freeze-Dried holds the largest share; ready-to-drink is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's MHLW has expanded FOSHU-approved health claims for marine-derived peptides, triggering procurement surges from domestic nutraceutical formulators. China's SAMR enforcement of GB standards on peptide manufacturing hygiene is redirecting export flows toward ISO-certified toll manufacturers. South Korea's MFDS framework for functional food registration is accelerating SKU development timelines for immune-support products.
China
Shandong and Zhejiang provinces concentrate enzymatic hydrolysis infrastructure for Crassostrea processing, with coastal clusters enabling just-in-time powder production. SAMR's tightening of health-food registration rules under GB standards is pushing exporters toward third-party ISO 22000 certification. Qingdao and Ningbo processing hubs are absorbing capacity expansion from toll manufacturers seeking NMPA compliance arbitrage.
Japan
Tokyo-Osaka nutraceutical formulators dominate procurement of hydrolyzed peptides under FOSHU framework expansions for physiological efficacy claims. MHLW and PMDA documentation requirements condition market entry on standardized bioactivity thresholds. Cold-chain marine sourcing from Japanese coastal waters anchors premium positioning for domestic peptide isolates in pharmacy distribution.
South Korea
Seoul-based derma brands are reformulating cosmetic matrices around marine-derived actives, creating pull-through demand for zinc-taurine peptide fractions. MFDS functional food registration pathways are compressing development timelines for immune-support SKUs. Busan-Ulsan processing corridors are integrating enzymatic hydrolysis capacity to serve both nutraceutical and cosmetic end-uses.
Norway
Swedish and Norwegian pharmacy chains are expanding shelf space for freeze-dried marine peptides in professional healthcare retail. REACH-aligned substance registration requirements are forcing supply chain documentation reconstruction for zinc content verification. Nordic freeze-dried formats occupy immune-support positioning across Scandinavian markets with distinct professional channel penetration.
United States
Dietary supplement manufacturers are sourcing specification-grade peptide contracts with defined molecular weight thresholds below 10 kDa. FDA cGMP enforcement on peptide manufacturing creates compliance separation for exporters with certificate-of-analysis continuity. West Coast nutraceutical clusters are consolidating procurement decisions toward multi-year supply agreements with integrated Asian processors.
Oyster Peptide Market Competitive Landscape
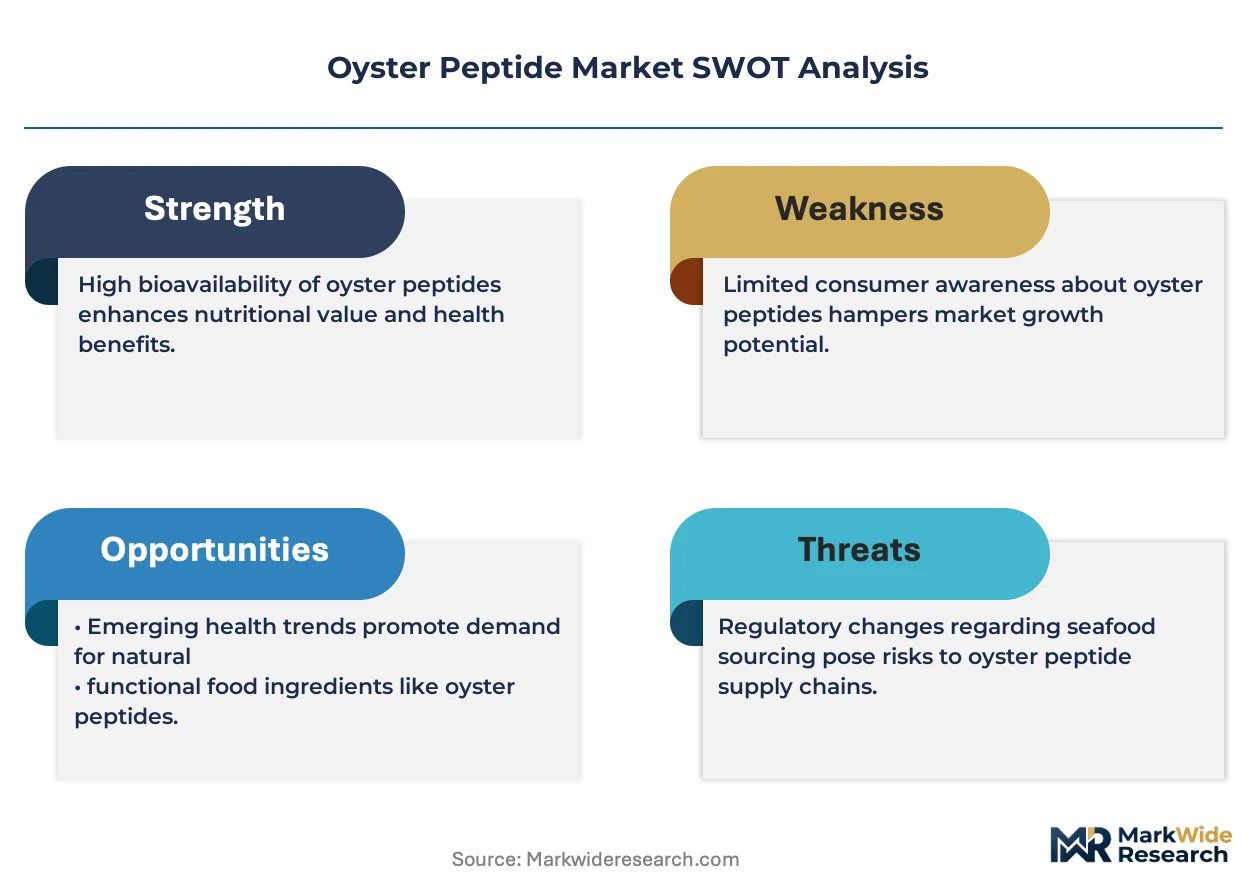
On the supply side, the industry is bifurcating between asset-light toll manufacturers with enzymatic capabilities and integrated processors with captive aquaculture contracts. The vendor base spans three strategic archetypes: coastal hydrolysis specialists leveraging proximity to Crassostrea sourcing, cold-chain marine operators commanding premium positioning through refrigerated distribution control, and precision fermentation entrants substituting plant-derived alternatives. Competitive dynamics center on ISO certification acquisition for China export access and membrane filtration technology licensing for molecular weight standardization.
Among Chinese biotech specialists, Hubei Nutratide biotech Co., Ltd and Zhongshi Duqing (Shandong) Biotech Co., Ltd exemplify the coastal hydrolysis archetype with enzymatic capabilities concentrated in Shandong province. Maruha Nichiro Corporation occupies a position representing Japanese cold-chain marine sourcing with premium market anchoring. Seagarden Group AS represents Nordic freeze-dried format specialization with pharmacy channel penetration across Scandinavian professional healthcare retail.
| Leading Market Players |
|---|
| SmartPEP |
| Huzhou Purestar Biochem Co., Ltd |
| Xuchang Shangke Chemical Co., Ltd |
| Hubei Nutratide biotech Co., Ltd |
| Zhongshi Duqing (Shandong) Biotech Co., Ltd |
| Maruha Nichiro Corporation |
| Fujifilm Wako Pure Chemical Corporation |
| Seagarden Group AS |
| XI AN CHEN LANG BIO TECH |
| Others |
Pricing and Supply Chain Analysis
Shandong and Zhejiang coastal processing clusters concentrate enzymatic hydrolysis capacity for Crassostrea sourcing, anchoring margin capture downstream among toll manufacturers with ISO 22000 credentials and certificate-of-analysis continuity. This upstream density enables premium positioning for exporters navigating China's SAMR registration tightening while compressing spot-market pricing for uncertified commodity peptide traders.
Pricing Analysis
Certification level creates the primary spread between premium and commodity tiers, with ISO 22000 and HACCP credentials commanding 15-25% premiums in cross-border e-commerce channels. Pricing stratifies across FOSHU-compliant documentation grades, standard nutraceutical inputs, and uncertified bulk powder. Cost compression in mid-tier functional beverage bases is intensifying because fermented plant proteins are capturing share. Nutraceutical formulators in Japan show least price sensitivity due to FOSHU efficacy documentation requirements, while commodity traders in spot markets face acute margin pressure.
Supply Chain Analysis
Tariff exposure between China and EU markets dominates supply chain risk planning for Asian exporters targeting EFSA novel food consultations. Geographic concentration centers on China, Japan, and South Korea for enzymatic hydrolysis infrastructure, with Nordic markets dependent on freeze-dried imports. Raw material dependencies include wild Crassostrea harvests, specialized protease enzymes, and pharmaceutical-grade gelatin for capsule formats. Distribution runs through pharmacy channels in Scandinavian markets, direct supplier relationships in Japan, and cross-border e-commerce platforms for Chinese exporters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oyster peptide markets sit in early-cycle expansion as FOSHU framework broadening and marine-derived cosmetic actives penetration create dual tailwinds for standardized bioactive fractions. Convenience-format liquid SKUs and professional pharmacy channel positioning represent underexploited penetration vectors with multi-year runway.
For Market Incumbents: Pre-empt precision fermentation entrants by securing captive aquaculture contracts for Crassostrea supply stability and accelerating membrane filtration technology licensing for sub-10 kDa standardization. Cold-chain marine sourcing from Japanese coastal waters and enzymatic hydrolysis talent retention constitute priority defensive levers against plant protein substitution in functional beverage bases.
For New Entrants and Emerging Players: Nordic pharmacy channel white space for freeze-dried immune-support SKUs represents the most penetrable entry point, with Swedish and Norwegian retailers expanding professional healthcare retail shelf space. Ready-to-drink liquid formats in Japanese convenience retail offer secondary attack vector. Go-to-market angle should leverage third-party ISO certification arbitrage for cross-border e-commerce premium positioning.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed coastal hydrolysis specialists in Shandong province lacking integrated testing laboratories. Long-term viability hinges on REACH-aligned documentation capabilities and multi-year supply agreement anchoring with Japanese nutraceutical formulators. Signal to watch is EFSA novel food ruling velocity for marine-derived peptide categories.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 22000 Certification Acquisition | Creates competitive separation for Chinese exporters navigating SAMR registration tightening and cross-border e-commerce premium positioning. |
| Continuous Tangential Flow System Adoption | Compresses capital intensity per kilogram output while improving taurine retention consistency for Japanese toll manufacturers. |
| Captive Crassostrea Aquaculture Contracting | Insulates processors from wild harvest volatility in East Asian coastal waters and secures input cost stability. |
| Pharmacy Channel Partnership Expansion | Captures unmet demand for freeze-dried formats in Swedish and Norwegian professional healthcare retail. |
| Cosmetic-Grade Peptide Isolate Development | Addresses Korean derma brand reformulation demand and REACH-aligned substance registration requirements. |
Research Methodology
Initial hypotheses were tested against primary input from enzymatic hydrolysis specialists, nutraceutical formulators, cosmetic R&D directors, and pharmacy procurement managers, then refined through secondary validation. Bottom-up triangulation incorporated trade customs data, SAMR health-food registration filings, FOSHU approval databases, and EFSA novel food consultation records. Top-down cross-checks applied macro peptide demand indicators from nutraceutical and marine-derived actives sectors.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning product format, application end-use, and molecular weight threshold. CAGRs derived from historical trajectory analysis and adoption curve modeling for convenience-format liquid SKUs. Industry-specific inputs included FOSHU claim expansion velocity, GB standard enforcement variance across Chinese provinces, and enzymatic hydrolysis capacity buildout timelines.
Macroeconomic conditions sit as an overlay; deviation in coastal aquaculture yields, marine protein commodity pricing, or East Asian trade policy would shift the trajectory. Forecasts reflect documented assumptions on regulatory pathway durations and bioactive fraction standardization adoption. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Dark Yeast Extract Market
Ingredients
South America Soy Protein Ingredients Market
Ingredients
Icing Shortening Market
Ingredients
Hydrolyzed Starch Market
Ingredients
Algae-Based Ingredients Market
Ingredients
North America and Europe Coconut Derivatives Market
Ingredients
Sodium Reduction Ingredients Market
Ingredients
Fiber Rich Flours Market
Ingredients
Africa Fats and Oil Market
Ingredients
Roll-Dried Starch Market
Ingredients
Eucalyptus Oil Market
Ingredients
Aroma Ingredients Market
Ingredients
Botanical Extracts Market
Ingredients
Meat Starter Culture Market
Ingredients
Karaya Gum Market
Ingredients
Middle East and Africa Dairy Protein Ingredients Market