
 Cold-Pressed Coconut Oil Market | 2026-2036
Cold-Pressed Coconut Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Cold-Pressed Coconut Oil Market Outlook
EU REACH regulation on solvent residues in cosmetic-grade oils is hardening quality thresholds for imports into Europe. Nutiva Inc. leverages its certified organic supply chain to sustain premium positioning across North American natural retail channels. Dabur India Ltd anchors its Ayurvedic portfolio with in-house cold-pressed oil extraction in Rajasthan and Himachal Pradesh.
Cold-pressed coconut oil denotes mechanically extracted endosperm oil from mature Cocos nucifera kernels processed below 49 degrees Celsius, preserving medium-chain triglyceride profiles and native antioxidant compounds for food, cosmetic, and therapeutic applications. Organic product type commands margin premiums due to certification complexity and limited hectarage, while unrefined grades retain polyphenol content valued by nutraceutical formulators. Glass bottle packaging dominates premium cosmetic channels, whereas pouches expand penetration in South Asian mass-market food segments.
FDA food-contact substance notifications and USDA organic certification govern US market access, while India's FSSAI mandates solvent-free labeling for cold-pressed claims on domestic retail packs. BIS standards for edible coconut oil in India further delineate pressing temperature limits and free fatty acid thresholds. Stakeholders must monitor evolving EU EFSA novel food opinions on lauric acid health claims, as these will determine permissible marketing language across export destinations and directly influence R&D investment priorities.
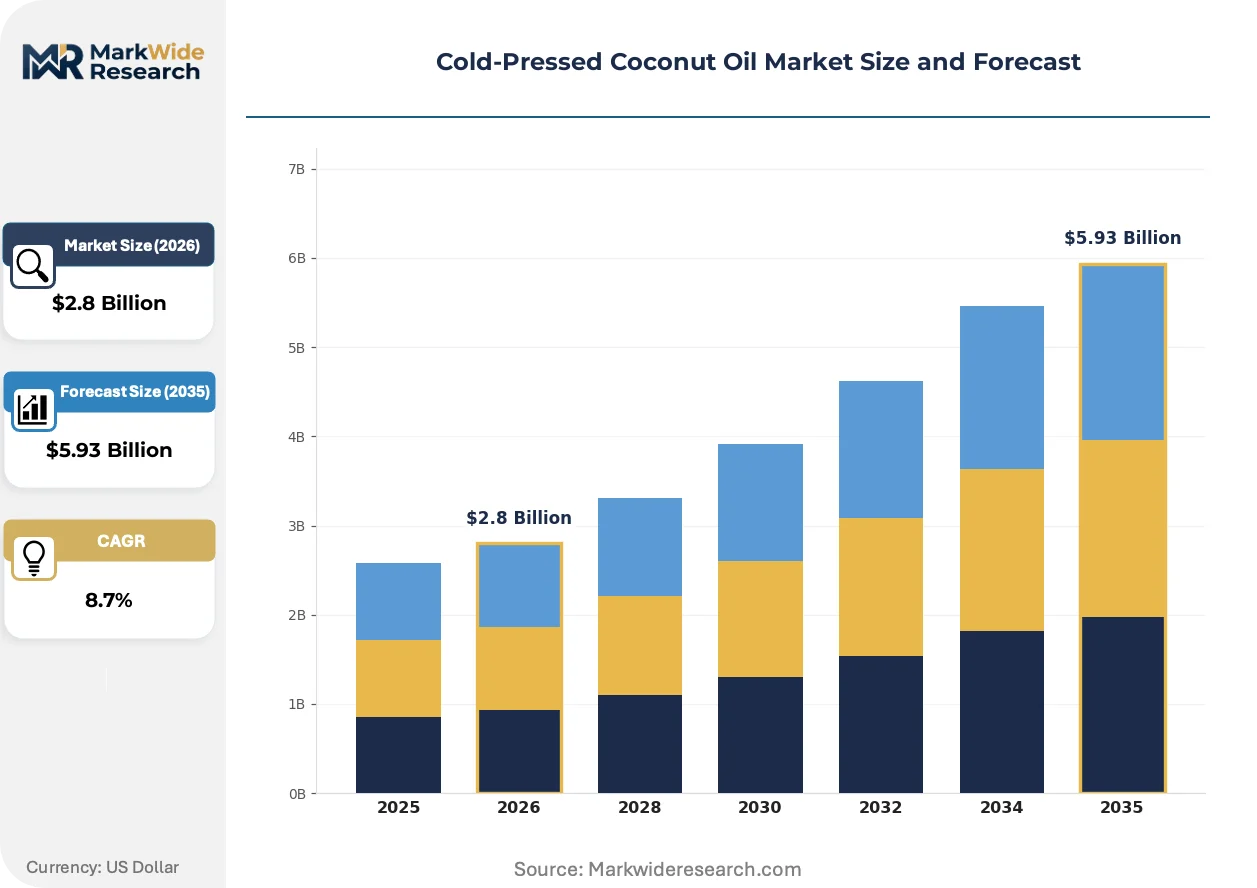
Market Dynamics
Mechanical pressing below 49 degrees Celsius is absorbing capital investment as REACH-compliant extraction methods displace solvent-based alternatives in European cosmetic supply chains. Kerala and Tamil Nadu processing clusters now dictate global availability of organic-grade feedstock.
Growth Catalysts
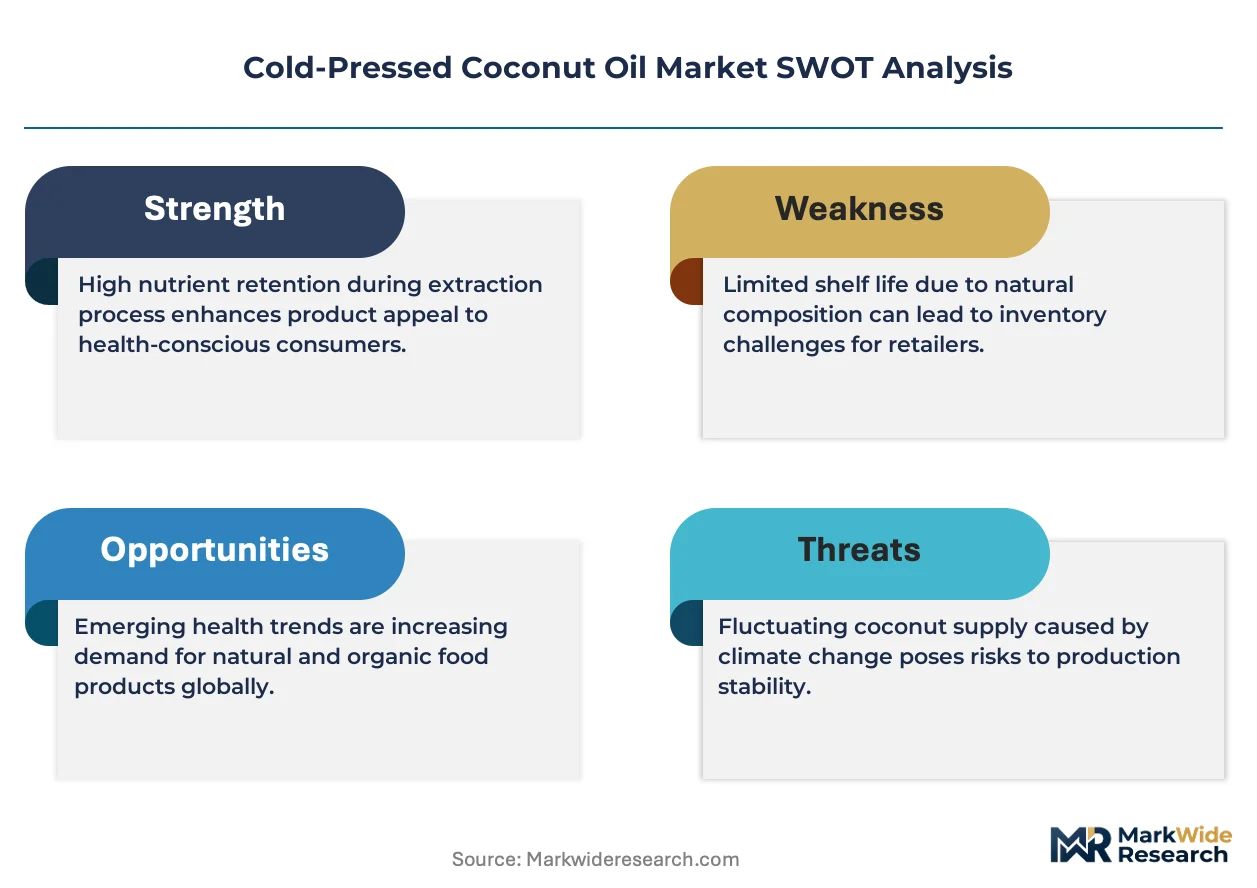
- EU REACH solvent restrictions:ECHA enforcement redirects cosmetic manufacturers toward mechanical-only pressing methods, tightening import quality thresholds and favoring certified organic supply chains.
- Ayurvedic nutraceutical formulators:India's domestic wellness brands are scaling cold-pressed oil procurement for polyphenol-retentive therapeutic applications.
- Clean-label cosmetic R&D:Personal care multinationals are reformulating around native antioxidant preservation in unrefined grades.
Market Restraints
- Copra input cost volatility:Weather-dependent harvests in Kerala and Tamil Nadu create margin compression for mechanical processors.
- Organic certification complexity:Limited certified hectarage and multi-year conversion timelines constrain premium-grade supply expansion.
- Refined oil substitution:Heat-processed alternatives at lower price points capture mass-market food applications in South Asian retail.
Strategic Opportunities
- North American natural retail channels:Certified organic positioning commands shelf-space premiums in specialty grocery and direct-to-consumer segments.
- Glass bottle cosmetic packaging:Premium personal care brands are migrating from plastic to pharmaceutical-grade glass for oxidative stability.
- FSSAI solvent-free labeling:India's domestic mandate creates first-mover advantage for mechanical processors in regulated retail packs.
Industry Challenges
- Skilled equipment operation:Temperature-controlled pressing requires trained technicians scarce in emerging processing regions.
- Multi-jurisdiction certification timelines:USDA organic, EU organic, and India Organic logos demand parallel audit tracks extending 18-24 months.
- Legacy solvent infrastructure conversion:Existing extraction facilities face capex barriers to mechanical retooling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold-Pressed Coconut Oil Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Conventional, Refined, Unrefined Application: Cosmetics, Food Industry, Nutraceuticals, Personal Care Packaging Type: Glass Bottles, Plastic Containers, Metal Cans, Pouches Distribution Channel: Online Retail, Hypermarkets, Specialty Stores, Supermarkets |
| Companies Covered | Nutiva Inc., Gramiyum, FreshMill Oils, Nature's Way Brands, NOW Health Group, Inc., Garden of Life, Spectrum Organic Products LLC, Dabur India Ltd, Vama Oil Private Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold-Pressed Coconut Oil Market Strategic Shifts
Low-temperature mechanical extraction is absorbing innovation investment as antioxidant preservation becomes a specification battleground. Three developments are compressing competitive timelines.
Continuous screw pressing with jacketed cooling is absorbing R&D focus from batch hydraulic systems. Cosmetic formulators in France and Germany are specifying this equipment for lauric acid profile consistency. The technology is absorbing market share from centrifugal methods by reducing oxidation markers below 2 meq O2/kg.
EFSA novel food opinions on lauric acid health claims are forcing marketing language revisions across export destinations. Nutraceutical brands are preemptively reformulating label claims pending 2025 guidance. The regulatory uncertainty is absorbing compliance resources most intensively in German and Dutch import channels.
Direct farm-gate procurement is compressing traditional broker intermediation in Kerala's coconut belt. Ayurvedic manufacturers are signing multi-year offtake agreements with Tamil Nadu cooperatives. This pattern is absorbing volume most rapidly in domestic Indian nutraceutical supply chains.
Cold-Pressed Coconut Oil Market Segmentation
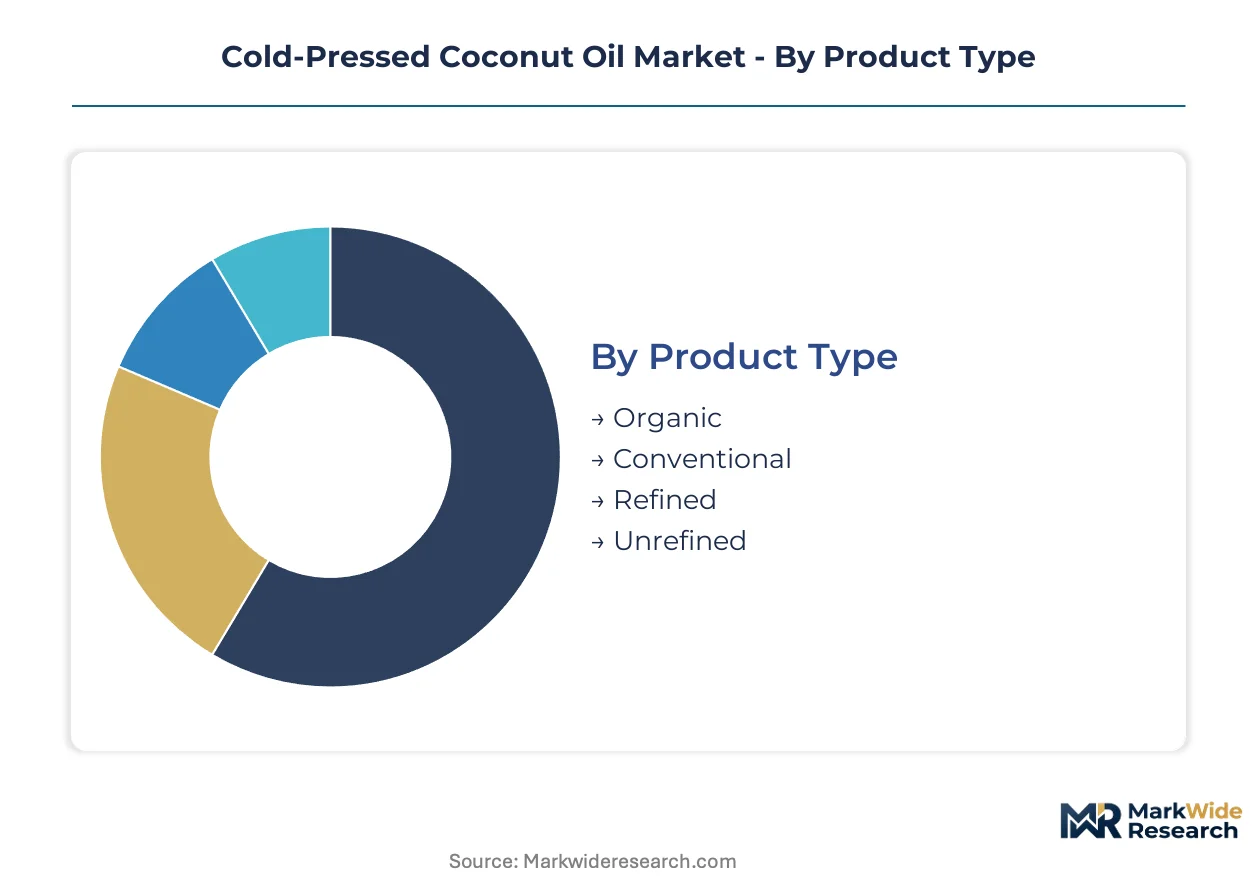
Cold-pressed coconut oil markets fragment across certification grades, end-use specifications, and channel formats that each demand distinct processing protocols and margin structures. Procurement decisions diverge sharply between cosmetic formulators prioritizing oxidative stability and food manufacturers optimizing per-unit extraction yields.
Product Type:
Certification complexity creates a steep value gradient from commodity-grade conventional supply to multi-audit organic chains with 18-24 month conversion timelines.
- Organic:USDA, EU organic, and India Organic logos require parallel audit tracks and limited certified hectarage in Kerala and Tamil Nadu. Ayurvedic nutraceutical brands in India absorb the majority of certified organic volume for polyphenol-retentive therapeutic formulations.
- Unrefined:Native antioxidant compounds preserved through mechanical pressing below 49 degrees Celsius command shelf-space premiums in North American natural retail channels. Cosmetic R&D teams specify unrefined grades for clean-label reformulations targeting ECHA REACH compliance.
- Conventional:Standard mechanical pressing without organic certification serves mass-market food applications where price elasticity dominates procurement.
- Refined:Heat-processed alternatives at lower price points capture South Asian retail segments where oxidative stability exceeds native compound preservation in purchase criteria.
Most installed capacity flows through Conventional. Expansion is steepest in Organic.
Application:
End-use specifications range from pharmaceutical-grade lauric acid profiles to bulk food-service volumes with relaxed free fatty acid thresholds.
- Cosmetics:ECHA REACH solvent restrictions redirect European personal care multinationals toward mechanical-only pressing methods with sub-2 meq O2/kg oxidation markers. Glass bottle packaging dominates premium cosmetic channels for oxidative stability.
- Nutraceuticals:India's domestic wellness brands scale cold-pressed oil procurement for medium-chain triglyceride therapeutic applications. EFSA novel food opinions on lauric acid health claims force preemptive label claim revisions across German and Dutch import channels.
- Food Industry:FSSAI solvent-free labeling mandates in India create first-mover advantage for mechanical processors in regulated retail packs.
- Personal Care:Direct-to-consumer segments in North America absorb certified organic positioning through specialty grocery and e-commerce channels.
Cosmetics commands the highest per-kilogram realized prices. Nutraceuticals is gaining share fastest.
Packaging Type:
Material selection tracks oxidative sensitivity and channel positioning across pharmaceutical-grade glass to flexible film formats.
- Glass Bottles:Pharmaceutical-grade glass migration from plastic dominates premium personal care brands seeking oxidative stability for lauric acid profile consistency.
- Pouches:Flexible film expands penetration in South Asian mass-market food segments where unit economics favor lightweight distribution.
- Plastic Containers:HDPE and PET formats serve mid-tier food retail with barrier properties sufficient for 12-month shelf life.
- Metal Cans:Tinplate and aluminum containers address industrial food-service volumes with puncture resistance and stackability.
Glass Bottles anchor premium positioning. Pouches is expanding most quickly.
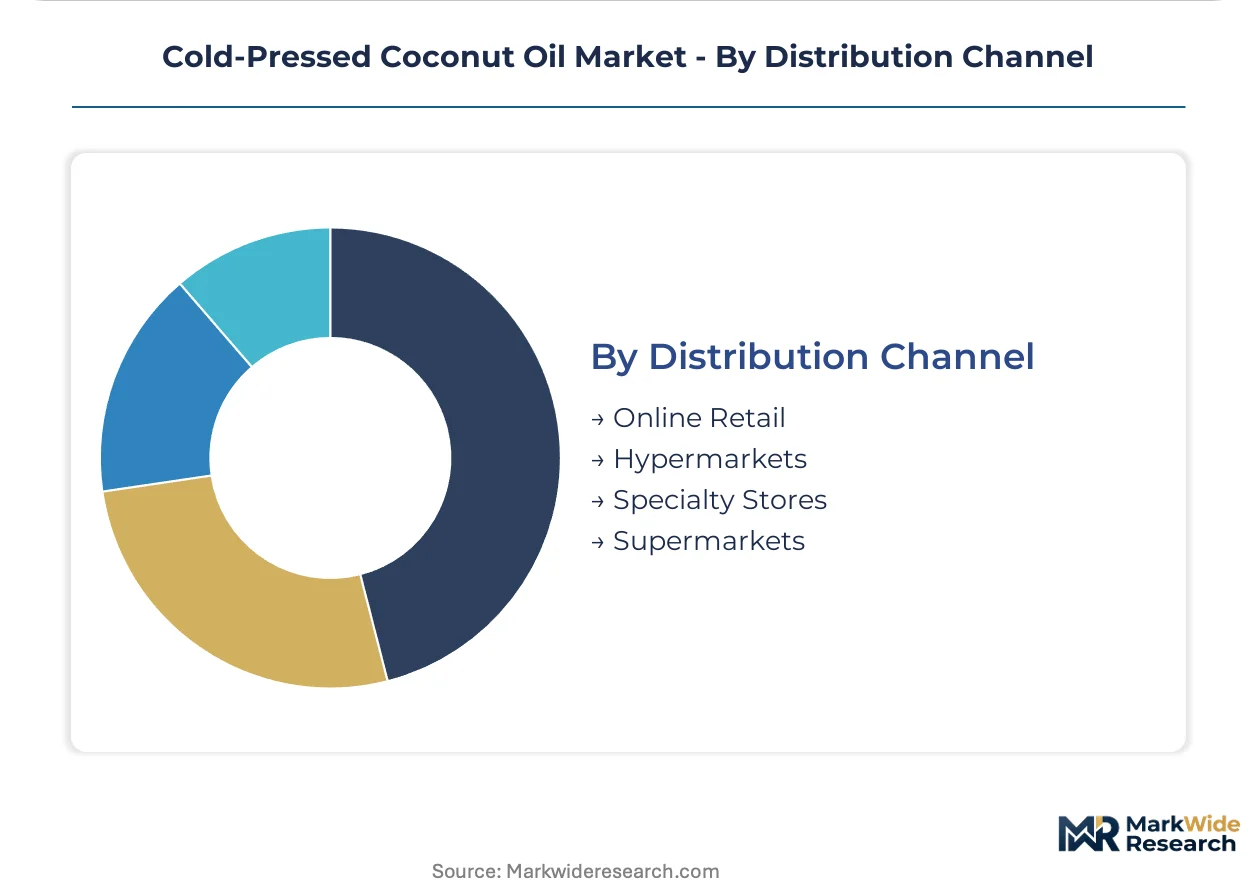
Distribution Channel:
Channel mix reflects certification tier and purchase frequency from high-touch specialty retail to automated replenishment.
- Specialty Stores:Natural retail channels in North America command shelf-space premiums for certified organic positioning with trained staff consultation.
- Online Retail:Direct-to-consumer segments absorb subscription-based replenishment for Ayurvedic nutraceutical brands with multi-year offtake agreements.
- Hypermarkets:Big-box formats capture conventional-grade volume through centralized procurement and private-label programs.
- Supermarkets:Mainline grocery distributes mid-tier unrefined grades to household consumers with FSSAI-compliant solvent-free labeling.
Specialty Stores concentrate premium throughput. Online Retail shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cold-pressed coconut oil processing originated in Kerala's coastal belt, where traditional wooden presses evolved into temperature-controlled mechanical systems. India now supplies both domestic Ayurvedic brands and export-oriented cosmetic multinationals from this historical foundation.
India
Ayurvedic nutraceutical brands in Maharashtra and Karnataka drive domestic absorption of certified organic grades. FSSAI mandates solvent-free labeling for cold-pressed claims, tightening retail compliance. Kerala's Alappuzha and Kollam clusters host mechanical pressing facilities serving European cosmetic supply chains.
United States
Natural retail channels in California and the Pacific Northwest absorb premium organic positioning through specialty grocers. FDA food-contact substance notifications govern import thresholds for cosmetic-grade oils. Hawaiian processing cooperatives supply domestic nutraceutical formulators with polyphenol-retentive unrefined grades.
Germany
Personal care multinationals in Hamburg and Düsseldorf specify sub-2 meq O2/kg oxidation markers for lauric acid profile consistency. ECHA REACH enforcement redirects procurement toward mechanical-only pressing methods. Bavarian import distributors manage EU organic certification verification for Asian supply chains.
Netherlands
Rotterdam's port infrastructure handles bulk organic feedstock redistribution across continental Europe. EFSA novel food opinions on lauric acid health claims force preemptive label revisions among Dutch nutraceutical importers. Amsterdam-based cosmetic R&D labs specify continuous screw pressing equipment for antioxidant preservation.
Australia
Queensland's tropical coast hosts emerging mechanical pressing operations targeting Asian export markets. TGA therapeutic goods guidelines influence cosmetic-grade oil specifications for domestic personal care brands. Sydney and Melbourne specialty retailers command shelf-space premiums for certified organic glass-bottle formats.
Cold-Pressed Coconut Oil Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification complexity, with organic-grade suppliers capturing shelf-space premiums in North American natural retail while conventional processors compete on per-unit extraction yields in South Asian mass markets. The vendor base arranges into three tiers: integrated Ayurvedic brands with captive extraction, certified organic specialists with multi-audit supply chains, and regional mechanical processors serving domestic food retail. Competitive moves concentrate on backward integration into Kerala and Tamil Nadu feedstock sourcing, plus pharmaceutical-grade glass packaging migration for oxidative stability.
Among North American certified organic specialists, Nutiva Inc. and Garden of Life occupy positions exemplifying premium-tier positioning through multi-audit supply chain architecture. Dabur India Ltd represents the integrated Ayurvedic archetype with in-house extraction capacity. These three anchors illustrate how certification complexity and captive processing create defendable margin structures against commodity-grade competition.
| Leading Market Players |
|---|
| Nutiva Inc. |
| Gramiyum |
| FreshMill Oils |
| Nature's Way Brands |
| NOW Health Group, Inc. |
| Garden of Life |
| Spectrum Organic Products LLC |
| Dabur India Ltd |
| Vama Oil Private Limited |
| Others |
Value Chain & Pricing Dynamics
Family-owned processing cooperatives in Kerala and Tamil Nadu anchor supply-side discipline, converting weather-dependent copra harvests into tiered pricing power through multi-year offtake agreements with Ayurvedic manufacturers. This ownership pattern concentrates bargaining leverage upstream while downstream cosmetic multinationals absorb organic-grade premiums dictated by ECHA REACH compliance timelines.
Pricing Analysis
Three-tier pricing structure across premium organic, certified unrefined, and conventional mechanical grades separates procurement tiers by certification complexity and oxidation marker thresholds. Price differentiation rests on USDA organic audit tracks versus FSSAI solvent-free labeling compliance, with glass-bottle cosmetic channels commanding shelf-space premiums over pouch-format food retail. Cost compression in conventional grades is intensifying because refined oil substitution captures South Asian mass-market volume. Contract food-service buyers exhibit highest price sensitivity, while European cosmetic formulators prioritize sub-2 meq O2/kg specification adherence over per-unit cost.
Supply Chain Analysis
Copra feedstock supply rests on Kerala and Tamil Nadu harvest cycles, with secondary sourcing from Sri Lankan and Indonesian coastal belts during Indian monsoon shortfalls. Raw material dependencies include mature Cocos nucifera kernel availability, pharmaceutical-grade glass bottle procurement, and continuous screw pressing equipment with jacketed cooling systems. Single-source vulnerability concentrates in Kerala's Alappuzha cluster, where mechanical pressing capacity serves both domestic Ayurvedic brands and European cosmetic supply chains. Distribution runs through Rotterdam bulk redistribution for continental Europe, direct farm-gate procurement compressing broker intermediation, and North American specialty retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with ECHA REACH solvent restrictions and FSSAI labeling mandates simultaneously constraining supply-side capacity and accelerating demand from clean-label cosmetic and nutraceutical formulators.
For Market Incumbents: Anticipate margin compression from emerging mechanical processors in Queensland and emerging Indian states by securing multi-year organic copra offtake agreements before hectarage conversion timelines lengthen. Certification investment represents the priority defensive lever, as parallel USDA-EU-India Organic audit tracks extending 18-24 months create captive supply advantages against late entrants. Channel control through direct-to-consumer subscription platforms reinforces pricing power against hypermarket private-label encroachment. For New Entrants and Emerging Players: Enter via Queensland's tropical coast processing capacity targeting Asian export markets underserved by Kerala supply concentration. The most penetrable white-space sits in Australian TGA-compliant therapeutic-grade oil for domestic personal care brands, with glass-bottle cosmetic packaging migration offering differentiation against incumbent plastic formats. A farm-gate procurement go-to-market angle compresses traditional broker margins while securing polyphenol-retentive feedstock consistency. For Investors and Strategic Acquirers: Integrated Ayurvedic brands with captive extraction capacity are the most active acquirer in this space, consolidating regional mechanical processors to secure REACH-compliant supply chains. Long-term viability over a 5-10 year window hinges on backward integration into certified organic hectarage rather than toll-processing dependence. The signal to watch is EFSA novel food opinion finalization on lauric acid health claims, which will determine permissible marketing language and R&D investment prioritization across German and Dutch import channels.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Organic Hectarage | Multi-year conversion timelines in Kerala and Tamil Nadu lock in feedstock security against REACH-compliant demand surges. |
| Continuous Screw Pressing Equipment Migration | Jacketed cooling systems reduce oxidation markers below 2 meq O2/kg for French and German cosmetic formulator specifications. |
| Pharmaceutical-Grade Glass Packaging Transition | Cosmetic brands migrate from plastic to glass bottles for lauric acid profile stability in premium personal care channels. |
| Direct Farm-Gate Procurement Agreements | Tamil Nadu cooperatives bypass broker intermediation through multi-year offtake contracts with Ayurvedic manufacturers. |
| FSSAI Solvent-Free Labeling Compliance | India's domestic mandate creates first-mover shelf-space advantage for mechanical processors in regulated retail packs. |
Study Parameters
Bottom-up Ayurvedic nutraceutical and cosmetic formulation modeling reconciled against top-down mechanical pressing capacity tracking forms the analytical core of this study. Primary interviews with extraction facility technicians, procurement leads at European personal care multinationals, FSSAI regulatory compliance officers, and Kerala cooperative managers combined with secondary validation from ECHA enforcement bulletins, EU organic certification databases, FSSAI labeling directives, and Indian customs export records. This dual-layer approach triangulates volume estimates against installed screw press and hydraulic system capacity across Kerala, Tamil Nadu, and emerging Queensland operations.
Historical trendline analysis of organic certification conversion rates, copra harvest yield variability, and cosmetic-grade oil import flows into Rotterdam and Hamburg established baseline growth parameters. Segmentation dimensions modeled include certification grade, end-use application, packaging material, and distribution channel complexity, with CAGRs derived from slope analysis of mechanical pressing investment absorption and REACH-driven supply chain redirection. Industry-specific forecast inputs incorporate EFSA novel food opinion timelines and Ayurvedic brand procurement scaling patterns.
Inputs from ECHA enforcement databases and Kerala cooperative export declarations were available through the study window; gaps in Queensland emerging processor capacity utilization introduce uncertainty bands around Asia-Pacific supply projections. Forecasts reflect documented assumptions regarding organic hectarage expansion timelines and lauric acid health claim regulatory resolution, with copra weather volatility and multi-jurisdiction certification audit backlogs representing specific revision triggers. A small set of named triggers—EFSA opinion finalization, FSSAI labeling enforcement intensity, and Queensland mechanical pressing commissioning rates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Asia-Pacific Soy Protein Market
Ingredients
Vegetable Powder Market
Ingredients
Grapeseed Oil Market
Ingredients
North America Soy Protein Concentrate Market
Ingredients
Global Starch Derivatives Market
Ingredients
Cooking Oil Market
Ingredients
Animal and Marine Fats and Oils Market
Ingredients
Fermentation Ingredient Market
Ingredients
Canada Whey Protein Ingredients Market
Ingredients
Mannan-Oligosaccharide (MOS) Market
Ingredients
Yeast Flakes Market
Ingredients
Barley Flake Market
Ingredients
Sodium Caseinate Market
Ingredients
Black Seed Oil Market
Ingredients
Chickpea Fiber Market
Ingredients
Citrus Based Dietary Fibers Market