
 Biotin Supplement Market | 2026-2036
Biotin Supplement Market Size, Share, and Industry Trends Forecast 2026-2036
Biotin Supplement Market Analysis
Multi-source ingredient procurement is hardening as a competitive necessity for biotin supplement manufacturers seeking supply resilience against raw material volatility. NOW Foods leverages vertical integration across its Nevada manufacturing campus to control quality from fermentation through finished tablet production. Solgar sustains its premium positioning through pharmaceutical-grade biotin sourcing protocols that exceed USP standards. Natrol competes aggressively in the gummy segment through proprietary flavor-masking technologies that mask biotin's characteristic sulfur notes.
Biotin, also known as vitamin B7 or coenzyme R, functions as a water-soluble cofactor for carboxylase enzymes essential in fatty acid synthesis and amino acid metabolism; commercial production relies primarily on microbial fermentation using genetically optimized strains of Serratia marcescens or Bacillus subtilis, yielding USP-grade material at purity thresholds exceeding 99.5 percent. The gummy format commands disproportionate margin pools as consumers prioritize palatability over unit cost, while plant-based ingredient sourcing anchors premium positioning as clean-label expectations intensify. Online retail channels represent the fastest-growing distribution vector, though pharmacies retain defensive value for clinical-grade formulations targeting diagnosed deficiency populations.
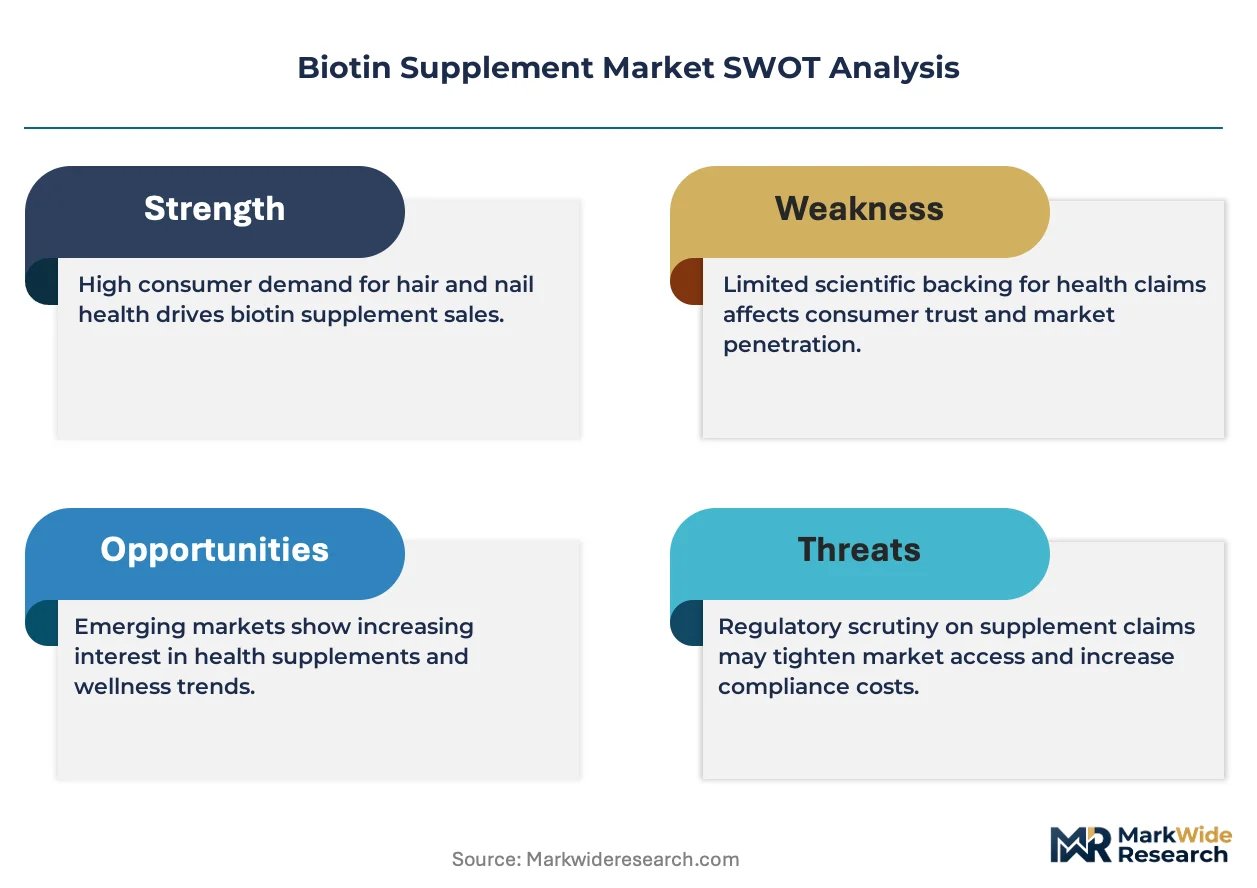
FDA's Current Good Manufacturing Practice regulations for dietary supplements enforce identity, purity, strength, and composition standards that elevate compliance costs for new market entrants. USP verification programs and NSF International certification create tiered quality signaling that shapes consumer trust and retail access decisions. Stakeholders must monitor evolving state-level ingredient disclosure mandates and synthetic biology regulatory frameworks that could redefine acceptable production methodologies.
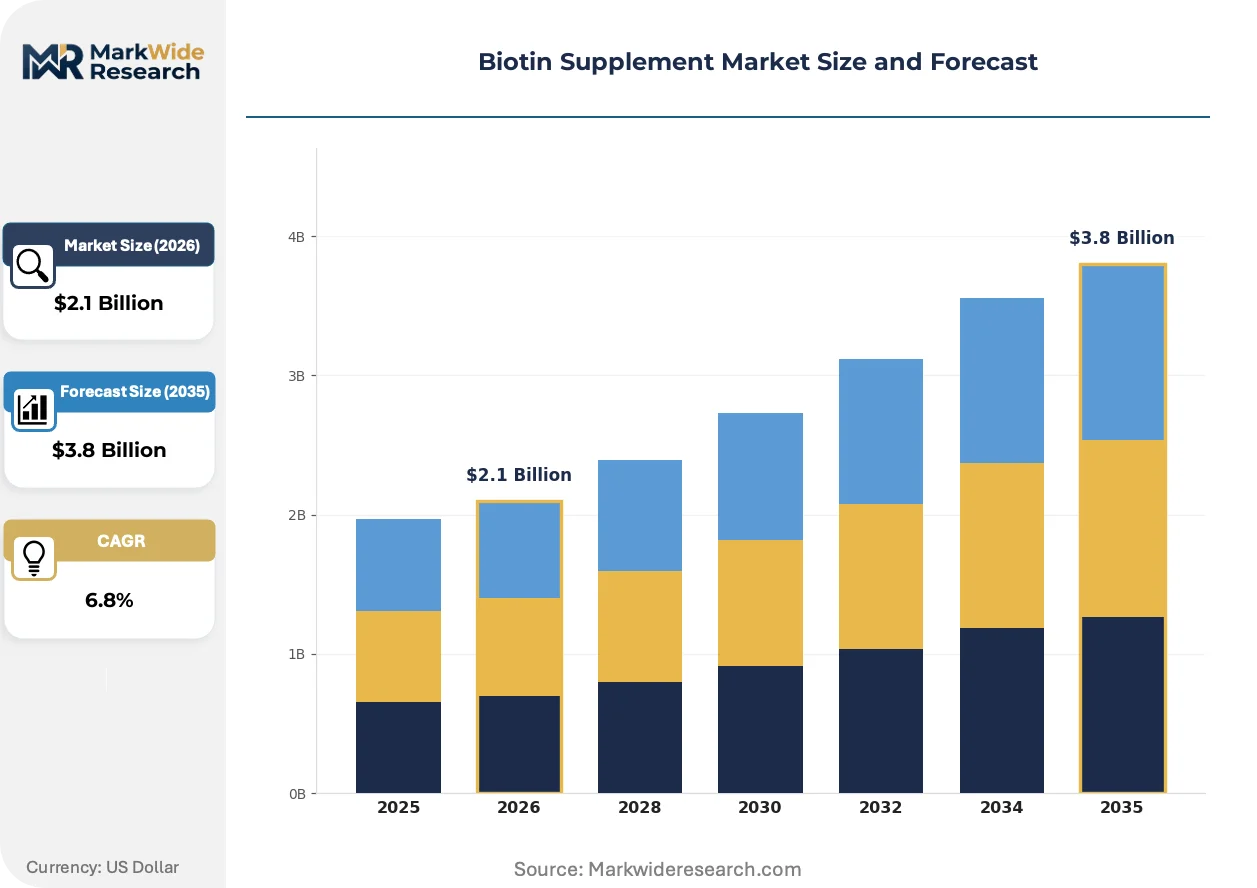
Market Dynamics
Clean-label certification wars are restructuring competitive advantage in biotin supplements, as third-party verification programs from USP and NSF International separate shelf-access winners from commodity suppliers in retail pharmacy and e-commerce channels.
Growth Catalysts
- Gen-Z hair wellness spending:Younger consumers allocate discretionary income toward preventive beauty nutrition, expanding the addressable base beyond diagnosed deficiency populations into lifestyle supplementation.
- FDA CGMP enforcement:Stricter identity and purity audits elevate barriers for informal importers, consolidating shelf space among compliant domestic manufacturers with verified supply chains.
- Fermentation yield optimization:CRISPR-edited Bacillus subtilis strains are cutting production cycle times and raw material waste in microbial biotin synthesis.
Market Restraints
- D-chiro-inositol substitution:PCOS-focused supplements featuring inositol complexes are capturing overlapping hair-health positioning at lower price points in women's health aisles.
- Chinese fermentation capacity concentration:Over 70 percent of USP-grade biotin API originates from Zhejiang and Shandong province facilities, creating geographic supply vulnerability.
- DSHEA labeling ambiguity:Structure-function claim limitations prevent manufacturers from communicating specific dermatological efficacy, compressing differentiation space.
Strategic Opportunities
- India pharmacy modernization:Organized retail chains and e-pharmacy platforms are professionalizing supplement distribution in tier-2 cities previously served by fragmented general trade.
- Synthetic biology regulatory clarity:Pending FDA guidance on precision-fermented ingredients could unlock novel production pathways with enhanced sustainability credentials.
- Subscription personalization:Direct-to-consumer platforms integrating hair mineral analysis and microbiome testing are creating stickier replenishment models than transactional retail.
Industry Challenges
- Flavor-masking R&D bottlenecks:Biotin's sulfur-containing structure resists conventional sweetener systems, requiring specialized encapsulation expertise that concentrates among a handful of gummy specialists.
- Cross-border e-commerce compliance:Divergent maximum permitted biotin levels between FDA, EFSA, and TGA jurisdictions create inventory fragmentation for global direct-to-consumer brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biotin Supplement Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Gummies, Powders Ingredient Source: Plant-Based, Animal-Based, Synthetic, Organic Target Demographic: Women, Men, Children, Seniors Distribution Channel: Online Retail, Supermarkets, Health Stores, Pharmacies |
| Companies Covered | Nature's Bounty, Solgar, NOW Foods, Natrol, Nature Made, GNC, Goli Nutrition, OLLY, HUM Nutrition, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biotin Supplement Market Emerging Trajectories
Digital-native supplement brands are weaponizing supply chain transparency as a primary differentiation vector, converting fermentation traceability from compliance cost into consumer-facing storytelling assets.
Continuous fermentation monitoring using Raman spectroscopy and machine-learning feedback loops is automating real-time purity adjustments in bioreactor operations. Mid-scale contract manufacturers in North America and Western Europe are adopting these sensor arrays to reduce batch rejection rates and shorten release timelines. The technology is automating quality assurance labor previously performed by offline HPLC testing, compressing working capital requirements for finished goods inventory.
REACH registration requirements for novel fermentation-derived ingredients are tightening substance documentation obligations for European market entry. Manufacturers must now submit comprehensive toxicological dossiers for process-related impurities and genetic modification disclosure. Clinical-grade biotin positioned for pharmacy distribution faces the steepest compliance cost escalation, driving some suppliers toward cosmetic-grade positioning with relaxed purity claims.
Subscription bundling with complementary nutraceuticals is displacing single-SKU purchasing patterns among millennial and Gen-Z cohorts. Direct-to-consumer platforms are consolidating biotin with collagen peptides and zinc into hair-health kits, capturing higher basket values than standalone vitamin sales. This behavior shift is most pronounced in United States and United Kingdom markets where personalized wellness apps drive replenishment timing.
Biotin Supplement Market Segmentation
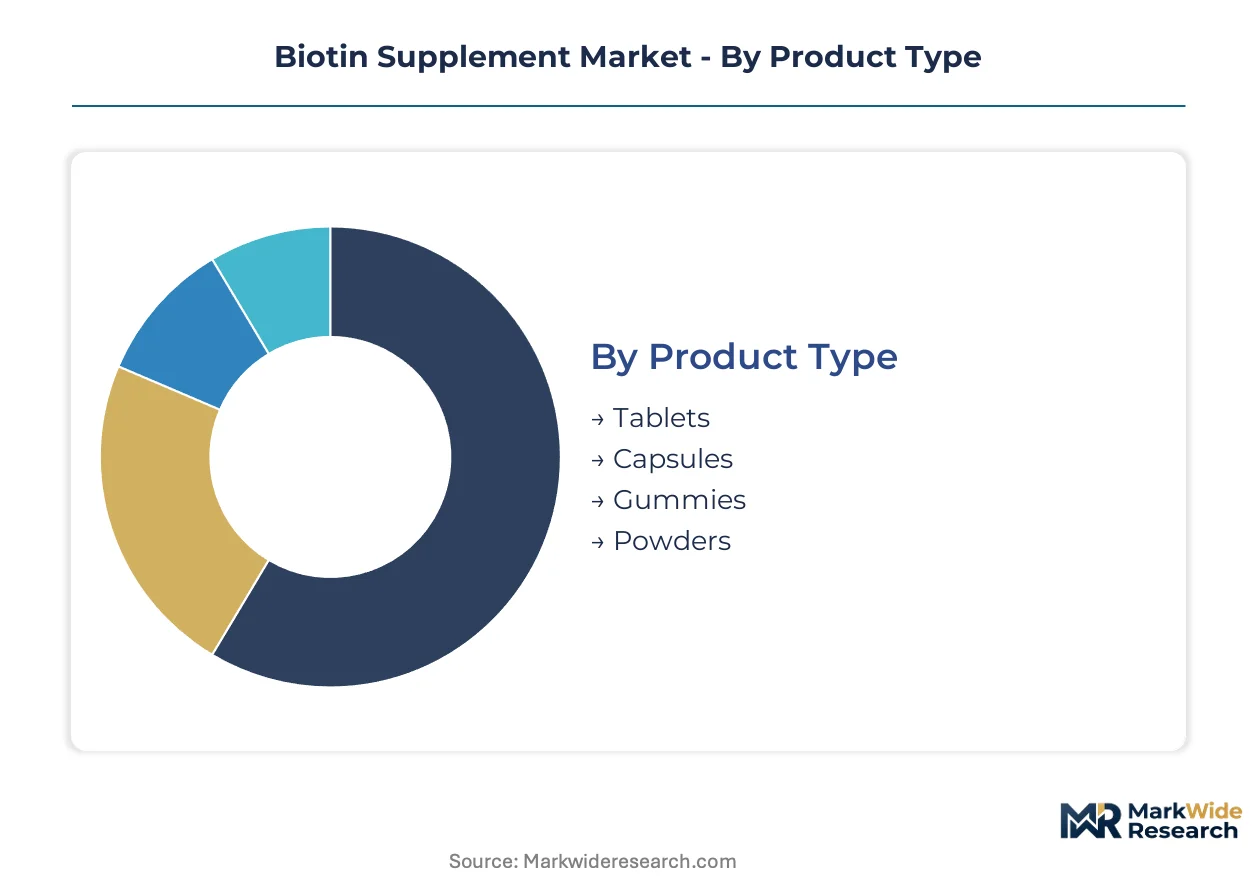
Biotin supplement segmentation reveals how format innovation and sourcing claims reshape margin capture across consumer touchpoints. Manufacturers configure product portfolios around palatability thresholds, clean-label premiums, and channel-specific compliance requirements.
Product Type:
Volume concentrates in legacy oral solids, yet margin pools have migrated toward palatable delivery systems that reduce compliance friction among non-deficiency users.
- Tablets:Compressed biotin with standard USP-grade excipients delivers cost-efficient unit economics for pharmacy and mass retail distribution. Demand clusters among diagnosed deficiency populations and price-sensitive replenishment buyers in United States and Germany, where insurance-adjacent purchasing favors clinical presentation formats.
- Gummies:Gelatin or pectin matrices suspend biotin alongside flavor-masking systems that neutralize sulfur off-notes, commanding 40-60% retail price premiums over tablets. Growth concentrates in millennial and Gen-Z cohorts across United States and United Kingdom direct-to-consumer channels, where subscription bundling with collagen and zinc amplifies basket values.
- Capsules:Hard-shell gelatin or vegetable cellulose enclosures protect biotin from moisture degradation during extended shelf life.
- Powders:Bulk biotin with minimal excipient load targets functional food integration and compounding pharmacy applications.
Today's leader: Tablets. Tomorrow's challenger: Gummies.
Ingredient Source:
Clean-label positioning has elevated sourcing transparency from supply chain detail to primary purchase driver, with certification costs stratifying competitive tiers.
- Synthetic:Microbial fermentation via CRISPR-optimized Bacillus subtilis yields USP-grade biotin exceeding 99.5% purity at industrial scale. Supply concentrates in Zhejiang and Shandong province facilities, creating geographic vulnerability that drives multi-sourcing mandates among North American and Western European finished goods manufacturers.
- Plant-Based:Biotin extracted from plant matrices or produced via precision fermentation using plant-derived feedstocks captures EFSA-aligned clean-label demand in France, Germany, and Netherlands retail channels.
- Animal-Based:Traditional extraction from organ tissues persists in niche clinical applications requiring documented biological origin.
- Organic:USDA or EU Organic certification restricts synthetic processing aids, limiting supplier pools and extending lead times.
Synthetic sources anchor current volume. Plant-based positioning gains fastest in premium tier.
Target Demographic:
Preventive beauty nutrition has expanded addressable demand beyond traditional deficiency populations into lifestyle supplementation across gender and age cohorts.
- Women:Hair and nail wellness positioning drives the largest absolute consumption, with PCOS-adjacent marketing capturing hormonal health adjacencies in United States and United Kingdom.
- Men:Beard growth and hair retention claims target emerging male grooming nutrition segments.
- Children:Pediatric formulations require flavor-optimized delivery and strict heavy metal testing protocols.
- Seniors:Cognitive and metabolic health positioning aligns biotin with B-complex supplementation for aging populations.
Women dominate current purchasing. Men represent the steepest expansion trajectory.
Distribution Channel:
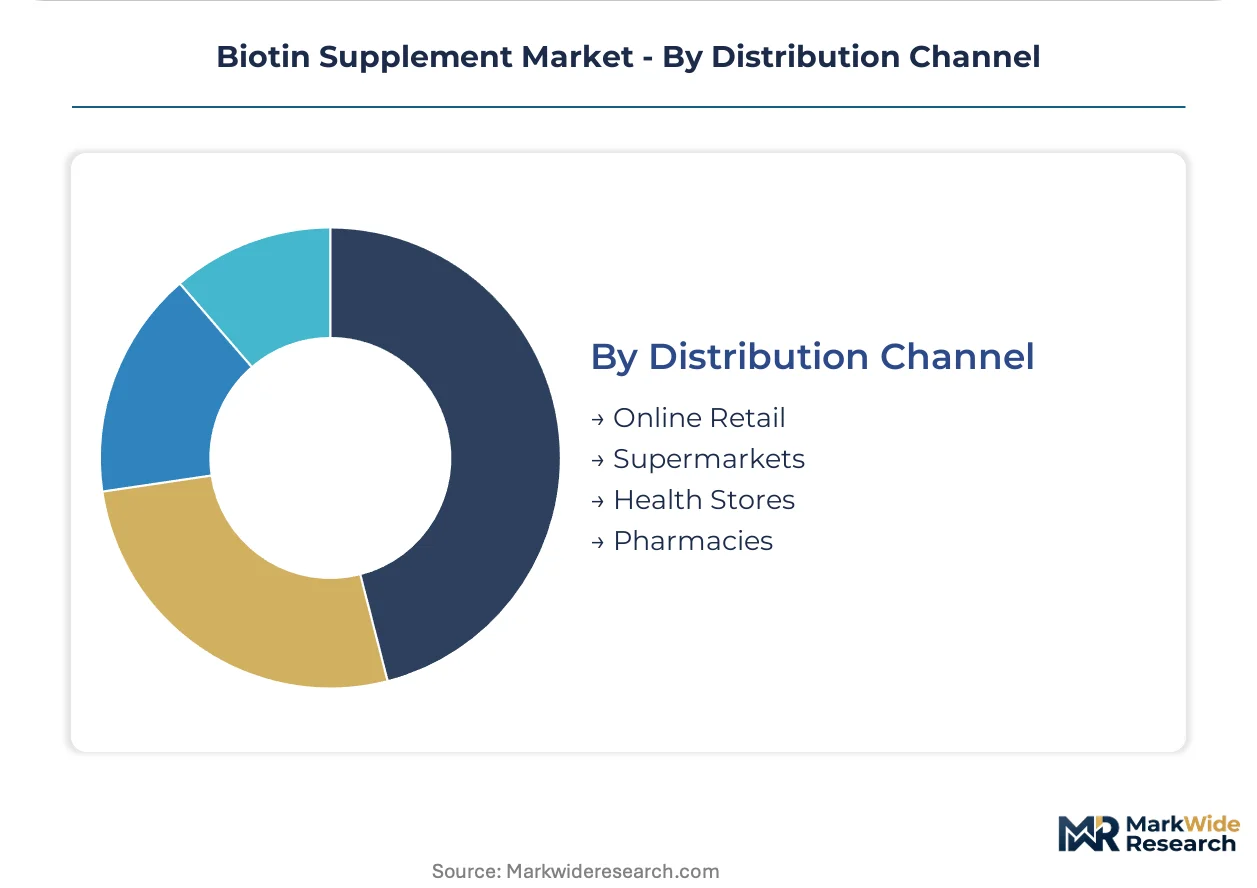
Channel selection determines regulatory exposure, margin structure, and consumer relationship depth for biotin brands.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators enable subscription personalization, hair mineral analysis integration, and rapid format experimentation. FDA CGMP compliance and state-level labeling mandates create compliance differentiation among domestic versus cross-border sellers.
- Pharmacies:Clinical-grade positioning with USP or NSF verification sustains defensive value for deficiency-diagnosed populations requiring pharmacist consultation.
- Supermarkets:Mass-market gummy and tablet SKUs compete on shelf placement and promotional velocity.
- Health Stores:Specialty retailers emphasize third-party certification and practitioner-grade potency tiers.
Online retail leads growth velocity. Pharmacies retain trust anchor for clinical positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zhejiang and Shandong provinces anchor biotin API production, yet finished goods manufacturing and consumption patterns fragment across distinct national markets with divergent regulatory and channel structures.
United States
Gen-Z hair wellness spending and subscription personalization drive direct-to-consumer growth. FDA CGMP regulations enforce identity and purity standards that elevate compliance costs for new entrants. Nevada hosts vertically integrated manufacturing campuses controlling fermentation through finished tablet production.
Germany
Clean-label certification demand and pharmacy-grade positioning sustain premium tier consumption. REACH registration requirements tighten substance documentation for fermentation-derived ingredients. Frankfurt and Munich clusters concentrate third-party verification laboratories serving EU market entry.
China
Domestic beauty nutrition adoption and precision fermentation R&D investment expand both supply and demand sides. NMPA dietary supplement filing requirements standardize manufacturing practice enforcement. Zhejiang province facilities supply over 70 percent of USP-grade biotin API globally.
United Kingdom
Millennial subscription bundling with collagen and zinc amplifies basket values in direct-to-consumer channels. MHRA borderline regulations govern cosmetic-nutraceutical positioning claims. London and Southeast England host digital-native brands leveraging supply chain transparency as differentiation.
India
Organized retail chain expansion and e-pharmacy platform growth professionalize supplement distribution in tier-2 cities. FSSAI labeling mandates and manufacturing license requirements structure market entry. Maharashtra and Karnataka clusters concentrate contract manufacturing capacity serving domestic and export markets.
Biotin Supplement Market Vendor Landscape
Global majors compete with regional champions across certification tiers and channel access, producing a tiered structure where USP-verified pharmaceutical-grade suppliers defend pharmacy shelf space against digital-native brands capturing subscription-driven direct sales. Three archetypes dominate: vertically integrated fermentation-to-finished-goods manufacturers, premium-positioned third-party-certified specialists, and flavor-technology-focused gummy innovators. Competitive moves concentrate on multi-source ingredient procurement for supply resilience and proprietary delivery format development for palatability differentiation.
Among US-based manufacturers, NOW Foods exemplifies vertical integration archetypes with captive fermentation and finished goods capacity, while Solgar occupies premium-tier positioning through pharmaceutical-grade sourcing protocols exceeding baseline standards. Natrol represents the gummy specialization vector with proprietary flavor-masking capabilities targeting palatability-sensitive demographics.
| Leading Market Players |
|---|
| Nature's Bounty |
| Solgar |
| NOW Foods |
| Natrol |
| Nature Made |
| GNC |
| Goli Nutrition |
| OLLY |
| HUM Nutrition |
| Others |
Supply Flow & Price Mechanics
CRISPR-edited Bacillus subtilis strains are compressing fermentation cycle times while concentrating production knowledge among Zhejiang and Shandong province specialists, simultaneously lowering unit production costs and hardening geographic supply vulnerability that shapes pricing power across finished goods tiers.
Pricing Analysis
Input-cost pass-through from fermentation feedstock volatility and USP-grade certification tiers structures a three-tier pricing framework across premium, standard, and economy levels. Price differentiation rests on pharmaceutical-grade purity thresholds versus cosmetic-grade positioning, with FDA CGMP compliance costs amplifying spreads between verified and unverified suppliers. Pricing pressure stems from D-chiro-inositol substitution in PCOS-adjacent hair health segments. Price-sensitive replenishment buyers in mass retail channels contrast with premium-insensitive direct-to-consumer subscribers prioritizing palatability and personalization.
Supply Chain Analysis
Single-source vulnerability sits with Zhejiang and Shandong province fermentation facilities supplying over 70 percent of USP-grade biotin API globally. Raw material dependencies center on dextrose feedstocks, pharmaceutical-grade excipients, and specialized flavor-masking encapsulation systems. Tariff exposure on Chinese-origin API imports creates inventory fragmentation risk for North American finished goods manufacturers. Distribution runs through vertically integrated contract manufacturers with captive fermentation capacity, direct-to-consumer subscription platforms, and pharmacy wholesale networks serving clinical-grade demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation yield optimization and gummy format premiums are expanding margin capture opportunities beyond commodity tablet economics, positioning biotin supplements as a margin-expansion story for stakeholders with differentiated delivery capabilities.
For Market Incumbents: Anticipate flavor-masking R&D bottlenecks concentrating among a handful of gummy specialists by securing proprietary encapsulation partnerships or captive technology acquisition. Defend pharmacy shelf access through NSF International and USP verification investments that informal importers cannot replicate. Prioritize multi-source API procurement mandates to hedge Zhejiang and Shandong concentration risk. For New Entrants and Emerging Players: Enter via men's grooming nutrition segments where beard growth and hair retention claims remain underdeveloped relative to saturated women's hair wellness positioning. Target tier-2 Indian cities through e-pharmacy platform partnerships as organized retail professionalizes distribution. Deploy subscription personalization integrating hair mineral analysis to capture sticky replenishment economics. For Investors and Strategic Acquirers: Valuations sit cheapest among synthetic fermentation specialists with unbranded API supply contracts rather than finished goods manufacturers facing direct-to-consumer customer acquisition costs. Long-term viability hinges on synthetic biology regulatory clarity unlocking precision-fermented production pathways. Watch FDA guidance on genetically modified organism disclosure as the critical inflection signal for acceptable production methodology expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Flavor-Masking Technology Acquisition | Proprietary encapsulation expertise neutralizes biotin's sulfur off-notes for gummy format dominance. |
| Multi-Source API Procurement Mandate | Geographic diversification beyond Zhejiang and Shandong reduces tariff and supply disruption exposure. |
| Direct-to-Consumer Subscription Launch | Hair mineral analysis integration creates stickier replenishment models than transactional retail channels. |
| USP Verification Investment | Third-party certification separates pharmacy-access winners from commodity suppliers in retail consolidation. |
| Precision Fermentation R&D Partnership | Synthetic biology regulatory clarity could unlock novel production pathways with enhanced sustainability credentials. |
Methodological Framework
Direct dialogue with supplement brand managers, contract manufacturing executives, fermentation process engineers, pharmacy category buyers, and regulatory affairs specialists grounded qualitative findings. Secondary validation drew from FDA dietary supplement CGMP enforcement records, USP verification program databases, NSF International certification listings, and customs trade data on biotin API imports. Bottom-up volume modeling triangulated against top-down market sizing across product type, ingredient source, target demographic, and distribution channel dimensions.
Bottom-up segment-level demand modeling combined with top-down macroeconomic anchoring generated volume and value outputs across the projection horizon. Segmentation dimensions included product format, sourcing claim tier, demographic targeting, and channel structure alongside regional regulatory cluster differentiation. CAGRs were derived from growth rate convergence analysis applied to historical trajectory patterns and forward-looking catalyst assessments. Forecast inputs incorporated Gen-Z preventive beauty nutrition spending elasticity and FDA CGMP enforcement intensity assumptions.
Inputs from primary stakeholder interviews and secondary regulatory databases were available through the study window; gaps in real-time fermentation capacity utilization data and private-label contract pricing introduce uncertainty bands around API supply forecasts. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
GLP-1 Meal Replacement Market
Nutritional Supplements
Energy Gums Market
Nutritional Supplements
Asia-Pacific Amino Acid in Dietary Supplements Market
Nutritional Supplements
India Personalized Nutrition Market
Nutritional Supplements
Coral Calcium Supplements Market
Nutritional Supplements
Nutraceutical Gummies Market
Nutritional Supplements
US Ketones Market
Nutritional Supplements
Gummy Vitamins Market
Nutritional Supplements
Nutritional Oil Powder Market
Nutritional Supplements
Mushroom Powders Market
Nutritional Supplements
Health Supplements Market
Nutritional Supplements
Personalized Nutrition and Supplements Market
Nutritional Supplements
Vitamin K2 Market
Nutritional Supplements
Vitamin B3 Market
Nutritional Supplements
Olive Supplements Market
Nutritional Supplements
Europe Omega-3 Products Market