
 Ketogenic Diet Food Market | 2026-2036
Ketogenic Diet Food Market Size, Share, and Industry Trends Forecast 2026-2036
Ketogenic Diet Food Market Analysis
Clean-label certification is bifurcating the Ketogenic Diet Food Market into premium organic tiers and mass-market conventional lines. Perfect Keto leverages grass-fed ingredient sourcing to anchor its premium positioning. Nestlé competes through manufacturing scale across multiple distribution channels. Quest Nutrition differentiates via protein-forward formulations that extend beyond traditional keto demographics.
Ketogenic diet food comprises low-carbohydrate, high-fat products formulated to induce and maintain nutritional ketosis, typically restricting net carbohydrates to under 50 grams daily while elevating fat content to 70-80 percent of caloric intake. Manufacturers employ cold-pressed extraction and microencapsulation to preserve MCT oil stability and enhance bioavailability in ready-to-drink formats. Snacks and beverages capture the fastest expansion as convenience-seeking consumers prioritize portable formats over meal kits requiring preparation time. Dairy applications sustain margin concentration through fermented product lines with extended shelf stability. Online retail channels lead volume growth, though supermarkets retain higher average transaction values for planned pantry stocking.
FDA nutrition labeling requirements for carbohydrate declarations shape product formulation decisions and packaging redesign cycles. EFSA health claim regulations govern permissible language around weight management and metabolic outcomes in European markets, while the EU Green Deal pressures sustainable sourcing credentials for coconut oil and grass-fed dairy inputs. Stakeholders must monitor evolving low-carbohydrate certification standards across multiple jurisdictions to maintain compliant market access.
Market Dynamics
FDA and EFSA labeling convergence for low-carbohydrate claims is forcing simultaneous packaging redesigns across multiple jurisdictions, compressing formulation cycles while elevating compliance costs for mid-tier manufacturers lacking regulatory affairs scale.
Growth Catalysts
- Fitness Enthusiast Demand:Specialty grocery channels in the United States dedicate expanding shelf space to ketogenic SKUs as bodybuilding and CrossFit communities normalize high-fat nutritional protocols for mainstream consumers.
- Microencapsulation Technology:Cold-pressed extraction processes preserve MCT oil bioavailability in ready-to-drink formats, enabling portable consumption occasions previously inaccessible to oil-based products requiring refrigeration.
- EU Green Deal Sourcing Mandates:Sustainable certification requirements for coconut oil and grass-fed dairy inputs accelerate supplier consolidation toward vertically integrated producers with traceable supply chains.
Market Restraints
- Input Cost Volatility:Grass-fed butter and MCT oil prices fluctuate with weather patterns affecting coconut harvests in Southeast Asia and pasture conditions in Oceania.
- Supply Concentration Risk:Premium organic ingredient sourcing clusters among limited certified suppliers in New Zealand and Australia, creating bottleneck vulnerability for clean-label tier expansion.
- Technical Shelf-Stability Limitations:Fermented dairy applications achieve extended stability while meat-based keto products remain constrained by oxidation and pathogen control challenges.
Strategic Opportunities
- Direct-to-Consumer Platform Expansion:Subscription models bypass supermarket slotting fees while capturing recurring revenue from adherence-focused consumers seeking pantry replenishment automation.
- Protein-Forward Formulation Convergence:Hybrid keto-performance nutrition products attract crossover demand from endurance athletes and intermittent fasting practitioners outside traditional ketogenic demographics.
- USDA Organic Certification Tailwinds:Federal organic labeling standards create price-premium justification for ingredient transparency investments that differentiate mass-market entrants.
Industry Challenges
- Regulatory Affairs Talent Scarcity:Multi-jurisdictional low-carbohydrate claim compliance requires specialized expertise navigating FDA nutrition labeling and EFSA health claim frameworks simultaneously.
- Manufacturing Line Reconfiguration Costs:Dedicated allergen-free facilities for dairy-based keto products demand capital deployment that strains mid-cap balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ketogenic Diet Food Market |
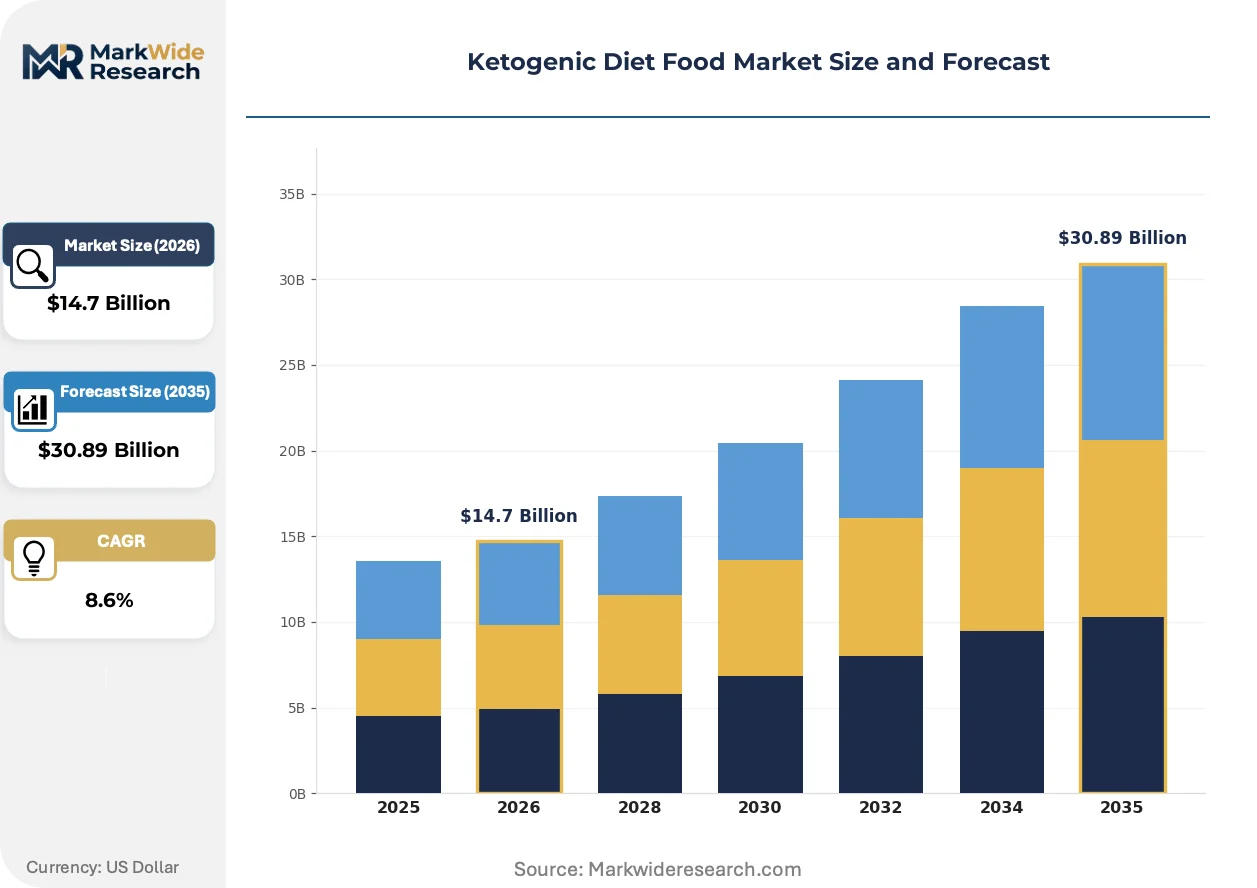
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snacks, Meal Kits, Dairy, Beverages Ingredient Type: Grass-Fed Butter, Coconut Oil, Almond Flour, MCT Oil Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Stores Consumer Segment: Fitness Enthusiasts, Weight Loss Seekers, Health-Conscious Individuals, Others |
| Companies Covered | Perfect Keto, Nestlé, Danone S.A., Pruvit Ventures, Inc., Quest Nutrition, Atkins Nutritionals, Bulletproof 360, Inc., Kiss My Keto, Primal Kitchen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ketogenic Diet Food Market Emerging Trajectories
Clean-label certification protocols are fragmenting competitive positioning into distinct organic premium and conventional economy tiers, with formulation transparency becoming the primary axis of differentiation rather than macronutrient ratios alone.
Microencapsulation technology for MCT oil stabilization is fragmenting product format possibilities. Beverage manufacturers adopt these processes to introduce shelf-stable ketogenic coffee and smoothie applications without refrigeration requirements. This capability compression is enabling direct-to-consumer brands to bypass traditional cold-chain distribution partnerships entirely.
EFSA health claim regulations governing weight management language are tightening permissible marketing communications. Manufacturers must reformulate packaging to remove metabolic outcome assertions while substituting structural benefit descriptions. European markets exhibit the most pronounced compliance response, with reformulated labels appearing ahead of enforcement deadlines.
Subscription-based replenishment models are displacing conventional retail stocking behaviors among adherence-focused consumers. Online channels capture volume growth as automated delivery reduces planning friction for pantry-dependent dietary protocols. United States metropolitan markets demonstrate the highest subscription penetration rates among dual-income households with limited meal preparation time.
Ketogenic Diet Food Market Segmentation
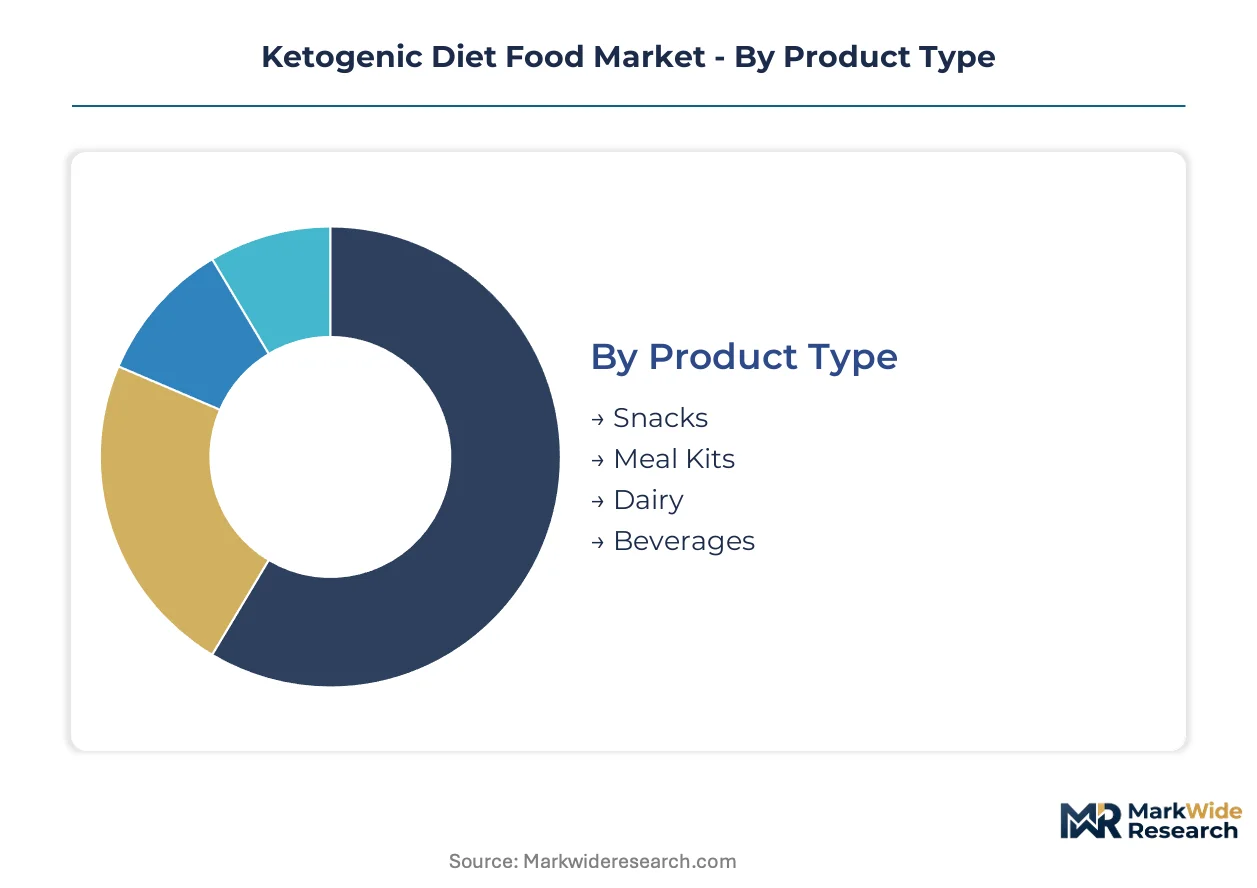
Ketogenic food segmentation tracks how macronutrient specifications, ingredient sourcing tiers, and purchase occasions fragment demand across incompatible channel economics. Manufacturers must match formulation investments to the shelf-stability and margin requirements of each route-to-market.
Product Type:
Channel economics split these formats between impulse-purchase convenience and planned pantry replenishment cycles.
- Snacks:Portable formats with extended shelf stability dominate checkout-line placements and direct-to-consumer subscription boxes. CrossFit affiliates and specialty gyms in the United States drive bulk procurement of individually wrapped bars and nut packets for member retail.
- Beverages:Microencapsulated MCT oil formulations enable ambient-temperature distribution previously impossible for fat-based drinks. Ready-to-drink ketogenic coffees capture the fastest volume expansion through Amazon and Thrive Market, bypassing refrigerated logistics entirely.
- Meal Kits:Pre-portioned ingredients with preparation instructions target time-constrained households seeking adherence support without recipe planning.
- Dairy:Fermented products like kefir and aged cheeses deliver margin concentration through extended stability and premium positioning in grass-fed tiers.
Dairy dominates installed base through fermented stability. Beverages is where expansion concentrates.
Ingredient Type:
Cost tiers separate premium clean-label positioning from mass-market accessibility.
- MCT Oil:Medium-chain triglyceride concentrates derived from coconut or palm kernel oil deliver rapid ketone elevation. Demand clusters in ready-to-drink applications where bioavailability claims justify price premiums over conventional fats.
- Grass-Fed Butter:Pasture-raised dairy inputs anchor premium tier differentiation through omega-3 ratio marketing. New Zealand and Australian suppliers control certified volumes, creating procurement bottlenecks for scale manufacturers.
- Coconut Oil:Virgin and refined grades serve distinct formulation needs across baking and frying applications.
- Almond Flour:Blanched and natural varieties substitute for wheat in baking mixes with lower carbohydrate density.
Grass-fed butter commands price premiums through scarcity certification. MCT oil is climbing the fastest through beverage format adoption.
Distribution Channel:
Volume and margin capture diverge between automated replenishment and planned stocking behaviors.
- Online Retail:Subscription models bypass slotting fees while capturing recurring revenue from adherence-focused consumers. Amazon and direct-to-consumer platforms anchor United States volume growth through pantry replenishment automation.
- Supermarkets:Planned purchase occasions deliver higher average transaction values for multi-item basket building. Kroger and Whole Foods Market dedicate expanding shelf space to ketogenic SKUs as specialty diet sections consolidate.
- Health Food Stores:Staff expertise and sampling programs support trial conversion for unfamiliar formulations.
- Specialty Stores:CrossFit boxes and yoga studios capture impulse purchases through proximity to usage occasions.
Supermarkets dominate installed base through pantry-stocking frequency. Online retail is where expansion concentrates.
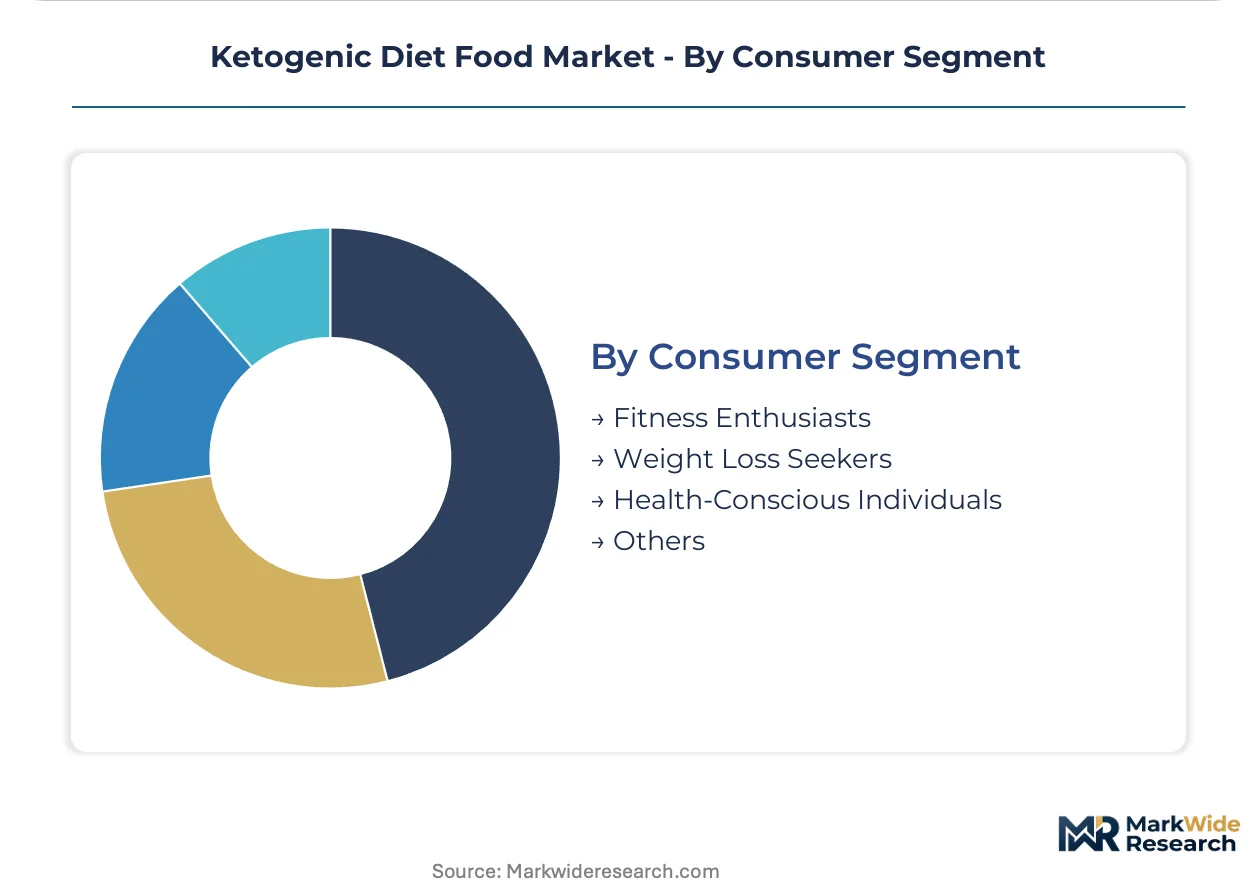
Consumer Segment:
Adherence motivation shapes price sensitivity and format preferences across usage occasions.
- Fitness Enthusiasts:Bodybuilding and CrossFit practitioners normalize high-fat protocols through peer influence and performance claims. This segment drives protein-forward formulation demand that extends beyond strict ketogenic macronutrient ratios.
- Weight Loss Seekers:Metabolic outcome expectations drive trial purchases with high churn risk if scale movement stalls. Meal kits and portion-controlled snacks target this group's planning friction.
- Health-Conscious Individuals:General wellness positioning attracts consumers seeking carbohydrate reduction without strict ketosis maintenance.
- Others:Medical ketogenic diet adherents and epilepsy management protocols represent prescription-adjacent demand with distinct formulation requirements.
Fitness enthusiasts dominate installed base through community-normalized adherence. Weight loss seekers represent the steepest expansion trajectory through resolution-driven trial spikes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency for MCT oil and grass-fed dairy inputs shapes regional market development, with net exporters in Oceania and Southeast Asia supplying formulation hubs in North America and Europe. Trade flows concentrate premium ingredient procurement through vertically integrated channels.
United States
Fitness enthusiasts and CrossFit affiliates drive specialty grocery shelf expansion across metropolitan markets. FDA nutrition labeling requirements for carbohydrate declarations compress formulation cycles and elevate compliance costs. Austin and Denver anchor direct-to-consumer brand clusters where subscription models bypass traditional retail slotting fees.
Germany
Health-conscious consumers seeking carbohydrate reduction without strict ketosis maintenance expand addressable demand beyond traditional adherents. EFSA health claim regulations governing weight management language force packaging redesigns ahead of enforcement deadlines. Munich and Hamburg concentrate clean-label manufacturing investments for EU market access.
Australia
Premium organic ingredient sourcing clusters among certified grass-fed butter suppliers in Victoria and New South Wales. Pasture conditions and drought patterns create procurement bottlenecks for scale manufacturers dependent on Oceania dairy inputs. Sydney anchors traceable supply chain verification services for export certification.
United Kingdom
Online retail channels capture volume growth through Amazon and specialized subscription platforms serving time-constrained households. Post-Brexit regulatory divergence from EFSA frameworks creates parallel compliance obligations for manufacturers serving EU and UK markets. London concentrates direct-to-consumer brand headquarters and influencer marketing operations.
Netherlands
EU Green Deal sustainable sourcing mandates accelerate supplier consolidation toward vertically integrated producers with certified coconut oil traceability. Rotterdam's port infrastructure handles Southeast Asian MCT oil imports for European formulation facilities. Amsterdam anchors plant-based keto innovation clusters responding to flexitarian demand crossover.
Ketogenic Diet Food Market Vendor Landscape
Listed leaders compete with private specialists across certification tiers, with public companies leveraging manufacturing scale while private operators exploit agility in formulation innovation. Market structure fragments across three distinct tiers: multinational food conglomerates with diversified portfolios, dedicated keto-native brands with ingredient sourcing specialization, and emerging direct-to-consumer operators with subscription-first business models. Dominant competitive moves include strategic partnerships for supply chain access and portfolio diversification into adjacent performance nutrition categories.
Within the premium-tier vector, Perfect Keto exemplifies grass-fed ingredient sourcing specialization, while Nestlé represents multinational scale deployment across multiple distribution channels. Quest Nutrition occupies a position bridging keto and broader protein-forward performance nutrition demand. These three anchors illustrate how competitive positioning splits between purity-focused certification plays and mass-market accessibility strategies.
| Leading Market Players |
|---|
| Perfect Keto |
| Nestlé |
| Danone S.A. |
| Pruvit Ventures, Inc. |
| Quest Nutrition |
| Atkins Nutritionals |
| Bulletproof 360, Inc. |
| Kiss My Keto |
| Primal Kitchen |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between New Zealand grass-fed butter suppliers and US-based keto manufacturers lock in both supply access and price visibility, insulating premium tier producers from spot market volatility while compressing margins for mid-tier competitors lacking procurement scale. These contractual structures concentrate purchasing power among vertically integrated operators capable of multi-year commitments, while smaller brands absorb input cost swings through shorter-term arrangements.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in the ketogenic food sector. Fitness enthusiasts purchasing through CrossFit affiliates and specialty gyms exhibit the lowest price sensitivity due to community-validated quality expectations, while weight-loss seekers in mass retail channels drive cost compression through high churn and promotional dependency. Price differentiation hinges on USDA Organic certification status and grass-fed ingredient sourcing tier, with FDA-compliant labeling investments adding fixed cost burdens that widen spreads between tiers. Pricing pressure stems from MCT oil supply volatility tied to Southeast Asian coconut harvest cycles, forcing reformulation trade-offs or margin absorption.
Supply Chain Analysis
Strategic stockpiling of MCT oil and grass-fed dairy inputs dominates inventory strategy among large-scale manufacturers, while direct-to-consumer brands favor just-in-time fulfillment to minimize working capital tied to perishable formulations. Geographic supply concentration centers on New Zealand and Australia for certified grass-fed butter, with Southeast Asia—particularly Indonesia and the Philippines—anchoring virgin coconut oil and MCT oil extraction. Raw material dependencies include coconut-derived MCT oil, pasture-raised dairy fats, and almond flour substitutes for wheat-free baking applications. Single-source vulnerability runs through New Zealand's concentrated organic dairy certification bodies, where drought conditions create procurement bottlenecks. Distribution runs through Amazon's fulfillment infrastructure and refrigerated logistics partnerships for dairy-based products requiring cold-chain integrity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among subscription-platform aggregators and specialty grocery chains, fragmenting negotiating leverage for mid-tier manufacturers dependent on fragmented retail access. This consolidation dynamic rewards scale players with portfolio breadth while squeezing single-SKU operators on slotting fees and promotional fund demands.
For Market Incumbents: Compound defensive positioning through backward integration into grass-fed dairy sourcing in Oceania and captive MCT oil refining partnerships in Southeast Asia. Nestlé and Danone S.A. should accelerate certification investments ahead of EFSA health claim enforcement deadlines to lock in premium tier access. Threats from protein-forward crossover brands like Quest Nutrition demand formulation R&D convergence with performance nutrition protocols. Channel control through direct-to-consumer platform ownership represents the critical lever for margin defense against retail consolidation. For New Entrants and Emerging Players: Lead with white-space capture in medical ketogenic protocols and pediatric epilepsy management applications, where prescription-adjacent positioning commands reimbursement-adjacent pricing power. The most penetrable segment sits among intermittent fasting practitioners seeking hybrid keto-performance products outside strict macronutrient adherence. European markets exhibit underdeveloped clean-label tier penetration relative to US saturation. Go-to-market execution should emphasize subscription-first automation targeting dual-income metropolitan households with limited meal preparation bandwidth. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated operators with traceable Oceania dairy supply chains and established FDA compliance infrastructure. Long-term viability across the projection horizon favors acquisition targets combining direct-to-consumer subscription scale with manufacturing asset ownership rather than pure-brand plays dependent on co-packing arrangements. The signal to watch is EFSA health claim enforcement stringency, which will bifurcate compliant premium tiers from reformulation-challenged mass-market entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Grass-Fed Supply Chain Integration | Backward integration into New Zealand dairy sourcing secures certified input access against procurement bottlenecks. |
| Microencapsulation Technology Licensing | Cold-pressed MCT oil stabilization enables ambient-temperature distribution bypassing refrigerated logistics partnerships. |
| Direct-to-Consumer Platform Buildout | Subscription automation captures recurring revenue from adherence-focused consumers while eliminating retail slotting fees. |
| Protein-Forward Formulation Extension | Hybrid keto-performance positioning attracts CrossFit and endurance athlete demand outside strict ketogenic demographics. |
| EFSA Compliance Certification Investment | Preemptive packaging redesign ahead of enforcement deadlines preserves European market access against regulatory exclusion. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews combined with secondary validation across regulatory filings and trade databases. Stakeholder roles engaged included brand managers at keto-native companies, category buyers at Whole Foods Market and Kroger, supply chain directors managing Oceania dairy procurement, regulatory affairs specialists navigating FDA nutrition labeling and EFSA health claim frameworks, and formulation scientists developing microencapsulation processes. Secondary sources encompassed FDA CFR Title 21 food labeling standards, EFSA health claim register entries, USDA organic certification databases, and customs trade records for coconut oil and MCT oil imports. Bottom-up volume estimates from SKU-level retail audit data were triangulated against top-down category spending projections derived from household panel surveys.
Across the analysis window, the forecasting framework modeled demand trajectories by product type, ingredient sourcing tier, distribution channel economics, and consumer adherence motivation. Segmentation dimensions included snacks versus beverages versus dairy applications, grass-fed versus conventional input grades, online subscription versus supermarket replenishment behaviors, and fitness enthusiast versus weight-loss seeker versus medical protocol consumer segments. CAGRs were derived from trend extrapolation of historical volume data adjusted for regulatory inflection points and technology adoption curves. Industry-specific forecast inputs incorporated MCT oil price volatility indices tied to Southeast Asian harvest cycles and EFSA enforcement timeline assumptions.
Underlying assumptions cover sustained fitness community normalization of high-fat protocols, stable Oceania pasture conditions for grass-fed dairy supply, and gradual EFSA health claim compliance adoption, with deviation risk concentrated in input cost spikes from climate-driven coconut harvest disruptions or accelerated regulatory enforcement. Forecasts reflect these assumptions with explicit scenario weighting for compliance cost pass-through feasibility. Revision becomes warranted when MCT oil spot prices exceed contract thresholds or when EFSA issues binding guidance eliminating metabolic outcome language from packaging entirely.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Global Egg Protein Powder Market
Nutritional Supplements
Phytonutrients Market
Nutritional Supplements
Biotin Supplement Market
Nutritional Supplements
Red Yeast Rice Market
Nutritional Supplements
Lactates Market
Nutritional Supplements
Europe Collagen Peptides Market
Nutritional Supplements
Grass-Fed Collagen Market
Nutritional Supplements
DHA Oil Supplement Market
Nutritional Supplements
Garlic Extract Supplement Market
Nutritional Supplements
Weight Loss Supplements Market
Nutritional Supplements
US Nutraceuticals Market
Nutritional Supplements
Human Milk Oligosaccharides (HMO) Market
Nutritional Supplements
South America Dietary Supplement Market
Nutritional Supplements
Mushroom Powders Market
Nutritional Supplements
Iron Supplement Market
Nutritional Supplements
Europe Nutritional Beverages Market