
 Oyster Shell Calcium Market | 2026-2036
Oyster Shell Calcium Market Size, Share, and Industry Trends Forecast 2026-2036
Oyster Shell Calcium Market Analytics
Modular tablet-and-capsule bundling is realigning how retail consumers purchase oyster shell calcium, moving single-format SKUs toward combination packs that pair immediate-release tablets with sustained-release capsules. Pacific Bio leverages its coastal processing infrastructure to control raw shell sourcing costs. J.M. Huber Corporation anchors its position through pharmaceutical-grade purification technology. Gulshan Polyols Ltd. competes on volume scale in animal feed grade material.
Oyster shell calcium consists of calcium carbonate derived from crushed and processed oyster shells, typically containing 35-40% elemental calcium by weight with trace minerals including magnesium and strontium that distinguish it from limestone-derived alternatives; manufacturers calcine or micronize shells to achieve particle sizes between 5-50 microns for supplement and pharmaceutical applications. Powder formulations dominate production volume due to lower processing costs and flexible downstream use across food fortification and animal feed, while tablet and capsule formats command stronger margins in retail channels where dosing convenience drives premium positioning. The dietary supplements application leads absolute demand as aging populations in East Asia prioritize bone health maintenance.
The US FDA oversees New Dietary Ingredient notifications for oyster shell calcium entering supplement formulations, while Japan's MHLW sets purity standards for natural calcium sources in Foods for Specified Health Uses. India's FSSAI enforces heavy metal limits on shell-derived minerals sold as nutraceuticals, creating compliance barriers for unprocessed imports. Stakeholders must monitor evolving marine resource sustainability certifications as coastal harvesting restrictions tighten in key shell-producing regions.
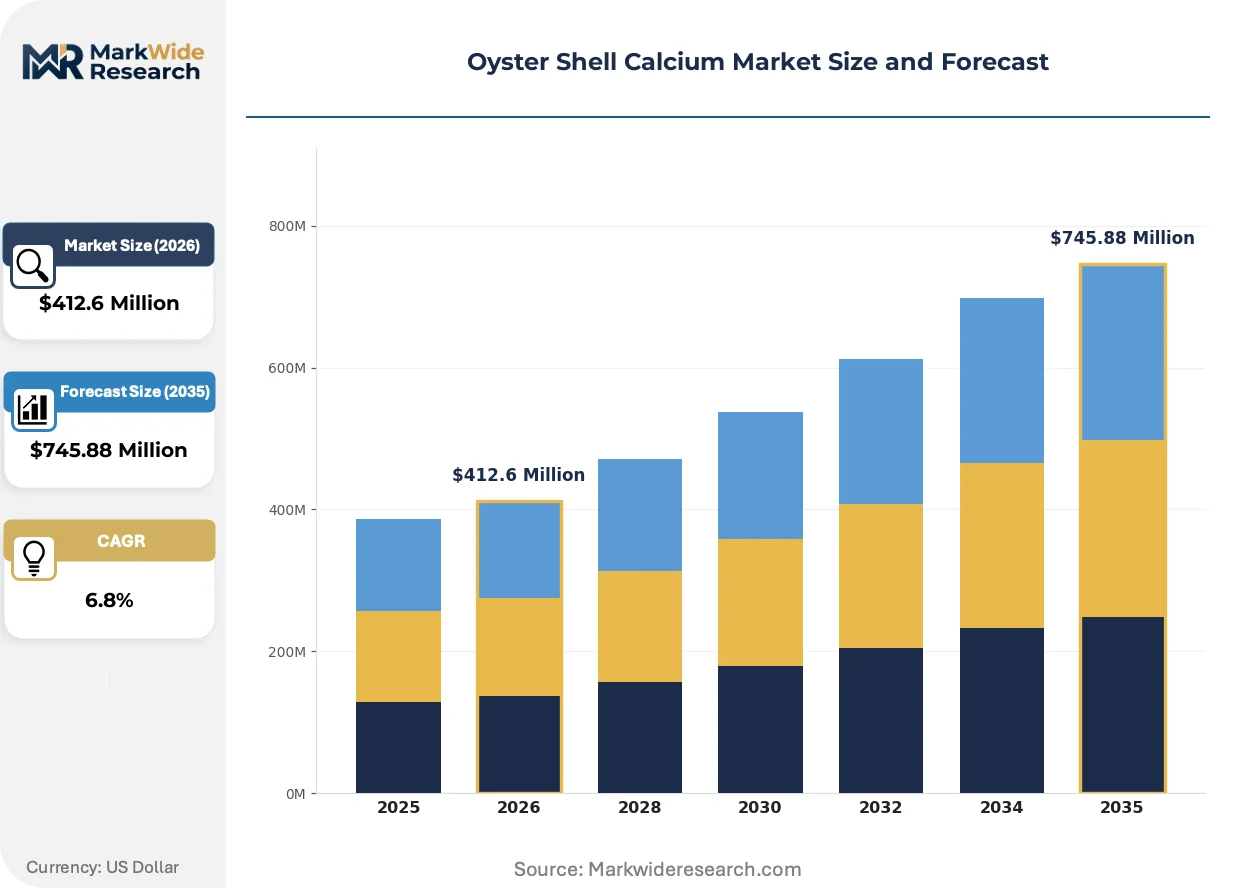
Market Dynamics
Modular tablet-and-capsule bundling is restructuring oyster shell calcium retail economics, forcing manufacturers to reconfigure production lines for combination-pack formats while coastal processing infrastructure becomes the decisive cost-control lever.
Growth Catalysts
- Japan's MHLW Foods for Specified Health Uses framework:Natural calcium sources receive preferential regulatory treatment over synthetic alternatives, accelerating marine-derived mineral adoption in functional foods.
- Animal feed fortification:Layer poultry and aquaculture operations are expanding oyster shell calcium inclusion rates to improve eggshell density and skeletal development in farmed species.
- Micronization technology:Particle size reduction to 5-50 microns is unlocking pharmaceutical-grade applications previously inaccessible to shell-derived material.
Market Restraints
- Coastal harvesting restrictions:Shell-producing regions in Southeast Asia face seasonal moratoriums that compress raw material availability during peak processing months.
- Limestone substitution:Synthetic calcium carbonate from geological sources offers 15-20% lower input costs for price-sensitive animal feed applications.
- US FDA New Dietary Ingredient notification:Supplement manufacturers face 75-day pre-market review cycles that extend product launch timelines and elevate compliance expenditure.
Strategic Opportunities
- India's FSSAI nutraceutical pathway:Heavy metal testing protocols for shell-derived minerals create first-mover advantages for certified suppliers in an underpenetrated market.
- Sustained-release capsule formats:Combination packs pairing immediate and extended-release delivery systems command retail shelf space premiums in aging-population markets.
- Marine sustainability certification:MSC and ASC standards for coastal shell harvesting are becoming procurement prerequisites for European pharmaceutical buyers.
Industry Challenges
- Calcination energy costs:Thermal processing of raw shells requires natural gas or biomass furnace infrastructure that faces carbon pricing pressure in regulated jurisdictions.
- Trace mineral consistency:Batch-to-batch variation in magnesium and strontium content complicates pharmaceutical formulation standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oyster Shell Calcium Market |
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Tablets, Capsules Application: Dietary Supplements, Food Fortification, Animal Feed, Pharmaceuticals End User: Retail Consumers, Health Food Stores, Hospitals, Veterinarians Distribution Channel: Online Retail, Supermarkets, Pharmacies, Specialty Stores |
| Companies Covered | Pacific Bio, Caltron Clays & Chemicals Pvt. Ltd., J.M. Huber Corporation, Gulshan Polyols Ltd., Sigma Minerals Ltd., Omya AG, Fujian Dongshan Juyuan Calcium Carbonate Co., Ltd., Maruo Calcium Co., Ltd., Shiraishi Calcium Kaisha, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oyster Shell Calcium Market Evolving Landscape
Processing technology convergence and regulatory granularity are fragmenting competitive moats in oyster shell calcium, separating coastal-integrated processors from toll-dependent competitors.
Low-temperature calcination with controlled atmosphere retention is rewriting quality benchmarks for pharmaceutical-grade material. Japanese supplement manufacturers are adopting these systems at replacement cycle pace to preserve heat-sensitive trace minerals. The technology is compressing acceptable purity thresholds and disqualifying conventional high-heat processors from premium contracts.
EU REACH registration requirements for calcium carbonate derived from biogenic sources are tightening substance identity documentation. Manufacturers must now demonstrate shell provenance and processing chain custody to maintain market access. Pharmaceutical and food-grade segments are responding by integrating coastal sourcing operations rather than relying on spot-market shell purchases.
Direct-to-practitioner distribution is displacing traditional retail pharmacy stocking for clinical nutrition applications. Functional medicine clinics and integrative health practices are establishing preferred supplier relationships with traceable shell-source processors. This channel rotation is most visible in Germany and the Netherlands where practitioner-dispensed supplement protocols carry higher patient compliance rates.
Oyster Shell Calcium Market Segmentation
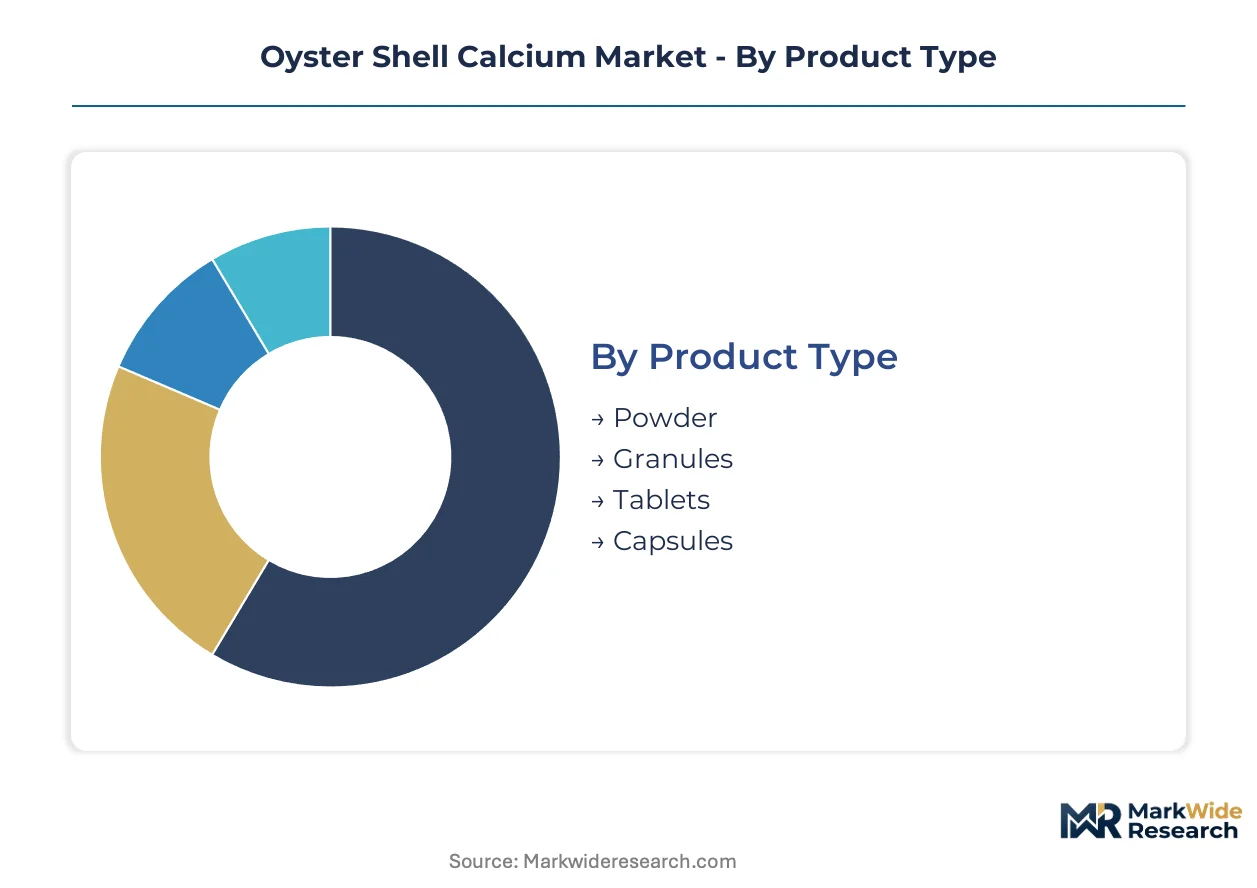
Oyster shell calcium manufacturers configure production assets around format-specific capital requirements. Powder and granule lines demand heavy calcination infrastructure, while tablet and capsule finishing requires precision compression and encapsulation equipment with distinct payback periods.
Product Type:
Capital intensity peaks with micronization and pharmaceutical-grade purification systems, while commodity grinding operations require lower upfront investment.
- Powder:Raw calcium carbonate milled to 50-200 microns serves bulk food fortification and animal feed applications. Demand concentrates in Southeast Asian aquaculture operations where shell-derived mineral inclusion improves shrimp exoskeleton formation. Coastal processors with integrated drying capacity capture margin from toll-dependent competitors.
- Tablets:Direct-compression formats containing 500-600mg elemental calcium dominate Japanese convenience-store supplement shelves. Osaka and Tokyo metropolitan consumers favor scored immediate-release tablets for bone health protocols. Compression tooling investments and disintegration testing protocols create barriers for unqualified entrants.
- Granules:Intermediate particle size (200-500 microns) bridges powder and tablet applications, primarily flowing into veterinary compounding and institutional food service.
- Capsules:Hard-shell gelatin and HPMC formats enable sustained-release formulations with enteric coating options for acid-sensitive consumers.
Most installed capacity flows through Powder. Expansion is steepest in Tablets.
Application:
Regulatory pathway complexity varies sharply across end-use segments, with pharmaceutical and nutraceutical channels demanding distinct compliance architectures.
- Dietary Supplements:Capsule and tablet formats targeting aging populations in Japan and South Korea. The US FDA's 75-day New Dietary Ingredient notification cycle shapes supplier qualification timelines.
- Animal Feed:Layer poultry operations specify 3-5% calcium inclusion for eggshell strength. Vietnamese and Indonesian commercial farms are expanding oyster shell sourcing as limestone substitution faces digestibility concerns.
- Food Fortification:Micronized powder integrates into flour, dairy, and beverage matrices. India's FSSAI heavy metal limits for shell-derived minerals constrain unprocessed import flows.
- Pharmaceuticals:Excipient-grade material for antacid and calcium supplementation prescriptions requires batch-to-batch trace mineral documentation. EU REACH biogenic source registration demands shell provenance chain custody.
Volume concentration sits with Animal Feed. Value expansion is climbing the fastest in Pharmaceuticals.
End User:
Procurement authority and technical specification sophistication diverge across buyer categories, from mass-market retail to clinical institutional purchasing.
- Retail Consumers:Direct-to-consumer online channels and pharmacy purchases. German and Dutch functional medicine clinics are establishing preferred supplier relationships with traceable processors.
- Health Food Stores:Staff-assisted selling environments in Japan favor natural-source positioning over synthetic alternatives.
- Hospitals:Clinical nutrition departments specify pharmaceutical-grade material for inpatient supplementation protocols.
- Veterinarians:Companion animal and livestock practitioners prescribe calcium supplementation for metabolic disorders and reproductive health.
Transaction volume concentrates through Retail Consumers. Specification tightening is most pronounced in Hospitals.
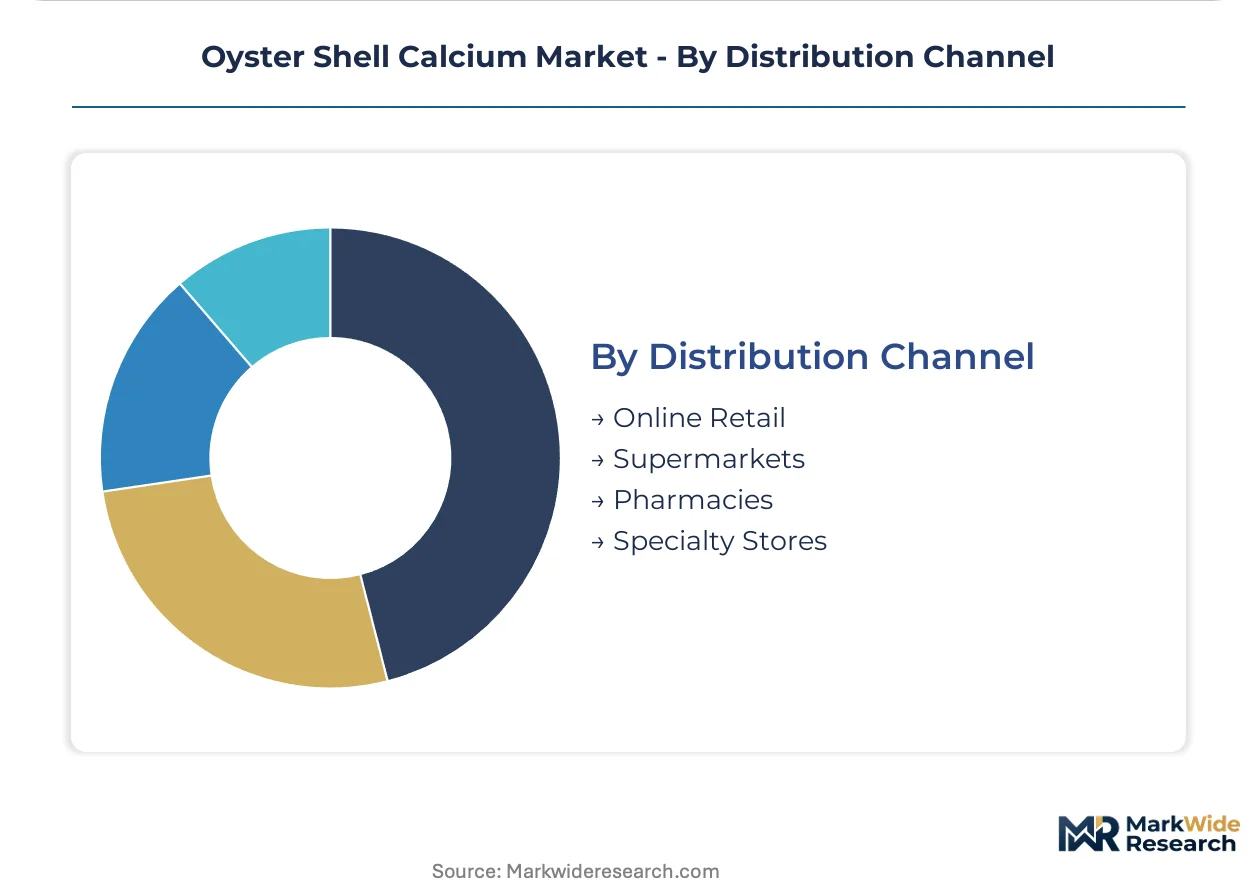
Distribution Channel:
Channel economics fragment between low-touch digital fulfillment and high-service physical retail with divergent working capital requirements.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators. Subscription bundling of immediate-release and sustained-release formats is gaining traction in aging-population markets.
- Supermarkets:Mass-market placement of powder and tablet SKUs with price-competitive positioning against limestone-derived alternatives.
- Pharmacies:Pharmacist-recommended selection in Japan and South Korea favors marine-source natural positioning.
- Specialty Stores:Integrative health practitioners and clinical nutrition suppliers in Germany and the Netherlands dispense traceable-source protocols with higher patient compliance rates.
Revenue share concentrates in Pharmacies. Digital penetration is expanding most quickly through Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oyster shell calcium processing originated in coastal Japan during the mid-20th century, where traditional calcination methods met modern pharmaceutical standards. The industry subsequently dispersed across Pacific Rim economies with established shell harvesting infrastructure.
Japan
Aging demographics and Foods for Specified Health Uses (FOSHU) approvals for marine-derived minerals sustain premium supplement demand. Japan's Ministry of Health, Labour and Welfare maintains stricter purity thresholds for natural calcium than synthetic alternatives. Osaka and Tokyo metropolitan clusters host tablet compression and sustained-release capsule finishing operations serving domestic retail pharmacy networks.
United States
Dietary supplement manufacturers face FDA New Dietary Ingredient notification requirements that extend supplier qualification timelines for shell-derived materials. The 75-day pre-market review cycle elevates compliance expenditure for imported raw material. Coastal processing facilities in the Pacific Northwest leverage proximity to shell harvesting grounds for captive raw material supply.
India
FSSAI heavy metal testing protocols for shell-derived nutraceuticals create compliance barriers for unprocessed imports while opening first-mover advantages for certified domestic processors. Layer poultry operations in Gujarat and Maharashtra specify oyster shell calcium for eggshell density improvement. The country's national food regulator enforces batch documentation requirements that favor integrated coastal processors over toll-dependent competitors.
Vietnam
Commercial aquaculture expansion drives bulk powder demand for shrimp exoskeleton formation and skeletal development in farmed species. Seasonal harvesting moratoriums in shell-producing coastal provinces compress raw material availability during peak processing months. Mekong Delta processing clusters integrate drying capacity to capture margin from spot-market shell purchasers.
Germany
Direct-to-practitioner distribution channels through functional medicine clinics and integrative health practices favor traceable shell-source processors with chain-of-custody documentation. EU REACH registration requirements for biogenic calcium carbonate tighten substance identity documentation obligations. The country's pharmaceutical and food-grade segments respond by qualifying preferred suppliers rather than spot-market purchasing.
Oyster Shell Calcium Market Competitive Landscape
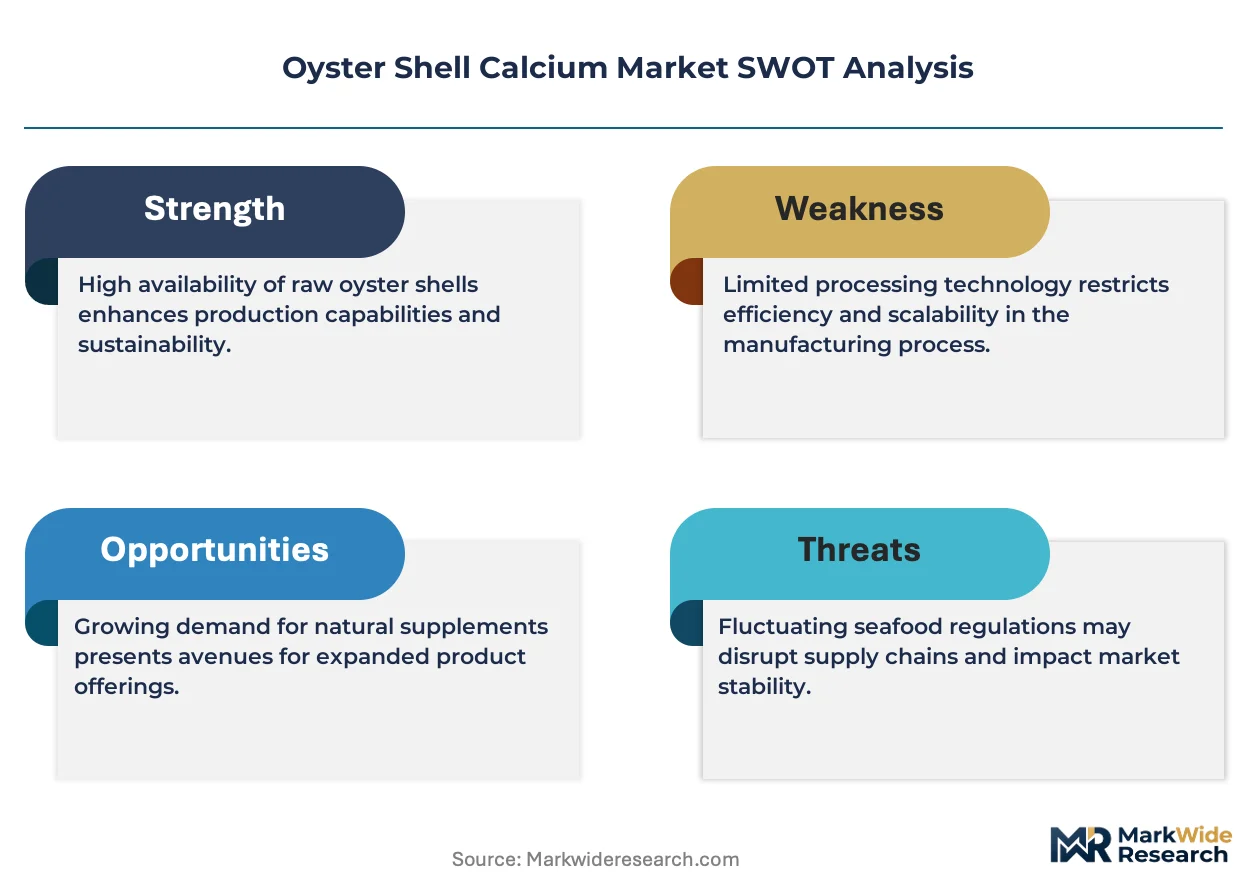
Premium-margin players sit above commodity-margin players across purification technology and coastal sourcing integration. The vendor base separates into three functional tiers: pharmaceutical-grade specialists with micronization capabilities, animal feed volume processors with calcination infrastructure, and toll-dependent traders without captive shell supply. Strategic differentiation concentrates on backward integration into coastal harvesting operations and sustained-release formulation technology licensing.
Within the coastal-integrated tier, Pacific Bio exemplifies infrastructure-heavy positioning through controlled shell sourcing. J.M. Huber Corporation occupies a position among purification-technology specialists serving pharmaceutical-grade contracts. Gulshan Polyols Ltd. represents volume-scale animal feed material production. Maruo Calcium Co., Ltd. and Shiraishi Calcium Kaisha, Ltd. anchor Japanese-origin natural calcium positioning in East Asian supplement markets.
| Leading Market Players |
|---|
| Pacific Bio |
| Caltron Clays & Chemicals Pvt. Ltd. |
| J.M. Huber Corporation |
| Gulshan Polyols Ltd. |
| Sigma Minerals Ltd. |
| Omya AG |
| Fujian Dongshan Juyuan Calcium Carbonate Co., Ltd. |
| Maruo Calcium Co., Ltd. |
| Shiraishi Calcium Kaisha, Ltd. |
| Others |
Value Network & Pricing Analysis
Pharmaceutical-grade certification tiers split oyster shell calcium into divergent economic strata, where micronization capability and marine sustainability documentation command 40-60% premiums over animal feed grades while calcination energy costs and coastal harvesting restrictions compress margins at the commodity end. This bifurcation manifests in supply chain configurations: premium processors integrate backward into controlled shell sourcing to secure MSC and ASC chain-of-custody documentation, whereas volume operators depend on spot-market shell purchases subject to seasonal moratoriums in Vietnamese and Indonesian coastal provinces.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, nutraceutical-grade, and animal feed-grade levels dominates oyster shell calcium transactions, with differentiation driven by particle size certification and heavy metal testing protocols under Japan's MHLW and India's FSSAI frameworks. Cost compression in animal feed tiers is intensifying because limestone substitution offers 15-20% lower input costs for price-sensitive layer poultry operations, while pharmaceutical buyers show minimal price sensitivity due to excipient standardization requirements and batch-to-batch trace mineral documentation obligations.
Supply Chain Analysis
Shell collection and calcination residue recycling flows remain underdeveloped, with most processors disposing of thermal processing byproducts rather than recovering calcium oxide for agricultural liming applications. Raw material supply concentrates in Vietnam, Indonesia, and coastal Japan, where seasonal harvesting moratoriums create Q3-Q4 availability crunches. Production draws from oyster aquaculture waste streams, limestone-adjacent geological deposits, and imported pre-processed carbonate. Single-source vulnerability runs through Mekong Delta drying clusters exposed to monsoon logistics disruption. Distribution runs through direct-to-practitioner channels in Germany and Netherlands alongside traditional pharmacy networks in East Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oyster shell calcium functions as a regulatory compounder where Japan's MHLW Foods for Specified Health Uses framework accelerates marine-derived mineral adoption by mandating preferential purity thresholds for natural calcium sources over synthetic alternatives.
For Market Incumbents: Anchor market position through captive coastal processing infrastructure in Vietnamese and Indonesian shell-producing regions, insulating against seasonal raw material crunches that cripple toll-dependent competitors. Invest in low-temperature calcination systems to preserve heat-sensitive trace minerals and disqualify conventional high-heat processors from Japanese pharmaceutical-grade contracts. Defend against limestone substitution in animal feed tiers by emphasizing digestibility advantages in layer poultry applications. For New Entrants and Emerging Players: The premium-to-economy price gap in Indian nutraceutical channels offers viable entry positioning for certified domestic processors capable of meeting FSSAI heavy metal testing protocols that block unprocessed imports. Target Gujarat and Maharashtra layer poultry operations with bulk powder offerings that substitute for limestone in eggshell density applications. Pursue direct-to-practitioner distribution partnerships with German functional medicine clinics seeking traceable shell-source documentation. For Investors and Strategic Acquirers: Consolidation pressure builds where coastal processing infrastructure scarcity intersects with tightening EU REACH biogenic source registration requirements that demand shell provenance chain custody. Five-to-ten year viability favors backward-integrated processors with micronization capabilities over toll-dependent traders lacking captive shell supply. Monitor MSC and ASC certification adoption rates among European pharmaceutical buyers as inflection indicators for premium-tier margin sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coastal Shell Sourcing | Captive raw material supply insulates against Vietnamese and Indonesian seasonal harvesting moratoriums. |
| Low-Temperature Calcination Technology Deployment | Japanese pharmaceutical-grade contracts demand heat-sensitive trace mineral preservation that conventional furnaces cannot deliver. |
| Marine Sustainability Certification Acquisition | MSC and ASC standards are becoming procurement prerequisites for European pharmaceutical and food-grade buyers under EU REACH. |
| Sustained-Release Capsule Format Development | Combination packs pairing immediate and extended-release delivery systems command retail shelf space premiums in aging-population markets. |
| Direct-to-Practitioner Channel Establishment | German and Dutch functional medicine clinics dispense traceable-source protocols with higher patient compliance rates than pharmacy retail. |
Research Methodology
Bottom-up dietary supplement and animal feed modeling reconciled against top-down coastal processing capacity tracking forms the analytical core of this study. Primary interviews with supplement formulation scientists, regulatory affairs specialists at FDA and MHLW, layer poultry procurement managers, and pharmaceutical excipient quality directors combined with secondary validation from customs trade databases, FSSAI heavy metal testing bulletins, SEC 10-K filings of publicly traded calcium processors, and EU REACH substance registration databases. Triangulation across these sources calibrated production volume estimates against import-export flows.
Historical trendline analysis of oyster shell calcium consumption patterns across powder, tablet, granule, and capsule formats informed projection modeling over the analysis window. Segmentation dimensions included product type, application across dietary supplements, animal feed, food fortification, and pharmaceuticals, end-user procurement sophistication, and distribution channel economics. CAGRs derived from fitted growth curves adjusted for regulatory milestone impacts, with specific inputs from Japan's aging demographic trajectory and India's layer poultry expansion rates.
Caveats apply where coastal harvesting restriction tightening, calcination energy cost escalation under carbon pricing regimes, or breakthrough synthetic calcium bioavailability improvements could materially shift the outlook. Practitioners should monitor EU REACH enforcement consistency, FSSAI certification pathway streamlining, and limestone substitution technology advances for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Global Corn Germs Supplements Market
Nutritional Supplements
Health Ingredients Market
Nutritional Supplements
Digestive Enzyme Complex Market
Nutritional Supplements
Fish Protein Isolate Market
Nutritional Supplements
Asia-Pacific Beta-Glucan Market
Nutritional Supplements
Natural Vitamin E Product Market
Nutritional Supplements
Phytonutrients Market
Nutritional Supplements
Botanical Supplements Market
Nutritional Supplements
Multivitamin and Mineral Supplements Market
Nutritional Supplements
South America Whey Protein Market
Nutritional Supplements
Oral Immunostimulant Market
Nutritional Supplements
Dextrose Monohydrate Market
Nutritional Supplements
Omega-3 Products Market
Nutritional Supplements
Australia Nutraceuticals Market
Nutritional Supplements
Omega 3 Market
Nutritional Supplements
Arabinogalactan Powder Market