
 Canada Protein Market | 2026-2036
Canada Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Protein Market Outlook
Market Context with Strategic Players
Alberta's emerging pulse-processing corridor is tilting investment toward pea-protein isolation capacity. Agropur Dairy Cooperative leverages its cooperative structure to anchor whey-protein supply contracts with domestic sports-nutrition brands. Cargill Inc competes through backward integration into canola and soybean crushing that feeds protein-concentrate streams. Glanbia Plc specializes in micronized whey isolates for performance-nutrition applications, occupying premium positioning in Canadian distribution channels.
Technical Definition and Structural Segments
Canada protein encompasses animal-derived and plant-derived macronutrient concentrates, isolates, and hydrolysates standardized to minimum protein content thresholds, manufactured through mechanical separation, enzymatic hydrolysis, or solvent extraction for nutritional fortification. Whey protein dominates volume flows through established dairy-processing infrastructure, while pea protein captures accelerated capacity expansion as extraction yields improve and flavor-profile masking technologies mature. Sports nutrition commands margin concentration due to brand premiums and athlete-specific certification requirements, whereas functional foods represent the fastest-growing application as CPG manufacturers reformulate legacy products with protein enrichment.
Regulatory Framework and Forward Outlook
Health Canada governs novel food ingredient approvals under the Food and Drugs Act, while CFIA enforces labeling standards for protein content claims and allergen declarations. The Canadian Food Inspection Agency's Safe Food for Canadians Regulations shape import and domestic manufacturing compliance burdens that filter market access for new entrants. Stakeholders must monitor evolving plant-protein classification debates under Health Canada's novel food determinations, as these rulings will dictate which emerging protein sources achieve commercial scale in Canadian formulations.
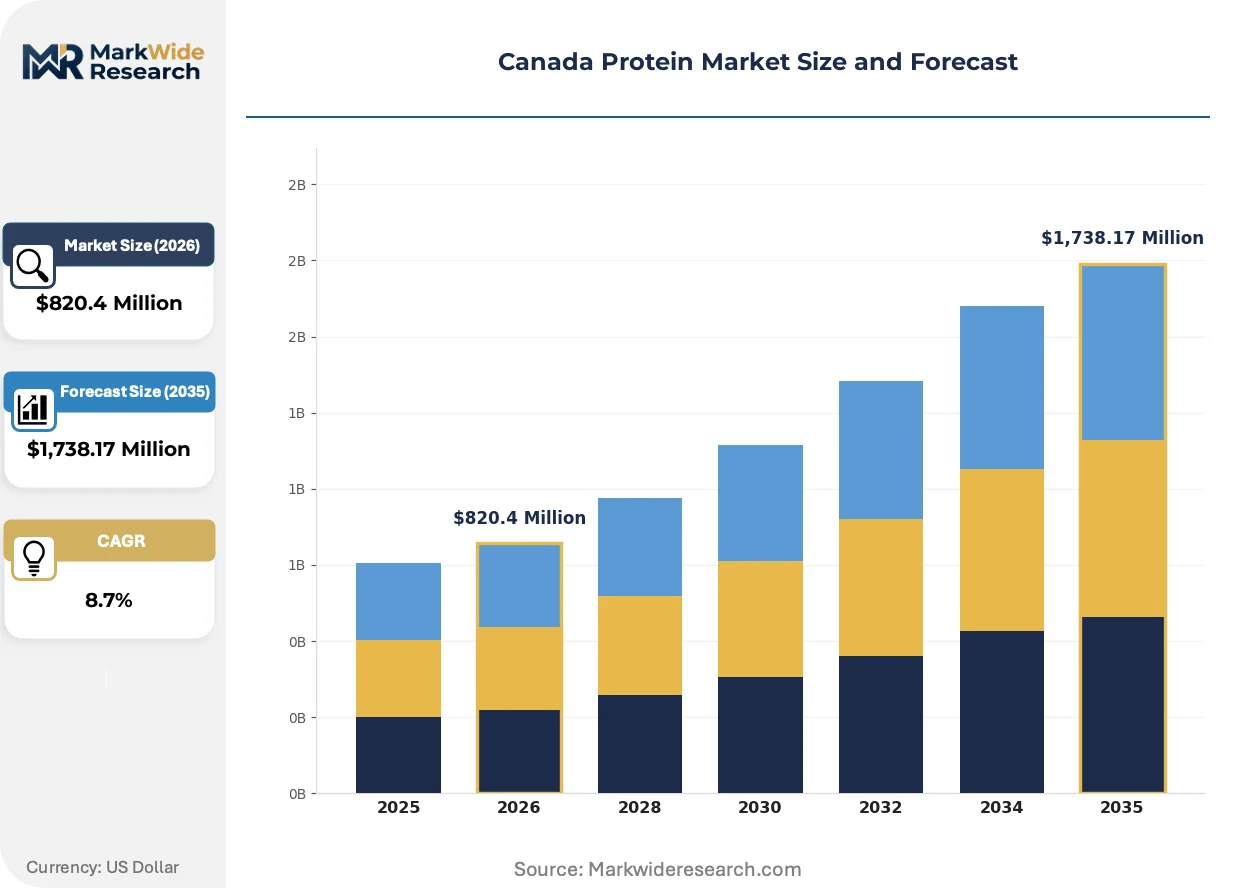
Market Dynamics
Health Canada's novel food determinations for plant-protein sources are compressing product development timelines while Alberta's pulse-processing investments reshape upstream supply geography.
Growth Catalysts
- CFIA labeling clarity:Standardized protein content claim rules reduce reformulation risk for functional food manufacturers expanding fortification programs.
- Sports nutrition shelf expansion:Canadian retailers are allocating dedicated protein-product sections, pulling through whey isolate and plant-blend SKUs.
- Enzymatic hydrolysis advances:Improved extraction yields from yellow pea varieties are lowering unit costs for domestic isolate production.
Market Restraints
- Novel food approval bottlenecks:Health Canada's determination backlog for emerging protein sources delays commercialization of fermentation-derived and insect-based ingredients.
- Dairy-whey supply concentration:Quebec and Ontario processing infrastructure dominates animal-protein flows, creating geographic single-source risk.
- Canola-meal protein limitations:Anti-nutritional factors and color instability restrict food-grade applications, capping oilseed-crushing byproduct valorization.
Strategic Opportunities
- Atlantic Canada underpenetration:Protein-fortified CPG presence lags Ontario-Quebec benchmarks, creating first-mover whitespace for regional distribution partnerships.
- Cell-cultured protein regulatory pathway:Health Canada's pre-market notification framework offers clarity for cultivated meat and dairy protein entrants.
- Direct-to-athlete subscription channels:E-commerce platforms bypass retail slotting fees, capturing margin from performance-nutrition consumers.
Industry Challenges
- Flavor-masking formulation expertise:Shortage of food scientists skilled in pea-protein off-note suppression limits clean-label product launches.
- Organic certification timelines:CFIA-accredited body backlogs delay organic protein ingredient qualification for export-oriented brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Protein Market |
| Market Size in 2026 | $820.4 Million |
| Market Size in 2035 | $1,738.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Protein, Casein Protein, Soy Protein, Pea Protein Application: Sports Nutrition, Functional Foods, Dietary Supplements, Animal Feed End User: Athletes, Bodybuilders, Health-Conscious Consumers, Vegans Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Agropur Dairy Cooperative, DuPont de Nemours Inc., Archer Daniels Midland Company, Lactalis Canada, Glanbia Plc, Roquette Frères, Cargill Inc, Burcon NutraScience Corporation, Saputo Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Protein Market Strategic Shifts
Protein ingredient technology is fragmenting across extraction methodologies while regulatory clarity and channel diversification reshape competitive access.
Precision fermentation for dairy-identical proteins is migrating from pharmaceutical contract manufacturing to food-grade production. Canadian biotech startups are securing toll-manufacturing agreements with existing fermentation facilities. This technology is compressing the timeline for novel whey and casein alternatives to reach price parity with conventional isolates.
Health Canada's Safe Food for Canadians Regulations enforcement is intensifying traceability requirements for imported protein concentrates. Domestic manufacturers are accelerating lot-level digital tracking system deployment. Sports nutrition brands sourcing international isolates face the steepest compliance cost increases.
Athlete certification programs are driving purchasing preference fragmentation. Third-party tested NSF Certified for Sport and Informed Sport labels are displacing unverified protein SKUs in performance channels. British Columbia and Alberta specialty retailers report the fastest certification-driven assortment shifts.
Canada Protein Market Segmentation
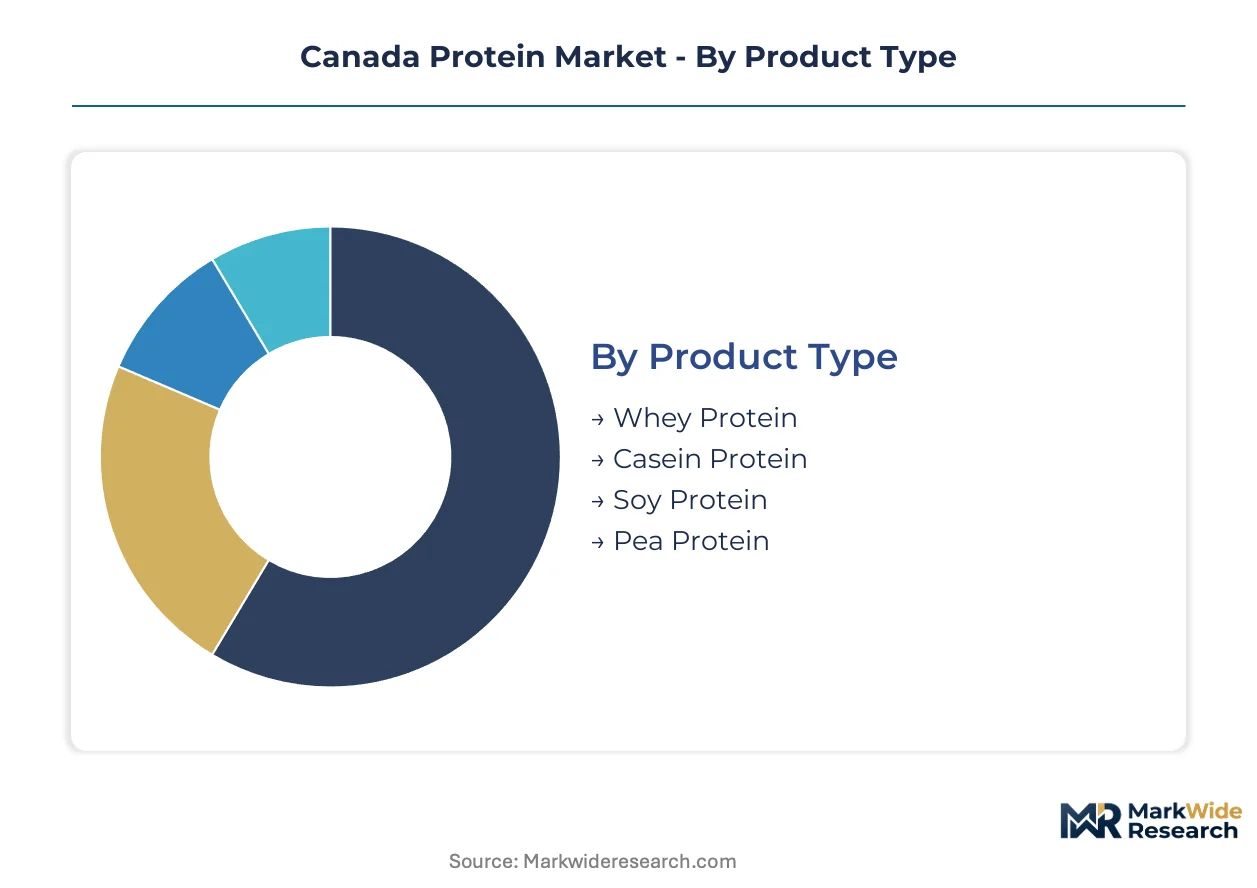
Protein ingredient purchasing in Canada fragments across performance-driven athletes seeking certified sports nutrition, health-conscious consumers prioritizing clean-label functional foods, and specialized dietary requirements from vegan and plant-based adopters. Each segment demands distinct formulation specifications, certification standards, and channel access patterns that reshape manufacturer portfolio priorities.
Product Type:
Mature extraction technologies dominate animal-derived categories while plant-protein isolation advances rapidly through enzymatic yield improvements and flavor-profile engineering.
- Whey Protein:Dairy-derived concentrates and isolates standardized to 80-90% protein content, manufactured through ultrafiltration and ion-exchange processes. Demand concentrates in Ontario and Quebec sports nutrition channels, where Agropur's cooperative infrastructure anchors domestic supply security and athlete-certification programs drive premium SKU placement.
- Pea Protein:Yellow pea isolates achieving 85%+ protein purity through wet-fractionation and air-classification advances. Alberta's emerging pulse-processing corridor captures capacity expansion as extraction yields improve and off-note masking technologies mature for clean-label CPG integration.
- Casein Protein:Micellar casein and calcium caseinate delivering slow-release amino acid profiles for overnight recovery formulations. Quebec dairy cooperatives control upstream supply through captive milk-protein separation infrastructure.
- Soy Protein:Defatted soy flour and soy protein isolates from domestic crushing operations, constrained by allergen labeling requirements and consumer preference shifts toward non-GMO and organic certifications.
Whey protein retains volume leadership; pea protein holds the steepest expansion curve.
Application:
Margin concentration varies sharply across channels, with sports nutrition commanding brand premiums while functional foods scale through mass-market CPG reformulation.
- Sports Nutrition:Protein powders, ready-to-drink beverages, and recovery bars targeting athlete performance with third-party certification requirements. CFIA labeling clarity for protein content claims reduces reformulation risk for domestic manufacturers expanding fortification programs.
- Functional Foods:Protein-enriched dairy alternatives, baked goods, and snack categories capturing mainstream consumer trial. British Columbia and Alberta retailers report the fastest assortment expansion as CPG brands respond to clean-label demand.
- Dietary Supplements:Capsule and tablet formats targeting aging demographics and specific health conditions, distributed primarily through pharmacy and online channels with stricter Health Canada Natural Health Product licensing.
- Animal Feed:Canola meal and oilseed processing byproducts valorized for livestock nutrition, limited by anti-nutritional factors restricting food-grade upgrade pathways.
Functional foods scale fastest through retail penetration; sports nutrition defends margin concentration through certification barriers.
End User:
Professional and recreational athletes anchor premium pricing power while vegan adopters reshape plant-protein demand trajectories.
- Athletes:Competitive and recreational performers requiring NSF Certified for Sport or Informed Sport verification for anti-doping compliance. Direct-to-athlete subscription channels bypass retail slotting fees and capture margin from performance-nutrition consumers.
- Vegans:Strict plant-based consumers driving pea-protein and emerging fermentation-derived ingredient demand, with purchasing decisions weighted toward complete amino acid profiles and sustainability credentials.
- Bodybuilders:High-volume protein consumers prioritizing cost-per-gram efficiency and leucine content thresholds, concentrated in specialty retail and online bulk purchasing.
- Health-Conscious Consumers:Mainstream wellness adopters seeking convenient protein enrichment without specialized athletic requirements, accessible through supermarket and mass-market channels.
Athletes retain premium pricing authority; vegans accelerate plant-protein formulation investment.
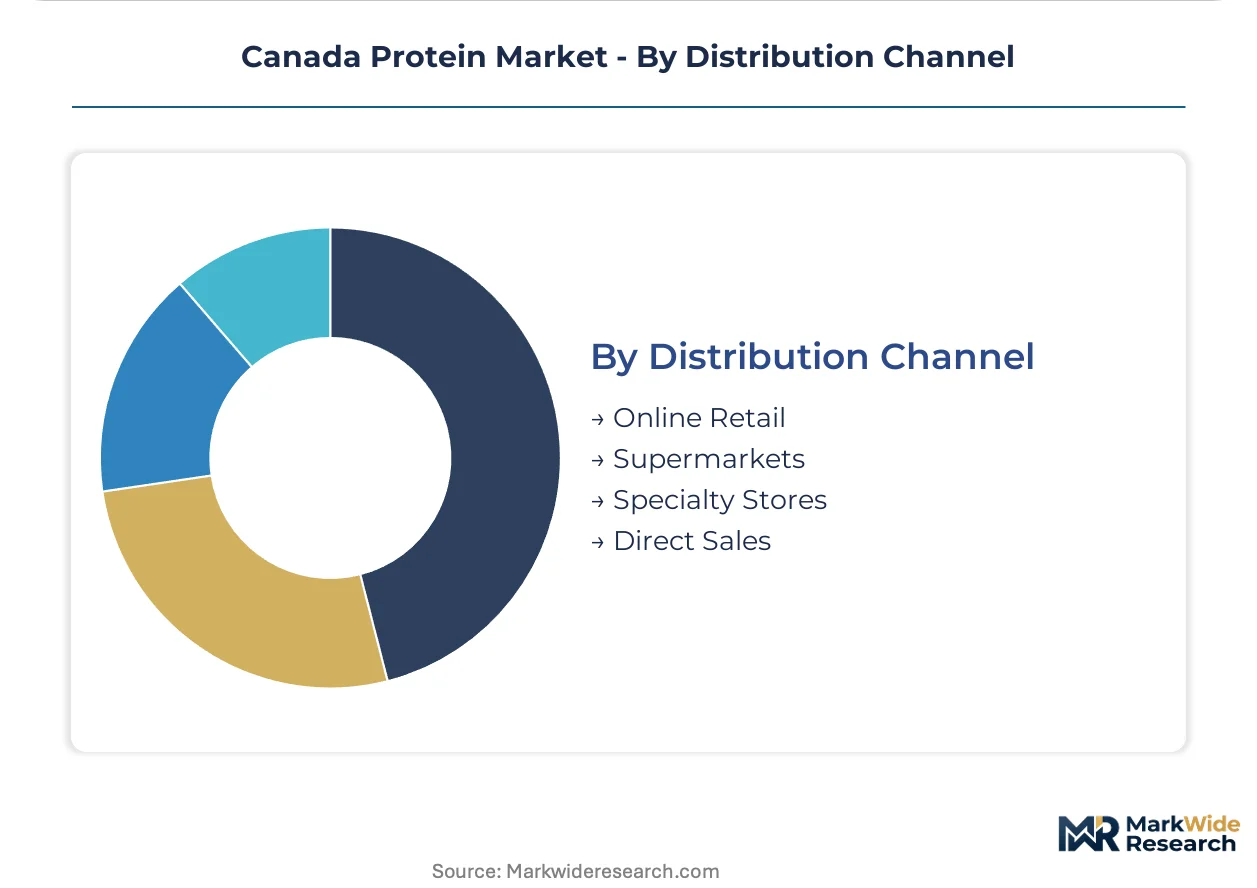
Distribution Channel:
Channel diversification is compressing traditional retail dominance as e-commerce platforms capture subscription loyalty and specialty retailers differentiate through certified assortment.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators offering subscription models and personalized formulation bundles. Atlantic Canada underpenetration creates first-mover whitespace for regional distribution partnerships.
- Specialty Stores:Independent and chain health food retailers curating third-party certified and organic protein selections. British Columbia specialty retailers report the fastest certification-driven assortment shifts.
- Supermarkets:Mass-market grocery channels expanding dedicated protein-product sections, pulling through whey isolate and plant-blend SKUs into mainstream purchasing occasions.
- Direct Sales:Multi-level marketing and practitioner channels for clinical-grade and personalized nutrition protocols, constrained by regulatory scrutiny of health claims.
Online retail captures the steepest share gain; supermarkets defend volume throughput through shelf-space expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health Canada anchors regulatory oversight for protein ingredient commercialization, while provincial manufacturing clusters concentrate production capacity across distinct agricultural corridors.
Ontario
Dairy-processing infrastructure dominates animal-protein flows through established whey and casein separation facilities. CFIA labeling enforcement for protein content claims shapes reformulation decisions for functional food manufacturers headquartered in the Golden Horseshoe. Toronto anchors sports nutrition brand distribution networks serving eastern Canadian retail channels.
Quebec
Cooperative dairy structures control upstream milk-protein supply security for domestic formulators. Health Canada's novel food determination backlog delays commercialization timelines for emerging plant-protein entrants seeking eastern market access. Montreal corridor clusters extraction technology providers serving both dairy and pulse-protein processors.
Alberta
Pulse-processing investments reshape upstream supply geography through yellow pea isolation capacity expansion. Provincial agricultural programs support extraction yield improvements for clean-label CPG integration. Calgary-Edmonton corridor attracts toll-manufacturing agreements for fermentation-derived protein startups.
British Columbia
Specialty retailers drive the fastest certification-driven assortment shifts for NSF Certified for Sport and Informed Sport verification. Direct-to-athlete subscription channels bypass traditional retail slotting fees in Vancouver's e-commerce ecosystem. Health Canada Natural Health Product licensing requirements filter pharmacy-channel supplement entries.
Atlantic Canada
Protein-fortified CPG presence lags Ontario-Quebec benchmarks across supermarket and mass-market channels. Regional distribution partnerships offer first-mover whitespace for functional food brands seeking underpenetrated shelf expansion. CFIA Safe Food for Canadians Regulations compliance costs disproportionately burden smaller maritime formulators.
Canada Protein Market Competitive Environment
Capability concentration sits with specialized extraction technology providers; scale advantage sits with integrated agricultural processors and multinational ingredient suppliers. The vendor base organizes around three strategic archetypes: cooperative dairy structures with captive milk-protein supply, oilseed and grain processors with backward integration into crushing operations, and toll-manufacturing biotech specialists. Dominant competitive moves include capacity expansion in Alberta's pulse-processing corridor and strategic partnerships bridging fermentation technology with existing food-grade production infrastructure.
Within the cooperative dairy tier, Agropur Dairy Cooperative and Lactalis Canada exemplify structures leveraging captive milk supply for whey and casein isolate production. Glanbia Plc occupies a position representing premium-tier micronized whey specialization for performance-nutrition certification requirements. Cargill Inc anchors the integrated agricultural processor archetype through oilseed crushing operations feeding protein-concentrate streams.
| Leading Market Players |
|---|
| Agropur Dairy Cooperative |
| DuPont de Nemours Inc. |
| Archer Daniels Midland Company |
| Lactalis Canada |
| Glanbia Plc |
| Roquette Frères |
| Cargill Inc |
| Burcon NutraScience Corporation |
| Saputo Inc. |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on Quebec and Ontario dairy-processing infrastructure determines both pricing tier spreads and supply chain shape. Health Canada novel food approval bottlenecks compress development timelines while concentrating pricing power among established whey isolate suppliers.
Pricing Analysis
Quebec-Ontario price spreads exceed Alberta-British Columbia benchmarks due to dairy cooperative supply concentration and CFIA compliance cost differentials. Three-tier pricing structure across premium, standard, and economy levels separates NSF Certified for Sport isolates from conventional whey concentrates and bulk commodity grades. Cost compression in economy tiers is intensifying because enzymatic hydrolysis advances lower pea-protein unit costs. Bodybuilders show highest price sensitivity through bulk purchasing behavior; athletes demonstrate lowest sensitivity due to certification requirements.
Supply Chain Analysis
Health Canada novel food determinations function as de facto export controls limiting fermentation-derived and insect-based protein flows into commercial channels. Geographic supply concentration centers on Canada, USA, and select European toll-manufacturing partners for precision fermentation capacity. Raw material dependencies draw from yellow pea varieties, dairy milk solids, and canola crushing streams. Single-source vulnerability concentrates in Quebec-Ontario dairy infrastructure. Distribution runs through supermarket dedicated protein sections, specialty retail certification-curated assortments, and direct-to-athlete subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada's protein market represents early-cycle expansion as precision fermentation technology migrates from pharmaceutical contract manufacturing toward food-grade price parity. Plant-protein capacity additions in Alberta pulse-processing corridors accelerate adoption curves beyond traditional dairy supply constraints.
For Market Incumbents: Build captive supply moats through backward integration into Alberta pea-protein isolation capacity and Quebec dairy cooperative supply contracts. Defensive consolidation should prioritize enzymatic hydrolysis yield improvements to counter fermentation-derived substitute threats. Channel control through direct-to-athlete subscription platforms protects margin from retail slotting fee compression.
For New Entrants and Emerging Players: Establish a beachhead in Atlantic Canada protein-fortified CPG whitespace where supermarket shelf expansion lags Ontario-Quebec benchmarks. Target functional foods reformulation partnerships with maritime CPG manufacturers seeking first-mover regional positioning. Go-to-market angle should leverage CFIA labeling clarity for protein content claims to reduce incumbent reformulation risk advantages.
For Investors and Strategic Acquirers: Health Canada's cell-cultured protein regulatory pathway clarity reshapes the acquisition landscape toward fermentation technology specialists with toll-manufacturing agreements. Long-term viability centers on five-to-ten year horizon positioning as novel protein sources achieve commercial scale. Acquisition target archetype: Canadian biotech startups securing food-grade fermentation capacity partnerships. Signal to watch: Health Canada novel food determination backlog resolution timelines as inflection indicator for emerging protein source market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Alberta Pulse-Processing Capacity Expansion | Captures enzymatic yield improvements for clean-label CPG integration at lower unit costs. |
| Precision Fermentation Toll-Manufacturing Agreements | Compresses timeline for dairy-identical proteins to reach price parity with conventional isolates. |
| NSF Certified for Sport Program Investment | Secures premium shelf placement in British Columbia and Alberta specialty retail channels. |
| Direct-to-Athlete Subscription Channel Launch | Bypasses retail slotting fees while capturing margin from performance-nutrition consumer segments. |
| Atlantic Canada Distribution Partnership Formation | Exploits underpenetrated supermarket and mass-market protein-fortified CPG whitespace. |
Study Parameters
Initial hypotheses were tested against primary input from protein ingredient procurement managers, sports nutrition brand formulators, CFIA regulatory affairs specialists, and Alberta pulse-processing facility operators and refined through secondary validation. Secondary sources drew from Health Canada novel food determination databases, CFIA Safe Food for Canadians Regulations guidance documents, Canadian dairy cooperative annual reports, and customs trade data on protein concentrate imports. Bottom-up capacity assessments and top-down demand modeling were triangulated to establish market size parameters.
Demand-supply-balance framing anchored the analytical approach across the projection horizon. Segmentation dimensions modeled included product type tiers, application channels, end-user archetypes, and provincial distribution patterns. CAGRs were derived from elasticity-adjusted volume projections and value-chain margin analysis. Industry-specific forecast inputs incorporated enzymatic hydrolysis yield improvement curves and Health Canada approval timeline probability distributions.
Sensitivities concentrate around Health Canada novel food determination backlog resolution, Alberta pulse-processing capacity commissioning schedules, and dairy-whey supply concentration disruption events. Forecasts reflect documented assumptions regarding regulatory pathway clarity and extraction technology maturation curves. Material shifts in Health Canada's classification rulings for plant-protein sources would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Selenium Yeast Market
Nutritional Supplements
South America Omega-3 Products Market
Nutritional Supplements
Global Natural Health Supplements Market
Nutritional Supplements
Global Antioxidant Market
Nutritional Supplements
Whey Protein Concentrate Market
Nutritional Supplements
Marine Supplements Market
Nutritional Supplements
Organic Whey Protein Market
Nutritional Supplements
Japan Protein Market
Nutritional Supplements
Nutritional Drink Market
Nutritional Supplements
Marine Collagen Market
Nutritional Supplements
Longevity and Anti-Aging Brain Health Supplements Market
Nutritional Supplements
Vegan Protein Supplements Market
Nutritional Supplements
Middle East and Africa Nutricosmetics Market
Nutritional Supplements
Chromium Picolinate Market
Nutritional Supplements
Global Hangover Rehydration Supplements Market
Nutritional Supplements
Bovine Lactoferrin Market