
 Global Natural Health Supplements Market | 2026-2036
Global Natural Health Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Global Natural Health Supplements Market Outlook
Multi-source botanical sourcing is shifting toward vertically integrated supply chains as quality volatility pressures finished-goods consistency. Nestlé Health Science leverages captive cultivation partnerships across three continents to secure traceable raw material. Glanbia plc anchors its position through dairy-derived protein specialization that extends into sports nutrition adjacencies. BASF SE competes on synthetic vitamin B complexes while navigating natural-origin certification demands from European buyers.
Natural health supplements comprise orally administered products derived from plant, mineral, or microbial sources formulated to support physiological function beyond basic nutrition. Manufacturing relies on extraction protocols—supercritical CO2 for heat-sensitive botanicals, freeze-drying for probiotic viability—that preserve bioactive compound integrity through finished-goods shelf life. Herbal supplements occupy the deepest margin pool due to premium positioning and limited generic substitution, while probiotic formats in gummy and liquid delivery systems represent the fastest-expanding structural segment as palatability drives pediatric and senior compliance. Vitamins sustain volume leadership through fortified food crossover demand and pharmacy channel ubiquity.
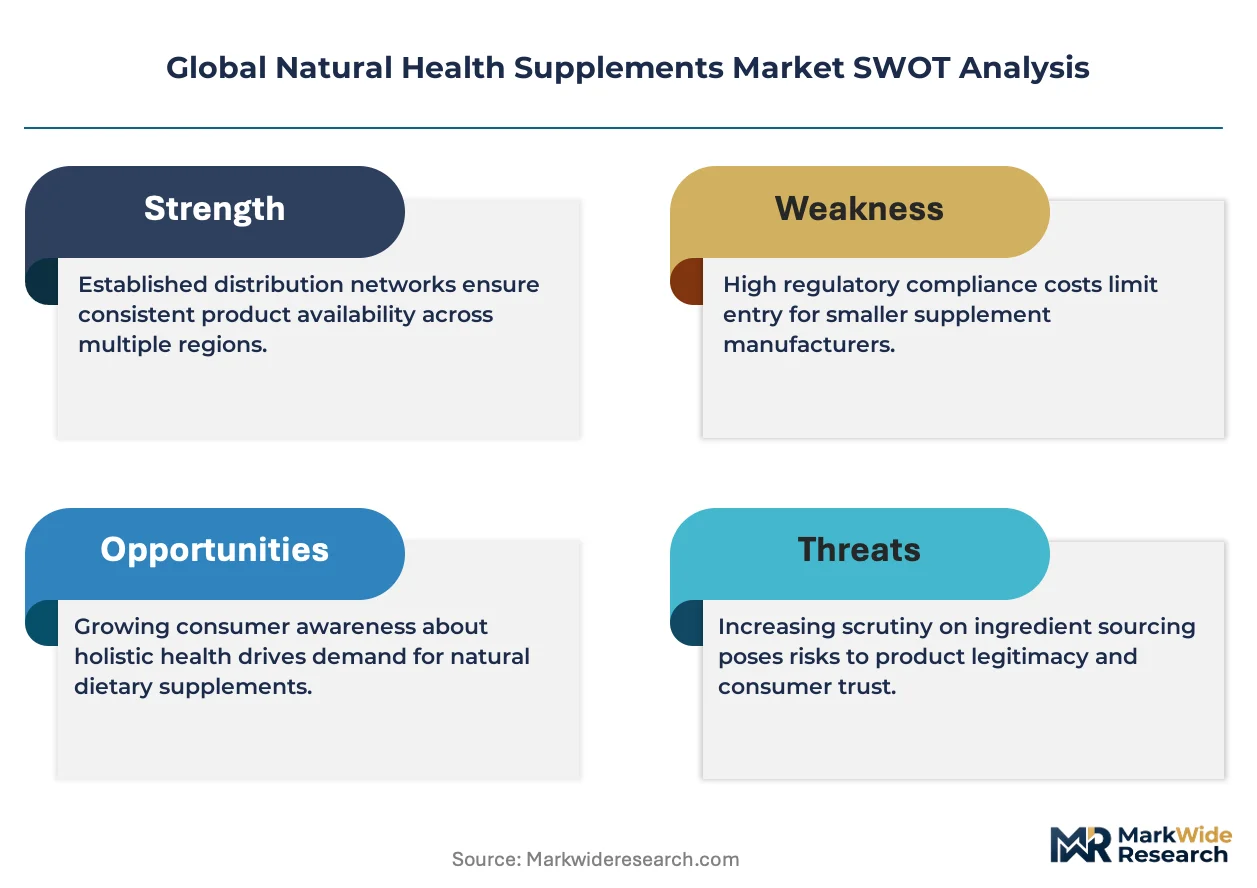
FDA's Current Good Manufacturing Practice framework for dietary supplements mandates identity testing, purity verification, and adulteration screening that elevates compliance costs for new market entrants. EFSA novel food authorizations and EMA traditional herbal registration pathways create asynchronous approval timelines across Atlantic markets, fragmenting launch sequencing for botanical innovators. Stakeholders must monitor evolving pharmacovigilance linkages between supplement adverse event reporting and national reimbursement exclusion lists that threaten category access.
Market Dynamics
Clean-label certification requirements are compressing formulation timelines as brands race to meet EFSA novel food authorizations before competitors secure shelf space in European pharmacy chains.
Growth Catalysts
- EFSA Novel Food Regulation:The EU's streamlined botanical safety assessments are accelerating ingredient approvals for traditional herbal entrants seeking pharmacy channel placement.
- Sports nutrition segment:Athlete demand for traceable recovery formulations is pulling supercritical CO2 extraction capacity toward high-margin protein-botanical combinations.
- Direct-to-consumer platforms:United States wellness subscriptions are bypassing traditional retail gatekeepers and capturing premium pricing through personalized regimen bundling.
Market Restraints
- Raw material concentration:Wild-harvested botanical supply clusters in specific Himalayan and Andean zones, exposing finished-goods makers to climate-driven harvest volatility.
- FDA cGMP compliance costs:Identity testing and adulteration screening mandates impose capital barriers that favor incumbent manufacturers with captive laboratory infrastructure.
- Synthetic vitamin substitution:BASF SE's chemically derived B-complex formulations undercut natural-origin pricing in cost-sensitive pharmacy segments.
Strategic Opportunities
- Geriatric compliance formats:Liquid and gummy probiotic delivery systems address swallowing difficulties in Japan's aging demographic, opening pediatric formulation crossover.
- India's Ayush export pathway:Ministry of AYUSH certification reciprocity agreements are creating accelerated market access for traditional medicine practitioners in Middle Eastern markets.
- Freeze-drying and encapsulation convergence:Combined technologies are extending probiotic viability through ambient supply chains, eliminating cold-chain infrastructure requirements.
Industry Challenges
- Phytochemistry analytical talent scarcity:Standardization of bioactive compound profiling requires specialized chromatography expertise that outpaces university pipeline output.
- Asynchronous approval timelines:FDA dietary supplement notifications and EMA traditional herbal registrations proceed on incompatible schedules, fragmenting global launch sequencing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Natural Health Supplements Market |
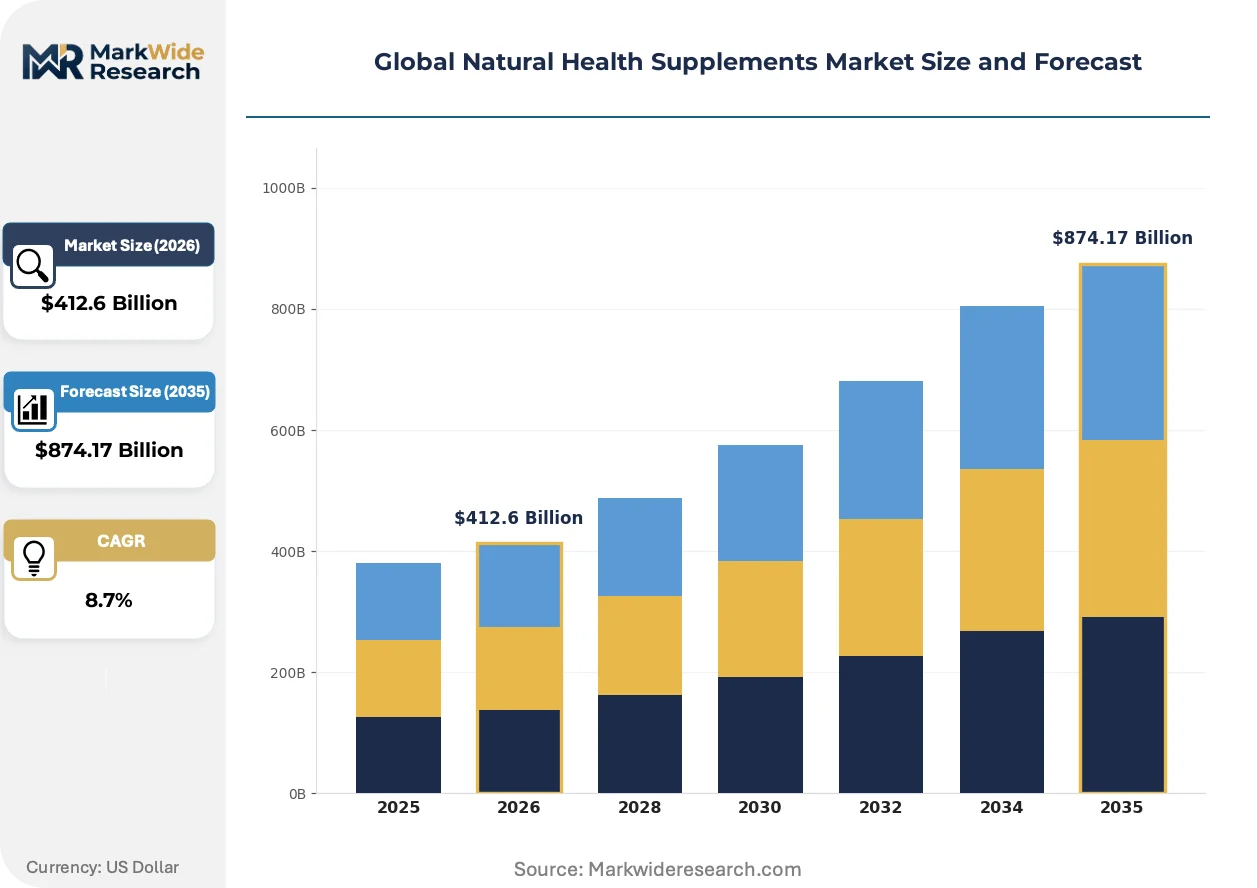
| Market Size in 2026 | $412.6 Billion |
| Market Size in 2035 | $874.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbal Supplements, Vitamins, Probiotics, Minerals Form: Capsules, Powders, Liquid, Gummies Distribution Channel: Online Stores, Supermarkets, Health Food Shops, Pharmacies Customer Type: Adults, Seniors, Athletes, Children |
| Companies Covered | Nestlé Health Science, Abbott Laboratories, Herbalife Nutrition, Amway, Glanbia plc, BASF SE, Nature's Bounty, Otsuka Holdings Co., Ltd, Archer Daniels Midland, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Natural Health Supplements Market Strategic Shifts
Biomanufacturing advances and regulatory digitization are compressing development cycles while reshaping how botanical ingredients achieve market authorization across Atlantic frameworks.
Supercritical CO2 extraction is converging with subcritical water processing to recover heat-sensitive polyphenols without organic solvent residues. Sports nutrition formulators in Germany and California are adopting these hybrid systems to meet clean-label claims. The technology convergence is enabling single-origin botanical positioning that commands shelf-space premiums in pharmacy channels.
EFSA's novel food transparency initiative is mandating full bioactive disclosure for botanical entrants seeking safety approvals. European manufacturers must now submit complete metabolomic profiles rather than marker compound summaries. Traditional herbal suppliers in Italy and Spain are restructuring documentation workflows to meet these digitized submission requirements.
Subscription-based personalized nutrition is displacing one-size-fits-all multivitamin purchasing in direct-to-consumer channels. United States platforms now bundle microbiome testing with probiotic regimen customization, capturing recurring revenue that retail pharmacies cannot match. This behavioral shift concentrates demand among urban wellness consumers willing to trade price transparency for convenience.
Global Natural Health Supplements Market Segmentation
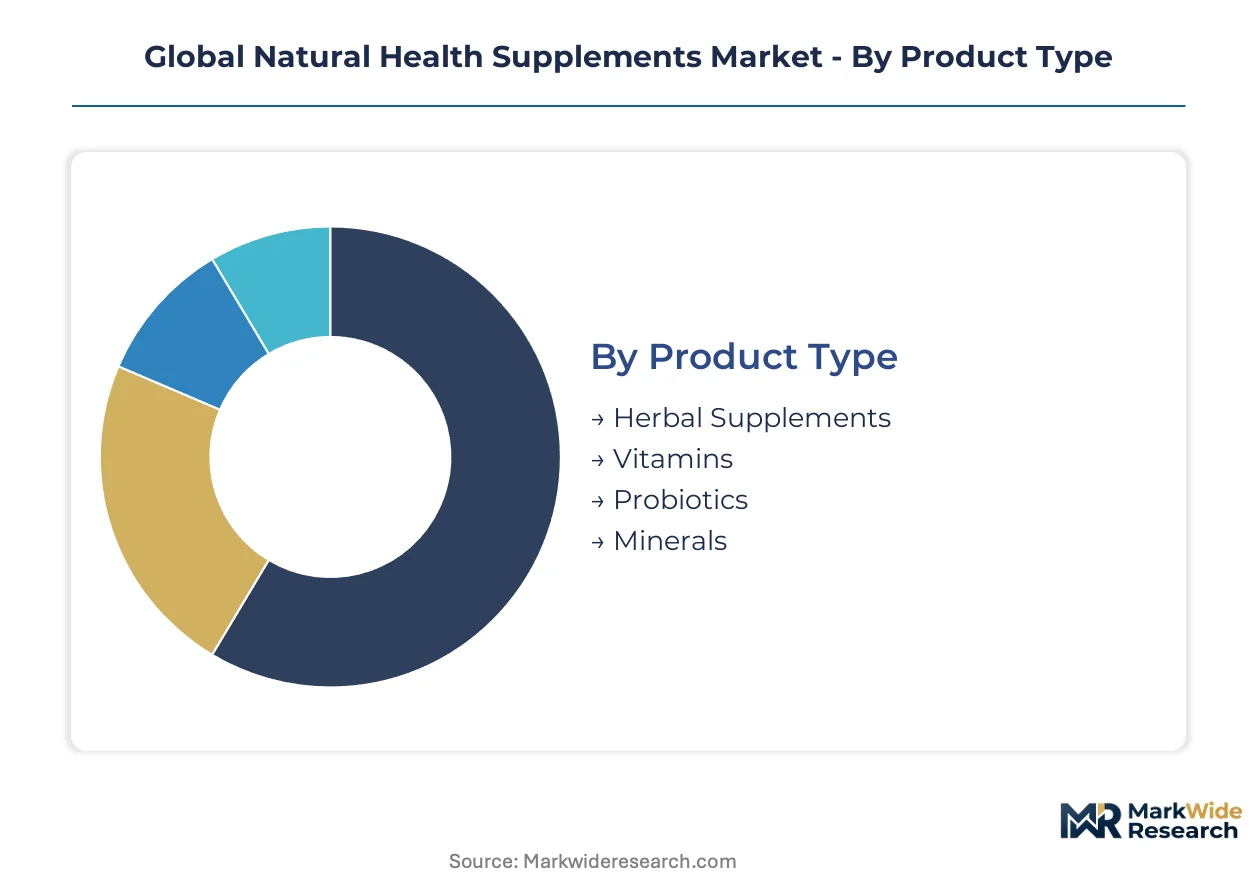
Segmentation in natural health supplements reveals how formulation chemistry, delivery mechanics, and purchase context fragment demand across distinct margin pools. Product type and form decisions determine manufacturing infrastructure requirements, while channel and customer splits dictate regulatory compliance burdens and marketing spend allocation.
Product Type:
Volume leadership concentrates in mass-market vitamins, while premium margin capture sits with specialized botanical extracts that resist generic substitution.
- Herbal Supplements:Plant-derived formulations containing standardized bioactive compounds—alkaloids, flavonoids, terpenoids—extracted through supercritical CO2 or ethanol protocols. Demand clusters in Germany and Italy where EFSA traditional herbal registrations enable pharmacy channel placement, though novel food authorization delays constrain new botanical entrants.
- Vitamins:Synthetic and fermentation-derived essential micronutrients formulated as single-entity or multivitamin complexes. Mass-market penetration in the United States and India sustains volume leadership through fortified food crossover and pharmacy OTC ubiquity, despite pricing pressure from BASF SE's chemically derived B-complex supply.
- Probiotics:Live microbial cultures—Lactobacillus, Bifidobacterium strains—requiring freeze-drying or encapsulation for ambient shelf stability. Pediatric and geriatric compliance in Japan's aging demographic drives gummy and liquid format innovation.
- Minerals:Chelated and inorganic elemental supplements—calcium, magnesium, zinc, iron—addressing deficiency correction and bone health protocols. Chelated forms command premium positioning in United States direct-to-consumer subscriptions.
Mature deployment sits with Vitamins. Newer deployment is concentrated in Probiotics.
Form:
Manufacturing cost tiers separate high-throughput powder operations from precision encapsulation and specialized gummy production lines.
- Capsules:Gelatin and hydroxypropyl methylcellulose shells delivering precise dosing with taste-masking for bitter botanical actives. Two-piece hard capsules dominate clinical trial supply and pharmacy professional channels where dosing accuracy outweighs convenience premiums.
- Powders:Bulk active ingredients with minimal excipient load, enabling flexible dosing and sports nutrition stacking protocols. Athletes in California and Germany drive demand for unflavored protein-botanical combinations that integrate with personalized regimen bundling.
- Liquid:Aqueous or oil-based suspensions addressing swallowing difficulties in pediatric and geriatric populations. Japan's Ministry of Health, Labour and Welfare guidelines on pediatric formulation safety shape liquid probiotic innovation pipelines.
- Gummies:Gelatin or pectin matrices combining palatability engineering with active stability challenges. Sugar-free and clean-label iterations are expanding most quickly in United States wellness subscriptions targeting compliance-driven repeat purchase.
High-volume production concentrates in Capsules. Steepest expansion trajectory is concentrated in Gummies.
Distribution Channel:
Channel selection determines margin retention, with direct-to-consumer platforms capturing recurring revenue that retail gatekeepers cannot replicate.
- Online Stores:Direct-to-consumer platforms and marketplace aggregators enabling subscription bundling and microbiome-test integration. United States wellness subscriptions bypass pharmacy retail markups through personalized regimen algorithms.
- Supermarkets:Mass-market shelf space for vitamins and mainstream botanicals with impulse-purchase positioning. Clean-label certification requirements compress formulation timelines as brands race for limited shelf resets.
- Health Food Shops:Specialty retail emphasizing organic certification, single-origin traceability, and practitioner consultation. EFSA novel food transparency mandates reshape how European health food retailers validate botanical provenance claims.
- Pharmacies:Professional-channel placement requiring regulatory registration—FDA dietary supplement notifications, EMA traditional herbal registrations, or national pharmacy reimbursement codes. Asynchronous approval timelines across Atlantic markets fragment global launch sequencing for botanical innovators.
Recurring revenue capture concentrates in Online Stores. Regulatory validation requirements concentrate in Pharmacies.
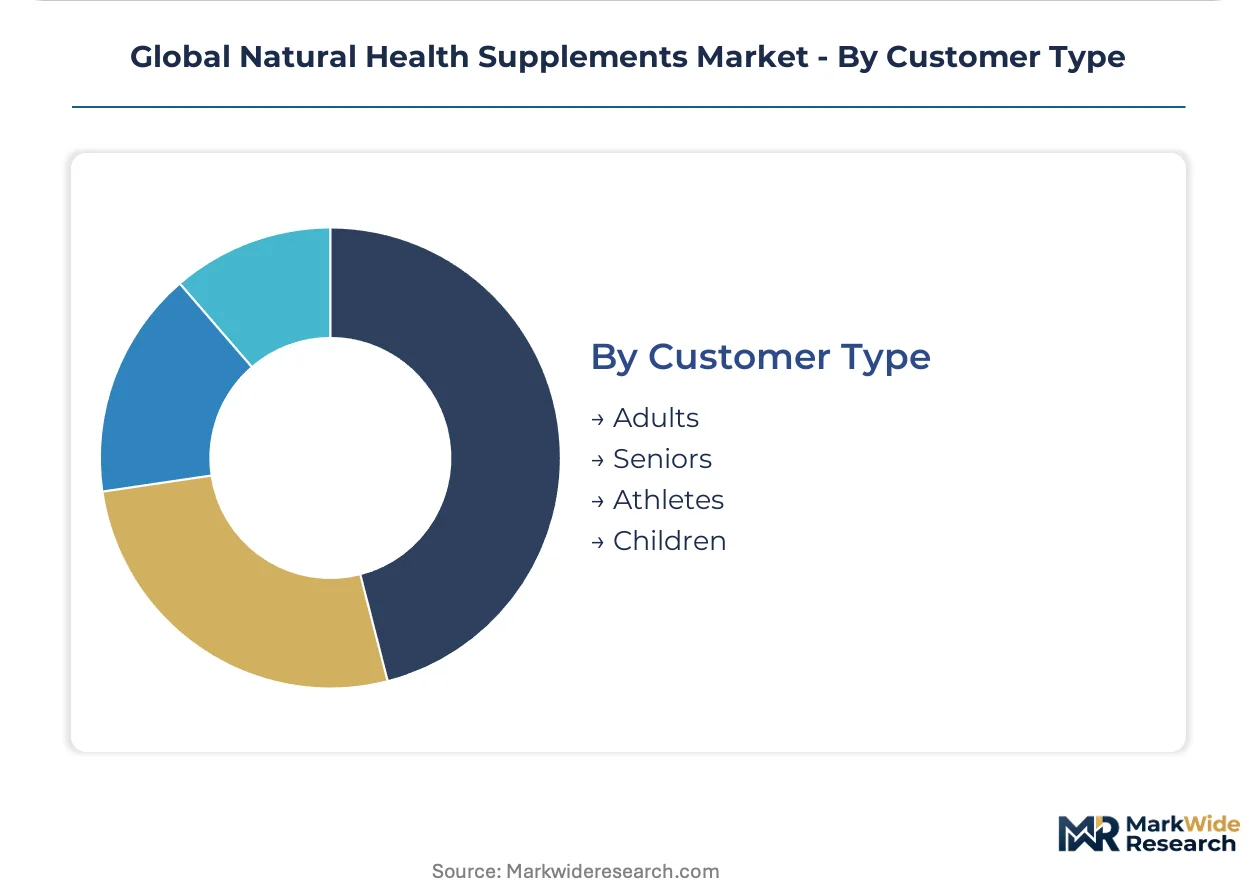
Customer Type:
Physiological life-stage segmentation dictates formulation potency, delivery format, and compliance packaging requirements.
- Adults:Working-age consumers aged 18-64 pursuing preventive wellness, stress management, and performance optimization. United States urban professionals drive subscription personalization through microbiome testing integration.
- Seniors:Consumers aged 65+ with swallowing difficulties, polypharmacy interactions, and bone-density concerns. Liquid and gummy probiotic formats address Japan's aging demographic compliance challenges.
- Athletes:Competitive and recreational performers prioritizing traceable recovery formulations and banned-substance certification. Supercritical CO2 extraction capacity shifts toward high-margin protein-botanical combinations for this segment.
- Children:Pediatric populations requiring palatability engineering, precise micro-dosing, and safety-validated excipients. Gummy formats with pectin bases gain share fastest where clean-label claims meet parental purchase criteria.
Subscription monetization concentrates with Adults. Format innovation investment concentrates with Children.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Himalayan and Andean wild-harvest zones anchor raw material sourcing for botanical extraction, while finished-goods manufacturing clusters concentrate in Germany, the United States, Japan, India, and Australia.
United States
Direct-to-consumer wellness subscriptions and microbiome-test bundling drive demand among urban professionals seeking personalized regimens. FDA Current Good Manufacturing Practice mandates for identity testing and adulteration screening elevate compliance barriers for new entrants. California sports nutrition formulators deploy supercritical CO2 extraction capacity toward protein-botanical combinations for athlete recovery segments.
Germany
EFSA traditional herbal registrations enable pharmacy channel placement for standardized botanical extracts, particularly alkaloid and flavonoid formulations. The EU Novel Food Regulation's streamlined safety assessments accelerate ingredient approvals for clean-label entrants. Bavarian extraction facilities converge supercritical CO2 with subcritical water processing to recover heat-sensitive polyphenols without organic solvent residues.
Japan
Liquid and gummy probiotic formats address compliance challenges in an aging demographic with swallowing difficulties. Ministry of Health, Labour and Welfare guidelines on pediatric formulation safety shape innovation pipelines for pectin-based delivery systems. Kanto region manufacturers extend probiotic viability through freeze-drying and encapsulation convergence, eliminating cold-chain infrastructure requirements.
India
Ministry of AYUSH certification reciprocity agreements create accelerated market access for traditional medicine practitioners targeting Middle Eastern export pathways. FSSAI fortification mandates sustain volume demand for mass-market vitamin complexes. Maharashtra-based suppliers leverage captive cultivation partnerships to secure traceable raw material for finished-goods consistency.
Australia
TGA regulatory validation requirements for complementary medicines concentrate professional-channel placement investments among incumbent manufacturers. Sports nutrition demand from recreational and competitive athletes pulls extraction capacity toward banned-substance-certified recovery formulations. Sydney and Melbourne direct-to-consumer platforms capture recurring revenue through subscription personalization that retail pharmacies cannot match.
Global Natural Health Supplements Market Competitive Environment
Capacity expansion dominates the current landscape as manufacturers secure captive cultivation partnerships and extraction infrastructure across three continents. The vendor base stratifies between multinational nutrition conglomerates with dairy-derived protein specialization, synthetic vitamin specialists navigating natural-origin certification demands, and botanical extraction specialists pursuing EFSA novel food authorizations. Three archetypes define competitive positioning: vertically integrated supply chain controllers, format innovation specialists in gummy and liquid delivery systems, and direct-to-consumer platform operators capturing recurring revenue through personalized regimen bundling. M&A activity and geographic expansion into Middle Eastern and Asia-Pacific markets represent the dominant competitive moves.
Within the nutrition conglomerate tier, Nestlé Health Science and Glanbia plc exemplify divergent strategic anchors. Nestlé Health Science occupies a position as a vertically integrated supply chain controller through captive cultivation partnerships spanning multiple continents. Glanbia plc sits within the dairy-derived protein specialization archetype, extending into sports nutrition adjacencies through extraction capacity deployment. Among synthetic input suppliers, BASF SE represents the chemically derived formulation specialist competing on cost while navigating European natural-origin certification demands. These three entities collectively illustrate how competitive positioning fragments across raw material control, manufacturing specialization, and certification pathway navigation.
| Leading Market Players |
|---|
| Nestlé Health Science |
| Abbott Laboratories |
| Herbalife Nutrition |
| Amway |
| Glanbia plc |
| BASF SE |
| Nature's Bounty |
| Otsuka Holdings Co., Ltd |
| Archer Daniels Midland |
| Others |
Value Chain & Pricing Dynamics
Supercritical CO2 extraction convergence with subcritical water processing is compressing production economics for heat-sensitive botanicals while simultaneously concentrating capacity among German and California facilities that can deploy hybrid systems at scale. This technology transition fragments pricing power between legacy solvent-based operators facing margin erosion and clean-label-certified manufacturers capturing pharmacy channel premiums.
Pricing Analysis
Warranty-backed certification bundling separates pharmacy-validated botanical extracts from unverified direct-to-consumer alternatives, with EFSA traditional herbal registrations and FDA cGMP compliance serving as the bundled assurance layer. Three-tier pricing structure across premium, standard, and economy levels tracks certification depth and extraction method transparency, with supercritical CO2-derived alkaloids commanding substantial markups over ethanol-extracted equivalents. Price differentiation hinges on traceability documentation and banned-substance testing depth, particularly for athlete-targeted recovery formulations. Cost compression in standard-tier vitamins is intensifying because BASF SE's synthetic B-complex supply undercuts fermentation-derived alternatives, though premium-tier buyers in United States wellness subscriptions exhibit minimal price sensitivity.
Supply Chain Analysis
Domestic-content mandates under India's Ministry of AYUSH certification reciprocity agreements are redirecting traditional herbal sourcing toward Maharashtra-based captive cultivation partnerships and away from Himalayan wild-harvest clusters. Wild-harvested botanical supply draws from specific Himalayan and Andean zones, while finished-goods manufacturing rests on extraction infrastructure in Germany, California, and Japan. Single-source vulnerability concentrates in climate-exposed wild-harvest regions where erratic monsoon patterns disrupt alkaloid-rich plant availability. Distribution runs through pharmacy professional channels in Europe, direct-to-consumer platforms in the United States, and health food retail in Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Freeze-drying and encapsulation convergence represents a technology-transition phase replacing legacy cold-chain-dependent probiotic logistics, with ambient-stable viability unlocking pediatric and geriatric format expansion.
For Market Incumbents: To counter synthetic vitamin substitution pressure from chemically derived B-complex suppliers, Nestlé Health Science and Glanbia plc should deepen backward integration into captive cultivation partnerships across three continents while accelerating EFSA novel food authorization submissions for proprietary botanical extracts. Certification investment in traditional herbal registrations serves as the priority defensive lever against emerging clean-label entrants. For New Entrants and Emerging Players: Direct-to-consumer wellness platforms offer the most penetrable channel white-space, particularly for microbiome-test-integrated subscription bundling that incumbent pharmacies cannot replicate. Target liquid and gummy probiotic formats for Japan's aging demographic and pediatric crossover segments. Pursue Ministry of AYUSH certification reciprocity as the go-to-market angle for Middle Eastern export pathways. For Investors and Strategic Acquirers: Exit pathways concentrate in format innovation specialists with demonstrated ambient-stability technology and direct-to-consumer recurring revenue engines. Long-term viability over the next decade favors vertically integrated supply chain controllers with multi-continent cultivation partnerships and pharmacy channel registration depth. Watch EFSA novel food authorization backlog clearance as the signal indicating inflection in European botanical market access.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Cultivation Partnership Expansion | Secures traceable raw material for Nestlé Health Science across Himalayan and Andean zones. |
| EFSA Novel Food Authorization Acceleration | Unlocks pharmacy channel placement for Italian and Spanish traditional herbal suppliers. |
| Freeze-Drying and Encapsulation Convergence | Eliminates cold-chain infrastructure requirements for Kanto region probiotic manufacturers. |
| Direct-to-Consumer Platform Launch | Captures recurring revenue through personalized regimen bundling in United States urban markets. |
| Ministry of AYUSH Certification Reciprocity | Creates accelerated Middle Eastern market access for Maharashtra-based traditional medicine exporters. |
Study Parameters
FDA dietary supplement notifications, EFSA novel food submission databases, and Ministry of AYUSH certification records formed the secondary backbone, cross-referenced with primary interviews involving extraction facility operators, pharmacy procurement managers, direct-to-consumer platform executives, and regulatory affairs specialists at botanical suppliers. Bottom-up demand modeling triangulated against top-down value chain analysis validated segmentation splits across product type, delivery format, and channel structure.
Historical trendline analysis of supercritical CO2 extraction capacity deployment and probiotic format innovation pipelines informed trajectory assumptions across the projection horizon. The analytical framework modeled dimensions including botanical source type, extraction methodology, regulatory approval pathway, distribution channel, and regional compliance cluster. CAGRs were synthesized from capacity expansion announcements, channel shift velocity, and substitution elasticity between synthetic and natural-origin vitamin formulations.
Caveats apply where EFSA-EMA asynchronous approval timeline resolution, Himalayan climate volatility, or FDA cGMP enforcement intensity shifts could materially shift the outlook. Forecasts reflect documented assumptions about regulatory digitization pace and clean-label certification adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Middle East and Africa Nutraceutical Excipients Market
Nutritional Supplements
Horehound Supplement Market
Nutritional Supplements
Low-Carb Fat Loss Market
Nutritional Supplements
Chromium Picolinate Market
Nutritional Supplements
Global Corn Germs Supplements Market
Nutritional Supplements
Middle East and Africa Amino Acid in Dietary Supplements Market
Nutritional Supplements
Coq10 Gummies Market
Nutritional Supplements
Digestive Health Supplements Market
Nutritional Supplements
Mushroom Powders Market
Nutritional Supplements
South America Botanical Supplements Market
Nutritional Supplements
Lipid Nutrition Market
Nutritional Supplements
Krill Oil Supplements Market
Nutritional Supplements
Nutrition Therapy Market
Nutritional Supplements
North America Bovine Lactoferrin Market
Nutritional Supplements
High-Concentrated Protein Market
Nutritional Supplements
Gummy Vitamins Market