
 Horehound Supplement Market | 2026-2036
Horehound Supplement Market Size, Share, and Industry Trends Forecast 2026-2036
Horehound Supplement Market Analytics
Market Dynamics and Competitive Structure
The capability gap between vertically integrated herb processors and contract-reliant brands is redrawing competitive boundaries in horehound supplements. Ricola Group AG leverages captive cultivation and proprietary extraction infrastructure to sustain margin control across European and North American pharmacy channels. NOW Foods competes on manufacturing scale, operating multi-form facilities that anchor cost positions in capsules and bulk extracts. Gaia Herbs differentiates through certified organic sourcing and vertical traceability, positioning its supply chain as a premium credential in health-store retail.
Product Definition and Segment Architecture
Horehound supplements deliver standardized preparations of Marrubium vulgare, a bitter-tonic herb containing marrubiin and volatile oils extracted through aqueous or ethanol processes for respiratory and digestive applications. Capsules dominate volume through pharmacy and supermarket channels where convenience drives repeat purchase, while extracts command premium pricing in practitioner-directed sales. Teas retain structural importance in European markets with established herbal traditions, whereas gummies represent the fastest-growing form as manufacturers target younger demographics through online retail and health-store placement.
Regulatory Environment and Strategic Outlook
The FDA oversees dietary supplement safety and labeling under DSHEA, while the USDA National Organic Program governs certification claims that shape consumer willingness-to-pay in premium tiers. The European Medicines Agency evaluates traditional herbal registrations under THMPD, creating divergent compliance pathways that fragment market access for standardized versus whole-herb products. Stakeholders must monitor evolving substantiation requirements for respiratory health claims, as regulatory scrutiny of cough-relief positioning intensifies across both jurisdictions and threatens existing marketing frameworks.
Market Dynamics
The FDA's intensifying scrutiny of respiratory health claims under DSHEA is compressing marketing frameworks and forcing manufacturers toward substantiation investments that favor scaled players with clinical trial capabilities over smaller entrants.
Growth Catalysts
- DSHEA Labeling Clarity:The FDA's 2023 guidance on structure-function claims has reduced enforcement ambiguity, allowing compliant brands to market cough-relief positioning with greater legal certainty.
- Ethanol Extraction Advancement:Supercritical CO2 and advanced ethanol methods are improving marrubiin standardization, enabling dose-consistent products that satisfy practitioner channels.
- United States Demand Concentration:American consumers' established herbal supplement habits and robust direct-to-consumer infrastructure create predictable offtake for domestic and imported horehound products.
Market Restraints
- Raw Material Volatility:Marrubium vulgare cultivation concentrates in Mediterranean and Balkan regions, exposing processors to climate-driven harvest variability and price spikes.
- THMPD Fragmentation:The European Medicines Agency's Traditional Herbal Medicinal Products Directive creates divergent registration pathways that block standardized extracts from whole-herb markets and vice versa.
- Synthetic Expectorant Substitution:Dextromethorphan and guaifenesin formulations retain pharmacy shelf dominance through insurance reimbursement and physician familiarity.
Strategic Opportunities
- Gummy Format Expansion:Younger demographics' aversion to capsules and bitters creates whitespace for palatable, low-dose horehound gummies distributed through TikTok-native wellness brands.
- USDA Organic Certification:The National Organic Program's consumer recognition enables 40-60% price premiums in health-store and subscription channels for certified supply chains.
- Practitioner Channel Penetration:Naturopathic and functional medicine clinics represent underdeveloped prescription-alternative outlets for liquid extracts with documented standardization.
Industry Challenges
- Substantiation Talent Scarcity:Clinical trial design and regulatory writing expertise for botanical claims commands premium salaries that strain mid-tier manufacturer budgets.
- Extraction Equipment Capex:GMP-compliant supercritical CO2 systems require seven-figure capital commitments that exclude contract manufacturers from premium extract segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Horehound Supplement Market |
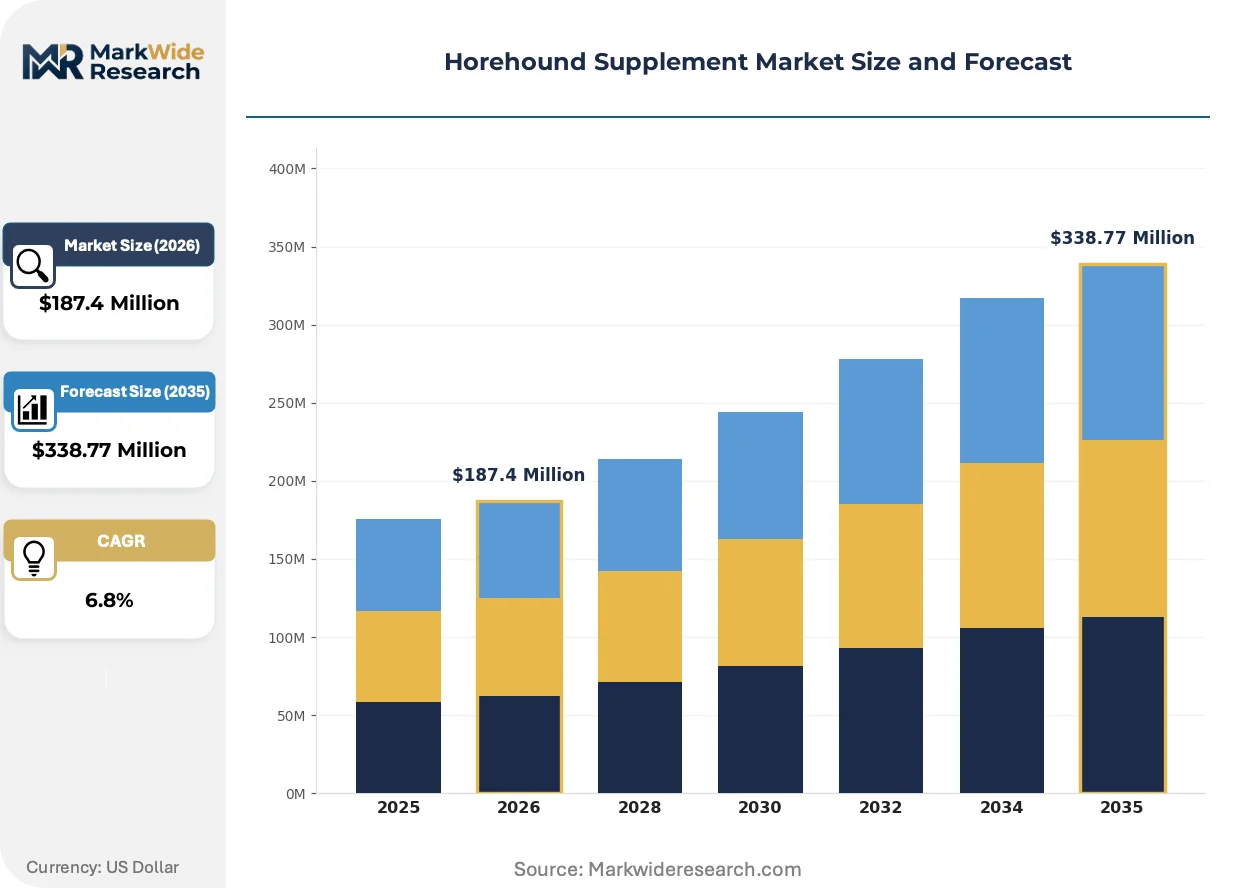
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Form: Capsules, Extracts, Teas, Gummies Application: Digestive Health, Respiratory Support, Immune Function, Cough Relief Distribution Channel: Online Retail, Health Stores, Pharmacies, Supermarkets Target Audience: Health Enthusiasts, Older Adults, Allergy Sufferers, Fitness Communities |
| Companies Covered | Ricola Group AG, Zarbee's Naturals, Nature's Way, Swanson Health Products, Gaia Herbs, Herb Pharm, Halls, Luden's, NOW Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Horehound Supplement Market Evolving Landscape
Formulation science and channel architecture are converging to reshape how horehound reaches consumers, with standardization technologies and digital distribution creating new competitive axes beyond traditional herbal retail.
Liposomal encapsulation technology is improving bioavailability of marrubiin and volatile oils in liquid preparations. Functional medicine practitioners and biohacker-oriented consumers are adopting these enhanced-absorption formats at accelerating rates. This delivery innovation is miniaturizing the effective dose threshold, enabling single-serving sachets and travel formats that expand usage occasions beyond home-based tea preparation.
EMA's evolving guidance on traditional herbal registrations is tightening evidence requirements for THMPD-listed cough remedies. Manufacturers must now demonstrate 30 years of traditional use including 15 years within EU member states, raising documentation barriers for non-European heritage products. Whole-herb teas with established European folk use are consolidating market access advantages over standardized extracts lacking comparable historical footprints.
Subscription commerce is displacing one-time health-store purchases for respiratory wellness regimens. Direct-to-consumer brands are capturing recurring revenue through allergy-season auto-ship programs, replacing the episodic buying patterns that dominated pharmacy and supermarket channels. This behavioral shift is most pronounced in United States coastal metropolitan markets where digital-native wellness consumption concentrates.
Horehound Supplement Market Segmentation
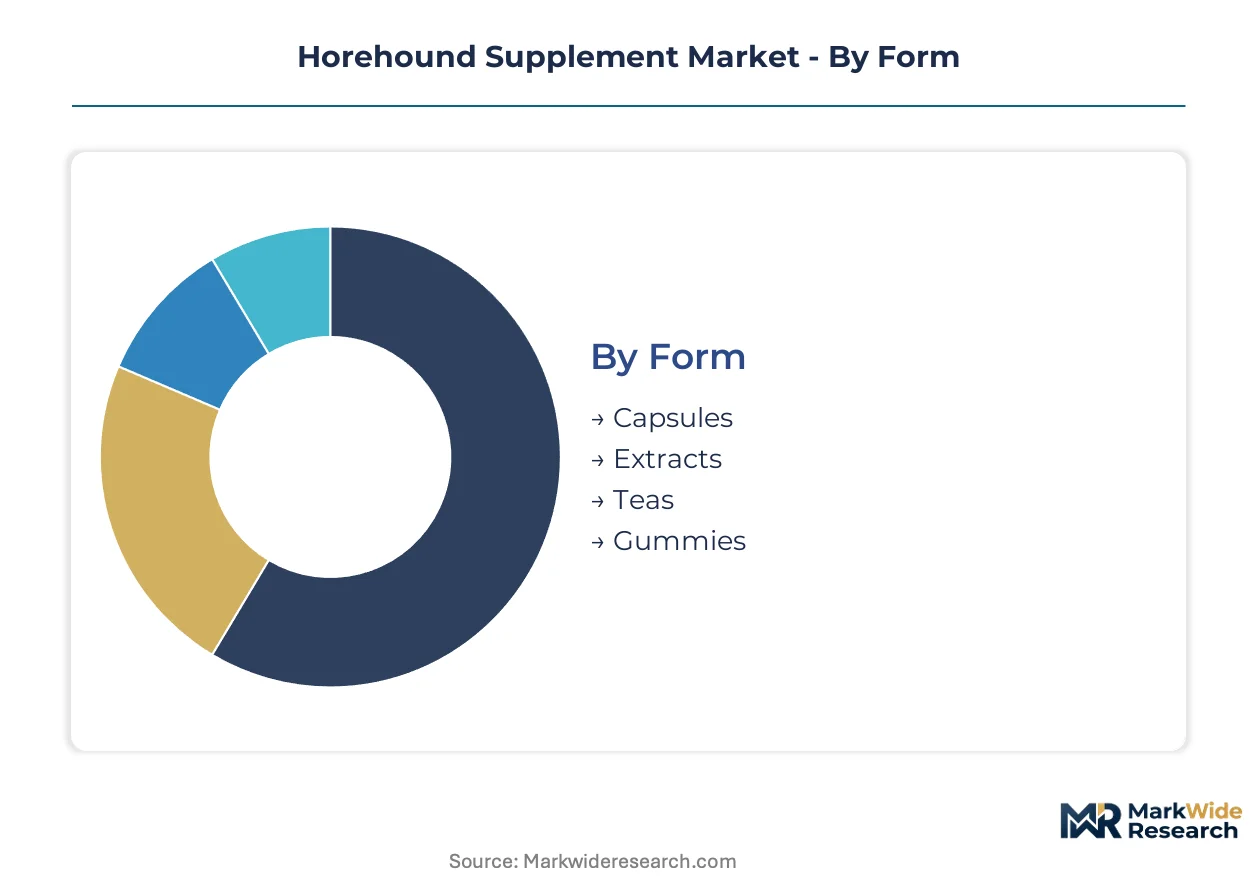
Form, application, and channel architectures in horehound supplements determine margin capture and regulatory exposure. Segment boundaries align with FDA DSHEA claim categories and USDA organic certification pathways that shape consumer willingness-to-pay.
Form:
FDA structure-function claim substantiation requirements and extraction method disclosures create divergent compliance burdens across delivery formats.
- Capsules:Standardized marrubiin doses in gelatin or vegetable shells dominate pharmacy and supermarket placement. United States health enthusiasts favor measured dosing convenience that supports daily respiratory regimens without preparation time.
- Extracts:Concentrated liquid or powdered preparations deliver higher marrubiin potency per serving. Practitioner-directed sales in functional medicine clinics concentrate demand where clinical documentation of standardization justifies premium positioning.
- Teas:Whole-herb aqueous preparations retain established European markets under EMA THMPD traditional use registrations.
- Gummies:Palatable low-dose formats target younger demographics through TikTok-native wellness brands and subscription channels.
Established volume favors capsules; emerging adoption favors gummies.
Application:
Claim architecture under DSHEA and EMA THMPD determines which applications support structure-function positioning versus traditional herbal registration.
- Respiratory Support:Seasonal allergy and bronchial wellness applications drive United States consumer trial. FDA scrutiny of cough-relief claims intensifies substantiation requirements that favor scaled manufacturers with clinical capabilities.
- Cough Relief:Traditional expectorant positioning faces synthetic substitution pressure from dextromethorphan and guaifenesin formulations with pharmacy reimbursement advantages.
- Digestive Health:Bitter-tonic traditional use claims align with EMA THMPD pathways in European markets.
- Immune Function:General wellness positioning encounters broader competitive set from elderberry, echinacea, and zinc formulations.
Regulatory clarity concentrates investment in respiratory support; claim risk diverts resources from cough relief.
Distribution Channel:
Channel selection determines margin structure, certification visibility, and consumer education intensity required for conversion.
- Online Retail:Direct-to-consumer infrastructure enables subscription auto-ship programs and USDA organic credential visibility. Coastal United States metropolitan markets concentrate demand where digital-native wellness consumption patterns dominate.
- Health Stores:Practitioner-adjacent positioning supports extract sales with standardization documentation and trained staff consultation.
- Pharmacies:Pharmacy shelf placement requires competitive positioning against reimbursed synthetic expectorants with physician familiarity advantages.
- Supermarkets:Mass-market capsule placement depends on price-competitive manufacturing scale and packaging clarity for self-directed purchase.
Recurring revenue concentrates in online retail; margin protection concentrates in health stores.
Target Audience:
Demographic targeting aligns with format preferences, channel concentration, and seasonal purchase patterns that shape customer lifetime value.
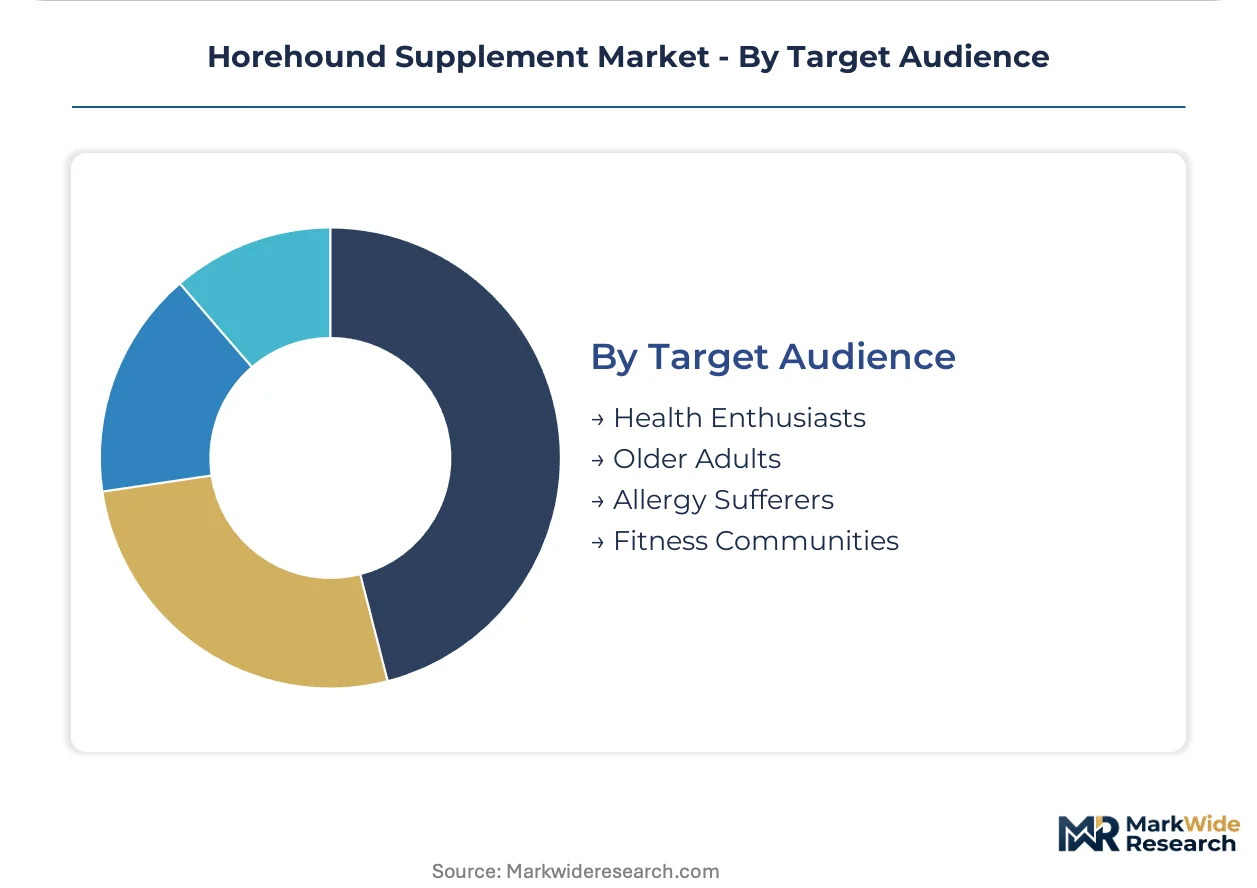
- Allergy Sufferers:Seasonal respiratory regimens drive predictable spring and fall purchase spikes. United States consumers with established herbal supplement habits show highest trial rates for standardized extract formats.
- Health Enthusiasts:Biohacker-oriented consumers adopt liposomal encapsulation and novel delivery innovations at premium price points.
- Older Adults:Traditional tea preparations and familiar capsule formats align with established consumption patterns in European heritage markets.
- Fitness Communities:Pre-workout respiratory support and post-exposure immune applications represent emerging use case development.
Seasonal predictability favors allergy sufferers; format innovation favors health enthusiasts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from Mediterranean cultivation zones to North American processing facilities define the horehound supplement trade balance, with finished product value concentrating in direct-to-consumer channels across coastal metropolitan markets.
United States
Direct-to-consumer subscription models and established herbal supplement consumption patterns drive demand concentration in California and New York metropolitan corridors. The FDA's DSHEA framework governs structure-function claim substantiation, creating compliance thresholds that favor scaled manufacturers. Pacific Northwest distribution clusters in Oregon and Washington State process imported raw material into certified organic finished goods for health-store and online channels.
Germany
EMA THMPD traditional herbal registrations sustain whole-herb tea markets where three-generation consumption patterns persist in Bavaria and Baden-Württemberg. The German Federal Institute for Drugs and Medical Devices enforces documentation requirements for cough-relief positioning that diverge from standardized extract pathways. Frankfurt-Rhine-Main logistics hubs coordinate Balkan-sourced raw material distribution across Central European pharmacy networks.
Switzerland
Swissmedic pharmaceutical-grade manufacturing standards and Alpine herb heritage positioning support premium extract exports to North American practitioner channels. The country's bilateral recognition agreements with EU regulatory frameworks enable seamless cross-border distribution. Zurich and Basel pharmaceutical clusters concentrate liposomal encapsulation R&D for next-generation delivery formats.
United Kingdom
Post-Brexit divergence from EMA THMPD pathways has created parallel registration requirements under the UK's Traditional Herbal Registration scheme. London and Southeast England health-store retail maintains demand for organic-certified capsules despite compressed pharmacy shelf access. Manchester and Birmingham distribution centers process EU-imported extracts for domestic online retail fulfillment.
Italy
Sicilian and Calabrian cultivation zones supply Marrubium vulgare raw material to processors serving both domestic traditional use markets and export pharmaceutical channels. The Italian Medicines Agency enforces EU Traditional Herbal Medicinal Products Directive implementation with specific regional documentation requirements. Lombardy-based extraction facilities in Milan's industrial periphery specialize in supercritical CO2 processing for standardized marrubiin concentrates.
Horehound Supplement Market Competitive Landscape
Concentration sits with vertically integrated herb processors and scaled contract manufacturers that control cultivation-through-extraction infrastructure. The competitive structure fragments between captive-supply specialists and outsourcing-dependent brands competing on manufacturing scale. Three archetypes dominate: Mediterranean-heritage processors with proprietary cultivation, North American multi-form manufacturers, and certified-organic traceability specialists. Capacity expansion in supercritical CO2 extraction and strategic partnerships for subscription channel access represent the dominant competitive moves reshaping market position.
Among heritage European processors, Ricola Group AG exemplifies captive cultivation and proprietary extraction infrastructure sustaining margin control across pharmacy channels. NOW Foods occupies a position as a North American scaled manufacturer operating multi-form facilities that anchor cost positions in standardized extracts. Gaia Herbs represents the certified-organic traceability archetype, positioning vertical supply chain documentation as a premium credential in health-store and practitioner-directed sales.
| Leading Market Players |
|---|
| Ricola Group AG |
| Zarbee's Naturals |
| Nature's Way |
| Swanson Health Products |
| Gaia Herbs |
| Herb Pharm |
| Halls |
| Luden's |
| NOW Foods |
| Others |
Value Network & Pricing Analysis
Ninety-day Mediterranean harvest-to-extraction lead times tether margin structures to Balkan climate volatility, concentrating pricing power with processors holding captive cultivation buffers against spot-market raw material spikes.
Pricing Analysis
The customization-premium spread between practitioner-directed liquid extracts and mass-market capsules runs wide, with three-tier pricing structure across premium, standard, and economy levels separating USDA-certified organic SKUs from conventional bulk formats. Price differentiation hinges on extraction standardization documentation and organic certification visibility. Pricing pressure stems from synthetic expectorant substitution in pharmacy channels where insurance reimbursement favors dextromethorphan formulations. Allergy sufferers in subscription channels show lowest price sensitivity; supermarket capsule buyers exhibit highest elasticity.
Supply Chain Analysis
Adriatic port congestion during autumn harvest windows chokes Marrubium vulgare flows to North American processors, forcing inventory build strategies that strain working capital for non-integrated brands. Cultivation concentrates in Italy, Albania, and Morocco, with raw material quality grading on marrubiin content and volatile oil profiles. Supply chain risk rests on single-source vulnerability as climate-driven harvest failures in Sicily propagate price shocks through contract manufacturer networks. Distribution runs through health-store wholesale cooperatives and direct-to-consumer fulfillment centers anchored in Oregon and New York distribution clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clinical trial design expertise for botanical respiratory claims commands salary premiums that exclude mid-tier manufacturers, concentrating substantiation capabilities among scaled players with captive research infrastructure.
For Market Incumbents: Consolidate backward integration into Mediterranean cultivation zones to buffer raw material volatility and block contract-reliant competitors from premium extract segments. Acquire supercritical CO2 extraction capacity in Lombardy to serve practitioner channels demanding documented marrubiin standardization. Defend against gummy-format entrants by locking exclusive supply agreements with TikTok-native wellness distribution platforms. For New Entrants and Emerging Players: USDA Organic certification fast-track programs offer white-space entry into subscription channels where coastal metropolitan consumers pay premiums for traceable supply chains. Target underpenetrated naturopathic clinic networks in Pacific Northwest corridors with single-serving liposomal sachet formats. Pursue influencer-partnership go-to-market angles that bypass incumbent pharmacy shelf dominance. For Investors and Strategic Acquirers: Long-term, this sits as a wellness-subscription play because recurring revenue models in respiratory wellness categories exhibit lower churn than episodic pharmacy purchases. Acquisition candidates should display captive herb processing infrastructure or established THMPD registration portfolios in European heritage markets. Watch FDA enforcement intensity on cough-relief structure-function claims as the inflection signal determining marketing framework viability for non-clinical players.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Cultivation Expansion | Backward integration into Sicilian growing regions secures marrubiin-grade raw material against climate volatility. |
| Practitioner Channel Partnership | Functional medicine clinic networks in California and New York extract premium pricing for standardized liquid formats. |
| USDA Organic Certification Program | National Organic Program credentials unlock 40-60% price premiums in health-store and subscription channels. |
| Supercritical CO2 Capacity Addition | GMP-compliant extraction infrastructure enables dose-consistent products satisfying naturopathic prescription alternatives. |
| Subscription Commerce Platform Launch | Auto-ship respiratory regimens capture recurring revenue and displace episodic pharmacy purchasing patterns. |
Research Methodology
The analysis maps form-specific segments (capsules, extracts, teas, gummies), application categories (respiratory support, cough relief, digestive health), and channel architectures, each validated through procurement managers at health-store cooperatives, extraction facility operations directors, regulatory affairs specialists at dietary supplement manufacturers, and naturopathic clinic purchasing coordinators. Primary interview insights triangulated against FDA DSHEA guidance documents, USDA National Organic Program certification databases, EMA THMPD registration filings, and customs import records for Marrubium vulgare raw material flows. Bottom-up volume builds from extraction capacity utilization and top-down demand estimates from channel shipment data were reconciled to produce segment outputs.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with modeled dimensions spanning delivery form, application claim architecture, distribution channel, and organic certification status. CAGRs were derived from segment-level growth trajectory analysis incorporating allergy seasonality patterns, practitioner channel penetration rates, and gummy format adoption curves. Forecast inputs included Balkan cultivation yield variability indices and FDA enforcement intensity proxies for respiratory health claim substantiation requirements.
Underlying assumptions cover stable DSHEA structure-function claim frameworks and continued consumer willingness-to-pay for organic certification, with deviation risk concentrated in EMA THMPD evidence requirement tightening and synthetic expectorant reimbursement expansion. Practitioners should keep alternative scenarios live as regulatory enforcement priorities and climate-driven harvest disruptions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Custom Supplement Formulation Service Market
Nutritional Supplements
Enteral Nutrition Market
Nutritional Supplements
Selenium Yeast Market
Nutritional Supplements
Iron Supplement Market
Nutritional Supplements
Spain Whey Protein Market
Nutritional Supplements
Global General Well-Being Dietary Supplements Market
Nutritional Supplements
Bone Meal Supplement Market
Nutritional Supplements
North America Prenatal Supplements Market
Nutritional Supplements
Diet Pills Market
Nutritional Supplements
Omega 3 Supplements Market
Nutritional Supplements
Tongkat Ali Market
Nutritional Supplements
Cod Liver Oil Market
Nutritional Supplements
Nutraceutical Supplements Market
Nutritional Supplements
Coq10 Gummies Market
Nutritional Supplements
L-Leucine Market
Nutritional Supplements
Asia-Pacific Omega-3 Products Market