
 North America Beta-Glucan Market | 2026-2036
North America Beta-Glucan Market Size, Share, and Industry Trends Forecast 2026-2036
North America Beta-Glucan Market Analytics
Multi-source procurement from oat millers and yeast fermentation suppliers is shifting as manufacturers seek supply security against grain price volatility. Tate & Lyle PLC leverages its North American grain processing infrastructure to secure consistent soluble beta-glucan output. Kerry Group anchors its position through integrated application labs that bridge ingredient supply and finished formulation support. Ceapro Inc differentiates via its specialized aqueous extraction technology for high-purity oat fractions.
Beta-glucan comprises glucose polymers linked by beta-glycosidic bonds, with (1,3)(1,6)-D-linkages in yeast and mushroom sources and mixed (1,3)(1,4)-D-linkages in cereal grains; molecular weight and branching ratio determine viscosity, solubility, and immune receptor binding affinity for nutraceutical and pharmaceutical applications. Soluble beta-glucan commands premium positioning in dietary supplements due to its demonstrated cholesterol-lowering and immunomodulatory bioactivity. Yeast-derived fractions are gaining traction in pharmaceutical applications where beta-1,3/1,6 glucan structures meet stringent purity thresholds for injectable and topical formulations.
The FDA oversees GRAS self-affirmation and food additive petitions for beta-glucan ingredients entering the U.S. food and supplement supply, while Health Canada and PMRA regulate beta-glucan health claims and novel food approvals for the Canadian market. USDA organic certification and non-GMO verification standards increasingly filter market access for premium-positioned oat and mushroom sources. Stakeholders must monitor evolving immunomodulatory health claim substantiation requirements and dual-jurisdiction compliance costs as cross-border ingredient trade intensifies.
Market Dynamics
The FDA's streamlined GRAS notification pathway for novel beta-glucan sources is compressing ingredient approval timelines from years to months, reshaping how dietary supplement manufacturers source and formulate immune health products across the United States and Canada.
Growth Catalysts
- Immune health portfolio expansion:Dietary supplement manufacturers in California's functional food cluster are accelerating beta-glucan fortification across gummy, capsule, and powder formats to capture post-pandemic consumer preference for proven immunomodulatory ingredients.
- USDA organic certification tailwinds:Premium oat-derived beta-glucan suppliers leveraging non-GMO verification and organic standards are commanding shelf space in natural retail channels across the Great Plains grain processing belt.
- Pharmaceutical purity thresholds:Yeast-derived beta-1,3/1,6 glucan structures meeting stringent injectable-grade specifications are unlocking new formulation partnerships with topical and parenteral drug developers in the Northeast corridor.
Market Restraints
- Oat futures volatility:Grain price swings in the Great Plains are compressing margins for cereal-sourced beta-glucan processors dependent on regional milling contracts.
- Dual-jurisdiction compliance costs:Cross-border ingredient trade between the United States and Canada requires parallel FDA GRAS self-affirmation and Health Canada novel food approvals, extending time-to-market.
- Fermentation capacity concentration:Yeast-derived beta-glucan supply hinges on a limited North American fermentation infrastructure base, creating bottleneck risk during demand surges.
Strategic Opportunities
- Canadian health claim substantiation:Health Canada's evolving immunomodulatory claim framework offers first-mover advantage for suppliers investing in clinical trial data specific to Canadian regulatory requirements.
- Mushroom-derived beta-glucan convergence:Integration of aqueous extraction technology with mycelium cultivation systems is opening pharmaceutical-grade supply chains previously dominated by yeast sources.
- Direct-to-practitioner channel development:Functional medicine clinicians in Texas and Florida are bypassing traditional retail to prescribe beta-glucan protocols, creating high-margin subscription revenue streams.
Industry Challenges
- Biopolymer characterization expertise shortage:Analytical chemists capable of validating molecular weight distribution and branching ratios for beta-glucan bioactivity claims command premium salaries, constraining mid-tier manufacturer R&D expansion.
- Legacy ERP integration friction:Grain processors upgrading to batch-level traceability systems for FDA compliance face data migration complexity with decades-old milling operation software.
- Patent thickets around receptor binding assays:Licensing disputes over Dectin-1 and CR3 binding validation methods are delaying novel source commercialization timelines for emerging suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Beta-Glucan Market |
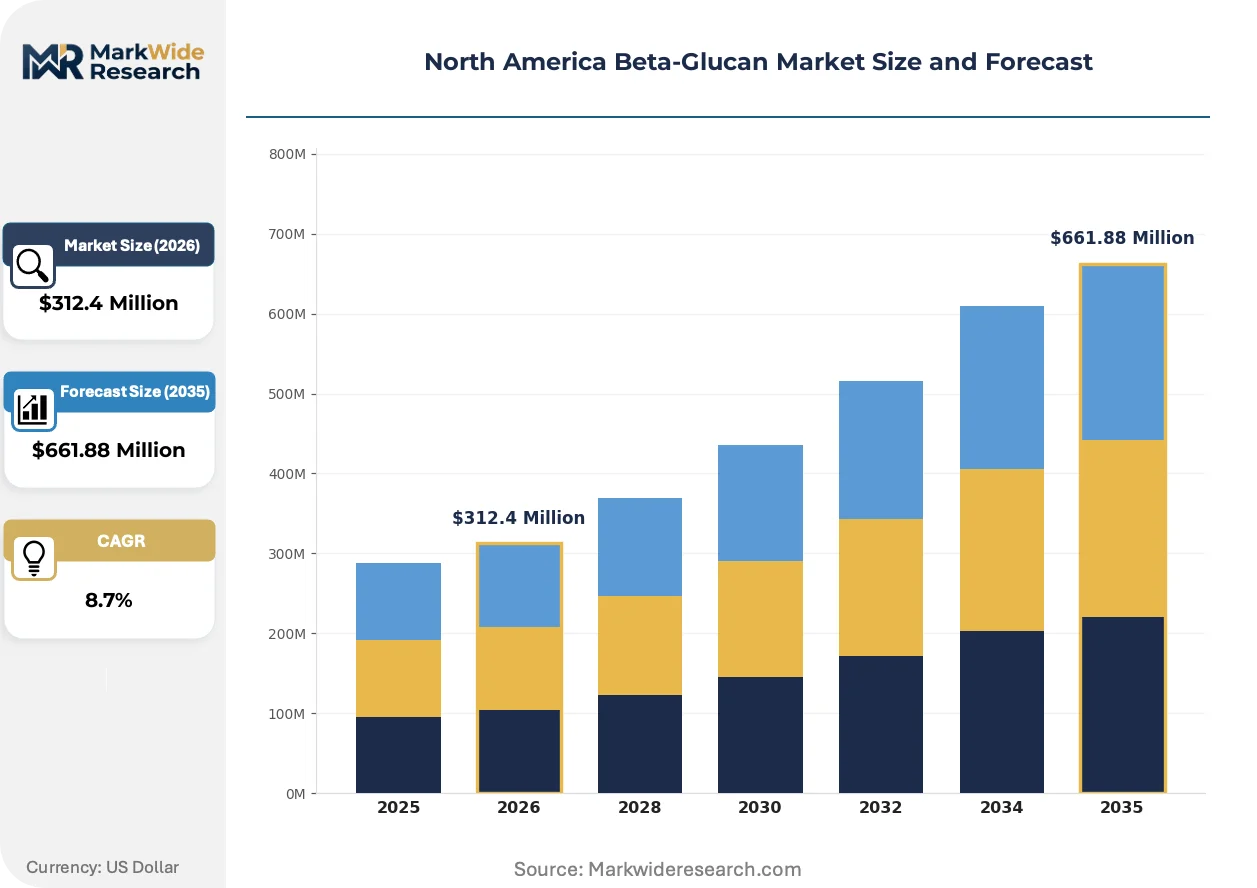
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soluble, Insoluble, Micro, Granules Application: Food and Beverage, Dietary Supplements, Pharmaceuticals, Animal Feed Source: Oats, Barley, Yeast, Mushrooms End User: Healthcare, Food Industry, Agriculture, Vitamins |
| Companies Covered | Tate & Lyle PLC, Kerry Group, Koninklijke DSM N.V., Associated British Foods Plc, Super Beta Glucan, Ceapro Inc, Biotec Pharmacon ASA, Biothera the Immune Health Company, Kemin Industries, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Beta-Glucan Market Evolving Landscape
Continuous aqueous extraction systems are displacing solvent-based methods across North American oat processing facilities, compressing production cycles while elevating beta-glucan purity profiles for pharmaceutical-grade applications.
Membrane filtration technology is automating the separation of high-molecular-weight beta-glucan fractions from oat bran hydrolysates. Contract manufacturers in Minnesota and Saskatchewan are retrofitting existing grain processing lines with ceramic ultrafiltration modules. This automation is compressing the cost differential between food-grade and nutraceutical-grade beta-glucan outputs.
The FDA's 2023 updated guidance on GRAS self-affirmation for polysaccharide ingredients has clarified bioequivalence demonstration requirements. Supplement manufacturers are restructuring stability study protocols to preempt agency scrutiny. Yeast-derived beta-glucan suppliers targeting injectable applications face the steepest documentation burden under the revised framework.
Practitioner-channel purchasing is consolidating immune health ingredient procurement for functional medicine clinics across Arizona and Colorado. Distributors are unbundling bulk beta-glucan from formulation services, forcing ingredient suppliers to develop direct educational content for clinical decision-makers. This disintermediation is most visible in the Southwest corridor where integrative health networks are verticalizing their own supplement lines.
North America Beta-Glucan Market Segmentation
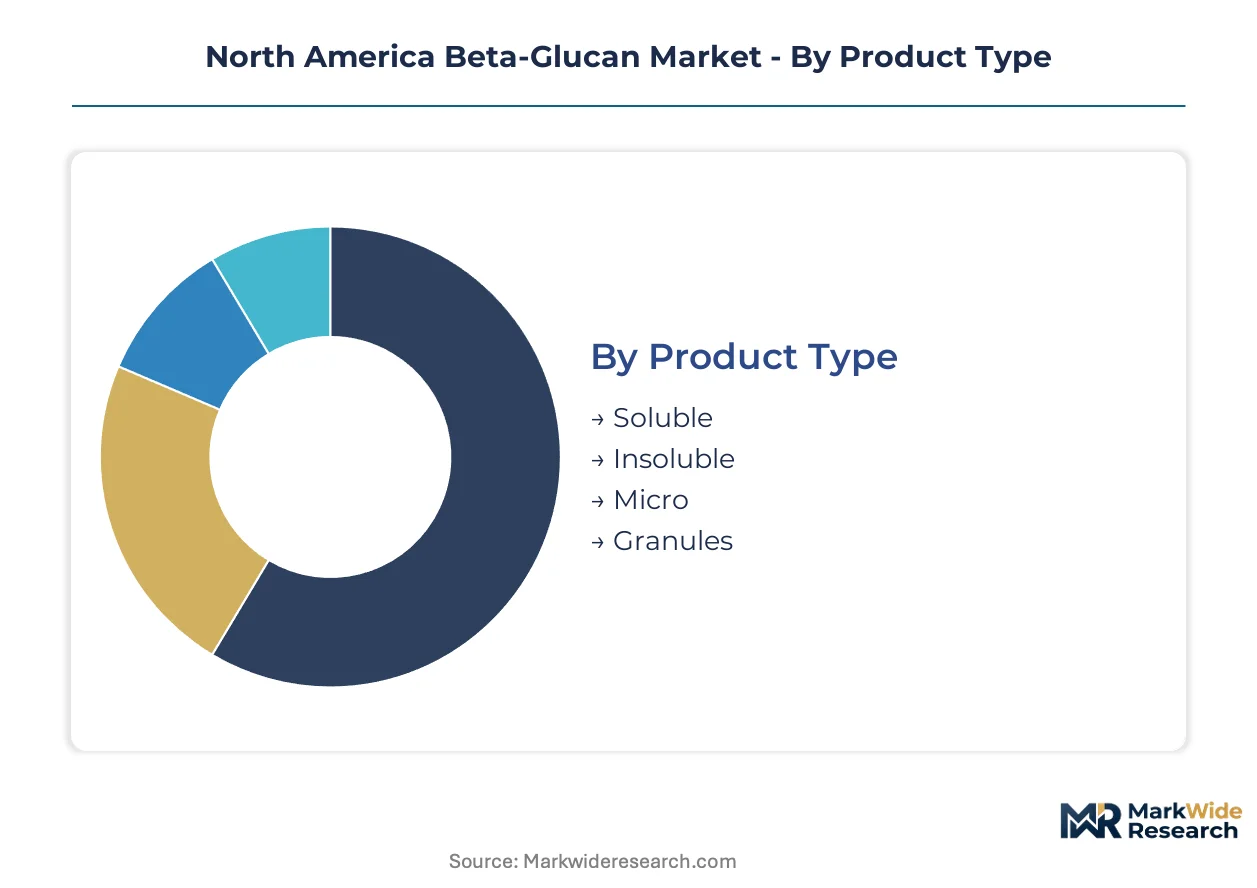
Segmentation in the North American beta-glucan market reflects divergent purity requirements across immune health formulations, cholesterol management applications, and pharmaceutical injectables. Manufacturers configure extraction and processing infrastructure around these distinct specification tiers rather than pursuing one-size-fits-all output.
Product Type:
Upgrade cycles from insoluble to soluble fractions are accelerating as dietary supplement brands reformulate for bioavailability claims and FDA GRAS notification alignment.
- Soluble:Glucose polymers with mixed (1,3)(1,4)-D-linkages demonstrate viscosity-dependent cholesterol reduction and immunomodulatory activity. California's functional food cluster drives demand for soluble fractions in gummy and beverage applications where dissolution clarity matters.
- Insoluble:Cell wall-bound beta-glucan fractions retain structural integrity through thermal processing. Great Plains grain processors supply insoluble grades to baked goods manufacturers seeking fiber enrichment without moisture binding complications.
- Micro:Micronized particle sizes below 50 microns enhance dispersibility in instant drink mixes. Sports nutrition brands in Colorado specification-test micro grades for suspension stability.
- Granules:Agglomerated formats reduce dusting during high-speed capsule filling operations. Contract manufacturers in Minnesota prefer granules for tablet compression workflows.
Soluble beta-glucan sits at the top of the volume ranking, with micro grades climbing the fastest as beverage fortification expands.
Application:
Cost tier differentiation separates pharmaceutical-grade validation requirements from food-grade processing economics, with dietary supplements occupying the middle ground on purity documentation.
- Food and Beverage:Cereal-derived fractions dominate functional food fortification where FDA GRAS self-affirmation suffices. Oat millers in the Great Plains supply standardized extracts for yogurt and bread applications.
- Dietary Supplements:Capsule, powder, and gummy formats concentrate immune health positioning. Texas and Florida practitioner channels prescribe beta-glucan protocols directly to functional medicine patients.
- Pharmaceuticals:Yeast-derived beta-1,3/1,6 structures meeting USP injectable specifications command premium positioning. Northeast corridor drug developers partner with fermentation suppliers for parenteral formulation trials.
- Animal Feed:Beta-glucan immunomodulation in livestock reduces antibiotic dependency. Iowa and Nebraska feed compounders integrate yeast fractions into swine and poultry rations.
Dietary supplements generate the highest revenue concentration, while pharmaceutical applications show the steepest expansion trajectory as clinical validation accumulates.
Source:
Supply concentration geography dictates procurement risk profiles, with oat cultivation volatility in the Great Plains contrasting fermentation capacity constraints for yeast-derived output.
- Oats:Mixed-linkage (1,3)(1,4)-D-glucan from Avena sativa dominates cholesterol-lowering claims. Saskatchewan and Minnesota milling infrastructure supports aqueous extraction scale-up.
- Barley:Higher beta-glucan content than oats but limited cultivar standardization. Montana and North Dakota grain elevators supply specialty maltsters.
- Yeast:Saccharomyces cerevisiae cell walls yield beta-1,3/1,6 structures with Dectin-1 receptor specificity. North American fermentation capacity concentrates in Illinois and Wisconsin.
- Mushrooms:Lentinus edodes and Ganoderma lucidum mycelium deliver pharmaceutical-grade purity via aqueous extraction. British Columbia cultivation facilities serve West Coast nutraceutical processors.
Oat-derived beta-glucan holds the dominant volume position, with mushroom sources gaining share fastest as mycelium cultivation systems achieve pharmaceutical-grade yields.
End User:
Customer type maturity varies from established food industry procurement protocols to emerging practitioner-channel disintermediation in integrative health networks.
- Healthcare:Hospitals and clinics prescribe beta-glucan for postsurgical immune support. Arizona integrative health networks verticalize their own supplement lines.
- Food Industry:CPG manufacturers fortify across breakfast cereal, dairy alternative, and snack categories. California's functional food cluster leads formulation innovation.
- Agriculture:Livestock producers and aquaculture operations deploy beta-glucan for pathogen resistance. Mississippi catfish farms trial yeast fractions in feed rations.
- Vitamins:Multivitamin and single-ingredient immune health brands compete on purity certification. Utah supplement manufacturers source organic-verified oat extracts.
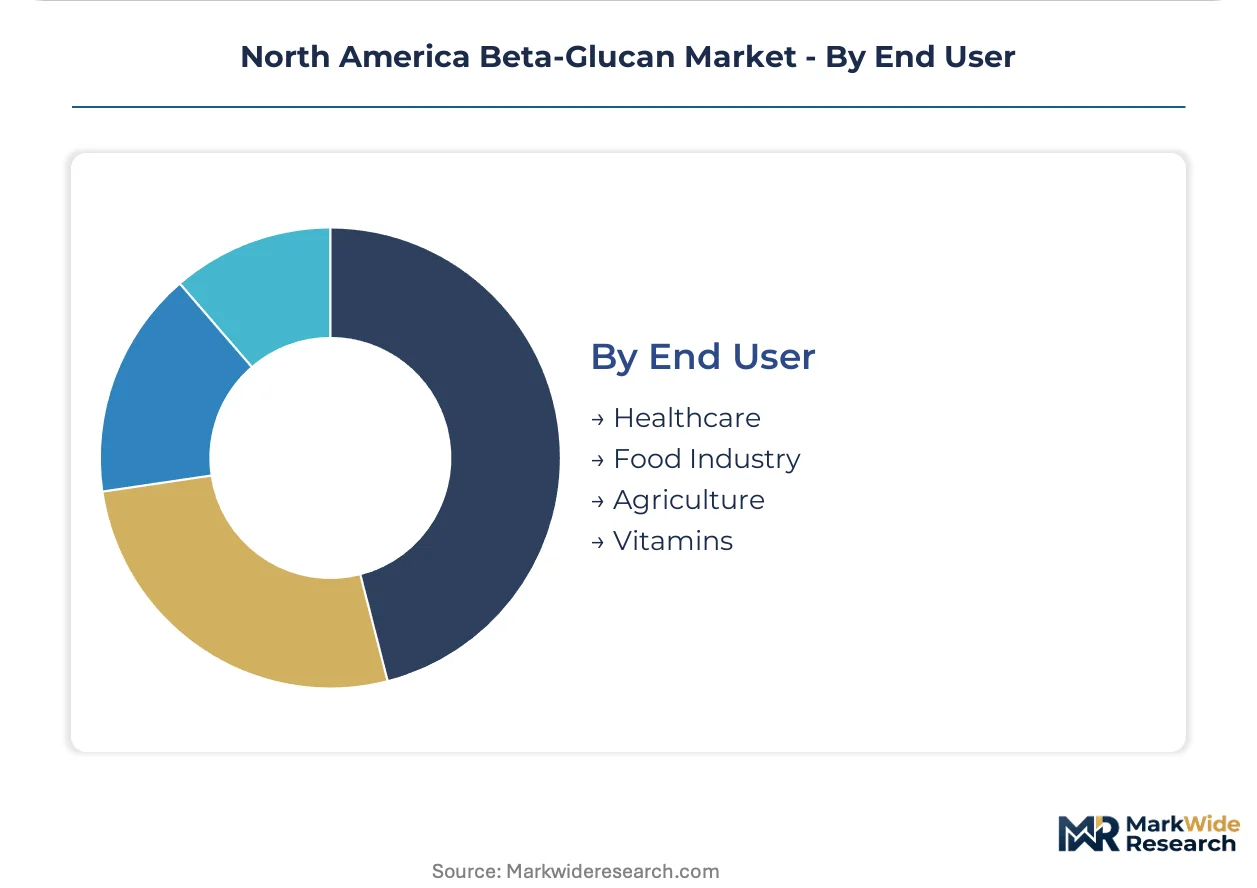
The food industry maintains the highest procurement volume, with healthcare end users expanding most quickly as functional medicine protocols gain clinical adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's functional food cluster anchors North American beta-glucan demand through its concentration of dietary supplement innovation and immune health formulation. The region's integration of aqueous extraction infrastructure with fermentation capacity shapes supply security calculations across the continent.
United States
FDA GRAS notification streamlining accelerates novel beta-glucan source approvals for immune health portfolios. The 2023 updated guidance on polysaccharide bioequivalence demonstration restructures stability study protocols for supplement manufacturers. California's functional food cluster drives gummy and beverage format innovation, while Minnesota contract manufacturers deploy ceramic ultrafiltration for pharmaceutical-grade outputs.
Canada
Health Canada's evolving immunomodulatory claim framework creates first-mover advantages for clinical trial investment. PMRA novel food approval requirements run parallel to FDA processes, extending cross-border time-to-market for ingredient suppliers. Saskatchewan milling infrastructure supports aqueous extraction scale-up for oat-derived fractions targeting cholesterol-lowering positioning.
Mexico
Feed compounders in central states trial yeast-derived beta-glucan for swine and poultry antibiotic reduction protocols. The national agricultural regulator oversees novel feed additive registrations for immunomodulatory ingredients. Bajío Region grain processors evaluate oat bran fractionation partnerships with U.S. extraction technology providers.
North America Beta-Glucan Market Competitive Landscape
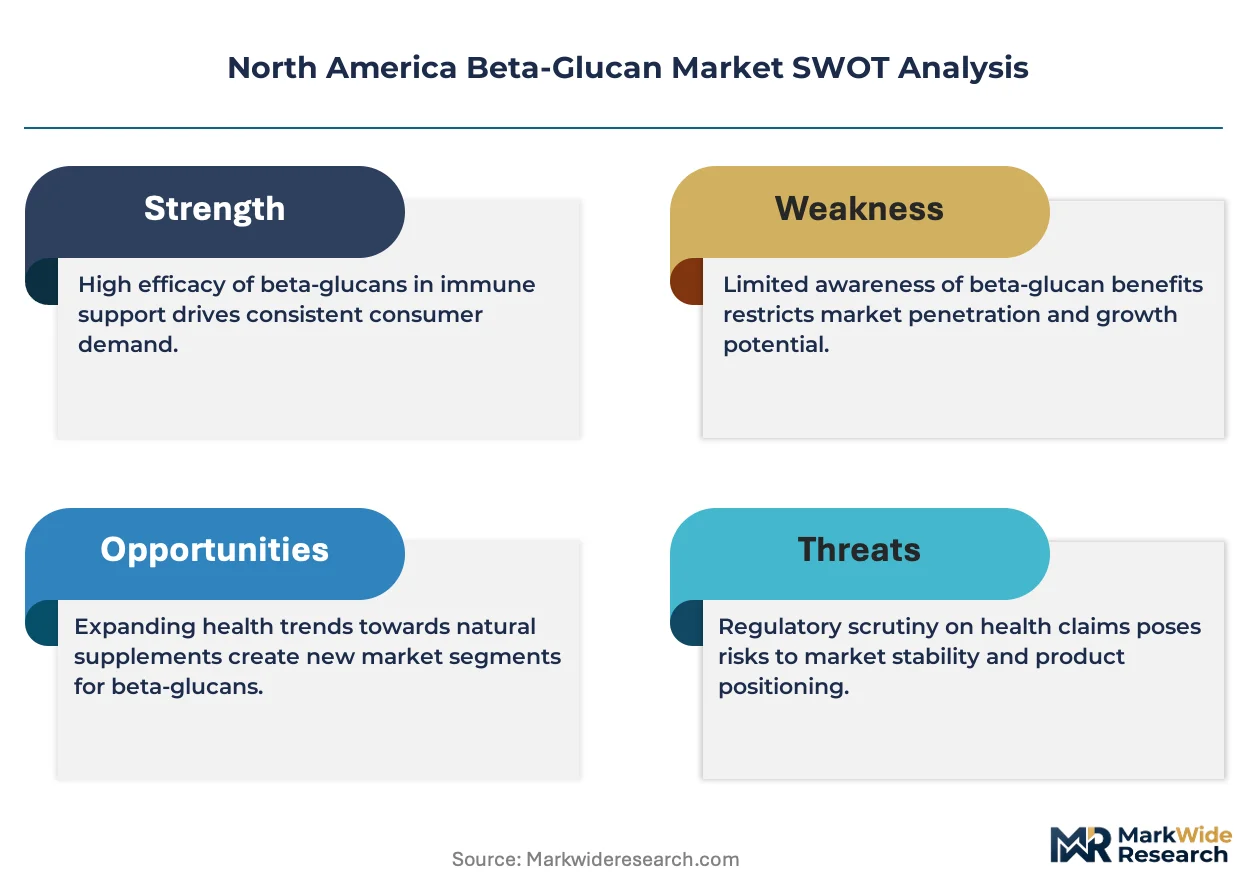
Global majors compete with regional champions across extraction technology and application formulation capabilities. The market structure tiers between integrated grain processors with captive supply chains and specialized fermentation suppliers serving pharmaceutical purity thresholds. Three archetypes dominate: aqueous extraction specialists, integrated ingredient-application platforms, and yeast fermentation purists. Capacity expansion in membrane filtration infrastructure and strategic partnerships bridging raw material security with finished formulation support represent the dominant competitive vectors.
Within the integrated processing tier, Tate & Lyle PLC and Kerry Group exemplify scale-driven positions leveraging North American grain infrastructure. Ceapro Inc occupies a specialist niche through its aqueous extraction focus. These three entities represent the spectrum from commodity-scale supply to technology-differentiated purity positioning.
| Leading Market Players |
|---|
| Tate & Lyle PLC |
| Kerry Group |
| Koninklijke DSM N.V. |
| Associated British Foods Plc |
| Super Beta Glucan |
| Ceapro Inc |
| Biotec Pharmacon ASA |
| Biothera the Immune Health Company |
| Kemin Industries |
| Others |
Value Network & Pricing Analysis
Practitioner-channel buyers in Arizona and Colorado integrative health networks command subscription-based pricing models that reward purity certification and clinical trial substantiation over commodity spot purchasing. This buyer concentration shifts pricing power toward suppliers with captive aqueous extraction infrastructure and FDA GRAS documentation depth.
Pricing Analysis
Grain futures volatility in the Great Plains passes through directly to cereal-sourced beta-glucan contract rates, compressing margins for oat millers without backward integration into cultivation. Three-tier pricing structure across pharmaceutical-grade, nutraceutical-grade, and food-grade certification levels separates yeast-derived injectable fractions from soluble oat extracts and insoluble fiber grades. Cost compression in food-grade segments is intensifying because membrane filtration automation narrows the purity-cost gap with premium tiers. Dietary supplement brands show highest price sensitivity, while Northeast parenteral drug developers absorb premiums for USP-validated yeast fractions.
Supply Chain Analysis
USDA organic certification and non-GMO verification standards reshape sourcing toward Saskatchewan and Minnesota oat cultivation regions with traceable cultivation records. Raw material flows draw from Great Plains grain elevators, Illinois fermentation facilities, and British Columbia mycelium cultivation operations. Single-source vulnerability concentrates in North American yeast fermentation capacity, where limited bioreactor infrastructure creates bottleneck exposure during immune health demand surges. Distribution runs through California formulation hubs for finished supplements, with direct-to-practitioner channels disintermediating traditional wholesale in Southwest corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as post-pandemic immune health portfolios pivot from commodity positioning toward clinical-grade purity specifications with validated receptor binding data.
For Market Incumbents: Deepen aqueous extraction technology moats through ceramic ultrafiltration retrofits that compress pharmaceutical-grade production cycles. Defend against mushroom-derived beta-glucan entrants by locking long-term mycelium supply agreements with British Columbia cultivation facilities. Prioritize Health Canada immunomodulatory claim investments to secure first-mover positioning in evolving regulatory frameworks. For New Entrants and Emerging Players: Begin with Texas and Florida practitioner-channel white space where functional medicine protocols bypass retail margin compression. Target pharmaceutical-grade mushroom-derived fractions as the most penetrable tier, given aqueous extraction technology convergence with mycelium systems. Lead with direct educational content for clinical decision-makers rather than distributor-dependent market entry. For Investors and Strategic Acquirers: Integrated ingredient-application platforms are the most active acquirer in this space, seeking aqueous extraction specialists to bridge raw material security with formulation services. Long-term viability centers on suppliers with dual-jurisdiction FDA-Health Canada regulatory infrastructure and captive fermentation or extraction assets. Watch Health Canada immunomodulatory claim approvals as the inflection signal for premium pricing tier expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Ultrafiltration Retrofit | Minnesota contract manufacturers compress pharmaceutical-grade output costs through automated membrane separation. |
| Health Canada Clinical Trial Investment | First-mover suppliers secure immunomodulatory claim advantages under evolving Canadian regulatory frameworks. |
| Mycelium Cultivation Partnership | British Columbia facilities unlock pharmaceutical-grade mushroom-derived supply chains previously dominated by yeast sources. |
| Direct-to-Practitioner Channel Buildout | Arizona integrative health networks bypass retail disintermediation through verticalized supplement line development. |
| Dual-Jurisdiction Compliance Infrastructure | Parallel FDA GRAS and Health Canada novel food approvals reduce cross-border time-to-market friction. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each jurisdiction combining executive interviews with dietary supplement formulators, oat mill procurement directors, fermentation facility operators, and Health Canada regulatory consultants. Secondary validation draws from FDA GRAS notification filings, USDA organic certification databases, Health Canada novel food approval records, and Great Plains grain futures trading data. Bottom-up volume triangulation across extraction technology tiers reconciles with top-down market sizing through ingredient supplier revenue aggregation.
Granularity-level modeling disaggregates volume and value across source type, application tier, purity grade, and end-user channel throughout the forecast period. CAGRs derive from segment-level growth rate blending weighted by current revenue concentration. Forecast inputs incorporate oat futures volatility scenarios, fermentation capacity expansion timelines, and practitioner-channel penetration assumptions for Southwest integrative health networks.
Several conditions sit outside the modeled scope, including unforeseen FDA guidance revisions on polysaccharide bioequivalence, extreme climate events affecting Great Plains oat yields, and patent litigation outcomes over Dectin-1 receptor binding assays. Forecasts reflect documented assumptions regarding regulatory pathway stability and raw material supply continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Natural Immune Booster Market
Nutritional Supplements
Fish Oil Supplements Market
Nutritional Supplements
Complete Nutrition Products Market
Nutritional Supplements
Vitamin Shot Market
Nutritional Supplements
North America Bovine Lactoferrin Market
Nutritional Supplements
Global Hemp Protein Market
Nutritional Supplements
Chia-Based Protein Market
Nutritional Supplements
Global Beta-Alanine Market
Nutritional Supplements
Latin America Herbal Supplements Market
Nutritional Supplements
Nutrient Dense Food Products Market
Nutritional Supplements
Plant Based Iron Supplements Market
Nutritional Supplements
Europe Feed Prebiotics Market
Nutritional Supplements
Asia-Pacific Arachidonic Acid Market
Nutritional Supplements
Whey Basic Protein Isolates Market
Nutritional Supplements
Europe Collagen Peptides Market
Nutritional Supplements
Olive Supplements Market