
 Non-Fish Omega 3 Supplements Market | 2026-2036
Non-Fish Omega 3 Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Fish Omega 3 Supplements Market Analytics
Pharmaceutical and nutraceutical end-use vertical demand is consolidating around plant-derived DHA and EPA formulations. BASF SE leverages its fermentation biotechnology platform to supply algal omega-3 concentrates to supplement manufacturers across Europe. DSM-Firmenich anchors the premium ingredient tier through its life'sDHA branded algal oil platform. NOW Foods competes aggressively on softgel and liquid delivery formats through direct-to-consumer and natural retail channels.
Non-fish omega 3 supplements deliver alpha-linolenic acid (ALA), docosahexaenoic acid (DHA), or eicosapentaenoic acid (EPA) extracted from marine microalgae, terrestrial oilseeds, or fermented biomass, typically standardized to 200-600 mg active fatty acids per serving for cardiovascular and cognitive health applications. Algal oil dominates value contribution due to its direct DHA bioavailability without metabolic conversion, while flaxseed oil occupies the mass-market ALA segment where price sensitivity shapes purchasing. Softgel delivery mode leads volume throughput because of oxidation protection and consumer familiarity, though gummies are gaining fastest among fitness enthusiasts and younger retail customers seeking palatability.
FDA GRAS notifications and EFSA Novel Food approvals determine which algal strains and extraction solvents gain market access in the United States and European Union respectively, with REACH compliance adding purity testing burdens for imported oil concentrates. India's FSSAI and China's NMPA maintain separate registration requirements for algae-derived supplements, creating multi-jurisdictional compliance costs for exporters. Stakeholders must monitor how EU F-Gas Regulation restrictions on solvent-based extraction methods redirect capital toward supercritical CO2 processing infrastructure.
Market Dynamics
Fermentation biotechnology for algal DHA extraction is consolidating supply-side power among biotechnology platforms while fragmenting finished-product competition through lowered barrier-to-entry for contract manufacturers.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on solvent-based extraction methods accelerate capital redeployment toward supercritical CO2 processing infrastructure, favoring processors with existing clean-tech capabilities.
- Pharmacy-channel concentration in Germany:Sustainability labeling requirements and pharmacist recommendation protocols create preferential shelf placement for plant-derived omega-3 sources over fish oil alternatives.
- Fermentation biotechnology maturation:Strain optimization and continuous-culture systems reduce unit production costs for algal DHA, enabling price parity with mid-tier fish oil concentrates.
Market Restraints
- Input cost volatility:Fermentation-grade glucose and nitrogen feedstock prices fluctuate with agricultural commodity cycles, compressing margin predictability for biomass producers.
- Supply concentration risk:A limited number of biotechnology platforms control proprietary algal strain libraries, creating bottleneck vulnerability for downstream supplement brands.
- Regulatory friction:India's FSSAI and China's NMPA maintain non-harmonized registration requirements for algae-derived supplements, multiplying compliance costs for exporters targeting both markets.
Strategic Opportunities
- Pediatric and prenatal formulations:Direct DHA bioavailability without metabolic conversion positions algal oil to capture share in pregnancy and early childhood nutrition segments where conversion efficiency concerns dominate.
- Gummy delivery format expansion:Palatability-driven consumption among fitness enthusiasts and younger retail customers opens white space beyond traditional softgel dominance.
- REACH-compliant supercritical extraction:EU purity testing burdens for imported oil concentrates reward processors with established European analytical infrastructure and documentation capabilities.
Industry Challenges
- Multi-jurisdictional compliance timelines:FDA GRAS notifications, EFSA Novel Food approvals, and separate national registrations create elongated product launch cycles that strain working capital.
- Algal strain IP licensing complexity:Proprietary DHA-producing microorganisms require negotiated access agreements that fragment supply security and inflate ingredient costs for non-integrated brands.
- Oxidation stability certification:Peroxide value and anisidine index testing protocols vary across retail channels, demanding redundant quality documentation for pharmacy versus natural retail placement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Fish Omega 3 Supplements Market |
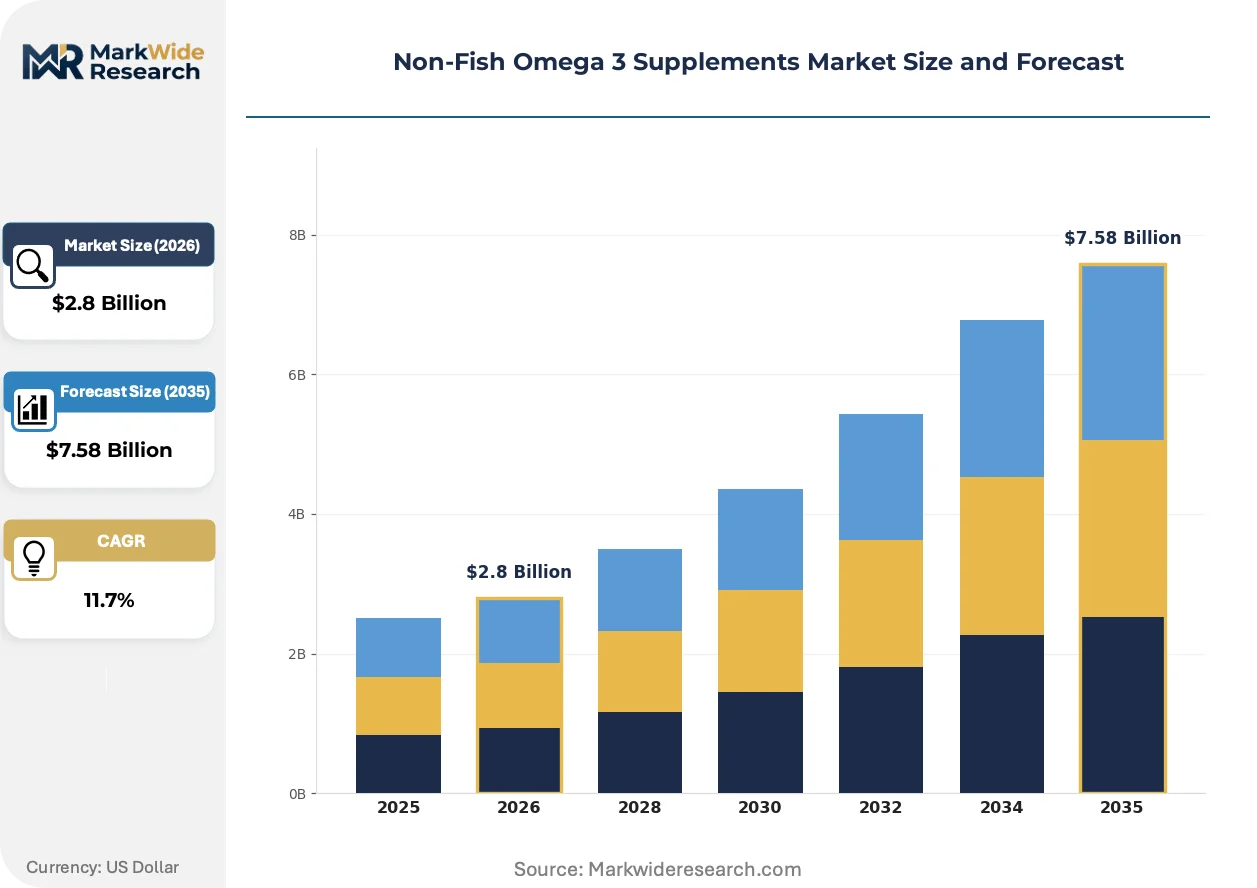
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.58 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flaxseed Oil, Algal Oil, Chia Seed Oil, Hemp Seed Oil Delivery Mode: Softgels, Liquid, Gummies, Capsules End User: Retail Customers, Fitness Enthusiasts, Healthcare Professionals, Athletes Ingredient Source: Plant-Based, Organic, Non-GMO, Others |
| Companies Covered | Nordic Naturals, Deva Nutrition LLC, NOW Foods, Ora Organic, BASF SE, ADM, Dsm-firmenich, Jarrow Formulas, Solgar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Fish Omega 3 Supplements Market Evolving Landscape
Biotechnology platforms are actively reshaping competitive boundaries through fermentation-derived ingredient supply, while regulatory pressure on extraction solvents and shifting channel preferences reconfigure downstream value capture.
Supercritical CO2 extraction technology is expanding into algal oil processing as the dominant non-thermal concentration method. Premium supplement manufacturers in Germany and the Netherlands are adopting this infrastructure to meet pharmacy-channel purity specifications. The technology is expanding into mid-tier contract manufacturing, compressing the historical premium attached to solvent-free processing and enabling broader brand access to clean-label positioning.
REACH compliance requirements for imported oil concentrates are tightening analytical documentation burdens across European supply chains. ECHA substance evaluation protocols now mandate expanded contaminant screening for novel algal strains entering the region. Specialty ingredient distributors with established European testing infrastructure are capturing margin from exporters lacking in-house analytical capabilities.
Direct-to-consumer subscription models are displacing traditional natural retail stocking for liquid and softgel omega-3 formats. Fitness-oriented buyers in North American and German markets favor automated replenishment over periodic pharmacy purchases. This channel rotation concentrates customer data ownership with vertically integrated brands and compresses slotting fee burdens that historically disadvantaged smaller algal oil specialists.
Non-Fish Omega 3 Supplements Market Segmentation
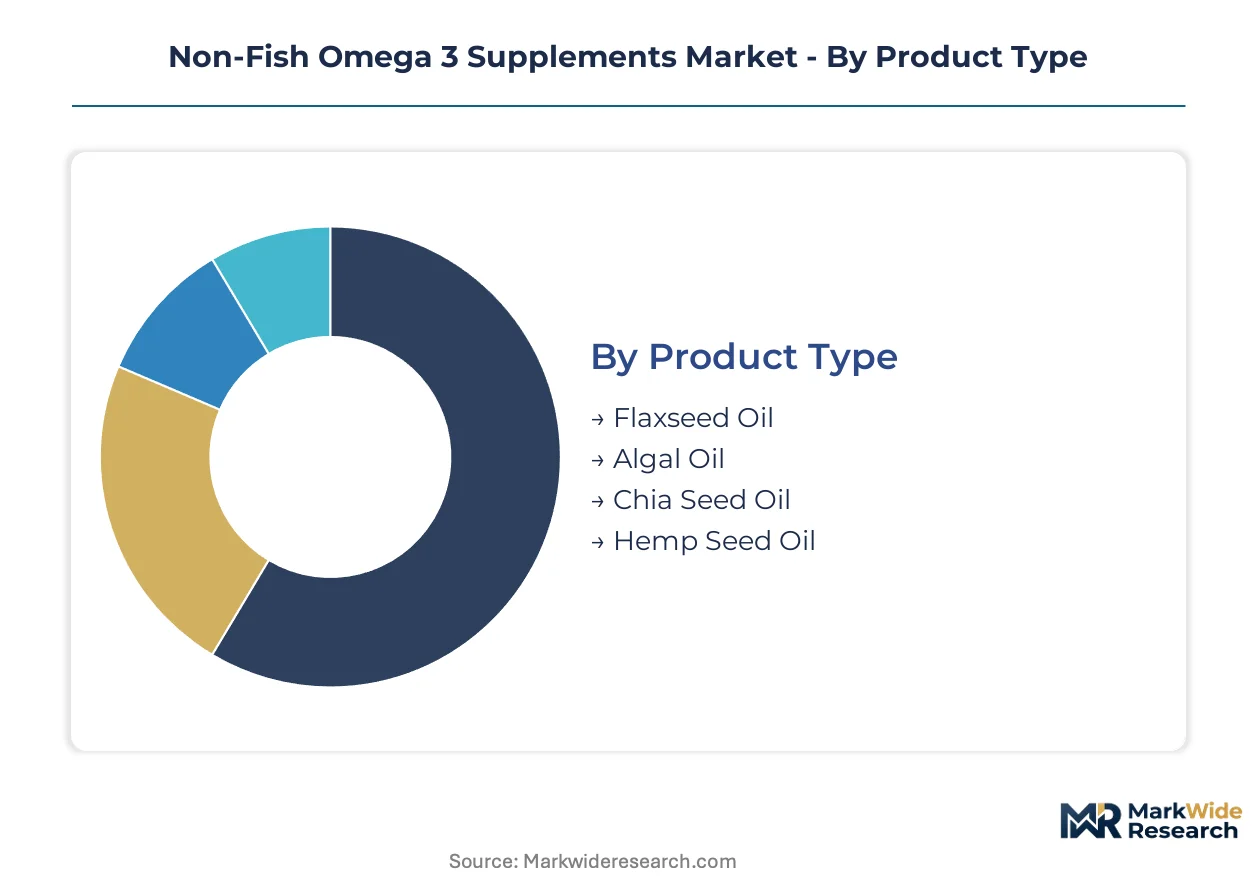
Segmentation in the non-fish omega-3 market reveals divergent margin profiles across extraction technologies and delivery formats. Manufacturers optimize formulation strategies by matching algal oil's bioavailability premium against flaxseed oil's cost scalability.
Product Type:
Volume leadership belongs to mass-market ALA sources, while premium pricing concentrates around direct DHA bioavailability.
- Flaxseed Oil:Cold-pressed alpha-linolenic acid from Linum usitatissimum seeds dominates unit economics through agricultural commodity pricing. German pharmacy chains stock flaxseed formulations for price-sensitive cardiovascular consumers, though metabolic conversion inefficiency limits penetration in prenatal segments.
- Algal Oil:Fermentation-derived docosahexaenoic acid from Schizochytrium or Crypthecodinium strains delivers preformed DHA without hepatic elongase conversion. DSM-Firmenich's life'sDHA platform supplies this segment, with demand clustering in US prenatal and pediatric formulations where conversion concerns dominate purchase decisions.
- Chia Seed Oil:Salvia hispanica-derived ALA with elevated antioxidant content from polyphenol matrices.
- Hemp Seed Oil:Cannabis sativa seed extract delivering balanced omega-3 to omega-6 ratios alongside gamma-linolenic acid.
Mature deployment sits with Flaxseed Oil. Newer deployment is concentrated in Algal Oil.
Delivery Mode:
Format selection tracks oxidation sensitivity and consumer demographic preferences across retail channels.
- Softgels:Gelatin or carrageenan-encapsulated oil concentrates with nitrogen headspace flushing for peroxide value stability. German pharmacy procurement specifications favor softgel oxidation protection metrics, driving quality-tier segmentation through peroxide and anisidine index certification.
- Liquid:Bottled oil concentrates with tocopherol or rosemary extract antioxidant systems enabling dose flexibility. Direct-to-consumer subscription brands in North America prioritize liquid formats for fitness enthusiasts seeking customizable daily intake volumes.
- Gummies:Pectin-based chewable matrices masking marine notes with citrus or berry flavor systems.
- Capsules:Two-piece hard shell formats accommodating powder or beadlet oil formulations.
Volume concentration remains with Softgels. Steepest expansion trajectory belongs to Gummies.
End User:
Customer archetypes separate by purchase channel authority and nutritional literacy levels.
- Retail Customers:Mass-market purchasers selecting supplements through supermarket or e-commerce channels with limited healthcare professional consultation. India's FSSAI registration requirements for algae-derived products create compliance friction for brands targeting this price-sensitive segment.
- Fitness Enthusiasts:Performance-oriented consumers prioritizing recovery and inflammation management through subscription replenishment models.
- Healthcare Professionals:Pharmacist and physician channels in Germany and the Netherlands where sustainability labeling influences recommendation protocols.
- Athletes:Competitive sports participants seeking batch-tested formulations with Informed Sport or NSF Certified for Sport verification.
Established demand centers on Retail Customers. Emerging demand clusters with Fitness Enthusiasts.
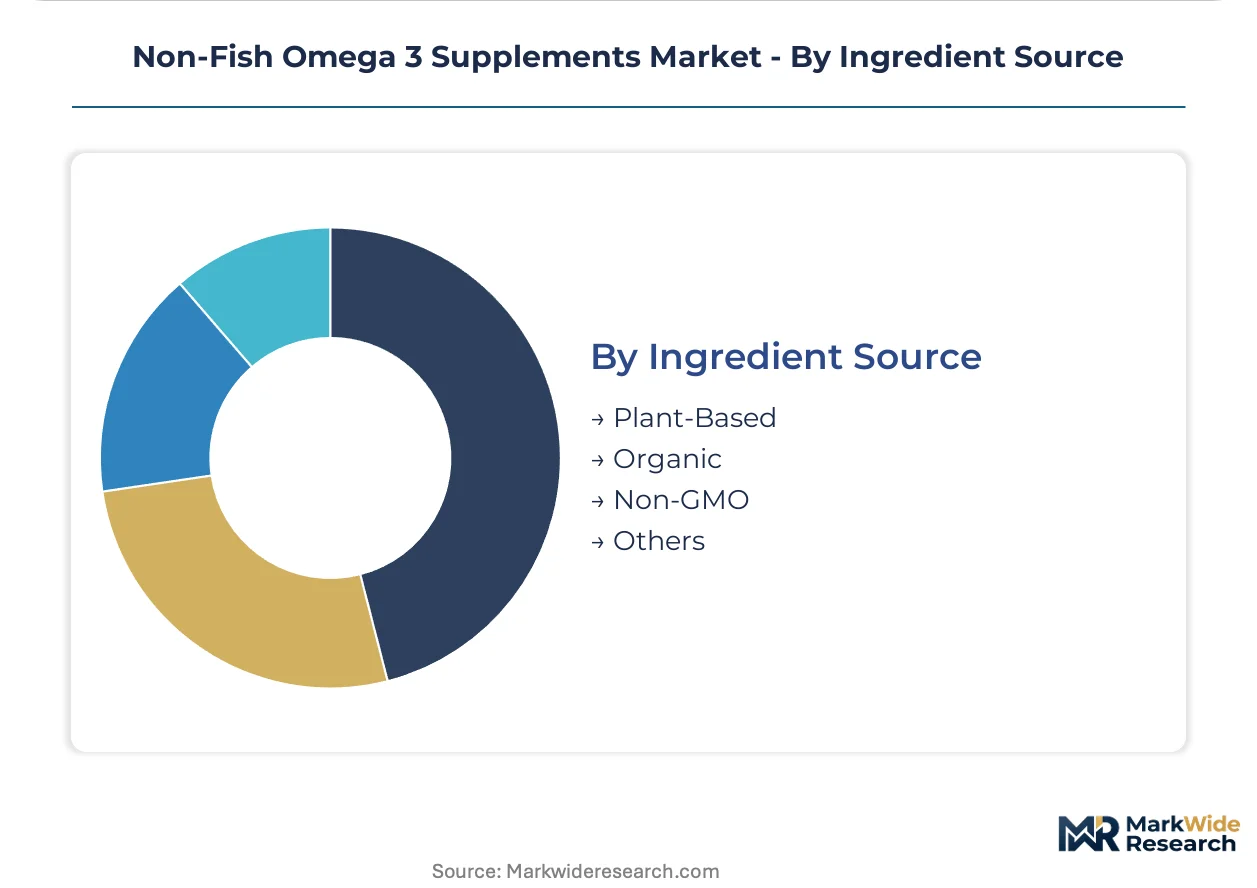
Ingredient Source:
Certification tiering creates price stratification across clean-label positioning claims.
- Plant-Based:Broad category encompassing all non-animal omega-3 sources including fermentation-derived and mechanically extracted oils. EU F-Gas Regulation compliance requirements favor supercritical CO2 processing for plant-based concentrates entering German and Dutch pharmacy channels.
- Organic:Certified organic oilseeds or algae biomass meeting USDA NOP or EU Organic Regulation cultivation standards.
- Non-GMO:Identity-preserved supply chains with third-party verification excluding recombinant DNA techniques.
- Others:Emerging sources including genetically edited algal strains or novel fermentation substrates.
Certification maturity concentrates in Plant-Based. Regulatory complexity is expanding fastest for Organic.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biotechnology special economic zones in Hamburg and Mannheim concentrate algal fermentation infrastructure, channeling federal R&D tax credits toward strain optimization facilities that supply DHA concentrates to European supplement manufacturers.
Germany
Pharmacy-channel procurement protocols prioritize sustainability-labeled plant-derived omega-3 over fish oil alternatives, with EFSA Novel Food approvals streamlining algal DHA entry. The EU F-Gas Regulation restricts solvent-based extraction, redirecting capital toward supercritical CO2 processors in Hamburg's port industrial zone.
United States
FDA GRAS notifications for Schizochytrium-derived DHA enable rapid formulation launches in prenatal and pediatric segments. Direct-to-consumer subscription brands concentrate in California's Bay Area and Austin, Texas, leveraging automated replenishment to displace traditional natural retail channels.
China
NMPA registration requirements for algae-derived supplements create compliance friction for imported concentrates, favoring domestic fermentation platforms. Yangtze River Delta biotech clusters in Shanghai and Suzhou scale proprietary algal strain production for both local consumption and export to Southeast Asian markets.
India
FSSAI maintains separate registration pathways for algae-derived supplements, elongating product launch cycles for foreign brands. Maharashtra's Mumbai-Pune industrial corridor hosts contract manufacturing facilities serving price-sensitive retail customers with flaxseed oil formulations.
Netherlands
REACH compliance infrastructure for imported oil concentrates rewards distributors with established European analytical capabilities. Rotterdam's port logistics hub processes algal oil shipments from fermentation facilities, with ECHA substance evaluation protocols mandating expanded contaminant screening for novel strains.
Non-Fish Omega 3 Supplements Market Competitive Landscape
Top-tier vendors anchor biotechnology platforms with proprietary strain libraries, while mid-tier finished-product brands compete on delivery format innovation and channel access. The market exhibits tiered concentration: fermentation-derived ingredient supply consolidates among specialized biotech firms, downstream supplement competition fragments across softgel, liquid, and gummy formats. Two strategic archetypes dominate—vertically integrated fermentation-to-brand operators and pure-play contract manufacturers leveraging licensed strain access. Competitive moves center on supercritical CO2 processing capacity expansion and direct-to-consumer subscription infrastructure deployment.
Among European biotechnology platforms, BASF SE and DSM-Firmenich occupy positions representing the premium ingredient tier, with the latter anchoring branded algal oil supply through its life'sDHA platform. NOW Foods exemplifies the aggressive finished-product competitor, competing across softgel and liquid delivery formats through natural retail and direct-to-consumer channels. These three entities represent the span from upstream fermentation control to downstream brand ownership.
| Leading Market Players |
|---|
| Nordic Naturals |
| Deva Nutrition LLC |
| NOW Foods |
| Ora Organic |
| BASF SE |
| ADM |
| Dsm-firmenich |
| Jarrow Formulas |
| Solgar |
| Others |
Value Network & Pricing Analysis
Pharmacy-channel buyers in Germany concentrate purchasing power through sustainability-labeled procurement protocols, anchoring a contract-based long-term offtake model that rewards REACH-compliant supercritical CO2 processors with price premiums over solvent-extracted alternatives.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as German pharmacy chains demand rapid replenishment of algal DHA concentrates meeting EFSA Novel Food specifications. Three-tier pricing structure across premium, standard, and economy levels separates DSM-Firmenich's life'sDHA platform from mid-tier fermentation suppliers and commodity flaxseed oil processors. Price differentiation rests on certification grade and oxidation stability metrics, with peroxide value documentation commanding substantial uplifts. Pricing pressure stems from fermentation-grade glucose feedstock volatility, compressing margins for biomass producers while retail customers in India exhibit highest price sensitivity due to FSSAI compliance cost pass-through.
Supply Chain Analysis
Domestic-content mandates in China's NMPA registration pathway reshape sourcing toward Yangtze River Delta fermentation facilities, displacing imported algal oil concentrates in favor of locally produced Schizochytrium-derived DHA. Supply concentrates in Germany, the United States, and China, with Hamburg's port industrial zone and Shanghai's biotech clusters anchoring upstream biomass production. Raw material dependencies include fermentation-grade glucose, nitrogen feedstocks, and nitrogen headspace flushing systems for oxidation protection. Single-source vulnerability concentrates around proprietary algal strain libraries controlled by limited biotechnology platforms. Distribution runs through pharmacy channels in Germany, direct-to-consumer subscription models in North America, and contract manufacturing networks in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-constrained dynamics in proprietary algal strain access prop pricing power for integrated fermentation platforms, with biotechnology IP licensing bottlenecks limiting downstream brand expansion.
For Market Incumbents: Cement supply security through captive strain library acquisition or exclusive licensing agreements with Hamburg and Mannheim fermentation facilities, while expanding supercritical CO2 processing capacity to capture EU F-Gas Regulation compliance premiums. Defend against contract manufacturer fragmentation by locking pharmacy-channel shelf placement through sustainability certification bundling. For New Entrants and Emerging Players: Begin with gummy delivery format specialization targeting fitness enthusiasts in North American subscription channels, where palatability-driven consumption and lower oxidation stability requirements reduce barrier-to-entry versus pharmacy-grade softgel competition. White space concentrates in pediatric and prenatal formulations where direct DHA bioavailability commands recommendation authority from healthcare professionals. For Investors and Strategic Acquirers: The window for entry favors biotechnology platforms with established EFSA Novel Food approval track records and REACH-compliant analytical infrastructure. Long-term viability hinges on fermentation cost curve positioning as strain optimization matures. Watch NMPA and FSSAI regulatory harmonization progress as inflection signal for cross-border supply chain consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Expansion | EU F-Gas Regulation compliance secures pharmacy-channel access in Germany and Netherlands. |
| Proprietary Strain Library Acquisition | Exclusive Schizochytrium access eliminates supply bottleneck vulnerability for downstream brands. |
| Direct-to-Consumer Subscription Launch | Automated replenishment concentrates customer data ownership with vertically integrated operators. |
| EFSA Novel Food Approval Pathway | Streamlined regulatory entry accelerates product launches for fermentation-derived DHA concentrates. |
| Pediatric Formulation Development | Direct DHA bioavailability captures prenatal recommendation protocols without metabolic conversion concerns. |
Research Methodology
Trade databases, EFSA Novel Food approval registers, and FDA GRAS notification filings formed the secondary backbone, supplemented by customs records tracking algal oil concentrate flows through Rotterdam and Hamburg ports. Primary interviews with fermentation biotechnology directors, pharmacy procurement managers at German chains, supplement brand formulation scientists, and contract manufacturing executives validated supply-side concentration and channel pricing dynamics. Bottom-up strain production capacity estimates triangulated against top-down pharmacy-channel sales data.
Historical trendline analysis of fermentation cost curves and pharmacy-channel shelf placement patterns anchored the projection framework across the analysis window. Segmentation dimensions modeled include extraction technology tier, delivery format, end-user archetype, and certification grade. CAGRs derived from biomass production scaling assumptions and channel migration rates for subscription versus retail purchasing. Industry-specific inputs incorporated EU F-Gas Regulation implementation timelines and NMPA registration backlog estimates.
Underlying measurement precision varies by segment; pharmacy-channel volume data carries tighter precision than direct-to-consumer subscription flows where private brand reporting gaps persist. Forecasts reflect assumptions around strain optimization rates and regulatory approval velocity. Algal oil oxidation stability certification protocol divergence and feedstock commodity price volatility present revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Global Hangover Rehydration Supplements Market
Nutritional Supplements
Natural Immune Booster Market
Nutritional Supplements
North America Immune Health Supplements Market
Nutritional Supplements
Canada Nutraceuticals Market
Nutritional Supplements
Bone Supplements Market
Nutritional Supplements
Functional Carbohydrates Market
Nutritional Supplements
Throat Lozenges Market
Nutritional Supplements
Prickly Pear Seed Oil Nutricosmetic Bases Market
Nutritional Supplements
Arabinogalactan Powder Market
Nutritional Supplements
Testosterone Booster Supplements Market
Nutritional Supplements
Isolate Whey Protein Market
Nutritional Supplements
Global Soluble Dietary Fibers Market
Nutritional Supplements
Health Supplements Market
Nutritional Supplements
Bypass Fat Supplement Market
Nutritional Supplements
United States Vitamin D Supplements Market
Nutritional Supplements
Maternity Vitamins and Supplements Market