
 Vegan Protein Supplements Market | 2026-2036
Vegan Protein Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Protein Supplements Market Insights
The gap between premium single-source isolates and commodity blended powders is rebalancing as raw material costs diverge. Glanbia plc leverages its dairy-alternative ingredient infrastructure to control pea protein supply chains from field to finished goods. Orgain differentiates through organic certification and pediatric positioning, while Garden of Life anchors the non-GMO verified segment with fermented protein formats. Sunwarrior competes in the sprouted and raw processing niche, sustaining higher price points through minimal heat treatment claims.
Vegan protein supplements comprise isolated, concentrated, or hydrolyzed plant proteins formulated for human consumption, typically delivering 15-30 grams of protein per serving with complete or complementary amino acid profiles achieved through blending legume and grain sources. These products serve commercial purposes spanning sports recovery, meal replacement, and clinical nutrition support for populations with dairy allergies or ethical dietary restrictions. Pea protein dominates volume production due to superior solubility and neutral flavor relative to hemp or rice alternatives, though soy protein retains the largest established manufacturing base. The ready-to-drink form captures the fastest expansion as convenience-seeking health-conscious consumers shift from powder preparation, while online retail concentrates margin pools through subscription models and direct-to-consumer branding.
FDA nutrition labeling rules and EFSA health claim assessments shape permissible protein content declarations and allergen warnings across major markets, with USDA organic standards and EU organic regulations further segmenting premium positioning. India's FSSAI and China's SAMR are tightening import registration requirements for novel plant protein sources, altering market access timelines for international suppliers. Stakeholders must monitor evolving amino acid scoring methodologies and carbon footprint disclosure mandates as these criteria increasingly influence procurement decisions and retail placement.
Market Dynamics
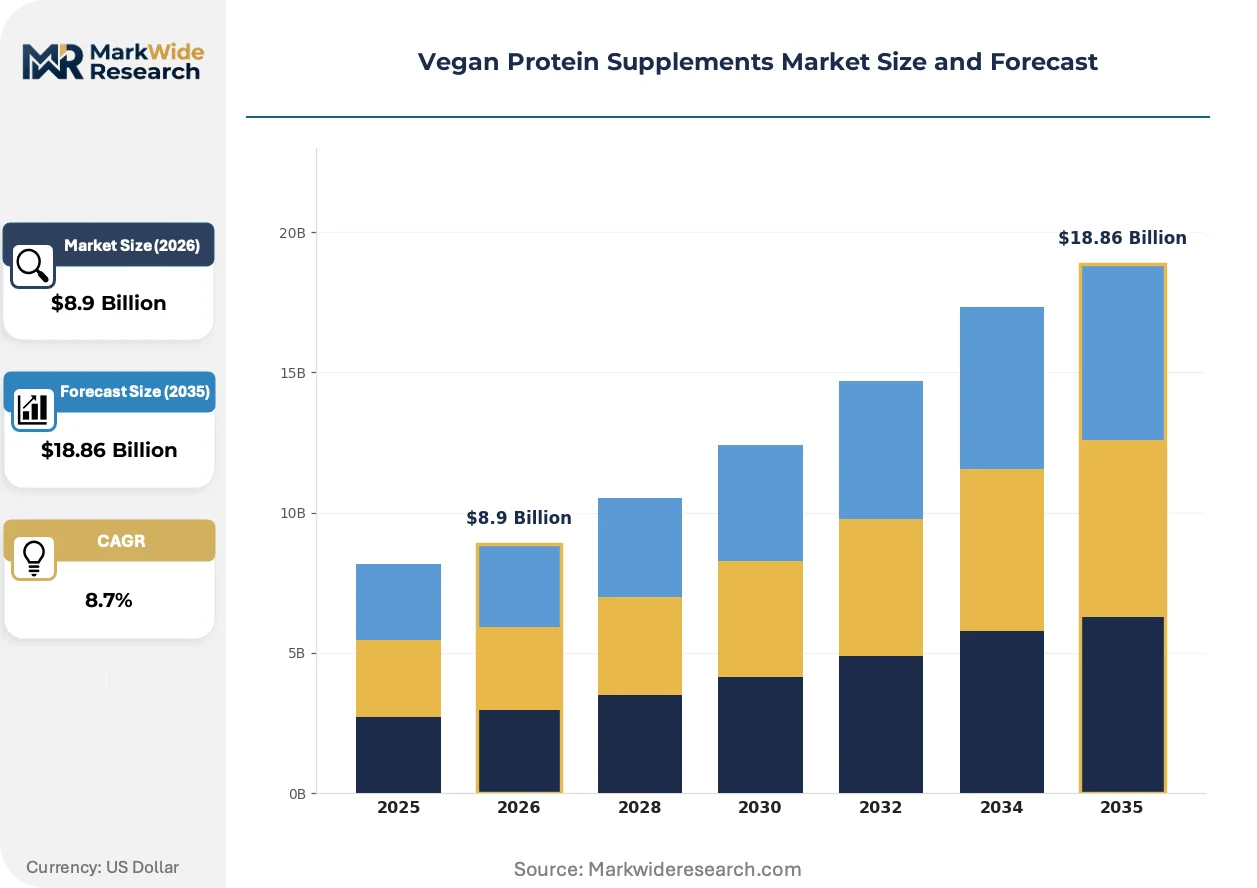
Clean-label certification mandates from FDA and EFSA are compressing formulation timelines while raw material divergence between pea protein isolates and commodity blends is rebalancing competitive positioning across supply tiers.
Growth Catalysts
- Fitness Enthusiast Demand:Sports recovery applications are pulling premium isolate volumes as gym culture professionalizes protein supplementation routines.
- USDA Organic Standards:Certification requirements under USDA and EU organic regulations are segmenting premium shelf placement and margin pools.
- Ready-to-Drink Convenience:Liquid formats are capturing time-constrained consumers shifting from powder preparation rituals toward grab-and-go nutrition.
Market Restraints
- Pea Protein Supply Concentration:Field-to-finished goods control by integrated processors creates input cost volatility for standalone brands.
- Solubility Limitations:Hemp and rice alternatives lag pea protein in neutral flavor and dispersibility, constraining formulation flexibility.
- Import Registration Friction:India's FSSAI and China's SAMR are extending novel plant protein approval timelines, delaying market access.
Strategic Opportunities
- Pediatric Positioning:Organic-certified formulations for children represent underpenetrated white space beyond adult sports nutrition.
- Fermented Protein Formats:Non-GMO verified fermentation processes are creating differentiation through enhanced bioavailability claims.
- Subscription Direct-to-Consumer:Online retail infrastructure enables recurring revenue capture and margin retention outside wholesale channels.
Industry Challenges
- Amino Acid Scoring Expertise:Formulation teams lack depth in PDCAAS and DIAAS calculation methodologies for complementary protein blending.
- Carbon Footprint Verification:Lifecycle assessment documentation requirements are extending certification timelines and compliance costs.
- Legacy Equipment Retrofit:Spray-drying and extrusion assets require capital reconfiguration for minimal-heat sprouted processing claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Protein Supplements Market |
| Market Size in 2026 | $8.9 Billion |
| Market Size in 2035 | $18.86 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pea Protein, Rice Protein, Hemp Protein, Soy Protein End User: Fitness Enthusiasts, Athletes, Health-Conscious Consumers, Bodybuilders Form: Powder, Bar, Ready-to-Drink, Capsule Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Health Food Stores |
| Companies Covered | Vega, Glanbia plc, NOW Foods, Orgain, Garden of Life, Sunwarrior, Abbott Laboratories, PlantFusion, ALOHA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Protein Supplements Market Trends and Innovations
Processing technology convergence with sustainability verification systems is restructuring how plant proteins achieve price premiums and retail placement authority.
Precision fermentation is modularizing protein production by enabling microbial hosts to express complete amino acid profiles without agricultural cultivation. Biotech ingredient suppliers are contracting with sports nutrition brands seeking supply security outside climate-dependent crop cycles. This technology is modularizing the upstream segment, compressing traditional field-to-factory supply chains into controlled bioreactor operations.
EFSA health claim assessments are tightening permissible protein content declarations and substantiation requirements for muscle maintenance benefits. Manufacturers must now generate clinical trial data packages to support label claims previously accepted through compositional analysis alone. Ready-to-drink formats face the steepest compliance burden as liquid products carry higher consumer expectation for functional efficacy messaging.
Health-conscious buyers are consolidating purchases around certified-clean labels that bundle organic, non-GMO, and carbon-neutral attributes into single trust marks. Specialty retailers are responding with curated aisle layouts that segregate verified products from conventional alternatives, effectively creating in-store channel tiers. Germany and Brazil display the most advanced retail infrastructure for this segmentation, with dedicated plant-based nutrition sections in mainstream supermarkets.
Vegan Protein Supplements Market Segmentation
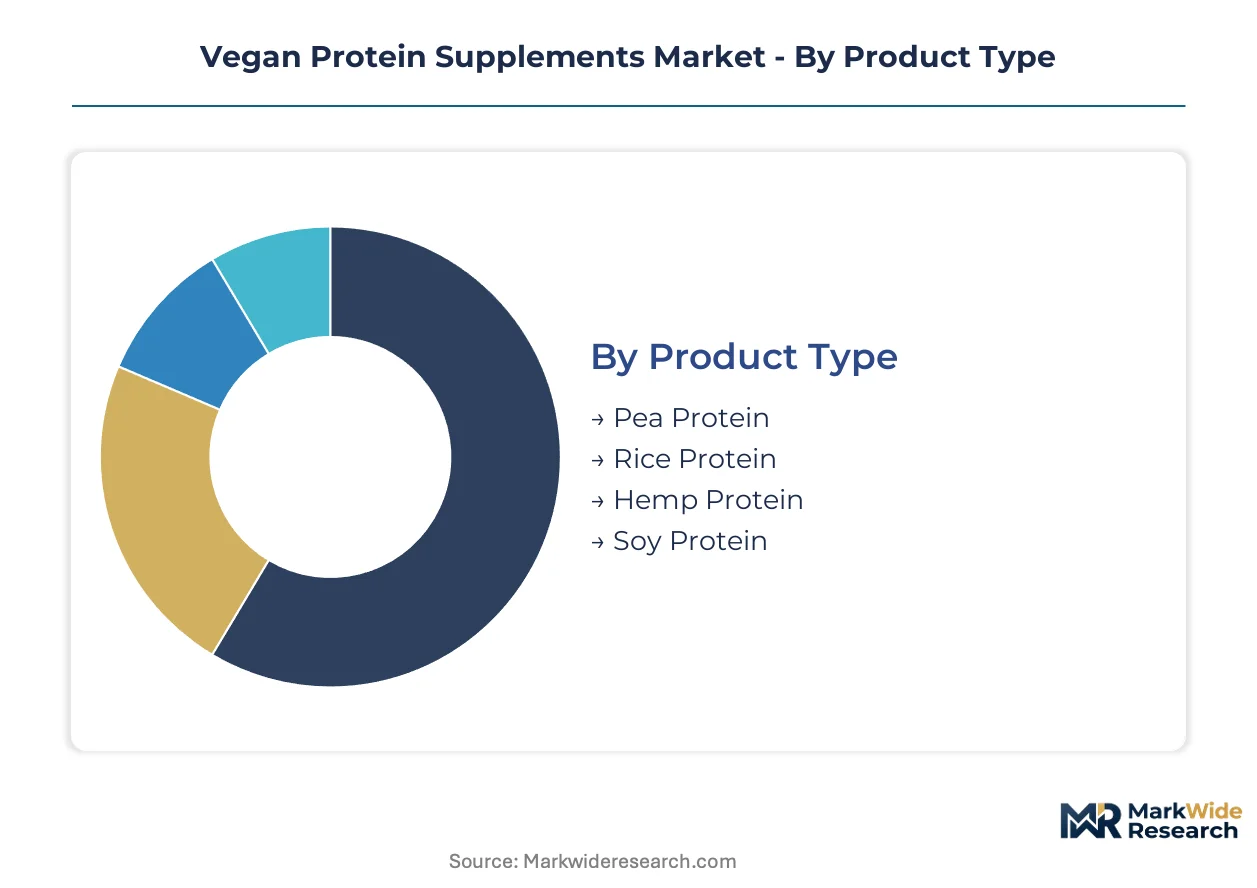
Plant protein sourcing, formulation complexity, and certification requirements vary sharply across product categories, creating distinct margin pools and regulatory exposure profiles for manufacturers.
Product Type:
Pea protein isolates trigger EFSA novel food assessments for hydrolyzed variants, while soy protein faces FDA allergen labeling mandates that compress formulation timelines for blended products.
- Pea Protein:Isolates deliver 80-90% protein content with superior solubility and neutral flavor relative to alternative sources. Demand concentrates among fitness enthusiasts in Germany where clean-label certification requirements under EFSA frameworks command premium shelf placement.
- Soy Protein:Retains the largest established manufacturing base with complete amino acid profiles achieved through conventional isolation. FDA allergen disclosure rules create compliance friction for brands targeting US retail expansion.
- Rice Protein:Hypoallergenic positioning serves pediatric and sensitive-diet segments with complementary amino acid blending requirements.
- Hemp Protein:Retains fiber and omega fatty acid content through minimal processing, constraining protein concentration but appealing to raw-food positioning.
Leading the category by volume: soy protein. Expanding most quickly: pea protein.
End User:
Professional versus recreational consumption patterns split procurement channels and price tolerance, with institutional buyers demanding batch consistency documentation absent from direct-to-consumer sales.
- Fitness Enthusiasts:Represent the core buyer segment where adoption continues to strengthen through sports recovery applications. Gym culture professionalization in Brazil drives premium isolate volumes through specialty retail channels.
- Health-Conscious Consumers:Convenience-seeking buyers shifting from powder preparation toward grab-and-go nutrition. USDA organic certification requirements segment this population into verified and conventional purchasing tiers.
- Athletes:Competitive performers requiring batch-tested formulations with banned-substance verification through third-party programs.
- Bodybuilders:High-dose consumers prioritizing leucine content and amino acid scoring metrics in product selection.
Dominating current revenue: fitness enthusiasts. Gaining share fastest: health-conscious consumers.
Form:
Processing intensity and packaging requirements create divergent capital investment profiles, with liquid formats demanding aseptic filling infrastructure absent from dry blending operations.
- Powder:Dominates production volume through lower per-unit packaging costs and extended shelf stability. EFSA health claim assessments impose steeper compliance burdens as consumer expectation for functional efficacy messaging rises.
- Ready-to-Drink:Captures the fastest expansion as time-constrained consumers abandon preparation rituals. India's FSSAI import registration requirements extend approval timelines for novel plant protein sources in liquid formats.
- Bar:Extrusion and coating processes require moisture management expertise to prevent texture degradation during shelf life.
- Capsule:Serves clinical nutrition support for populations with precise dosing requirements or swallowing difficulties.
Highest volume concentration: powder. Steepest expansion trajectory: ready-to-drink.
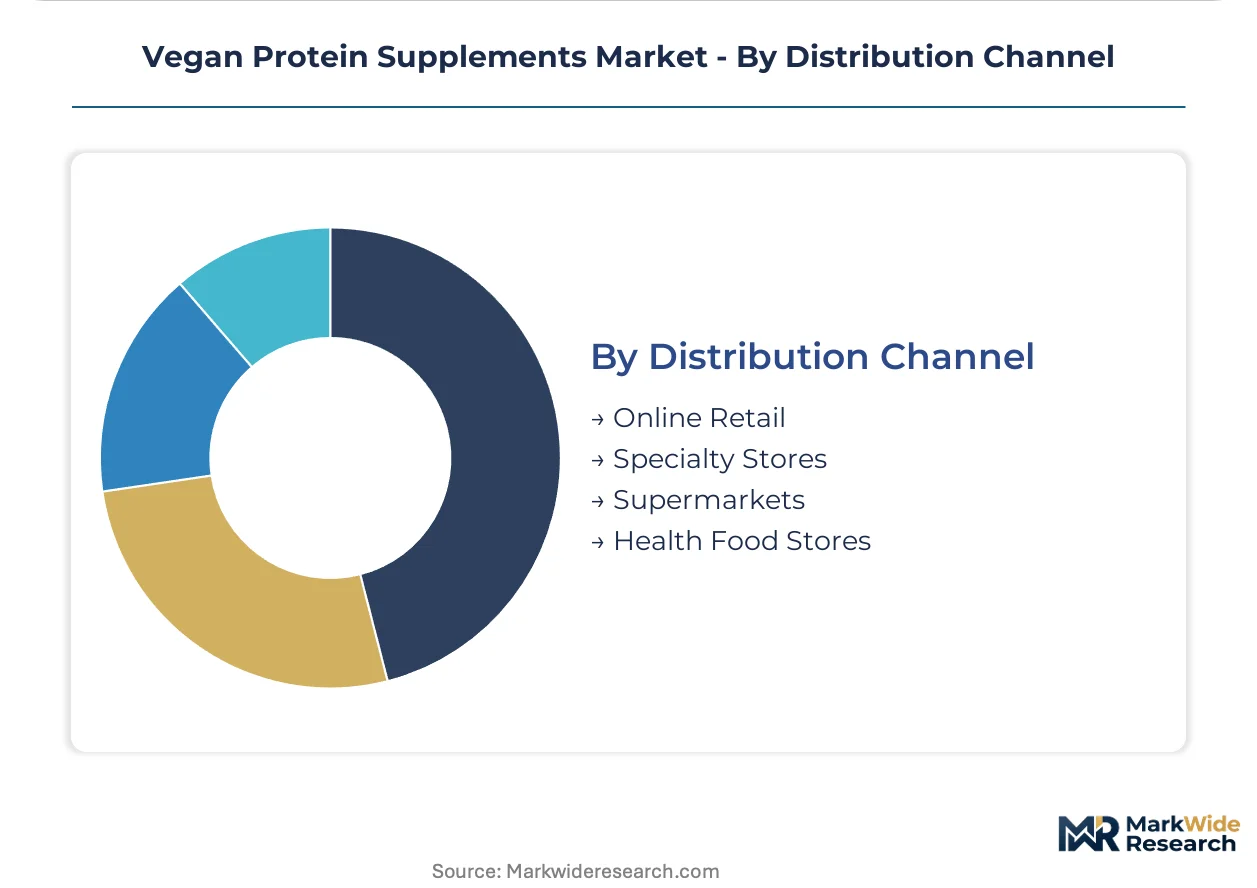
Distribution Channel:
Margin retention and customer data ownership favor direct channels, while physical retail delivers trial conversion and impulse purchase velocity unavailable through digital fulfillment.
- Online Retail:Concentrates margin pools through subscription models and direct-to-consumer branding. China's SAMR tightening of cross-border e-commerce regulations alters market access timelines for international suppliers.
- Specialty Stores:Curated aisle layouts in Germany segregate verified products from conventional alternatives, creating in-store channel tiers that reward certification investment.
- Supermarkets:Mainstream placement in Brazil demonstrates advanced retail infrastructure for plant-based nutrition segmentation.
- Health Food Stores:Staff expertise drives conversion for complex formulation claims requiring explanation.
Largest current share: online retail. Climbing the fastest: specialty stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Los Angeles anchors North American vegan protein innovation through its dense concentration of direct-to-consumer brands and specialty retail infrastructure serving fitness-forward consumer bases.
United States
Fitness enthusiasts in California and Texas drive premium isolate demand through specialized gym retail channels. FDA nutrition labeling rules enforce stricter protein content declarations and allergen warnings, compressing formulation timelines for new entrants. Chicago's manufacturing corridor hosts spray-drying facilities reconfiguring legacy equipment for minimal-heat processing claims.
Germany
Clean-label certification requirements under EFSA frameworks command premium shelf placement in Berlin and Munich supermarkets. EU organic regulations segment verified products into dedicated aisle layouts, rewarding certification investment with margin retention. The country's central European logistics position enables distribution efficiency across neighboring markets.
Brazil
Gym culture professionalization in São Paulo and Rio de Janeiro pulls premium isolate volumes through specialty retail channels. ANVISA import registration requirements extend approval timelines for novel plant protein sources, altering market access for international suppliers. The Southeast region demonstrates the most advanced retail infrastructure for plant-based nutrition segmentation in Latin America.
China
SAMR tightening of cross-border e-commerce regulations alters market access timelines for international vegan protein suppliers targeting health-conscious consumers in Shanghai and Beijing. The country's dual carbon goals accelerate domestic precision fermentation investment, modularizing protein production outside agricultural cultivation cycles. Yangtze River Delta biotech clusters contract with sports nutrition brands seeking supply security.
India
FSSAI import registration requirements extend approval timelines for novel plant protein sources in liquid formats, delaying ready-to-drink market entry for foreign brands. Maharashtra and Karnataka host emerging domestic manufacturers serving fitness enthusiasts in Mumbai and Bangalore. The country's vegetarian dietary traditions create receptive consumer bases for plant-based nutrition expansion.
Vegan Protein Supplements Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tiers, with organic and non-GMO verified portfolios retaining pricing authority in specialty retail channels. The vendor base stratifies between integrated processors controlling field-to-finished goods supply chains and standalone brands dependent on third-party raw material sourcing. Three archetypes dominate: dairy-alternative infrastructure leverage, organic pediatric positioning, and minimal-heat processing specialists. Competitive moves concentrate on backward integration into pea protein cultivation and direct-to-consumer subscription infrastructure buildout.
Within the infrastructure-leverage tier, Glanbia plc represents integrated supply chain control, while Orgain and Garden of Life exemplify certification-driven differentiation strategies. Sunwarrior occupies a position in the sprouted processing niche, sustaining higher price points through specific processing claims. These three companies anchor distinct competitive vectors: supply security, organic verification, and raw-format positioning respectively.
| Leading Market Players |
|---|
| Vega |
| Glanbia plc |
| NOW Foods |
| Orgain |
| Garden of Life |
| Sunwarrior |
| Abbott Laboratories |
| PlantFusion |
| ALOHA |
| Others |
Pricing and Supply Chain Analysis
Certification-ladder bifurcation between USDA Organic verified isolates and conventional blended powders manifests in both margin retention and upstream procurement configurations, as EFSA clean-label mandates compress formulation timelines while raw material divergence rewards backward integration into pea protein cultivation.
Pricing Analysis
Value-based pricing anchors on bioavailability outcomes and amino acid completeness, with three-tier pricing structure across premium, standard, and economy levels segmenting by certification grade and processing intensity. Price differentiation stems from organic verification and minimal-heat processing claims, while cost compression in commodity blends intensifies due to pea protein supply concentration. Fitness enthusiasts demonstrate lowest price sensitivity, whereas health-conscious casual buyers exhibit highest elasticity.
Supply Chain Analysis
Certification gating through FDA allergen labeling and EFSA novel food assessments concentrates supply relationships among pre-qualified processors. Raw material flows draw from Canada, France, and China for pea protein isolate, with soy protein sourcing anchored in Brazil and India. Single-source vulnerability pervades hydrolyzed variant production. Distribution runs through direct-to-consumer subscription platforms and specialty retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as clean-label compliance costs and carbon footprint verification requirements force sub-scale brands toward exit or acquisition.
For Market Incumbents: Anchor premium positioning through captive pea protein supply from field to finished goods, while deepening certification moats via EFSA health claim substantiation investments. Precision fermentation entrants threaten commodity tier displacement; defend through exclusive biotech partnerships and spray-drying asset retrofit for minimal-heat processing claims. For New Entrants and Emerging Players: Precision fermentation technology offers a technology-first wedge into supply-constrained isolate segments, bypassing climate-dependent crop cycles. Pediatric organic formulations and Brazil's gym retail channels present the most penetrable white-space targets. A direct-to-consumer subscription launch with carbon-neutral verification captures recurring revenue outside wholesale margin compression. For Investors and Strategic Acquirers: Re-rating potential sits with integrated processors controlling field-to-finished goods supply chains given raw material cost divergence catalysts. Long-term viability favors organic-certified portfolios with fermentation capability access. Monitor EFSA amino acid scoring methodology revisions as inflection indicator for formulation obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pea Cultivation | Captive supply from Canadian and French farming cooperatives insulates against input cost volatility. |
| Precision Fermentation Partnership | Bioreactor-based protein production decouples supply security from agricultural climate exposure. |
| Direct-to-Consumer Subscription Launch | Recurring revenue retention bypasses specialty retail margin extraction in Germany and Brazil. |
| USDA Organic Certification Investment | Premium shelf placement in US supermarkets commands price authority over conventional alternatives. |
| EFSA Health Claim Substantiation | Clinical trial data packages enable muscle maintenance messaging previously blocked by compositional analysis alone. |
Research Methodology
Multi-period observation of certification adoption rates, raw material cost spreads, and channel shift patterns anchored the trend analysis, supplemented by interviews with plant protein formulation scientists, specialty retail category buyers, organic certification auditors, and sports nutrition brand executives. Secondary validation drew from FDA nutrition labeling guidance documents, EFSA novel food assessment registers, USDA organic certification databases, and customs trade flow records. Bottom-up volume builds and top-down macro constraint checks triangulated market sizing.
Input-output matrix modeling connected pea protein isolate supply capacity to ready-to-drink format demand projections across the analysis window, with segmentation dimensions spanning protein source type, end-user archetype, product form, and distribution channel. CAGRs derived from regression analysis against fitness participation rates and organic food expenditure indices, incorporating precision fermentation capacity buildout assumptions and EFSA regulatory timeline scenarios as scenario-weighted inputs.
Several conditions sit outside the modeled scope, including unforeseen novel food approval accelerations, trade policy disruptions affecting Canadian pea protein exports, and breakthrough microbial strain efficiencies in fermentation platforms. Forecasts reflect documented assumptions regarding certification cost trajectories and consumer willingness-to-pay for carbon-neutral claims. A model refresh is warranted upon material change in EFSA amino acid scoring methodology or SAMR cross-border e-commerce enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Medium-Chain Triglycerides Market
Nutritional Supplements
Global Antioxidant Market
Nutritional Supplements
Andro Supplements Market
Nutritional Supplements
Dietary Fiber Gummies Market
Nutritional Supplements
Middle-East and Africa Dietary Supplement Market
Nutritional Supplements
Krill Oil Market
Nutritional Supplements
Asia-Pacific Omega-3 Products Market
Nutritional Supplements
Garlic Supplements Market
Nutritional Supplements
Liuweidihuang Market
Nutritional Supplements
Milk Thistle Market
Nutritional Supplements
Latin America Herbal Supplements Market
Nutritional Supplements
Mexico Collagen Peptides Market
Nutritional Supplements
Bone Broth Protein Powder Market
Nutritional Supplements
Ketogenic Diet Market
Nutritional Supplements
Vegan Supplements Market
Nutritional Supplements
Choline Bitartrate Market